
 Water Testing Meter Market | 2026-2036
Water Testing Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Water Testing Meter Market Analytics
Chinese electrochemical sensor production is rebalancing as domestic manufacturers scale membrane electrode output. Thermo Fisher Scientific sustains R&D intensity across optical dissolved oxygen platforms. Danaher Corporation anchors its position through bench meter specialization for pharmaceutical QC labs. Horiba competes aggressively in multiparameter handheld units for field environmental monitoring.
Water testing meters are electrochemical or optically based instruments that quantify parameters such as pH, dissolved oxygen, conductivity, turbidity, and specific ion concentration through calibrated sensor probes and reference electrodes, serving primary industrial purposes in regulatory compliance verification and process control for water-dependent operations. Portable meters lead volume sales due to decentralized field deployment by environmental agencies and utility crews, while bench meters command stronger margin pools from laboratories requiring NIST-traceable precision and automated data logging. Multiparameter configurations represent the fastest-growing product configuration as operators seek to reduce instrument count and streamline workflow across drinking water testing and wastewater analysis applications.
EPA Safe Drinking Water Act amendments and EU Drinking Water Directive recasts are forcing municipalities to upgrade from colorimetric spot tests to continuous digital monitoring with documented calibration trails. ISO 17025 laboratory accreditation requirements and China's GB standards for drinking water quality are shaping procurement specifications and supplier qualification protocols across industrial and environmental end users. Stakeholders must weigh electrochemical against optical technology commitments as regulatory detection limits tighten and total cost of ownership calculations shift toward sensor longevity and interchangeability.
Market Dynamics
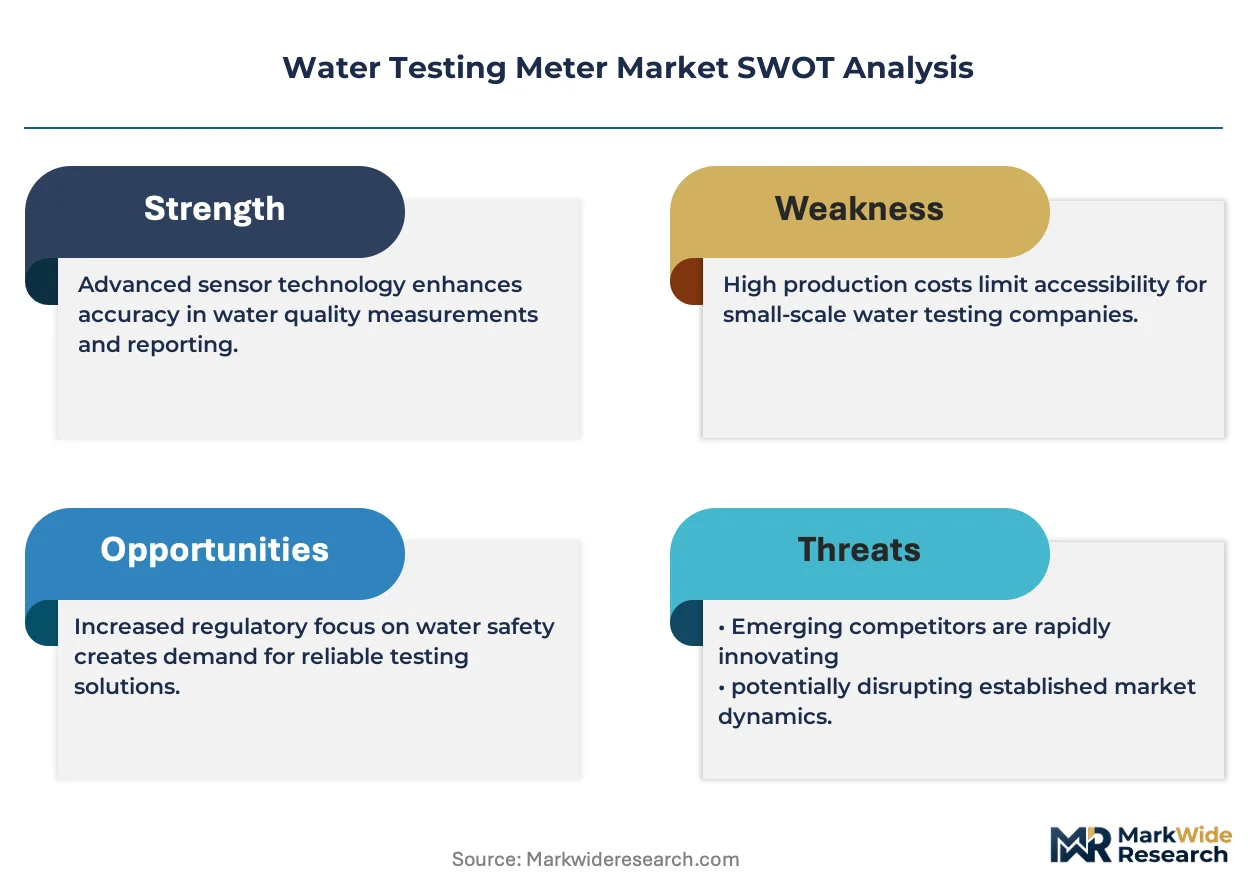
Municipal utilities face simultaneous pressure from tightening EPA discharge thresholds and aging infrastructure replacement cycles, forcing capital allocation toward continuous digital monitoring systems with documented calibration trails rather than periodic spot testing.
Growth Catalysts
- EPA Safe Drinking Water Act amendments:Municipalities must upgrade from colorimetric tests to continuous digital monitoring with NIST-traceable precision, expanding procurement of bench and portable meter systems.
- Membrane electrode scaling:Chinese domestic manufacturers are rebalancing electrochemical sensor production toward higher-output membrane electrode architectures, reducing unit costs for dissolved oxygen and ion-selective probes.
- Pharmaceutical QC lab expansion:Bench meter demand concentrates in pharmaceutical quality control laboratories requiring automated data logging and multi-parameter validation protocols.
Market Restraints
- Reference electrode supply concentration:Silver-silver chloride reference electrode production clusters in East Asian component suppliers, exposing meter manufacturers to input volatility and single-source risk.
- Optical sensor cost premium:Fluorescent dissolved oxygen and turbidity sensors carry 3-4x electrochemical equivalent pricing, limiting adoption in budget-constrained municipal contracts.
- ISO 17025 accreditation friction:Laboratory procurement specifications require supplier qualification protocols that extend sales cycles and elevate compliance documentation burdens.
Strategic Opportunities
- India drinking water infrastructure:BIS standards alignment and centralized rural water quality monitoring programs create procurement windows for portable multiparameter units.
- Cloud-connected calibration services:Meter-as-a-service models with remote diagnostic capabilities are penetrating environmental agency fleets seeking to reduce field technician deployment.
- Wastewater nutrient monitoring convergence:Nitrate and phosphate ion-selective electrode integration with optical turbidity platforms enables single-instrument compliance for discharge permitting.
Industry Challenges
- Electrochemist technician scarcity:Field calibration and sensor maintenance require specialized expertise that utility workforces lack, elevating training costs and service contract dependency.
- Legacy SCADA integration complexity:New digital meters must interface with decades-old municipal control systems through proprietary protocol converters, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Testing Meter Market |
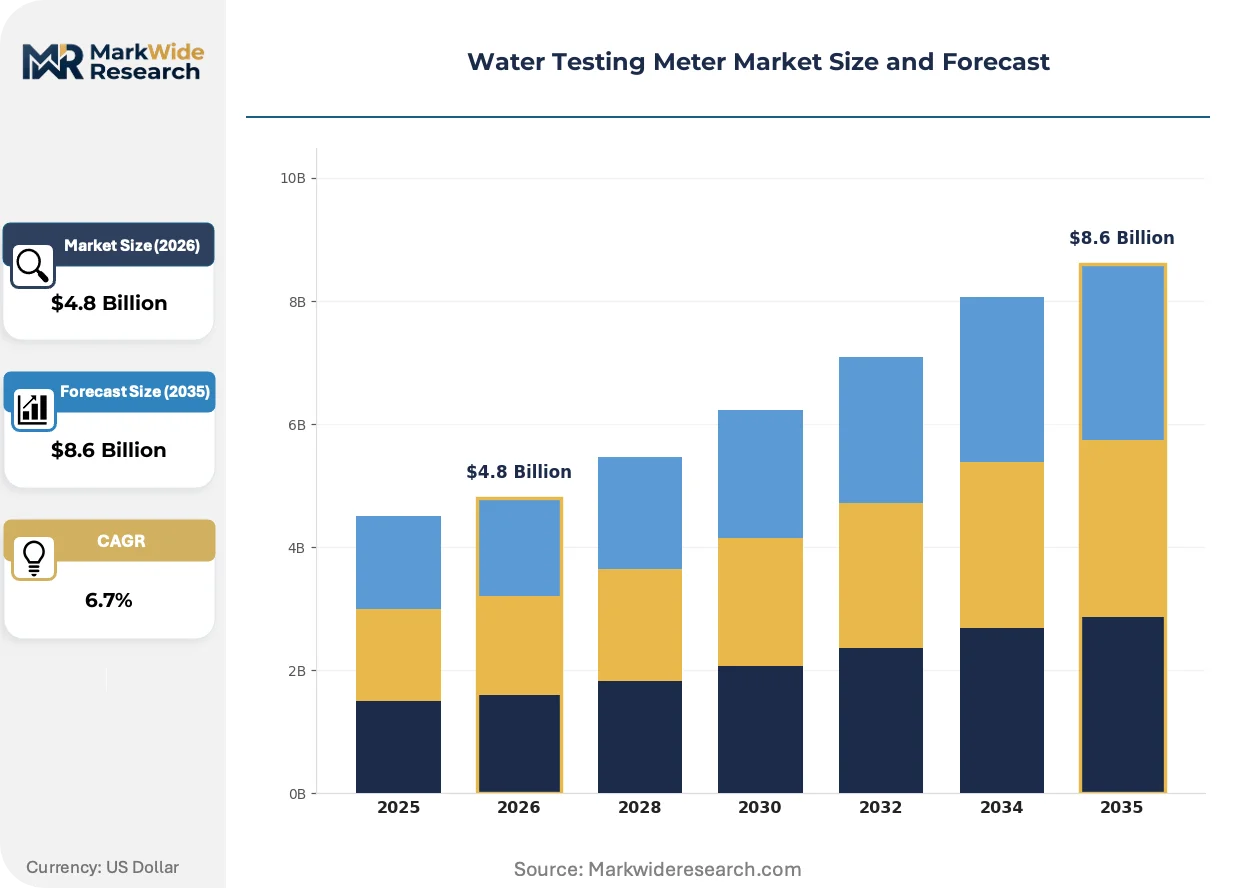
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Bench Meters, Multiparameter Meters, pH Meters Technology: Electrochemical, Optical, Colorimetric, Conductivity End User: Laboratories, Environmental Agencies, Industrial Facilities, Agricultural Sector Application: Drinking Water Testing, Wastewater Analysis, Aquaculture Monitoring, Industrial Water Quality |
| Companies Covered | Honeywell International, Thermo Fisher Scientific, Danaher Corporation, Hach, Mettler-Toledo International, Horiba, Emerson Electric, PerkinElmer, Badger Meter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Testing Meter Market Evolving Landscape
Sensor miniaturization and wireless telemetry are compressing the form-factor gap between laboratory-grade precision and field-deployable durability, enabling new deployment paradigms across distributed water networks.
Microfluidic sample handling is electrifying bench meter architectures by integrating automated flow injection with electrochemical detection cells. Pharmaceutical and environmental laboratories are adopting these systems to reduce manual pipetting error and accelerate throughput. The technology is compressing technician time-per-sample while elevating reproducibility metrics required for ISO 17025 accreditation.
EU Drinking Water Directive recasts are mandating lower detection thresholds for lead, PFAS, and disinfection byproducts across member state water utilities. Industrial consequence includes forced replacement of colorimetric field kits with digital meters capable of parts-per-billion resolution. Germany and France are accelerating procurement most aggressively, with utility operators prioritizing multiparameter handheld units with documented calibration trails.
Environmental agencies are unbundling after-sales service from hardware procurement, contracting third-party calibration providers rather than manufacturer service networks. This channel shift is disrupting traditional meter vendor revenue models concentrated in annual maintenance agreements. The pattern is most visible in United States municipal utilities seeking to reduce vendor lock-in and optimize total cost of ownership across dispersed meter fleets.
Water Testing Meter Market Segmentation
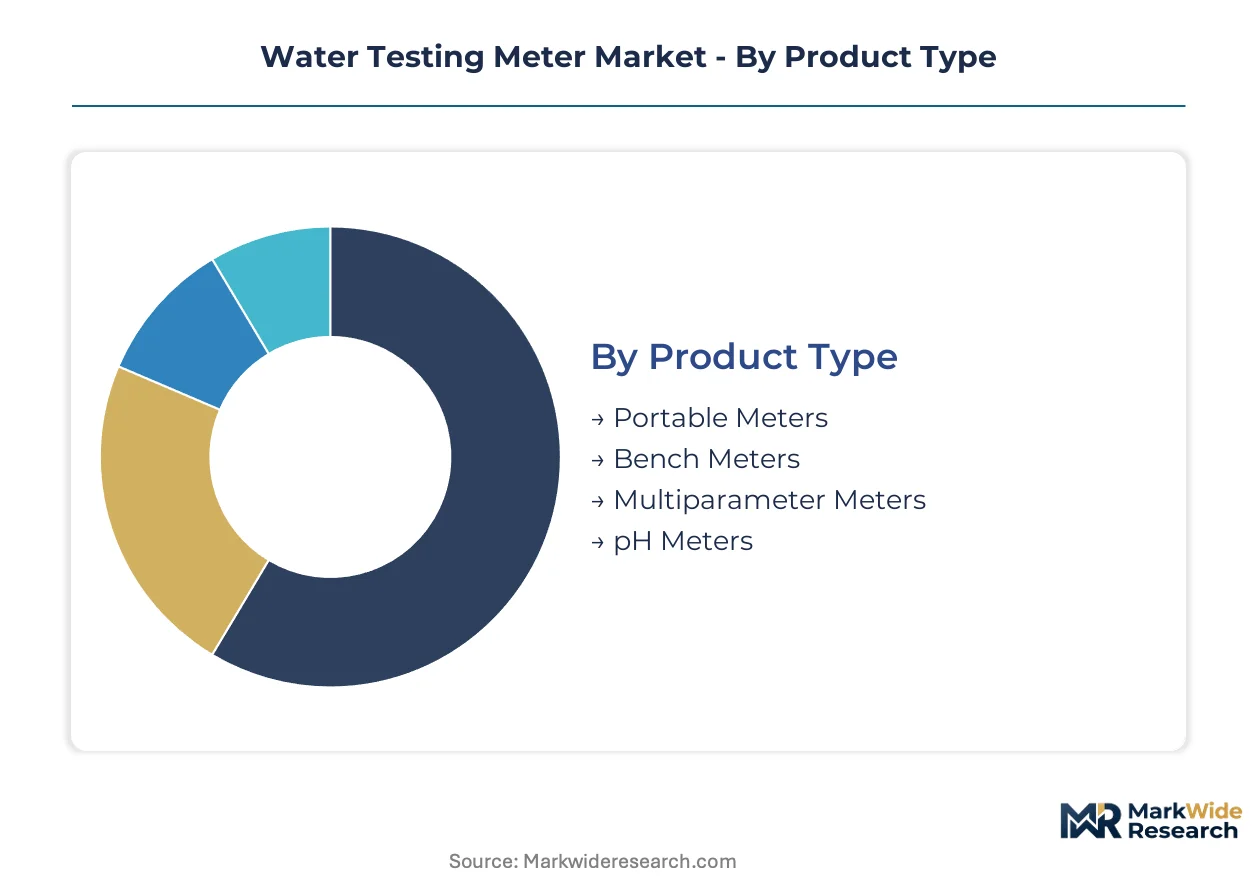
Water testing meter procurement splits across four distinct classification schemes, each shaping supplier qualification protocols and margin structures differently. Certification requirements from EPA, ISO, and national standards bodies create divergent compliance burdens across these segment boundaries.
Product Type:
Portable meters carry lighter ISO 17025 documentation requirements than bench systems, while multiparameter configurations demand broader calibration traceability across multiple analyte channels.
- Portable Meters:Battery-powered handheld units with membrane electrode or optical probe interfaces prioritize field durability and rapid deployment. Environmental agencies in the United States and Germany concentrate procurement here for stream monitoring and utility spot-checking, driven by decentralized regulatory enforcement mandates.
- Bench Meters:Laboratory-grade instruments with automated temperature compensation and NIST-traceable reference electrodes support high-precision validation workflows. Pharmaceutical QC labs in Switzerland and academic research facilities anchor demand, constrained by extended supplier qualification cycles under ISO 17025 protocols.
- Multiparameter Meters:Integrated platforms combining pH, dissolved oxygen, conductivity, and turbidity sensing in single housings.
- pH Meters:Dedicated hydrogen ion concentration instruments with glass or ISFET electrode architectures.
Portable meters sit at the top of the volume ranking, with multiparameter meters climbing the fastest.
Technology:
Cost tiers separate electrochemical platforms from optical alternatives, with fluorescence-based dissolved oxygen sensors commanding premium positioning against membrane electrode equivalents.
- Electrochemical:Membrane electrode and ion-selective probe technologies leverage silver-silver chloride reference systems for potentiometric measurement. Chinese domestic manufacturers are scaling output aggressively, compressing unit economics for municipal utilities in India and Brazil.
- Optical:Fluorescent dissolved oxygen and nephelometric turbidity sensors eliminate electrolyte depletion issues but carry substantial upfront cost premiums. German wastewater treatment operators and Japanese aquaculture facilities absorb these prices for reduced maintenance intervals.
- Colorimetric:Reagent-based field test kits with visual or photometric endpoint detection.
- Conductivity:Four-electrode and toroidal cell architectures for total dissolved solids estimation.
Electrochemical platforms dominate unit shipments, though optical systems are gaining share fastest in premium applications.
End User:
Customer type determines calibration frequency requirements and service contract attachment rates, with laboratories demanding highest-touch support models.
- Laboratories:ISO 17025-accredited analytical facilities requiring automated data logging and audit trail documentation. Environmental testing labs in France and food safety laboratories in Italy drive replacement cycles, constrained by proficiency testing overhead.
- Environmental Agencies:Federal and state regulatory bodies with fleet deployment across watershed monitoring networks. The United States EPA and Germany's federal environmental agencies standardize on multiparameter handheld units for field compliance verification.
- Industrial Facilities:Power generation, chemical processing, and semiconductor fabrication plants with continuous process control requirements.
- Agricultural Sector:Irrigation water quality monitoring and livestock operation compliance testing.
Laboratories generate strongest margin contribution, with environmental agencies representing the steepest expansion trajectory.
Application:
Regulatory detection limit tightening is forcing application-specific technology migrations, particularly for emerging contaminant monitoring.
- Drinking Water Testing:Distribution system compliance verification against EPA Safe Drinking Water Act and EU Drinking Water Directive thresholds. United States municipal utilities and French water operators are upgrading from colorimetric kits to digital platforms for lead and PFAS detection.
- Wastewater Analysis:Discharge permitting compliance with nutrient loading and toxicity testing requirements. German industrial pretreatment facilities and Chinese municipal plants concentrate procurement for nitrogen and phosphate monitoring.
- Aquaculture Monitoring:Dissolved oxygen and pH control for intensive fish farming operations.
- Industrial Water Quality:Boiler feedwater, cooling tower, and ultrapure water specification compliance.
Drinking water testing commands largest revenue pool, while wastewater analysis expands most quickly on nutrient monitoring convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor production is migrating toward jurisdictions with lower environmental compliance costs for electrochemical component fabrication, while end-use demand concentrates in regions with tightening discharge thresholds and infrastructure replacement cycles.
United States
EPA Safe Drinking Water Act amendments are forcing municipal utilities to replace colorimetric field kits with continuous digital monitoring systems. The agency's revised lead and PFAS detection mandates are accelerating procurement of multiparameter handheld units across the Great Lakes and Ohio River watersheds. Pittsburgh and Cleveland water authorities are standardizing on bench meters with NIST-traceable calibration trails for distribution system compliance.
Germany
Federal environmental agencies are deploying fleet-scale multiparameter units for river basin monitoring under EU Drinking Water Directive recasts. The country's wastewater treatment operators are absorbing optical sensor premiums to reduce maintenance intervals on dissolved oxygen platforms. Industrial pretreatment facilities in the Ruhr region are converging nitrate and phosphate monitoring into single-instrument configurations for discharge permitting compliance.
China
Domestic membrane electrode manufacturers are scaling output aggressively to serve municipal plants upgrading under GB standards for drinking water quality. The Ministry of Ecology and Environment is tightening discharge thresholds for industrial facilities in the Yangtze River Delta. Shenzhen and Shanghai water utilities are procuring portable electrochemical platforms for decentralized field deployment across aging distribution networks.
India
BIS standards alignment and centralized rural water quality monitoring programs are creating procurement windows for portable multiparameter units. The Jal Jeevan Mission is expanding testing protocols across state water supply departments. Gujarat and Maharashtra utilities are piloting cloud-connected calibration services to reduce field technician deployment costs across dispersed meter fleets.
Japan
METI efficiency standards are shaping procurement specifications for semiconductor fabrication plants requiring ultrapure water quality verification. Aquaculture operators in Kyushu are adopting optical dissolved oxygen sensors for intensive fish farming operations. Osaka-based environmental laboratories are driving replacement cycles for ISO 17025-accredited bench systems with automated data logging capabilities.
Water Testing Meter Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue membrane electrode commoditization through scaled manufacturing. The vendor base stratifies across three tiers: diversified instrumentation conglomerates with full-spectrum portfolios, electrochemical specialists with captive sensor production, and regional assemblers importing reference electrodes from East Asian component suppliers. Competitive positioning hinges on calibration service attachment rates and cloud-connected fleet management capabilities rather than hardware differentiation alone. M&A activity targets aftermarket service networks, while greenfield capacity concentrates in lower-cost electrochemical probe fabrication.
Among diversified instrumentation conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify the premium-tier archetype through bench meter specialization and pharmaceutical QC lab anchoring. Horiba occupies a distinct position in multiparameter handheld units for field environmental monitoring. These three entities represent contrasting strategic vectors: optical platform R&D intensity, vertical control over precision reference systems, and aggressive pricing in portable configurations respectively.
| Leading Market Players |
|---|
| Honeywell International |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Hach |
| Mettler-Toledo International |
| Horiba |
| Emerson Electric |
| PerkinElmer |
| Badger Meter |
| Others |
Value Network & Pricing Analysis
EU Drinking Water Directive recasts are tightening detection thresholds for lead, PFAS, and disinfection byproducts, gating qualified supply to manufacturers with documented calibration trails and ISO 17025-accredited production lines while reserving premium-tier pricing access for vendors offering NIST-traceable precision and automated data logging capabilities.
Pricing Analysis
Distributor margins absorb 15-25 points on portable electrochemical meters before reaching municipal procurement officers, while direct-to-OEM channels for bench systems command steeper discounts tied to volume commitments. Three-tier pricing structure across premium optical platforms, standard membrane electrode systems, and economy colorimetric alternatives separates pharmaceutical QC labs from budget-constrained utilities. Cost compression in Chinese-manufactured membrane electrodes is intensifying because domestic scaling has collapsed unit economics for dissolved oxygen and ion-selective probes. Environmental agencies exhibit highest price sensitivity, prioritizing fleet-standardized portable units, whereas semiconductor fabrication plants absorb optical premiums for ultrapure water verification.
Supply Chain Analysis
Refurbishment flows for silver-silver chloride reference electrodes are emerging as Chinese manufacturers recover precious metal content from decommissioned probes, reducing raw material draw from East Asian component suppliers. Production gravity centers on China for membrane electrode scaling, Germany for precision optical sensor assembly, and the United States for NIST-traceable calibration standard production. Critical input dependencies span silver wire for reference systems, specialty glass for pH electrodes, and fluoropolymer membranes for dissolved oxygen probes. Single-source vulnerability concentrates in East Asian silver-silver chloride suppliers, exposing meter assemblers to input volatility. Distribution runs through authorized service networks for laboratory-grade systems and direct municipal contracting for portable fleet deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Water Testing Meter Market functions as a stable compounder, with regulatory detection limit tightening across EPA and EU mandates ensuring replacement cycle continuity regardless of macroeconomic fluctuations.
For Market Incumbents: Deploy cloud-connected calibration service bundling to lock in recurring revenue streams against emerging meter-as-a-service entrants. Incumbents should consolidate aftermarket service networks through targeted acquisitions, capturing environmental agency procurement shifts away from manufacturer-tied maintenance agreements. Silver-silver chloride supply concentration represents a critical vulnerability; backward integration into reference electrode production or dual-sourcing partnerships with Chinese membrane electrode specialists mitigates single-source exposure. For New Entrants and Emerging Players: Small-to-medium municipal utilities in India's Jal Jeevan Mission expansion present the most penetrable buyer archetype, with BIS standards alignment creating procurement windows for portable multiparameter units priced below premium optical tiers. Agricultural irrigation monitoring in Brazil and Southeast Asia offers secondary white-space, where dissolved oxygen and pH verification for intensive aquaculture lacks incumbent saturation. A direct-to-utility sales model with localized calibration partnerships bypasses established distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional assemblers importing East Asian reference electrodes, where margin compression from Chinese membrane electrode scaling has depressed earnings multiples without impairing long-term demand fundamentals. Target acquisition archetypes include electrochemical specialists with captive sensor production and ISO 17025-accredited service networks. The signal to watch is EPA enforcement intensity around lead and PFAS detection mandates, which accelerates municipal upgrade cycles and expands addressable market for digital platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Calibration Service Launch | Environmental agencies in the United States are unbundling after-sales service from hardware procurement, creating recurring revenue opportunities. |
| Membrane Electrode Capacity Expansion | Chinese domestic manufacturers scaling output aggressively compress unit economics for dissolved oxygen and ion-selective probes. |
| Multiparameter Platform Integration | Operators seek to reduce instrument count and streamline workflow across drinking water testing and wastewater analysis applications. |
| ISO 17025 Accreditation Investment | Laboratory procurement specifications require documented calibration trails that extend sales cycles for qualified suppliers. |
| Optical Sensor R&D Partnership | German wastewater treatment operators absorb fluorescence-based dissolved oxygen premiums for reduced maintenance intervals. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal utility procurement officers, environmental agency fleet managers, pharmaceutical QC lab directors, electrochemical sensor manufacturing engineers, and aftermarket calibration service providers with secondary validation against EPA enforcement databases, EU Drinking Water Directive implementation reports, SEC 10-K filings from diversified instrumentation conglomerates, and Chinese GB standards documentation. Bottom-up segment sizing triangulated against top-down regulatory mandate impact modeling.
Segment-weighting approaches distributed value and volume across product type, technology platform, end-user category, and application, with additional granularity for regulatory compliance tier and calibration service attachment. CAGRs were derived from replacement cycle analysis tied to EPA and EU mandate implementation timelines, cross-referenced with municipal capital expenditure patterns and pharmaceutical facility expansion pipelines. Forecast inputs incorporated membrane electrode cost curves from Chinese manufacturing scaling and optical sensor adoption elasticity in premium wastewater treatment applications.
Underlying measurement precision varies by segment; laboratory-grade bench systems with NIST-traceable calibration carry tighter precision than portable field-deployable units. Forecasts reflect assumptions around regulatory enforcement intensity, silver price volatility for reference electrode production, and Chinese export policy continuity for membrane components. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market
Water and Wastewater Treatment
Ecological Wastewater Treatment Market
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Water Aeration System Market
Water and Wastewater Treatment
Global Wastewater Diffused Aerator Market
Water and Wastewater Treatment
Latin America Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Commercial Atmospheric Water Generator Market
Water and Wastewater Treatment
Agricultural Wastewater Treatment Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Sewage Pump Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market