
 Global Enhanced Water Market | 2026-2036
Global Enhanced Water Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enhanced Water Market Analysis
Fitness enthusiasts and athletes is shifting toward electrolyte-enhanced and vitamin-fortified hydration as post-workout recovery routines gain mainstream adherence. PepsiCo, Inc. leverages its Gatorade distribution muscle to dominate sports-focused retail channels. The Coca-Cola Company competes through Smartwater and Vitaminwater brand extensions in convenience and grocery formats. Nestlé S.A. sustains premium positioning with mineral-enhanced offerings in European and Asian markets.
Enhanced water denotes potable water fortified with vitamins, minerals, electrolytes, plant extracts, or amino acids to deliver targeted physiological benefits beyond basic hydration, typically formulated with controlled osmolality and pH ranges for rapid absorption. Functional water and electrolyte water command the largest volume pools, while vitamin water captures premium margin concentration among health-conscious urban consumers. E-commerce channels are expanding fastest among distribution segments, though supermarkets retain dominant shelf-space control in mature markets.
The US FDA governs additive safety and health claim substantiation under Federal Food, Drug, and Cosmetic Act provisions, while EU EFSA mandates pre-market approval for novel functional ingredients through the Novel Food Regulation. Japan's Ministry of Health, Labour and Welfare maintains separate Foods for Specified Health Uses certification that shapes export eligibility for fortified beverages. Stakeholders must monitor evolving caffeine and sweetener thresholds across jurisdictions to anticipate reformulation requirements and label adaptation costs.

Market Dynamics
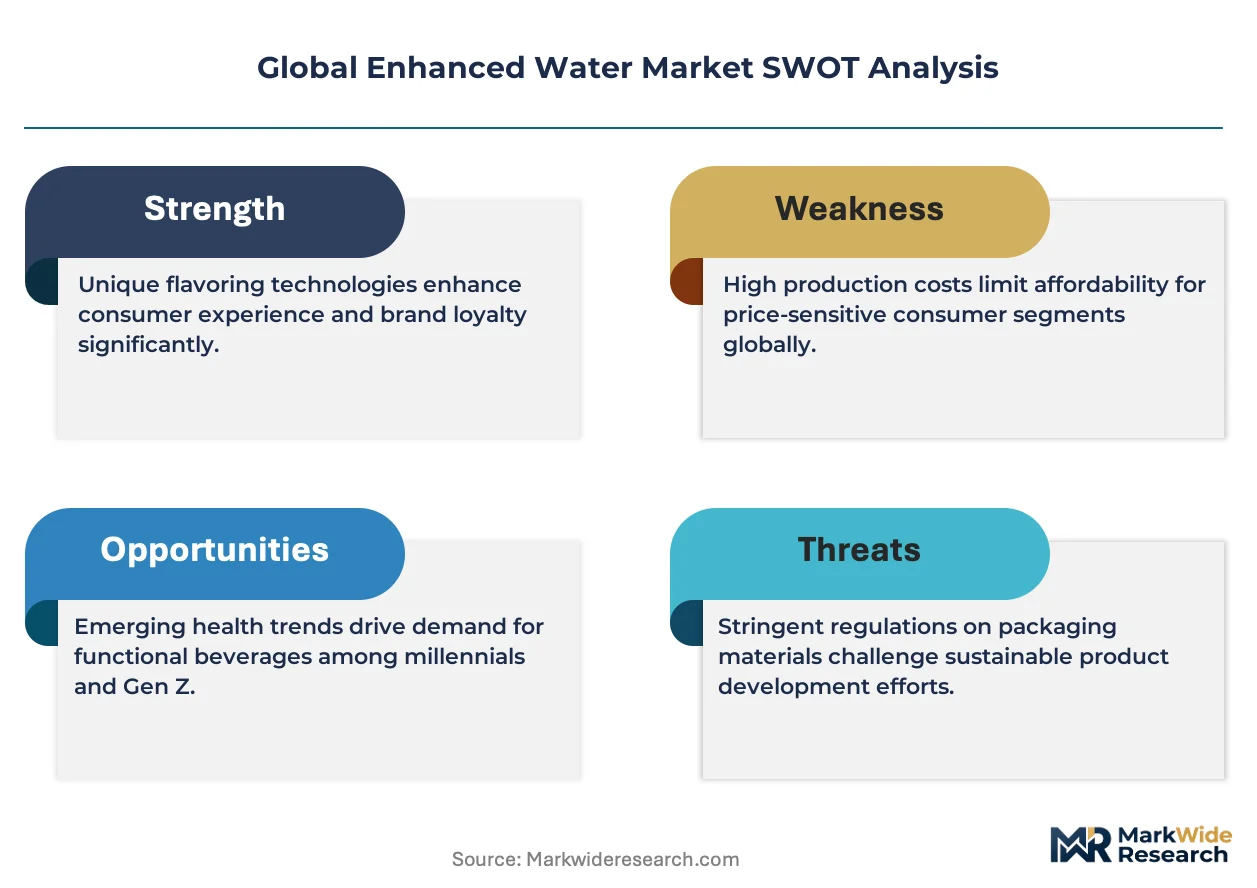
The enhanced water market is contending with divergent regulatory approval pathways for functional ingredients that fragment product standardization and force parallel formulation tracks across major jurisdictions.
Growth Catalysts
- EU Novel Food Regulation:Pre-market safety assessments for bioactive compounds are clarifying ingredient legitimacy, enabling faster European retail penetration for electrolyte-fortified lines.
- Fitness recovery protocols:Post-exercise hydration routines among amateur athletes are normalizing functional water as a training staple rather than a niche supplement.
- Mineral sourcing from Iceland:Volcanic filtration infrastructure is supplying distinct electrolyte profiles that command shelf-space premiums in German and Japanese convenience channels.
Market Restraints
- Bottle-grade PET resin volatility:Packaging input costs swing with crude oil derivatives, compressing margin predictability for mid-tier producers.
- Spring water source concentration:Premium aquifer access clusters in Alpine and Nordic territories, creating geographic supply vulnerability.
- EFSA health claim substantiation:The requirement for human intervention studies delays vitamin-fortified product launches by 18-24 months.
Strategic Opportunities
- India FSSAI functional beverage pathway:Emerging regulatory clarity is opening formal retail channels for electrolyte waters previously confined to informal distribution.
- Direct-to-subscription models:Replenishment algorithms tied to activity-tracker data are capturing recurring revenue from endurance sports participants.
- Plant-derived amino acid convergence:Fermentation-based L-carnitine and taurine synthesis is reducing reliance on petrochemical precursors.
Industry Challenges
- Food technologist scarcity:Formulation expertise spanning beverage osmolality, pH stability, and bioactive shelf-life remains concentrated with legacy soft-drink R&D teams.
- Multi-jurisdiction label adaptation:Simultaneous compliance with FDA nutrient content claims, EFSA health claims, and Japan FOSHU certification strains regulatory affairs bandwidth.
- Cold-chain last-mile integrity:Temperature-sensitive probiotic waters require refrigerated distribution infrastructure that conflicts with ambient logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enhanced Water Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Water, Flavored Water, Vitamin Water, Electrolyte Water Distribution Channel: Supermarkets, Health Stores, E-commerce, Convenience Stores End User: Athletes, Health-Conscious Consumers, Children, Fitness Enthusiasts Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | The Kraft Heinz Company, 4C Foods Corp., The Coca-Cola Company, Stur Drinks, Arizona Beverages USA, PepsiCo, Inc., Unilever PLC, Hydrant Inc., Nestlé S.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enhanced Water Market Emerging Trajectories
Formulation science and distribution infrastructure are diverging from mass-market beverage conventions toward precision-targeted physiological outcomes and channel-specific product architectures.
Electrolyte dosing technology is modularizing. Precision micro-dosing systems now allow single-base water SKUs to carry variable mineral payloads activated at point-of-consumption. Athletes and clinical hydration programs are adopting these configurable formats fastest. This architecture is compressing finished-goods inventory requirements while expanding customization revenue streams.
EU EFSA is tightening caffeine threshold enforcement for non-energy functional beverages. The industrial consequence is a wave of reformulation away from stimulant-adjacent positioning toward purely hydrational or recovery-focused claims. Vitamin-fortified still waters targeting German and French grocery channels are most affected, with several lines pivoting to magnesium and zinc emphasis.
Urban professionals are consolidating hydration purchases around subscription-replenishment models that displace impulse convenience-store buying. E-commerce platforms with predictive algorithms are capturing this behavioral shift fastest. This pattern is most visible in Tokyo, London, and New York metropolitan corridors where delivery density supports same-day fulfillment economics.
Global Enhanced Water Market Segmentation
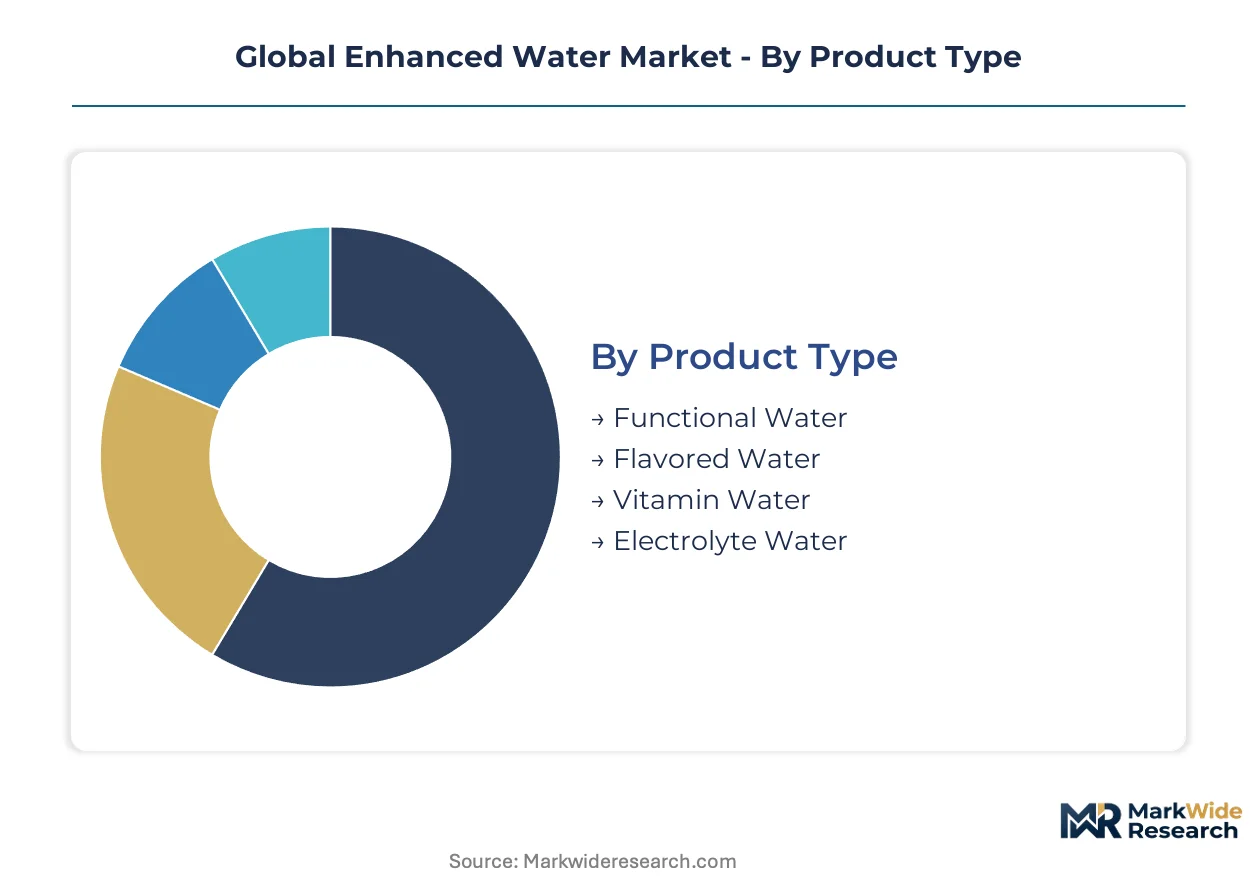
Enhanced water manufacturers navigate distinct demand profiles across product formulations, purchase occasions, and consumption contexts. Segmentation clarity enables targeted formulation investments and channel-specific distribution economics.
Product Type:
Formulation intensity and functional claim substantiation separate buyers by their willingness to pay for physiological outcomes beyond basic hydration.
- Functional Water:Fortified with plant extracts, amino acids, or adaptogens targeting stress reduction and cognitive performance. German and Japanese health stores stock these at premium shelf positions, though EFSA health claim substantiation requirements delay European launches.
- Electrolyte Water:Sodium, potassium, and magnesium formulations with controlled osmolality for rapid absorption. Athletes in the United States drive recurring bulk purchases through direct-to-subscription platforms tied to training load data.
- Flavored Water:Natural essence infusions without caloric sweeteners, appealing to consumers transitioning from sugary soft drinks. Shelf placement competes directly with carbonated alternatives in United States convenience channels.
- Vitamin Water:B-complex and antioxidant fortification targeting urban professionals seeking convenient micronutrient supplementation. Japanese FOSHU certification requirements shape export eligibility and label complexity.
Volume concentrates in electrolyte formulations; steepest expansion trajectory belongs to functional waters with adaptogenic positioning.
Distribution Channel:
Channel selection determines margin structure, temperature control requirements, and impulse versus planned purchase dynamics.
- Supermarkets:Dominant shelf-space control in mature markets with multi-SKU brand blocks driving trial. German and United States grocery chains demand slotting fees that disadvantage emerging regional players.
- E-commerce:Subscription algorithms and predictive replenishment capture endurance sports participants in Tokyo, London, and New York metropolitan corridors. Cold-chain fulfillment infrastructure limits probiotic water expansion.
- Health Stores:Curated assortments emphasizing clean-label certifications and novel bioactive ingredients. Staff recommendation influence sustains premium pricing power.
- Convenience Stores:Impulse purchase velocity with grab-and-go refrigeration. Single-serve pricing premiums offset lower basket values in Japanese and United States urban locations.
Supermarkets anchor current revenue; e-commerce climbs fastest as replenishment algorithms displace convenience-store impulse buying.
End User:
Consumption occasion and physiological need intensity create divergent formulation and packaging requirements.
- Fitness Enthusiasts:Post-workout recovery routines normalize functional water as training staples rather than niche supplements. Magnesium and zinc emphasis is displacing caffeine-adjacent positioning under tightening EFSA thresholds.
- Athletes:Amateur and professional competitors requiring precise electrolyte replacement with batch-tested purity. Precision micro-dosing systems allow configurable mineral payloads activated at point-of-consumption.
- Health-Conscious Consumers:Urban professionals consolidating hydration purchases around subscription models. Clean-label demands pressure reformulation away from synthetic vitamins toward fermentation-derived alternatives.
- Children:Parental purchasing decisions prioritize reduced sugar content and recognizable ingredient lists. Portion-controlled packaging formats and flavor profiles adapted to pediatric palates.
Fitness enthusiasts generate the largest addressable base; athlete segments command the highest per-liter pricing through precision formulation.
Packaging Type:
Material selection balances shelf stability, sustainability signaling, and cold-chain infrastructure compatibility.
- Bottles:Bottle-grade PET resin dominates mass-market volumes despite crude oil derivative cost volatility. Recycled content claims increasingly influence German and Japanese purchase decisions.
- Tetra Packs:Aseptic carton formats for ambient-stable functional waters with extended distribution reach. Lightweight logistics advantages in emerging markets with underdeveloped refrigeration infrastructure.
- Cans:Aluminum formats gaining share in sparkling functional water variants. Infinite recyclability messaging resonates with United States sustainability-conscious demographics.
- Pouches:Flexible formats for single-serve on-the-go consumption with reduced material intensity. Limited to ambient-stable formulations without probiotic or temperature-sensitive ingredients.
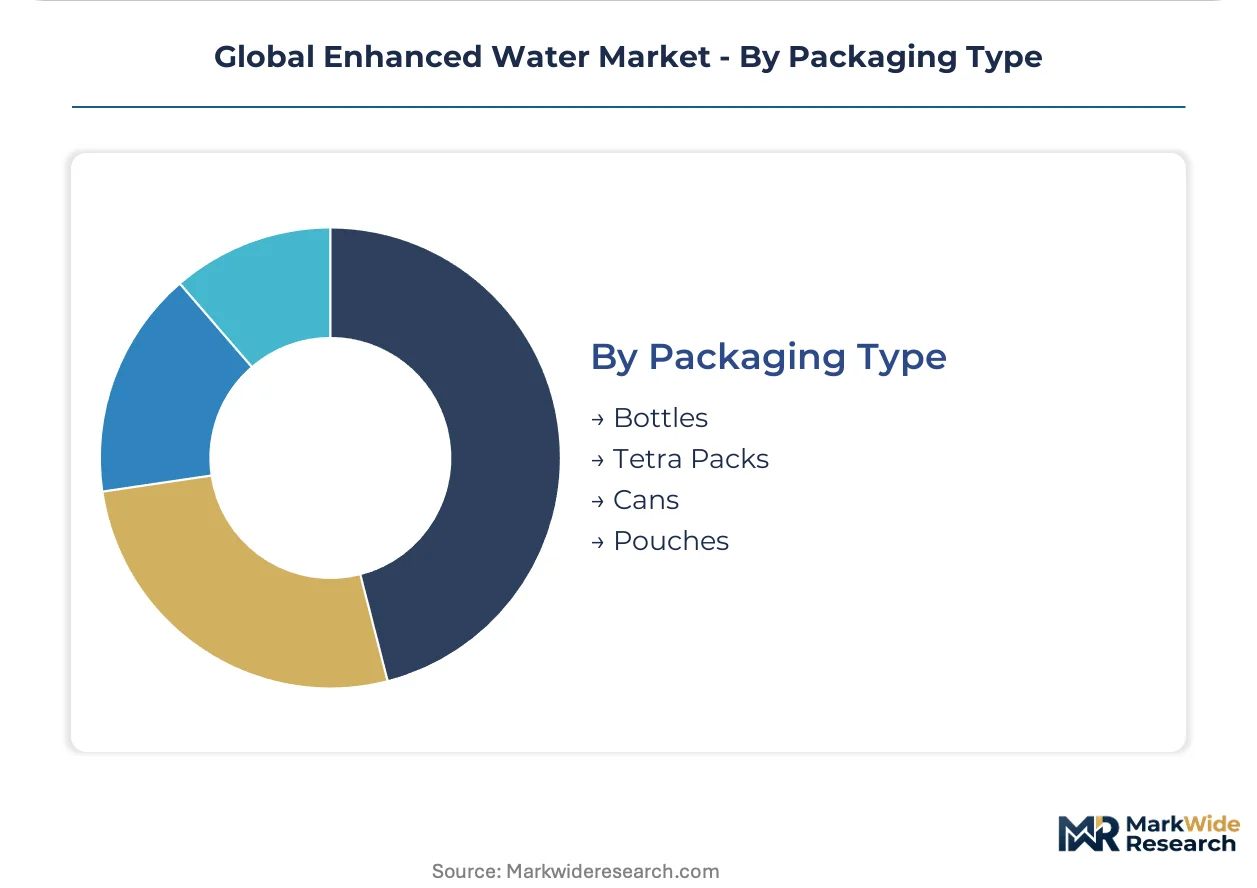
Bottles retain volume leadership; cans gain fastest in sparkling sub-segments as aluminum sustainability credentials displace PET perception.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Dubai and Singapore concentrate bottling infrastructure for Asia-Pacific re-export. Tax incentives in Bavaria and North Rhine-Westphalia anchor German mineral extraction and formulation R&D. Special economic zones in Shenzhen and Ningbo support China's contract manufacturing dominance for functional beverage exports.
United States
Fitness culture and direct-to-consumer subscription models drive electrolyte water demand across metropolitan corridors. The FDA governs additive safety and health claim substantiation under Federal Food, Drug, and Cosmetic Act provisions. Austin and Denver host emerging formulation startups targeting endurance sports participants with precision-dosing technologies.
Germany
Clean-label preferences and mineral water heritage sustain premium positioning for functional variants in grocery and convenience channels. EFSA mandates pre-market approval for novel functional ingredients through the Novel Food Regulation. The Rhine-Main region clusters beverage R&D facilities serving both domestic retail and export markets.
Japan
Aging demographics and workplace wellness programs expand demand for vitamin-fortified and stress-reduction formulations. The Ministry of Health, Labour and Welfare maintains Foods for Specified Health Uses certification shaping export eligibility. Tokyo and Osaka metropolitan areas concentrate subscription-model adoption among urban professionals.
China
Rising health consciousness and e-commerce penetration accelerate functional water trial among middle-class consumers. SAMR oversees food safety and novel ingredient approvals under national standards. The Yangtze River Delta hosts contract manufacturers supplying both domestic brands and export markets.
India
Amateur sports participation and urban hydration awareness expand addressable demand beyond traditional soft drinks. FSSAI is clarifying functional beverage regulatory pathways previously confined to informal distribution. Mumbai and Bangalore emerge as test markets for electrolyte water subscription services.
Global Enhanced Water Market Vendor Landscape
Top-tier vendors anchor mass-market distribution through grocery and convenience dominance, while mid-tier specialists carve premium positions via health-store channels and direct-to-consumer platforms. The vendor base clusters around three strategic archetypes: diversified beverage conglomerates with cross-category leverage, mineral-water heritage players with sourcing advantages, and digital-native entrants with subscription-first business models. Competitive moves center on portfolio diversification into adjacent functional categories and geographic expansion through regional licensing agreements.
Within the diversified beverage conglomerate tier, PepsiCo, Inc. and The Coca-Cola Company occupy positions exemplifying scale-driven channel control, while Nestlé S.A. represents mineral-heritage premium positioning. These entities anchor competitive dynamics through existing retail relationships and formulation infrastructure rather than pure-play functional water specialization.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| 4C Foods Corp. |
| The Coca-Cola Company |
| Stur Drinks |
| Arizona Beverages USA |
| PepsiCo, Inc. |
| Unilever PLC |
| Hydrant Inc. |
| Nestlé S.A |
| Others |
Supply Flow & Price Mechanics
Premium-mid-economy pricing differentiation separates Icelandic volcanic-filtered electrolyte waters from commodity PET-bottled alternatives, with certification ladders and cold-chain requirements driving parallel supply chain investments across German and Japanese retail channels. Subscription-based replenishment algorithms in United States metropolitan corridors compress margin predictability for spot-market entrants while rewarding vertically integrated mineral extractors with long-term offtake stability.
Pricing Analysis
Short lead-time premiums attach to precision micro-dosing formats activated at point-of-consumption, while spot inventory of standard electrolyte formulations trades at discounted rates in United States convenience channels. Pricing stratifies across premium, standard, and economy tiers based on mineral sourcing provenance and EFSA health claim substantiation status. Price differentiation stems from clean-label certification levels and cold-chain logistics requirements. Cost compression in mid-tier PET-bottled segments intensifies due to crude oil derivative volatility. Amateur athletes and fitness enthusiasts demonstrate highest price sensitivity, while clinical hydration programs and endurance competitors accept premium positioning for batch-tested purity.
Supply Chain Analysis
Food technologist scarcity in the Rhine-Main region and Austin-Denver corridor constrains formulation capacity expansion for precision-dosing startups competing against legacy soft-drink R&D teams. Manufacturing gravity centers on Germany, Japan, and the United States for mineral extraction and beverage formulation, with contract manufacturing clusters in China's Yangtze River Delta serving export markets. Raw material dependencies include bottle-grade PET resin, volcanic-filtered mineral concentrates, and fermentation-derived amino acid precursors. Single-source vulnerability in Alpine and Nordic aquifer access threatens premium mineral supply security. Distribution runs through supermarket slotting-fee gatekeepers in mature markets and direct-to-subscription platforms in metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure mounts as multi-jurisdiction label adaptation costs and EFSA health claim substantiation timelines force smaller regional brands toward acquisition or exit. Regulatory affairs bandwidth constraints and formulation expertise concentration favor scaled players with legacy beverage infrastructure.
For Market Incumbents: Anticipate EFSA caffeine threshold enforcement by accelerating magnesium and zinc formulation pivots ahead of stimulant-adjacent positioning bans. Acquire precision micro-dosing technology capabilities in Austin and Denver startup clusters to defend against subscription-native entrants. Channel control through direct-to-consumer replenishment algorithms anchored in activity-tracker data represents the critical defensive lever.
For New Entrants and Emerging Players: Launch via health-store curated assortments in German and Japanese markets where staff recommendation influence sustains premium pricing power and slotting-fee barriers are lower than supermarket channels. Target India's emerging FSSAI-compliant formal retail channels previously confined to informal electrolyte water distribution. White-space opportunity concentrates in plant-derived amino acid formulations with fermentation-based L-carnitine and taurine synthesis reducing petrochemical precursor reliance.
For Investors and Strategic Acquirers: Re-rating potential sits with mineral-water heritage players possessing captive Icelandic volcanic filtration infrastructure given shelf-space premium capture in German and Japanese convenience channels. Long-term viability over the coming decade hinges on backward integration into mineral sourcing and formulation R&D rather than pure-play brand marketing. Acquisition target archetype: regional electrolyte specialists with established FOSHU certification in Japan or Novel Food approval in Europe. Monitor FSSAI regulatory clarity in India as inflection indicator for emerging market formalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Micro-Dosing Technology Acquisition | Captures configurable mineral payload revenue from endurance athletes and clinical hydration programs. |
| Direct-to-Consumer Subscription Platform Launch | Displaces impulse convenience-store buying through predictive replenishment algorithms in Tokyo and New York corridors. |
| Icelandic Mineral Source Backward Integration | Secures distinct electrolyte profiles commanding shelf-space premiums in German and Japanese retail channels. |
| EFSA Health Claim Substantiation Investment | Accelerates European market entry for adaptogenic functional waters delayed by human intervention study requirements. |
| FSSAI Regulatory Compliance Pathway Development | Opens formal retail channels for electrolyte waters previously confined to informal Indian distribution networks. |
Methodological Framework
Multi-period observation of EFSA Novel Food approval timelines, FSSAI regulatory pathway developments, and subscription-platform adoption rates anchored the trend analysis, supplemented by interviews with beverage formulation R&D directors, health-store category buyers, electrolyte brand managers, and cold-chain logistics operators. Secondary validation drew from FDA additive safety filings, EFSA health claim registers, Japan FOSHU certification databases, and Nielsen retail audit data across United States, German, and Japanese metropolitan corridors. Bottom-up SKU-level volume aggregation triangulated against top-down category expenditure estimates from national beverage trade associations.
Segment-weighting across product type, distribution channel, end user, and packaging format dimensions structured the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating mineral sourcing cost trajectories and regulatory approval velocity differentials. Forecast inputs included PET resin price volatility indices and precision-dosing technology penetration assumptions across endurance sports participant demographics.
The model assumes a particular technology adoption path; alternative pathways for point-of-consumption micro-dosing activation would alter the outlook for traditional ready-to-drink formulation economics. Forecasts reflect assumptions regarding EFSA enforcement consistency and FSSAI formalization timelines. Material deviation in regulatory approval velocity or crude oil derivative pricing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Agricultural Wastewater Treatment Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Packaged Wastewater Treatment Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Commercial Atmospheric Water Generator Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Global Biological Wastewater Treatment Market
Water and Wastewater Treatment
Mobile Wastewater Treatment Plant Market
Water and Wastewater Treatment
Javelle Water Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market