
 Ecological Wastewater Treatment Market | 2026-2036
Ecological Wastewater Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ecological Wastewater Treatment Market Foresight
China's Yangtze River Delta is reshaping supply patterns through aggressive membrane bioreactor manufacturing scale-up. Veolia Water Technologies leverages its European engineering heritage to dominate high-complexity industrial installations. Xylem anchors North American utility relationships with smart monitoring integration. Kurita Water Industries specializes in compact bioreactor systems for Asia-Pacific chemical clusters.
Ecological wastewater treatment deploys constructed wetlands, membrane bioreactors, and advanced biological processes to remove contaminants through natural or biomimetic pathways, typically achieving biochemical oxygen demand reduction below 20 mg/L for sensitive discharge environments. The technology serves municipalities and industries seeking compliance with stringent effluent standards without energy-intensive mechanical infrastructure. Constructed wetlands occupy the largest installed base due to minimal operating expenditure and proven performance in tropical climates. Membrane bioreactors represent the fastest-expanding segment as food processors and pharmaceutical manufacturers pursue water reuse targets. Biological treatment methods command premium pricing where operators lack land availability for passive systems.
The EPA enforces effluent limitation guidelines that compel U.S. power utilities and meat processors toward nutrient-removal technologies. The EU Urban Wastewater Treatment Directive revision tightens phosphorus and nitrogen thresholds, redirecting municipal capex toward ecological upgrades. China's MEE implements river basin total pollutant load controls that restrict conventional activated sludge expansions in water-stressed provinces. Stakeholders must weigh biological process reliability against climate volatility when selecting between passive wetland and intensified bioreactor architectures.
Market Dynamics
Membrane bioreactor manufacturing scale-up in China's Yangtze River Delta is compressing equipment lead times and forcing European engineering firms to defend premium positioning through performance guarantees rather than brand heritage alone.
Growth Catalysts
- EU Urban Wastewater Treatment Directive:Municipal utilities in Germany are expanding constructed wetlands capacity to meet tightened phosphorus discharge thresholds. Passive biological systems command preference where land availability permits.
- Zero-liquid-discharge mandates:India's national pollution control board enforcement in the Tiruppur textile belt is accelerating membrane bioreactor deployments for water reuse. Processors face facility closure for non-compliance.
- Membrane manufacturing:Domestic production lines in Jiangsu province are reducing bioreactor membrane import dependency. Cost curves are flattening for submerged hollow-fiber configurations.
Market Restraints
- Specialized biofilm media supply:Carrier material for moving bed bioreactors concentrates among three German chemical suppliers. Freight costs from Rhineland plants add 12-18% to Asian project budgets.
- Polymer price volatility:PVDF and PES membrane feedstock costs fluctuate with fluorochemical availability. Chinese environmental ministry restrictions on PFAS precursor production tighten raw material access.
- Constructed wetlands land intensity:Passive systems require 2-5 square meters per population equivalent. Urban municipalities in Japan and South Korea lack developable parcels for tertiary treatment expansion.
Strategic Opportunities
- Southeast Asia industrial parks:Vietnam's processing zones along the Dong Nai River lack centralized biological treatment. Build-operate-transfer contracts for textile and electronics clusters offer 15-20 year revenue visibility.
- Constructed wetland-nutrient recovery convergence:Hybrid systems harvesting phosphorus from wetland biomass are qualifying for EU Green Deal circular economy subsidies. Fertilizer offtake agreements with agricultural cooperatives improve project returns.
- Smart monitoring integration:Dissolved oxygen and turbidity sensors with cloud-based predictive control are opening retrofits of 1990s-era activated sludge plants. North American utilities prioritize operational expenditure reduction over capital replacement.
Industry Challenges
- Process engineering talent scarcity:Design of integrated anaerobic-aerobic configurations requires specialized expertise in microbial kinetics. European technical universities produce fewer graduates than retirement rates in water sector consultancies.
- Legacy SCADA integration:Bioreactor automation platforms must interface with 1980s-era municipal control systems. Protocol translation adds commissioning delays and cybersecurity exposure.
- Performance guarantee enforcement:Constructed wetlands exhibit seasonal efficiency variation. Contractors face liquidated damages disputes when tropical storm events disrupt treatment performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ecological Wastewater Treatment Market |
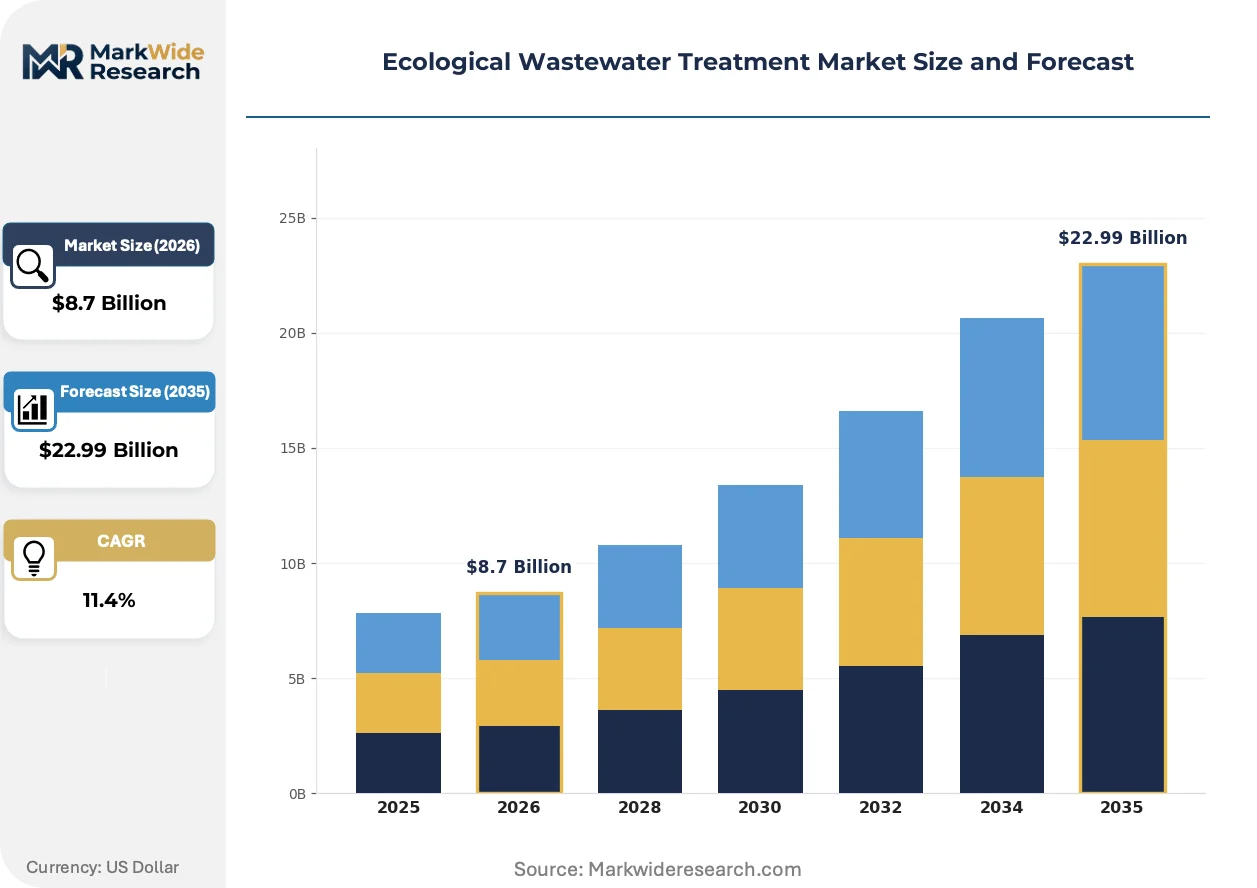
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Constructed Wetlands, Bioreactors, Membrane Bioreactors, Aerobic Treatment Application: Industrial Wastewater, Municipal Wastewater, Agricultural Runoff, Residential Applications Treatment Method: Physical Treatment, Chemical Treatment, Biological Treatment, Advanced Oxidation End User: Chemical Industry, Food Processing, Textile Sector, Energy Sector |
| Companies Covered | Evoqua Water Technologies, Thermax, Veolia Water Technologies, Acciona, Microvi Biotech, SUEZ, Epic Cleantec, Kurita Water Industries, Xylem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ecological Wastewater Treatment Market Shifts & Advancements
Biological treatment architectures are converging with digital control systems and circular resource recovery, compressing the traditional separation between passive ecological processes and intensified mechanical platforms.
Smart sensor networks is digitizing operational oversight across distributed wetland arrays and centralized bioreactor facilities. Dutch water authorities are deploying fiber-optic dissolved oxygen probes with machine-learning calibration in the Rhine-Meuse delta. Real-time performance visibility is compressing response latency for process upsets from days to hours.
The EU Urban Wastewater Treatment Directive revision tightens total nitrogen thresholds to 10 mg/L for sensitive catchments. Municipal operators in the Netherlands and Denmark are retrofitting denitrifying filters ahead of existing activated sludge trains. Capital programs are prioritizing biological nutrient removal over chemical precipitation to reduce ferric chloride consumption.
Water reuse certification is restructuring procurement criteria for food and beverage processors. Unilever and Nestlé manufacturing sites in water-stressed Spanish provinces now require tertiary biological treatment with pathogen log-reduction validation. Equipment vendors are bundling performance-based service contracts rather than discrete hardware sales to capture recurring revenue streams.
Ecological Wastewater Treatment Market Segmentation
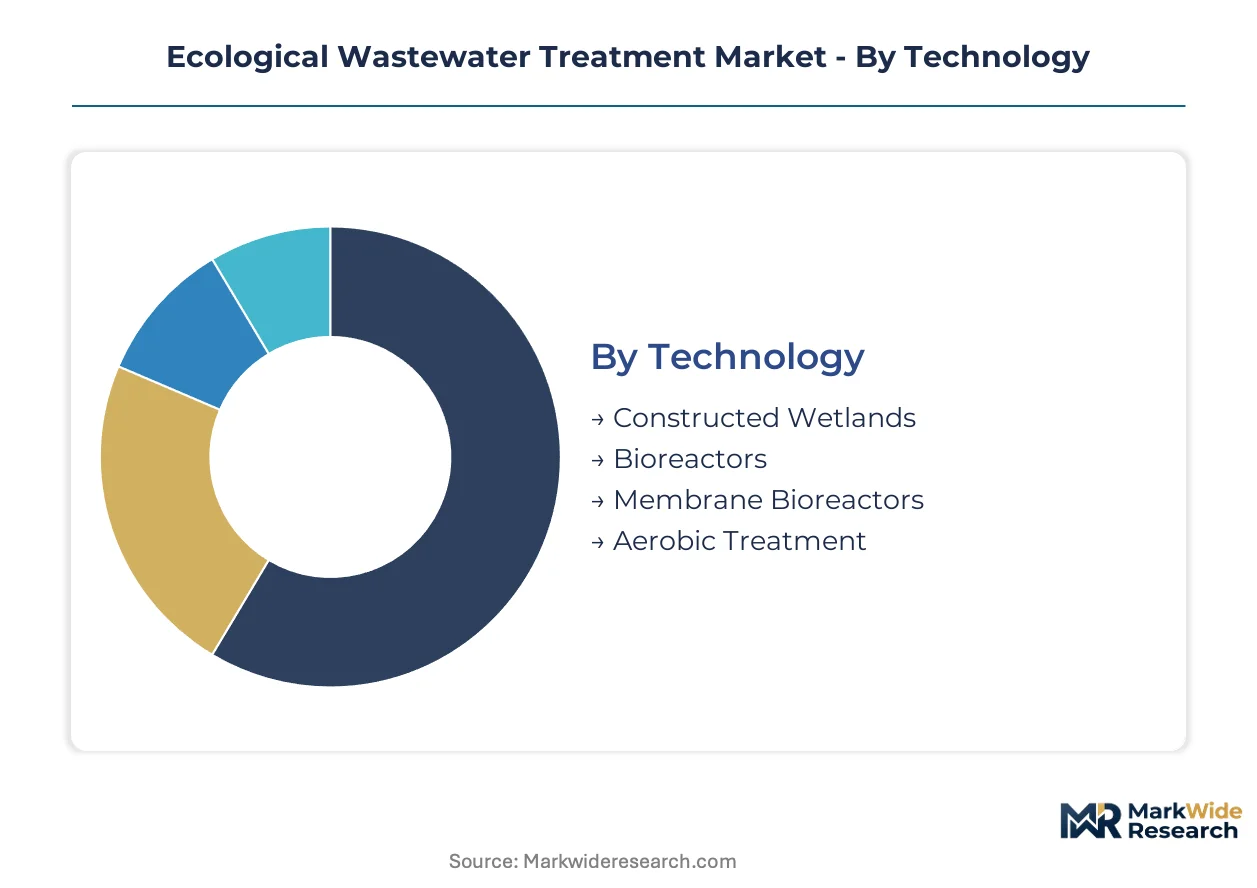
Technology selection in ecological wastewater treatment hinges on land availability, effluent stringency, and operational sophistication. Cycle times vary dramatically: passive wetland systems operate for decades with minimal intervention, while membrane bioreactors demand 5-7 year membrane replacement schedules. Understanding these temporal dynamics helps operators match capital deployment to regulatory horizons.
Technology:
Replacement cycles separate slow-turnover passive systems from fast-depreciating intensified platforms. Membrane bioreactors require capital refresh every half-decade, while constructed wetlands amortize over 25-30 years.
- Constructed Wetlands:Engineered ecosystems utilizing soil, vegetation, and microbial communities to filter contaminants through gravity-driven hydraulic pathways. German municipal utilities under the EU Urban Wastewater Treatment Directive are expanding wetland capacity where land permits, driven by phosphorus discharge thresholds that passive systems meet without chemical dosing.
- Membrane Bioreactors:Hybrid systems combining suspended-growth bioreactors with micro- or ultrafiltration membranes for direct solids separation. China's Yangtze River Delta manufacturing clusters are absorbing the steepest expansion trajectory as food processors and pharmaceutical manufacturers pursue water reuse certification.
- Bioreactors:Contained vessels optimizing microbial degradation through controlled aeration and retention time. Compact configurations serve Asia-Pacific chemical clusters with limited footprint availability.
- Aerobic Treatment:Oxygen-dependent biological oxidation of organic pollutants in activated sludge or trickling filter configurations. Legacy installations dominate North American municipal infrastructure.
Constructed wetlands dominate installed base. Membrane bioreactors are where expansion concentrates.
Application:
Revenue concentration tilts toward industrial discharge compliance where enforcement carries facility closure risk. Municipal procurement moves slower but offers contract duration advantages.
- Industrial Wastewater:Process-integrated treatment for manufacturing effluent containing heavy metals, organics, or nutrients. India's Tiruppur textile belt is absorbing membrane bioreactor deployments under zero-liquid-discharge mandates enforced by the national pollution control board.
- Municipal Wastewater:Centralized biological treatment for urban sewage networks. Dutch water authorities are retrofitting denitrifying filters ahead of activated sludge trains to meet EU total nitrogen thresholds of 10 mg/L.
- Agricultural Runoff:Nutrient capture from fertilizer-laden drainage before watershed discharge. Constructed wetlands treat phosphorus loading from concentrated animal feeding operations in the US Midwest.
- Residential Applications:Decentralized septic replacement and cluster treatment for unsewered developments. Package plants serve exurban communities in water-stressed Spanish provinces.
Industrial wastewater commands premium pricing. Municipal contracts anchor long-term revenue visibility.
Treatment Method:
Biological platforms are displacing chemical precipitation as operators seek to reduce ferric chloride consumption and sludge handling costs. Advanced oxidation remains niche due to energy intensity.
- Biological Treatment:Microbial metabolism of organic and nitrogenous pollutants through engineered ecosystems or suspended-growth reactors. The EU Urban Wastewater Treatment Directive revision is redirecting municipal capex toward biological nutrient removal.
- Advanced Oxidation:Hydroxyl radical generation for recalcitrant compound destruction. Pharmaceutical manufacturers deploy UV-ozone hybrids for active pharmaceutical ingredient elimination.
- Physical Treatment:Screening, sedimentation, and filtration for solids and grit removal. Preliminary stages protect downstream biological processes.
- Chemical Treatment:Coagulation, flocculation, and precipitation for phosphorus and suspended solids removal. Ferric chloride dosing faces cost pressure from supply chain volatility.
Biological treatment captures the largest project pipeline. Advanced oxidation is climbing fastest in pharmaceutical discharge applications.
End User:
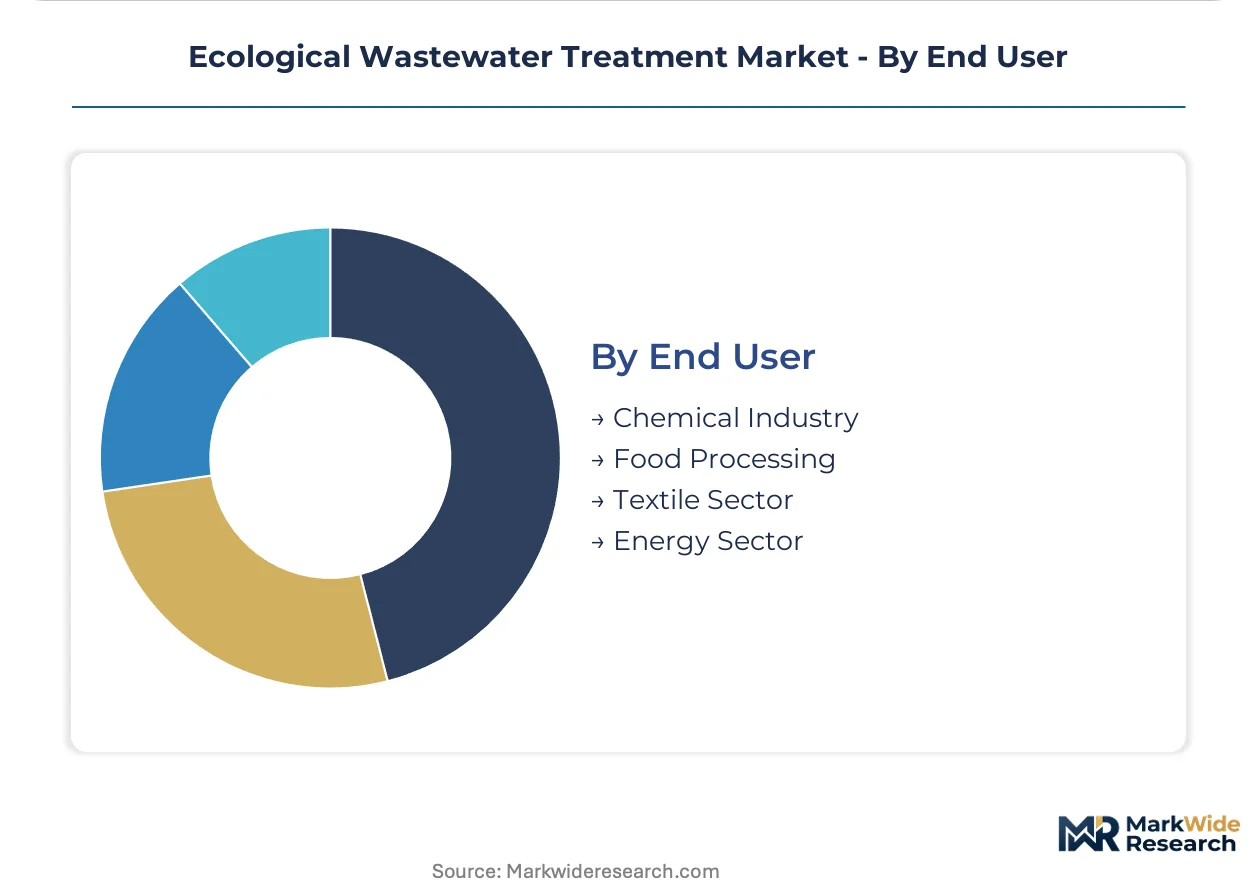
Food and beverage processors are restructuring procurement around water reuse certification, while energy sector demand concentrates on cooling tower blowdown treatment.
- Food Processing:High-strength organic wastewater from dairy, meat, and beverage operations with nutrient loading challenges. Unilever and Nestlé manufacturing sites in water-stressed Spanish provinces now require tertiary biological treatment with pathogen log-reduction validation.
- Textile Sector:Dye-laden effluent with recalcitrant organics and heavy metals. India's national pollution control board enforcement is accelerating membrane bioreactor adoption for zero-liquid-discharge compliance.
- Chemical Industry:Complex effluent with variable pH, toxicity, and biodegradable fraction. Asia-Pacific chemical clusters favor compact bioreactor systems.
- Energy Sector:Cooling water, produced water, and flue gas desulfurization wastewater. US power utilities face EPA effluent limitation guidelines compelling nutrient-removal technology adoption.
Food processing leads contract value. Textile sector compliance deadlines are driving the steepest near-term demand spike.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany favors passive constructed wetlands for municipal phosphorus compliance, while China and India pursue membrane-intensive industrial reuse. This consumption-mix differential reflects land availability constraints against zero-discharge enforcement pressure.
United States
EPA effluent limitation guidelines compel power utilities and meat processors toward nutrient-removal biological systems. The Clean Water Act enforcement prioritizes phosphorus and nitrogen thresholds in Chesapeake Bay and Great Lakes watersheds. Midwest concentrated animal feeding operations deploy constructed wetlands for agricultural runoff phosphorus capture.
Germany
Municipal utilities expand constructed wetlands capacity under tightened EU Urban Wastewater Treatment Directive phosphorus discharge thresholds. The Rhineland hosts three specialized suppliers of moving bed bioreactor carrier media. North Rhine-Westphalia water authorities retrofit denitrifying filters ahead of activated sludge trains for total nitrogen compliance.
China
Dual carbon goals accelerate membrane bioreactor deployments in Jiangsu province manufacturing clusters. MEE river basin total pollutant load controls restrict conventional activated sludge expansions in water-stressed provinces. Yangtze River Delta food processors and pharmaceutical manufacturers absorb the steepest bioreactor capacity expansion.
India
National pollution control board zero-liquid-discharge mandates drive membrane bioreactor adoption in Tiruppur textile belt. Facility closure threats enforce compliance deadlines for dye-laden effluent treatment. Processors face capital deployment pressure as enforcement timelines compress.
Netherlands
Dutch water authorities deploy fiber-optic dissolved oxygen probes with machine-learning calibration in Rhine-Meuse delta wetland arrays. EU total nitrogen thresholds of 10 mg/L for sensitive catchments redirect municipal capex toward biological nutrient removal. Denitrifying filter retrofits ahead of existing activated sludge trains dominate capital programs.
Ecological Wastewater Treatment Market Competitive Landscape
Capability concentration sits with European engineering heritage firms; scale advantage sits with Asia-Pacific manufacturing specialists. The market structures around three tiers: full-service multinationals, regional technology licensors, and compact system fabricators. Strategic archetypes include performance-guarantee defenders, membrane manufacturing scale-up players, and smart monitoring integrators. Dominant competitive moves center on manufacturing localization and outcome-based service contracting.
Within the full-service multinational tier, Veolia Water Technologies and SUEZ occupy positions anchored by European engineering heritage and municipal relationship depth. Xylem exemplifies the smart monitoring integration archetype through North American utility platform deployment. Kurita Water Industries represents compact bioreactor specialization for Asia-Pacific chemical cluster constraints.
| Leading Market Players |
|---|
| Evoqua Water Technologies |
| Thermax |
| Veolia Water Technologies |
| Acciona |
| Microvi Biotech |
| SUEZ |
| Epic Cleantec |
| Kurita Water Industries |
| Xylem |
| Others |
Supply & Pricing Matrix
Jiangsu province membrane manufacturing clusters compress equipment lead times and redistribute pricing power toward domestic Chinese suppliers, forcing European engineering firms to defend premium positioning through performance guarantees rather than brand heritage alone.
Pricing Analysis
Chinese domestic membrane production compresses price spreads between Jiangsu-manufactured submerged hollow-fiber configurations and imported European alternatives. Three-tier pricing structure across performance-guaranteed, standard-specification, and economy-tier equipment separates municipal utilities with long-term service contracts from industrial buyers optimizing capital expenditure. Pricing pressure stems from domestic manufacturing scale-up in the Yangtze River Delta. Municipal wastewater utilities exhibit highest price sensitivity due to budget cycle constraints, while pharmaceutical manufacturers pursuing water reuse certification show lowest sensitivity.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk for moving bed bioreactor carrier media, where three Rhineland chemical suppliers control specialized biofilm material production. Component sourcing draws from Germany for engineered media, China for membrane modules, and Japan for precision sensors. Single-source vulnerability concentrates in fluorochemical feedstock for PVDF membranes following Chinese environmental ministry PFAS precursor restrictions. Distribution runs through engineering-procurement-construction contractors for industrial projects and direct municipal procurement for utility-scale installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ecological wastewater treatment is restructuring toward service-attach revenue models, with smart monitoring integration and membrane replacement service contracts expanding faster than discrete hardware sales.
For Market Incumbents: Pre-empt membrane manufacturing localization by establishing Jiangsu province fabrication partnerships or captive production lines. Defend European municipal relationships by bundling predictive maintenance software with constructed wetland performance guarantees. Vertical integration into hollow-fiber membrane production hedges against Chinese supply disruption.
For New Entrants and Emerging Players: Pursue Southeast Asia industrial park build-operate-transfer contracts, where Vietnam's Dong Nai River processing zones lack centralized biological treatment infrastructure. Target textile clusters in Tiruppur with compact membrane bioreactor systems optimized for zero-liquid-discharge compliance timelines. Lead with outcome-based service contracts rather than capital equipment sales.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because tightening EU Urban Wastewater Treatment Directive thresholds and China's MEE river basin controls create durable demand visibility. Acquire compact bioreactor specialists with Asia-Pacific chemical cluster relationships. Watch membrane replacement cycle timing as an inflection indicator for recurring revenue conversion.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Manufacturing Localization | Jiangsu province production lines reduce import dependency for Yangtze River Delta food processors. |
| Smart Monitoring Platform Integration | Dutch water authorities deploy fiber-optic dissolved oxygen probes with machine-learning calibration. |
| Constructed Wetland-Nutrient Recovery Convergence | EU Green Deal circular economy subsidies qualify phosphorus harvesting from wetland biomass. |
| Outcome-Based Service Contracting | Unilever and Nestlé manufacturing sites in Spanish provinces require performance-based validation. |
| Denitrifying Filter Retrofit Programs | Dutch and Danish municipal operators meet EU total nitrogen thresholds ahead of activated sludge trains. |
Research Methodology
A standing panel of municipal utility planning officers, industrial plant engineers, membrane manufacturing procurement leads, and EPC contractor project managers provided ongoing calibration across primary interviews and secondary validation. Bottom-up and top-down triangulation combined regulatory filing analysis from EPA and EU Urban Wastewater Treatment Directive implementation reports, customs trade data for membrane module imports, and municipal capital expenditure disclosures. Secondary sources included MEE river basin pollutant load control announcements, industry association technology deployment surveys, and equipment vendor service contract filings.
Scenario-bracketing framed projections across technology selection, application stringency, and regional enforcement intensity dimensions. Segmentation modeling spanned constructed wetlands, membrane bioreactors, and compact bioreactor architectures against municipal, industrial, and agricultural end-use categories. CAGRs derived from equipment replacement cycle analysis, regulatory deadline mapping, and capacity expansion announcements throughout the projection horizon. Forecast inputs incorporated membrane degradation curves, wetland seasonal efficiency variation, and smart sensor adoption rates.
Sensitivities concentrate around EU directive implementation timelines, Chinese PFAS precursor production restrictions, and tropical climate event frequency affecting constructed wetland performance. Forecasts reflect documented assumptions on enforcement consistency and technology cost curve trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
Commercial Atmospheric Water Generator Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
Wastewater Clarifier Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Global Wastewater Treatment Services Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Water Aeration System Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Sludge Dewatering Equipment Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market