
 Agricultural Wastewater Treatment Market | 2026-2036
Agricultural Wastewater Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Wastewater Treatment Market Intelligence
Multi-source equipment procurement is consolidating around a handful of technology-integrated vendors. Veolia leverages its geographic footprint across European dairy belts to anchor service contracts. Suez competes through membrane specialization in high-salinity agricultural zones. Evoqua Water Technologies sustains R&D intensity in anaerobic system design for livestock farm clusters.
Agricultural wastewater treatment encompasses physical, chemical, and biological processes that remove suspended solids, nutrients, pathogens, and organic load from farm effluent streams, typically achieving biochemical oxygen demand reductions exceeding 85 percent before discharge or reuse. Its primary purpose centers on enabling regulatory-compliant water recycling, nutrient recovery for fertilizer substitution, and biogas generation from organic decomposition. Membrane bioreactor deployments command premium pricing in confined livestock operations where space constraints and effluent strength converge. Constructed wetland systems occupy a mature cost niche in row-crop irrigation districts with available land buffers. Anaerobic treatment segments attract capital in dairy and swine regions where biogas production offsets energy costs.
The EPA enforces concentrated animal feeding operation discharge permits under the Clean Water Act, mandating nutrient management plans that directly shape technology selection. China's MEE applies GB 18596 standards to livestock wastewater, while the EU Nitrates Directive caps nitrogen application rates that force treatment investments. Stakeholders must weigh regulatory trajectory against total cost of ownership as phosphorus recovery mandates spread beyond current jurisdictions.
Market Dynamics
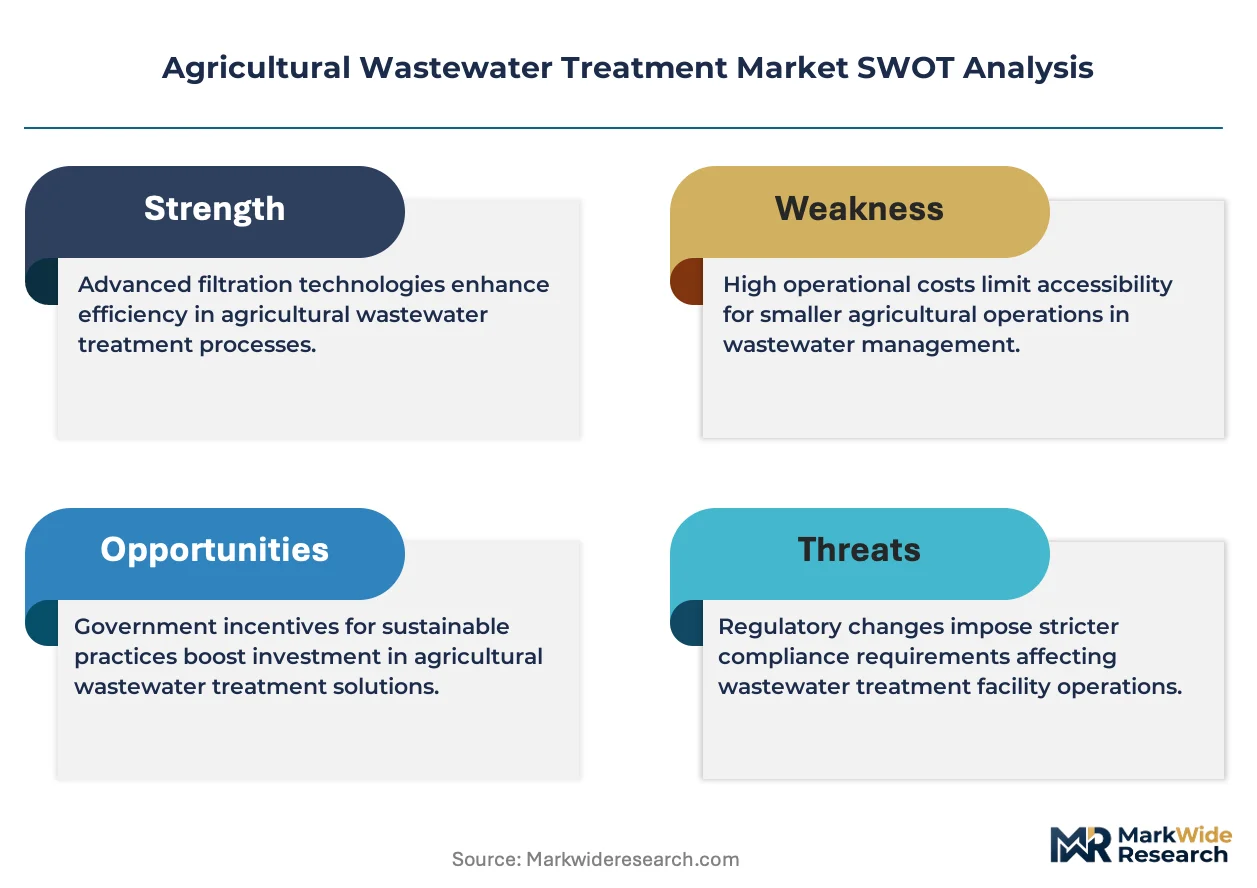
Phosphate discharge limits under the EU Nitrates Directive are forcing concentrated livestock operations to upgrade from lagoon storage to membrane bioreactor systems, compressing technology adoption timelines across dairy belts in the Netherlands, Germany, and Denmark.
Growth Catalysts
- EU Nitrates Directive enforcement:Nitrogen application caps in vulnerable zones mandate farm-level treatment investments, pulling demand toward nutrient recovery systems.
- Membrane bioreactor specialization:Space-constrained confined animal feeding operations deploy compact MBR units to meet Clean Water Act discharge permits.
- China aquaculture expansion:MEE enforcement of GB 18596 standards for livestock wastewater drives anaerobic digestion adoption with biogas capture.
Market Restraints
- Membrane replacement costs:Fouling-prone polymeric membranes in high-salinity agricultural zones require 3-5 year replacement cycles that strain operational budgets.
- Specialized civil engineering scarcity:Constructed wetland design expertise concentrates in Dutch and Belgian consulting firms, creating bottlenecked project pipelines.
- Natural treatment land requirements:Free-water surface wetlands demand 2-5 hectares per thousand cubic meters daily, excluding land-scarce operations.
Strategic Opportunities
- Phosphorus recovery mandates:Emerging regulations in Germany and Switzerland create pull for struvite crystallization reactors that convert wastewater to fertilizer-grade products.
- Sensor-integrated process control:Real-time dissolved oxygen and ammonia monitoring converges with automated blower systems to cut energy intensity in activated sludge units.
- Polish dairy cluster penetration:EU cohesion fund subsidies for environmental infrastructure cover 50-85 percent of capital costs for anaerobic digesters in underdeveloped regions.
Industry Challenges
- Process modeling skill gaps:Biological nutrient removal design requires specialized wastewater engineering expertise that agricultural extension services rarely provide.
- Legacy lagoon retrofit complexity:Existing earthen storage systems lack hydraulic profiles compatible with advanced treatment trains, demanding complete infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Wastewater Treatment Market |
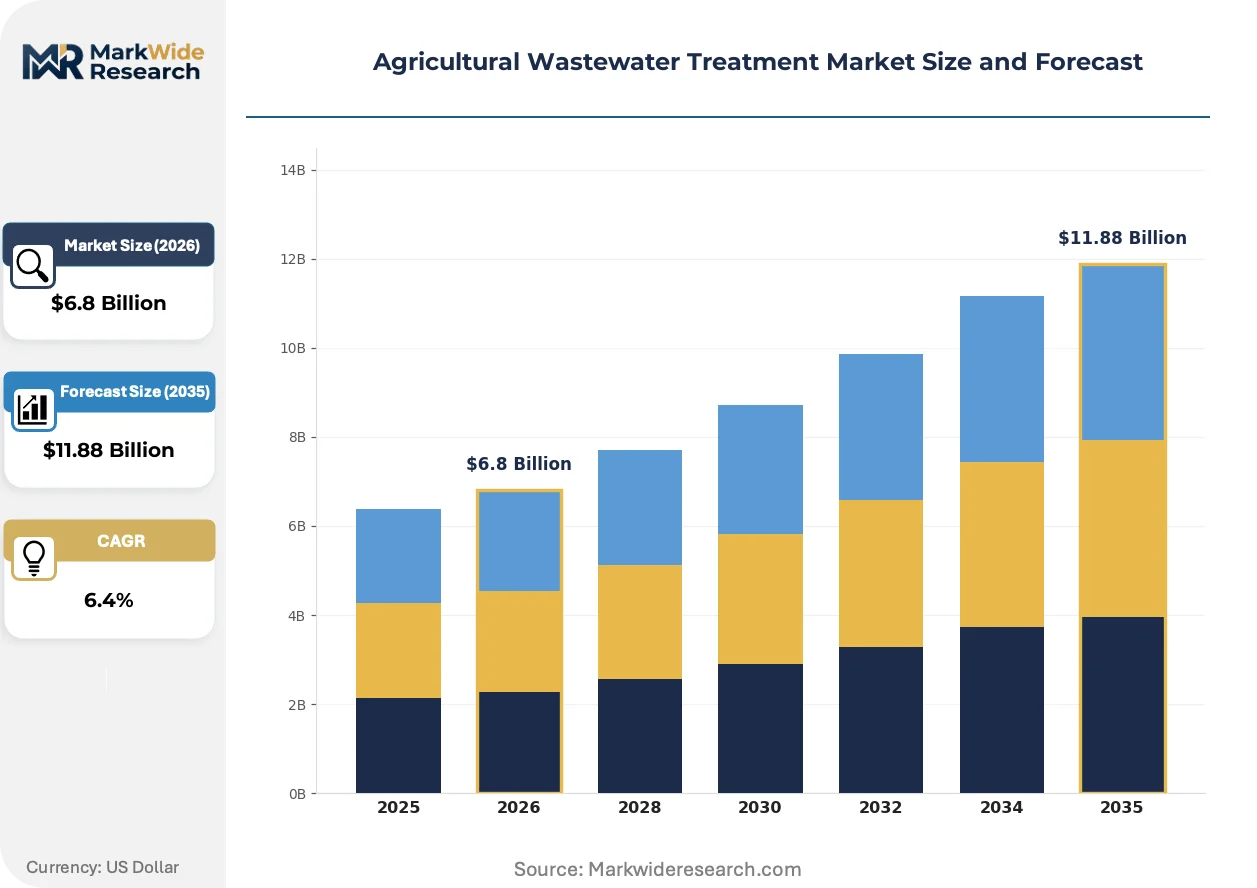
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Aerobic Treatment, Anaerobic Treatment, Membrane Bioreactor, Constructed Wetland Application: Irrigation, Nutrient Recovery, Soil Conditioning, Biogas Production End User: Agriculture Producers, Food Processors, Livestock Farms, Aquaculture Service Type: Consulting, Equipment Rental, Operation & Maintenance, Design & Engineering |
| Companies Covered | DuPont, Aquatech International, Suez, IDE Technologies, Saltworks Technologies, Veolia, Jacobs, Hella Water, Evoqua Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Wastewater Treatment Market Strategic Shifts & Innovations
Digital process control and modular reactor architectures are compressing deployment timelines while regulatory stringency tightens around nutrient discharge. Equipment vendors now bundle remote monitoring with hardware to secure recurring revenue streams.
Membrane aerated biofilm reactors are automating dissolved oxygen delivery through silicone tube diffusers that self-regulate based on biofilm thickness. Dutch dairy cooperatives deploy these systems in retrofit configurations where blower infrastructure is absent. The technology is automating labor-intensive process control while cutting energy consumption versus conventional fine-bubble aeration.
EPA's renewed focus on concentrated animal feeding operation enforcement under the Clean Water Act is elevating nutrient management plan compliance to operational priority. Permitting delays now stretch 18-24 months in watersheds with impaired water quality listings. Swine operations in the Chesapeake Bay watershed face the strictest scrutiny, with Virginia and Maryland requiring seasonal discharge prohibitions that force zero-liquid-discharge system adoption.
Service unbundling is fragmenting traditional design-build-operate contracts into separate procurement streams for process design, equipment supply, and remote operations support. Large livestock integrators now direct-source membrane modules while outsourcing biological process optimization to specialized consultants. This pattern is most pronounced in Denmark and the Netherlands where cooperative ownership structures enable collective bargaining for technology components.
Agricultural Wastewater Treatment Market Segmentation
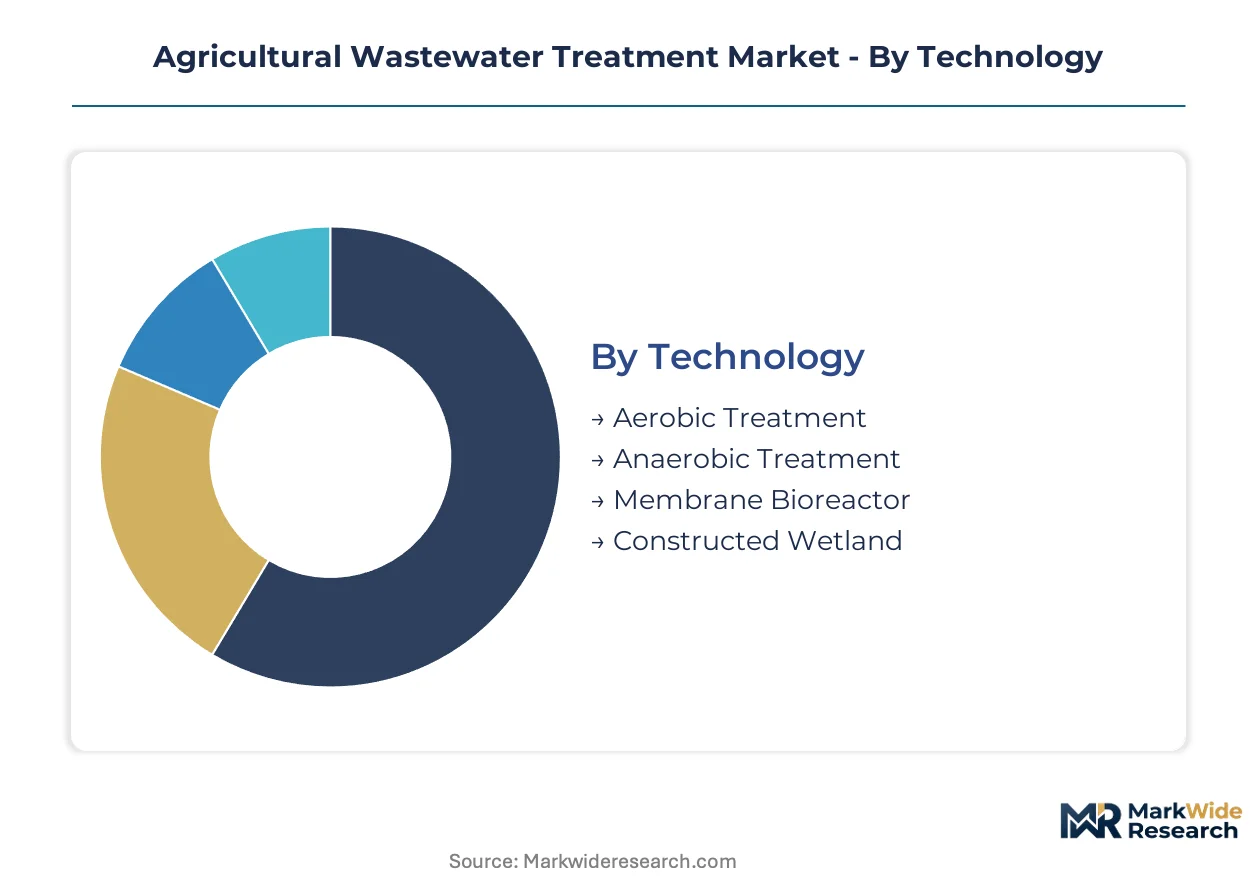
Technology selection in agricultural wastewater treatment hinges on effluent strength, land availability, and energy recovery potential. Distinct process configurations serve confined livestock operations versus extensive row-crop systems, creating divergent capital intensity profiles across deployment scenarios.
Technology:
Process design pivots on oxygen delivery mechanisms and biomass retention strategies that determine footprint, energy demand, and effluent quality.
- Aerobic Treatment:Activated sludge and sequencing batch reactors oxidize organic load through mechanical aeration, achieving biochemical oxygen demand reductions exceeding 85 percent. Dairy cooperatives in the Netherlands deploy these systems where phosphate discharge limits under the EU Nitrates Directive mandate tertiary nutrient removal.
- Membrane Bioreactor:Submerged hollow-fiber or flat-sheet membranes retain biomass at concentrations three to five times conventional activated sludge, compressing reactor volume by 60-70 percent. Space-constrained swine operations in the Chesapeake Bay watershed adopt MBR units to meet zero-liquid-discharge seasonal prohibitions imposed by Virginia and Maryland regulators.
- Anaerobic Treatment:Covered lagoons and upflow anaerobic sludge blanket reactors decompose organic matter in oxygen-absent environments, generating biogas for combined heat and power. China's MEE enforcement of GB 18596 standards for livestock wastewater drives adoption across Shandong and Sichuan farm clusters.
- Constructed Wetland:Engineered free-water surface and subsurface-flow systems exploit microbial communities rooted in gravel or soil media to polish effluent naturally. Dutch and Belgian consulting firms dominate design expertise for these land-intensive installations serving irrigation districts with available buffer zones.
Mature deployment sits with constructed wetlands. Newer deployment is concentrated in membrane bioreactor systems.
Application:
Value extraction from farm effluent varies by resource recovery priority — water reuse, nutrient capture, or energy generation — shaping technology bundling decisions.
- Irrigation:Treated effluent substitutes for freshwater withdrawals in water-stressed agricultural zones, requiring pathogen reduction and salinity management. California's Central Valley operators deploy ultraviolet disinfection coupled with reverse osmosis to meet food safety standards for produce irrigation.
- Biogas Production:Anaerobic digestion of manure and silage leachate yields methane for on-farm electricity generation or grid injection. German dairy clusters under the Renewable Energy Sources Act leverage feed-in tariffs to amortize digester capital costs within five to seven years.
- Nutrient Recovery:Struvite crystallization and ammonia stripping extract phosphorus and nitrogen for fertilizer-grade products. Switzerland's impending phosphorus recovery mandates are pulling demand toward reactor systems that convert wastewater to marketable inputs.
- Soil Conditioning:Biosolids and treated effluent improve soil organic matter and moisture retention in degraded agricultural lands. Australian broadacre wheatbelt operators apply Class B biosolids under state EPA permits to offset synthetic fertilizer requirements.
Volume concentration rests with irrigation reuse. Steepest expansion trajectory belongs to biogas production.
End User:
Operational scale and regulatory exposure dictate treatment sophistication — from simple storage lagoons to fully instrumented biological nutrient removal trains.
- Livestock Farms:Concentrated animal feeding operations generate high-strength effluent requiring continuous treatment to comply with EPA Clean Water Act discharge permits. Swine integrators in North Carolina's Neuse River basin face nutrient management plan obligations that force lagoon-to-digester retrofits.
- Aquaculture:Recirculating aquaculture systems and pond effluent carry suspended solids and nitrogenous waste that threaten receiving waters. China's GB standards enforcement targets coastal shrimp farming provinces with mandatory settling and biofiltration upgrades.
- Agriculture Producers:Row-crop and specialty crop operations manage runoff from fertilizer application and processing washwater through sedimentation basins and vegetative buffers. Midwestern corn-soybean belt farmers deploy two-stage ditches to intercept tile drainage nutrients before watershed entry.
- Food Processors:Fruit and vegetable canning, dairy, and meat processing facilities discharge high-carbon, high-solids wastewater requiring pretreatment before municipal sewer discharge or direct environmental release. Wisconsin cheese processors operate anaerobic pretreatment to reduce organic loading fees assessed by municipal treatment plants.
Regulatory pressure is most intense for livestock farms. Technology upgrade rates are climbing fastest among aquaculture operators.
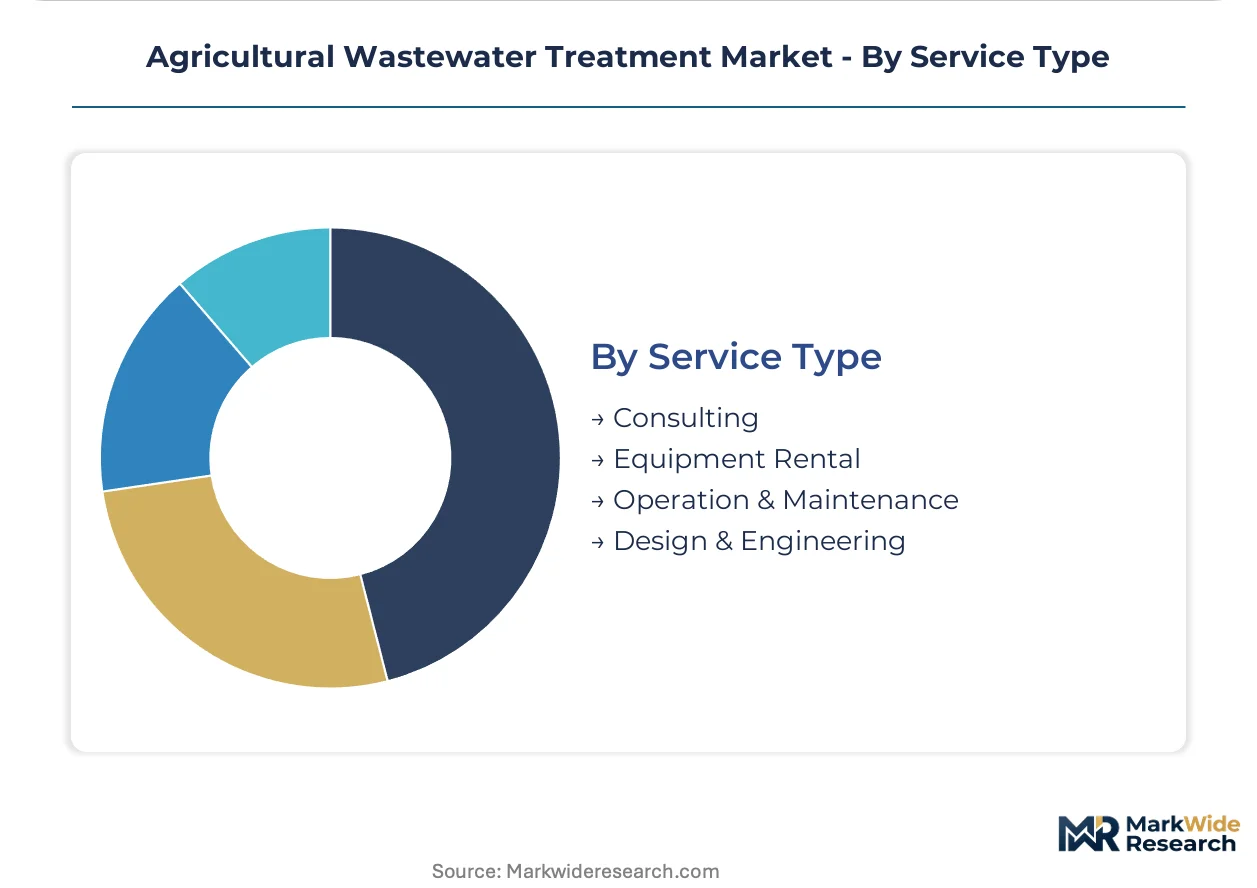
Service Type:
Procurement unbundling is fragmenting traditional design-build-operate contracts into specialized workstreams with distinct margin profiles.
- Operation & Maintenance:Remote monitoring, biomass management, and membrane cleaning sustain treatment performance over asset lifecycles. Danish livestock cooperatives outsource biological process optimization to specialized consultants while direct-sourcing hardware components.
- Design & Engineering:Process modeling, civil works specification, and regulatory permitting convert farm constraints into constructible treatment trains. Dutch engineering firms command premium fees for constructed wetland hydraulics expertise that remains scarce outside the Low Countries.
- Equipment Rental:Mobile treatment units and temporary membrane skids serve seasonal processing peaks and emergency compliance situations. California tomato processors lease dissolved air flotation systems during six-week harvest windows to avoid year-round capital commitment.
- Consulting:Nutrient management plan preparation, permit application support, and technology selection advisory guide capital deployment decisions. EPA's 18-24 month permitting timelines in impaired watersheds elevate consultant value for expedited approval strategies.
Margin stability favors operation and maintenance contracts. Procurement volume is shifting fastest toward design and engineering services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manure-rich livestock belts in the Netherlands, Germany, and Denmark anchor European treatment demand. Dairy cooperative density in these regions concentrates capital deployment for nutrient recovery infrastructure.
United States
Concentrated animal feeding operations in North Carolina's Neuse River basin and Virginia's Chesapeake Bay watershed drive lagoon-to-digester retrofits. EPA Clean Water Act discharge permits mandate nutrient management plans that force technology upgrades. Swine integrators in Iowa and Minnesota face seasonal zero-liquid-discharge prohibitions that compress adoption timelines for membrane bioreactor systems.
China
Shandong and Sichuan farm clusters generate high-strength effluent requiring anaerobic digestion with biogas capture. MEE enforcement of GB 18596 standards for livestock wastewater pulls demand toward covered lagoon systems. Coastal shrimp farming provinces face mandatory settling and biofiltration upgrades under stricter aquaculture effluent rules.
Germany
Dairy clusters under the Renewable Energy Sources Act leverage feed-in tariffs to amortize digester capital costs within five to seven years. Phosphorus recovery mandates emerging in federal states create pull for struvite crystallization reactors. Bavarian and Lower Saxon cooperatives deploy nutrient recovery systems to comply with tightened phosphate discharge limits.
Netherlands
Phosphate discharge limits under the EU Nitrates Directive force farm-level upgrades from lagoon storage to membrane bioreactor systems. Dutch dairy cooperatives in Friesland and Overijssel deploy membrane aerated biofilm reactors where blower infrastructure is absent. Engineering firms in the Randstad command premium fees for constructed wetland hydraulics expertise that remains scarce outside the Low Countries.
Switzerland
Impending phosphorus recovery mandates are pulling demand toward reactor systems that convert wastewater to fertilizer-grade products. Lake Geneva and Lake Constance watersheds face strict nutrient loading caps that force agricultural treatment investments. Swissmedic-aligned environmental standards create regulatory pull for advanced biological nutrient removal in alpine dairy regions.
Agricultural Wastewater Treatment Market Key Industry Players
Technology licensing dominates the current landscape as equipment vendors bundle remote monitoring with hardware to secure recurring revenue streams. The vendor base clusters around three archetypes: integrated water multinationals with geographic footprints across agricultural belts, membrane specialists serving high-salinity zones, and anaerobic system designers targeting livestock farm clusters. Consolidation pressure is mounting as service unbundling fragments traditional design-build-operate contracts into separate procurement streams for process design, equipment supply, and remote operations support.
Within the integrated multinational tier, Veolia and Suez occupy positions anchored by European dairy belt service contracts and membrane specialization respectively. Evoqua Water Technologies exemplifies the R&D-intensive archetype focused on anaerobic system design for confined livestock operations. Among these, Veolia represents the geographic expansion model, Suez the technology specialization approach, and Evoqua the innovation-driven positioning. Chinese fabricators and regional engineering firms compete on cost for standardized activated sludge units in emerging agricultural zones.
| Leading Market Players |
|---|
| DuPont |
| Aquatech International |
| Suez |
| IDE Technologies |
| Saltworks Technologies |
| Veolia |
| Jacobs |
| Hella Water |
| Evoqua Water Technologies |
| Others |
Cost & Logistics Intelligence
Constructed wetland hydraulics specialists concentrated in Dutch and Belgian consulting firms command 40-60 percent labor-cost premiums over general civil engineering contractors, widening spreads between premium design-engineering bundles and standardized equipment-only procurement tiers.
Pricing Analysis
Extended warranty and remote monitoring bundling separates membrane bioreactor vendors pursuing recurring revenue from unbundled equipment suppliers competing on capital cost alone. Three-tier pricing structure across premium, standard, and economy levels reflects membrane material grade (PVDF versus PES polymers) and automation depth. Cost compression in economy-tier activated sludge units is intensifying because Chinese fabricators are exporting standardized skids at marginal cost. Livestock cooperatives in Poland and Romania exhibit highest price sensitivity due to EU cohesion fund dependency, while Chesapeake Bay watershed integrators face inelastic demand from seasonal zero-liquid-discharge mandates.
Supply Chain Analysis
Membrane module refurbishment and reverse logistics flows from fouled hollow-fiber replacements feed secondary markets in Southeast Asian aquaculture zones. Manufacturing concentration rests on Germany, Japan, and South Korea for precision-machined diffusers and silicone tube aerators. Polymeric membrane production draws from fluoropolymer resin suppliers in Belgium and specialty chemical processors in the United States. Single-source vulnerability sits with hollow-fiber spinning equipment manufacturers in Germany. Distribution runs through regional water technology distributors serving dairy belts, bypassing general industrial supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agricultural wastewater treatment sector sits in a technology-transition phase where membrane aerated biofilm reactors are displacing conventional fine-bubble aeration in blower-constrained retrofit scenarios.
For Market Incumbents: Deepen vertical integration into membrane module manufacturing to capture replacement-cycle margins currently flowing to Japanese and German specialty suppliers. Defend service contract renewals by embedding sensor-integrated process control as a locked-in feature rather than optional add-on, neutralizing the threat of unbundled procurement patterns spreading from Danish cooperatives. For New Entrants and Emerging Players: Small-scale aquaculture operators in Vietnam and Indonesia represent an underserved buyer archetype lacking access to Dutch-engineered constructed wetland expertise. Enter through mobile treatment unit leasing models that bypass capital-intensive infrastructure commitments. Partner with regional engineering firms in Poland to access EU cohesion fund subsidized installations. For Investors and Strategic Acquirers: The window for entry favors anaerobic system designers with proprietary biogas optimization software and established livestock farm cluster relationships. Long-term viability hinges on phosphorus recovery mandate expansion beyond Germany and Switzerland into France and Austria. Monitor EPA enforcement intensity in impaired watersheds as the inflection indicator for zero-liquid-discharge system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Module Backward Integration | Captures recurring replacement revenue from fouling-prone polymeric membranes in high-salinity zones. |
| Sensor-Integrated Process Control Launch | Locks in recurring SaaS revenue while cutting energy intensity for Dutch dairy cooperative clients. |
| Phosphorus Recovery Technology Licensing | Positions vendors ahead of Swiss and German mandates for struvite crystallization reactor deployment. |
| Mobile Treatment Unit Fleet Expansion | Serves seasonal California tomato processing peaks without year-round capital commitment. |
| EU Cohesion Fund Partnership Structure | Unlocks 50-85 percent capital subsidies for Polish dairy cluster anaerobic digester installations. |
Research Approach
Independent corroboration across technology vendor engineering directors, livestock cooperative operations managers, and Dutch consulting firm hydraulics specialists underwrites the qualitative findings. Secondary validation draws from EPA Clean Water Act enforcement databases, EU Nitrates Directive implementation reports, and China MEE GB standard compliance filings. Bottom-up equipment shipment tracking and top-down regulatory mandate sizing triangulate market scope.
Comparable-period anchoring to historical CAFO permit issuance rates and digester installation subsidies calibrates the projection horizon. Segmentation dimensions span technology type, application priority, end-user scale class, and service procurement model. CAGRs derive from slope analysis across technology substitution curves and regulatory enforcement intensity indices. Forecast inputs include membrane replacement cycle frequencies and biogas feed-in tariff trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to phosphorus recovery mandate geographic spread and EPA watershed impairment listing expansions. Practitioners should monitor EU Nitrates Directive enforcement variance across member states and Chesapeake Bay seasonal discharge prohibition renewals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Packaged Wastewater Treatment Market
Water and Wastewater Treatment
Javelle Water Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
Latin America Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Ecological Wastewater Treatment Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Sewage Pump Market
Water and Wastewater Treatment
Sewage Treatment Service Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
Borehole Yield Testing Market