
 Latin America Membrane Bioreactor (MBR) Market | 2026-2036
Latin America Membrane Bioreactor (MBR) Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Membrane Bioreactor (MBR) Market Intelligence
Market Context
Advanced aeration control integrated with submerged membrane modules is reshaping how biological treatment trains are configured across Latin American utilities. Kubota Corporation leverages its flat-sheet membrane manufacturing base to anchor supply relationships with major Brazilian water operators. Pentair plc sustains competitive positioning through specialized hollow fiber systems engineered for high-solids industrial streams. Veolia Water Technologies dominates turnkey project delivery by controlling engineering, procurement, and commissioning channels across Mexico and Colombia.
Technical Definition and Segment Structure
A membrane bioreactor combines suspended-growth biological treatment with membrane filtration, typically employing polymeric hollow fiber or flat-sheet membranes with pore sizes of 0.01 to 0.4 microns to separate treated water from mixed liquor without secondary clarifiers. The technology achieves effluent quality suitable for direct discharge or reuse while reducing plant footprint by 30-50% compared to conventional activated sludge systems. Hollow fiber configurations lead Latin American municipal procurement due to lower capital intensity and established supplier networks, while flat-sheet membranes command premium positioning in industrial applications where chemical cleaning frequency drives lifecycle cost differentiation. Skid-mounted installations represent the fastest-growing installation category as utilities prioritize phased capacity expansion and reduced civil works.
Regulatory Frame and Outlook
Brazil's CONAMA and Mexico's SEMARNAT enforce progressively stringent biochemical oxygen demand and total suspended solids limits that mandate tertiary treatment upgrades, directly accelerating MBR specification in new plant design. ANA in Brazil and CONAGUA in Mexico shape water reuse policy that expands addressable demand beyond discharge compliance toward agricultural and industrial recycle streams. Stakeholders must monitor how proposed updates to Chile's NCh standards and Argentina's water authority protocols redirect procurement specifications toward nutrient removal capabilities.
Market Dynamics
Brazil's CONAMA Resolution 430 enforcement is compressing procurement timelines for municipal utilities, forcing simultaneous capacity expansion and effluent quality upgrades that favor modular membrane systems over conventional activated sludge retrofits.
Growth Catalysts
- CONAMA Resolution 430:Brazil's tightened biochemical oxygen demand and total suspended solids limits mandate tertiary treatment, directing São Paulo metropolitan utilities toward membrane-based solutions.
- Valley of Mexico basin water stress:CONAGUA reuse policies expand addressable demand beyond discharge compliance toward agricultural and industrial recycle streams.
- Hollow fiber membrane manufacturing:Advancing domestic production capabilities in Brazil reduce lead times and localize supply chains for skid-mounted MBR systems.
Market Restraints
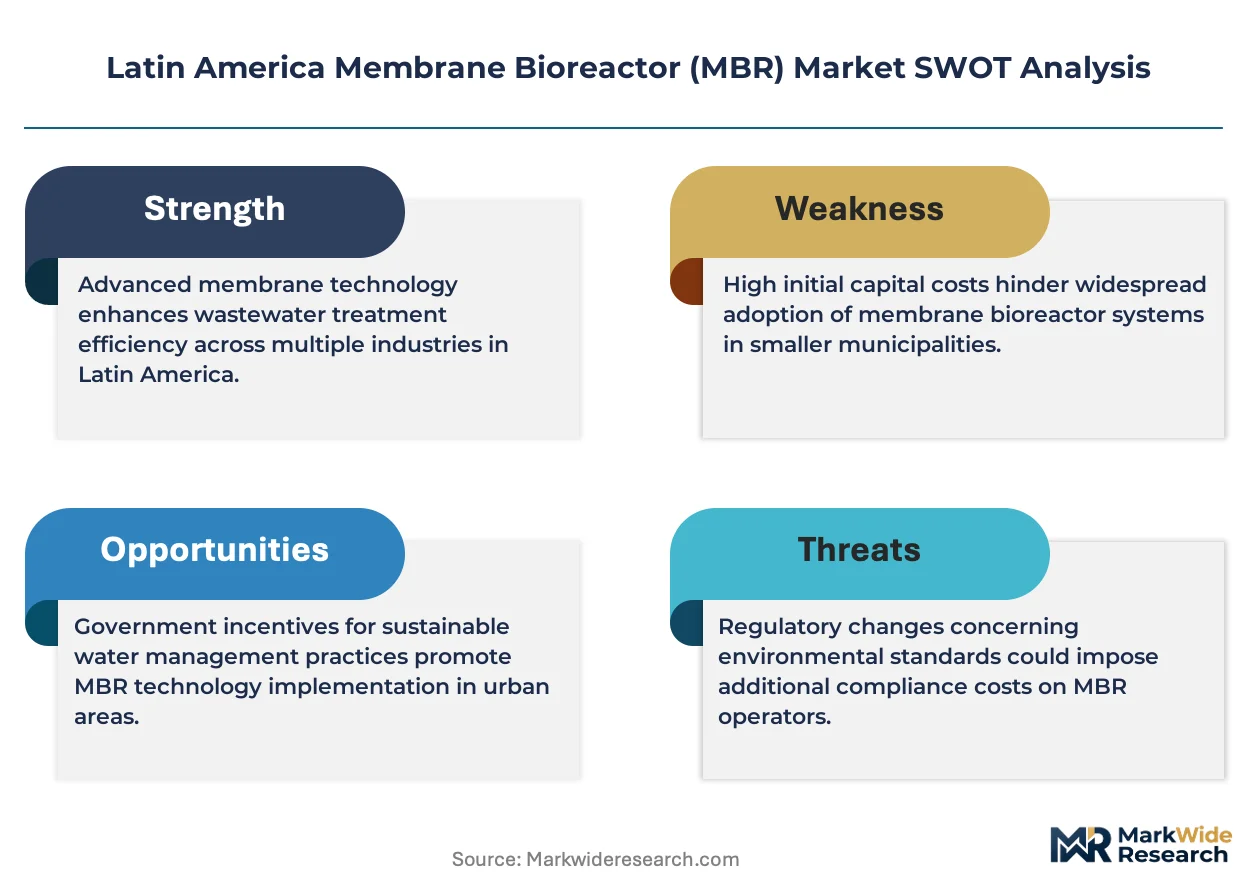
- Membrane replacement cost volatility:Polymeric hollow fiber and flat-sheet modules require scheduled replacement every 5-7 years, exposing utilities to petrochemical input price swings.
- Specialized technical labor scarcity:Brazil and Mexico lack sufficient certified membrane maintenance technicians, constraining operational readiness for small and mid-sized utilities.
- Conventional activated sludge persistence:Lower upfront capital requirements for traditional biological treatment continue to win budget-constrained municipal tenders outside major metropolitan zones.
Strategic Opportunities
- Colombia's underserved Andean cities:Medellín and Bogotá wastewater infrastructure gaps create entry points for turnkey MBR providers ahead of anticipated regulatory tightening.
- Chile NCh standard updates:Proposed nutrient removal mandates will redirect procurement specifications toward enhanced biological phosphorus and nitrogen removal capabilities.
- Industrial zero-liquid-discharge convergence:Mining and food processing sectors in Peru and Chile integrate MBR with reverse osmosis and evaporation for closed-loop water systems.
Industry Challenges
- Membrane fouling management expertise:Utilities struggle to optimize chemical cleaning protocols, shortening membrane lifespan and inflating lifecycle costs beyond projected models.
- Legacy SCADA integration complexity:Older treatment plants in Mexico's provincial cities require substantial control system upgrades to accommodate automated membrane operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Membrane Bioreactor (MBR) Market |
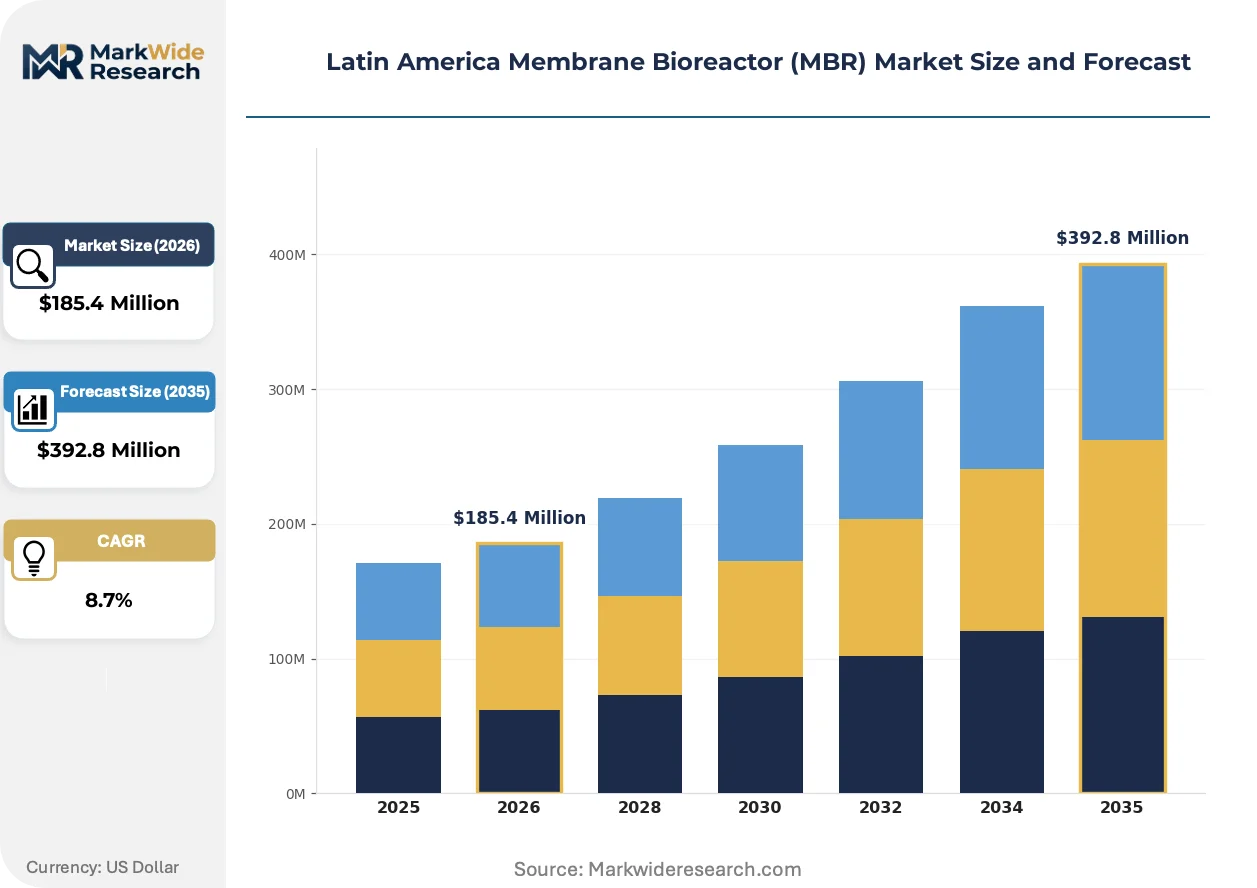
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $392.8 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
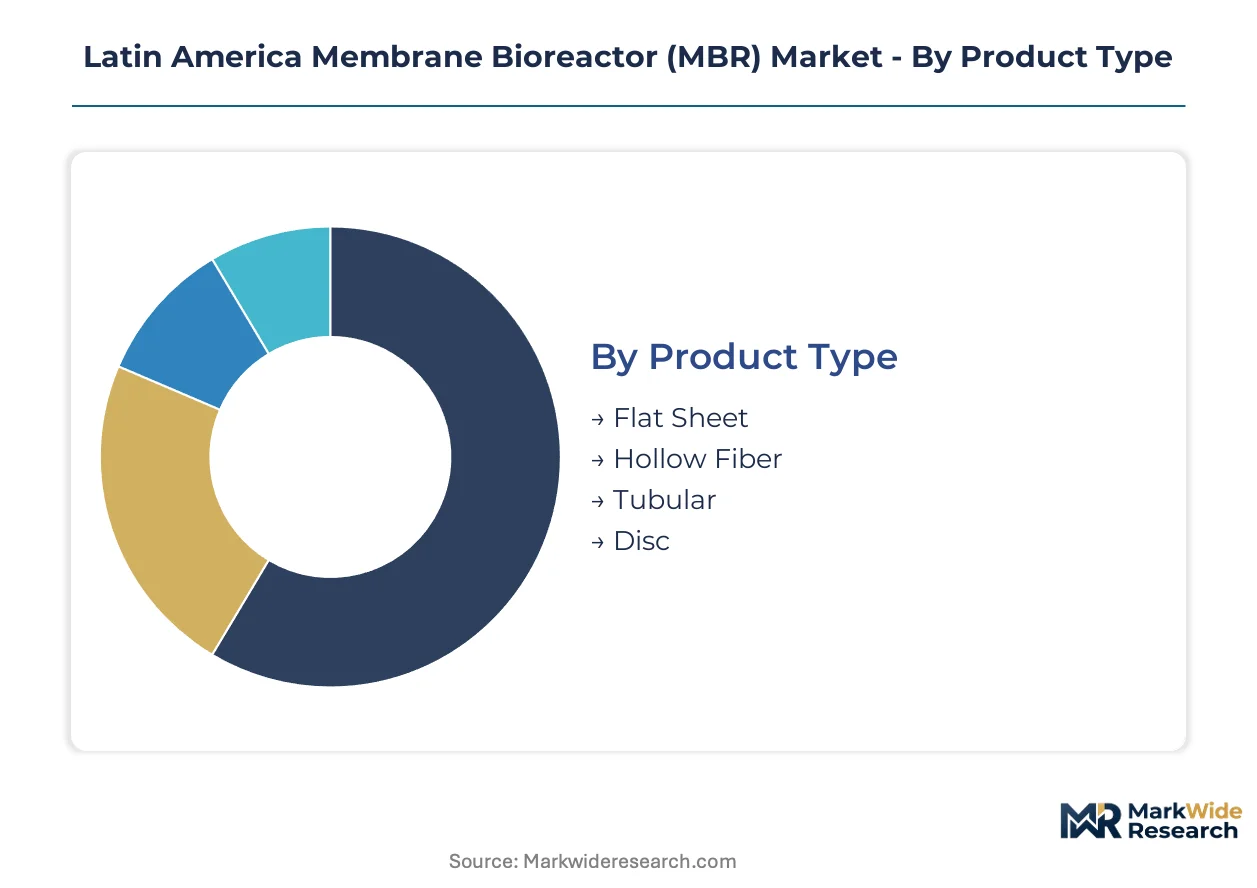
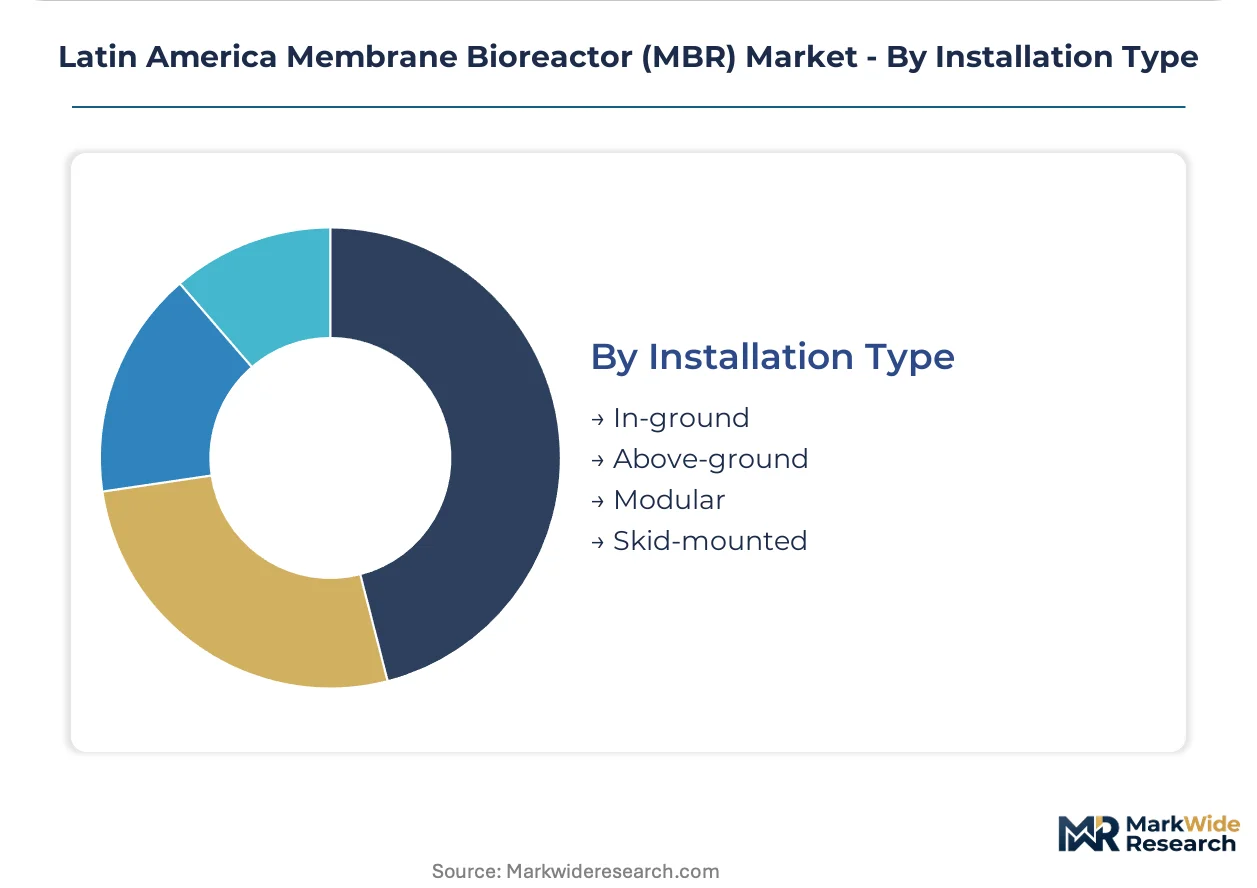
| Segmentation | Product Type: Flat Sheet, Hollow Fiber, Tubular, Disc Application: Wastewater Treatment, Municipal, Industrial, Reuse End User: Water Utilities, Food & Beverage, Pharmaceuticals, Oil & Gas Installation Type: In-ground, Above-ground, Modular, Skid-mounted |
| Companies Covered | Kubota Corporation, Pentair plc, Veolia Water Technologies, Koch Membrane Systems, Inc., Mitsubishi Chemical Aqua Solutions Co., Ltd., SUEZ Water Technologies & Solutions, Toray Industries, Inc., Alfa Laval AB, Evoqua Water Technologies, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Membrane Bioreactor (MBR) Market Strategic Shifts & Innovations
Automation and predictive maintenance systems are restructuring how Latin American utilities operate membrane assets, shifting from reactive cleaning schedules toward condition-based monitoring that preserves membrane integrity and reduces chemical consumption.
Submerged flat-sheet membrane configurations with integrated advanced aeration control are collapsing the footprint differential between MBR and conventional systems. Brazilian industrial operators in food and beverage processing adopt these compact units to expand treatment capacity within existing plant boundaries. The technology is collapsing civil works requirements by enabling above-ground installation on constrained urban sites.
SEMARNAT's progressive enforcement of total nitrogen limits in Mexico's priority river basins is mandating enhanced biological nutrient removal capabilities. Industrial discharge permits now require denitrification performance that conventional activated sludge cannot reliably achieve. Northern Mexico's manufacturing corridor utilities are responding by specifying anoxic zone integration within MBR process trains.
Performance-based service contracting is displacing traditional equipment procurement across major Brazilian water operators. São Paulo's state water utility now contracts membrane availability and effluent quality guarantees rather than purchasing capital assets outright. This model concentrates vendor risk and rewards operational excellence, visible most prominently in Brazil's Southeast region where private concession models dominate.
Latin America Membrane Bioreactor (MBR) Market Segmentation
Membrane configuration, application intensity, and installation constraints each redirect procurement economics across Latin American utilities. Segment-level variation in replacement cycles and civil works requirements shapes vendor selection criteria and project financing structures.
Product Type:
Mature polymeric configurations dominate municipal procurement while emerging ceramic and modified geometries gain traction in high-strength industrial streams.
- Hollow Fiber:Polyvinylidene fluoride or polyethersulfone filaments arranged in bundled configurations achieve high packing density with low energy demand for scouring. São Paulo metropolitan utilities specify hollow fiber modules for phased capacity expansion at existing treatment sites.
- Flat Sheet:Rigid membrane panels mounted in stacked cassettes permit aggressive chemical cleaning protocols without structural deformation. Food and beverage processors in Brazil's Southeast region favor flat-sheet systems for high-solids wastewater with elevated fat and oil content.
- Tubular:Internal recirculation configurations handle viscous industrial effluents with high suspended solids loading.
- Disc:Rotating membrane assemblies reduce fouling intensity through shear generation at the membrane surface.
Hollow Fiber handles the majority of throughput; Flat Sheet is the fastest mover on share.
Application:
Volume concentration clusters in municipal discharge compliance while margin expansion concentrates in reuse and industrial recycle streams.
- Wastewater Treatment:Biological oxygen demand reduction and suspended solids removal for direct river or ocean discharge. CONAMA Resolution 430 enforcement across Brazil's state water utilities accelerates membrane specification for tertiary treatment upgrades.
- Municipal:Population-dense urban centers deploy submerged membrane bioreactors to reduce plant footprint within constrained sites. Mexico's Valley of Mexico basin utilities specify MBR for capacity expansion without land acquisition.
- Industrial:Process water treatment for manufacturing sectors with variable effluent composition and stringent discharge permits.
- Reuse:Agricultural irrigation and industrial cooling water production from treated municipal effluent.
Municipal captures the largest project volume; Reuse is climbing the fastest as CONAGUA policies expand addressable demand.
End User:
Customer type determines financing structure and operational risk allocation across Latin American procurement.
- Water Utilities:State and municipal operators with concession-based service contracts. Performance-based contracting models in Brazil's Southeast region shift membrane availability risk to vendor operators.
- Food & Beverage:Processors generating high-strength organic wastewater with seasonal flow variation. Breweries and dairy operations specify flat-sheet MBR for fat, oil, and grease tolerance.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturers requiring validated removal of trace contaminants.
- Oil & Gas:Produced water treatment and refinery effluent polishing for discharge or recycle.
Water Utilities command the dominant share of installed base; Food & Beverage is gaining share fastest on industrial discharge tightening.
Installation Type:
Civil works intensity and project timeline flexibility segment procurement approaches across metropolitan and provincial markets.
- Skid-mounted:Pre-assembled process trains delivered as modular units minimize on-site construction duration. Brazilian utilities prioritize skid-mounted MBR for rapid deployment at satellite treatment locations.
- Modular:Standardized tank and membrane configurations permit phased capacity expansion with minimal retrofit disruption.
- Above-ground:Elevated concrete or steel tankage eliminates excavation requirements in high water table zones.
- In-ground:Conventional buried construction for greenfield sites with favorable geotechnical conditions.
Skid-mounted is expanding most quickly on reduced civil works and accelerated commissioning timelines; In-ground retains share in greenfield provincial projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Membrane bioreactor equipment and engineering services flow predominantly from Japanese, European, and North American suppliers into Brazilian and Mexican utilities, with limited reverse trade in hollow fiber manufacturing emerging from São Paulo industrial zones.
Brazil
São Paulo metropolitan utilities deploy submerged membrane systems to expand capacity within existing treatment boundaries. CONAMA Resolution 430 mandates tertiary treatment upgrades that bypass conventional activated sludge retrofits. The state's water utility concession model concentrates procurement in the Southeast region, where performance-based contracting now dominates.
Mexico
Valley of Mexico basin utilities specify MBR for water reuse applications under CONAGUA pressure. SEMARNAT enforces total nitrogen limits in priority river basins that conventional biological treatment cannot satisfy. Northern Mexico's manufacturing corridor integrates denitrification-capable membrane trains for industrial discharge compliance.
Chile
Mining sector water recycling drives ceramic and modified membrane specification in the Atacama and Antofagasta regions. Proposed NCh standard updates toward nutrient removal will redirect municipal procurement in Santiago toward enhanced biological phosphorus removal. Industrial zero-liquid-discharge systems converge MBR with reverse osmosis for closed-loop operations.
Colombia
Medellín and Bogotá wastewater infrastructure gaps create procurement opportunities ahead of anticipated regulatory tightening. The national environmental authority shapes discharge standards that will eventually mandate membrane-based tertiary treatment. Andean cities prioritize skid-mounted installations to accelerate commissioning on constrained urban sites.
Argentina
Buenos Aires provincial utilities evaluate membrane technology for metropolitan plant upgrades. The country's water authority protocols are evolving toward stricter biochemical oxygen demand limits that favor modular biological treatment. Industrial processors in Córdoba and Santa Fe pilot flat-sheet systems for high-strength food processing effluents.
Latin America Membrane Bioreactor (MBR) Market Key Industry Players
On the supply side, the industry is tiered between integrated membrane manufacturers, specialized system integrators, and regional engineering contractors. Japanese and European membrane producers anchor the premium tier through proprietary hollow fiber and flat-sheet technologies. Turnkey project specialists control engineering, procurement, and commissioning channels. Competitive moves concentrate on performance-based service contracting and localized manufacturing partnerships to reduce lead times.
Among integrated membrane manufacturers, Kubota Corporation and Toray Industries exemplify the premium-tier archetype through proprietary flat-sheet and hollow fiber production capabilities. Veolia Water Technologies occupies a position within the turnkey project delivery segment, controlling EPC channels across Mexico and Colombia. These three entities represent distinct competitive vectors: captive membrane manufacturing, specialized system integration, and full-service project execution.
| Leading Market Players |
|---|
| Kubota Corporation |
| Pentair plc |
| Veolia Water Technologies |
| Koch Membrane Systems, Inc. |
| Mitsubishi Chemical Aqua Solutions Co., Ltd. |
| SUEZ Water Technologies & Solutions |
| Toray Industries, Inc. |
| Alfa Laval AB |
| Evoqua Water Technologies |
| Others |
Cost & Logistics Intelligence
Petrochemical input volatility for polyvinylidene fluoride and polyethersulfone resins compresses margin buffers across hollow fiber and flat-sheet membrane tiers while simultaneously forcing procurement officers toward longer-term polymer supply contracts that reshape inventory holding patterns and working capital intensity.
Pricing Analysis
Current-generation hollow fiber modules command 15-25% premiums over prior-generation configurations with enhanced fouling resistance coatings, while next-generation ceramic-composite membranes in pilot deployment carry substantial markups justified by extended replacement cycles. Pricing stratifies across premium flat-sheet, standard hollow fiber, and economy tubular tiers based on membrane geometry complexity and chemical cleaning protocol tolerance. Cost compression in standard hollow fiber segments is intensifying because Brazilian domestic manufacturing expansion adds polyvinylidene fluoride production capacity. Municipal water utilities exhibit highest price sensitivity due to concession-based budget constraints, while mining sector operators in Chile demonstrate lowest sensitivity given zero-liquid-discharge compliance requirements.
Supply Chain Analysis
Export control restrictions on advanced membrane manufacturing equipment from Japanese and European sources limit technology transfer for sub-0.1 micron precision extrusion systems, constraining localization timelines for Brazilian hollow fiber producers. Manufacturing gravity centers on Japan for flat-sheet membrane cassettes, Germany for precision polymer extrusion equipment, and China for polyvinylidene fluoride resin feedstock. Raw material dependencies span petrochemical-derived polymers, ceramic alumina substrates, and proprietary coating chemistries. Single-source vulnerability concentrates in specialized hollow fiber spinning equipment where two European suppliers dominate global installation bases. Distribution runs through turnkey engineering-procurement-construction contractors who bundle membrane modules with civil works and commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane availability guarantees and chemical cleaning chemical supply contracts represent the fastest-expanding recurring revenue layer, outpacing hardware sales as Brazilian utilities shift toward performance-based service contracting that transfers operational risk to vendors.
For Market Incumbents: Build captive hollow fiber manufacturing capacity in São Paulo industrial zones to defend against emerging Korean membrane suppliers targeting Latin American municipal tenders through aggressive pricing. Secure CONAMA pre-qualification status for modular skid-mounted configurations to lock out non-certified competitors from state water utility procurement pipelines. Deepen backward integration into polyvinylidene fluoride resin compounding to buffer petrochemical price volatility exposure. For New Entrants and Emerging Players: Establish a beachhead in Colombia's Andean cities ahead of anticipated regulatory tightening that will mandate tertiary treatment upgrades currently absent from Medellín and Bogotá infrastructure planning. Target skid-mounted MBR installations for rapid commissioning advantages on constrained urban sites where incumbent lead times stretch 18-24 months. Pursue partnership structures with regional engineering contractors lacking membrane expertise but controlling civil works relationships. For Investors and Strategic Acquirers: The market sits at an infrastructure-upgrade phase that favors vertically integrated membrane manufacturers with turnkey project execution capabilities over pure-play equipment suppliers. Long-term viability hinges on service revenue attachment rates and membrane replacement contract duration rather than initial project margins. Monitor CONAGUA enforcement intensity in Mexico's priority river basins as the signal indicating acceleration toward nutrient-removal-capable system specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Hollow Fiber Manufacturing | Reduces lead times for Brazilian utilities facing CONAMA-mandated upgrade deadlines. |
| Performance-Based Service Contracting | Shifts membrane availability risk to vendors under São Paulo concession models. |
| Ceramic Membrane Pilot Deployment | Targets mining sector zero-liquid-discharge requirements in Chilean Atacama operations. |
| Skid-Mounted System Standardization | Accelerates commissioning timelines for Colombian Andean city infrastructure gaps. |
| Denitrification-Capable Process Train Integration | Addresses SEMARNAT total nitrogen limits in Mexico's northern manufacturing corridor. |
Research Approach
A standing panel of municipal utility operations directors, membrane system maintenance technicians, EPC contractor project managers, and water authority regulatory officers provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from ANA and CONAGUA policy documents, CONAMA Resolution 430 technical annexes, and membrane supplier technical bulletins. Bottom-up project pipeline tracking across 40+ municipal and industrial installations triangulated against top-down market sizing from equipment procurement databases.
Scenario-bracketing around regulatory enforcement intensity and petrochemical price trajectories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass membrane configuration geometry, application intensity tier, installation type constraints, and end-user financing structure. CAGRs derived from unit deployment trajectories and average selling price evolution by membrane technology generation. Industry-specific forecast inputs incorporated hollow fiber replacement cycle data and skid-mounted system adoption curves from Brazilian state water utility procurement records.
Sensitivities concentrate around CONAMA enforcement consistency, CONAGUA reuse policy implementation pace, and polyvinylidene fluoride resin price volatility. Forecasts reflect documented assumptions regarding regulatory timeline adherence and membrane manufacturing localization progress. Material shifts in Brazilian federal environmental authority funding levels or Mexican presidential administration water policy priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Wastewater Clarifier Market
Water and Wastewater Treatment
Sewage Pump Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Sewage Treatment Service Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Global Wastewater Diffused Aerator Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Sludge Dewatering Equipment Market
Water and Wastewater Treatment
Water Testing Meter Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Global Biological Wastewater Treatment Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
Javelle Water Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market