
 Primary Water and Wastewater Treatment Equipment Market | 2026-2036
Primary Water and Wastewater Treatment Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Water and Wastewater Treatment Equipment Market Intelligence
Industrial manufacturers are redrawing procurement priorities for primary treatment hardware as municipal utilities defer capital spending. Xylem Inc. dominates large-scale clarifier installations across North American utility networks. Evoqua Water Technologies differentiates through chemical-physical hybrid systems for manufacturing end users. SUEZ anchors European municipal contracts with integrated screening-to-clarification workflows.
Primary water and wastewater treatment equipment encompasses the initial stage of contaminant removal through physical processes such as gravity sedimentation, bar screening, and dissolved air flotation operating at hydraulic retention times of 1-3 hours. This equipment removes settleable solids, floatable materials, and coarse particulates to protect downstream biological processes and reduce organic loading. Clarifiers capture the largest share of product-type value due to their structural steel intensity and basin civil works. Screens are gaining fastest in coastal and flood-prone municipalities where stormwater debris loads are rising. Physical treatment technology leads installed base volumes while advanced oxidation segments command premium pricing for industrial reuse applications.
The US EPA enforces effluent limitation guidelines that mandate specific removal efficiencies for total suspended solids and biochemical oxygen demand at primary stages. China's MEE implements dual carbon goals that tighten discharge permits for industrial clusters along the Yangtze and Pearl River deltas. The EU Green Deal's urban wastewater treatment directive revision is expanding nutrient removal requirements that cascade back to primary process reliability. Stakeholders must monitor how regulatory tightening on emerging contaminants redirects capital from conventional clarification toward chemically enhanced primary treatment.
Market Dynamics
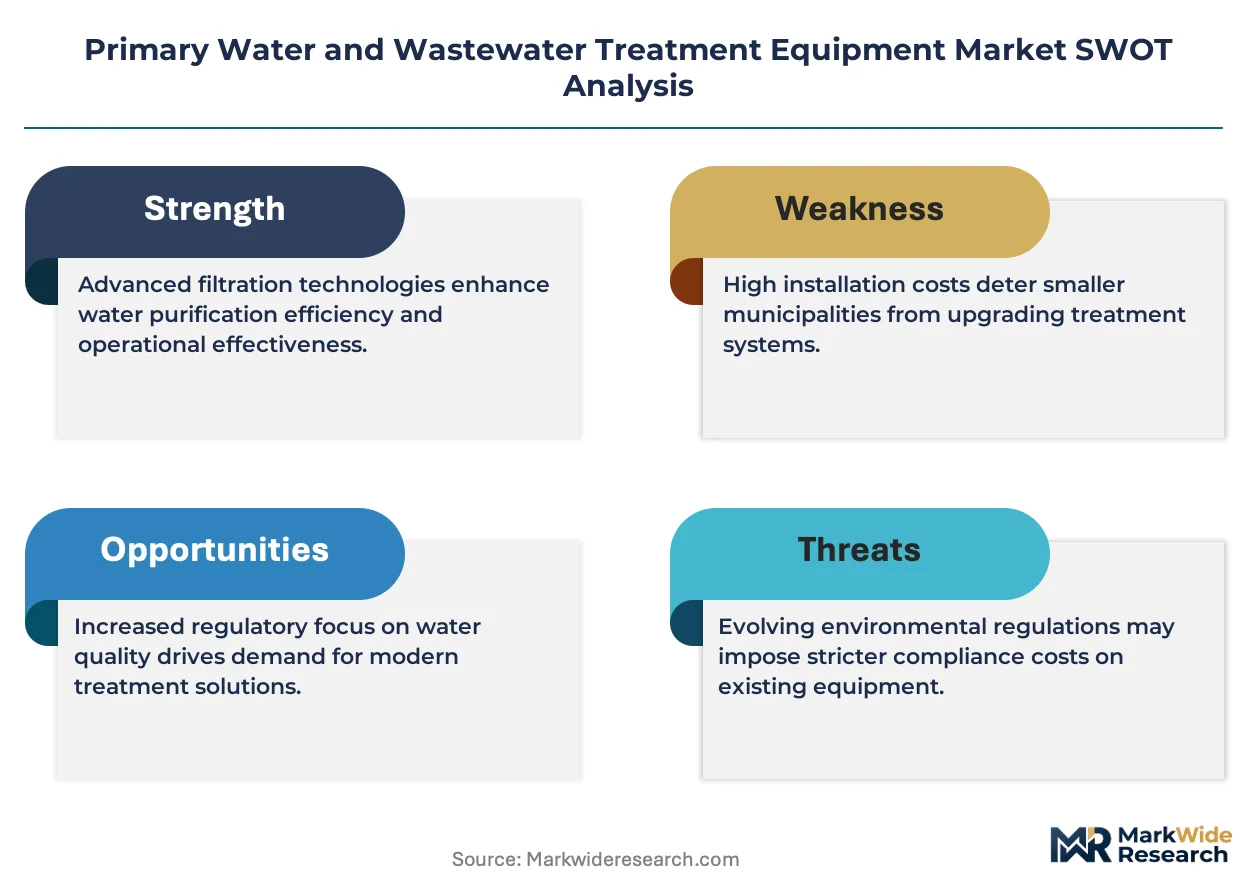
Regulatory tightening on effluent quality is forcing municipal utilities to front-load capital into primary treatment stages before biological upgrades, compressing procurement timelines and favoring suppliers with integrated screening-to-clarification capabilities.
Growth Catalysts
- US EPA Effluent Guidelines:Revised total suspended solids and biochemical oxygen demand mandates require physical screening upgrades across aging municipal infrastructure.
- Zero-Liquid-Discharge Mandates:China's MEE enforcement along the Yangtze and Pearl River deltas is driving industrial corridor investment in robust primary processing capacity.
- Stormwater Debris Loading:Coastal municipalities facing intensified flood patterns are accelerating bar screen and grit chamber installations to protect downstream assets.
Market Restraints
- Structural Steel Volatility:Clarifier basin construction faces input cost pressure from fluctuating steel and concrete markets, squeezing fixed-bid municipal contracts.
- European Supplier Concentration:Integrated screening-to-clarification workflows anchor heavily with SUEZ and regional champions, limiting price competition for large-scale European utility awards.
- Clarifier Footprint Constraints:Urban land scarcity prevents circular basin deployment in dense Chinese industrial zones, forcing costlier rectangular or stacked configurations.
Strategic Opportunities
- India's AMRUT 2.0 Expansion:Underpenetrated tier-2 and tier-3 cities offer clarifier and screen demand as the national mission extends sewerage coverage beyond metropolitan cores.
- Chemical-Physical Hybrid Convergence:Coagulant-enhanced primary treatment paired with dissolved air flotation opens industrial reuse applications previously requiring full secondary trains.
- EU Green Deal Nutrient Cascade:The urban wastewater treatment directive revision expands reliability requirements at primary stages, creating retrofit demand for automated screening controls.
Industry Challenges
- Process Control Engineering Gap:Municipal utilities lack instrumentation specialists to optimize chemically enhanced primary treatment dosing regimes, delaying commissioning.
- Legacy SCADA Integration:New automated bar screens and clarifier drives must interface with decades-old control architectures, extending project timelines and testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Water and Wastewater Treatment Equipment Market |
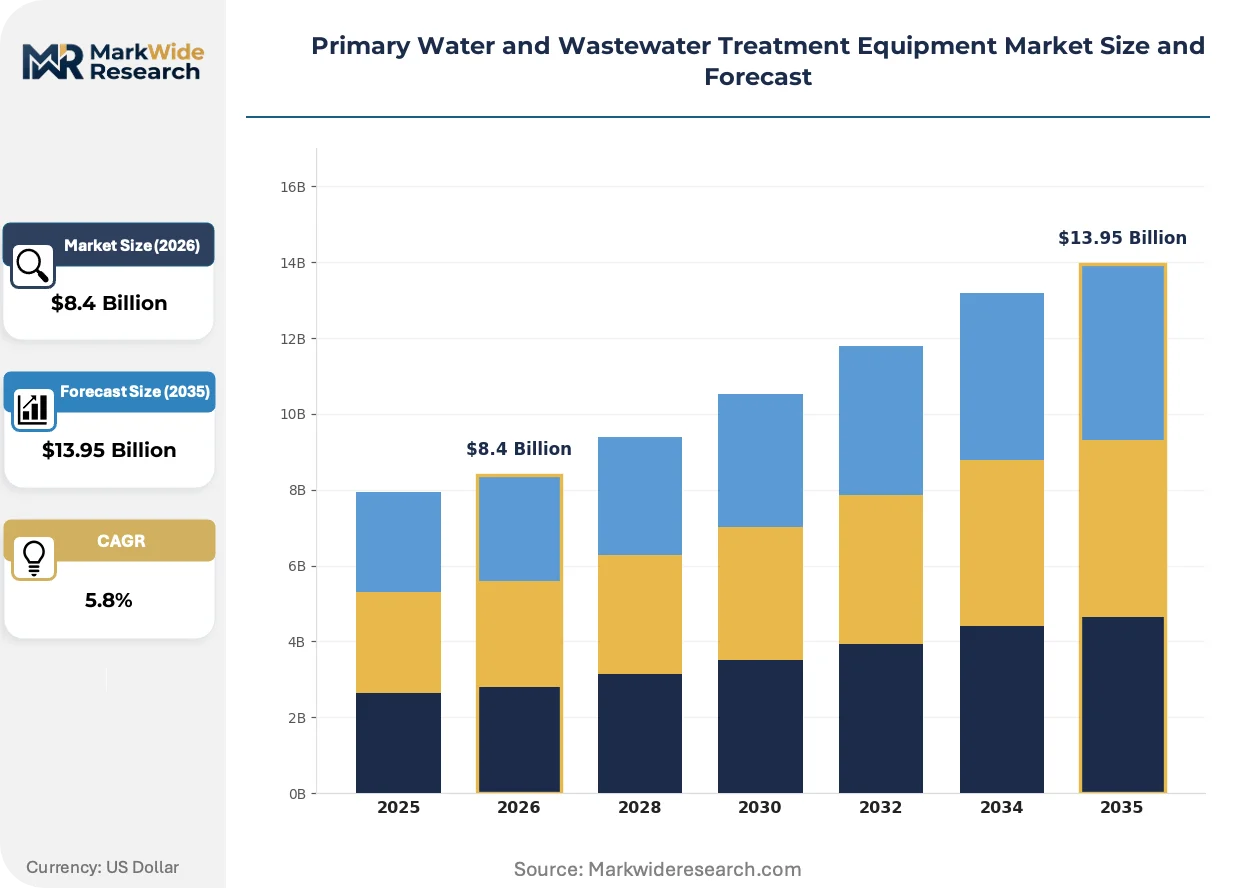
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.95 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clarifiers, Filters, Screens, Aerators Application: Municipal, Industrial, Agricultural, Recreational Technology: Biological Treatment, Chemical Treatment, Physical Treatment, Advanced Oxidation End User: Utilities, Manufacturing, Agriculture, Food & Beverage |
| Companies Covered | Fluence Corporation Limited, SUEZ, Veolia Water Technologies, Kurita Water Industries Ltd., Grundfos, Xylem Inc., Aquatech International Corporation, WesTech Engineering, Evoqua Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Water and Wastewater Treatment Equipment Market Strategic Shifts & Innovations
Equipment suppliers are embedding sensors and predictive algorithms into physical treatment assets, transforming primary stages from passive sedimentation into actively managed process nodes that feed real-time data to biological downstream operations.
Dissolved air flotation technology is decomposing the clarifier's historical dominance in industrial pre-treatment applications. Food and beverage processors facing high-strength organic loads are adopting compact flotation units at twice the pace of conventional sedimentation basins. This shift is decomposing the structural steel intensity that previously defined project economics, enabling packaged skid-mounted systems to capture mid-scale manufacturing contracts previously reserved for engineered civil works.
The EU Green Deal's urban wastewater treatment directive revision is cascading nutrient removal obligations backward to primary process reliability. German and Dutch utilities must now demonstrate consistent settleable solids capture to avoid downstream biological failure. Clarifier manufacturers are responding with automated sludge blanket level controls and real-time flow pacing to meet these tightened performance guarantees.
Industrial buyers are unbundling after-sales service contracts from initial equipment procurement. Large manufacturing end-users in China's Pearl River delta now contract maintenance separately through third-party water service operators rather than original equipment suppliers. This pattern is most visible in electronics and textile clusters where zero-liquid-discharge compliance demands specialized chemical-physical system expertise that equipment vendors struggle to staff locally.
Primary Water and Wastewater Treatment Equipment Market Segmentation
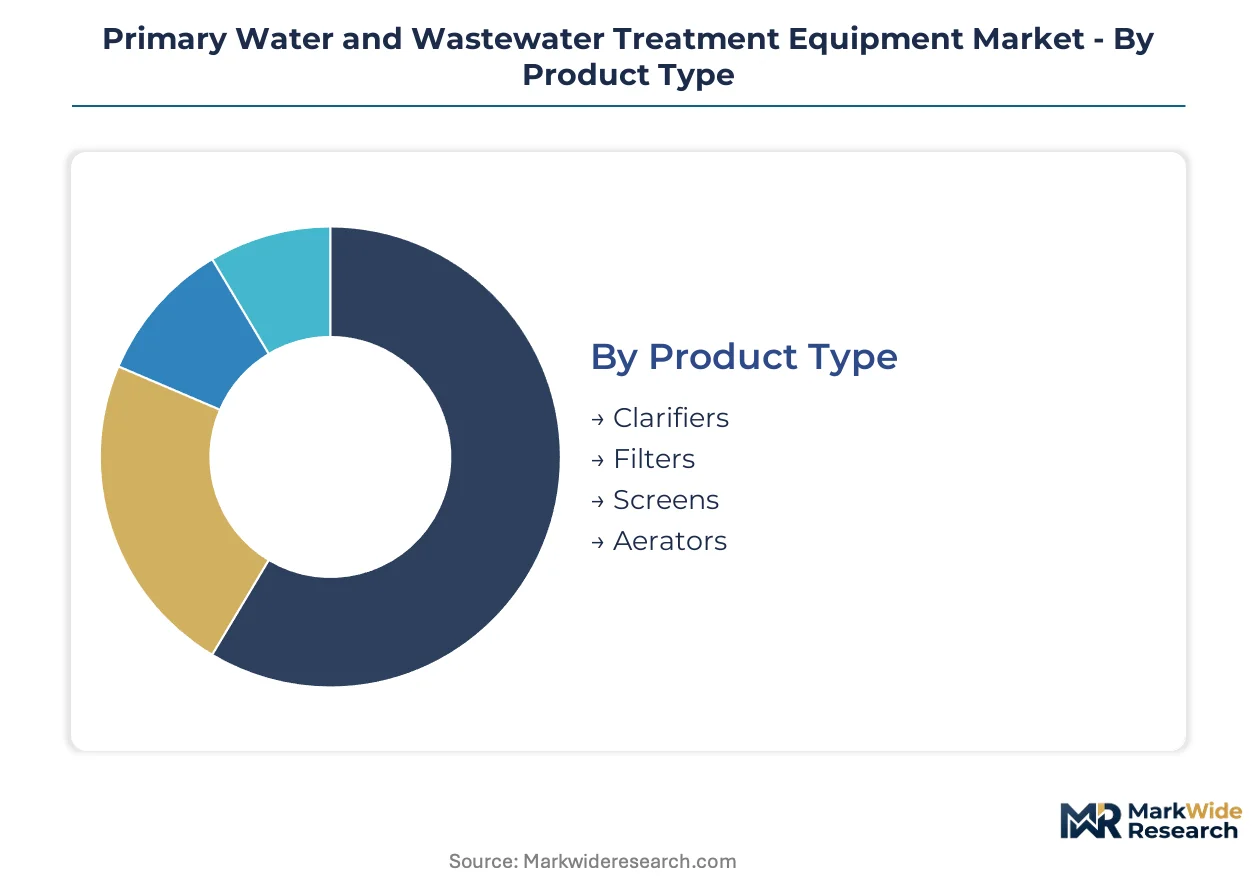
Segmentation in primary treatment equipment reveals divergent margin structures across civil-works-intensive clarifiers versus packaged skid systems. Procurement patterns split between municipal utilities favoring integrated screening-to-clarification workflows and industrial buyers unbundling service from hardware.
Product Type:
Margin pools concentrate in clarifiers due to structural steel intensity and basin civil works, while screens capture premium pricing in coastal flood-prone deployments.
- Clarifiers:Circular and rectangular sedimentation basins with automated sludge blanket controls dominate municipal utility procurement. Demand concentrates in drought-prone US states where utilities expand primary capacity ahead of biological upgrades.
- Screens:Bar screens and fine screens with real-time debris load sensing protect downstream biological assets. Coastal municipalities facing intensified stormwater patterns are accelerating installations to prevent clarifier fouling.
- Filters:Granular media and membrane pre-treatment units capture residual solids post-clarification. Industrial zero-liquid-discharge clusters in China's Pearl River delta specify these for reuse compliance.
- Aerators:Surface and diffused aeration equipment supports biological pre-treatment stages. Food and beverage processors deploy these for high-strength organic load conditioning.
Clarifiers hold installed capacity. Screens are rotating up the share rankings.
Application:
Volume concentration tracks capital allocation patterns, with municipal utilities front-loading primary treatment investment ahead of biological system upgrades.
- Municipal:City utilities operate gravity sedimentation and bar screening at 1-3 hour hydraulic retention times. US EPA effluent guideline revisions are forcing physical screening upgrades across aging infrastructure.
- Industrial:Manufacturing facilities deploy compact dissolved air flotation and chemically enhanced primary treatment. China's MEE enforcement along the Yangtze River delta mandates robust pre-processing for discharge permits.
- Agricultural:Livestock and irrigation operations utilize simplified screening and settling for nutrient-laden runoff. Nutrient removal obligations under the EU Green Deal are cascading to primary stage reliability.
- Recreational:Golf courses and park districts install small-scale clarification for stormwater retention ponds. These applications favor packaged skid systems over engineered civil works.
Municipal anchors procurement volume. Industrial is expanding most quickly.
Technology:
Pricing stratification separates premium advanced oxidation systems from standardized physical treatment, with hybrid chemical-physical configurations capturing mid-tier industrial reuse applications.
- Physical Treatment:Gravity sedimentation, bar screening, and dissolved air flotation remove settleable solids and floatables without chemical addition. This technology leads installed base volumes across municipal networks.
- Chemical Treatment:Coagulant-enhanced primary treatment improves solids capture efficiency. German and Dutch utilities specify these systems to meet tightened EU urban wastewater directive reliability requirements.
- Biological Treatment:Pre-denitrification and anaerobic stages reduce organic loading ahead of secondary processes. These configurations appear in nutrient-sensitive watersheds.
- Advanced Oxidation:Ozonation and UV-based processes target emerging contaminants for industrial reuse. Electronics manufacturers in China's industrial corridors deploy these for zero-liquid-discharge compliance.
Physical treatment dominates installed capacity. Advanced oxidation is climbing the fastest.
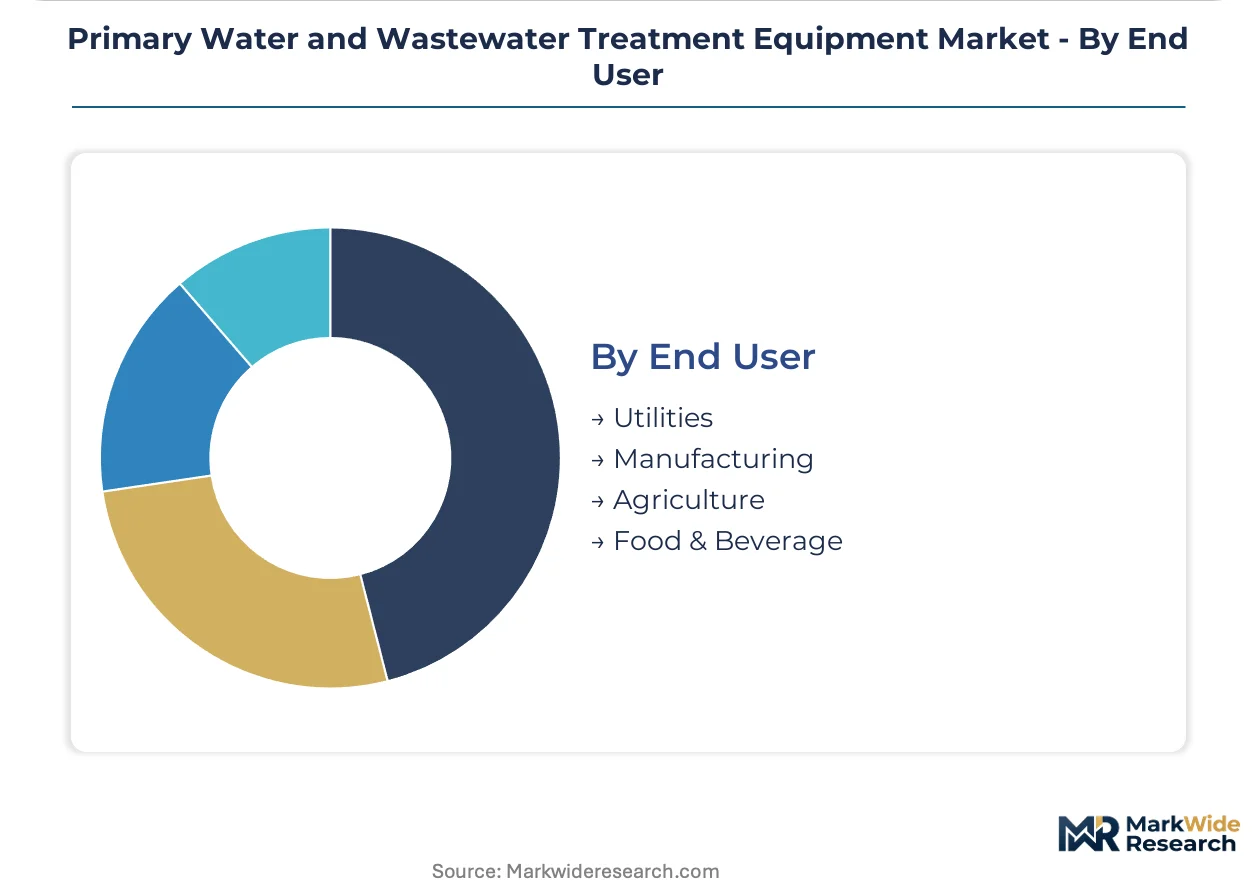
End User:
Customer-type differentiation reflects procurement sophistication, with utilities favoring integrated long-term contracts and manufacturing segments unbundling service from equipment.
- Utilities:Municipal water and wastewater authorities specify clarifier-centric workflows with 20-year asset lifecycles. India's AMRUT 2.0 mission is extending procurement to tier-2 and tier-3 cities.
- Manufacturing:Electronics and textile clusters contract maintenance separately through third-party water service operators. This pattern is concentrated in China's Pearl River delta.
- Agriculture:Irrigation districts and livestock operations prioritize low-maintenance screening equipment. These buyers favor standardized configurations over customized engineering.
- Food & Beverage:Processors facing high-strength organic loads adopt compact flotation units at twice the pace of conventional sedimentation. Dissolved air flotation technology is decomposing clarifier dominance in this segment.
Utilities anchor equipment value. Food and beverage is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German clarifier manufacturers export engineered steel basins to Dutch and Danish utilities upgrading under EU Green Deal mandates. This trade corridor channels fabrication expertise toward nutrient-sensitive watersheds while Chinese industrial clusters source compact dissolved air flotation systems domestically.
United States
Drought-prone utilities in Arizona, Texas, and California are expanding primary treatment capacity ahead of biological upgrades. The US EPA's revised effluent limitation guidelines mandate specific total suspended solids removal efficiencies that force physical screening retrofits across aging municipal infrastructure. Houston and Phoenix anchor procurement demand for circular clarifiers with automated sludge blanket controls.
Germany
Dutch and Danish utilities import German-engineered clarifier basins to meet tightened reliability requirements under the EU urban wastewater treatment directive revision. The EU Green Deal cascades nutrient removal obligations backward to primary process performance guarantees. The Ruhr industrial corridor hosts fabrication capacity for automated screening-to-clarification workflows serving Rhine watershed municipalities.
China
Industrial corridor cities along the Yangtze and Pearl River deltas are deploying robust primary processing capacity under MEE zero-liquid-discharge enforcement. The country's dual carbon goals tighten discharge permits for electronics and textile clusters. Shenzhen and Suzhou concentrate demand for chemically enhanced primary treatment paired with dissolved air flotation for reuse compliance.
India
Tier-2 and tier-3 cities under the AMRUT 2.0 national mission are extending sewerage coverage beyond metropolitan cores into underpenetrated municipal markets. The Central Public Health and Environmental Engineering Organisation sets design standards for primary treatment infrastructure. Ahmedabad and Jaipur represent emerging procurement nodes for bar screens and grit chambers as state utilities front-capital investment.
Netherlands
German and Belgian equipment suppliers capture contracts for integrated screening-to-clarification workflows serving Randstad urban utilities. The EU Green Deal's urban wastewater treatment directive revision expands nutrient removal requirements that cascade to primary stage reliability. Rotterdam and Amsterdam anchor demand for automated sludge blanket level controls and real-time flow pacing systems.
Primary Water and Wastewater Treatment Equipment Market Key Industry Players
Player mix skews toward integrated water technology conglomerates with clarifier-centric municipal workflows and specialized chemical-physical system providers for industrial reuse. Market structure concentrates around three strategic archetypes: full-service utilities contractors with 20-year asset lifecycle offerings, compact packaged system specialists capturing mid-scale manufacturing contracts, and regional fabrication champions serving geographically concentrated utility networks. Dominant competitive moves include backward integration into structural steel basin fabrication and technology licensing partnerships for dissolved air flotation process controls.
Within the integrated conglomerate tier, Xylem Inc., SUEZ, and Veolia Water Technologies exemplify divergent geographic anchoring strategies. Xylem occupies a position representing North American utility network penetration with clarifier installation workflows. SUEZ anchors European municipal contracts through screening-to-clarification integration capabilities. Veolia Water Technologies sits within the industrial reuse application space, exemplifying chemical-physical hybrid system deployment for manufacturing end users requiring zero-liquid-discharge compliance.
| Leading Market Players |
|---|
| Fluence Corporation Limited |
| SUEZ |
| Veolia Water Technologies |
| Kurita Water Industries Ltd. |
| Grundfos |
| Xylem Inc. |
| Aquatech International Corporation |
| WesTech Engineering |
| Evoqua Water Technologies |
| Others |
Cost & Logistics Intelligence
Twenty-four to thirty-six week lead times for structural steel clarifier basins concentrate pricing power with German and Chinese fabricators capable of in-house rolling mill capacity, while municipal utilities absorb cost volatility through fixed-bid contract structures that squeeze margin at the project-execution tier.
Pricing Analysis
The physical-chemical-advanced oxidation technology-generation pricing gap stratifies equipment procurement across three performance tiers. Premium-mid-economy pricing differentiation separates clarifier-centric municipal workflows with 20-year service bundling from compact dissolved air flotation skids sold on per-unit transactional terms to industrial buyers. Pricing pressure stems from structural steel volatility compressing fixed-bid municipal contracts, with tier-2 Indian utilities exhibiting highest price sensitivity against North American drought-state authorities prioritizing reliability guarantees over capital cost minimization.
Supply Chain Analysis
Germany and China anchor engineered steel basin fabrication for circular clarifiers serving Rhine and Yangtze watershed utilities. Raw material feeds draw from specialty structural steel grades, corrosion-resistant coating systems, and precision sludge blanket instrumentation. Single-source vulnerability concentrates in German automated drive component suppliers for clarifier mechanisms. Distribution runs through EPC contractors and third-party water service operators unbundling maintenance from initial hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in industrial reuse applications where municipal-centric incumbents under-serve manufacturing clusters demanding chemically enhanced primary treatment expertise. The unbundling of after-sales service from equipment procurement creates niche entry points for specialized operators.
For Market Incumbents: Shield clarifier installation workflows in North American utility networks through backward integration into structural steel basin fabrication, countering margin compression from volatile input costs. Deepen captive supply of automated sludge blanket controls to meet EU Green Deal reliability mandates cascading to primary stages. For New Entrants and Emerging Players: Aftermarket service contract fragmentation in China's Pearl River delta electronics clusters offers white-space penetration where original equipment suppliers lack localized chemical-physical system expertise. Target India's AMRUT 2.0 tier-2 cities through packaged skid configurations bypassing civil-works-intensive clarifier competition. Lead with third-party operator partnerships rather than direct equipment sales. For Investors and Strategic Acquirers: Long-term, this sits as a utility-to-industrial pivot play because regulatory tightening on effluent quality redirects capital from conventional municipal infrastructure toward manufacturing reuse applications. Acquisition focus centers on compact dissolved air flotation specialists with zero-liquid-discharge compliance track record. Watch for MEE enforcement intensity along Yangtze industrial corridors as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Structural Steel Fabrication | Captive basin production insulates margin from commodity volatility affecting German and Chinese competitors. |
| Chemical-Physical Hybrid System Development | Coagulant-enhanced primary treatment opens industrial reuse contracts previously requiring full biological trains. |
| Automated Screening Control Deployment | Real-time debris load sensing meets EU urban wastewater directive reliability requirements cascading from nutrient mandates. |
| Third-Party Service Operator Partnership | Localized maintenance expertise captures unbundled contracts in China's zero-liquid-discharge electronics clusters. |
| Packaged Skid System Expansion | Compact dissolved air flotation units penetrate mid-scale food and beverage manufacturing previously reserved for engineered civil works. |
Research Approach
The analysis maps clarifier, screen, filter, and aerator sub-sectors, each validated through utility capital planning directors, industrial facility engineers, EPC contractor procurement leads, and aftermarket service operators. Primary interview findings triangulate against EPA effluent guideline filings, MEE discharge permit databases, EU urban wastewater directive revision texts, and customs trade data for structural steel equipment imports. Bottom-up project pipeline assessment and top-down regulatory-driven capital allocation modeling converge on segment-level demand estimates.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type, application category, technology tier, and end-user procurement sophistication. CAGRs derive from regulatory-mandated upgrade cycle timing and industrial capacity expansion announcements. Forecast inputs incorporate hydraulic retention time specifications and sludge blanket control automation penetration curves.
Underlying assumptions cover continued EPA guideline enforcement, MEE zero-liquid-discharge mandate expansion, and EU Green Deal directive implementation, with deviation risk concentrated in structural steel commodity volatility and municipal budget cycle delays. Recalibration cycles align with material shifts in regulatory tightening schedules and industrial corridor discharge permit revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market
Water and Wastewater Treatment
Packaged Wastewater Treatment Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Water Testing Meter Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Global Biological Wastewater Treatment Market
Water and Wastewater Treatment
Latin America Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Global Enhanced Water Market