
 Tertiary Water and Wastewater Treatment Equipment Market | 2026-2036
Tertiary Water and Wastewater Treatment Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Tertiary Water and Wastewater Treatment Equipment Market Analytics
Industrial facilities is reorganizing procurement priorities around zero-liquid discharge and micropollutant removal, pulling capital away from traditional municipal buyers. Veolia Environnement S.A. anchors its position through integrated service contracts spanning operations and equipment replacement cycles. Xylem Inc. differentiates via digital monitoring platforms bundled with tertiary hardware. Pentair plc competes on modular skid-mounted systems that reduce on-site construction timelines for pharmaceutical and semiconductor plants.
Tertiary water and wastewater treatment equipment encompasses advanced physical, chemical, and biological processes applied after secondary treatment to remove residual suspended solids, dissolved organics, nutrients, pathogens, and emerging contaminants before discharge or reuse. Membrane bioreactor systems typically operate at flux rates of 15–30 LMH with pore sizes below 0.1 micron, while reverse osmosis units achieve salt rejection exceeding 99% for high-purity industrial applications. Filtration Systems and Reverse Osmosis Systems capture the dominant share of product-type revenue as industrial users prioritize water recovery ratios above 85%. Membrane Technology leads technology adoption due to declining unit costs per cubic meter and expanding applications in brackish water desalination and process water recycling.
The EPA enforces effluent limitation guidelines that mandate nutrient removal for municipal and industrial dischargers, while the EU Urban Wastewater Treatment Directive and REACH framework restrict chemical additives and set micropollutant watch lists that shape equipment specifications. China's MEE enforces increasingly stringent Class IV surface water standards that tertiary systems must achieve for direct discharge. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance thresholds for per- and polyfluoroalkyl substances and pharmaceutical residues will determine which membrane and advanced oxidation technologies achieve design-in status across municipal and industrial project pipelines.
Market Dynamics
Membrane technology cost compression is redrawing competitive boundaries between equipment tiers, forcing suppliers to bundle digital monitoring and service contracts to defend margin structures.
Growth Catalysts
- EU Urban Wastewater Treatment Directive:Nutrient removal mandates in Germany and France are accelerating membrane bioreactor retrofits at municipal plants.
- Zero-liquid discharge rules:India's Central Pollution Control Board enforcement in textiles and pharmaceuticals is pulling capital toward reverse osmosis and evaporation systems.
- Semiconductor fabrication:Ultra-pure water requirements in Taiwan and South Korea are driving 99%-plus salt rejection specifications for process water recycling.
Market Restraints
- Membrane replacement cycles:Polyamide thin-film composite elements require 3-5 year replacement, creating recurring opex burdens that delay municipal procurement approvals.
- Skilled technician scarcity:Advanced oxidation process calibration and membrane integrity testing demand certified operators unavailable in secondary cities across Southeast Asia.
- Energy intensity:Reverse osmosis systems consume 3-4 kWh per cubic meter, exposing operators to electricity price volatility in markets with fossil-dependent grids.
Strategic Opportunities
- Vietnam's Red River Delta:Industrial park wastewater discharge rules are tightening faster than local supplier capacity, creating openings for packaged tertiary skid systems.
- UV-LED convergence:Mercury-free disinfection modules paired with advanced oxidation are reducing footprint and chemical handling at pharmaceutical sites.
- Performance-based service contracts:Municipal authorities in Indonesia are piloting availability-payment models that shift capex risk to equipment-service integrators.
Industry Challenges
- Legacy SCADA integration:Brownfield municipal plants operate 1990s-era control architectures that resist API connectivity with cloud-based membrane monitoring platforms.
- PFAS analytical capacity:Detection of per- and polyfluoroalkyl substances at parts-per-trillion levels requires lab infrastructure absent from most industrial facility quality departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tertiary Water and Wastewater Treatment Equipment Market |
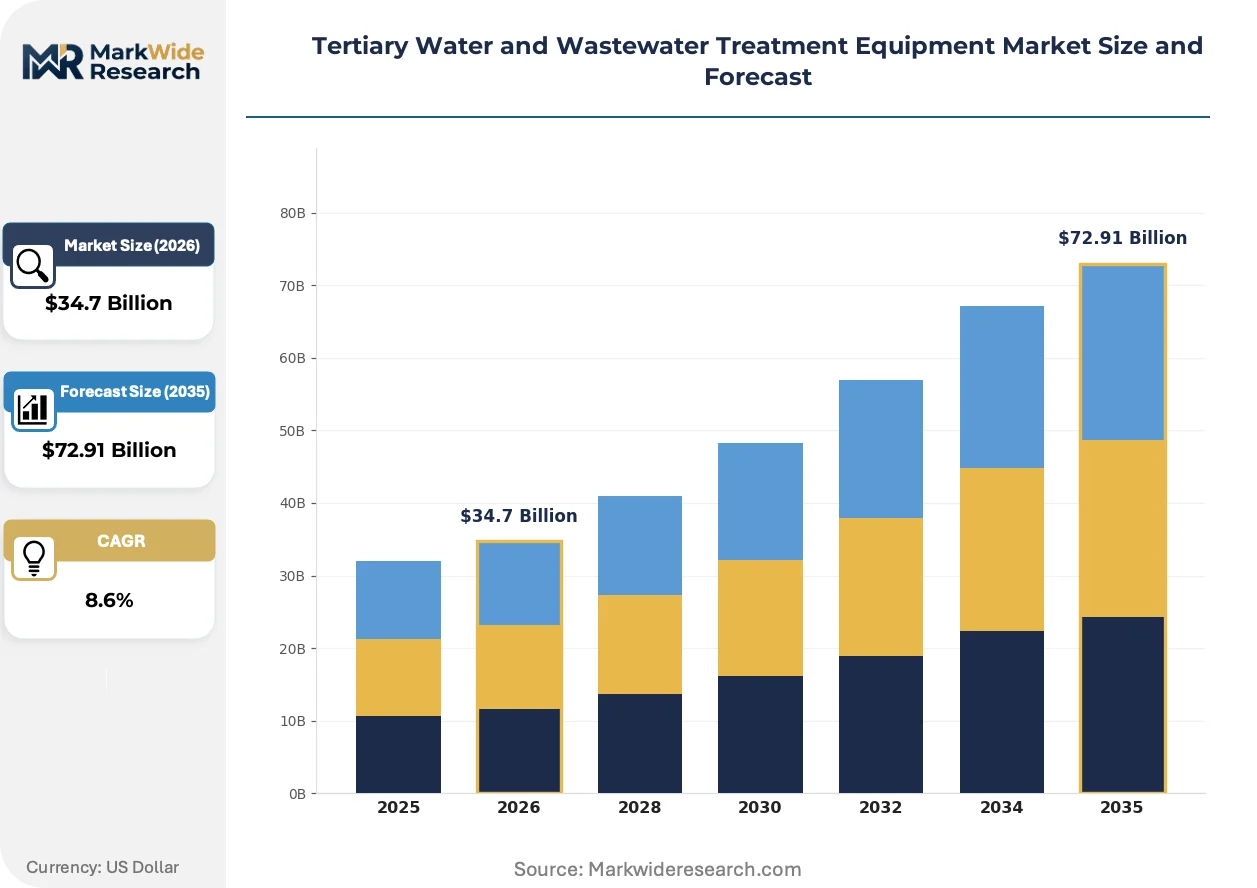
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtration Systems, UV Disinfection Units, Chlorination Equipment, Reverse Osmosis Systems Technology: Treatability Processes, Membrane Technology, Chemical Treatment, Biological Treatment End User: Municipal Water Authorities, Industrial Facilities, Agricultural Operations, Research Institutions Installation: On-site Installations, Centralized Systems, Modular Solutions, Retrofit Applications |
| Companies Covered | Veolia Environnement S.A., Xylem Inc., SUEZ Group, Ecolab Inc., Pentair plc, DuPont de Nemours, Inc., Aquatech International LLC, 3M Company, Inc., Calgon Carbon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tertiary Water and Wastewater Treatment Equipment Market Evolving Landscape
Equipment manufacturers are embedding predictive algorithms directly into membrane skids, shifting value capture from hardware sales to uptime-guaranteed service arrangements.
Ceramic membrane modules with titanium dioxide photocatalytic coatings are supplanting polymeric ultrafiltration in high-temperature industrial streams. Food and beverage processors in the Netherlands and California are adopting these systems for protein recovery and CIP wastewater reuse. The shift is compressing replacement frequencies from 5 years to 10-plus years while enabling steam sterilization protocols incompatible with polymer substrates.
REACH framework updates adding pharmaceutical residues and microplastics to watch lists are forcing equipment specification changes across EU municipal tenders. German utilities now require advanced oxidation capability as standard in membrane bioreactor packages, not optional add-ons. Italian and Spanish equipment distributors report 18-month backlog extensions as engineering teams redesign validation protocols for emerging contaminant removal claims.
Buying committees at Indian textile clusters are consolidating vendor relationships from 4-5 suppliers per plant to single-source integrated service contracts. The compression reflects zero-liquid discharge compliance deadlines and the operational complexity of managing multiple membrane technologies. Tamil Nadu and Gujarat state pollution control boards are accelerating this consolidation by requiring certified operator training as a condition of discharge permit renewal.
Tertiary Water and Wastewater Treatment Equipment Market Segmentation
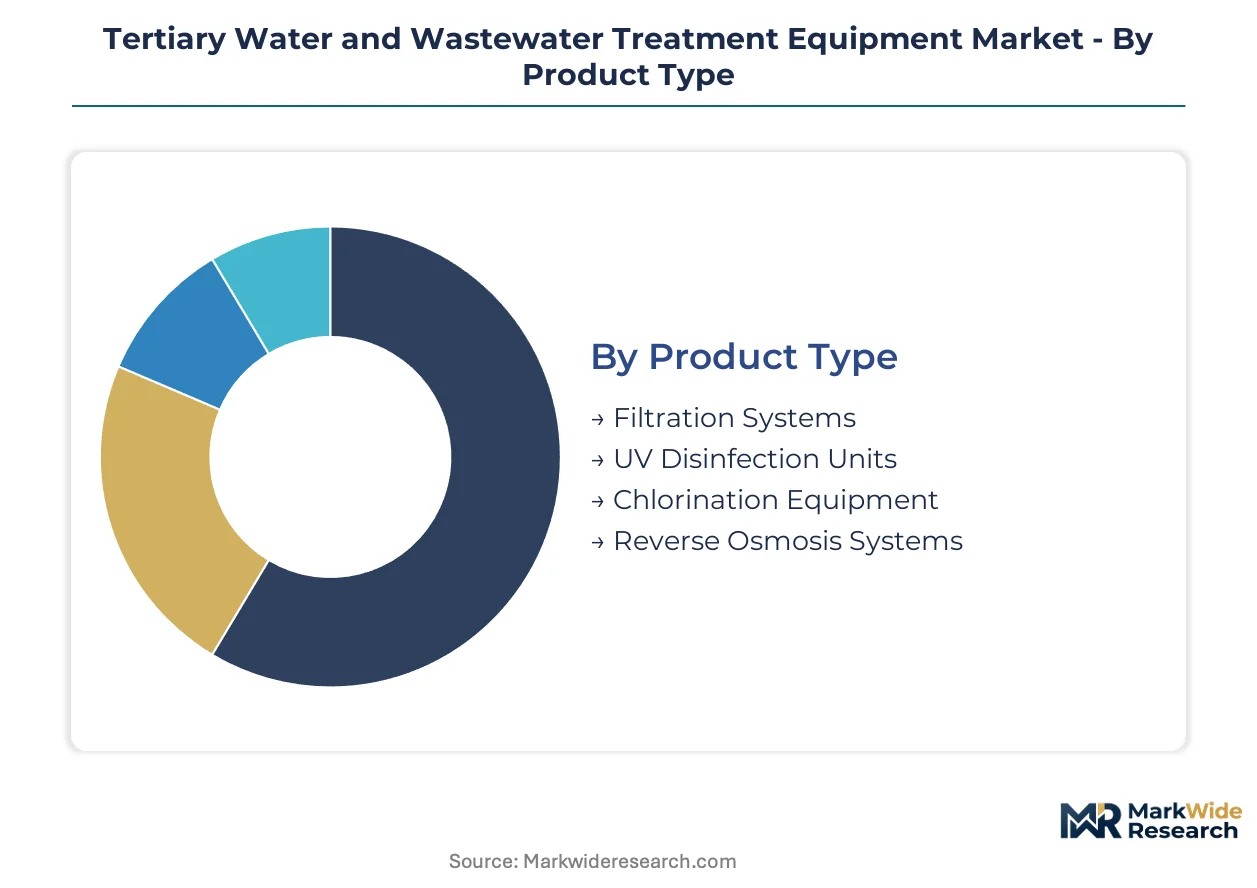
Tertiary equipment segmentation reveals where capital allocation shifts as membrane cost compression and digital integration reshape procurement priorities across municipal and industrial buyers.
Product Type:
Substitution pressure from membrane-based systems is forcing traditional chemical and physical treatment segments to bundle monitoring services or retreat to niche applications.
- Filtration Systems:Multi-media and activated carbon configurations remove residual suspended solids and organics downstream of secondary clarifiers. Demand concentrates in India's textile clusters where zero-liquid discharge rules mandate 85%-plus water recovery ratios before evaporation stages.
- Reverse Osmosis Systems:Polyamide thin-film composite membranes achieve 99%-plus salt rejection for semiconductor fabrication and pharmaceutical process water. Taiwan and South Korea fabs specify these units for ultra-pure water recycling loops that feed lithography and wafer cleaning stations.
- UV Disinfection Units:Low-pressure mercury and emerging UV-LED arrays inactivate pathogens without chemical residuals.
- Chlorination Equipment:Sodium hypochlorite and on-site electrochlorination systems persist in cost-sensitive municipal applications with legacy infrastructure.
Filtration Systems anchors the volume base while Reverse Osmosis Systems gains share at the steepest rate.
Technology:
Cost tiers separate mature chemical methods from membrane platforms where declining unit economics per cubic meter are displacing conventional trains.
- Membrane Technology:Microfiltration, ultrafiltration, nanofiltration, and reverse osmosis modules operate at flux rates of 15–30 LMH with pore precision below 0.1 micron. Germany and France municipal retrofits under EU nutrient removal mandates are accelerating membrane bioreactor deployments at aging activated sludge plants.
- Treatability Processes:Advanced oxidation using ozone, UV/hydrogen peroxide, and Fenton reactions mineralize recalcitrant organics and pharmaceutical residues. REACH framework watch list expansion is forcing Italian and Spanish utilities to specify oxidation capability as standard in new tenders.
- Chemical Treatment:Coagulation, flocculation, and pH adjustment remain prevalent in developing markets with lower electricity reliability.
- Biological Treatment:Fixed-film and suspended growth polishers target nutrient removal where space constraints limit physical expansion.
Membrane Technology commands the premium tier while Treatability Processes expands most quickly on emerging contaminant compliance.
End User:
Customer type determines specification intensity, with industrial buyers demanding 99%-plus purity and municipal authorities prioritizing operational simplicity.
- Industrial Facilities:Semiconductor, pharmaceutical, and textile plants specify skid-mounted tertiary trains with digital monitoring integration. India's Central Pollution Control Board enforcement in Tamil Nadu and Gujarat is consolidating vendor relationships toward single-source service contracts.
- Municipal Water Authorities:Southeast Asian cities deploy membrane bioreactors to meet tightening effluent standards with limited operator pools.
- Agricultural Operations:Nutrient recovery and irrigation reuse applications favor lower-cost filtration and UV configurations.
- Research Institutions:Pilot-scale advanced oxidation and membrane testing equipment supports technology validation for commercial scale-up.
Industrial Facilities anchors the volume base while Municipal Water Authorities climbs the fastest on infrastructure renewal cycles.
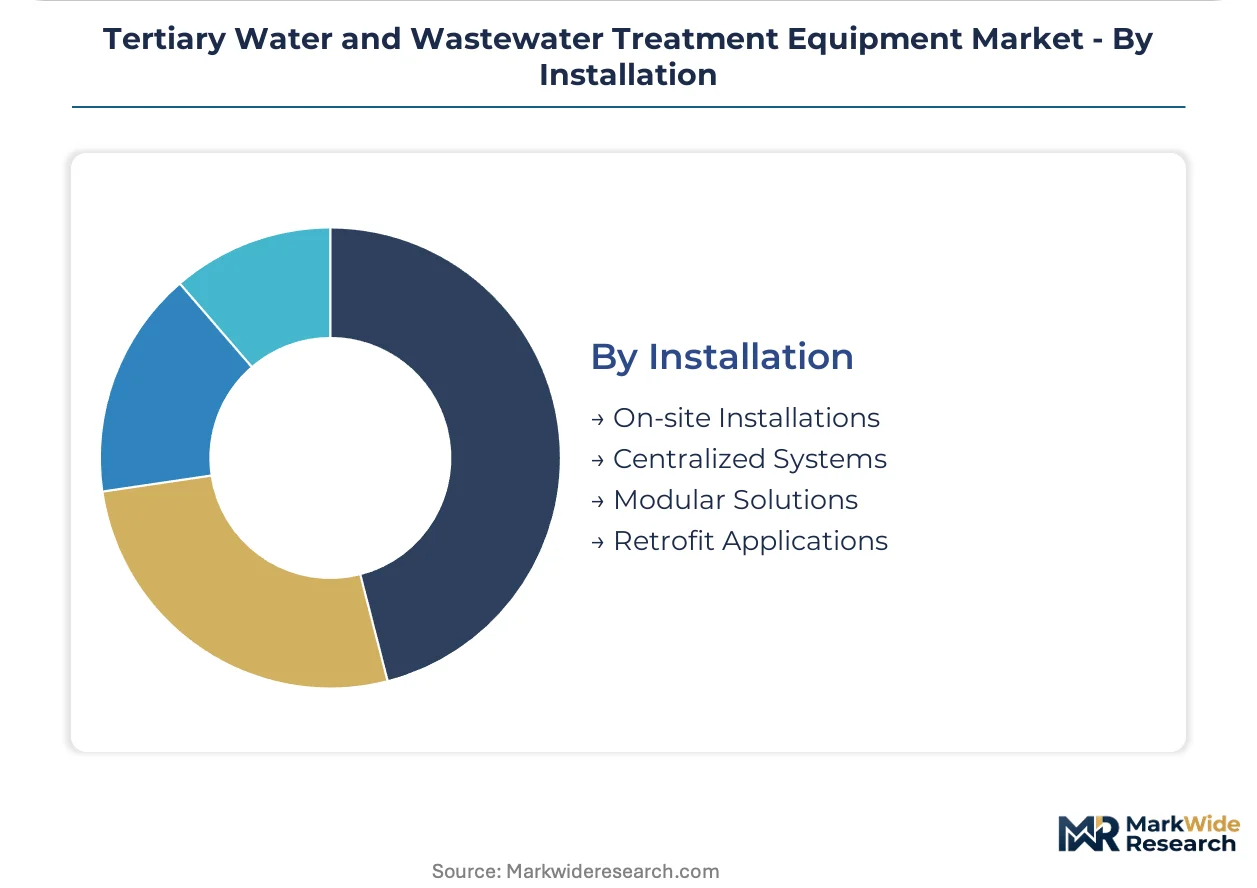
Installation:
Supply concentration among modular specialists is displacing field-erected systems where construction timelines and skilled labor scarcity delay project completion.
- Modular Solutions:Pre-engineered skid-mounted systems integrate membranes, pumps, and controls for rapid deployment. Vietnam's Red River Delta industrial parks specify these units as local supplier capacity lags behind tightening discharge rule implementation.
- Retrofit Applications:Brownfield membrane bioreactor upgrades and tertiary additions to existing activated sludge plants dominate European and North American capital planning.
- On-site Installations:Custom-built trains persist for large-volume industrial users with site-specific water quality challenges.
- Centralized Systems:Regional tertiary hubs serving multiple municipalities remain limited to dense urban corridors with coordinated planning authorities.
Modular Solutions anchors the volume base while Retrofit Applications shows the steepest expansion trajectory on aging infrastructure replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's role in advanced membrane fabrication and municipal system deployment. Major port infrastructure across East Asia's manufacturing belts drives concentrated demand for ultra-pure water recycling systems.
Germany
Membrane bioreactor retrofits dominate capital planning at aging activated sludge plants. The EU Urban Wastewater Treatment Directive mandates nutrient removal thresholds that force equipment upgrades. Bavarian and North Rhine-Westphalian utilities specify advanced oxidation capability as standard in new tenders, not optional add-ons.
United States
Semiconductor fabrication clusters in Arizona and Texas specify 99%-plus salt rejection systems for lithography water loops. EPA effluent limitation guidelines enforce nutrient removal for municipal and industrial dischargers. The Colorado River Basin states accelerate procurement of zero-liquid discharge trains as drought conditions intensify water reuse mandates.
India
Textile clusters in Tamil Nadu and Gujarat consolidate vendor relationships toward single-source service contracts. The Central Pollution Control Board enforces zero-liquid discharge rules that pull capital toward reverse osmosis and evaporation systems. National missions for clean water accelerate procurement of UV disinfection infrastructure across secondary cities.
China
Class IV surface water standards from MEE require tertiary system achievement for direct discharge permits. Yangtze River Delta semiconductor fabs drive demand for ultra-pure water recycling with process water recovery ratios above 85%. Shandong Peninsula chemical parks deploy packaged tertiary skids as local supplier capacity lags behind tightening discharge implementation.
Vietnam
Red River Delta industrial parks specify modular skid-mounted systems as construction timelines compress. National wastewater discharge rules tighten faster than local engineering capacity can field-erect custom trains. Bac Ninh and Hai Phong manufacturing zones pilot performance-based service contracts that shift capex risk to equipment-service integrators.
Tertiary Water and Wastewater Treatment Equipment Market Competitive Landscape
Listed leaders compete with private specialists across service integration and digital platform bundling. The vendor base spans three tiers: integrated water-service conglomerates with operations contracts, equipment-focused manufacturers with modular product lines, and regional system integrators with project execution capabilities. Consolidation pressure intensifies as membrane cost compression erodes hardware margins and pushes players toward recurring revenue models. Dominant competitive moves include backward integration into membrane element production and geographic expansion through local manufacturing joint ventures.
Within the integrated service tier, Veolia Environnement S.A. and SUEZ Group exemplify archetypes that bundle operations, maintenance, and equipment replacement cycles under long-term contracts. Xylem Inc. occupies a position representing the digital-native equipment manufacturer archetype, differentiating through monitoring platforms bundled with tertiary hardware rather than standalone hardware sales. These three anchors illustrate how competitive positioning increasingly depends on service contract duration and uptime guarantees rather than unit shipment volumes.
| Leading Market Players |
|---|
| Veolia Environnement S.A. |
| Xylem Inc. |
| SUEZ Group |
| Ecolab Inc. |
| Pentair plc |
| DuPont de Nemours, Inc. |
| Aquatech International LLC |
| 3M Company, Inc. |
| Calgon Carbon Corporation |
| Others |
Value Network & Pricing Analysis
REACH framework updates and EPA effluent guidelines gate supply qualification while simultaneously stratifying price tiers based on contaminant removal certification levels. Buyers in the EU and United States face dual hurdles: membrane modules must demonstrate pharmaceutical residue and PFAS removal capability to qualify for tenders, while price premiums attach to validated performance guarantees.
Pricing Analysis
Volume-discount tiering structures separate municipal bulk procurement from industrial spot purchases. Three-tier pricing stratifies across premium certified systems, standard membrane configurations, and economy-grade chemical treatment trains. Price differentiation hinges on salt rejection certification tiers and bundled digital monitoring service levels. Cost compression in polyamide thin-film composites is intensifying because Chinese membrane manufacturers are expanding capacity. Municipal water authorities in Southeast Asia exhibit highest price sensitivity, while semiconductor fabs in Taiwan and South Korea show least sensitivity due to uptime guarantee requirements.
Supply Chain Analysis
Japan and Germany anchor high-precision membrane element fabrication, while China dominates polyamide resin and module housing production. Raw material dependencies draw from specialty polymer feedstocks, titanium dioxide photocatalytic coatings, and precision pump components. Single-source vulnerability concentrates in advanced ceramic membrane substrates where Japanese suppliers control sintering expertise. Distribution runs through equipment-service integrators who bundle installation with long-term maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital platform interoperability between membrane monitoring systems and municipal SCADA architectures is creating platform-economics inflection points. Equipment vendors who achieve API standardization gain ecosystem lock-in advantages.
For Market Incumbents: Fortify position through backward integration into membrane element production and captive supply of polyamide resins. Emerging Chinese membrane manufacturers threaten margin structures in standard-tier equipment. Certification investment in REACH-compliant pharmaceutical residue removal validates premium pricing tiers.
For New Entrants and Emerging Players: EU MDR-equivalent fast-track certification for PFAS removal capability opens municipal tender access previously blocked by incumbent validation histories. Vietnam's Red River Delta industrial parks represent most penetrable geography due to supplier capacity gaps. Go-to-market through performance-based service contracts shifts capex risk and accelerates reference site accumulation.
For Investors and Strategic Acquirers: EPA pharmaceutical residue monitoring mandates reshape the acquisition landscape toward advanced oxidation specialists. Five-to-ten year viability favors equipment-service integrators with recurring revenue models over pure hardware manufacturers. Target acquisition archetype: regional system integrators with certified operator training capabilities in India and Southeast Asia. Signal to watch: consolidation of textile cluster vendor relationships from multi-supplier to single-source contracts in Tamil Nadu and Gujarat.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Elements | Captive polyamide resin supply defends margin compression from Chinese entrants. |
| Digital Platform Certification | API standardization with municipal SCADA systems creates switching cost barriers. |
| Performance-Based Service Contracts | Availability-payment models shift capex risk and extend customer lock-in duration. |
| Advanced Oxidation Capability Integration | REACH pharmaceutical residue mandates make oxidation standard in EU tenders. |
| Regional Manufacturing Joint Ventures | Local production in Vietnam and India circumvents logistics bottlenecks and tariff exposure. |
Research Methodology
A standing panel of municipal plant engineers, industrial facility managers, membrane technology R&D directors, and equipment procurement officers provided ongoing calibration. Primary interviews combined with secondary validation from EPA effluent guideline databases, EU Urban Wastewater Treatment Directive implementation reports, and Central Pollution Control Board enforcement records. Bottom-up equipment shipment tracking triangulated against top-down capital expenditure surveys across municipal and industrial buyer segments.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for membrane module imports and project finance databases for municipal infrastructure awards. The analytical framework modeled product type, technology tier, end-user category, and installation format across the projection horizon. CAGRs derived from equipment replacement cycle analysis and regulatory compliance deadline clustering. Industry-specific inputs included semiconductor fab water recovery ratio specifications and textile cluster zero-liquid discharge implementation timelines.
Underlying assumptions cover regulatory enforcement intensity, membrane cost compression trajectories, and electricity price volatility in fossil-dependent grids, with deviation risk concentrated in PFAS analytical capacity buildout and skilled technician availability. Recalibration cycles align with material shifts in EU REACH framework updates and EPA effluent limitation guideline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Sludge Dewatering Equipment Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Javelle Water Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Global Wastewater Diffused Aerator Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Packaged Wastewater Treatment Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Sewage Treatment Service Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Ecological Wastewater Treatment Market