
 Biaxially Oriented Polyamide (BOPA) Films Market | 2026-2036
Biaxially Oriented Polyamide (BOPA) Films Market Size, Share, and Industry Trends Forecast 2026-2036
Biaxially Oriented Polyamide (BOPA) Films Market Analysis
Polymer engineering talent scarcity in advanced film extrusion is redrawing competitive boundaries across the BOPA value chain. Toray Industries leverages its captive resin synthesis capabilities to secure feedstock continuity. Kuraray Company anchors its position through specialized co-extrusion expertise in medical-grade barrier films. Xiamen Changsu Industrial Corporation Limited dominates Greater China supply through integrated stretching lines and regional logistics control.
Biaxially oriented polyamide films are manufactured by stretching cast polyamide sheets in both machine and transverse directions, typically achieving thickness tolerances within 51-100µm for standard packaging grades and above 150µm for heavy-duty industrial applications, to deliver exceptional oxygen barrier properties and puncture resistance for perishable goods protection. Barrier films command premium positioning as shelf-life extension requirements intensify across protein and dairy supply chains. Co-extruded films represent the fastest-growing product architecture, driven by multi-layer structures that eliminate separate lamination steps.
China's SAMR enforces GB standards for food-contact plastics that mandate migration testing for amide oligomers, while Japan's METI promotes resource-efficient packaging under its circular economy roadmap. The EU REACH framework restricts certain phthalate plasticizers in films entering European consumer goods channels. Stakeholders must monitor evolving substance restrictions across major destination markets and align R&D roadmaps with preemptive compliance certification.
Market Dynamics
Co-extrusion technology is compressing traditional lamination workflows while China's GB standards for food-contact materials force reformulation of amide-based barrier layers across Asian supply chains.
Growth Catalysts
- Extended shelf-life mandates:Protein and dairy processors in China and Southeast Asia specify multi-layer BOPA structures to reduce cold-chain spoilage losses.
- GB 4806.7-2016 migration limits:China's SAMR enforcement drives converter investment in oligomer-controlled resin grades for export-qualified output.
- Co-extrusion line expansion:Integrated stretching and layer-combining equipment eliminates separate adhesive lamination, cutting unit costs for high-volume converters.
Market Restraints
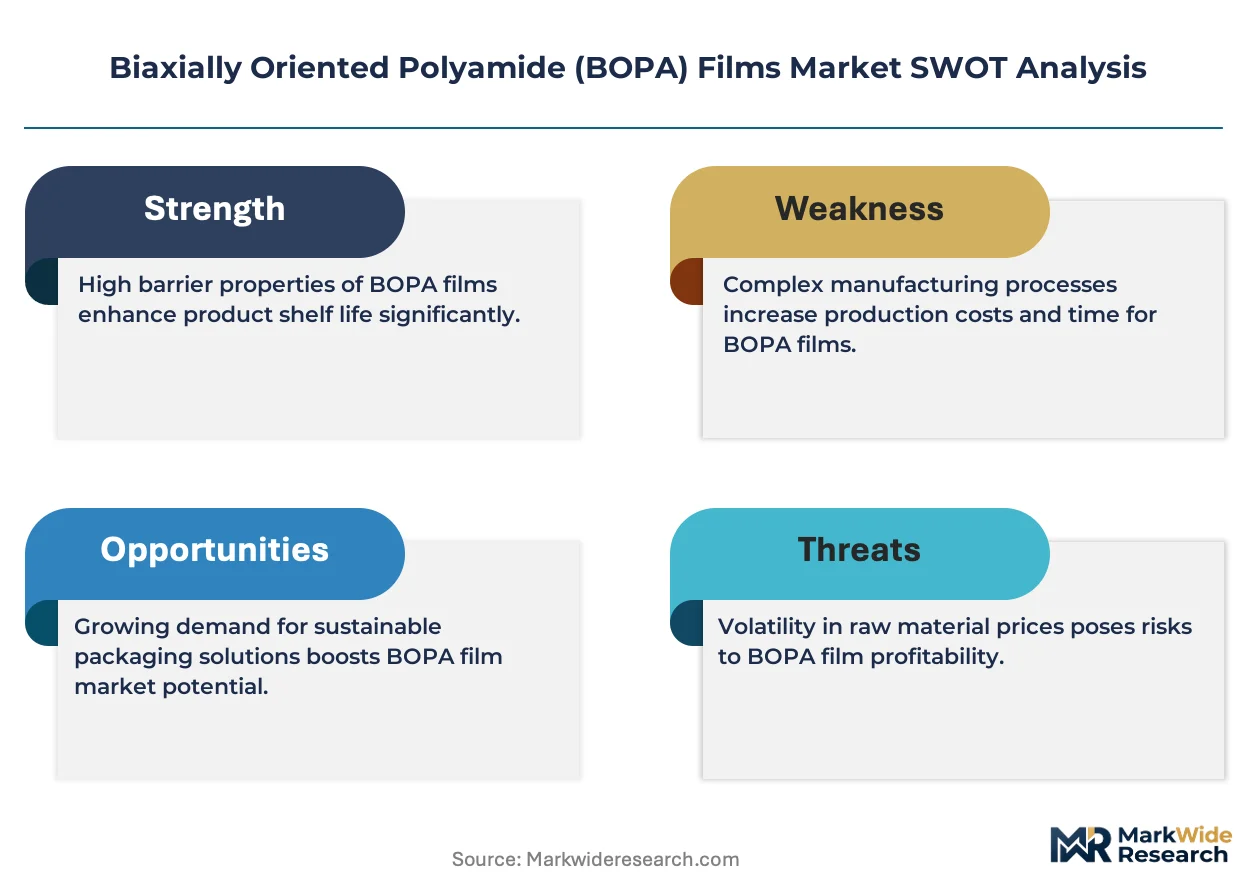
- Caprolactam feedstock volatility:Nylon-6 resin prices swing with benzene and cyclohexane derivative markets, squeezing film margin stability.
- Regional supply concentration:China's Yangtze River Delta hosts over half of Asian BOPA capacity, creating single-point disruption exposure.
- Polyethylene terephthalate substitution:PET films with metallized or oxide-coated layers capture cost-sensitive barrier applications in snack packaging.
Strategic Opportunities
- Medical-grade barrier films:Sterile pharmaceutical packaging in Japan and South Korea demands validated 150µm+ structures with documented lot traceability.
- India's FSSAI packaging modernization:Processed food sector expansion in Maharashtra and Gujarat creates demand for oxygen-barrier substrates meeting 12-month shelf-life targets.
- Digital printing compatibility:Corona-treated BOPA surfaces enable short-run flexible packaging for regional brand launches without plate costs.
Industry Challenges
- Polymer engineering talent scarcity:Biaxial stretching process control requires expertise spanning rheology, heat transfer, and web handling that few technical programs cultivate.
- Dual certification timelines:Simultaneous GB standard compliance for China and EU REACH registration for European export extends product qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biaxially Oriented Polyamide (BOPA) Films Market |
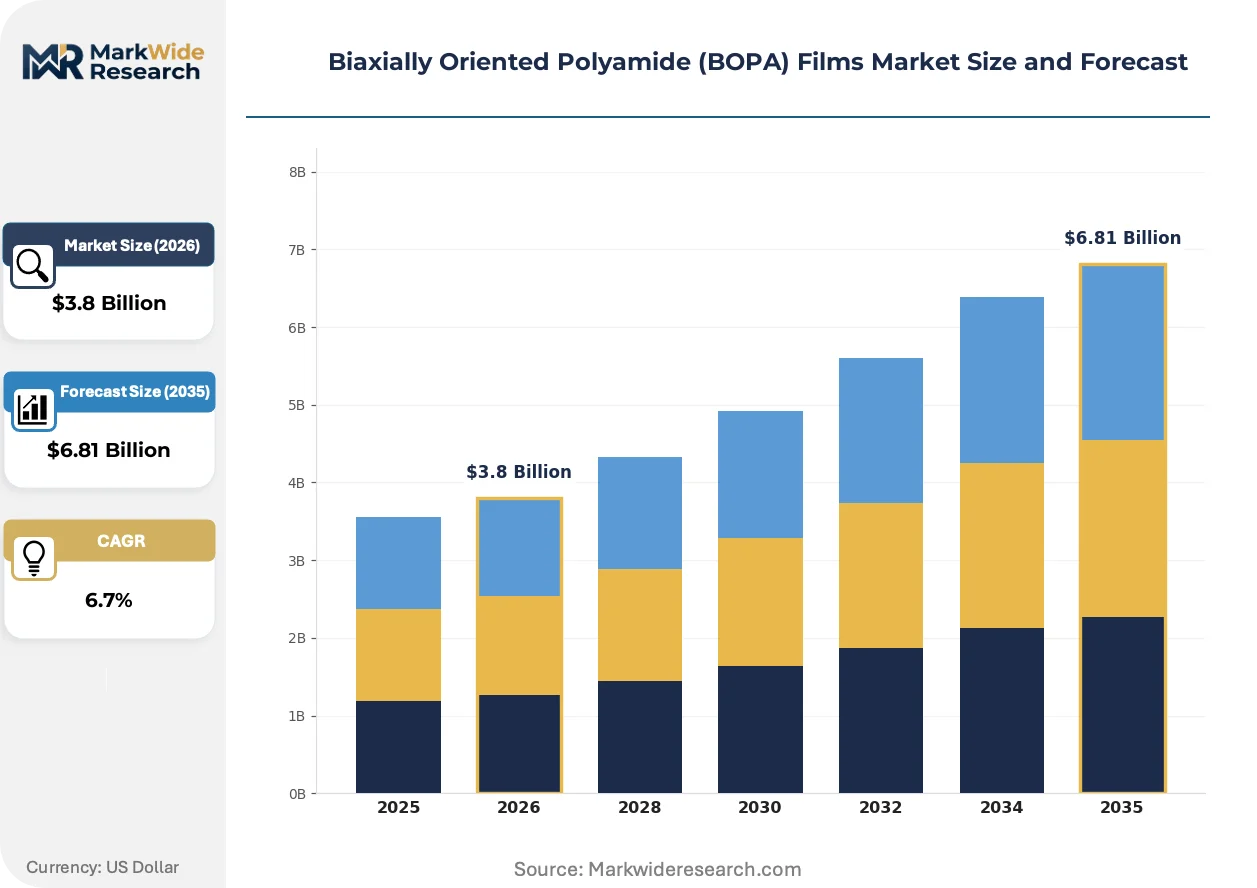
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Films, Barrier Films, Co-extruded Films, Metalized Films Application: Food Packaging, Medical Packaging, Electronics, Industrial Packaging End User: Food Industry, Pharmaceutical Industry, Automotive, Consumer Goods Thickness: Up to 50µm, 51-100µm, 101-150µm, Above 150µm |
| Companies Covered | Toyobo, Yuncheng Plastic Industry, AdvanSix, Toray Industries, Kuraray Company, Mitsubishi Chemical Corporation, Xiamen Changsu Industrial Corporation Limited, Mondi plc, Unitika Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biaxially Oriented Polyamide (BOPA) Films Market Emerging Trajectories
Process intensification and regulatory chemistry requirements are restructuring how BOPA films are formulated, certified, and sold into downstream channels.
Sequential biaxial stretching with inline thickness gauging is fragmenting the traditional split between machine-direction and transverse-direction specialist equipment. High-speed packaging converters in Japan and South Korea adopt these integrated lines to reduce gauge variation below 3% for thin-film applications. The technology compresses capital requirements for mid-scale entrants while eroding the scale advantages of legacy sequential stretching halls.
EU REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation of slip and antiblock additives in films bound for European consumer goods markets. ECHA substance evaluation has flagged several amide-based processing aids for additional toxicological review. Converters serving dual China-EU supply chains are accelerating migration to bio-based lubricant systems to preempt regulatory divergence.
Direct converter-brand relationships are displacing traditional distributor channels for specification-grade BOPA volumes. Large protein processors in China's coastal provinces now contract directly with Xiamen and Shandong film producers for customized oxygen transmission rates and seal-initiation temperatures. This channel compression concentrates pricing leverage with volume buyers while squeezing regional distributor margins across East Asian markets.
Biaxially Oriented Polyamide (BOPA) Films Market Segmentation
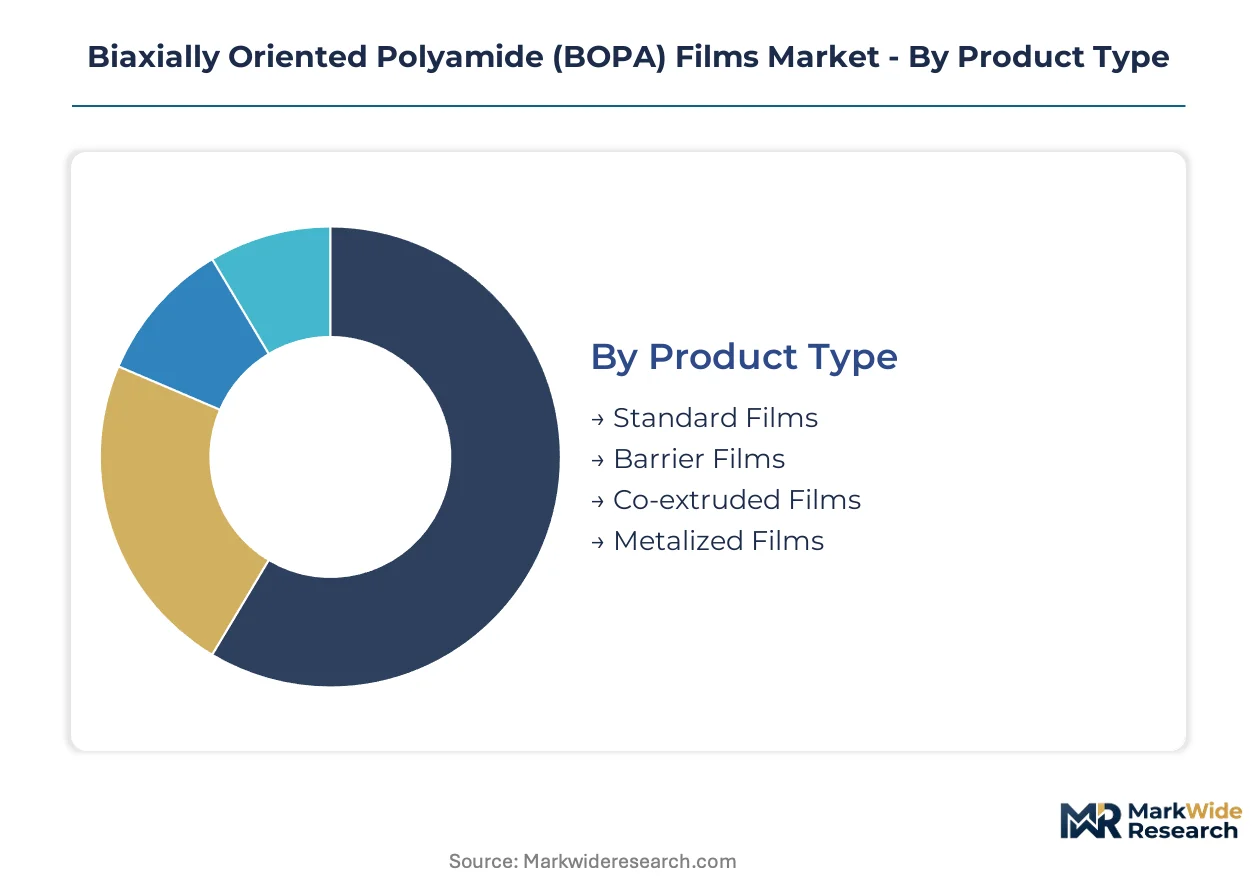
BOPA film specifications diverge sharply across downstream channels, with medical and food-grade volumes flowing through validated converter networks while industrial grades move via distributor channels. Thickness tolerances and barrier certifications determine which segments command direct procurement relationships versus spot-market transactions.
Product Type:
Channel configuration varies by technical complexity, with co-extruded and barrier grades commanding direct converter-brand contracts while standard films flow through regional distributors.
- Co-extruded Films:Multi-layer structures combine polyamide with tie layers and sealant substrates in a single extrusion pass, eliminating separate adhesive lamination steps. Protein processors in China's coastal provinces specify these for oxygen transmission rates below 50 cm³/m²/day, locking in direct supply agreements with integrated stretch-line operators.
- Barrier Films:Metallized or oxide-coated variants deliver moisture and gas barrier performance for extended shelf-life applications. Dairy supply chains in Japan and South Korea absorb expanded capacity as METI guidelines tighten packaging material efficiency benchmarks.
- Standard Films:Unmodified biaxially oriented polyamide serves general-purpose flexible packaging with 51-100µm gauge ranges.
- Metalized Films:Vacuum-deposited aluminum layers enhance barrier properties for snack and confectionery segments.
By volume, standard films lead. By growth pace, co-extruded variants are expanding most quickly.
Application:
End-use concentration shapes margin structures, with medical and food packaging commanding certification premiums while industrial applications compete on unit economics.
- Food Packaging:Oxygen barrier properties protect perishable proteins and dairy through cold-chain distribution. China's Yangtze River Delta converters serve both domestic brands and export-qualified output under GB 4806.7-2016 migration limits.
- Medical Packaging:Sterile barrier systems for pharmaceutical products demand validated 150µm+ structures with documented lot traceability. Japanese and South Korean healthcare supply chains specify these for terminally sterilized devices.
- Electronics:Anti-static and moisture-barrier formats protect sensitive components during assembly and shipment.
- Industrial Packaging:Heavy-duty formats with puncture resistance serve chemicals and agricultural inputs.
Food packaging dominates absolute volume. Medical packaging posts the steepest expansion trajectory as healthcare infrastructure modernizes across East Asia.
End User:
Customer scale determines procurement modality, with multinational food and pharmaceutical groups centralizing specifications while automotive and consumer goods buyers fragment across regional converters.
- Food Industry:Processed meat and cheese processors specify multi-layer structures to reduce spoilage losses in extended distribution networks.
- Pharmaceutical Industry:Sterile packaging requirements in Japan and South Korea drive demand for validated barrier films with extractables testing documentation.
- Automotive:Chemical-resistant formats protect components during just-in-time assembly logistics.
- Consumer Goods:Personal care and household products utilize printed BOPA for shelf differentiation.
The food industry absorbs the largest share by tonnage. Pharmaceutical demand is climbing fastest as regulatory traceability requirements intensify.
Thickness:
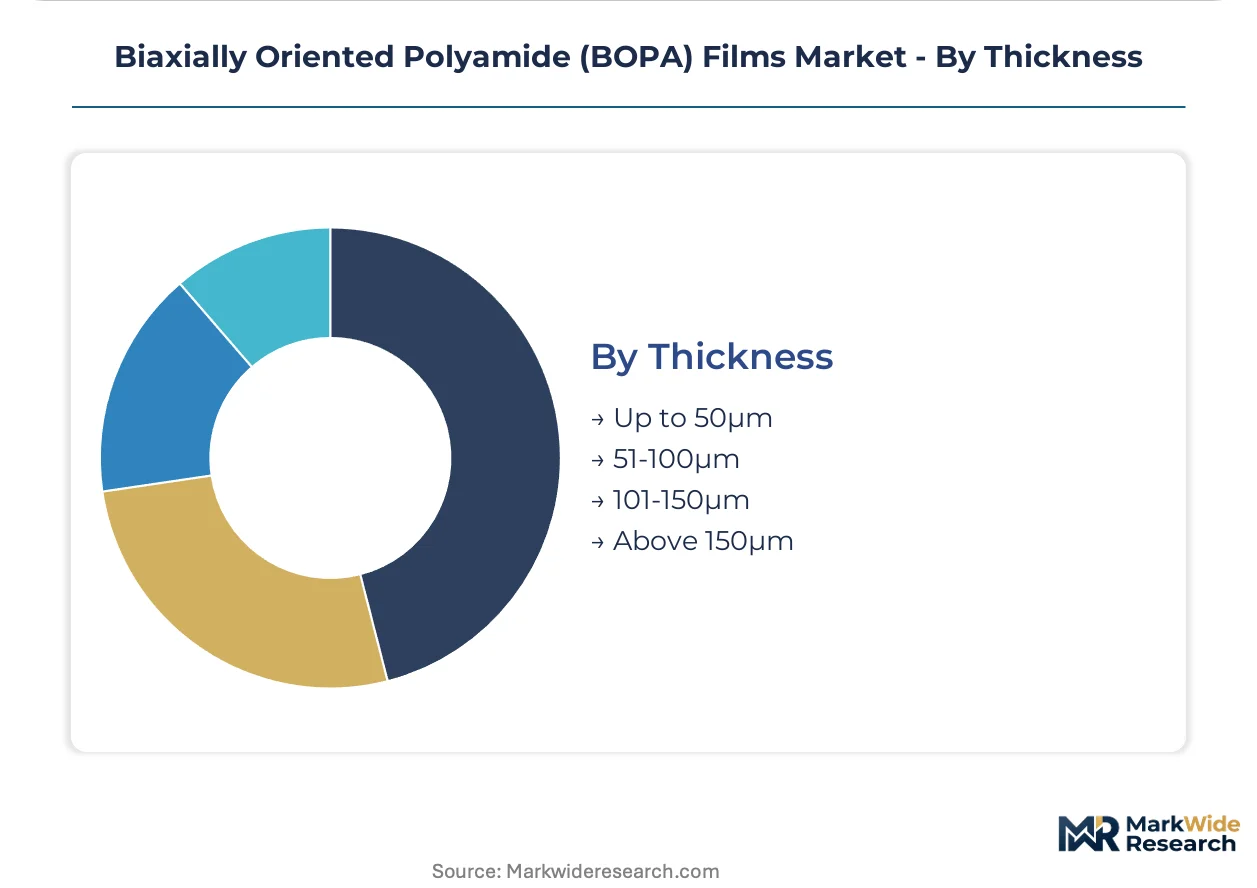
Gauge selection correlates with barrier performance requirements and equipment compatibility across converter installed bases.
- 51-100µm:Standard packaging grades balance barrier performance with downstream converting efficiency. High-speed form-fill-seal lines in China's packaging clusters run these gauges for frozen food and processed meat applications.
- Above 150µm:Heavy-duty industrial and medical-grade structures deliver puncture resistance and seal integrity under stress. Japanese pharmaceutical contract manufacturers specify these for terminally sterilized device packaging.
- Up to 50µm:Ultra-thin formats serve lightweight flexible packaging with reduced material intensity.
- 101-150µm:Mid-range gauges bridge standard and heavy-duty applications.
The 51-100µm band leads by volume. Above-150µm grades are gaining share fastest as medical and industrial specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GB standards enforced by China's SAMR anchor regulatory gravity for BOPA film compliance across Asian supply chains, with migration testing for amide oligomers setting baseline specifications for export-qualified output. Japanese METI energy-efficiency guidelines and EU REACH substance restrictions create multi-jurisdictional certification demands for integrated film producers.
China
Protein processors and dairy distributors in coastal provinces specify multi-layer BOPA structures for 12-month shelf-life targets. SAMR enforces GB 4806.7-2016 migration limits that mandate oligomer-controlled resin grades. The Yangtze River Delta packaging cluster hosts integrated stretching lines serving both domestic brands and European export channels.
Japan
Pharmaceutical contract manufacturers demand validated 150µm+ sterile barrier films with documented lot traceability for terminally sterilized devices. METI promotes resource-efficient packaging under its circular economy roadmap. Kansai-based converters absorb expanded metallized film capacity as healthcare infrastructure modernizes.
Germany
Snack and confectionery processors specify oxide-coated barrier films for premium shelf-life applications. ECHA substance evaluation under REACH Annex XVII flags amide-based processing aids for toxicological review. Industrial packaging converters in North Rhine-Westphalia pilot bio-based lubricant systems to preempt regulatory divergence.
United States
Frozen food distributors and processed meat processors specify puncture-resistant formats for cold-chain distribution networks. FDA food-contact substance notifications govern amide oligomer thresholds in flexible packaging. Midwestern converting clusters in Illinois and Ohio integrate high-speed form-fill-seal lines for 51-100µm standard grades.
India
FSSAI packaging modernization drives demand for oxygen-barrier substrates in Maharashtra and Gujarat processed food sectors. Central food safety mandates align with 12-month shelf-life specifications for regional brand launches. Western India converting hubs expand corona-treated surface capacity for digital printing compatibility.
Biaxially Oriented Polyamide (BOPA) Films Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the BOPA film market, with captive resin synthesis and co-extrusion expertise defining competitive boundaries. Three archetypes dominate: integrated petrochemical-to-film operators controlling upstream nylon-6 supply, specialized barrier film engineers with medical-grade validation capabilities, and regional scale players leveraging logistics control over dense packaging clusters. Capacity expansion and direct converter-brand contracting represent the dominant competitive moves, displacing traditional distributor channels for specification-grade volumes.
Among Japanese integrated producers, Toray Industries and Kuraray Company exemplify the upstream-captive archetype, with resin synthesis capabilities securing feedstock continuity against caprolactam volatility. Xiamen Changsu Industrial Corporation Limited occupies a position within the China-centric scale tier, anchoring supply relationships across the Yangtze River Delta packaging cluster through integrated stretching line operations.
| Leading Market Players |
|---|
| Toyobo |
| Yuncheng Plastic Industry |
| AdvanSix |
| Toray Industries |
| Kuraray Company |
| Mitsubishi Chemical Corporation |
| Xiamen Changsu Industrial Corporation Limited |
| Mondi plc |
| Unitika Ltd. |
| Others |
Supply Flow & Price Mechanics
Metallized PET films displacing BOPA in cost-sensitive snack packaging are compressing regional price premiums while simultaneously shifting converter procurement geography toward integrated Chinese producers with captive nylon-6 supply.
Pricing Analysis
Chinese Yangtze River Delta producers quote standard-grade BOPA at 15-20% discounts to Japanese integrated manufacturers, compressing margin structures across Asia-Pacific. Three-tier pricing structure across medical-grade, food-grade, and industrial-grade certifications separates validated pharmaceutical volumes from commodity flexible packaging. Pricing pressure stems from caprolactam feedstock volatility and PET substitution in barrier applications. Regional brand processors in Southeast Asia exhibit highest price sensitivity, while Japanese pharmaceutical contract manufacturers absorb premiums for lot-traceable sterile barrier films.
Supply Chain Analysis
Container availability constraints on Shanghai-Rotterdam and Shanghai-Los Angeles trade lanes are extending lead times for European and North American converters sourcing specification-grade volumes. Supply concentrates in China, Japan, and South Korea, with the Yangtze River Delta hosting over half of Asian stretching capacity. The value chain draws from benzene derivatives, caprolactam monomer, and specialized co-extrusion equipment. Single-point disruption exposure from Yangtze River Delta concentration represents the dominant structural risk. Distribution runs through direct converter-brand contracts for medical and food-grade volumes, with regional distributors handling industrial-grade spot transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against metallized PET and oxide-coated barrier films capturing cost-sensitive flexible packaging segments.
For Market Incumbents: Shield specification-grade positioning by deepening captive resin synthesis capabilities and securing dual GB-REACH certification ahead of regulatory divergence. Accelerate co-extrusion line investment in China's coastal provinces to capture direct contracting relationships with protein processors. PET substitution pressure and caprolactam volatility are the priority threats to neutralize. For New Entrants and Emerging Players: Differentiate on medical-grade validation capabilities and digital printing surface treatment for short-run flexible packaging. Target India's Maharashtra and Gujarat processed food sectors where FSSAI modernization creates oxygen-barrier substrate demand without entrenched incumbent relationships. Pursue corona-treated BOPA supply agreements with regional brand launchers seeking plateless printing economics. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated petrochemical-to-film operators with captive nylon-6 supply and established converter-brand direct relationships. Long-term viability over a 5-10 year window rests on regulatory compliance infrastructure and medical-grade validation capabilities rather than commodity scale. Watch for GB standard amendments and EU REACH substance list expansions as inflection indicators requiring portfolio recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Toray Industries and Kuraray secure feedstock continuity against benzene derivative volatility. |
| Co-extrusion Line Expansion | Xiamen Changsu eliminates adhesive lamination steps, cutting unit costs for Yangtze River Delta converters. |
| Dual Certification Investment | Simultaneous GB 4806.7-2016 and EU REACH compliance extends product qualification cycles but locks in export access. |
| Medical-grade Validation Buildout | Japanese pharmaceutical contract manufacturers demand 150µm+ structures with documented lot traceability. |
| Digital Printing Surface Treatment | Corona-treated BOPA enables short-run regional brand launches without plate costs in India's western hubs. |
Methodological Framework
Cross-validation between converter procurement data and resin producer output statistics anchors the qualitative findings in this BOPA film analysis. Primary interviews with film extrusion plant managers, downstream food packaging procurement leads, pharmaceutical contract manufacturing quality directors, and medical device sterile barrier engineers combined with secondary validation from customs trade data, SAMR GB standard filings, METI circular economy roadmaps, and SEC 10-K disclosures from listed petrochemical producers. Bottom-up capacity utilization modeling and top-down end-use demand estimation triangulate volume outputs.
Sensitivity analysis across caprolactam price scenarios, PET substitution elasticity, and regulatory compliance timeline variations stress-tests projection robustness. Segmentation modeling spans product architecture, application channel, end-user industry, thickness grade, and regional production hub. CAGRs derive from fitted growth curves calibrated to historical capacity expansion patterns and announced stretching line investments. Forecast inputs include protein processor shelf-life specifications, pharmaceutical validation requirements, and FSSAI packaging modernization timelines.
Decision-makers should treat outputs as directional under assumptions of sustained GB standard enforcement and stable benzene derivative feedstock availability; material deviation would warrant model refresh. Recalibration cycles align with shifts in SAMR regulatory amendments, ECHA substance evaluations, and announced co-extrusion capacity additions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Global BOPP Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Brazil Plastic Packaging Films Market
Poly film
MDO-PE Films Market
Poly film
Colombia Plastic Packaging Films Market
Poly film
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Cleanroom Film and Bags Market
Poly film
Polyimide Films and Tapes Market
Poly film
Waste Wrap Film Market
Poly film
PVC Cling Film Market
Poly film
Poly Coated Kraft Paper Market
Poly film
Printed Plastic Films Market
Poly film
Twist Wrap Film Market
Poly film
Cellulose Film Packaging Market
Poly film
Polyolefin Films Market