
 PVC Cling Film Market | 2026-2036
PVC Cling Film Market Size, Share, and Industry Trends Forecast 2026-2036
PVC Cling Film Market Intelligence
Procurement power within the PVC cling film market is consolidating among large-scale supermarket chains and multinational food processors, creating demand for consistent, high-volume supply. Amcor plc leverages its extensive global manufacturing footprint to serve these major accounts with standardized product lines. Other key suppliers like Berry Global Inc. and Mondi Group compete by offering broad portfolios that include specialized stretch films and films with recycled content.
PVC cling film is a thin polyvinyl chloride sheet, produced via cast or blown extrusion and formulated with plasticizers for enhanced flexibility. Its primary purpose is to create a tight, transparent seal over food, leveraging high cling properties and controlled gas permeability to preserve freshness. Food packaging applications represent the largest segment, with plain film dominating volume over printed film. Distribution runs through a mix of channels, where supermarkets and wholesale represent the highest volume pathway to market.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern food-contact grade film composition. These standards, along with chemical regulations like REACH in Europe, impose strict limits on plasticizer migration, particularly for phthalates. This compliance pressure is forcing investment in R&D for safer alternatives. Strategic decision-making now centers on balancing material performance with evolving global safety mandates and consumer sentiment.
Market Dynamics
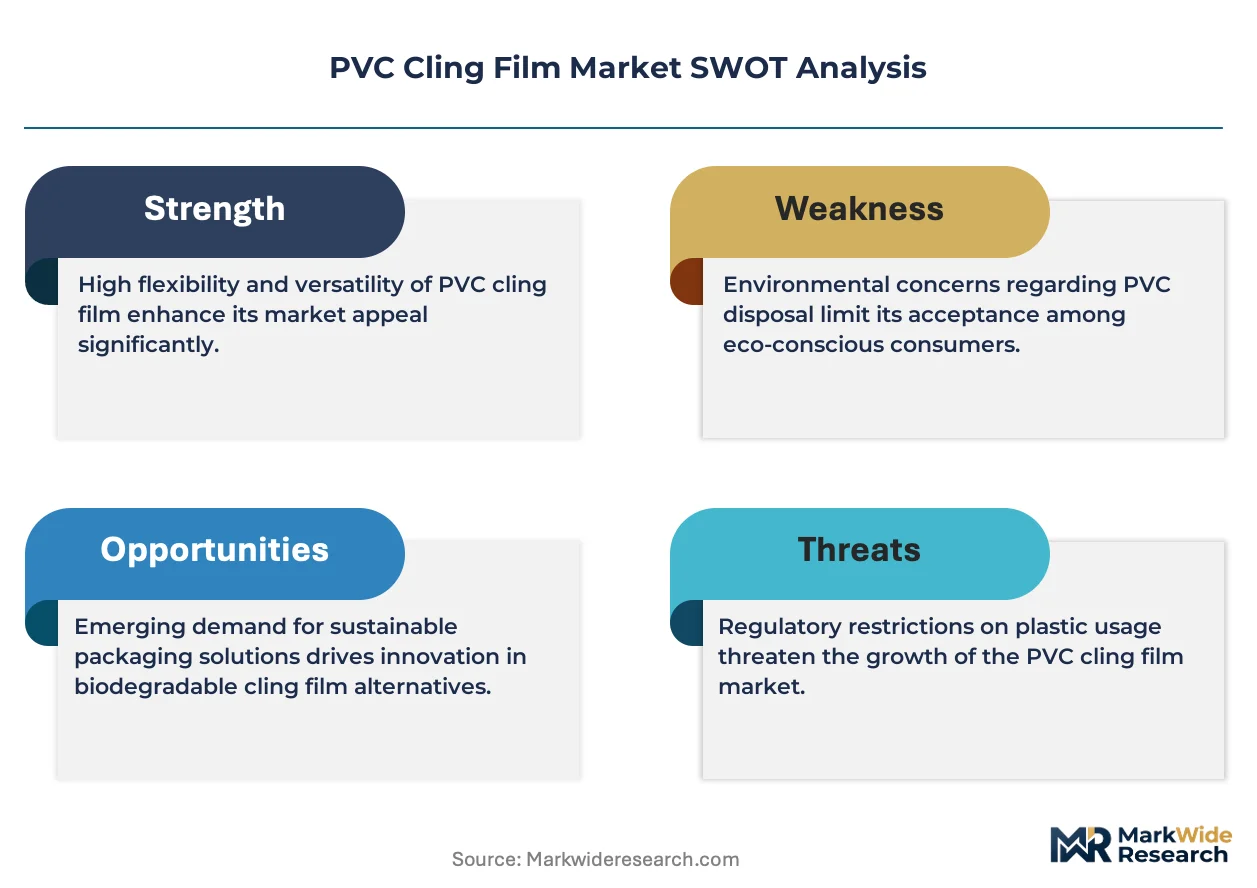
The central structural force shaping the PVC cling film market is the regulatory pressure on plasticizer composition. Mandates from bodies like the US FDA and Europe's EFSA are compelling a fundamental shift in material science, prioritizing food safety over incremental performance gains.
Growth Catalysts
- Retail Expansion in Asia:The rapid growth of hypermarkets and organized food retail in countries like China and India creates sustained, high-volume demand for food packaging films to preserve fresh produce, meat, and prepared foods.
- Superior Material Properties:PVC's inherent high cling, elasticity, and controlled oxygen permeability provide an optimal solution for securing and preserving food items, a functional advantage that sustains its use in demanding food service and retail environments.
- Innovation in Formulations:Investment in developing safer, non-phthalate plasticizers is creating new product categories that meet stringent food-contact standards, unlocking access to health-conscious consumer segments and premium retail channels.
Market Restraints
- Substitution from Alternative Polymers:Competition from polyethylene (PE) and other polyolefin-based films, which are often marketed as more environmentally friendly alternatives, presents a significant substitution threat, particularly in regions with strong anti-PVC sentiment.
- Regulatory Compliance Costs:Adherence to stringent chemical safety regulations, such as REACH in Europe, imposes significant costs related to testing, certification, and reformulation to limit the migration of substances like phthalates.
- Raw Material Price Volatility:The market is exposed to price fluctuations in key feedstocks, including PVC resin and plasticizers, which can compress manufacturer margins and create pricing instability for end-users.
Strategic Opportunities
- Bio-Based Plasticizers:Developing and commercializing PVC films formulated with bio-based plasticizers offers a path to differentiate products on sustainability and safety, appealing to environmentally conscious brands and consumers.
- Expansion into Non-Food Applications:Opportunities exist in industrial and consumer goods sectors for wrapping and bundling applications where PVC's high cling and clarity are advantageous but food-contact compliance is not a factor.
- Growth in Emerging Retail Markets:Targeting the expanding modern grocery sectors in Latin America and Southeast Asia provides an avenue for growth as these regions adopt packaging standards common in developed markets.
Industry Challenges
- Navigating Complex Food-Contact Laws:Manufacturers face the operational challenge of managing disparate and evolving food-contact regulations across geographies, requiring dedicated compliance teams to ensure market access in North America, Europe, and Asia.
- Negative Consumer Perception:Overcoming public concerns regarding the environmental and health impacts of PVC requires significant investment in consumer education and transparent communication about the safety and benefits of modern, compliant film formulations.
- Capital-Intensive Production:The high cost of cast and blown film extrusion lines creates a significant barrier to entry and makes it difficult for producers to quickly adapt manufacturing capabilities to new material formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC Cling Film Market |
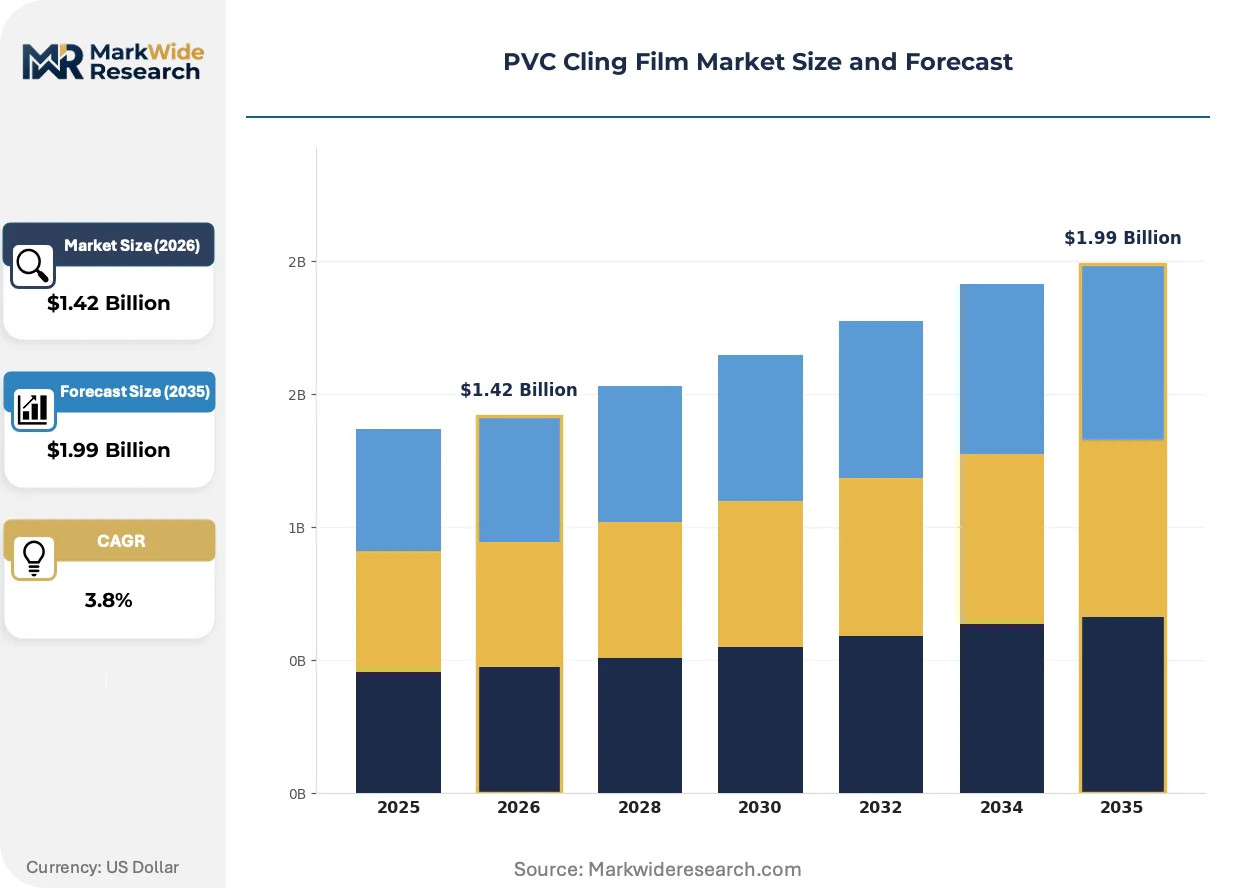
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $1.99 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain Film, Printed Film, Barriers Film, Stretch Film Application: Food Packaging, Medical Applications, Industrial Use, Household Use Thickness: Thin, Medium, Thick, Extra Thick Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Amcor plc, Mondi Group, Berry Global Inc., Klockner Pentaplast, Mitsubishi Plastics Inc., Sealed Air Corporation, AEP Industries Inc., Nan Ya Plastics, Intertape Polymer Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC Cling Film Market Strategic Shifts & Innovations
Material science is balancing the functional requirements of food preservation with heightened regulatory and consumer demands for safer packaging. This dynamic is driving innovation away from pure performance enhancement and toward compliance-focused reformulation and sustainable material development.
Development of non-phthalate plasticizers, such as dioctyl terephthalate (DOTP), is a primary focus. Food processors and premium retailers are leading adoption, driven by a need to meet stringent food-contact standards and enhance brand safety credentials. This shift toward safer chemistry is absorbing R&D investment, re-centering the industry's innovation agenda on material compliance and human health impact.
Europe's REACH regulation directly influences PVC film composition by controlling chemical substances. The framework mandates rigorous evaluation for substances of very high concern, including certain phthalates, restricting their use in consumer and food-contact applications. This affects all manufacturers supplying the EU market, forcing reformulation with approved plasticizers to maintain legal access and avoid significant penalties.
Large supermarket chains are implementing procurement policies based on corporate sustainability mandates. This change is disrupting traditional cost-based purchasing, favoring suppliers who can provide films with certified recycled content or formulations free of specific chemicals of concern. This trend is most pronounced in North America and Western Europe, where retailer brand reputation is closely tied to environmental and health-conscious product assortments.
PVC Cling Film Market Segmentation
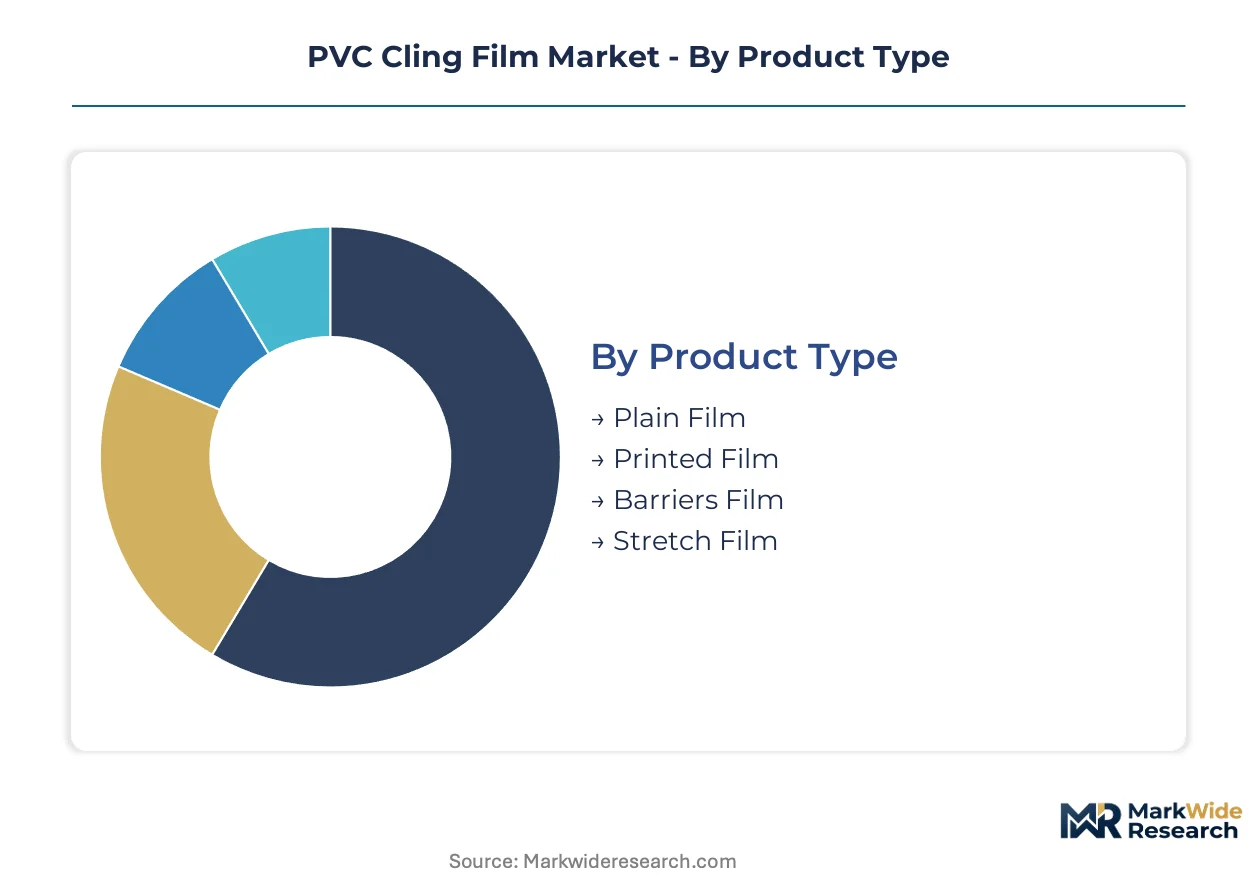
The PVC cling film market's segmentation reveals the diverse applications and product specifications that meet varying end-user requirements. Understanding these distinct segments is crucial for manufacturers to align production capabilities with specific demand patterns and for suppliers to optimize their distribution strategies. Each segment reflects unique material science demands or logistical considerations.
Product Type:
The concentration of PVC film manufacturing capacity heavily favors high-volume, standardized product types, reflecting the industrial scale required for efficient production.
- Plain Film:This unmodified PVC film, produced via cast or blown extrusion, relies on inherent cling properties for effective sealing. Demand concentrates in food packaging for fresh produce, driven by cost-effectiveness and high volume retail requirements in markets like China.
- Stretch Film:Engineered for superior elongation and recovery, this film often features enhanced puncture resistance for demanding applications. Industrial pallet wrapping and specialized bundling applications in North America utilize this film for secure transportation and load stability.
- Printed Film:Features branding, product information, or decorative elements, primarily used for consumer-facing packaged goods where visual appeal is important.
- Barriers Film:Incorporates additional layers or specialized formulations to improve gas and moisture barrier properties, extending shelf life for oxygen-sensitive foods.
Plain Film absorbs the bulk of installed capacity; Stretch Film is expanding most quickly.
Application:
Volume-driven applications dictate the scale of production and material specifications across the PVC cling film market.
- Food Packaging:Utilizes PVC film's high cling and controlled permeability for preserving the freshness of perishable items like meats, cheeses, and vegetables. Supermarket chains and food processors in India drive significant demand for these films to meet consumer expectations for fresh produce.
- Industrial Use:Encompasses various non-food applications such as bundling, protective wrapping, and pallet stabilization for manufactured goods. Manufacturing and logistics sectors in Europe increasingly adopt PVC films for their durability and secure load containment.
- Medical Applications:Employed for sterile packaging of medical devices and pharmaceutical products, requiring strict regulatory compliance and material purity.
- Household Use:Refers to consumer-level cling wrap sold for food storage and general kitchen utility, distributed through retail channels globally.
Food Packaging applications generate the highest volume demand, while Medical Applications command premium pricing due to stringent requirements.
Thickness:
The choice of film thickness is primarily driven by the specific application requirements for protection, durability, and cost-efficiency.
- Thin:Characterized by minimal gauge, optimized for cost-efficiency and light-duty wrapping where high cling is paramount. Retail fresh produce sections in Brazil frequently employ thin films for economic and efficient packaging of fruits and vegetables.
- Thick:Designed for enhanced durability and puncture resistance, suitable for heavy-duty protection and extended preservation. Industrial packaging of sharp-edged products and long-term storage in warehouses in the US benefit from thick film properties.
- Medium:Offers a balanced combination of strength, flexibility, and cost, making it suitable for general-purpose food and non-food wrapping applications.
- Extra Thick:Provides maximum protection against abrasion and impact, primarily used in highly demanding industrial applications for heavy or irregularly shaped items.
The selection of film thickness directly correlates with the required mechanical strength and barrier performance for specific end-uses.
Distribution Channel:
Customer type significantly influences the preferred distribution channel, with large commercial buyers favoring direct or wholesale procurement.
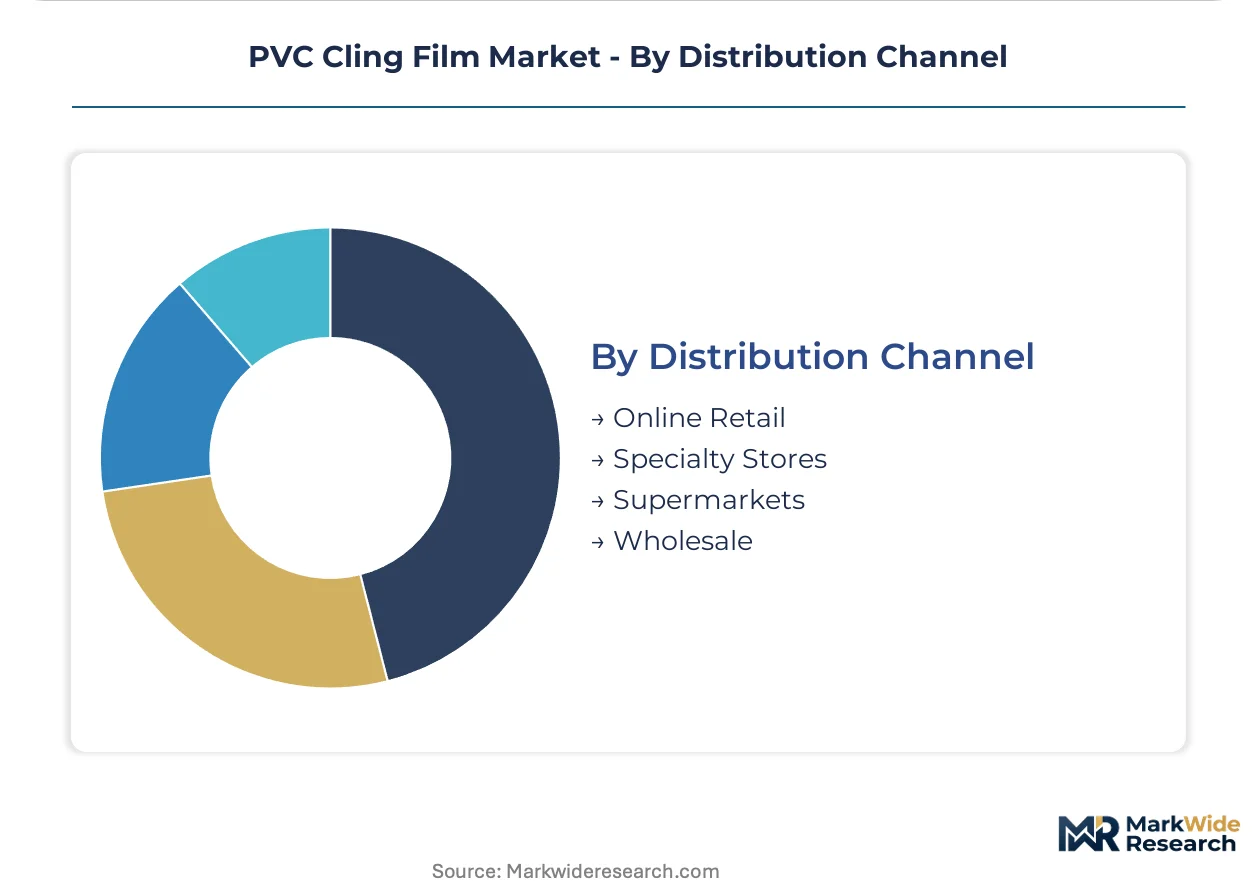
- Supermarkets:Represents direct supply to large grocery chains for in-store packaging of fresh produce, meats, and deli items. Major European supermarket groups drive substantial volumes, demanding consistent quality and competitive pricing from their suppliers.
- Wholesale:Involves bulk distribution to food service providers, smaller independent retailers, and industrial users through large-scale distributors. Food processing plants and restaurant supply companies in China rely on wholesale channels for their high-volume film procurement.
- Online Retail:Facilitates direct-to-consumer sales of household-sized cling film, often emphasizing convenience, brand variety, and home delivery services.
- Specialty Stores:Cater to niche markets like gourmet food shops or craft suppliers, offering specific film types or smaller quantities with specialized customer service.
Supermarkets and Wholesale channels account for the vast majority of PVC cling film volume, reflecting established procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for PVC cling film concentrates in regions with extensive food processing and retail infrastructure. China's expansive food processing and hypermarket sectors drive significant volume requirements for packaging. This global demand pattern shapes supply chain dynamics and regional investment priorities.
China
China's vast food processing industry and rapidly expanding hypermarket networks sustain high-volume demand for PVC cling film for fresh produce. The country's GB standards rigorously govern food-contact materials, influencing local formulations. Manufacturing hubs in the Yangtze River Delta actively innovate to meet these stringent domestic requirements.
United States
American supermarket chains and the extensive food service sector require consistent, high-volume PVC film for fresh food preservation. The US FDA mandates strict compliance for all food-contact grade films, driving material safety. Major food processing centers in the Midwest integrate these films extensively for packaging and distribution.
Germany
Germany's sophisticated food retail sector and robust industrial base create steady demand for PVC cling film, especially for secure load containment. Europe's EFSA and REACH regulations strictly limit plasticizer migration, compelling reformulation efforts. Manufacturers in North Rhine-Westphalia focus on producing compliant films for both domestic and export markets.
India
India's fast-growing organized food retail and hypermarket expansion drives significant demand for PVC cling film for fresh produce and meat. The FSSAI sets food safety standards that influence packaging material composition and usage. Major distribution hubs like Mumbai and Delhi-NCR see high consumption of these films across their supply chains.
Brazil
Brazilian retail fresh produce sections frequently employ thin PVC films, prioritizing cost-efficiency and effective sealing for fruits and vegetables. ANVISA dictates specific requirements for food packaging materials to ensure consumer safety. Food distribution networks in São Paulo and Minas Gerais depend on these films for their daily operations.
PVC Cling Film Market Key Industry Players
Established producers occupy the standard tier, focusing on high-volume plain film, while specialized entrants pursue niche applications like barrier films or sustainable formulations. The market structure exhibits consolidation among major global players serving large supermarket chains and multinational food processors. Key strategic archetypes include diversified packaging conglomerates and specialized film manufacturers. Companies frequently engage in capacity expansion and portfolio diversification to maintain market share.
At the scale-driven end, Amcor plc exemplifies a global manufacturing footprint, serving major accounts with standardized product lines across diverse geographies. Berry Global Inc. represents a diversified packaging specialist, offering broad portfolios that include specialized stretch films and films with recycled content. Mondi Group further anchors this segment, providing comprehensive packaging solutions that meet evolving sustainability and safety mandates. These companies occupy a strong position by leveraging extensive distribution networks and catering to high-volume procurement needs. Their offerings often include advanced formulations for specific food contact compliance, addressing regulatory shifts effectively.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| Berry Global Inc. |
| Klockner Pentaplast |
| Mitsubishi Plastics Inc. |
| Sealed Air Corporation |
| AEP Industries Inc. |
| Nan Ya Plastics |
| Intertape Polymer Group Inc. |
Cost & Logistics Intelligence
The certification-driven divergence between medical-grade PVC film and commodity plain film significantly impacts pricing and supply chain configurations. Premium segments command higher prices due to stringent regulatory compliance and specialized manufacturing, while high-volume plain film operates on tighter margins and spot market dynamics.
Pricing Analysis
Volume-driven plain film typically operates on contract-based long-term offtake agreements for large buyers, while specialized films utilize tiered premium pricing. Price differentiation stems from FDA/EFSA certification levels, the volume scale of procurement, and the inclusion of advanced non-phthalate plasticizer formulations. Cost compression in the plain film segment is intensifying due to volatility in PVC resin and plasticizer raw material prices. Retail fresh produce sections in Brazil and China exhibit high price sensitivity, whereas medical applications and premium food retailers prioritize compliance over cost.
Supply Chain Analysis
Dual-sourcing requirements are becoming standard practice for major food processors and supermarket chains to mitigate supply risks and ensure regulatory compliance. Geographic supply concentration is notable in China, the United States, and Germany, which serve both domestic and export markets. The supply chain draws heavily from key raw materials like PVC resin and various plasticizers. Regulatory restriction on specific plasticizers, such as those under Europe's REACH, presents a structural risk, necessitating costly reformulation efforts. Distribution runs through direct supply channels to large supermarkets and wholesale networks for industrial and food service users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PVC cling film market functions as a supply-constrained story in its specialized segments, where the high capital investment for advanced extrusion lines and R&D for compliant formulations props pricing.
For Market Incumbents: Cement market leadership by investing heavily in advanced non-phthalate plasticizer R&D to meet evolving FDA and EFSA standards, mitigating substitution threats from alternative films. Expand manufacturing capacity strategically in emerging retail markets like Southeast Asia and Latin America to secure long-term supply contracts with regional hypermarket chains. Deepen vertical integration into plasticizer production to control input costs and ensure a consistent supply of compliant materials.
For New Entrants and Emerging Players: Enter via niche applications requiring specialized barrier properties or bio-based plasticizer formulations, targeting health-conscious consumer segments and premium retailers. Focus on regions with less established modern retail infrastructure but growing organized food sectors, such as parts of Africa. Leverage agile production methods for smaller, customized batches, offering a go-to-market angle of rapid innovation and specialized compliance solutions for specific food categories.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized film manufacturers given their expertise in compliant formulations and access to premium segments driven by food safety mandates. Long-term viability rests on companies demonstrating clear pathways to sustainable material science and robust regulatory adherence over the next decade. Target acquisition profiles include mid-sized firms with proprietary non-phthalate plasticizer technologies or strong regional distribution networks in Asia. Watch for significant market share shifts in the medical packaging segment as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Bio-Based Plasticizers | Differentiates products on sustainability, appealing to environmentally conscious brands and consumers. |
| Capacity Expansion in Asia | Secures high-volume supply for rapidly growing hypermarket and food processing sectors. |
| Certification for Medical Applications | Unlocks access to premium, high-margin segments with stringent regulatory requirements. |
| Diversification into Non-Food Applications | Reduces reliance on food packaging, leveraging PVC's cling properties in industrial sectors. |
| Long-Term Supply Contracts | Stabilizes revenue streams and secures consistent demand from large supermarket chains. |
Research Approach
Document review covered regulatory filings (US FDA, Europe EFSA, REACH), industry association reports (plastics, packaging), and corporate financial disclosures, complemented by interviews. Interviews included procurement managers at large supermarket chains, R&D directors at film manufacturers, and supply chain leads at food processors. This approach combined primary insights with secondary validation for a comprehensive market understanding. Bottom-up and top-down triangulation ensured data accuracy.
Historical data was cross-referenced against expert panel input to project market trajectories across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, thickness, and distribution channel, alongside regional regulatory compliance. Compound annual growth rates were derived from volume and value projections, incorporating PVC resin and plasticizer price trends.
Revisions become necessary when significant shifts in chemical regulations or major raw material supply disruptions materialize. Forecasts reflect assumptions regarding compliance costs and consumer sentiment. Deviation in regulatory enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polylaminate Capsules Market
Poly film
Canada Plastic Packaging Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
Surface Printed Film Market
Poly film
Embossed Film Market
Poly film
Multi-Layer Blown Films Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
Chocolate Wrapping Films Market
Poly film
Polypropylene Film Market
Poly film
Global Fluoropolymer Films Market
Poly film
Colombia Plastic Packaging Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Poly Coated Kraft Paper Market
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
Poland Plastic Packaging Films Market
Poly film
Japan Plastic Packaging Film Market