
 MDO-PE Films Market | 2026-2036
MDO-PE Films Market Size, Share, and Industry Trends Forecast 2026-2036
MDO-PE Films Market Foresight
Flexible packaging converter procurement is tilting toward suppliers with captive resin-to-film capabilities. Amcor leverages its integrated global manufacturing footprint to secure long-term supply agreements with multinational food brands. Berry Global anchors North American volume through specialized rollstock production for fresh produce applications. Taghleef Industries competes across Europe with differentiated opaque and coated film grades for premium shelf appeal.
Machine-direction oriented polyethylene films undergo controlled stretching to enhance tensile strength, optical clarity, and barrier performance while maintaining mono-material recyclability. The process typically achieves orientation ratios between 4:1 and 8:1, yielding films with superior puncture resistance for high-speed form-fill-seal operations. Rolls dominate volume throughput as the standard input for downstream converting equipment, while pouches capture expanding margin pools in ready-meal and pet food segments. The 20-40 micron thickness band leads overall consumption, though above-60 micron grades are gaining traction in agricultural mulch and industrial liner applications where mechanical durability outweighs unit economics.
The EU Green Deal and Packaging and Packaging Waste Regulation (PPWR) are mandating recyclability-by-design criteria that favor mono-PE structures over multi-material laminates. FDA food contact notifications and state-level extended producer responsibility laws in California and New York are similarly reshaping formulation and substrate selection in the Americas. Stakeholders must monitor evolving certification requirements for advanced recycling compatibility and calibrate capital allocation between mechanical recycling-compatible grades and emerging chemical recycling feedstock partnerships.
Market Dynamics
EU Green Deal mandates and the Packaging and Packaging Waste Regulation are redirecting converter capital toward mono-material PE structures, collapsing demand for multi-layer laminates that previously dominated flexible food packaging.
Growth Catalysts
- EU Green Deal recyclability mandates:The regulation's design-for-recycling criteria force brand owners to eliminate incompatible adhesive layers and metallized substrates from primary packaging.
- Fresh produce rollstock demand:Retail chains in Germany and France are specifying MDO-PE for breathable overwrap applications requiring optical clarity and puncture resistance.
- Orientation ratio advances:Process improvements achieving 8:1 stretch ratios deliver barrier performance comparable to oriented polypropylene while maintaining polyethylene recycling streams.
Market Restraints
- Ethylene feedstock volatility:Cracker margins in the US Gulf Coast and Northwest Europe swing with naphtha-to-ethane arbitrage, compressing film extruder margins during feedstock spikes.
- Specialized MDO line concentration:Equipment capable of 4-8 meter widths and precise temperature profiling concentrates among a limited installed base of European and North American converters.
- Mechanical recycling contamination limits:Current sorting infrastructure cannot reliably separate MDO-PE from biaxially oriented polypropylene in mixed flexible waste streams, limiting closed-loop claims.
Strategic Opportunities
- Agricultural mulch films:Above-60 micron grades with UV stabilization represent an underdeveloped outlet where mechanical durability commands premium pricing over standard geomembranes.
- Chemical recycling feedstock partnerships:Pyrolysis and hydrothermal processing developments in the Netherlands and Belgium create offtake pathways for films that fail mechanical recycling specifications.
- Ready-meal pouch conversion:Retortable mono-PE structures are displacing aluminum-containing laminates in single-serve applications where microwaveability and recyclability claims intersect.
Industry Challenges
- Orientation process control expertise:MDO line operation requires simultaneous mastery of temperature profiling, nip roll pressure calibration, and web tension management that exceeds conventional blown film skill sets.
- Extended producer responsibility compliance timelines:California's SB 54 and New York's packaging reduction laws impose reporting deadlines that outpace converter certification cycles for advanced recycling compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MDO-PE Films Market |
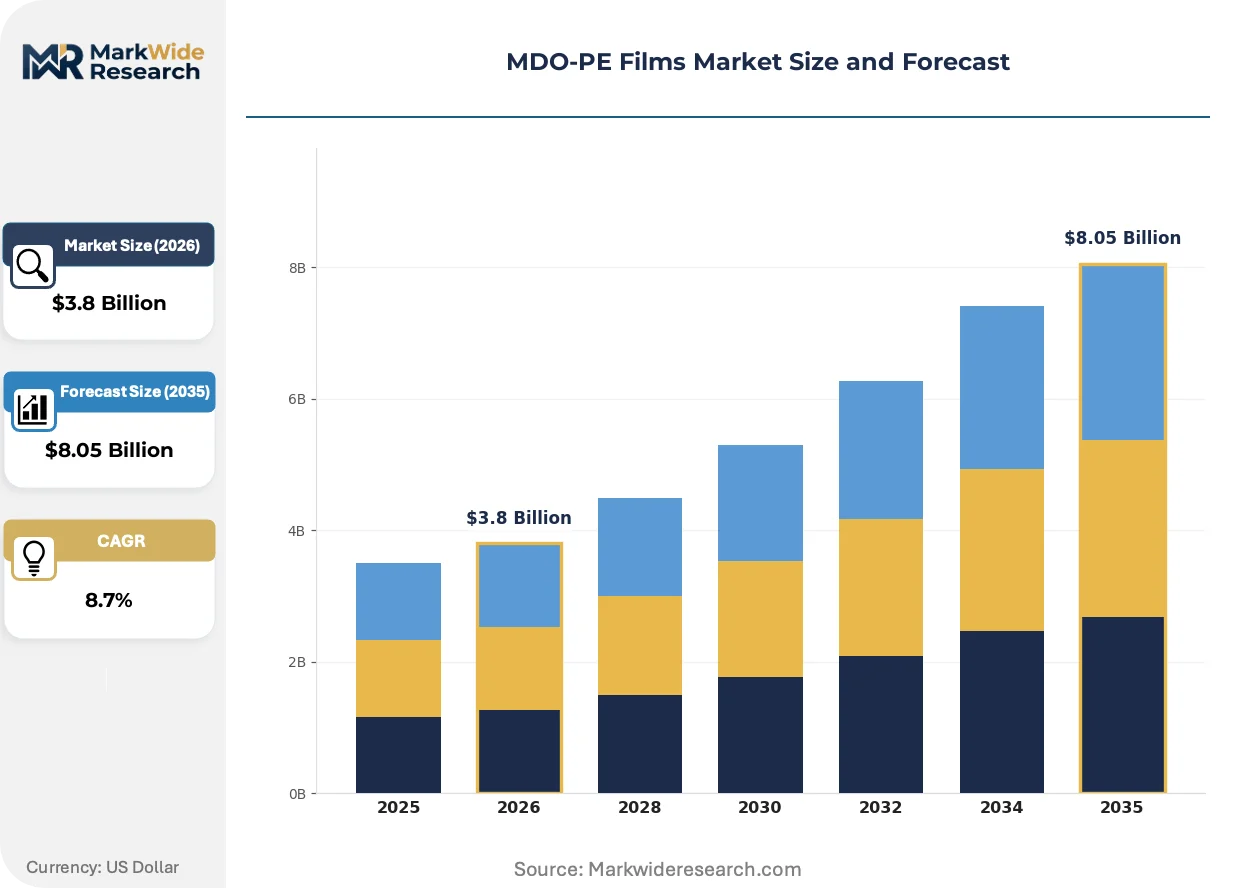
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rolls, Sheets, Bags, Pouches End Use Industry: Packaging, Agriculture, Automotive, Electronics Thickness: Below 20 Micron, 20-40 Micron, 40-60 Micron, Above 60 Micron Form: Transparent, Opaque, Colored, Coated |
| Companies Covered | Jindal Films, Coveris Holdings, Amcor, Innovia Films, Avery Dennison Corporation, ExxonMobil, Polibak, Taghleef Industries, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MDO-PE Films Market Shifts & Advancements
Digital process control systems and inline quality analytics are compressing development cycles for custom film grades while regulatory pressure accelerates substitution away from non-recyclable structures.
Inline thickness gauging combined with machine learning feedback loops is digitizing quality assurance on MDO lines. Major converters in Germany and Italy are retrofitting existing equipment with spectral sensors that adjust draw ratios in real time. This capability compresses qualification timelines for brand-owner specifications from months to weeks.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating traditional grease-resistant coatings from food-contact films. The European Chemicals Agency's 2023 PFAS restriction proposal forces reformulation toward silicone-based or bio-derived barrier treatments. Premium snack and confectionery segments in France and Benelux are first movers in validating replacement chemistries.
Direct converter-brand partnerships are displacing distributor-mediated procurement for volume food packaging. Retail chains in Germany now negotiate multi-year rollstock agreements specifying recycled content thresholds and carbon footprint certifications. This concentration of buying power compresses margins for mid-tier converters lacking scale or sustainability credentials.
MDO-PE Films Market Segmentation
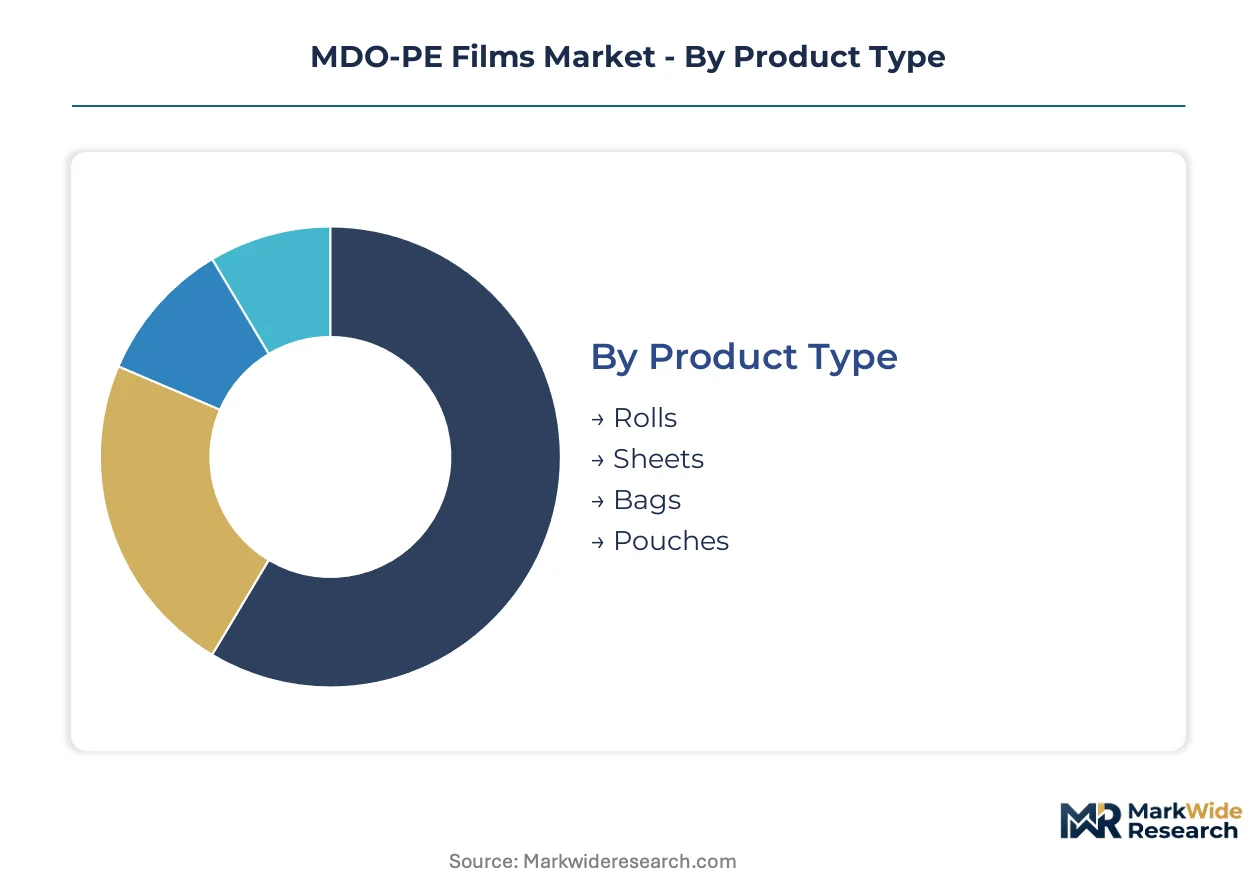
MDO-PE film specifications diverge sharply across converting equipment and end-use durability requirements. Converter procurement teams segment supply by form factor, mechanical properties, and optical characteristics to match downstream process constraints.
Product Type:
After-sales service intensity varies dramatically by product type, with rollstock converters demanding 24-hour technical support for web-break incidents while pouch suppliers prioritize formulation troubleshooting.
- Rolls:Standard mill rolls ranging from 500mm to 4-meter widths feed flexographic and rotogravure printing lines. German and Italian converters specify tight gauge tolerance bands for high-speed lamination. By volume, rolls lead. By growth pace, pouches are ahead.
- Pouches:Pre-formed stand-up and flat pouches capture premium margin pools in ready-meal and pet food segments where retail brands specify finished-goods delivery. French retail chains negotiate direct supply agreements bypassing traditional distributor networks.
- Sheets:Cut-to-size formats serve thermoforming operations for produce trays and industrial blisters. Sheet demand concentrates in Benelux converting clusters serving cross-border food packaging.
- Bags:Side-seal and bottom-gusseted configurations target bulk agricultural and chemical containment where puncture resistance outweighs optical clarity requirements.
Rollstock maintains throughput dominance while pouches reshape margin distribution toward finished-goods capabilities.
End Use Industry:
Application-driven cost tiers separate commodity packaging from engineered agricultural and automotive specifications where failure tolerance approaches zero.
- Packaging:Flexible food packaging absorbs the majority of MDO-PE volume, with breathable overwrap for fresh produce and retortable mono-PE structures displacing aluminum laminates in single-serve applications. EU Green Deal recyclability mandates accelerate converter qualification timelines.
- Agriculture:Above-60 micron grades with UV stabilization command premium pricing for mulch films and greenhouse covers where mechanical durability spans multiple growing seasons. Dutch agricultural cooperatives specify extended UV resistance certification.
- Automotive:Interior trim protection films and component dunnage utilize puncture-resistant grades for just-in-time parts logistics. German OEM supply chains specify ESD-dissipative formulations for electronics handling.
- Electronics:Cleanroom-compatible films protect displays and semiconductors during assembly and shipment. Swiss precision manufacturing clusters demand particulate contamination testing protocols.
Packaging generates the highest absolute volume. Agriculture demonstrates the steepest expansion trajectory as sustainability claims penetrate primary production.
Thickness:
Volume concentration sits in mid-range specifications while specialty grades above 60 microns unlock differentiated pricing power.
- 20-40 Micron:The workhorse band for form-fill-seal operations balances material efficiency against web-handling integrity. Major retail brands in Germany specify this range for primary food contact layers.
- Above 60 Micron:Heavy-duty grades target agricultural mulch, industrial liners, and construction membranes where mechanical durability outweighs unit economics. Belgian chemical recycling pilots process out-of-spec thick films into pyrolysis feedstock.
- Below 20 Micron:Ultra-thin specifications stretch orientation technology to limits for lightweight overwrap where barrier performance is secondary to material minimization.
- 40-60 Micron:Intermediate gauges serve secondary packaging and collation shrink applications requiring higher stiffness than standard food-contact grades.
The 20-40 micron band dominates current throughput. Above-60 micron grades are gaining share fastest as agricultural and industrial durability requirements intensify.
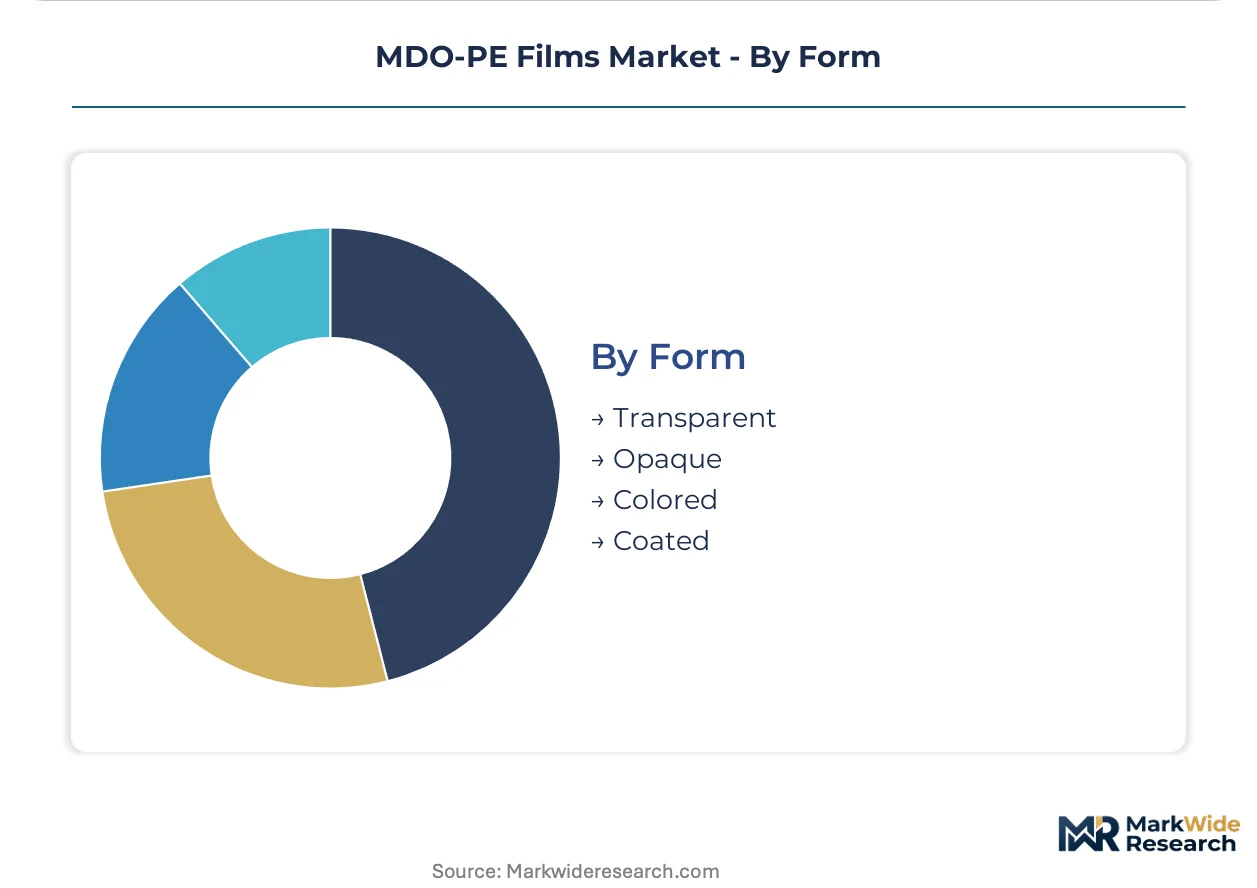
Form:
Customer type and shelf-appeal requirements drive form selection, with premium brands specifying differentiated optical properties.
- Transparent:Optical clarity grades enable product visibility for fresh produce and retail merchandise. French supermarket chains mandate haze specifications below 5% for premium overwrap applications.
- Opaque:Light-blocking formulations protect light-sensitive contents in dairy and pharmaceutical packaging. White-pigmented grades dominate Nordic dairy converter specifications.
- Coated:Functional surface treatments deliver grease resistance, oxygen barrier, or heat-seal enhancement. REACH PFAS restrictions force silicone-based coating validation across Benelux snack packaging.
- Colored:Brand-specific tints and security tints serve loyalty program packaging and anti-counterfeiting applications. Italian confectionery brands specify Pantone-matched custom runs.
Transparent films lead by volume. Coated grades are climbing the fastest as barrier functionality migrates into mono-material recyclable structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command 15-20% pricing premiums over Italian competitors due to integrated resin-to-film capabilities and direct brand partnerships. US Gulf Coast producers leverage ethane feedstock advantages but face margin compression from European sustainability compliance requirements.
Germany
Fresh produce retail chains and automotive component logistics drive MDO-PE specification intensity. The EU Green Deal's Packaging and Packaging Waste Regulation forces elimination of incompatible adhesive layers from primary packaging. The Düsseldorf-Cologne corridor hosts specialized converters supplying breathable overwrap to Rewe and Aldi Süd with 24-hour technical support contracts.
United States
Extended producer responsibility laws in California and New York reshape formulation selection for national food brands. FDA food contact notification requirements govern barrier coating approvals for retortable mono-PE structures. The US Gulf Coast ethane cracker corridor supplies resin to Berry Global's specialized rollstock operations for fresh produce applications.
France
Premium snack and confectionery segments validate silicone-based barrier treatments ahead of REACH PFAS restrictions. The European Chemicals Agency's 2023 restriction proposal eliminates traditional grease-resistant coatings. The Lyon-Grenoble cluster concentrates coated film production for dairy and pharmaceutical light-blocking applications.
Netherlands
Chemical recycling feedstock partnerships with pyrolysis developers create offtake pathways for out-of-specification films. Dutch agricultural cooperatives specify extended UV resistance certification for above-60 micron mulch grades. The Rotterdam-Antwerp port complex enables integrated resin import and film export logistics for Benelux converting clusters.
Italy
Digital process control retrofits with spectral sensors compress qualification timelines from months to weeks. REACH restrictions force reformulation of functional surface treatments across snack packaging segments. The Bologna-Modena converting belt specializes in Pantone-matched custom runs for confectionery brand owners.
MDO-PE Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin supply and coating formulation. The vendor base concentrates among European and North American converters with captive MDO line capabilities. Three archetypes dominate: integrated multinational packaging platforms, regional rollstock specialists, and resin-backed film producers. Capacity expansion and strategic partnerships represent the primary competitive moves, with chemical recycling feedstock agreements emerging as a differentiation vector.
Among integrated packaging platforms, Amcor and Berry Global exemplify scale-driven archetypes with global manufacturing footprints. Taghleef Industries occupies a position within the regional specialist tier, competing across Europe with differentiated film grades. These three entities represent distinct strategic postures: multinational direct brand partnerships, North American volume anchoring through specialized production, and European premium shelf-appeal positioning.
| Leading Market Players |
|---|
| Jindal Films |
| Coveris Holdings |
| Amcor |
| Innovia Films |
| Avery Dennison Corporation |
| ExxonMobil |
| Polibak |
| Taghleef Industries |
| Berry Global |
| Others |
Supply & Pricing Matrix
The Düsseldorf-Cologne corridor anchors European MDO-PE capacity, where integrated resin-to-film converters command 15-20% pricing premiums over Italian competitors through direct brand partnerships and 24-hour technical support contracts.
Pricing Analysis
Configured-to-order pricing for custom gauge tolerances and coating specifications carries 25-35% premiums over standard rollstock grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EU Green Deal recyclability compliance and carbon footprint thresholds commanding top-tier positioning. Cost compression in standard 20-40 micron bands is intensifying because German retail chains consolidate procurement through multi-year direct agreements. Commodity-oriented buyers in agricultural mulch applications exhibit highest price sensitivity, while premium snack and confectionery brands prioritize optical clarity and barrier performance over unit economics.
Supply Chain Analysis
Contract manufacturing concentrates among specialized MDO line operators in Germany, Italy, and the Netherlands with equipment capable of 4-8 meter widths and precise temperature profiling. Ethylene feedstock draws from US Gulf Coast ethane crackers and Northwest European naphtha-based production, with resin supply tethered to cracker margin volatility. Single-source vulnerability concentrates in specialized orientation line engineering and spectral sensor retrofit capabilities. Distribution runs through direct converter-brand partnerships displacing traditional distributor networks, particularly for French retail chains and Dutch agricultural cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through direct procurement consolidation, as German retail chains negotiate multi-year rollstock agreements that compress margins for mid-tier converters lacking scale or sustainability credentials.
For Market Incumbents: Insulate margin position through captive resin-to-film integration and chemical recycling feedstock partnerships with pyrolysis developers in the Netherlands and Belgium. Threat substitution from biaxially oriented polypropylene in mixed waste streams limits closed-loop claims, demanding mechanical recycling-compatible grade certification investment as the priority defensive lever. For New Entrants and Emerging Players: Establish a beachhead in above-60 micron agricultural mulch films where UV stabilization specifications and extended durability certification command premium pricing over standard geomembranes. The most penetrable white-space sits in Dutch agricultural cooperatives and Belgian chemical recycling pilots processing out-of-spec thick films, with go-to-market traction through direct grower-outreach bypassing traditional distribution. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with digital process control retrofits and inline quality analytics capabilities. Long-term viability across the analysis window hinges on backward integration into resin supply and coating formulation. Acquisition target archetype: regional European specialists with installed MDO line capacity and direct brand partnerships. The signal to watch is California SB 54 and New York packaging reduction law compliance timeline acceleration outpacing converter certification cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive ethylene sourcing from US Gulf Coast crackers insulates margin from naphtha-to-ethane arbitrage swings. |
| Chemical Recycling Feedstock Partnership | Pyrolysis offtake agreements with Dutch and Belgian processors create pathways for non-mechanically-recyclable films. |
| Digital Process Control Retrofit | Spectral sensor deployment compresses brand-owner qualification timelines from months to weeks. |
| Direct Brand Partnership Expansion | Multi-year rollstock agreements with German retail chains bypass distributor networks and lock volume. |
| PFAS-Free Coating Validation | Silicone-based barrier treatment certification ahead of REACH restrictions secures premium snack and confectionery supply. |
Research Methodology
The analysis maps rollstock, pouch, sheet, and bag sub-sectors, each validated through converter procurement leads, brand owner packaging directors, MDO line operations managers, and chemical recycling technology developers. Primary interviews with film extruder plant managers, retail chain sustainability officers, and agricultural cooperative specification teams combined with secondary validation from EU Green Deal regulatory filings, ECHA REACH restriction proposals, FDA food contact notification databases, and SEC 10-K disclosures from integrated packaging platforms. Bottom-up volume triangulation across thickness bands, form factors, and end-use industries reconciled with top-down resin consumption estimates.
Assumptions held fixed include EU Green Deal recyclability mandate enforcement timelines and mechanical recycling infrastructure sorting capabilities, while ethylene feedstock cost trajectories and chemical recycling capacity buildouts were varied across scenarios. Segmentation dimensions modeled encompass product type, end-use industry, thickness specification, and optical form, with regional production hub clustering. CAGRs were derived from demand elasticity analysis against brand owner sustainability target trajectories, incorporating orientation ratio technology advancement curves and agricultural mulch film penetration rates.
Sensitivities concentrate around PPWR implementation pace, cracker margin volatility, and chemical recycling offtake agreement execution. Forecasts reflect documented assumptions regarding mono-material substitution rates and extended producer responsibility compliance timelines. Quarterly review of EU regulatory enforcement actions, US state-level EPR law progressions, and pyrolysis capacity commissioning announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Global BOPP Films Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
Multi-Layer Blown Films Market
Poly film
Poly Coated Kraft Paper Market
Poly film
PP Laminating Films Market
Poly film
China Plastic Packaging Film Market
Poly film
PP Film Blowing Machine Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
Vinyl Films Market
Poly film
Isotropic Film Market
Poly film
Recyclable Lidding Films Market
Poly film
Polyethylene Cast Film Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Global Specialty Films Polymer Market
Poly film
Chocolate Wrapping Films Market
Poly film
Soft Touch Film Market