
 Colombia Plastic Packaging Films Market | 2026-2036
Colombia Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Plastic Packaging Films Market Insights
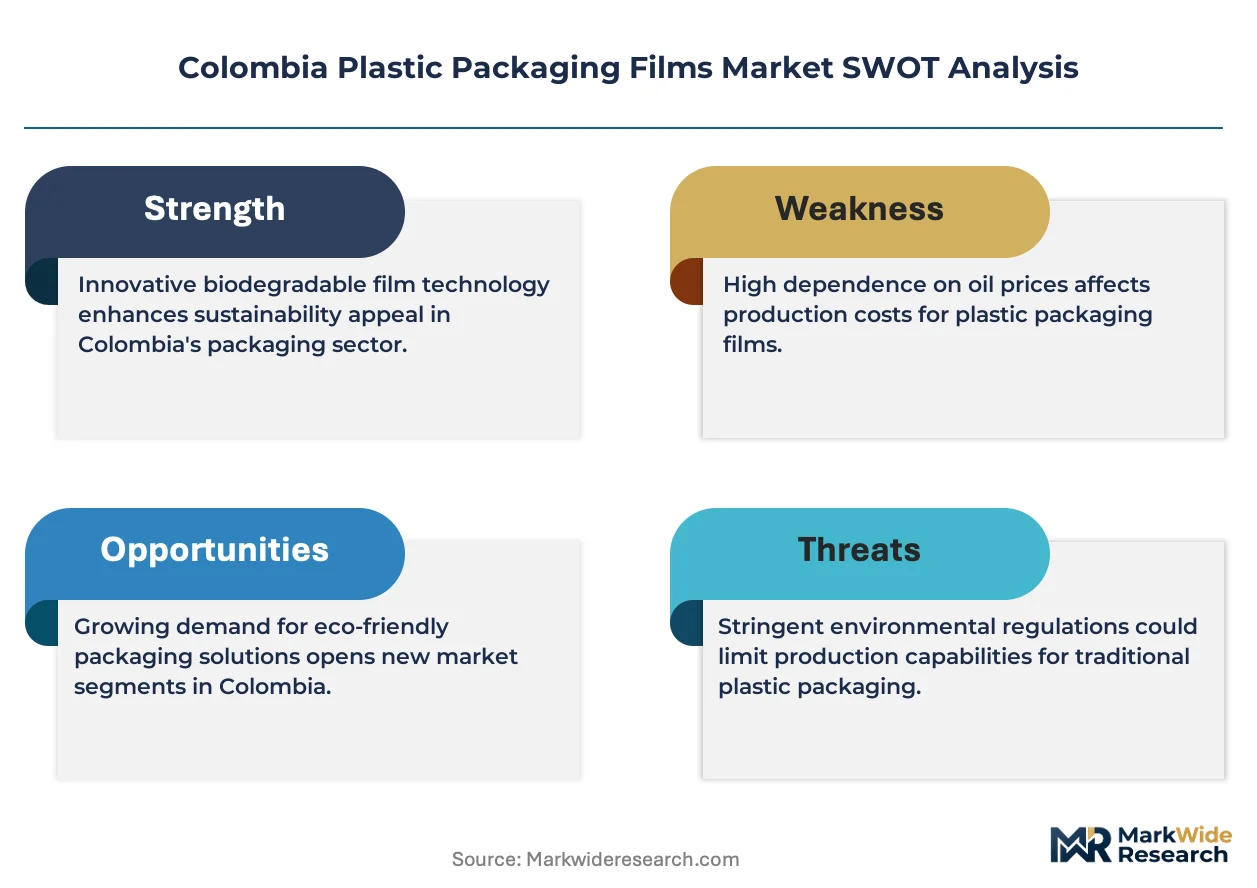
Technical service contracts for extrusion line calibration and die maintenance are expanding as a discrete revenue layer in Colombia's plastic packaging films sector. Amcor Plc leverages its regional technical service centers to lock in multi-year maintenance agreements with Andean converters. Berry Global Inc. anchors its Colombian position through backward integration into resin compounding, while Sealed Air Corporation differentiates via proprietary barrier coating technologies for protein packaging.
Colombia plastic packaging films are thermoplastic sheet or tubular structures, typically 12 to 150 microns thick, manufactured through blown or cast extrusion of polyethylene, polypropylene, polyethylene terephthalate, or polyvinyl chloride resins, designed to provide moisture barrier, gas protection, and mechanical containment for packaged goods. PE formulations dominate Colombian volume due to their cost position in flexible food wrapping and agricultural mulch applications, while PET films command premium positioning in electronics and pharmaceutical blister packaging where optical clarity and dimensional stability matter. The thin-gauge segment leads overall tonnage but faces margin compression from resin volatility, whereas heavy-gauge industrial films sustain stronger unit economics through specialized anti-corrosive and UV-stabilized formulations.
Colombia's Ministry of Environment and Sustainable Development enforces Law 2232 on single-use plastics and extended producer responsibility, compelling film producers to reformulate toward mono-material recyclable structures or absorb compliance penalties. The National Institute of Metrology (INM) certifies thickness tolerances and migration limits for food-contact films, creating a compliance threshold that filters out informal converters. Stakeholders must monitor how upcoming regulatory revisions to chemical recycling pathways reshape resin sourcing strategies and capital allocation for extrusion asset upgrades.
Market Dynamics
Colombia's Ministry of Environment and Sustainable Development is forcing film converters to abandon multi-material laminates in favor of mono-PE and mono-PP structures that mechanical recycling streams can process, reshaping resin procurement and extrusion equipment deployment across the Andean manufacturing corridor.
Growth Catalysts
- Extended Producer Responsibility Mandates:Law 2232 compliance deadlines are accelerating converter investment in recyclable film lines. Bogotá-based processors are retrofitting blown film assets to handle high-percentage recycled content feedstocks.
- Protein Packaging Demand:Cold chain expansion for beef and poultry exports is pulling multilayer barrier films into Medellín's packaging cluster. Dairy processors in the Sabana de Bogotá industrial zone are specifying oxygen-scavenging coextrusions.
- Polyethylene Cost Position:PE resin availability through Cartagena's petrochemical hub sustains cost advantages for flexible food wrapping against imported alternatives.
Market Restraints
- Resin Price Volatility:Ethylene and propylene feedstock fluctuations compress margins for thin-gauge commodity films, particularly affecting converters without backward integration into compounding.
- Recycling Infrastructure Gaps:Colombia's mechanical recycling capacity for post-industrial film scrap concentrates around Cali, forcing Bogotá and Medellín converters to absorb elevated logistics costs or stockpile waste.
- Barrier Performance Trade-offs:Mono-material recyclable structures sacrifice oxygen and moisture protection versus legacy multi-layer laminates, limiting adoption in premium pharmaceutical blister applications.
Strategic Opportunities
- Chemical Recycling Pathways:Upcoming regulatory revisions to pyrolysis and depolymerization standards could unlock feedstock flexibility for converters serving Coca-Cola's Andean bottling operations.
- Agricultural Mulch Films:UV-stabilized PE formulations for coffee and flower cultivation in the Coffee Triangle represent underpenetrated volume, with cooperatives shifting from conventional mulching to biodegradable alternatives.
- Technical Service Contracts:Extrusion line calibration and die maintenance agreements are emerging as sticky revenue layers, with regional service centers locking in multi-year commitments from mid-tier converters.
Industry Challenges
- Migration Testing Bottlenecks:INM certification timelines for food-contact compliance stretch 14-18 weeks, delaying product launches for converters without established laboratory relationships.
- Skilled Extrusion Technician Scarcity:Die gap adjustment and layer distribution optimization expertise concentrates among aging workforces in Cali's manufacturing corridor, constraining line utilization rates for new market entrants.
- Legacy Equipment Retrofit Costs:Converting existing blown film lines from multi-material to mono-material output requires screw and die replacement capital that informal converters cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Plastic Packaging Films Market |
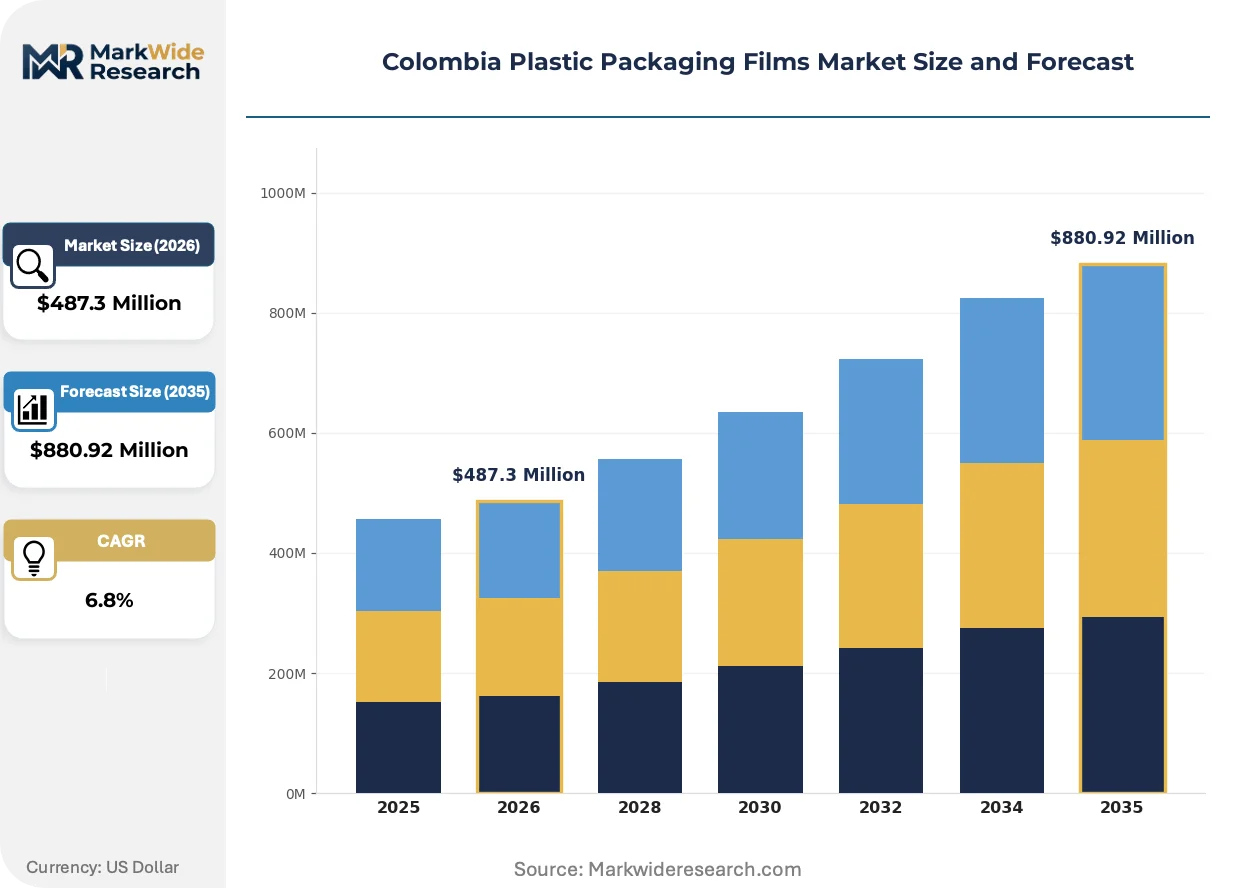
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PE, PP, PET, PVC Application: Food, Beverage, Electronics, Healthcare End User: Retail, Manufacturing, E-commerce, Agriculture Thickness: Thin, Medium, Heavy, Ultra-heavy |
| Companies Covered | Taghleef Industries, Berry Global Inc., Distripacking Colombia SAS, Plafilm SA, Amcor Plc, Sealed Air Corporation, Oben Holding Group, CORBEL S A, Empaques Transparentes SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Plastic Packaging Films Market Trends and Innovations
Active barrier coating technologies and digital printing integration are compressing traditional film value chains, while regulatory pressure on recyclability accelerates equipment replacement cycles across Colombia's converter base.
Plasma-enhanced chemical vapor deposition (PECVD) barrier coatings are electrifying competitive positioning in protein packaging. Poultry processors in Antioquia are specifying silicon oxide-coated PE films at triple the adoption rate of conventional metallized alternatives. This technology is electrifying margin structures by eliminating aluminum foil layers while maintaining shelf-life performance.
Colombia's Ministry of Environment and Sustainable Development is tightening chemical recycling pathway approvals under pending Law 2232 revisions. Industrial clusters anticipate pyrolysis-derived resin qualification for food-contact applications within 24 months. Cali's converter corridor is pre-positioning extrusion assets to accept these alternative feedstocks.
Brand-owner sustainability scorecards are compressing supplier qualification cycles. Postobón and Alpina are unbundling film procurement from legacy converter relationships, running parallel qualification tracks for certified circular-content suppliers. This behavioral shift concentrates in Bogotá's beverage and dairy packaging procurement functions.
Colombia Plastic Packaging Films Market Segmentation
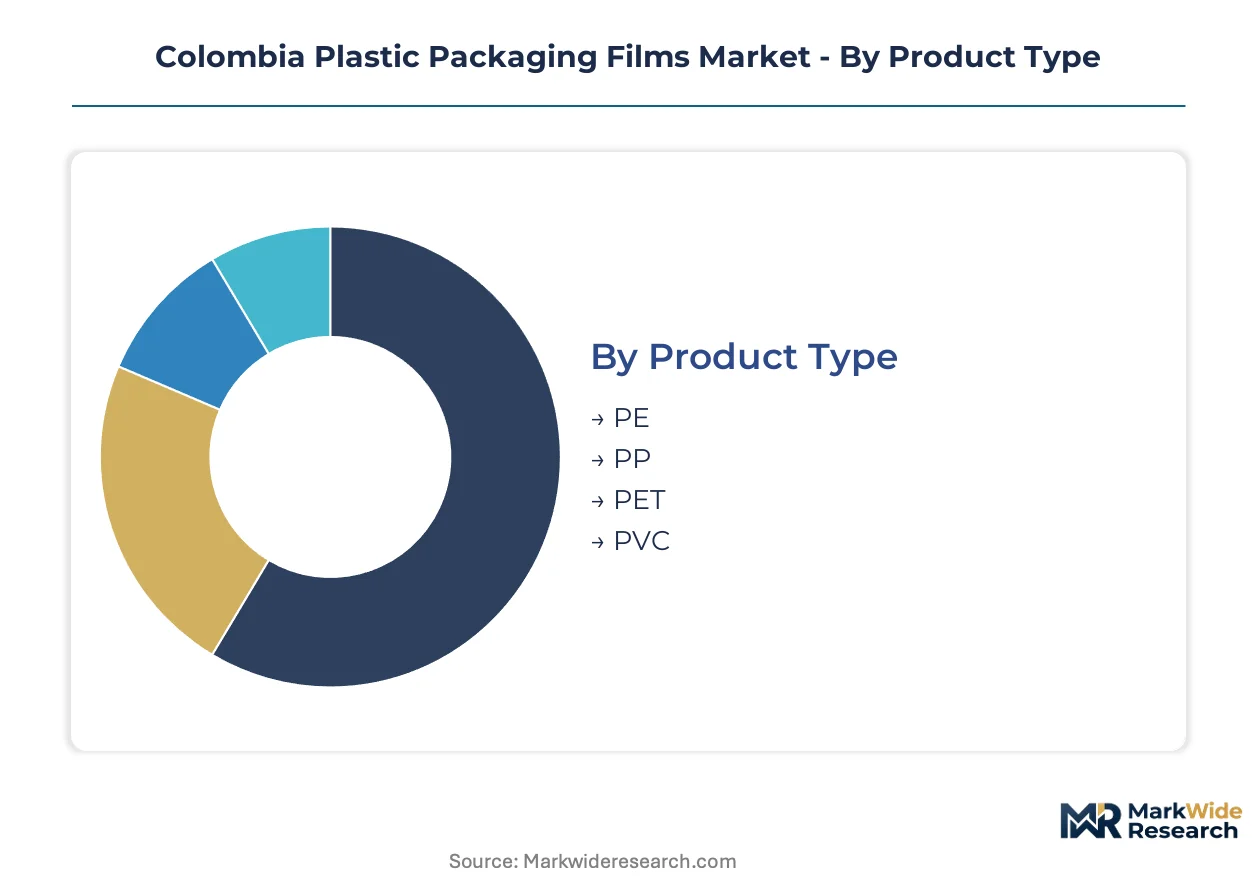
Colombia's plastic packaging films market fragments across resin chemistry, end-use performance requirements, and gauge specifications. Converter procurement patterns diverge sharply between commodity food wrapping and precision pharmaceutical barrier applications.
Product Type:
Buyers in this category sort by cost position, barrier performance, and recyclability compliance under Law 2232.
- PE:Polyethylene formulations dominate Colombian tonnage through blown extrusion of LDPE and LLDPE grades. Bogotá food processors specify PE for flexible meat and produce wrapping where moisture barrier and heat-sealability matter. Cartagena's petrochemical hub sustains resin cost advantages against imported alternatives.
- PP:Polypropylene films command premium positioning in cast extrusion formats for high-clarity applications. Medellín dairy converters favor biaxially oriented PP for cheese and yogurt lidding where stiffness and moisture resistance compete. Mono-PP structures align with Ministry of Environment recyclability mandates better than multi-material laminates.
- PET:Polyester films deliver dimensional stability and optical clarity for electronics and pharmaceutical blister packs. Cali's manufacturing corridor processes PET for export-oriented medical device packaging.
- PVC:Polyvinyl chloride persists in shrink-wrap applications for beverage multipacks despite regulatory pressure on chlorine-containing resins.
Volume sits with PE; growth tilts toward PP as converters retrofit for mono-material recyclability.
Application:
Demand concentration tracks Colombia's export agriculture base and domestic consumption patterns.
- Food:Protein packaging in Antioquia and dairy films in Sabana de Bogotá absorb multilayer barrier coextrusions. Cold chain expansion for beef and poultry exports pulls oxygen-scavenging formulations into converter order books.
- Beverage:Postobón's procurement specifications drive demand for high-clarity shrink labels and collation films in Bogotá's bottling corridor.
- Electronics:Anti-static PET films protect semiconductor components assembled in Cali's free trade zones.
- Healthcare:Pharmaceutical blister packs require INM-certified migration-compliant structures with precise thickness tolerances.
Food captures current volume; healthcare expands most quickly on export pharmaceutical growth.
End User:
Procurement scale and technical sophistication separate customer tiers in this category.
- Retail:Supermarket chains in Bogotá and Medellín specify pre-printed PE bags with shelf-ready graphics. Volume concentration favors converters with rotogravure printing partnerships.
- Manufacturing:Industrial processors in Cali's corridor purchase heavy-gauge stretch wrap and VCI films for metal part protection during export shipment.
- E-commerce:Mercado Libre fulfillment centers in Bogotá drive demand for lightweight polymailer films with tear-resistant seals.
- Agriculture:Coffee cooperatives in the Coffee Triangle specify UV-stabilized mulch films, with biodegradable alternatives gaining trial adoption.
Retail holds installed volume; agriculture shows steepest expansion trajectory on export crop protection demand.
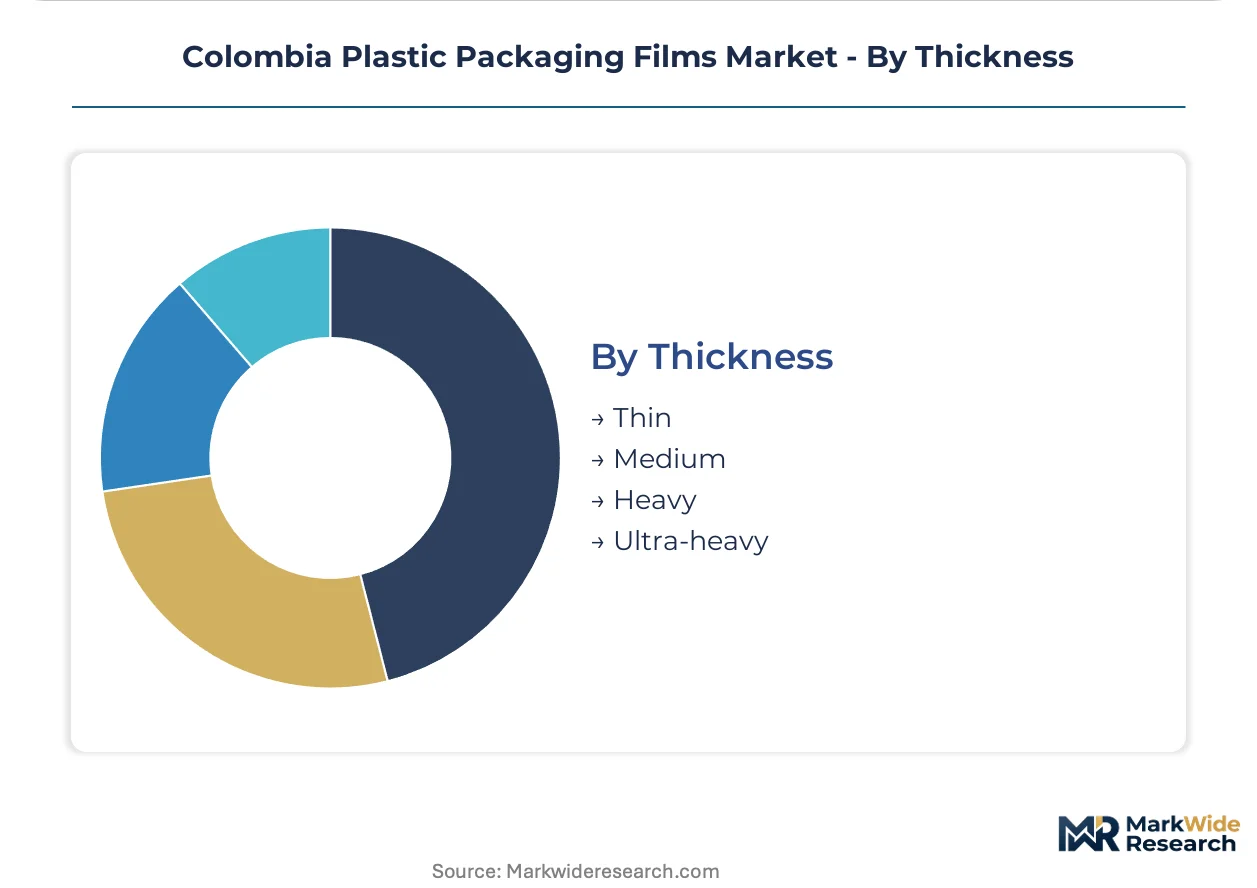
Thickness:
Margin structures invert across this category, with heavy gauges sustaining stronger unit economics.
- Thin:12-30 micron gauges serve bread bags and lightweight produce wrapping. Resin volatility compresses margins for commodity converters lacking backward integration.
- Medium:30-80 micron structures balance cost and performance for retail carry-out bags and industrial liners.
- Heavy:80-150 micron films deliver puncture resistance for agricultural mulch and construction vapor barriers. Anti-corrosive and UV-stabilized formulations command price premiums.
- Ultra-heavy:Above-150 micron gauges serve geomembrane and specialty industrial applications with limited local production capacity.
Thin gauges dominate tonnage; heavy gauges gain share fastest on agricultural and construction demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombia's plastic packaging films production clusters around Cartagena's petrochemical feedstock and the Andean converter corridor, while consumption concentrates in Bogotá's food processing belt and Medellín's protein packaging hub. This geographic split shapes logistics costs and technical service deployment patterns across the value chain.
Sabana de Bogotá
Dairy processors and beverage bottlers in this industrial zone absorb multilayer barrier films for yogurt lidding and oxygen-scavenging applications. Colombia's Ministry of Environment and Sustainable Development enforces Law 2232 extended producer responsibility rules, compelling converters to source mono-PE and mono-PP structures. Postobón's procurement specifications drive demand for high-clarity shrink labels in the capital's bottling corridor.
Antioquia Department
Beef and poultry exporters in Medellín's packaging cluster pull cold chain-compatible films with active barrier coatings. The National Institute of Metrology certifies migration limits for food-contact applications, creating compliance thresholds that filter informal suppliers. Poultry processors specify silicon oxide-coated PE films at accelerating rates versus conventional metallized alternatives.
Valle del Cauca
Cali's manufacturing corridor hosts heavy-gauge industrial film production for agricultural mulch and construction vapor barriers. Mechanical recycling capacity for post-industrial scrap concentrates here, forcing Bogotá and Medellín converters to absorb elevated logistics costs or develop local partnerships. UV-stabilized PE formulations for coffee cultivation in the Coffee Triangle represent expanding volume.
Cartagena Bolívar
The petrochemical hub sustains polyethylene resin cost advantages against imported alternatives through captive ethylene supply. Free trade zone status attracts multinational compounders seeking Andean market access. Resin availability underpins flexible food wrapping economics for thin-gauge commodity converters throughout the northern coast.
Colombia Plastic Packaging Films Market Competitive Landscape
Capital-heavy producers with captive resin compounding compete with asset-light converters sourcing feedstocks from third-party distributors. The market structures around three tiers: multinational integrated players with regional technical service centers, mid-scale domestic specialists with backward integration into compounding, and fragmented local converters serving commodity food wrapping. Dominant competitive moves include multi-year maintenance agreement lock-ins and extrusion asset retrofits for mono-material recyclability.
Among multinational integrated players, Amcor Plc and Berry Global Inc. occupy positions anchored by regional infrastructure and resin supply control. Sealed Air Corporation exemplifies the technology-differentiated archetype through proprietary barrier coating deployment. Mid-scale domestic specialists including Plafilm SA and Distripacking Colombia SAS represent the backward-integrated tier serving Andean protein and dairy processors with localized technical support.
| Leading Market Players |
|---|
| Taghleef Industries |
| Berry Global Inc. |
| Distripacking Colombia SAS |
| Plafilm SA |
| Amcor Plc |
| Sealed Air Corporation |
| Oben Holding Group |
| CORBEL S A |
| Empaques Transparentes SA |
| Others |
Pricing and Supply Chain Analysis
Backward integration into resin compounding anchors pricing power for Colombian film converters, with Berry Global Inc.'s captive feedstock operations in Cartagena insulating margin structures from ethylene volatility that squeezes asset-light competitors sourcing through distributors.
Pricing Analysis
Margin tightening in thin-gauge commodity films traces to ethylene feedstock volatility and resin price swings, while heavy-gauge industrial films sustain stronger unit economics through specialized UV-stabilized and anti-corrosive formulations. Three-tier pricing structure across premium barrier-coated, standard mono-material, and economy commodity levels separates converters by certification grade and technical service bundling. Pricing pressure accelerates in food-contact segments as Postobón and Alpina unbundle procurement from legacy relationships. Retail chains show highest price sensitivity; pharmaceutical blister pack buyers prioritize INM migration compliance over cost.
Supply Chain Analysis
Polyethylene resin supply rests on Cartagena's petrochemical hub and imported feedstocks from the US Gulf Coast and Middle Eastern producers. Key inputs include ethylene monomer, LLDPE and LDPE grades, and specialty additives for UV stabilization and oxygen scavenging. Single-source vulnerability concentrates around mechanical recycling capacity in Cali, forcing Bogotá converters to absorb elevated logistics costs. Distribution runs through converter-direct relationships with dairy processors in Sabana de Bogotá and protein packers in Medellín, supplemented by third-party distributors serving fragmented agricultural buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's plastic packaging films sector is consolidating around Law 2232 compliance investments that filter out informal converters lacking capital for mono-material extrusion retrofits.
For Market Incumbents: Deepen technical service contract penetration to lock in multi-year maintenance agreements with Andean converters, insulating against emerging regional competitors. Retrofit blown film assets for high-percentage recycled content feedstocks before chemical recycling pathway approvals reshape resin sourcing. Prioritize INM laboratory relationships to compress 14-18 week migration certification timelines that delay product launches. For New Entrants and Emerging Players: Regional distributors serving coffee cooperatives in the Coffee Triangle represent the most penetrable channel, with UV-stabilized mulch films and biodegradable alternatives showing trial adoption momentum. Target agricultural end-users through cooperative procurement networks rather than competing directly for Postobón and Alpina contracts. Lead with technical service bundling and extrusion line calibration capabilities to differentiate from commodity converters. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale domestic specialists with backward integration into compounding and established INM certification relationships. Long-term viability hinges on converters pre-positioning for pyrolysis-derived resin qualification under pending Law 2232 revisions. Watch chemical recycling regulatory approvals as the inflection signal for feedstock flexibility and asset valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Berry Global Inc.'s captive feedstock operations in Cartagena insulate margins from ethylene volatility. |
| Mono-Material Extrusion Retrofit | Converters serving Postobón and Alpina retrofit lines to meet Ministry of Environment recyclability mandates. |
| Technical Service Contract Expansion | Amcor Plc leverages regional service centers to lock multi-year maintenance agreements with Andean processors. |
| Active Barrier Coating Deployment | Sealed Air Corporation's silicon oxide coatings for Antioquia poultry processors eliminate aluminum foil layers. |
| Chemical Recycling Pre-Positioning | Cali's converter corridor positions extrusion assets for pyrolysis-derived resin qualification. |
Research Methodology
Document review covered trade customs data, SEC filings of multinational packaging firms, and Ministry of Environment regulatory filings, complemented by interviews with extrusion line operators, resin procurement managers at dairy processors, technical service directors, and INM certification specialists. Secondary validation drew from petrochemical production disclosures, extended producer responsibility compliance reports, and cold chain infrastructure assessments. Bottom-up converter capacity estimates triangulated against top-down resin consumption data.
Segment-level value and volume trajectories across the projection horizon reflect resin chemistry splits, gauge specifications, and end-use performance tiers including food-contact barrier requirements, pharmaceutical migration limits, and agricultural UV stabilization. CAGRs were derived from elasticity-adjusted demand modeling for protein packaging, dairy films, and industrial mulch applications. Industry-specific inputs included Law 2232 compliance timelines, chemical recycling pathway regulatory signals, and cold chain expansion rates for beef and poultry exports.
Caveats apply where resin price volatility, delays in chemical recycling approvals, or informal converter exit rates could materially shift the outlook. Forecasts reflect documented assumptions around regulatory enforcement intensity and mechanical recycling capacity expansion. A small set of triggers—pyrolysis-derived resin qualification timelines, INM certification backlog resolution, and skilled extrusion technician availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Polylaminate Capsules Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
Metallized Film Market
Poly film
Thermoforming Films Market
Poly film
Packaging Film Market
Poly film
Polypropylene Film Market
Poly film
Laminated Packaging Films Market
Poly film
Polyimide Films and Tapes Market
Poly film
Multi-Layer Blown Films Market
Poly film
Polypropylene Packaging Films Market
Poly film
Bundling Film Market
Poly film
PVC Film for Medical Market
Poly film
Formable Films Market
Poly film
PE Foam Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market