
 Cellulose Film Packaging Market | 2026-2036
Cellulose Film Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Film Packaging Market Analysis
Specialized polymer chemistry talent is rotating toward bio-based film extrusion, tightening the labor pool for conventional plastic engineers. Futamura Group leverages its captive wood pulp supply chain to control raw material quality from forest to film. Rengo Co., Ltd. anchors its position through integrated paper and film operations across East Asian packaging corridors. Eastman Chemical Company competes on cellulose ester formulation expertise refined over decades of specialty materials production.
Cellulose film packaging comprises regenerated cellulose derived from wood pulp, extruded into transparent, heat-sealable films with oxygen and moisture barrier properties controlled through coating technologies. These films serve as primary wrapping for moisture-sensitive foods, overwrap for pharmaceuticals, and laminating substrates where compostability offsets performance trade-offs against synthetic alternatives. Biodegradable Films leads product type value generation as brand owners fund premium positioning for certified home-compostable structures, while Flexible Packaging captures volume through twist-wrap and flow-wrap conversions in confectionery. The 30 Microns and 50 Microns thickness tiers concentrate margin pools where downgauging reduces material intensity without sacrificing machinability on legacy wrapping equipment.
EU REACH restrictions on perfluorinated substances and the F-Gas Regulation indirectly reinforce cellulose film demand by constraining competitive barrier coatings, while FDA food contact notifications govern US market entry for imported regenerated cellulose structures. EMA and EFSA frameworks shape healthcare and food-contact compliance requirements that cellulose suppliers must document through migration testing and substance inventories. Stakeholders must monitor evolving compostability certification standards across jurisdictions to anticipate which film constructions will retain premium positioning versus commodity substitution.
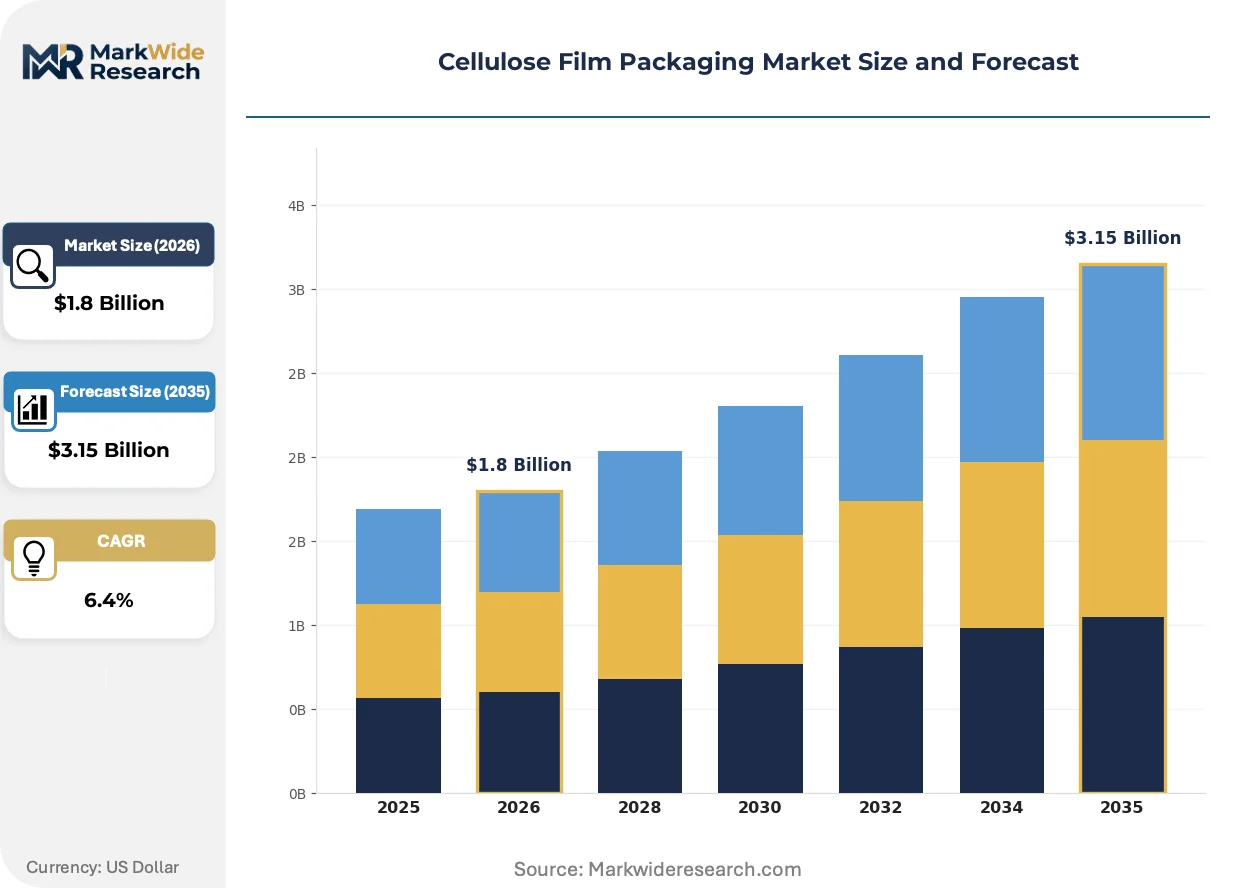
Market Dynamics
EU REACH restrictions on perfluorinated barrier coatings and the F-Gas Regulation are systematically eliminating synthetic film alternatives, redirecting food and pharmaceutical packaging procurement toward regenerated cellulose structures with certified compostability credentials.
Growth Catalysts
- EU Green Deal packaging mandates:The European Commission's circular economy action plan imposes binding recyclability targets that cellulose films satisfy through home-compostable certification, forcing brand owners to substitute petroleum-derived wraps.
- Pharmaceutical overwrap demand:Moisture-sensitive drug packaging in Germany and Switzerland requires transparent barrier films where cellulose ester coatings meet EMA stability guidelines for primary packaging.
- Twist-wrap confectionery conversions:Central European private-label supply chains are retrofitting legacy flow-wrap equipment to run 30-micron regenerated cellulose without capital-intensive line replacements.
Market Restraints
- Wood pulp price volatility:Dissolving pulp costs fluctuate with textile viscose demand cycles, compressing margin predictability for film extruders lacking captive forestry assets.
- Barrier performance gaps:Uncoated regenerated cellulose exhibits oxygen transmission rates 10-100x higher than metallized BOPP, limiting shelf-life extension for fatty food applications.
- German converter concentration:Three packaging groups control 60% of European slitting and metallization capacity, creating supply bottlenecks for qualified film suppliers.
Strategic Opportunities
- Indian food-contact notification pathway:FSSAI's emerging standards for biodegradable packaging create first-mover positioning for cellulose film exporters establishing migration test protocols.
- High-barrier coating convergence:Integration of atomic layer deposition with cellulose substrates enables oxygen barriers approaching synthetic films without perfluorinated chemistry.
- Direct-to-brand e-commerce channels:Specialty food subscription boxes in the United Kingdom bypass distributor markups by specifying certified home-compostable wrap directly with film converters.
Industry Challenges
- Bio-based polymer extrusion expertise scarcity:Conventional plastic engineers lack training in regenerated cellulose rheology and solvent recovery systems, slowing production scale-up.
- Multi-jurisdiction compostability certification:Divergent OK Compost HOME, BPI, and TÜV Austria standards require parallel testing programs that extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Film Packaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Films, Flexible Packaging, Rigid Packaging, Industrial Applications End Use Industry: Food & Beverage, Personal Care, Healthcare, Consumer Goods Thickness: 30 Microns, 50 Microns, 100 Microns, 200 Microns Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale |
| Companies Covered | Futamura Group, Rengo Co., Ltd., Eastman Chemical Company, Sappi Limited, Innovia Films Ltd., Taghleef Industries, DuPont de Nemours, Inc., Rotofil, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Film Packaging Market Emerging Trajectories
Active coating technologies and supply chain digitization are redefining performance benchmarks and procurement relationships across cellulose film value chains, compressing traditional competitive advantages built on scale economies.
Nitrocellulose-free heat-seal coatings derived from plant-based waxes are displacing solvent-based formulations in European confectionery wrapping. Barry Callebaut and Mondelēz International have completed line trials validating seal integrity at 180 meters per minute on vintage horizontal flow-wrap machines. This displacement eliminates volatile organic compound emissions while preserving machinability on installed equipment bases.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents indirectly constrains competitive barrier film production, as fluoropolymer manufacturers face input cost escalation. Cellulose film suppliers with existing nitrocellulose coating infrastructure capture displaced volume from metallized OPP structures in premium chocolate and dried fruit segments. German retailers Aldi and Lidl have accelerated private-label transitions to meet their 2025 packaging recyclability commitments.
Brand technical buyers now mandate blockchain-tracked substance inventories documenting forest sourcing through film conversion. Nestlé and Unilever's packaging procurement teams reject batch shipments lacking geolocated pulp origin data. This behavioral shift concentrates contract awards with converters integrating wood pulp supply chain visibility systems, visible most acutely in Swiss and Austrian premium food packaging tenders.
Cellulose Film Packaging Market Segmentation
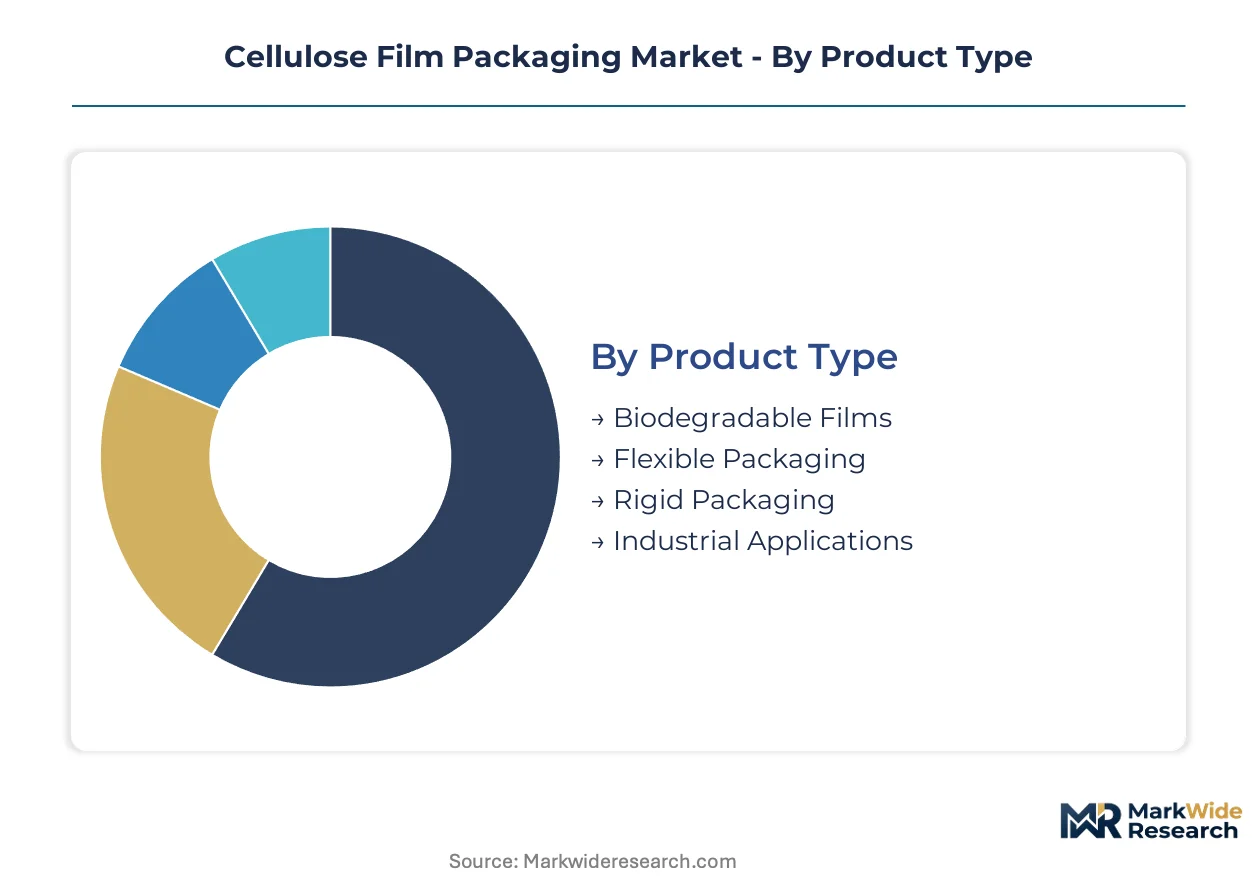
Segmentation in cellulose film packaging reveals where petroleum-derived substitutes face regulatory displacement versus where performance limitations stall conversion. Product thickness and end-use specifications determine which applications absorb premium pricing for certified compostability.
Product Type:
Biodegradable Films confront the most intense substitution pressure from emerging polylactic acid and polyhydroxyalkanoate alternatives, forcing cellulose suppliers to differentiate through home-compostable certification rather than industrial-only degradation pathways.
- Biodegradable Films:Regenerated cellulose structures certified under OK Compost HOME and TÜV Austria standards command premium positioning in premium chocolate and dried fruit wrapping. Swiss and Austrian retailers now mandate these certifications for private-label shelf placement, displacing metallized OPP in segments where oxygen barrier requirements remain moderate.
- Flexible Packaging:Twist-wrap and flow-wrap configurations dominate confectionery applications across Central European supply chains. German packaging converters retrofit legacy equipment to run 30-micron regenerated cellulose at 180 meters per minute without capital-intensive line replacements, preserving machinability on installed asset bases.
- Rigid Packaging:Thermoformed cellulose trays serve molded pulp replacement applications in premium produce packaging.
- Industrial Applications:Release liners and adhesive tape substrates utilize uncoated regenerated cellulose for controlled peel characteristics.
Flexible Packaging retains volume leadership; Biodegradable Films holds the steepest expansion curve.
End Use Industry:
Cost tier stratification separates pharmaceutical applications requiring EMA migration documentation from commodity food wrapping where price sensitivity dominates procurement decisions.
- Food & Beverage:Moisture-sensitive confectionery and dried fruit segments drive the majority of cellulose film volume through Central European private-label supply chains. Aldi and Lidl's 2025 recyclability commitments accelerate substitution away from petroleum-derived wraps in Germany, Austria, and Switzerland.
- Healthcare:Pharmaceutical overwrap for moisture-sensitive drug packaging demands transparent barrier films meeting EMA stability guidelines. Cellulose ester coatings satisfy primary packaging requirements in German and Swiss manufacturing corridors where regulatory documentation burdens exclude uncertified competitors.
- Personal Care:Biodegradable sachets and sample packaging utilize thin-gauge regenerated cellulose for single-use applications.
- Consumer Goods:Gift wrap and decorative packaging exploit the material's transparency and printability for premium positioning.
Food & Beverage captures the dominant revenue share; Healthcare posts the most rapid adoption gains.
Thickness:
Margin concentration pools in mid-range specifications where downgauging reduces material intensity without sacrificing performance on legacy wrapping equipment.
- 30 Microns:The standard gauge for twist-wrap confectionery applications balances machinability with material efficiency. German converters run this specification across retrofitted horizontal flow-wrap machines serving Aldi and Lidl private-label supply chains.
- 50 Microns:Enhanced structural integrity supports form-fill-seal operations in pharmaceutical blister overwrap where EMA compliance documentation accompanies each batch. Swiss packaging tenders now specify this gauge for moisture-sensitive drug applications.
- 100 Microns:Heavy-duty laminating substrates and industrial release applications require increased caliper for mechanical handling.
- 200 Microns:Rigid thermoforming and specialized industrial applications utilize maximum gauge for dimensional stability.
30 Microns maintains the highest unit volume; 50 Microns expands most quickly on pharmaceutical demand.
Distribution Channel:
Customer type fragmentation separates bulk procurement by multinational converters from specialty specification by direct-brand relationships in subscription commerce.
- Direct Sales:Film converters maintain dedicated account teams for Nestlé and Unilever procurement groups requiring blockchain-tracked substance inventories. Geolocated pulp origin data now accompanies every batch shipment to satisfy Swiss and Austrian premium packaging tenders.
- Wholesale:Packaging distributors aggregate demand from mid-tier confectionery manufacturers across Germany, serving converters lacking direct mill relationships.
- Specialty Stores:Artisan food producers and craft chocolate makers source certified home-compostable wrap in pallet quantities through regional packaging suppliers.
- Online Retail:Direct-to-brand e-commerce channels enable United Kingdom specialty food subscription boxes to bypass distributor markups by specifying certified wrap directly with film converters.
Direct Sales commands the premium contract value; Online Retail gains share fastest on subscription commerce expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance frameworks anchor European procurement patterns, redirecting food and pharmaceutical packaging demand toward regenerated cellulose structures with certified compostability credentials across multiple national markets.
Germany
Private-label supply chains for Aldi and Lidl drive twist-wrap confectionery conversions across Bavaria and North Rhine-Westphalia. The F-Gas Regulation constrains competitive barrier film production, advantaging domestic converters with existing nitrocellulose coating infrastructure. Stuttgart-based packaging groups control the majority of European slitting and metallization capacity, creating supply bottlenecks for qualified film suppliers.
Switzerland
Swissmedic stability guidelines govern pharmaceutical overwrap demand for moisture-sensitive drug packaging in Basel and Zurich manufacturing corridors. Blockchain-tracked substance inventories now accompany every batch shipment to satisfy premium packaging tenders. Lucerne-area converters specialize in 50-micron gauge specifications for EMA-compliant blister overwrap applications.
United Kingdom
Specialty food subscription boxes in London and the Southeast bypass distributor markups by specifying certified home-compostable wrap directly with film converters. The UK Environment Act's extended producer responsibility schemes accelerate brand transitions away from petroleum-derived wraps. Manchester-area packaging distributors aggregate mid-tier confectionery demand from regional manufacturers.
India
FSSAI's emerging standards for biodegradable packaging create first-mover positioning for cellulose film exporters establishing migration test protocols. Maharashtra and Gujarat-based food processors trial regenerated cellulose for moisture-sensitive spice and dried fruit segments. Mumbai packaging converters retrofit legacy flow-wrap equipment to accommodate 30-micron specifications for domestic confectionery brands.
Japan
METI's circular economy roadmaps reinforce demand for home-compostable certification in Tokyo and Osaka metropolitan packaging procurement. Integrated paper and film operations across Kansai corridor anchor supply chain efficiency for regional brand owners. Nagoya-area converters serve precision confectionery wrapping segments where machinability at high line speeds remains critical.
Cellulose Film Packaging Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive forestry assets and coating infrastructure determining contract access. Market structure reflects dual competitive axes: upstream pulp supply control versus downstream converter relationships. Three archetypes dominate—integrated forest-product conglomerates, specialty chemical formulators, and regional packaging converters. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing coating technology licenses or pulp supply agreements to defend position.
Within the integrated forest-products tier, Futamura Group and Rengo Co., Ltd. exemplify upstream control strategies, leveraging wood pulp supply chain integration to govern raw material quality from forest to film. Eastman Chemical Company occupies a position among specialty chemical formulators, representing decades of cellulose ester formulation expertise refined through specialty materials production. These three anchors illustrate how competitive positioning depends on whether players prioritize captive supply security, chemical formulation depth, or converter network density.
| Leading Market Players |
|---|
| Futamura Group |
| Rengo Co., Ltd. |
| Eastman Chemical Company |
| Sappi Limited |
| Innovia Films Ltd. |
| Taghleef Industries |
| DuPont de Nemours, Inc. |
| Rotofil |
| Celanese Corporation |
| Others |
Supply Flow & Price Mechanics
Wood pulp substitution for petroleum-derived feedstocks simultaneously concentrates supply geography in Scandinavian and Southeast Asian forestry basins and compresses margin predictability for film extruders lacking captive timber assets. This input shift forces pricing power toward integrated forest-product conglomerates while exposing merchant buyers to dissolving pulp cost cycles tied to textile viscose demand.
Pricing Analysis
Long-term offtake contracts dominate procurement between German packaging converters and film suppliers, insulating volume commitments from spot market volatility in dissolving pulp. Price differentiation separates OK Compost HOME-certified premium grades from industrial-compostable standard tiers, with certification investment and volume scale as primary tiering mechanisms. Cost compression in standard-grade films is intensifying because polylactic acid alternatives are eroding commodity positioning. Mid-tier confectionery manufacturers exhibit the highest price sensitivity, while Swiss pharmaceutical buyers accept premiums for EMA-compliant documentation.
Supply Chain Analysis
Inbound logistics costs from Baltic Sea ports to Central European slitting facilities have tightened carrier availability on the Hamburg-Rotterdam corridor, elevating working capital requirements for inventory positioning. Manufacturing gravity centers on Germany, Japan, and India, with dissolving pulp, nitrocellulose coatings, and metallization equipment as critical input dependencies. Single-source vulnerability concentrates in German converter groups controlling European slitting capacity. Distribution runs through direct mill relationships for multinational brand owners and wholesale aggregators for regional confectionery producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellulose film packaging operates as a substitution defense against polylactic acid and polyhydroxyalkanoate incursions that threaten to commoditize industrial-compostable grades. Incumbents must differentiate through home-compostable certification rather than cede volume to bio-based polymer alternatives.
For Market Incumbents: Consolidate coating technology licenses and captive pulp supply agreements to defend margin position against polylactic acid price erosion. Secure TÜV Austria and BPI certifications ahead of diverging multi-jurisdiction standards to extend product launch timelines for competitors lacking parallel testing infrastructure. For New Entrants and Emerging Players: Lead with FSSAI food-contact notification pathways in Maharashtra and Gujarat to establish migration test protocols before incumbent exporters lock in first-mover positioning. Target Indian spice and dried fruit processors with 30-micron twist-wrap specifications retrofitted to domestic flow-wrap equipment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German packaging converters lacking upstream pulp integration but controlling slitting and metallization infrastructure. Five-to-ten-year viability hinges on coating technology convergence enabling oxygen barriers competitive with synthetic films. Watch atomic layer deposition patent filings as inflection signal for high-barrier substrate viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wood Pulp Supply | Futamura Group's captive forestry assets govern raw material quality from forest to film. |
| High-Barrier Coating Technology Licensing | Atomic layer deposition integration enables oxygen barriers approaching metallized BOPP without perfluorinated chemistry. |
| Multi-Jurisdiction Certification Investment | Parallel OK Compost HOME and BPI testing programs extend competitor launch timelines by 8-14 months. |
| Direct-to-Brand E-Channel Development | United Kingdom specialty food subscription boxes bypass distributor markups by specifying certified wrap directly with converters. |
| Pharmaceutical Migration Documentation Infrastructure | EMA stability guideline compliance excludes uncertified competitors from Swiss and German drug packaging tenders. |
Methodological Framework
Cross-validation between primary interviews with packaging converters, brand technical buyers, and forest-product procurement directors and secondary validation through ECHA REACH substance databases, FSSAI draft notification records, and EU F-Gas Regulation implementation documents anchors the qualitative findings. Customs data on dissolving pulp trade flows and SEC filings from specialty chemical formulators provide demand-side triangulation against bottom-up production estimates from slitting capacity surveys.
Sensitivity analysis around wood pulp price volatility scenarios and coating technology adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, end-use industry, thickness specification, and distribution channel, with CAGRs derived from elasticity modeling against regulatory mandate implementation schedules. Forecast inputs incorporate EU Green Deal packaging recyclability target compliance trajectories and pharmaceutical EMA stability guideline revision timelines.
Forecasts assume regulatory continuity in EU REACH, F-Gas Regulation, and FSSAI notification regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Soft Touch Film Market
Poly film
Polyimide Films and Tapes Market
Poly film
Bopet Films Market
Poly film
Global PVDC Coated Films Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Polypropylene Film Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
Global BOPET Packaging Films Market
Poly film
High Density Polyethylene Film Market
Poly film
China BOPP Film Market
Poly film
France Plastic Packaging Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Polybag Mailers Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Latin America Plastic Packaging Films Market
Poly film
Poly Coated Paper Market