
 Global Label Adhesive Market | 2026-2036
Global Label Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Label Adhesive Market Foresight
Asian pressure-sensitive adhesive producers is expanding roll-coating capacity to serve surging label demand from e-commerce fulfillment centers. Henkel AG & Co. KGaA leverages its European R&D footprint to sustain formulation leadership in low-VOC acrylics for food-contact applications. 3M anchors North American supply through proprietary solvent-free adhesive platforms, while H.B. Fuller competes aggressively in Latin America with localized hot-melt production.
Label adhesives are bonding compositions—typically acrylic, rubber-based, or hot-melt polymers applied at 15–50 g/m² coat weight—that create permanent or removable attachment between a face stock and a substrate across temperature and humidity extremes. Their primary purpose is to ensure legibility, tamper evidence, and traceability of packaged goods through automated dispensing and end-use exposure. Acrylic formulations dominate pharmaceutical and electronics applications where clarity and UV resistance command premium positioning, while rubber-based systems retain cost leadership in general-purpose consumer goods labeling. Hot-melt adhesives represent the fastest-growing adhesive type as converters eliminate solvent drying stages to reduce energy intensity and regulatory exposure.
EPA VOC emissions rules, EU REACH chemical registration requirements, and FDA 21 CFR 175.105 food-contact adhesive standards collectively force reformulation investments and restrict market access for non-compliant suppliers. These frameworks elevate compliance costs for smaller compounders while rewarding scale players with dedicated regulatory affairs teams and pre-approved substance inventories. Stakeholders must monitor evolving PFAS restrictions and biobased content mandates across multiple jurisdictions to anticipate the next wave of product specification changes.
Market Dynamics
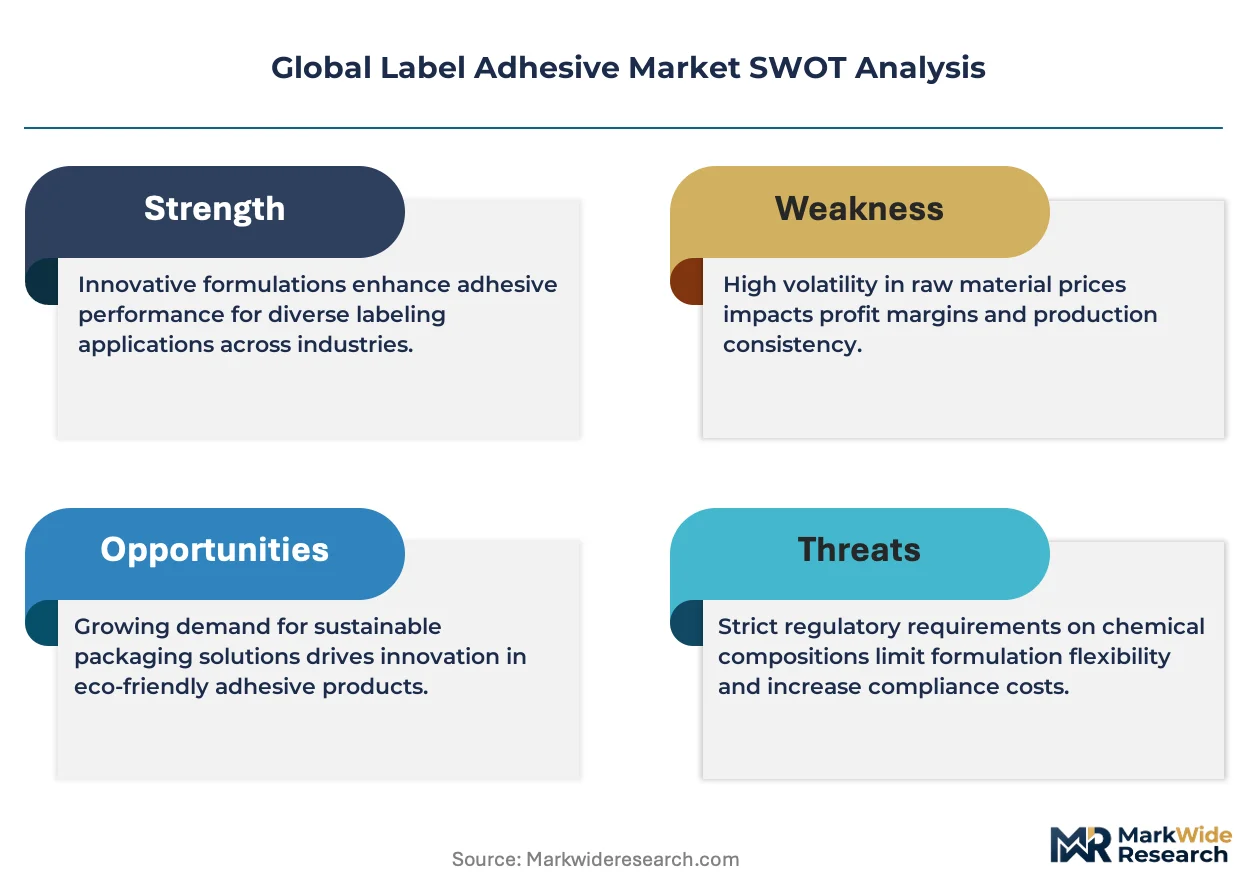
Hot-melt adhesive systems are absorbing capital investment from European and Asian converters seeking to eliminate solvent drying stages and satisfy tightening food-contact material rules.
Growth Catalysts
- E-commerce logistics expansion:Fulfillment centers in Germany and China are scaling pressure-sensitive label capacity to handle parcel tracking and returns management at industrial scale.
- FDA 21 CFR 175.105 compliance:Food packaging lines across multiple jurisdictions are converting adhesive systems to meet direct food-contact safety standards for ready-meal and fresh-produce applications.
- Pharmaceutical serialization mandates:Track-and-trace regulations in Brazil and European markets are driving tamper-evident label demand with specialized acrylic formulations.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and rubber-based adhesive producers face margin compression from propylene and styrene-butadiene price swings.
- Specialty resin supply concentration:High-performance tackifier production clusters in Southeast Asia create single-source vulnerability for premium hot-melt formulations.
- PFAS regulatory uncertainty:Pending restrictions on fluorinated processing aids in the EU and US states are forcing preemptive reformulation of release coatings.
Strategic Opportunities
- India packaging modernization:Domestic converter consolidation under BIS quality standards is creating demand for imported hot-melt coating technology and technical training.
- Biobased content mandates:EU Green Deal procurement rules are opening specification windows for adhesives derived from rosin esters and starch derivatives.
- UV-LED curing convergence:Narrow-web label presses are integrating instant-cure systems that eliminate thermal drying and enable thinner coat weights on heat-sensitive films.
Industry Challenges
- Formulation chemist scarcity:Experienced polymer scientists capable of balancing peel adhesion, shear resistance, and regulatory compliance command premium compensation and extended recruitment cycles.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and GB standard food-contact approvals require 18-36 month validation programs that delay regional product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Label Adhesive Market |
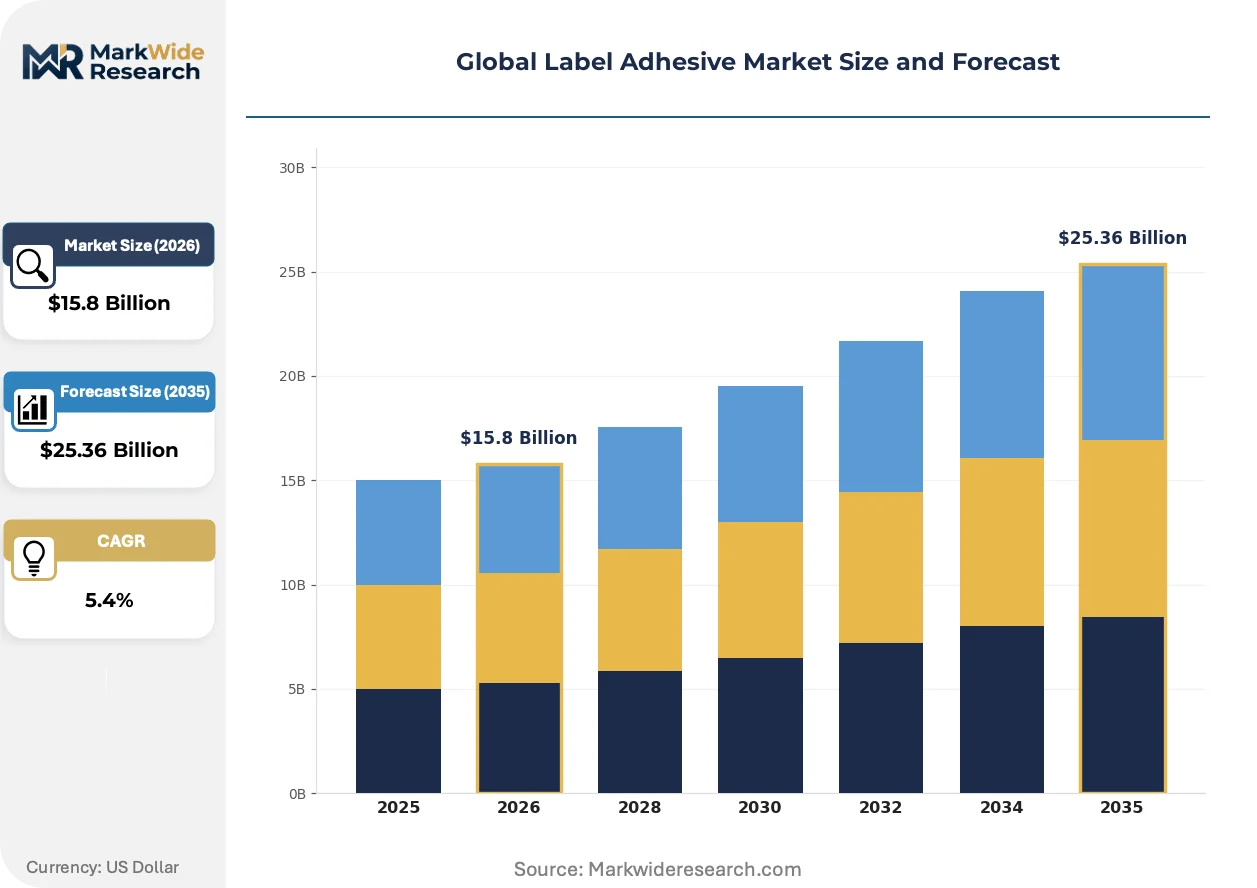
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $25.36 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Adhesive Type: Acrylic, Rubber-Based, Hot Melt, Silicone, Polyurethane Application: Food Packaging, Personal Care, Pharmaceuticals, Electronics, Household Products End User Industry: Manufacturing, Consumer Goods, Chemicals, Agriculture, Apparel Packaging Format: Rolls, Sheets, Tubes, Bottles, Pouches |
| Companies Covered | Avery Dennison Corporation, Henkel AG & Co. KGaA, 3M, H.B. Fuller, CCL Industries, The Dow Chemical Company, PPG Industries, Lintec Corporation, UPM Raflatac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Label Adhesive Market Shifts & Advancements
Adhesive performance specifications are tightening as end-users demand single formulations that perform across frozen, ambient, and heated supply chain conditions without label flag or adhesive bleed.
Water-based acrylic emulsions with sub-50 g/m² coat weights are absorbing share from solventborne systems in beverage and personal care labeling. Major brand owners in North America and Western Europe have mandated VOC reduction targets that exclude traditional solvent technologies from new equipment specifications. The shift is compressing demand for thermal oxidizer infrastructure and redirecting converter capital toward high-speed gravure and flexo coating lines.
EU REACH authorization requirements for substances of very high concern are forcing systematic substance inventory audits across adhesive supply chains. Compounders must demonstrate safe-use pathways or secure sunset-date extensions for legacy tackifiers and crosslinkers. Pharmaceutical and electronics label segments are responding fastest, establishing pre-approved raw material lists that exclude contested chemistries before regulatory deadlines.
Brand-owner sustainability scorecards are reshaping supplier selection criteria beyond unit cost to encompass carbon intensity, recyclability compatibility, and circular content verification. Major retailers in France and Germany now require adhesive suppliers to submit third-party lifecycle assessments as a condition of contract renewal. This behavioral shift is most visible in private-label food and cosmetics packaging, where procurement teams prioritize partners with documented bio-based feedstock sourcing and solvent recovery systems.
Global Label Adhesive Market Segmentation
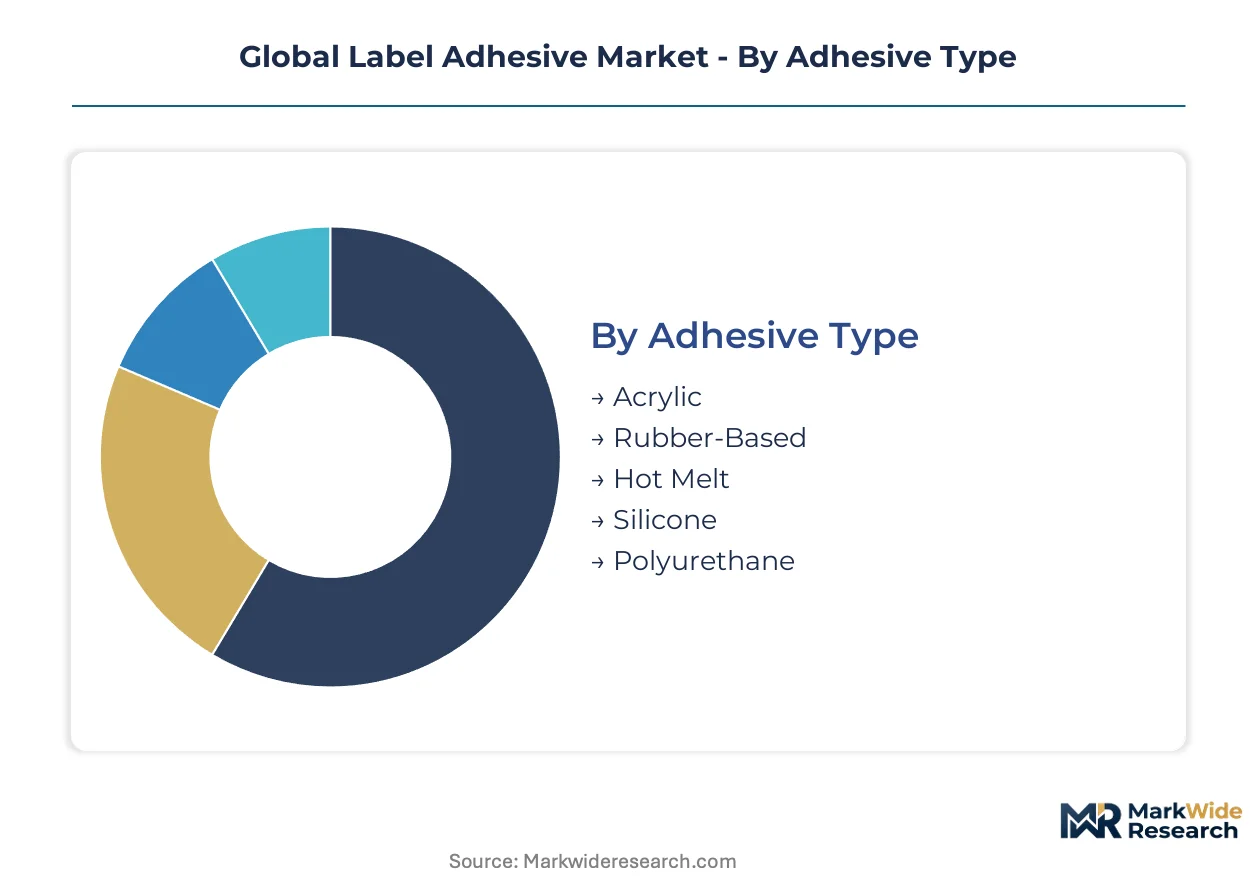
Label adhesive specifications diverge sharply across end-use environments, from frozen food logistics to sterile pharmaceutical cleanrooms. Manufacturers configure product portfolios around these segmentation axes to align formulation investments with compliance thresholds and volume concentration points.
Adhesive Type:
Standardized commodity formulations dominate high-volume segments while specialty polymers command premium positioning in regulated applications.
- Acrylic:Waterborne and solventborne copolymers delivering optical clarity and UV stability for transparent film labels. Pharmaceutical serialization mandates in Brazil and electronics traceability requirements in Germany concentrate demand for high-purity grades with low extractables profiles.
- Hot Melt:Thermoplastic block copolymers applied molten without solvent carriers, eliminating drying stages and thermal oxidizer infrastructure. Converters in China and Germany are absorbing capacity expansion for e-commerce logistics labels where instant tack and shear resistance prove critical.
- Rubber-Based:Natural and synthetic rubber tackifiers offering aggressive initial adhesion on corrugated and recycled substrates. Cost-sensitive consumer goods labeling in India and Southeast Asia sustains volume leadership despite regulatory pressure on aromatic process oils.
- Silicone:Crosslinked polydimethylsiloxane systems for removable and repositionable applications. High-value electronics and automotive labeling segments specify silicone release liners compatible with cleanroom assembly protocols.
- Polyurethane:Two-component reactive systems delivering chemical resistance and flexible bonding on elastomeric films. Niche penetration in medical device labeling and industrial safety signage where abrasion resistance outweighs unit cost premiums.
Leading the category by volume: Rubber-Based. Growing fastest: Hot Melt.
Application:
Regulatory intensity stratifies this dimension, with food-contact and pharmaceutical segments imposing the steepest compliance burdens on adhesive suppliers.
- Food Packaging:Direct and indirect food-contact adhesives governed by FDA 21 CFR 175.105 and EU 10/2011 migration limits. Ready-meal and fresh-produce segments in France and Germany are converting from solventborne to water-based and hot-melt systems to satisfy tightening authority scrutiny.
- Pharmaceuticals:Tamper-evident and unit-dose labeling with serialization compliance for track-and-trace mandates. Brazil's ANVISA regulations and EU Falsified Medicines Directive enforcement are driving specification upgrades toward acrylic formulations with documented extractables profiles.
- Personal Care:Moisture-resistant adhesives for shower-safe labels and cosmetic containers with premium aesthetic requirements. Brand-owner sustainability scorecards in Germany now mandate bio-based content thresholds for contract renewal eligibility.
- Electronics:Low-outgassing, static-dissipative adhesives for component labeling and battery identification. Japanese electronics manufacturers specify halogen-free formulations meeting JIS standards for flame retardancy.
- Household Products:General-purpose pressure-sensitive adhesives for detergents, cleaners, and air fresheners. Price competition from private-label retailers compresses margins, favoring rubber-based formulations with regional tackifier sourcing.
Dominant by revenue: Food Packaging. Steepest specification upgrades: Pharmaceuticals.
End User Industry:
Customer concentration patterns split between fragmented SME converters and consolidated multinational brand owners with centralized procurement.
- Manufacturing:Industrial equipment and automotive component labeling with durability requirements spanning temperature extremes. German automotive suppliers specify adhesives validated for paint-shop and under-hood exposure cycles.
- Consumer Goods:High-volume beverage, food, and personal care packaging with rapid line speeds and changeover flexibility. E-commerce fulfillment centers in China demand labels surviving drop tests and humidity exposure during last-mile delivery.
- Chemicals:GHS-compliant hazard communication labels resisting solvent splash and UV degradation. US OSHA and EU CLP classification requirements mandate substrate-adhesive combinations maintaining legibility after chemical contact.
- Agriculture:Seed and crop protection labeling with outdoor durability and biodegradation compatibility. Brazilian agrochemical distributors face ANVISA registration requirements paralleling pharmaceutical traceability standards.
- Apparel:Care label and size flag adhesives surviving industrial laundering and dry cleaning. Fast-fashion supply chains in Bangladesh and Vietnam prioritize low-cost hot-melt options with adequate wash resistance.
Highest volume concentration: Consumer Goods. Fastest procurement upgrade cycles: Chemicals.
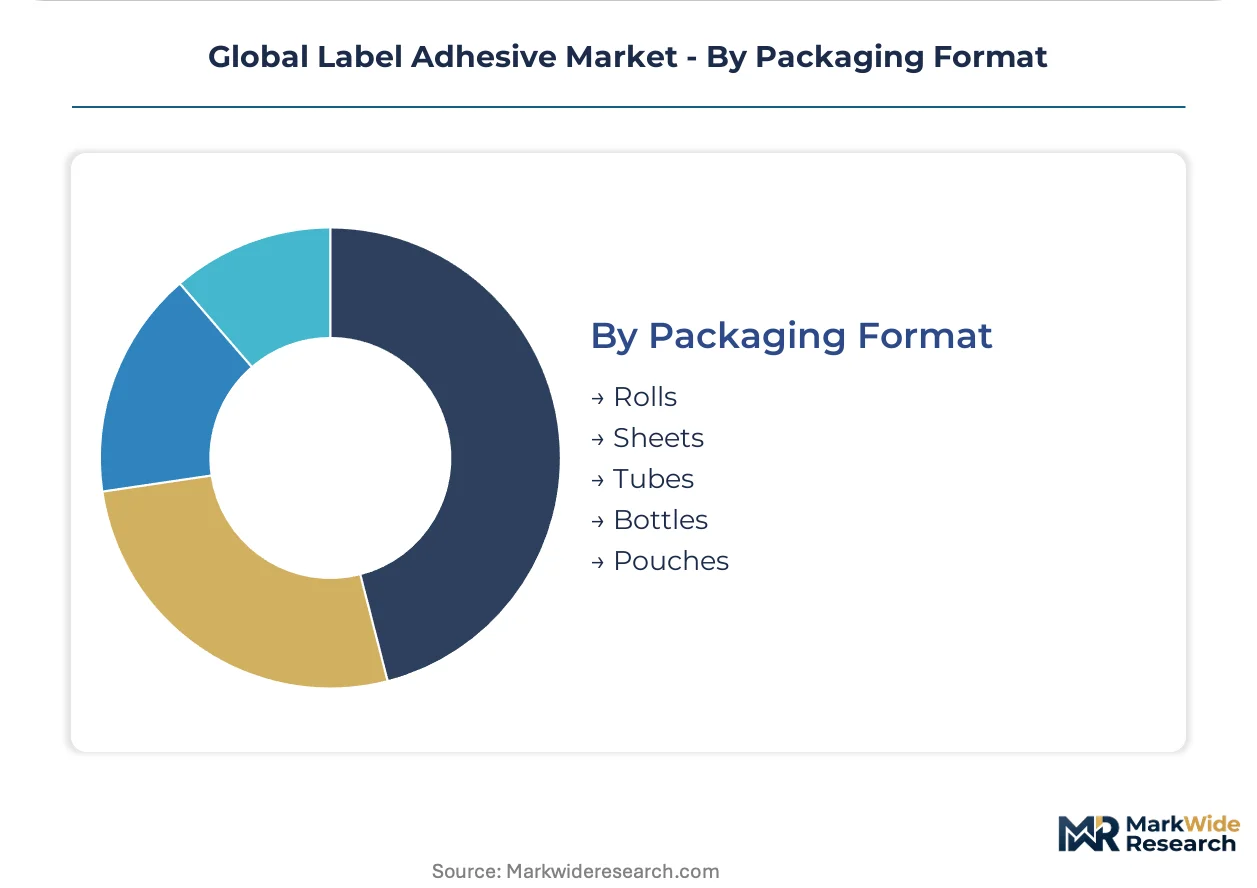
Packaging Format:
Converter equipment configuration and line speed requirements determine adhesive coat weight and dispensing compatibility across format types.
- Rolls:Continuous web pressure-sensitive materials for high-speed automatic label dispensers. German and Chinese converters are scaling roll-coating capacity to serve e-commerce logistics demand with 500-meter-plus jumbo roll formats.
- Sheets:Cut-to-size labels for sheet-fed offset and digital presses serving short-run customization. Commercial print shops in India favor sheet formats for pharmaceutical sample labeling with variable data integration.
- Tubes:Squeeze-resistant adhesives for flexible packaging in personal care and pharmaceutical ointments. Laminate tube manufacturers specify adhesions preventing delamination during crimp sealing.
- Bottles:Conformable labels for glass and PET containers with wet-glass and refrigerated adhesion requirements. Beverage bottlers in Mexico and Brazil prioritize hot-melt options for returnable bottle washing compatibility.
- Pouches:Flexible film labels for stand-up pouches and retort packaging. Retort sterilization cycles at 121°C demand specialized crosslinked acrylics preventing adhesive bleed and edge lifting.
Widest equipment compatibility: Rolls. Fastest format innovation: Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene and tackifier resin supply clusters in Southeast Asia and the US Gulf Coast shape regional adhesive production economics. Germany, China, and Brazil concentrate the fastest procurement expansion as local converters scale pressure-sensitive label capacity for e-commerce logistics and pharmaceutical serialization.
Germany
Automotive component labeling and pharmaceutical serialization drive specification upgrades across Bavaria and Baden-Württemberg. EU REACH authorization requirements for substances of very high concern force systematic substance inventory audits among compounders. The Rhine-Main cluster around Frankfurt anchors hot-melt coating technology investment serving pan-European fulfillment networks.
China
E-commerce fulfillment centers in the Yangtze River Delta and Pearl River Delta absorb expanded roll-coating capacity for parcel tracking labels. GB standards for food-contact materials tighten migration limit compliance for adhesives used in ready-meal packaging. Zhejiang and Jiangsu provinces concentrate water-based acrylic emulsion production serving domestic beverage and personal care converters.
Brazil
ANVISA pharmaceutical serialization mandates accelerate tamper-evident label procurement from São Paulo and Rio de Janeiro converters. Agrochemical distributors in Minas Gerais face registration requirements paralleling pharmaceutical traceability standards. Local hot-melt production scales to serve Latin American e-commerce logistics demand with reduced import dependency.
United States
FDA 21 CFR 175.105 compliance drives food packaging line conversion across Midwest and Southeast manufacturing corridors. EPA VOC emissions rules compress demand for thermal oxidizer infrastructure in favor of water-based and hot-melt systems. The Texas-Louisiana petrochemical corridor supplies propylene feedstock to acrylic adhesive producers facing margin pressure from price volatility.
India
BIS quality standards for packaging materials trigger converter consolidation in Maharashtra and Gujarat. Domestic demand for imported hot-melt coating technology rises as technical training partnerships expand. The Delhi-NCR pharmaceutical cluster upgrades label specifications to meet export compliance for regulated markets.
Global Label Adhesive Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biobased formulation certifications and regional licensing partnerships. The market structure consolidates around multinational chemical conglomerates with pre-approved raw material inventories and dedicated regulatory affairs teams. Three archetypes dominate: petrochemical-integrated compounders, specialty tackifier formulators, and regional converters with captive adhesive blending. Capacity expansion and strategic technology licensing represent the primary competitive moves as players eliminate solvent drying stages.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and 3M exemplify scale-driven archetypes with European and North American R&D footprints respectively. H.B. Fuller occupies a position within the specialty formulator tier, anchoring Latin American market presence through localized production strategies. These three entities represent distinct geographic and technological positioning vectors without overlapping core market focus.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Henkel AG & Co. KGaA |
| 3M |
| H.B. Fuller |
| CCL Industries |
| The Dow Chemical Company |
| PPG Industries |
| Lintec Corporation |
| UPM Raflatac |
| Others |
Supply & Pricing Matrix
Experienced formulation chemists concentrated in Germany and the US Midwest command premium compensation that widens spreads between premium-certified and commodity-grade adhesive tiers. Labor-cost differentials between these technical centers and emerging Asian compounding hubs translate directly into pricing stratification across hot-melt, acrylic, and rubber-based product lines.
Pricing Analysis
Service bundling separates pricing tiers, with premium suppliers including regulatory compliance support and formulation customization while economy-grade producers strip out technical assistance. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in commodity rubber-based segments intensifies because propylene and styrene-butadiene feedstock volatility compresses converter margins. Small-scale packaging converters in India and Southeast Asia exhibit highest price sensitivity, while pharmaceutical serialization mandates in Brazil and Germany render large brand owners least sensitive to unit cost premiums.
Supply Chain Analysis
Dual-sourcing requirements from major European and North American brand owners mandate multi-supplier qualification for critical tackifier resins and acrylic monomers. Geographic supply concentration centers on Germany, China, and the US Gulf Coast for petrochemical feedstocks, with Southeast Asian clusters dominating high-performance tackifier production. Raw material dependencies rest on propylene derivatives, rosin esters, and styrene-butadiene rubber. Single-source vulnerability in specialty resin supply creates structural risk for premium hot-melt formulations. Distribution runs through converter-direct relationships with regional chemical distributors serving fragmented SME label producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty resin capacity constraints in Southeast Asia prop pricing power for qualified suppliers, creating a supply-constrained market structure favoring incumbents with pre-approved substance inventories.
For Market Incumbents: Lock in long-term offtake agreements with propylene suppliers in the US Gulf Coast and German petrochemical corridors to defend against feedstock volatility. Secure REACH pre-registration for legacy tackifiers before sunset-date deadlines to maintain formulation continuity against emerging biobased entrants. For New Entrants and Emerging Players: Capture specification windows in India's packaging modernization wave by partnering with domestic converters for hot-melt coating technology transfer. White-space targets include BIS-certified food-contact adhesives and pharmaceutical export-grade formulations for Delhi-NCR cluster demand. For Investors and Strategic Acquirers: Re-rating potential sits with regional formulators possessing captive regulatory affairs capabilities given accelerating PFAS restriction timelines. Long-term viability favors acquisition targets with documented bio-based feedstock sourcing and solvent recovery infrastructure. Monitor EU Green Deal procurement rule implementation as inflection indicator for biobased mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tackifier Resins | Henkel and H.B. Fuller secure supply continuity against Southeast Asian concentration risk. |
| Regulatory Pre-Approval Investment | 3M sustains FDA 21 CFR 175.105 compliance leadership for food-contact adhesive platforms. |
| Biobased Formulation Certification | Specialty compounders capture EU Green Deal specification windows for rosin ester derivatives. |
| Regional Licensing Partnership | Technology licensors penetrate India's converter consolidation under BIS quality standards. |
| UV-LED Curing Technology Integration | Narrow-web press manufacturers enable thinner coat weights for heat-sensitive film labels. |
Research Methodology
Multi-period observation of adhesive formulation patent filings, regulatory submission timelines, and converter capacity announcements anchored the trend analysis, supplemented by interviews with technical R&D directors at compounders, procurement leads at downstream label converters, distribution channel partners, and regulatory affairs specialists. Secondary validation drew from ECHA REACH registration databases, FDA 21 CFR food-contact substance inventories, customs trade data for tackifier resin flows, and SEC filings of listed chemical conglomerates. Bottom-up volume estimates triangulated against top-down petrochemical feedstock consumption models.
Input-output matrices mapped adhesive type, application segment, packaging format, and regional production hub dimensions across the analysis window. CAGRs derived from elasticity-adjusted demand projections tied to e-commerce logistics expansion and pharmaceutical serialization mandate implementation schedules. Forecast inputs incorporated propylene price scenario modeling and EU PFAS restriction timeline assumptions.
The model holds under stable regulatory enforcement trajectories and petrochemical supply continuity; deviation in REACH authorization timelines or Southeast Asian resin export restrictions would shift volume projections. A model refresh is warranted upon material change in EU Green Deal biobased procurement thresholds or FDA food-contact adhesive standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Extended Text Labels Market
Labels
Sleeve Label Market
Labels
Sustainable Labels Market
Labels
Inventory Tags Market
Labels
India Print Label Market
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
Global Pressure Labels Market
Labels
ESD Protective Signage Labels Market
Labels
Shipping Label Market
Labels
Fiber Optic Labels Market
Labels
Global Label Market
Labels
Self-Adhesive Labels Market
Labels
Braille Labels Market
Labels
Freezer Label Market
Labels
Foil Labels Market
Labels
Pin Feed Labels Market