
 Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market | 2026-2036
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market Foresight
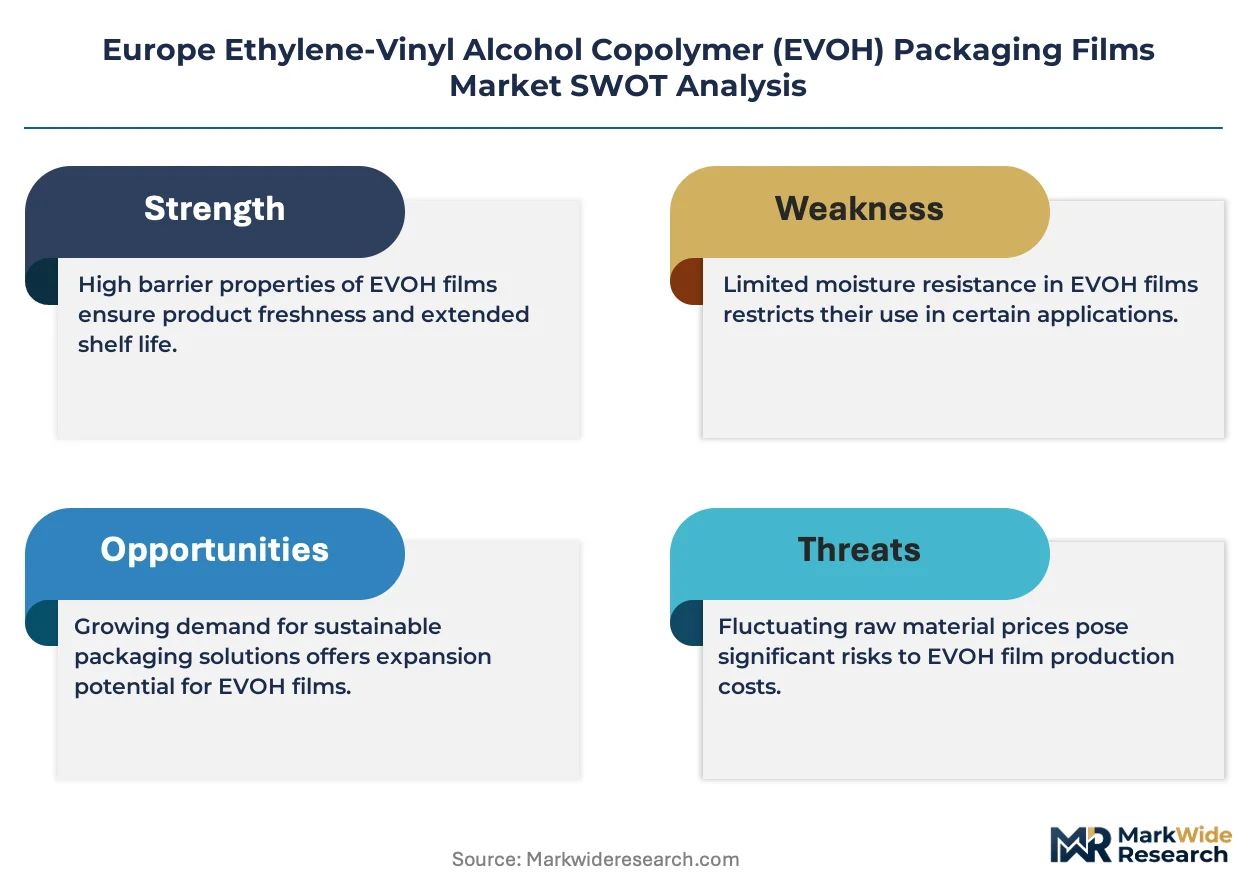
EU Packaging and Packaging Waste Regulation is pivoting the cost-of-entry calculus for EVOH film suppliers toward demonstrable recyclability and extended producer responsibility compliance. Mondi plc leverages its integrated paper and film operations to navigate circular-economy mandates across Central European converting networks. Kuraray Europe GmbH anchors its position through captive EVOH resin supply and deep specialization in oxygen-barrier grades for thermoforming applications. Arkema competes by extending its high-performance polymer portfolio into multilayer structures that meet emerging single-material recyclability criteria.
Ethylene-vinyl alcohol copolymer packaging films comprise thermoplastic barrier layers synthesized through copolymerization of ethylene and vinyl alcohol monomers, typically exhibiting oxygen transmission rates below 0.1 cc/m²/day at 20°C and 65% relative humidity when dry, and serve primarily to prevent oxidative degradation in sensitive packaged goods. The copolymer's hydroxyl-rich backbone creates tortuous molecular pathways that block gas permeation while permitting controlled coextrusion with polyolefin tie layers in cast or blown film processes. Barrier films command margin concentration due to their irreplaceable performance in retort and modified-atmosphere applications where alternative materials fail to match EVOH's oxygen scavenging efficiency. Coextruded films are gaining structural share as brand owners pursue mono-material polyethylene or polypropylene streams compatible with existing European mechanical recycling infrastructure. Multilayer films remain the volume backbone in pharmaceutical blister and industrial chemical packaging where regulatory validation cycles lock in specifications for extended periods.
REACH and the EU Green Deal frame chemical safety and carbon-intensity benchmarks that EVOH film formulations must satisfy to maintain market access across member states. ECHA substance evaluation protocols and emerging PPWR recyclability verification requirements are forcing converters to document polymer compatibility and sortability at end-of-life. Germany's national packaging regulator and France's extended producer responsibility schemes enforce differentiated fee modulation that rewards higher recycled content and penalizes non-recyclable multilayer constructions. Stakeholders must monitor how rapidly harmonized recyclability testing protocols displace national interpretive variations, as this standardization timeline will determine which film architectures retain economic viability across European converting networks.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing the viable design space for multilayer barrier films, forcing converters to reengineer coextruded structures toward mono-material recyclability without sacrificing oxygen barrier performance.
Growth Catalysts
- Extended producer responsibility schemes:France's Citeo fee modulation rewards high-barrier recyclable films, pulling EVOH grades into redesigned polyethylene streams.
- Modified-atmosphere packaging:Processed meat supply chains across Germany demand shelf-life extension that only ethylene-vinyl alcohol copolymers deliver at sub-0.1 cc/m²/day oxygen transmission.
- Rhine-Ruhr converting cluster:Proximity between coextrusion specialists and brand owners reduces logistics costs and specification turnaround times.
Market Restraints
- Ethylene feedstock volatility:Naphtha-derived ethylene cost swings compress margin predictability for EVOH resin producers.
- Asian resin concentration:Captive supply chains anchored in Japan and Korea create import dependency for European film converters.
- Mechanical recycling incompatibility:Legacy multilayer structures incorporating EVOH tie layers fail current PPWR sortability protocols.
Strategic Opportunities
- Spain and Italy underpenetration:Mediterranean processed food markets lag Northern Europe in high-barrier adoption, presenting volume expansion potential.
- Pharmaceutical blister films:EVOH's moisture and oxygen dual-barrier properties align with EMA stability requirements for sensitive drug formulations.
- Digital watermarking integration:AI-driven sorting infrastructure at European mechanical recycling plants enables traceable EVOH identification and separation.
Industry Challenges
- Coextrusion engineering scarcity:Specialized knowledge in seven- to nine-layer blown film dies remains concentrated among aging technical workforces in Germany and Austria.
- PPWR verification timelines:ECHA substance evaluation protocols delay recyclability certification for reformulated tie-layer adhesives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market |
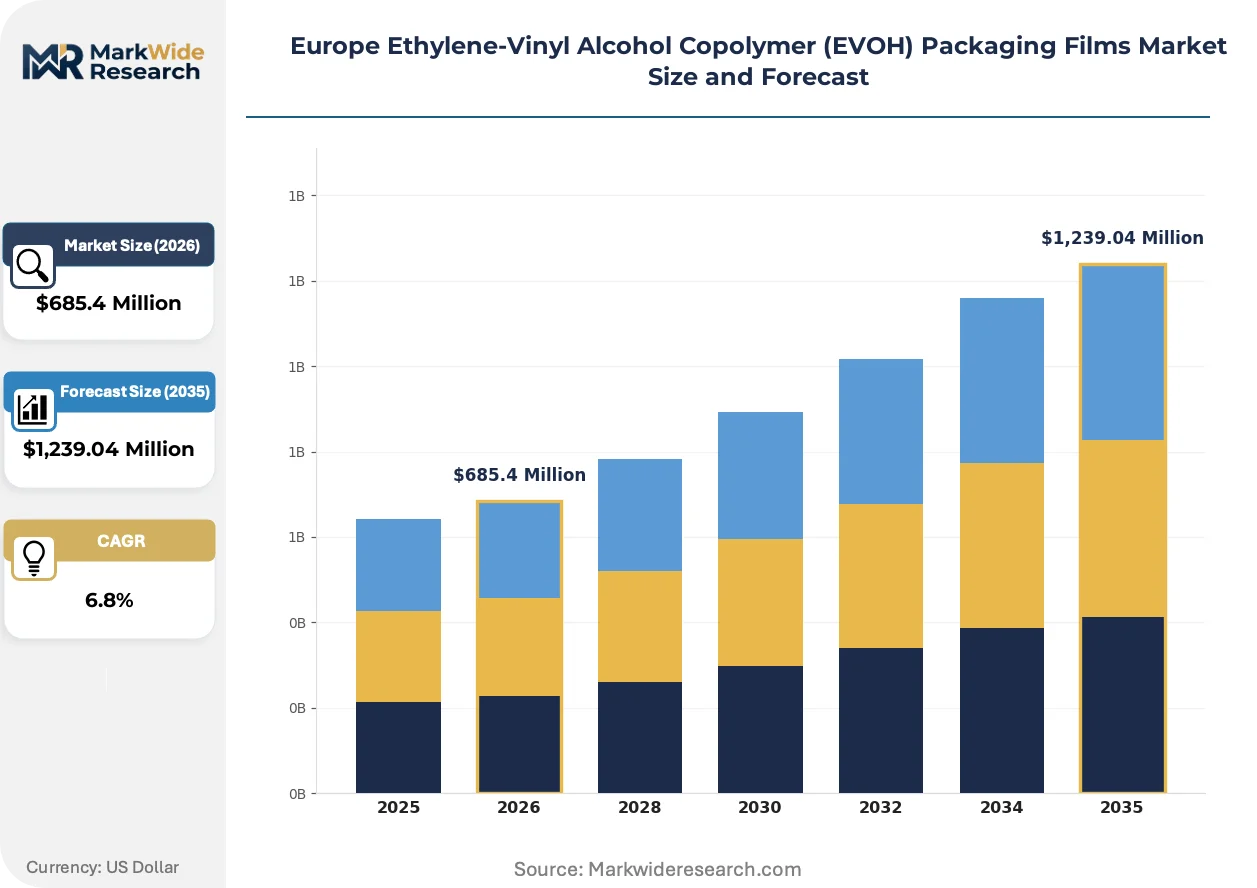
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Films, Barrier Films, Coextruded Films, Multilayer Films Application: Food Packaging, Pharmaceutical Packaging, Cosmetic Packaging, Industrial Packaging Thickness: Below 25 Micron, 25-50 Micron, 50-100 Micron, Above 100 Micron End User: Food & Beverage, Healthcare, Personal Care, Electronics |
| Companies Covered | Mondi plc, Arkema, Kuraray Europe GmbH, Innovia Films Ltd, Schur Flexibles, Nippon Gohsei (UK), Amcor plc, Taghleef Industries LLC, KUREHA CORPORATION, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market Shifts & Advancements
Film architecture innovation is accelerating as converters race to decouple barrier performance from multilayer complexity, with digital traceability and mono-material compatibility emerging as the dual pillars of next-generation specifications.
Mono-material polyethylene structures with ultrathin EVOH cores are rewriting the technical specifications that brand owners transmit to converters. Retail chains in Germany and the Netherlands now mandate recyclable streams that mechanical sorting infrastructure can process without delamination. This specification compression is eliminating legacy nylon-EVOH-polyethylene laminates from new product development cycles.
REACH substance evaluation protocols are forcing reformulation of adhesive tie layers that previously bonded EVOH to polyolefin substrates. ECHA scrutiny of isocyanate-based chemistries is extending validation timelines for new film constructions. Converters are responding by accelerating pilot trials with water-based or hot-melt alternatives that maintain interlayer adhesion through retort sterilization.
Brand owner technical audits are compressing supplier qualification cycles from twenty-four months to twelve months for critical food applications. Procurement teams at pan-European retailers now require documented recyclability pathways before contract award. This timeline pressure is most visible in France, where extended producer responsibility fees create immediate cost consequences for non-compliant packaging specifications.
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market Segmentation
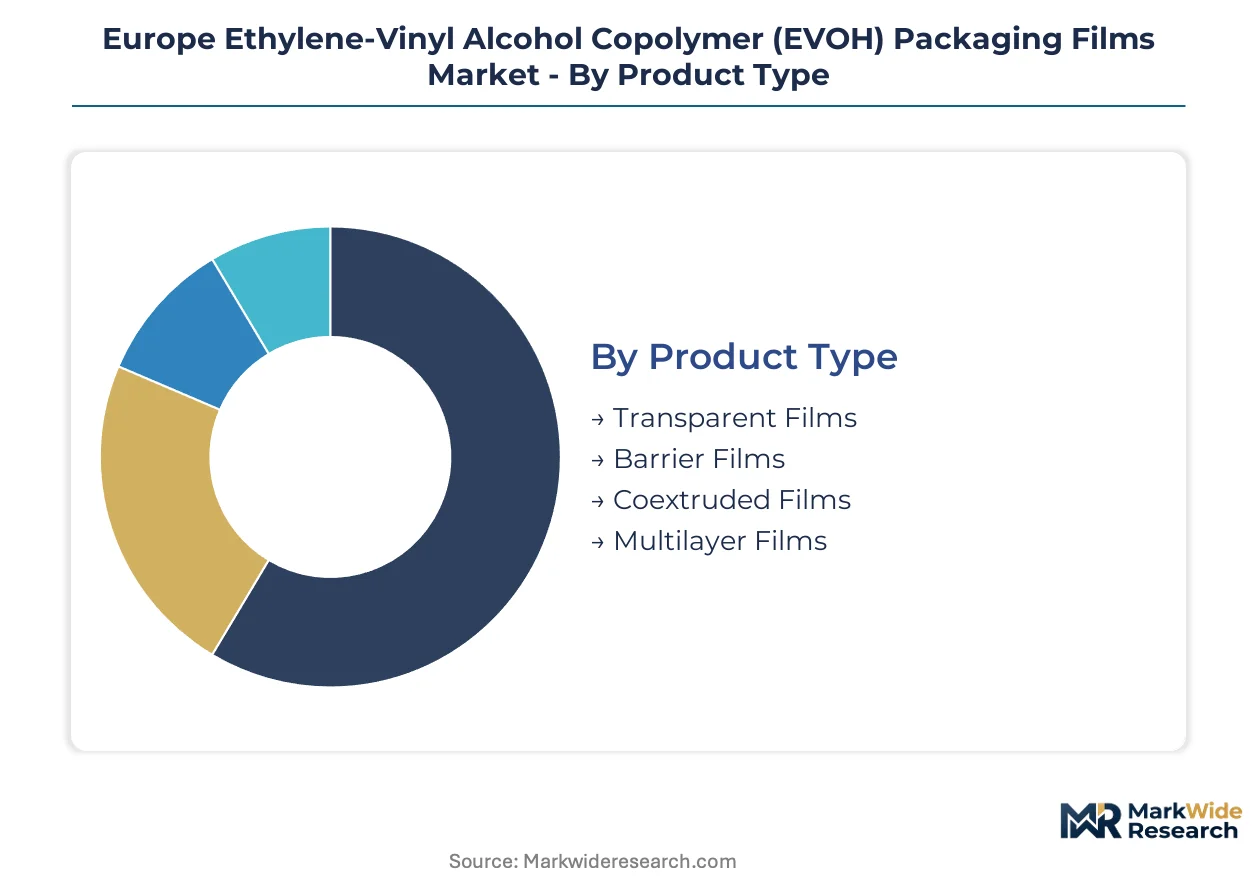
EVOH packaging films fragment across technical specifications that dictate coextrusion complexity and end-use compliance requirements. Each segmentation dimension carries distinct margin profiles and regulatory exposure across European converting networks.
Product Type:
Capital intensity escalates with layer complexity, as multiline coextrusion assets require seven- to nine-layer blown film dies that concentrate in Germany and Austria.
- Transparent Films:Single-layer or low-complexity constructions prioritize optical clarity for retail display applications. German meat processors specify these grades for modified-atmosphere trays where shelf visibility drives purchase decisions alongside oxygen barrier performance.
- Barrier Films:Oxygen transmission rates below 0.1 cc/m²/day at standard conditions define this category's technical threshold. Retort pouch applications across France absorb specialized grades where hydroxyl-rich EVOH backbones prevent oxidative degradation during aggressive thermal processing.
- Coextruded Films:Polyolefin tie-layer integration enables mono-material recyclable streams compatible with European mechanical sorting infrastructure.
- Multilayer Films:Legacy nylon-EVOH-polyethylene laminates face PPWR compliance pressure as ECHA substance evaluation protocols extend adhesive validation timelines.
Barrier films absorb the bulk of installed capacity; coextruded films are expanding most quickly.
Application:
Regulatory validation cycles vary dramatically, with pharmaceutical specifications locking in film architectures for extended periods while food packaging pivots rapidly toward recyclability mandates.
- Food Packaging:Processed meat and dairy supply chains across Germany and France constitute the primary demand vector. Extended producer responsibility fee modulation in France pulls EVOH grades into redesigned polyethylene streams that Citeo recognizes as recyclable.
- Pharmaceutical Packaging:EMA stability requirements for moisture-sensitive drug formulations favor EVOH's dual-barrier properties. Blister film specifications in Germany's pharmaceutical corridor near Frankfurt demand documented oxygen and water vapor transmission validation.
- Cosmetic Packaging:Premium skincare brands in Italy specify high-clarity barrier constructions for active-ingredient protection.
- Industrial Packaging:Chemical resistance specifications concentrate in Benelux petrochemical handling applications.
Food packaging commands the dominant revenue share; pharmaceutical packaging shows the steepest expansion trajectory as stability regulations tighten.
Thickness:
Material efficiency targets and downgauging imperatives are compressing average caliper specifications while preserving barrier performance through resin grade optimization.
- Below 25 Micron:Ultrathin EVOH cores in mono-material polyethylene structures represent the technical frontier. Dutch retail chain specifications now mandate sub-25-micron barrier layers that mechanical recycling infrastructure can process without delamination penalties.
- 25-50 Micron:Standard thermoforming webs for modified-atmosphere meat trays balance draw ratio performance against material cost. Germany's Rhine-Ruhr converting cluster processes substantial volumes in this range for pan-European protein brands.
- 50-100 Micron:Deep-draw pharmaceutical blister applications and industrial chemical containment specify this mid-range.
- Above 100 Micron:Heavy-duty retort and aseptic packaging for institutional food service retains niche demand.
The 25-50 micron band holds the majority of active capacity; below-25-micron grades are gaining share fastest as downgauging accelerates.
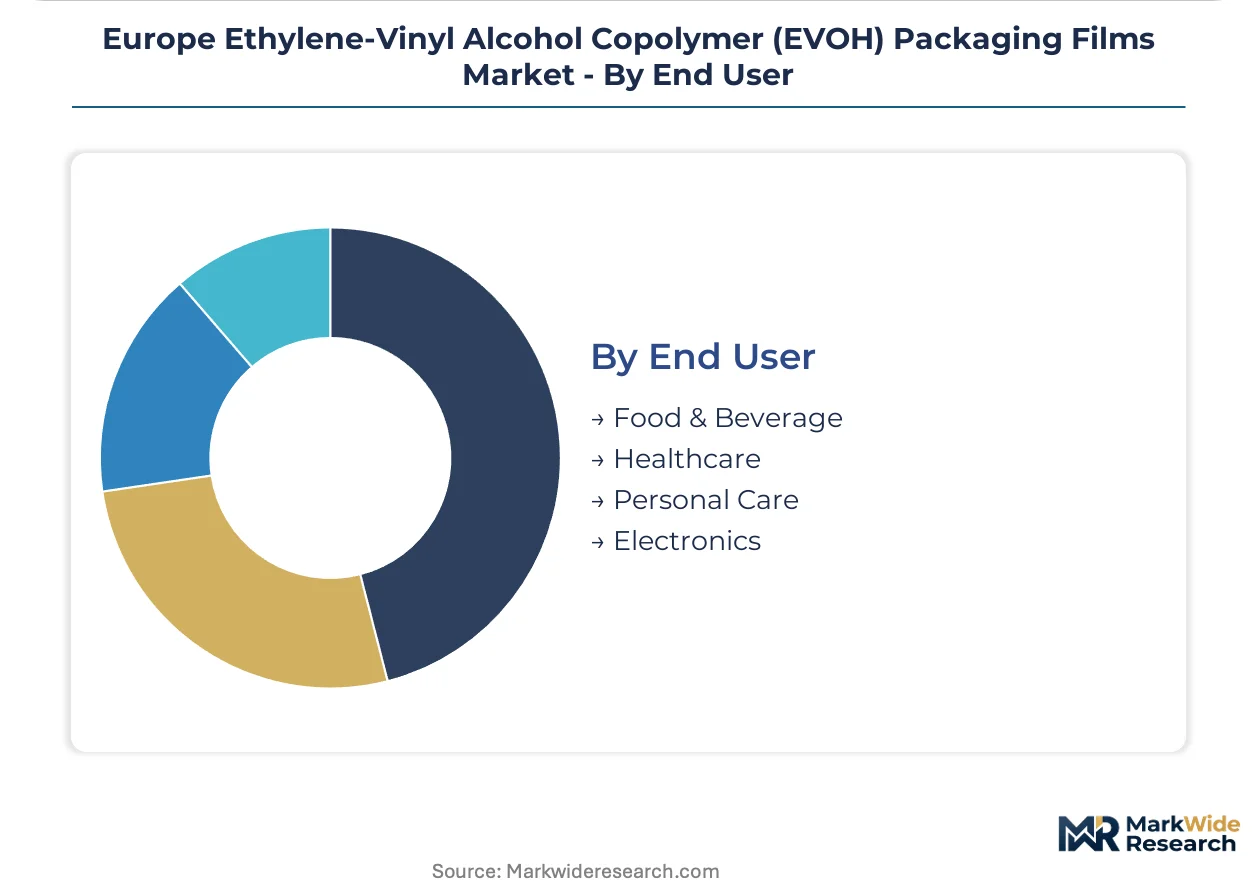
End User:
Procurement sophistication diverges sharply, with healthcare and electronics buyers imposing qualification protocols that extend supplier onboarding timelines versus food sector agility.
- Food & Beverage:Pan-European retailers compress supplier qualification from twenty-four months to twelve months for critical applications. Brand owner technical audits in France now require documented recyclability pathways before contract award.
- Healthcare:EMA and national competent authority oversight creates specification stickiness that protects incumbent film architectures. German hospital supply chains prioritize validated barrier performance over cost minimization.
- Personal Care:Premium cosmetic brands in Spain and Italy drive demand for high-aesthetic barrier constructions.
- Electronics:Moisture-sensitive component packaging concentrates in Eastern European manufacturing corridors.
Food and beverage absorbs the bulk of volume; healthcare is climbing the fastest as stability regulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and French food processors absorb the dominant share of EVOH film volumes, with the Rhine-Ruhr corridor and Greater Paris basin functioning as the twin demand poles. Extended producer responsibility fee modulation and modified-atmosphere packaging specifications pull technical grades toward these markets. REACH compliance and PPWR recyclability verification create divergent procurement timelines across member states.
Germany
Modified-atmosphere meat packaging specifications from pan-European protein brands concentrate demand in the Rhine-Ruhr converting cluster. The national packaging regulator enforces differentiated fee structures that reward higher recycled content in film constructions. Coextrusion specialists in Düsseldorf and Cologne maintain seven- to nine-layer blown film capacity for thermoforming webs serving dairy and processed meat supply chains.
France
Citeo's extended producer responsibility scheme modulates fees to favor high-barrier recyclable films, pulling EVOH grades into redesigned polyethylene streams. EMA stability requirements for pharmaceutical blister films sustain demand in the Greater Paris pharmaceutical corridor. Converters near Lyon and Strasbourg pilot ultrathin EVOH cores compatible with mechanical recycling infrastructure.
Italy
Premium cosmetic brands in Lombardy and Emilia-Romagna specify high-clarity barrier constructions for active-ingredient protection in skincare packaging. ANSM oversight of pharmaceutical packaging materials extends validation cycles for film specifications. The Northern Italian packaging belt around Milan and Bologna processes growing volumes of coextruded films for personal care applications.
Netherlands
Dutch retail chains mandate sub-25-micron barrier layers that mechanical sorting infrastructure can process without delamination penalties. The country's advanced waste management infrastructure enables rapid piloting of mono-material recyclable structures. Converters in the Randstad region collaborate with brand owners to compress supplier qualification cycles from twenty-four months to twelve months.
Spain
Mediterranean processed food markets lag Northern Europe in high-barrier adoption, presenting volume expansion potential for EVOH film suppliers. The national implementation of EU Packaging and Packaging Waste Regulation creates compliance timelines that lag Germany and France by twelve to eighteen months. Converters in Catalonia and Madrid develop coextrusion capabilities to serve emerging demand from Iberian meat processors.
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market Competitive Landscape
German and Austrian producers anchor one tier; Japanese and Korean resin specialists hold captive supply advantages through import-dependent relationships. The vendor base concentrates among integrated film converters with in-house coextrusion assets and regional resin distributors serving smaller thermoforming operations. Three archetypes dominate: integrated multinational packaging groups with circular-economy mandates, captive resin suppliers with deep barrier-grade specialization, and independent converters competing on specification turnaround. Capacity expansion in mono-material recyclable structures and strategic partnerships for digital watermarking integration represent the dominant competitive vectors.
Within the integrated multinational tier, Mondi plc and Amcor plc exemplify scale-driven positions that span paper and film operations across Central European converting networks. Kuraray Europe GmbH occupies a specialist position as a captive resin supplier with concentrated expertise in oxygen-barrier grades. Arkema sits within the high-performance polymer extension archetype, translating materials science capabilities into multilayer structures. These three anchors demonstrate how geographic proximity to brand owners, backward integration into resin supply, and compliance with emerging PPWR verification protocols define competitive positioning.
| Leading Market Players |
|---|
| Mondi plc |
| Arkema |
| Kuraray Europe GmbH |
| Innovia Films Ltd |
| Schur Flexibles |
| Nippon Gohsei (UK) |
| Amcor plc |
| Taghleef Industries LLC |
| KUREHA CORPORATION |
| Others |
Supply & Pricing Matrix
Pan-European protein brand procurement teams concentrate sufficient volume to command contract-based long-term offtake structures that compress spot-market premiums for EVOH film converters. Their consolidated purchasing power shapes pricing power distribution across the Rhine-Ruhr converting cluster.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to rush orders from German meat processors facing modified-atmosphere packaging line disruptions. Three-tier pricing structure across premium, standard, and economy levels separates certified recyclable grades from legacy multilayer constructions. Pricing pressure stems from ethylene feedstock volatility transmitted through naphtha-derived resin costs. Small thermoforming operations in Spain exhibit highest price sensitivity; pharmaceutical blister film buyers in Germany prioritize validated barrier performance over unit cost minimization.
Supply Chain Analysis
Regional distribution centers in Düsseldorf, Lyon, and Milan orchestrate hub-and-spoke patterns that position coextruded film inventory within four-hour trucking radius of major converting operations. Manufacturing gravity centers on Germany, Austria, and Japan, with captive resin supply chains anchored in East Asia creating import dependency for European converters. Raw material flows draw from ethylene crackers in Rotterdam and Antwerp, vinyl alcohol monomer facilities in Japan, and specialty adhesive suppliers in Germany. Single-source vulnerability concentrates in Kuraray's Soarnol resin supply. Distribution runs through integrated multinational packaging groups and independent converters serving regional thermoforming specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation erects a cost-of-compliance moat that rewards early recyclability certification investments while penalizing laggards with extended producer responsibility fee modulation.
For Market Incumbents: To counter Asian resin concentration and captive supply chain leverage, accelerate backward integration into adhesive tie-layer formulation capabilities and expand coextrusion capacity in the Rhine-Ruhr corridor to compress specification turnaround times for pan-European protein brands. For New Entrants and Emerging Players: Capture underpenetrated Mediterranean processed meat markets in Spain and Italy where EVOH adoption lags Northern Europe by twelve to eighteen months. Target pharmaceutical blister film specifications in the Greater Paris corridor where EMA stability requirements protect incumbent architectures. Pursue digital watermarking integration partnerships to enable AI-driven sorting infrastructure traceability. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent converters with seven- to nine-layer blown film die assets in Germany and Austria amid coextrusion engineering scarcity. Long-term viability over a five-to-ten-year window hinges on mono-material recyclable structure certification. Monitor PPWR harmonized recyclability testing protocol implementation timelines as the critical inflection signal for film architecture economic viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Formulation | REACH-compliant tie-layer chemistries accelerate PPWR verification timelines for coextruded structures. |
| Mono-Material Recyclable Structure Certification | Citeo fee modulation rewards certified polyethylene-EVOH streams in France's extended producer responsibility scheme. |
| Digital Watermarking Integration Partnership | AI-driven sorting infrastructure at Dutch mechanical recycling plants enables traceable EVOH identification. |
| Coextrusion Capacity Expansion in Rhine-Ruhr | Proximity to German meat processors reduces logistics costs and specification turnaround times. |
| Pharmaceutical Blister Film Validation Investment | EMA stability requirements in Frankfurt's pharmaceutical corridor lock in dual-barrier specifications. |
Research Methodology
Independent corroboration across plant managers at German coextrusion facilities, procurement leads at pan-European protein brands, distribution channel partners in the Benelux region, and technical R&D directors at adhesive suppliers underwrites the qualitative findings. Primary interviews with these stakeholders combined with secondary validation from customs and trade data, Cefic chemical industry reports, SEC 10-K filings of listed packaging groups, and ECHA substance evaluation protocols. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Rate-of-change decomposition across product type, application, thickness tier, and end-user vertical generates segment-level projections over the analysis window. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and technology substitution curves. Modeled inputs include ethylene feedstock cost indices, PPWR implementation timelines across member states, and coextrusion asset utilization rates in the Rhine-Ruhr cluster.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PPWR harmonization delays, REACH substance evaluation protocol extensions, and Asian resin supply disruptions. Outputs reflect documented assumptions around regulatory implementation timelines and feedstock cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyethylene Film Market
Poly film
PCR Lidding Films Market
Poly film
MDO-PE Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Thermoforming Films Market
Poly film
Recyclable Lidding Films Market
Poly film
Biaxially Oriented Polypropylene (BOPP) Films Market
Poly film
Timber Wrap Films Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market
Poly film
Tube Laminating Films Market
Poly film
Silicone Release Films Market
Poly film
Polyethylene Cast Film Market
Poly film
High Density Polyethylene Film Market
Poly film
PET Lidding Films Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
Soft Touch Film Market