
 Polyimide Films and Tapes Market | 2026-2036
Polyimide Films and Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Polyimide Films and Tapes Market Analytics
South Korea is tilting polyimide capacity toward electronics-grade output to serve domestic display and semiconductor packaging clusters. DuPont leverages its fluorinated polyimide patent estate to sustain premium positioning in aerospace insulation laminates. Kaneka Corporation anchors Asian supply through captive dianhydride monomer production and dedicated film casting lines.
Polyimide films and tapes comprise aromatic heterocyclic polymer substrates synthesized from pyromellitic dianhydride and aromatic diamines, typically processed by thermal imidization to achieve continuous service temperatures above 300°C for electrical insulation and dimensional stability under thermal stress. Flexible films lead value capture in flexible printed circuit board substrates where ultra-low coefficient of thermal expansion grades command price premiums over standard Kapton-equivalent products. Adhesive tapes compete on modified silicone and acrylic chemistries for bonding dissimilar materials in automotive power electronics, while rigid films occupy niche medical device catheter shaft applications requiring pushability and torque response.
EPA regulates perfluorinated compound emissions from polyimide precursor manufacturing under TSCA Section 5 premanufacture notification requirements, pushing producers toward non-fluorinated dianhydride alternatives. REACH restricts certain aromatic amine intermediates under SVHC candidate listing, compelling reformulation of legacy polyimide resin systems for European market access. Stakeholders must monitor evolving halogen-free flame retardancy mandates from IEC and UL as electric vehicle battery module insulation specifications tighten thermal runaway containment standards.
Market Dynamics
Polyimide film supply chains are compressing around captive dianhydride production as aromatic monomer costs swing with crude-derived feedstock volatility, forcing converters to secure backward integration or long-term offtake agreements to stabilize input economics.
Growth Catalysts
- Flexible PCB substrate demand:Electronics manufacturers in South Korea and Taiwan are expanding roll-to-roll processing capacity for ultra-thin polyimide films serving foldable display hinge circuits and chip-scale packaging substrates.
- REACH SVHC disclosure mandates:ECHA's candidate list expansion for aromatic amines is accelerating reformulation toward halogen-free, low-CTE grades that command specification premiums in European aerospace wiring harness applications.
- Electric vehicle battery module insulation:IEC thermal runaway containment standards are mandating polyimide-barrier composites between pouch cells, creating specification pull from automotive tier-one laminators in Germany and Japan.
Market Restraints
- PMDA monomer supply concentration:Pyromellitic dianhydride production clusters in China's Shandong province and Japan's Kansai region, exposing film casters to logistics disruptions and regional environmental enforcement actions.
- Fluorinated polyimide emission controls:EPA TSCA Section 5 premanufacture notification requirements for perfluorinated dianhydride alternatives are extending qualification timelines and raising R&D overhead for aerospace-grade formulations.
- Polyetherimide substitution in medical tubing:SABIC's Ultem resins are displacing rigid polyimide films in catheter shaft applications where pushability requirements have relaxed with minimally invasive procedure technique evolution.
Strategic Opportunities
- Indian electronics manufacturing clusters:PLI scheme incentives for semiconductor packaging and display fab investments are creating first-mover advantage for film suppliers establishing slitting and metallization operations in Gujarat and Tamil Nadu.
- 5G mmWave antenna substrate convergence:Low-dielectric-loss polyimide-copper laminates are hybridizing with liquid crystal polymer films in base station and smartphone antenna modules, opening specification windows for hybrid material suppliers.
- EU Green Deal circularity mandates:Ecodesign requirements for electronics recyclability are favoring thermoplastic polyimide alternatives to thermoset films in consumer device flexible circuits, rewarding reformulation capabilities.
Industry Challenges
- Specialized polymer processing talent scarcity:Thermal imidization reactor operation and solvent casting line optimization require expertise concentrated among aging workforces in Japan and the US, constraining capacity expansion velocity.
- UL 94 V-0 recertification timelines:Reformulated halogen-free flame-retardant grades face 12-18 month qualification cycles for electric vehicle battery applications, compressing product launch windows against fast-moving OEM specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyimide Films and Tapes Market |
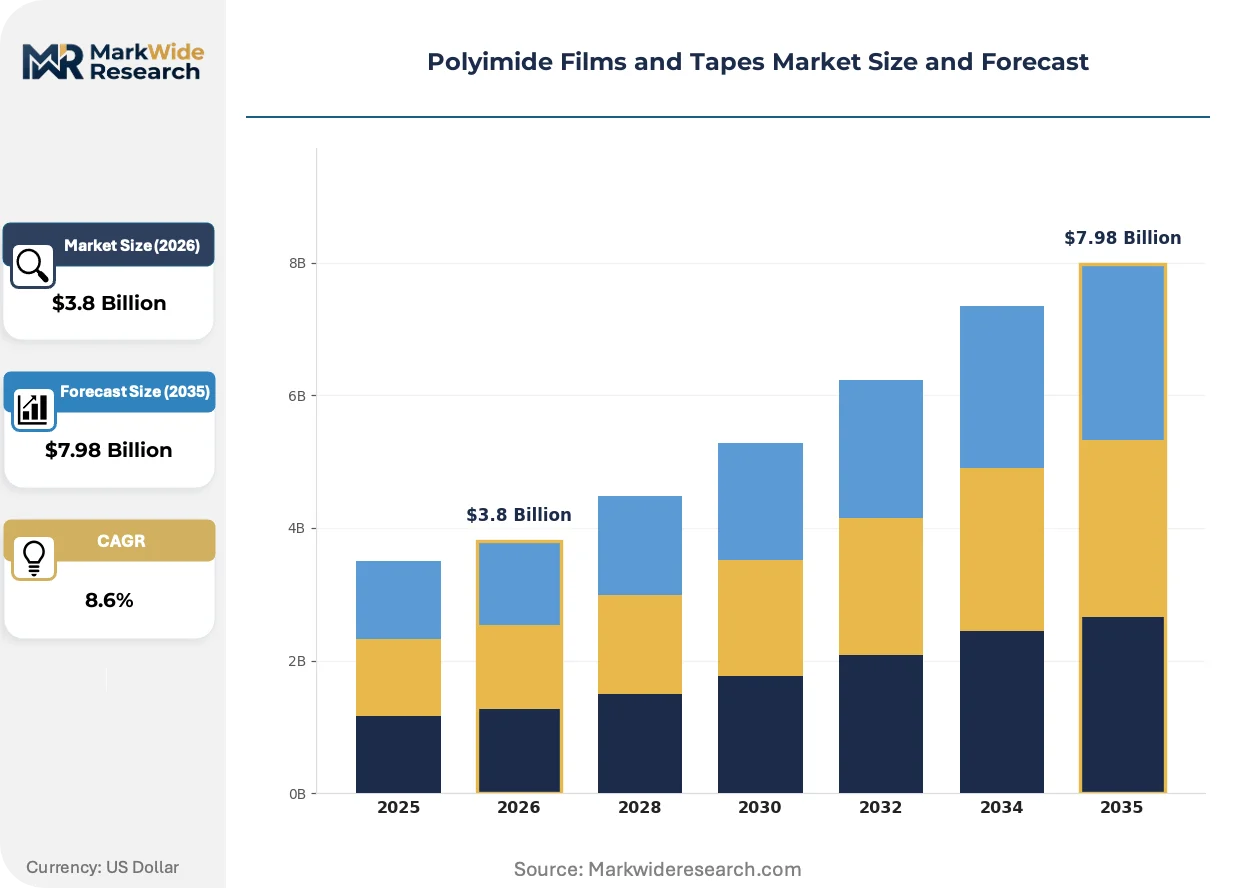
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Rigid Films, Adhesive Tapes, Coated Tapes End User: Aerospace, Electronics, Automotive, Medical Devices Application: Insulation, Component Support, Thermal Barriers, Circuit Boards Technology: Imide Synthesis, Thermal Processing, Co-extrusion, Adhesive Bonding |
| Companies Covered | DuPont, PI Advanced Materials Co., Ltd., Kaneka Corporation, Ube Industries Ltd., Toray Industries, Inc., SKC Kolon PI, Taimide Tech. Inc., Saint-Gobain, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyimide Films and Tapes Market Evolving Landscape
Material science convergence is dissolving traditional boundaries between high-performance polymer families as end-users demand substrates that simultaneously satisfy thermal, mechanical, and electrical performance thresholds previously served by distinct material categories.
Non-fluorinated dianhydride synthesis routes are hybridizing with conventional PMDA-based chemistry to reduce perfluorinated compound emissions while preserving dielectric performance. Aerospace wire insulation suppliers in France and Germany are piloting these formulations for next-generation aircraft harnesses. The structural consequence is a bifurcation in patent estates between fluorinated incumbent positions and open innovation around bio-derived dianhydride feedstocks.
REACH authorization requirements for certain aromatic amine process intermediates are compelling resin formulators to document full substance volume tracking through the supply chain. Film converters serving European medical device manufacturers are absorbing compliance costs through dedicated batch segregation and enhanced analytical testing protocols. Small-batch specialty grades for implantable device applications face the steepest cost inflation as ECHA scrutiny intensifies.
Specification consolidation among automotive battery module integrators is compressing supplier qualification cycles from 24 months toward 14 months. Tier-one laminators in South Korea are unbundling material certification from finished component validation, allowing parallel-track approval of new polyimide grades. This behavioral shift is most visible in the Hyundai-Kia supply chain, where thermal barrier specification updates now outpace traditional automotive material approval cadences.
Polyimide Films and Tapes Market Segmentation
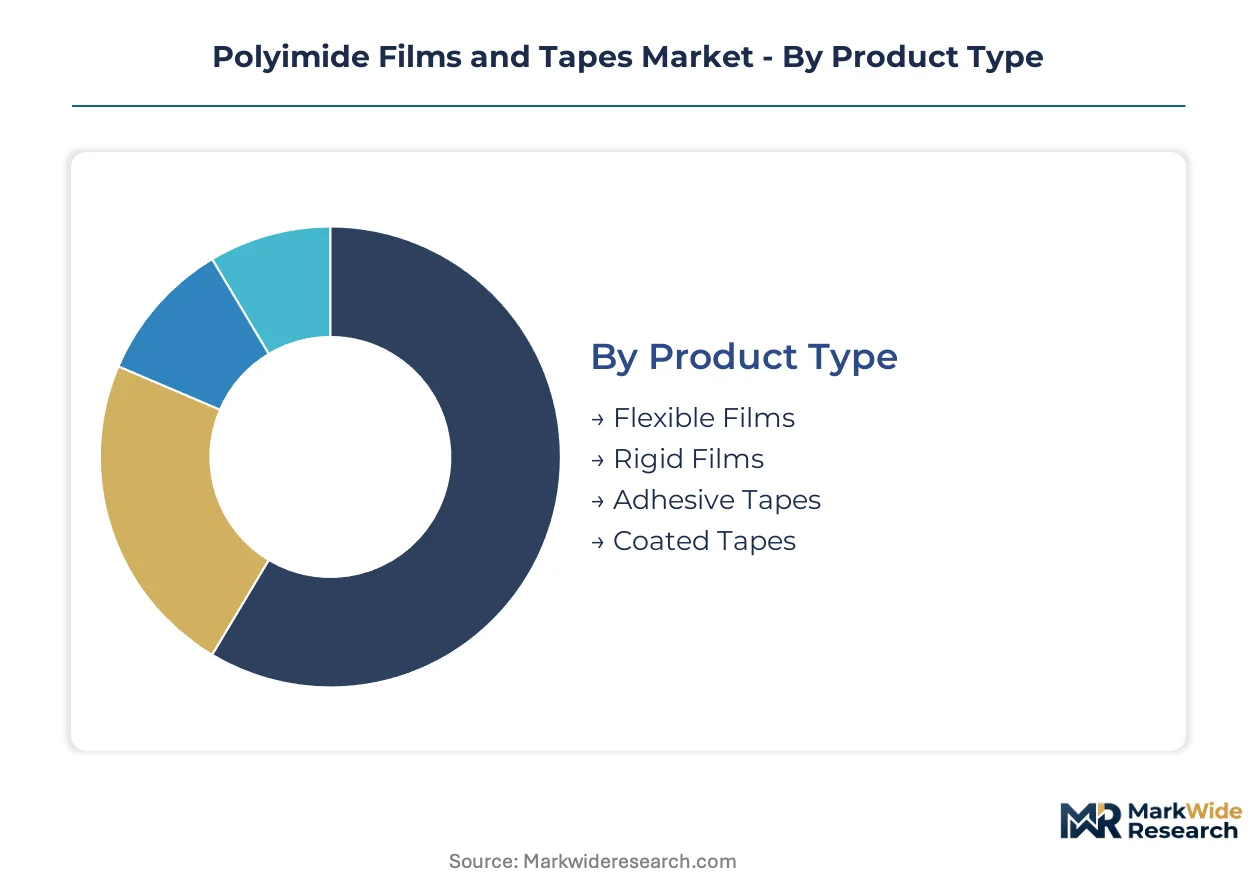
Polyimide film and tape specifications fragment across thermal, mechanical, and electrical performance thresholds. Each segment category carries distinct margin profiles and qualification barriers that reshape competitive positioning.
Product Type:
Cost tier differentiation separates commodity-grade substrates from specification-critical formulations where thermal stability and dimensional precision command premium multiples.
- Flexible Films:Ultra-thin aromatic polyimide substrates processed through continuous thermal imidization achieve thicknesses below 25 microns for dynamic flexing applications. Electronics manufacturers in South Korea absorb the majority of high-volume output for foldable display hinge circuits and chip-scale packaging substrates where low-CTE grades reduce solder joint fatigue.
- Adhesive Tapes:Modified silicone and acrylic pressure-sensitive adhesives laminated to polyimide carriers bond dissimilar materials across thermal expansion mismatches. Automotive power electronics module assemblers in Germany specify these grades for die-attach and thermal interface applications where outgassing control meets IEC 61215 reliability standards.
- Rigid Films:Higher modulus formulations processed through solvent casting and extended thermal cycling deliver pushability and torque transmission for catheter shaft applications. Medical device OEMs have relaxed rigid film specifications as minimally invasive techniques evolve toward softer access platforms.
- Coated Tapes:Metallized or ceramic-filled surface treatments modify surface energy and thermal emissivity for specialized bonding and heat-spreading functions. Aerospace wire harness suppliers in France pilot these formulations for next-generation aircraft electrical distribution systems.
Flexible films command the established base. The steepest expansion runs through adhesive tapes serving electric vehicle battery thermal management.
End User:
Application maturity and specification stringency divide end-use sectors between long-cycle aerospace qualifications and fast-moving consumer electronics ramps.
- Electronics:Flexible printed circuit board fabricators and semiconductor packaging houses consume the majority of ultra-thin film output. Taiwan and South Korea concentrate roll-to-roll metallization capacity where 5-micron copper cladding on 12.5-micron polyimide enables high-density interconnect substrates.
- Aerospace:Wire insulation and thermal blanket applications demand 50,000-hour thermal aging data and full traceability through AS9100 quality systems. Suppliers in Japan and the United States maintain locked-in positions through decades-long OEM qualification archives.
- Automotive:Battery module insulation and inverter substrate specifications are compressing from 24-month to 14-month approval cycles. Tier-one laminators in South Korea unbundle material certification from component validation to accelerate thermal barrier adoption.
- Medical Devices:Implantable and diagnostic applications face the steepest REACH compliance cost inflation as ECHA scrutiny intensifies for aromatic amine process residuals. Batch segregation and enhanced analytical testing protocols absorb margin at small-batch specialty grades.
Aerospace commands the established base. The steepest expansion runs through automotive as thermal runaway containment standards proliferate.
Application:
Functional role within the end-use assembly determines specification tier and pricing band more than raw material composition alone.
- Insulation:Electrical isolation in high-temperature environments requires dielectric strength above 3 kV/mil and tracking resistance to IEC 60112 standards. Motor and generator OEMs in Japan specify these grades for traction motor slot liners in hybrid vehicle platforms.
- Thermal Barriers:Inter-cell insulation in lithium-ion battery modules must contain thermal runaway propagation for 300 seconds per UN ECE R100 and GTR 20 protocols. Hyundai-Kia supply chain updates now outpace traditional automotive material approval cadences.
- Circuit Boards:Flexible copper-clad laminates for dynamic flexing applications balance etch precision against adhesive flow control. Roll-to-roll processing lines in Taiwan achieve pattern resolution below 20 microns for smartphone antenna modules.
- Component Support:Dimensional stability under mechanical load and thermal cycling protects sensitive semiconductor die during assembly and operation. Chip-scale packaging houses in South Korea drive consumption of ultra-low-CTE grades.
Insulation commands the established base. The steepest expansion runs through thermal barriers as electric vehicle production scales.
Technology:
Process capability and capital intensity separate incumbent producers from new entrants seeking specification entry points.
- Thermal Processing:Continuous belt thermal imidization reactors operating above 400°C convert polyamic acid precursor to fully cyclized polyimide. Japanese and US producers concentrate operational expertise among aging workforces, constraining capacity expansion velocity.
- Imide Synthesis:Dianhydride-diamine polycondensation chemistry determines final polymer architecture and property balance. Non-fluorinated dianhydride routes are hybridizing with conventional PMDA-based systems to reduce perfluorinated compound emissions.
- Co-extrusion:Multi-layer film structures combine polyimide core layers with thermoplastic skins for thermoformability and recyclability. EU Green Deal circularity mandates are favoring these architectures in consumer electronics applications.
- Adhesive Bonding:Silicone and acrylic pressure-sensitive adhesive lamination requires solvent removal and crosslinking control to meet outgassing specifications. Aerospace wire insulation suppliers in Germany pilot halogen-free formulations for next-generation harnesses.
Thermal processing commands the established base. The steepest expansion runs through co-extrusion as recyclability specifications harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA regulates perfluorinated compound emissions from polyimide precursor manufacturing under TSCA Section 5, pushing producers toward non-fluorinated dianhydride alternatives while REACH compliance in Europe tightens chemical disclosure requirements for resin formulations.
United States
Aerospace wire insulation manufacturers in Connecticut and Ohio absorb fluorinated polyimide grades for next-generation aircraft harnesses. EPA TSCA Section 5 premanufacture notification requirements extend qualification timelines for perfluorinated dianhydride alternatives. DuPont leverages its fluorinated polyimide patent estate to sustain premium positioning in aerospace insulation laminates from its Delaware-based operations.
South Korea
Electronics manufacturers drive accelerating consumption of high-temperature flexible substrates for foldable display hinge circuits. MFDS oversees chemical safety assessments for aromatic amine residuals in medical-grade formulations. Seoul Capital Area clusters concentrate roll-to-roll metallization capacity where 5-micron copper cladding on ultra-thin polyimide enables high-density interconnect substrates.
China
Domestic expansion of flexible printed circuit board fabrication concentrates demand through captive dianhydride production. MEE enforces environmental compliance on pyromellitic dianhydride manufacturing clusters in Shandong province. Yangtze River Delta fabricators absorb the majority of standard-grade film output for consumer electronics laminates.
Germany
Automotive tier-one laminators specify polyimide-barrier composites between pouch cells for thermal runaway containment. KBA incorporates IEC thermal runaway standards into vehicle type-approval protocols for electric vehicle battery modules. Bavaria-based wire harness suppliers pilot halogen-free formulations for next-generation aerospace electrical distribution systems.
Japan
Chip-scale packaging houses drive consumption of ultra-low-CTE grades for semiconductor substrate applications. METI coordinates domestic supply chain resilience initiatives for aromatic monomer feedstocks. Kansai region producers maintain locked-in positions through decades-long OEM qualification archives in aerospace wire insulation.
Polyimide Films and Tapes Market Competitive Landscape
Vertically integrated resin-to-film producers and specialized tape converters split the market between captive monomer economics and specification-critical formulation expertise. Japanese and US incumbents concentrate operational knowledge among aging workforces, constraining capacity expansion velocity. Three archetypes dominate: dianhydride-backward-integrated resin houses, dedicated film casting specialists, and adhesive-lamination converters. Competitive moves center on long-term offtake agreements for aromatic monomer supply and parallel-track material certification to compress automotive qualification cycles.
Within the vertically integrated tier, Kaneka Corporation anchors Asian supply through captive dianhydride monomer production, while DuPont occupies a position exemplifying fluorinated formulation patent estates. Among Korean electronics-grade specialists, SKC Kolon PI represents the roll-to-roll metallization convergence archetype serving display and semiconductor packaging clusters.
| Leading Market Players |
|---|
| DuPont |
| PI Advanced Materials Co., Ltd. |
| Kaneka Corporation |
| Ube Industries Ltd. |
| Toray Industries, Inc. |
| SKC Kolon PI |
| Taimide Tech. Inc. |
| Saint-Gobain |
| 3M |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Busan container freight corridors transmit cost volatility from pyromellitic dianhydride production clusters directly into film caster margins, amplifying price spreads between captive-monomer integrated producers and converter-dependent competitors while compressing standard-grade polyimide pricing power.
Pricing Analysis
Geographic price spreads widen between Japanese aerospace-grade formulations and Chinese standard-grade output. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified aerospace insulation from automotive thermal barrier grades and consumer electronics laminates. Cost compression in standard-grade flexible films intensifies as Yangtze River Delta fabricators expand roll-to-roll capacity. Automotive battery module assemblers exhibit lowest price sensitivity due to thermal runaway containment specification stringency, while consumer electronics converters negotiate aggressively on volume.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan-based flexible copper-clad laminate specialists and South Korean roll-to-roll metallization houses serving display and semiconductor packaging clusters. Raw material dependencies draw from pyromellitic dianhydride production in China's Shandong province and Japan's Kansai region, plus aromatic diamine intermediates subject to REACH SVHC scrutiny. Single-source vulnerability concentrates in PMDA monomer supply from environmental enforcement-exposed Chinese manufacturing zones. Distribution runs through captive film casting lines feeding directly to tier-one laminators, with limited spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across thermal, electrical, and mechanical performance thresholds creates defendable niche positions as electric vehicle battery module integrators compress qualification cycles and demand application-specific formulations.
For Market Incumbents: Pre-empt polyetherimide substitution in medical tubing by accelerating halogen-free, low-CTE grade development for retained catheter shaft specifications. Lock in backward integration through long-term offtake agreements with Shandong province PMDA producers before environmental enforcement tightens. Secure UL 94 V-0 recertification pipelines for automotive thermal barrier grades to outpace 14-month OEM approval cadences.
For New Entrants and Emerging Players: Build out slitting and metallization operations in Gujarat and Tamil Nadu to capture Indian PLI scheme semiconductor packaging demand before incumbent film suppliers establish local footprint. Target adhesive tape formulations for electric vehicle battery thermal interface applications where specification windows remain fluid and incumbent qualification archives carry less weight. Lead with halogen-free formulations to differentiate against legacy fluorinated polyimide positions.
For Investors and Strategic Acquirers: Specialist converters with captive dianhydride supply and established aerospace qualification archives represent the most defensible acquisition targets in a market where operational expertise concentrates among aging workforces. Long-term viability hinges on reformulation capabilities for REACH-compliant, non-fluorinated architectures. Watch for ECHA candidate list expansions affecting aromatic amine intermediates as inflection indicators forcing industry-wide resin system overhauls.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dianhydride Monomer | Captive PMDA supply insulates margins from Shandong environmental enforcement volatility. |
| Halogen-Free Formulation Development | ECHA SVHC scrutiny and IEC thermal runaway standards reward reformulation capabilities. |
| Parallel-Track Material Certification | Unbundled validation compresses automotive qualification cycles to match Hyundai-Kia specification updates. |
| Indian Manufacturing Footprint Expansion | PLI scheme incentives create first-mover advantage in Gujarat and Tamil Nadu clusters. |
| Co-Extrusion Technology Investment | EU Green Deal circularity mandates favor thermoplastic-skinned architectures for consumer electronics recyclability. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical company filings, and ECHA regulatory submissions. Primary interviews engaged film casting line operators, automotive tier-one laminator procurement leads, aerospace wire harness quality directors, and ECHA regulatory affairs consultants. Secondary validation drew from IEC standards documentation, UL certification databases, and national chemical industry association reports. Bottom-up capacity modeling triangulated against top-down end-use consumption estimates.
Forecast inputs include thermal processing capacity expansion timelines, REACH authorization pathway developments, and electric vehicle battery production ramp schedules across the analysis window. Segmentation dimensions encompass product type, end-use industry, application function, and technology platform. CAGRs derive from volume-demand elasticity modeling against substitution dynamics and regulatory compliance cost trajectories. Industry-specific inputs capture dianhydride monomer supply concentration risk and automotive qualification cycle compression effects.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed chemical conglomerates or accelerated fluorinated polyimide phase-outs would shift outcomes beyond modeled ranges. Quarterly review of ECHA candidate list publications, Shandong province environmental enforcement actions, and Hyundai-Kia thermal barrier specification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
France Plastic Packaging Films Market
Poly film
Polycarbonate Films Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Formable Films Market
Poly film
Polyolefin Films Market
Poly film
Twist Wrap Film Market
Poly film
Co Extruded Films Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
Tube Laminating Films Market
Poly film
Embossed Film Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
PVC Film for Medical Market
Poly film
Metallized Film Market
Poly film
China Plastic Packaging Film Market