
 Cleanroom Film and Bags Market | 2026-2036
Cleanroom Film and Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Cleanroom Film and Bags Market Analytics
Buyer concentration among contract semiconductor packaging houses is recalibrating procurement volumes for cleanroom films and bags. Tekni-Plex, Inc. leverages multi-layer coextrusion capabilities to serve pharmaceutical serialization requirements. Nelipak anchors European medical device packaging with controlled-environment film formats. Cleanroom Film & Bags (CFB) specializes in bespoke bag geometries for aerospace contamination control.
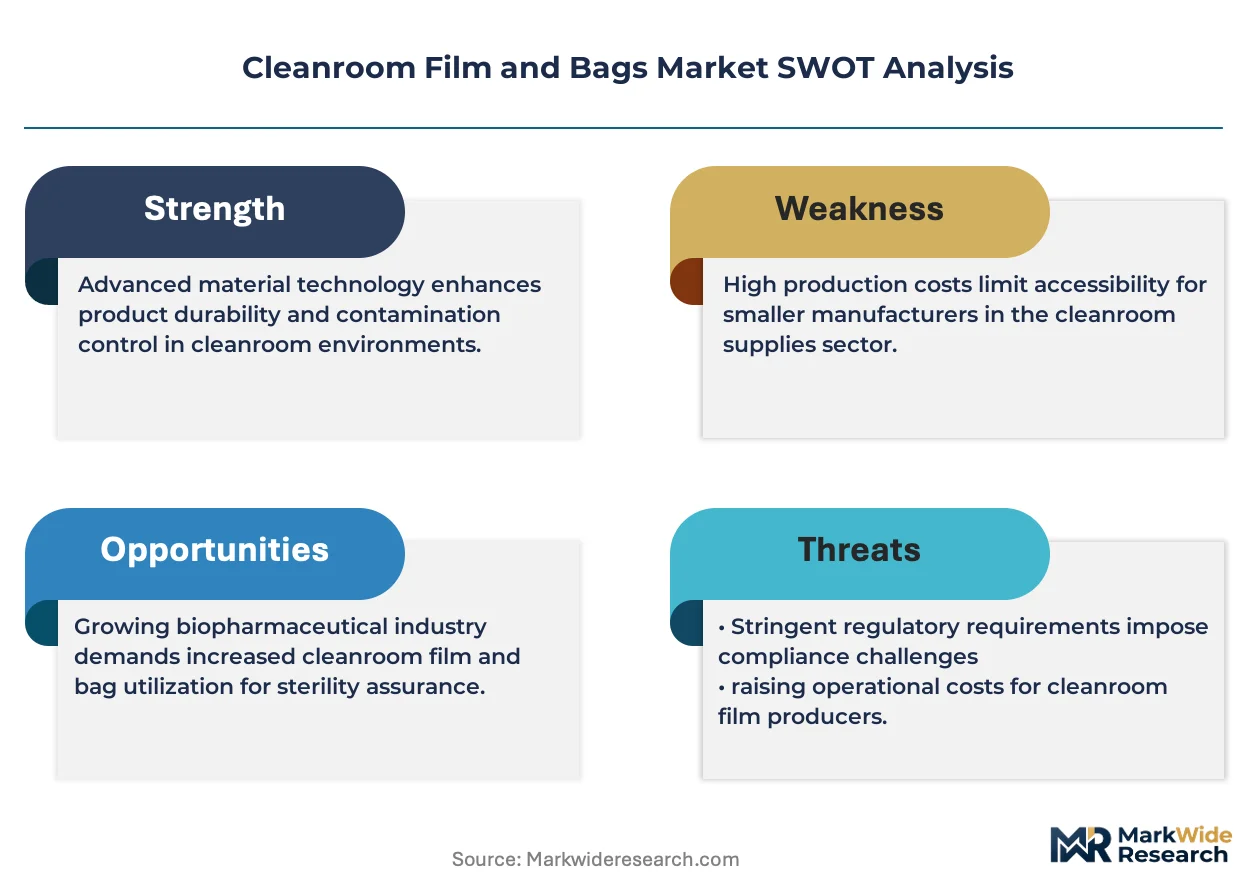
Cleanroom film and bags are engineered polymer barriers manufactured under ISO 14644-1 Class 5–8 conditions, typically extruded from low-density polyethylene or polypropylene with anti-static additives and sub-micron filtration compatibility, designed to maintain particulate-free environments for sensitive components and sterile products. Polyethylene formulations dominate volume due to cost scalability and chemical inertness, while polypropylene captures margin pools in autoclave-sterilizable pharmaceutical applications. Electronics and biotechnology applications are expanding fastest as wafer-level packaging and cell therapy production scale, whereas aerospace demand remains mature and cyclical.
FDA enforces 21 CFR Part 211 for pharmaceutical packaging integrity, while ISO 14644 governs cleanroom classification and testing protocols that directly specify film outgassing and particle-shedding thresholds. The EPA regulates volatile organic compound emissions from extrusion processes, shaping domestic manufacturing compliance costs. Stakeholders must monitor evolving EU MDR traceability requirements and dual carbon goals in China to anticipate material substitution timelines and regional sourcing reconfigurations.
Market Dynamics
Semiconductor packaging complexity in Taiwan and South Korea is forcing material upgrades across the cleanroom film supply base, as sub-micron particulate thresholds tighten and wafer-level packaging scales.
Growth Catalysts
- ISO 14644-1 Class 5 adoption:Semiconductor fabs in Hsinchu and Pyeongtaek are mandating stricter cleanroom classifications, pulling advanced multi-layer film formulations into volume production.
- Cell therapy manufacturing scale-up:Bioreactor-based autologous cell production in Massachusetts and North Carolina requires sterile barrier systems with validated particulate control.
- Dual carbon goals in China:MEE regulations on extrusion emissions are accelerating solvent-free coextrusion technology deployment among domestic suppliers.
Market Restraints
- Resin cost volatility:Low-density polyethylene feedstock prices fluctuate with naphtha cracking margins in the US Gulf Coast, compressing converter margins.
- East Asian supply concentration:Over 60% of Class 7-8 certified film extrusion capacity sits in Taiwan, South Korea, and coastal China, creating single-source risk.
- Autoclave compatibility limits:Standard polyethylene formulations cannot withstand 121°C steam sterilization cycles, restricting penetration into pharmaceutical parenteral packaging.
Strategic Opportunities
- Underpenetrated Indian pharmaceutical corridor:CDSCO serialization mandates for export-oriented injectables are creating first-mover openings for validated cleanroom bag suppliers near Hyderabad and Ahmedabad.
- EU MDR traceability requirements:Device manufacturers must implement lot-level digital tracking, favoring film converters with integrated printing and serialization capabilities.
- Aerospace contamination control:Satellite component cleanrooms in Colorado and Bavaria are specifying custom bag geometries for ion thruster assembly, a niche with limited incumbent competition.
Industry Challenges
- Cleanroom technician scarcity:ISO 14644 auditor certification programs in the US and Germany cannot match hiring velocity at expanding semiconductor packaging houses.
- Validation timeline compression:Pharmaceutical customers now demand 12-month film qualification cycles versus historical 24-month windows, straining quality documentation resources.
- Legacy ERP integration:Small and mid-sized converters struggle to connect batch-level manufacturing data with customer track-and-trace systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleanroom Film and Bags Market |
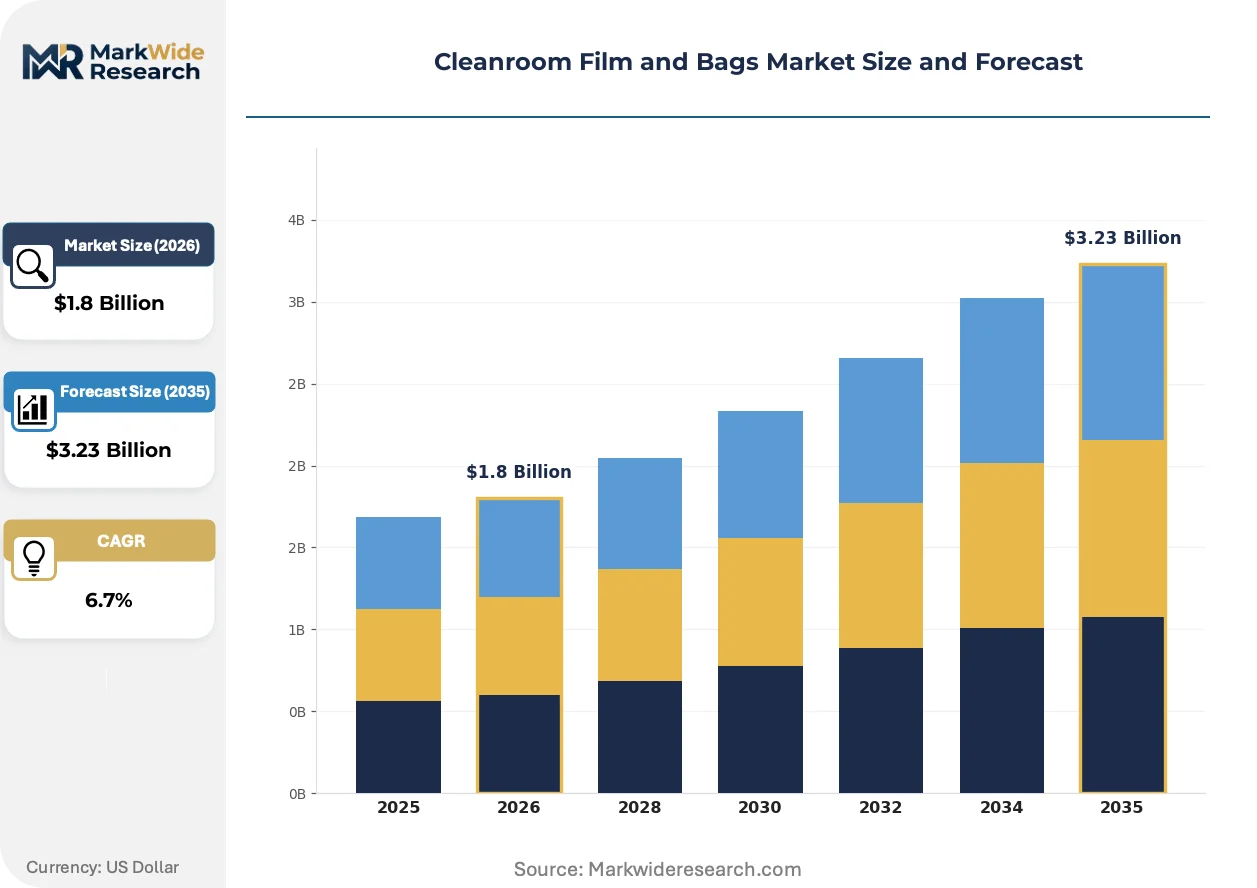
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Vinyl, Nylon Application: Pharmaceutical, Biotechnology, Electronics, Aerospace End User: Hospitals, Laboratories, Manufacturing, Research Facilities Thickness: Thin Film, Medium Film, Heavy Film, Ultra-Heavy Film |
| Companies Covered | Cleanroom Film & Bags (CFB), Tekni-Plex, Inc., AeroPackaging, Inc., Fruth Custom Packaging, Pristine Clean Bags, Nelipak, PPC Flex Company Inc, Degage Corp., Plitek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleanroom Film and Bags Market Evolving Landscape
Cleanroom film manufacturing is pivoting toward modular, specification-flexible production systems that can switch between semiconductor, pharmaceutical, and aerospace grades without line revalidation downtime.
Multi-layer coextrusion with in-line ionomer interlayers is modularizing how barrier properties are engineered into cleanroom bags. Semiconductor packaging houses in Taiwan are adopting these systems to customize oxygen and moisture transmission rates per wafer-level packaging protocol. The technology is compressing SKU proliferation costs while extending product lifecycles for film converters.
REACH restrictions on perfluorinated compounds are forcing European medical device manufacturers to reformulate anti-static additives in cleanroom films. ECHA substance evaluation timelines are accelerating substitution toward permanent static dissipative polymers. German and Swiss packaging converters are most affected, with some qualifying bio-based alternatives ahead of regulatory deadlines.
Consolidated procurement among contract semiconductor packaging houses is compressing supplier bases and extending master service agreements to 36-month terms. Direct film converter relationships are displacing distributor intermediaries in South Korea and Taiwan. The shift is most visible in Hsinchu Science Park, where TSMC-affiliated packaging vendors now source through qualified supplier lists rather than spot markets.
Cleanroom Film and Bags Market Segmentation
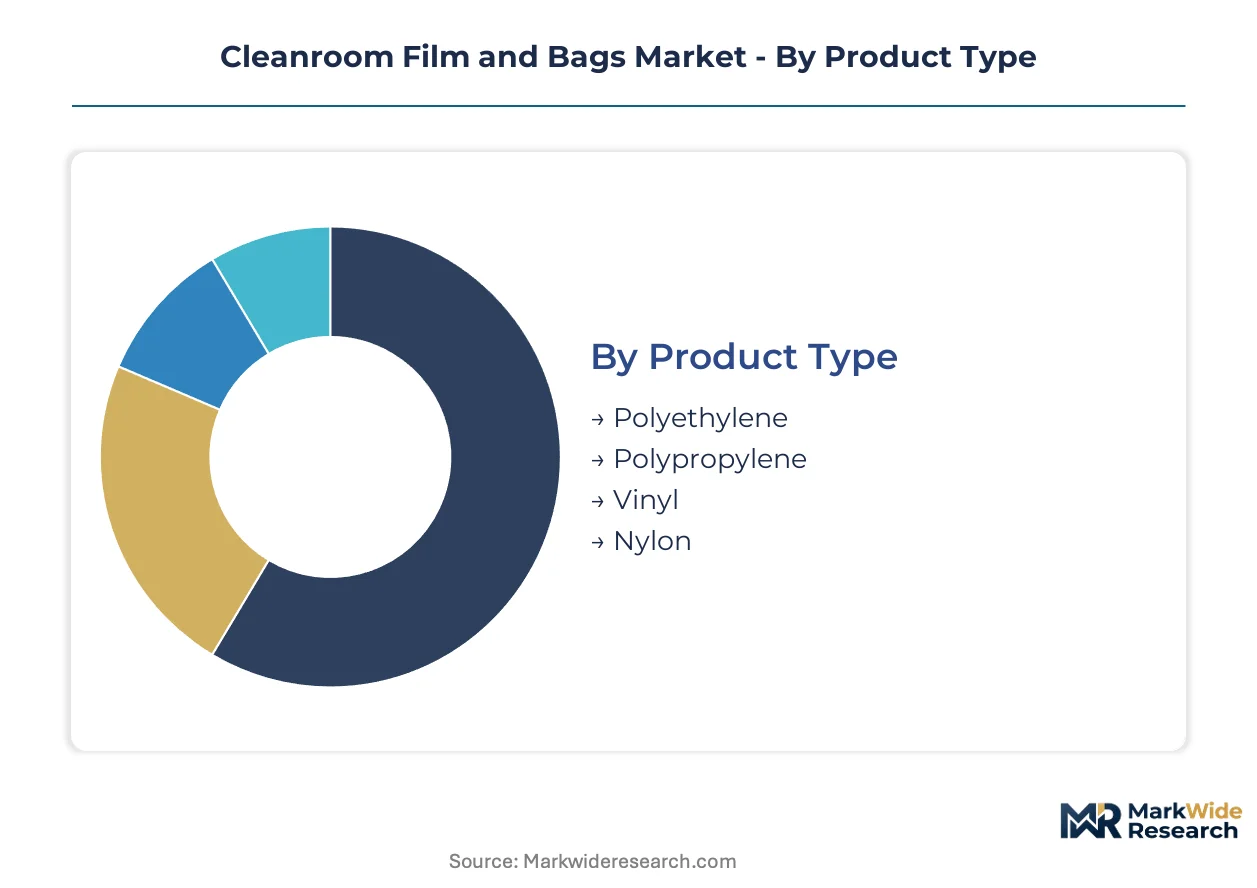
Cleanroom film specifications diverge sharply across end-use environments, with semiconductor fabs demanding sub-micron particulate control while pharmaceutical packaging prioritizes sterilization compatibility. Material selection and thickness calibration determine qualification timelines and procurement volumes in each vertical.
Product Type:
Upgrade cycles in East Asian semiconductor packaging are pulling advanced polymer formulations into volume production as ISO 14644-1 Class 5 adoption accelerates.
- Polyethylene:Low-density polyethylene dominates procurement volumes due to cost scalability and chemical inertness in electronics handling. Taiwanese wafer-level packaging houses specify multi-layer coextruded variants with ionomer interlayers for moisture barrier tuning.
- Polypropylene:Autoclave-sterilizable grades capture premium positioning in pharmaceutical parenteral packaging, withstanding 121°C steam cycles that degrade standard polyethylene. Massachusetts and North Carolina cell therapy facilities drive qualification demand for validated polypropylene barrier systems.
- Vinyl:Flexible PVC formulations serve aerospace contamination control with custom bag geometries for ion thruster assembly in Colorado and Bavaria cleanrooms.
- Nylon:High-tensile nylon films address specialty semiconductor wafer shipping applications requiring puncture resistance during automated handling.
Polyethylene sits at the top of the volume ranking, with polypropylene climbing the fastest as pharmaceutical autoclave requirements expand.
Application:
Cost tier stratification separates commodity electronics packaging from validated pharmaceutical barrier systems with 24-month qualification documentation.
- Electronics:Wafer-level packaging complexity in Hsinchu and Pyeongtaek is forcing material upgrades as sub-micron particulate thresholds tighten. Multi-layer coextrusion systems customize oxygen and moisture transmission rates per semiconductor protocol.
- Pharmaceutical:FDA 21 CFR Part 211 enforcement drives serialization-ready film formats with integrated printing capabilities. CDSCO mandates for Indian export-oriented injectables are creating first-mover openings near Hyderabad.
- Biotechnology:Bioreactor-based autologous cell production requires sterile barrier systems with validated particulate control and 12-month compressed qualification cycles.
- Aerospace:Satellite component cleanrooms specify bespoke bag geometries for precision assembly, a mature niche with cyclical procurement patterns.
Electronics commands the largest procurement volumes, while biotechnology gains share fastest on cell therapy manufacturing scale-up.
End User:
Customer type determines validation burden, with manufacturing facilities demanding batch-level traceability integration that strains legacy ERP systems at smaller converters.
- Manufacturing:Contract semiconductor packaging houses in South Korea and Taiwan are consolidating procurement through qualified supplier lists rather than spot markets, extending master service agreements to 36-month terms.
- Laboratories:Research-scale bioreactor operations in Massachusetts and North Carolina require sterile barrier systems with flexible volume procurement and rapid SKU switching.
- Hospitals:Central sterile supply departments source standard-grade polyethylene bags for general medical device handling with lower certification requirements.
- Research Facilities:Academic and government labs prioritize cost efficiency over advanced barrier specifications, sourcing through distributor intermediaries.
Manufacturing sits at the top of the volume ranking, with laboratories climbing the fastest on cell therapy production expansion.
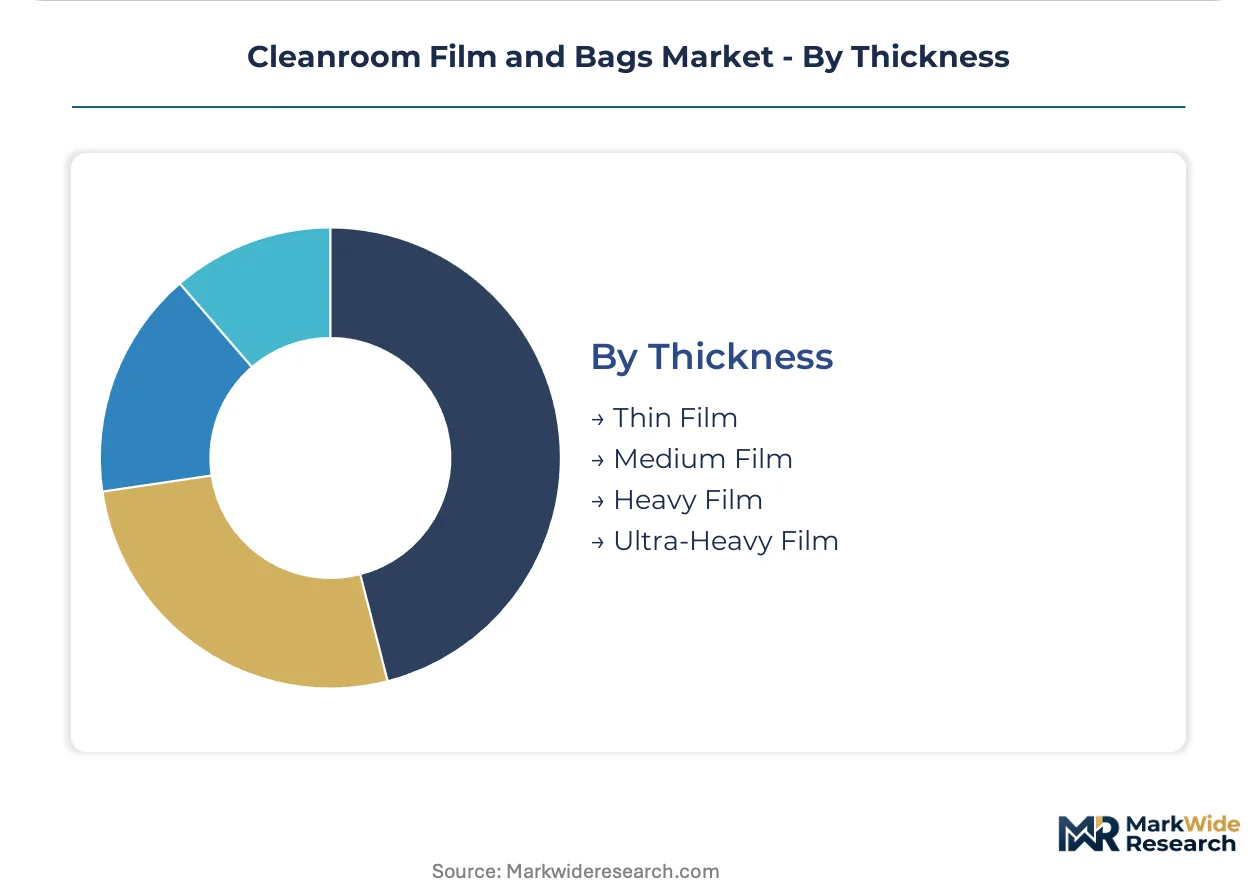
Thickness:
Performance tier differentiation aligns with handling severity, from delicate wafer shipping to heavy industrial component protection.
- Thin Film:Sub-50 micron formulations serve semiconductor wafer shipping where electrostatic discharge control and minimal outgassing override puncture resistance requirements.
- Medium Film:Standard 50-100 micron specifications balance cost and protection for general pharmaceutical and electronics handling across high-volume applications.
- Heavy Film:100-200 micron constructions address aerospace component transport with custom geometries for ion thruster assembly in satellite manufacturing cleanrooms.
- Ultra-Heavy Film:Above-200 micron specialty grades protect precision optical equipment and large-format semiconductor components during international logistics.
Medium film sits at the top of the volume ranking, with thin film climbing the fastest on wafer-level packaging miniaturization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ISO 14644 auditor certification programs in Germany and the United States cannot match hiring velocity at expanding semiconductor packaging houses, creating workforce bottlenecks that constrain regional capacity expansion timelines.
United States
Cell therapy manufacturing scale-up in Massachusetts and North Carolina requires sterile barrier systems with validated particulate control. FDA enforces 21 CFR Part 211 for pharmaceutical packaging integrity, driving serialization-ready film formats. Colorado satellite component cleanrooms specify custom bag geometries for ion thruster assembly.
Taiwan
Wafer-level packaging complexity in Hsinchu Science Park forces material upgrades as sub-micron particulate thresholds tighten. The island's national standards body aligns local cleanroom classifications with ISO 14644-1. TSMC-affiliated packaging vendors now source through qualified supplier lists rather than spot markets.
South Korea
Pyeongtaek semiconductor fabs mandate stricter ISO 14644-1 Class 5 cleanroom classifications, pulling advanced multi-layer film formulations into volume production. MFDS pharmaceutical serialization requirements shape export-oriented packaging specifications. Direct film converter relationships displace distributor intermediaries in the Seoul Capital Area.
China
Dual carbon goals under MEE regulations accelerate solvent-free coextrusion technology deployment among domestic suppliers. Coastal extrusion capacity concentrates in Taiwan-facing provinces. Yangtze River Delta electronics corridors drive procurement volume for Class 7-8 certified film.
Germany
REACH restrictions on perfluorinated compounds force medical device manufacturers to reformulate anti-static additives in cleanroom films. ECHA substance evaluation timelines accelerate substitution toward permanent static dissipative polymers. Bavarian satellite component cleanrooms specify bespoke bag geometries for precision assembly.
Cleanroom Film and Bags Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base organizes around three strategic archetypes: multi-material converters with coextrusion capabilities, region-anchored specialists serving single geographies, and aerospace-focused custom geometry providers. M&A activity concentrates among mid-cap converters seeking backward integration into resin compounding, while capacity expansion dominates among East Asian suppliers responding to semiconductor procurement consolidation.
Among North American diversified packaging groups, Tekni-Plex, Inc. occupies a position exemplifying multi-layer coextrusion capability for pharmaceutical serialization requirements. Nelipak represents the European medical device packaging anchor with controlled-environment film formats. Cleanroom Film & Bags (CFB) sits within the specialist tier as a pure-play serving bespoke aerospace contamination control geometries.
| Leading Market Players |
|---|
| Cleanroom Film & Bags (CFB) |
| Tekni-Plex, Inc. |
| AeroPackaging, Inc. |
| Fruth Custom Packaging |
| Pristine Clean Bags |
| Nelipak |
| PPC Flex Company Inc |
| Degage Corp. |
| Plitek |
| Others |
Value Network & Pricing Analysis
Captive resin compounding among Taiwanese and South Korean film extruders anchors both supply security and pricing power for ISO 14644-1 Class 5 certified materials, insulating qualified converters from naphtha volatility while locking out spot-market buyers.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for multi-layer coextruded films as Pyeongtaek semiconductor fabs consolidate procurement through 36-month master service agreements. Three-tier pricing structure across pharmaceutical-grade autoclave-compatible, electronics-grade moisture-barrier, and aerospace-grade custom geometry levels separates qualification burden from resin cost. Cost compression in standard polyethylene runs through naphtha cracking margin volatility in the US Gulf Coast. Contract semiconductor packaging houses exhibit lowest price sensitivity due to validation lock-in, while research facilities sourcing through distributors face highest sensitivity.
Supply Chain Analysis
Returns and lot-rejection flows from pharmaceutical customers in Massachusetts and North Carolina feed back into regrind streams for non-validated film grades, creating secondary material circuits parallel to prime resin channels. Raw material sourcing draws from Saudi Arabian naphtha derivatives, US Gulf Coast ethylene crackers, and Chinese polypropylene homopolymer. Single-source vulnerability concentrates in Taiwan-facing coastal China extrusion corridors where over sixty percent of Class 7-8 certified capacity sits. Distribution runs through direct converter relationships displacing distributor intermediaries in Hsinchu and Seoul Capital Area.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA 21 CFR Part 211 enforcement and ISO 14644-1 classification tightening continuously elevate barrier specification floors, converting compliance burden into pricing power for qualified suppliers.
For Market Incumbents: To counter resin cost volatility compressing converter margins, deepen backward integration into captive resin compounding near Hsinchu and Pyeongtaek clusters while extending 36-month master service agreements to lock pharmaceutical serialization demand before EU MDR traceability deadlines accelerate. For New Entrants and Emerging Players: Contract packaging houses in Hyderabad and Ahmedabad present the most penetrable entry vector as CDSCO serialization mandates for export-oriented injectables outpace validated local supply. Qualify autoclave-compatible polypropylene barrier systems with 12-month compressed validation cycles to bypass incumbent documentation advantages. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap converters with multi-layer coextrusion capabilities because semiconductor procurement consolidation is compressing supplier bases and extending qualified supplier list dominance. Monitor ECHA substance evaluation timelines for perfluorinated compound restrictions as inflection signals for anti-static additive substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-layer Coextrusion Capacity Expansion | Enables moisture barrier customization for TSMC-affiliated packaging vendors in Hsinchu. |
| Solvent-free Extrusion Technology Deployment | Aligns domestic Chinese suppliers with MEE dual carbon emission regulations. |
| Integrated Serialization Printing Capability | Captures EU MDR lot-level digital tracking requirements for device manufacturers. |
| Autoclave-compatible Polypropylene Qualification | Opens pharmaceutical parenteral packaging closed to standard polyethylene formulations. |
| Custom Geometry Aerospace Bag Development | Serves Colorado and Bavaria satellite component cleanrooms with limited incumbent competition. |
Research Methodology
Multiple input streams — primary interviews with cleanroom film procurement managers at semiconductor packaging houses, regulatory affairs specialists at pharmaceutical converters, and resin compounding technical directors — were reconciled against secondary sources including FDA 21 CFR guidance documents, ISO 14644-1 certification databases, and ECHA substance evaluation timelines. Bottom-up and top-down triangulation validated volume estimates across polyethylene, polypropylene, vinyl, and nylon product categories.
Data-stream reconciliation anchored the analytical framework across the projection horizon through segmented modeling by material type, application vertical, end-user category, and thickness specification. CAGRs were derived from trend extrapolation of procurement volumes at contract packaging houses in Taiwan and South Korea, cross-referenced with cell therapy manufacturing facility expansion announcements in Massachusetts and North Carolina.
Revisions become necessary when ECHA perfluorinated compound restrictions accelerate, MEE emission regulations tighten, or FDA pharmaceutical serialization deadlines shift. Practitioners should monitor ISO 14644 auditor certification program throughput in Germany and the United States for early signals of workforce-constrained capacity expansion delays.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polycarbonate Films Market
Poly film
In-Mould Label Film Market
Poly film
Silicone Release Films Market
Poly film
PET Lidding Films Market
Poly film
Soft Touch Film Market
Poly film
Waste Wrap Film Market
Poly film
MDO-PE Films Market
Poly film
Bi-Axially Oriented Polypropylene (BOPP) Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Germany Plastic Packaging Films Market
Poly film
Recyclable Lidding Films Market
Poly film
High Density Polyethylene Film Market
Poly film
India Plastic Packaging Film Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Chocolate Wrapping Films Market