
 Portugal Container Glass Market | 2026-2036
Portugal Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Portugal Container Glass Market Analytics
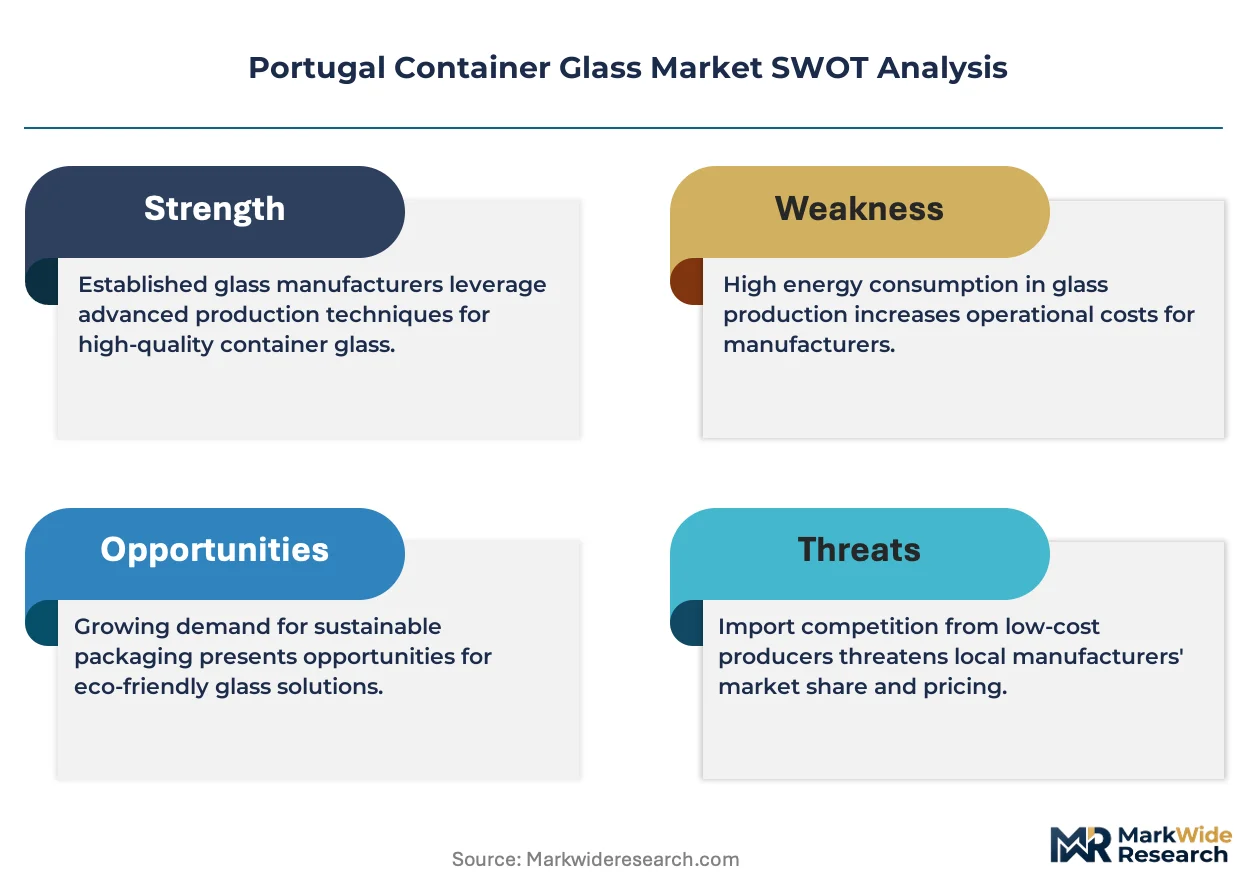
Premium borosilicate-grade and lightweight specification tiers is reorganizing procurement priorities across Portuguese container glass buyers. BA Vidro S.A. leverages vertical integration from furnace to decorated finish, sustaining cost discipline across northern Portugal manufacturing complexes. Vidrala S.A. anchors Iberian distribution through its consolidated Spanish-Portuguese logistics network, while Verallia Packaging differentiates via mold-design partnerships with heritage port wine houses.
Container glass comprises silica-soda-lime formulations formed through blow-and-blow or press-and-blow processes, yielding chemically inert vessels with thermal shock resistance between 40-60°C for beverage and pharmaceutical containment. Bottles occupy the dominant volume position due to wine, beer, and spirits packaging heritage, while Jars capture expanding margin pools in premium cosmetics and artisan food segments. Recycled Glass material grades are gaining specification share as EU packaging regulations tighten post-consumer content minimums, though Clear Glass retains price premiums in pharmaceutical and high-end beverage applications where visual clarity commands supplier selection.
Portugal's Environment Agency and EU REACH frameworks enforce cadmium and lead migration limits in food-contact glass, while BIS-equivalent Portuguese quality certification bodies align with EU Green Deal circularity mandates for post-consumer recycled content verification. These regulatory layers elevate compliance costs for smaller converters but create qualification barriers that favor scaled furnace operators with in-house laboratory testing. Stakeholders must monitor forthcoming EU packaging and packaging waste regulation revisions, as extended producer responsibility fee structures will reshape cost allocation between glass manufacturers and their FMCG customers.
Market Dynamics
EU Green Deal packaging waste mandates are compressing converter margins while forcing furnace operators toward post-consumer recycled content verification systems that smaller Portuguese players cannot fund internally.
Growth Catalysts
- Lightweighting specifications:Douro Valley wine houses demand sub-300 gram bordeaux bottles to cut logistics costs and carbon footprints per unit shipped.
- EU packaging and packaging waste regulation:Extended producer responsibility fee structures redirect investment toward closed-loop collection infrastructure in northern Portugal.
- Porto industrial corridor concentration:Just-in-time mold customization capabilities attract Iberian beverage exporters seeking rapid design iteration.
Market Restraints
- Natural gas price volatility:Furnace operations consume methane-intensive energy inputs with limited short-term substitution pathways.
- Recycled cullet supply fragmentation:Post-consumer glass collection rates vary sharply between Lisbon metropolitan and rural Alentejo zones.
- REACH cadmium migration limits:Decorative enamel testing protocols extend qualification timelines for heritage port wine decorated finishes.
Strategic Opportunities
- Algarve cosmetics packaging:Premium skincare brands seek amber and cobalt jar configurations for artisan product lines.
- Pharmaceutical borosilicate demand:Injectable drug containment standards create qualification pathways for thermally resistant glass grades.
- Digital mold-design partnerships:Heritage port houses co-develop limited-edition bottle geometries with converter technical teams.
Industry Challenges
- Furnace refractory engineering talent:Specialized thermal management expertise for oxy-fuel conversion projects remains scarce in Portuguese labor markets.
- Batch plant reconfiguration capex:Post-consumer cullet sorting and beneficiation equipment requires seven-figure capital commitments per production line.
- EU Green Deal compliance timeline compression:Rapidly tightening recycled content verification deadlines strain in-house laboratory testing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portugal Container Glass Market |
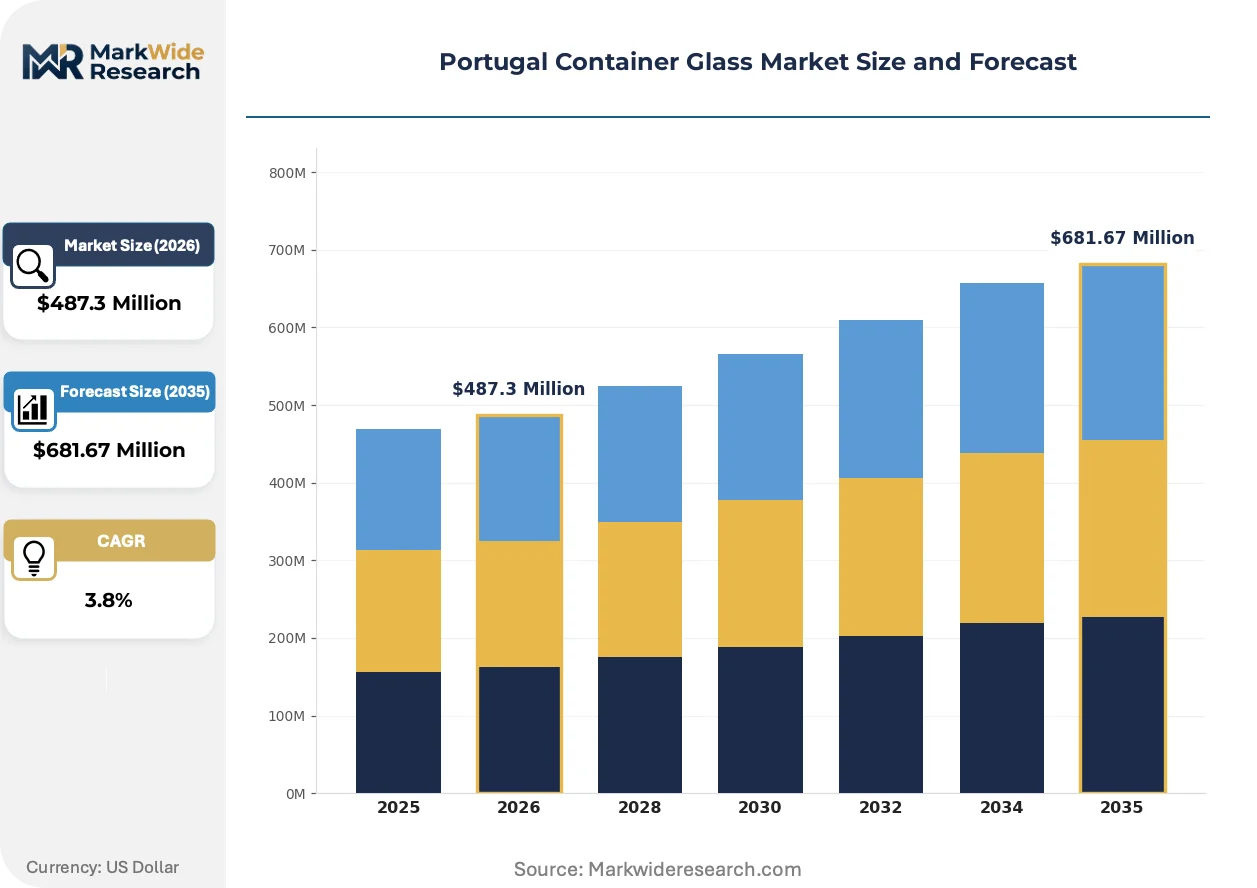
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tumblers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Material: Recycled Glass, Clear Glass, Colored Glass, Frosted Glass Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Depósito da Marinha Grande, BA Vidro S.A, Vidrala S.A, Berlin Packaging, Verallia Packaging, Verallia SA, Mercado do Vidro, Vidrala, BA Glass Portugal, S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portugal Container Glass Market Evolving Landscape
Electrification of melting technology and digital supply chain traceability are restructuring how Portuguese container glass converters qualify for premium beverage contracts and pharmaceutical certifications.
Oxy-fuel combustion retrofitting is supplanting conventional air-fuel furnace architectures across northern Portugal manufacturing complexes. Douro Valley wine bottlers specify these lower-NOx configurations to meet supply chain decarbonization pledges. The technology is compressing allowable emissions intensity thresholds for EU Green Deal compliance documentation.
Portugal's Environment Agency enforces cadmium and lead migration limits aligned with EFSA food-contact material frameworks. Testing protocol harmonization elevates laboratory certification costs for decorative finish applications. Heritage port wine houses respond by consolidating supplier relationships toward scaled furnace operators with captive analytical capabilities.
Direct converter-brand design collaboration is displacing traditional mold-broker intermediation in premium spirits packaging procurement. Porto-based technical teams embed with Alentejo distillery clients for rapid prototype iteration. This pattern concentrates specification influence among vertically integrated manufacturers with in-house decoration and finishing assets.
Portugal Container Glass Market Segmentation
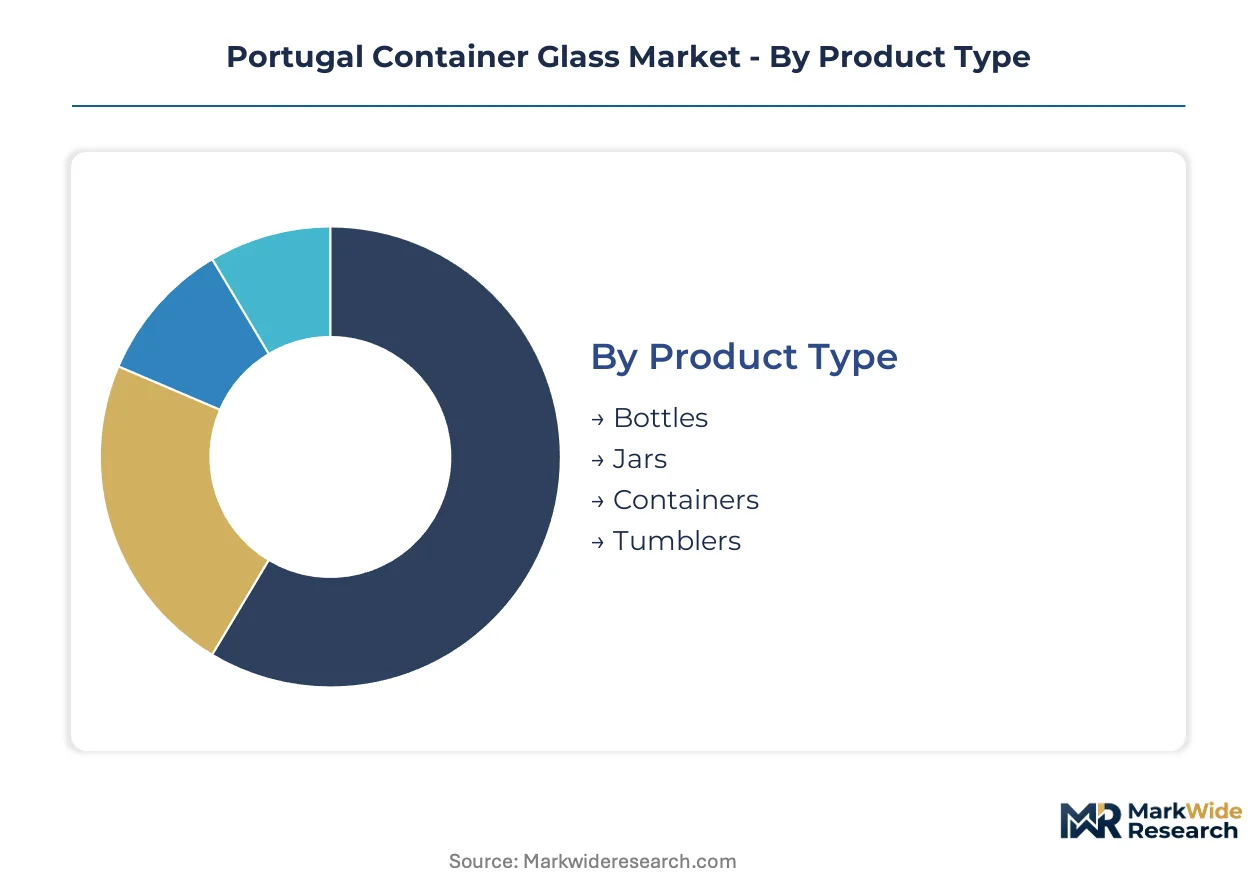
Portuguese container glass procurement channels demand precise specification alignment across product geometries, material grades, and end-use compliance tiers. Converter networks in the Porto industrial corridor route distinct segment mixes through wholesale bulk contracts versus specialty retail pathways.
Product Type:
Channel flow diverges sharply: bottles and jars move predominantly through wholesale agreements with beverage exporters, while tumblers and specialty containers reach cosmetics brands via specialty store distributors.
- Bottles:Silica-soda-lime formulations shaped through blow-and-blow or press-and-blow processes yield chemically inert vessels with thermal shock resistance between 40-60°C. Douro Valley wine houses and Alentejo spirits distillers concentrate procurement around sub-300 gram lightweight bordeaux configurations to compress logistics costs per export unit.
- Jars:Wide-mouth geometries with enhanced wall thickness accommodate vacuum-sealing requirements for artisan food and premium skincare applications. Algarve cosmetics brands and Portuguese honey exporters in the Centro region are expanding orders for amber and cobalt jar configurations in 200-500ml capacities.
- Containers:Rectangular and cylindrical storage formats serve household chemical and bulk pharmaceutical intermediates.
- Tumblers:Straight-sided drinking vessels without handles target hospitality and promotional merchandise channels.
By volume, bottles lead. By growth pace, jars are climbing the fastest.
End User:
Cost tier stratification separates premium pharmaceutical certification requirements from standard food-contact specifications, with cosmetics occupying intermediate price positioning.
- Food & Beverage:Wine, beer, spirits, and artisan food producers generate the dominant demand pull, with heritage port houses specifying decorated finishes requiring cadmium migration testing under EFSA-aligned protocols.
- Pharmaceuticals:Injectable drug containment standards mandate borosilicate-grade thermal resistance and USP Type I compliance, creating qualification barriers that favor furnace operators with captive laboratory testing.
- Cosmetics:Premium skincare brands seek distinctive coloration and surface treatments for shelf differentiation in amber, cobalt, and frosted finishes.
- Household Products:Cleaning chemical and home fragrance applications prioritize chemical compatibility and child-resistant closure compatibility over visual clarity.
Food & beverage commands volume leadership. Pharmaceuticals show the steepest margin expansion trajectory.
Material:
Supply concentration around northern Portugal furnace complexes shapes material availability, with post-consumer cullet collection infrastructure determining recycled glass penetration rates.
- Recycled Glass:Post-consumer cullet beneficiated to remove ceramics, metals, and organics before furnace re-melting. EU Green Deal circularity mandates are compressing converter timelines for recycled content verification systems.
- Clear Glass:Low-iron silica formulations deliver optical clarity for pharmaceutical and premium beverage applications where visual inspection commands supplier selection. Porto-area laboratories maintain EFSA-aligned migration testing for food-contact certification.
- Colored Glass:Amber, green, and cobalt variants incorporate transition metal oxides for UV protection and brand differentiation.
- Frosted Glass:Acid-etched or molded surface treatments provide tactile differentiation for cosmetics and gift-market positioning.
Clear glass dominates value capture. Recycled grades are gaining specification share fastest.
Distribution Channel:
Customer type segmentation separates high-volume exporters seeking just-in-time mold customization from smaller artisans requiring minimum-order flexibility.
- Wholesale:Direct converter relationships with Iberian beverage exporters concentrate around the Porto industrial corridor, where technical teams embed for rapid prototype iteration and mold design collaboration.
- Specialty Stores:Premium cosmetics and artisan food brands source distinctive jar configurations through curated distributor networks serving the Algarve and Lisbon metropolitan markets.
- Supermarkets:Private-label beverage and condiment packaging moves through consolidated procurement desks with standardized bottle geometries.
- Online Retail:E-commerce channels serve small-batch producers and custom decoration orders with extended lead times.
Wholesale channels handle volume leadership. Specialty stores are expanding most quickly in margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portugal's container glass output clusters along the Porto industrial corridor, where furnace complexes feed Iberian beverage export channels with just-in-time mold customization capabilities. The national market operates as a specialized node within broader EU packaging supply chains, with regulatory alignment to Brussels-driven circularity mandates shaping investment timelines across sub-regional manufacturing bases.
Northern Portugal
The Porto metropolitan zone and Marinha Grande glassmaking tradition generate the dominant production volume, serving Douro Valley wine houses with lightweight bordeaux configurations. EU Green Deal packaging waste regulations compress converter margins while forcing post-consumer recycled content verification systems. Furnace operators in this corridor leverage captive laboratory testing to meet EFSA-aligned cadmium migration limits for decorated port wine finishes.
Central Portugal
The Centro region's artisan food producers and honey exporters are expanding orders for amber jar configurations in 200-500ml capacities. Portugal's Environment Agency enforces batch-level traceability requirements that elevate compliance costs for smaller converters. Leiria and Coimbra industrial zones host secondary decoration and finishing facilities that supply Lisbon metropolitan distribution channels.
Alentejo
Spirits distillers in this southern region specify sub-300 gram lightweight bottles to compress logistics costs per export unit. Post-consumer glass collection rates lag northern zones, fragmenting recycled cullet supply for furnace feedstock. Évora and Beja sub-regions concentrate procurement relationships with vertically integrated manufacturers offering rapid prototype iteration.
Algarve
Premium skincare brands in this coastal region seek cobalt and frosted jar configurations for artisan cosmetics lines. REACH compliance timelines for decorative enamel testing extend qualification cycles for heritage-finish suppliers. Faro and Lagos logistics nodes connect specialty store distributors to Porto-based converter technical teams.
Lisbon Metropolitan Area
The capital region's consolidated procurement desks handle private-label beverage and condiment packaging through standardized bottle geometries. Extended producer responsibility fee structures under EU packaging regulation redirect investment toward closed-loop collection infrastructure. Setúbal and Sintra industrial suburbs host warehousing and distribution facilities for Iberian export consolidation.
Portugal Container Glass Market Competitive Landscape
Concentration sits with vertically integrated furnace operators that control batch formulation through decorated finishing in captive facilities. The vendor base separates into three tiers: scaled Iberian network players with cross-border logistics, Portuguese specialists leveraging Marinha Grande glassmaking heritage, and international packaging conglomerates with mold-design partnerships. Competitive dynamics center on oxy-fuel furnace retrofitting and digital mold-design collaboration rather than price-based rivalry.
Among Portuguese-heritage operators, BA Vidro S.A. and BA Glass Portugal, S.A. exemplify the vertically integrated archetype with northern manufacturing complexes. Vidrala S.A. and Vidrala anchor the Iberian-network tier through consolidated Spanish-Portuguese distribution capabilities. Verallia Packaging and Verallia SA represent the international conglomerate pattern with heritage port wine house partnerships. Depósito da Marinha Grande occupies a specialist position rooted in the region's historic glassmaking cluster. Berlin Packaging exemplifies the distributor-intermediary model serving smaller batch requirements.
| Leading Market Players |
|---|
| Depósito da Marinha Grande |
| BA Vidro S.A |
| Vidrala S.A |
| Berlin Packaging |
| Verallia Packaging |
| Verallia SA |
| Mercado do Vidro |
| Vidrala |
| BA Glass Portugal, S.A. |
| Others |
Value Network & Pricing Analysis
Post-consumer cullet substitution for virgin silica feedstock is compressing batch material costs while redistributing furnace economics toward northern Portugal complexes with captive beneficiation infrastructure. This input shift simultaneously concentrates supply geography around Porto-area operators and erodes price premiums for clear glass grades lacking recycled content verification.
Pricing Analysis
EU Green Deal packaging waste regulation dictates the pricing tier structure across Portuguese container glass procurement. Three-tier pricing structure across premium, standard, and economy levels separates borosilicate pharmaceutical certification from standard food-contact grades and commodity construction glass. Price differentiation rests on EFSA-aligned migration testing compliance and volume scale commitments from Douro Valley wine exporters. Cost compression in standard-tier bottles is intensifying because natural gas price volatility feeds directly into furnace operating economics. Small-batch artisan producers in Alentejo exhibit highest price sensitivity, while pharmaceutical buyers absorb premium pricing for USP Type I thermal resistance certification.
Supply Chain Analysis
Inventory cycles for mold customization average six to eight weeks across Porto industrial corridor converters serving Iberian beverage exporters. Supply concentrates in Spain, Portugal, and France for finished container glass distribution to EU markets. Raw material sourcing draws from Belgian soda ash, Spanish silica sand deposits, and domestic post-consumer cullet collection networks. Single-source vulnerability sits with natural gas supply contracts tied to volatile European spot markets. Distribution runs through converter-direct relationships with heritage port wine houses and consolidated wholesale desks for private-label beverage packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portuguese container glass demand tracks Iberian wine export volumes in a cyclical recovery pattern. Elevated port wine shipments to Anglo-Saxon markets are restocking distributor inventories after destocking phases.
For Market Incumbents: Secure captive laboratory testing capacity for EFSA-aligned cadmium migration protocols before EU packaging waste regulation verification deadlines compress qualification timelines. Defend mold-design partnerships with heritage Douro Valley houses through embedded technical teams that accelerate prototype iteration. Oxy-fuel furnace retrofitting capex requirements threaten smaller competitors unable to fund seven-figure batch plant reconfigurations.
For New Entrants and Emerging Players: Rapid small-batch customization for Algarve cosmetics brands represents a service-layer gap where scaled furnace operators under-serve minimum-order flexibility requirements. Target amber and cobalt jar configurations in 200-500ml capacities for premium skincare lines seeking distinctive shelf differentiation. Partner with specialty store distributors in Faro and Lagos logistics nodes to bypass wholesale channel consolidation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with Portuguese-heritage furnace operators lacking oxy-fuel conversion capital reserves. Five-to-ten year viability hinges on EU Green Deal compliance infrastructure rather than commodity glass pricing cycles. Monitor extended producer responsibility fee structure finalization as the inflection signal for margin allocation between manufacturers and FMCG customers.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofitting | Lowers NOx emissions intensity for EU Green Deal compliance documentation required by Douro Valley bottlers. |
| Post-Consumer Cullet Beneficiation | Captive sorting equipment secures recycled content verification for tightened circularity mandates. |
| Digital Mold-Design Partnerships | Embedded technical teams with heritage port houses displace traditional broker intermediation. |
| Pharmaceutical Borosilicate Qualification | USP Type I certification opens injectable drug containment pathways with steepest margin expansion. |
| Algarve Cosmetics Channel Expansion | Amber and cobalt jar configurations serve premium skincare brands seeking artisan positioning. |
Research Methodology
A standing panel of furnace operations directors, beverage procurement managers at Douro Valley wine houses, pharmaceutical packaging engineers, and EU regulatory affairs specialists provided ongoing calibration across primary fieldwork phases. Secondary validation drew from Portuguese Environment Agency circularity mandate filings, EU REACH restriction updates, EFSA food-contact material opinions, and Iberian customs trade data for container glass flows. Bottom-up volume modeling triangulated against top-down macroeconomic drivers.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product geometry, material grade tier, end-use compliance requirements, and regional production hub clustering. CAGRs were derived from regression analysis of historical shipment data and forward-looking capacity expansion announcements. Forecast inputs included natural gas price trajectory assumptions and post-consumer cullet collection rate projections for Lisbon metropolitan versus rural Alentejo zones.
Forecasts assume regulatory continuity in EU Green Deal implementation timelines and EFSA migration limit enforcement; material policy shifts would require re-modeling of compliance cost burdens. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Middle East and Africa Pharmaceutical Glass Packaging Market
Glass Packaging
Bulgaria Container Glass Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
Glass Jugs Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Container Glass Coatings Market
Glass Packaging
Mason Jars Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
Dosing Bottles Market