
 Double Coated Film Tapes Market | 2026-2036
Double Coated Film Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Double Coated Film Tapes Market Analysis
Polyester substrates is rebalancing cost-performance economics across bonding and surface protection applications. 3M Company leverages captive resin compounding to sustain margin control across North American electronics supply chains. Nitto Denko Corporation anchors high-temperature polyimide tape production for semiconductor back-end processes in East Asia. tesa SE competes through specialized thin-film constructions for automotive interior assembly.
Double coated film tapes consist of a carrier film with adhesive layers on both faces, typically engineered to thicknesses between twelve micrometers and two hundred micrometers for precision bonding, gasketing, or temporary surface protection in manufacturing workflows. The polyester product type dominates volume throughput due to its tensile strength and dimensional stability in automated dispensing equipment. Electronics end users represent the fastest-expanding demand pool as device assembly shifts toward thinner bonding interfaces and thermal management layers. Surface protection applications command premium pricing relative to commodity labeling uses because of clean-removal specifications and residue-free performance requirements.
EPA regulates volatile organic compound emissions from adhesive coating operations under Clean Air Act standards, while REACH restricts certain phthalate plasticizers in European tape formulations. China's GB standards and Japan's JIS specifications govern flame retardancy and electrical insulation grades for electronics-bound shipments. Manufacturers must monitor evolving substance restrictions and certification reciprocity between Asian export hubs and EU import requirements to preserve market access without redundant testing burdens.
Market Dynamics
Semiconductor packaging miniaturization is compressing bonding interface tolerances below fifty micrometers, forcing tape suppliers to synchronize adhesive rheology with automated die-attach equipment cycle times. This structural pressure cascades through substrate selection, coating precision, and clean-room logistics.
Growth Catalysts
- Device Miniaturization Mandates:Electronics assemblers in South Korea's semiconductor corridors specify sub-twenty-five-micrometer total thickness for thermal interface bonding layers, pulling demand toward ultra-thin polyester carriers.
- REACH Substance Restrictions:ECHA's evolving candidate list for SVHCs is accelerating reformulation toward solvent-free acrylic adhesives in European-bound electronics shipments.
- Automotive Interior Electrification:Cabin sensor integration and display bonding in German and Japanese vehicle platforms is opening specification windows for low-outgassing, high-shear tape constructions.
Market Restraints
- Petrochemical Feedstock Volatility:Polyester film and silicone adhesive raw materials track naphtha and siloxane monomer indices, compressing margin predictability for non-integrated coaters.
- East Asian Supply Concentration:Over seventy percent of polyimide film substrate capacity clusters in Japan and South Korea, creating geographic vulnerability to logistics disruptions or export licensing delays.
- Performance Ceiling in Extreme Thermal Cycling:Acrylic chemistry faces hard limits above one hundred fifty degrees Celsius continuous exposure, ceding ground to epoxy and cyanate ester alternatives in power module applications.
Strategic Opportunities
- Indian Electronics Manufacturing Corridors:PLI scheme incentives for semiconductor and mobile device assembly in Gujarat and Tamil Nadu are creating first-mover specification-setting windows for tape suppliers establishing local slitting and converting operations.
- Battery Cell Stack Bonding:Lithium-ion pouch cell lamination and thermal runaway barrier attachment in electric vehicle battery packs represents a greenfield application with distinct pressure-sensitive adhesive performance requirements.
- EU Battery Regulation Traceability:Mandatory digital product passports for industrial batteries entering European markets after twenty-twenty-six create demand for durable bonding solutions that survive full lifecycle environmental exposure documentation.
Industry Challenges
- Clean-Room Coating Expertise Scarcity:Precision adhesive deposition for semiconductor-grade tapes requires operators trained in particulate control protocols below Class one thousand, a skill set concentrated in Japan and limited elsewhere.
- Multi-Jurisdiction Certification Parallelism:Simultaneous pursuit of UL recognition, VDE certification, and GB standard compliance for a single electronics-bound product line extends qualification timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double Coated Film Tapes Market |
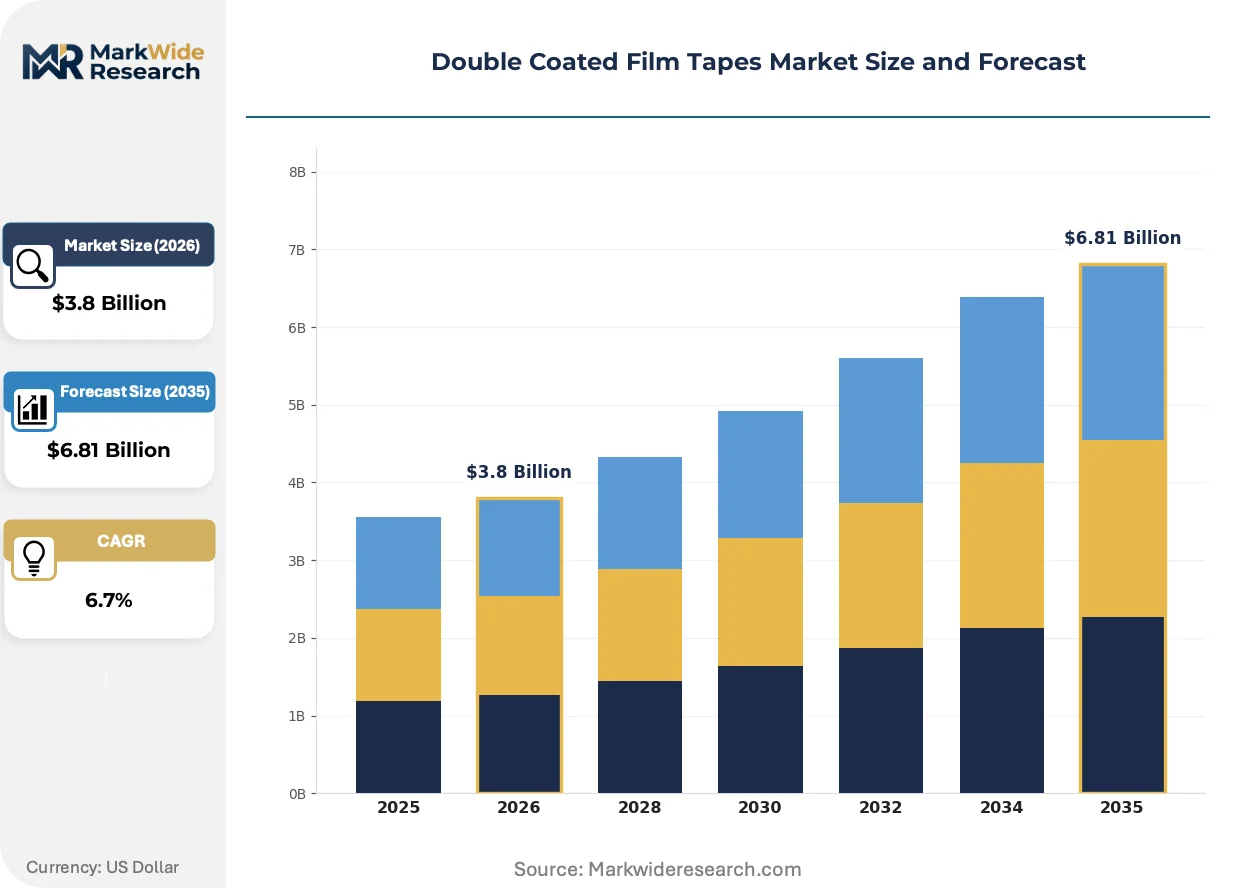
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polyimide, Acrylic, PVC End User: Electronics, Automotive, Packaging, Construction Application: Surface Protection, Bonding, Labeling, Insulation Thickness: Thin, Medium, Thick, Ultra-Thin |
| Companies Covered | 3M Company, Nitto Denko Corporation, tesa SE, Avery Dennison Corporation, Lintec Corporation, Shurtape Technologies, LLC, Intertape Polymer Group, Adchem Corporation, MACtac, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double Coated Film Tapes Market Emerging Trajectories
Thermal management integration and regulatory substance restrictions are converging to redefine tape specification criteria across electronics and transportation end uses. Suppliers are repositioning around functional performance rather than commodity substitution.
Ultra-thin polyimide carriers with vapor-deposited metal grounding layers are absorbing electromagnetic interference shielding functions previously handled by separate gaskets and conductive paints. Smartphone and tablet manufacturers in Taiwan and mainland China are qualifying these constructions for five-millimeter-thin device architectures. The technology is absorbing margin from discrete EMI component suppliers while compressing bill-of-materials layer counts.
EPA's National Emission Standards for Hazardous Air Pollutants for surface coating operations is tightening volatile organic compound limits below twenty-five tons per year for major sources. Adhesive coaters in the US Southeast are retrofitting thermal oxidizers and switching to hot-melt or UV-curable chemistries to maintain operating permits. Electronics-bound production lines face the steepest compliance costs due to clean-room air exchange requirements that compound emission control complexity.
Consolidated procurement desks at tier-one electronics contract manufacturers are compressing supplier qualification lists from twelve to fifteen approved vendors per commodity to three to four strategic partners with regional converting capabilities. Foxconn and Pegatron procurement teams in Shenzhen and Kaohsiung now demand localized inventory hubs and twenty-four-hour technical response as baseline contract terms. This concentration is most visible in China's Pearl River Delta, where tape suppliers without in-country slitting operations are exiting approved vendor lists regardless of technical performance.
Double Coated Film Tapes Market Segmentation
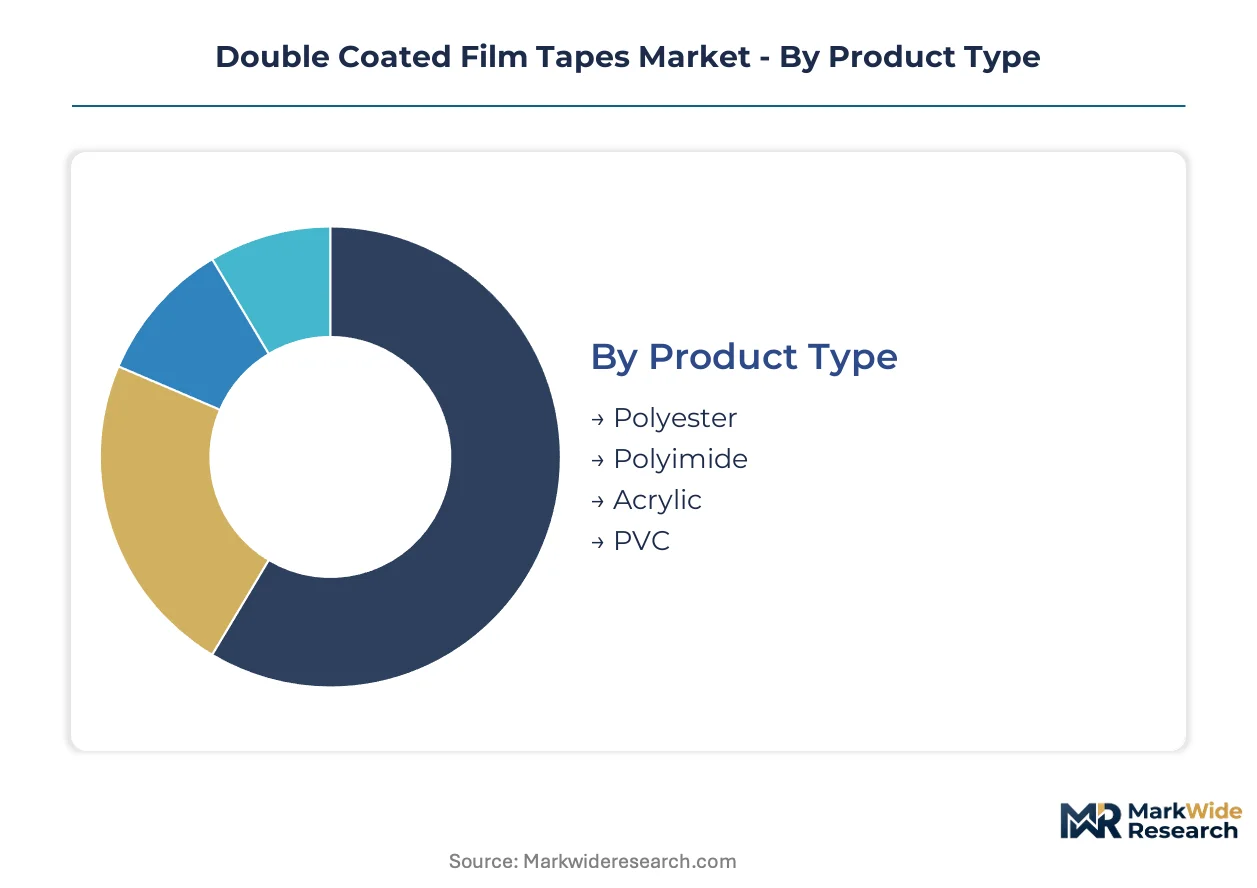
Segmentation in double coated film tapes reveals how substrate chemistry, end-use thermal requirements, and precision thickness specifications create distinct procurement corridors. Electronics assemblers prioritize dimensional stability and clean-removal properties, while automotive buyers emphasize shear strength across temperature cycling.
Product Type:
Upgrade cycles in semiconductor packaging and display lamination are pulling demand toward higher-performance substrates that replace legacy constructions.
- Polyester:Biaxially oriented polyethylene terephthalate film delivers tensile strength above 200 MPa and dimensional stability under automated dispensing. Demand concentrates in China's coastal manufacturing provinces for smartphone display bonding and temporary surface protection during assembly workflows.
- Polyimide:Aromatic polyimide film maintains mechanical integrity above 200°C continuous exposure, essential for semiconductor back-end processes and flexible circuit lamination. South Korea's semiconductor packaging corridors specify polyimide carriers for thermal interface bonding layers under 50 micrometers total thickness.
- Acrylic:Cast acrylic film substrates offer optical clarity and UV resistance for display applications and signage mounting.
- PVC:Polyvinyl chloride film provides cost-effective conformability for general industrial masking and temporary floor marking.
Polyester sits at the top of the volume ranking, with polyimide climbing the fastest.
End User:
Cost tier stratification separates specification-intensive electronics procurement from price-sensitive construction applications.
- Electronics:Device miniaturization mandates sub-25-micrometer bonding interfaces for thermal management and electromagnetic shielding. Taiwan and mainland China smartphone manufacturers absorb premium pricing for residue-free clean removal.
- Automotive:German and Japanese vehicle platforms specify low-outgassing acrylic and silicone adhesives for cabin sensor integration and display bonding under 85°C dashboard exposure.
- Packaging:Folding carton and corrugated box manufacturers utilize medium-tack constructions for temporary closure and pallet stabilization.
- Construction:Weather-resistant masking and vapor barrier sealing applications prioritize cost per square meter over precision thickness tolerance.
Electronics commands the highest specification density, with automotive gaining share fastest on electrification trends.
Application:
Application selection tracks the tension between permanent structural bonding and temporary process protection.
- Surface Protection:Clean-removal specifications require adhesive formulations that release without residue across 30-90 day exposure windows. Premium pricing reflects silicone adhesive chemistry and controlled peel adhesion below 8 N/25mm.
- Bonding:Structural assembly applications demand shear strength above 20 N/cm² and resistance to thermal cycling between -40°C and 150°C for automotive underhood and power electronics.
- Labeling:Barcode and asset tracking applications utilize facestock-compatible adhesives with initial tack optimized for corrugated and polyolefin surfaces.
- Insulation:Electrical grade tapes meet dielectric strength requirements above 3 kV for motor winding and transformer applications.
Bonding holds the largest volume position, with surface protection expanding most quickly on clean-room qualification requirements.
Thickness:
Thickness selection correlates directly with automation compatibility and thermal impedance targets in precision assembly.
- Ultra-Thin:Below 25 micrometer total construction enables 5-millimeter-thin device architectures and minimizes thermal resistance in semiconductor packages. South Korea and Taiwan electronics assemblers specify ultra-thin polyimide for die-attach processes.
- Thin:25-50 micrometer range balances handling characteristics with space constraints in automotive interior sensor mounting.
- Medium:50-100 micrometer constructions dominate general industrial bonding and surface protection with forgiving application tolerances.
- Thick:Above 100 micrometer tapes provide gap-filling capability and cushioning for uneven substrates in construction and heavy equipment applications.
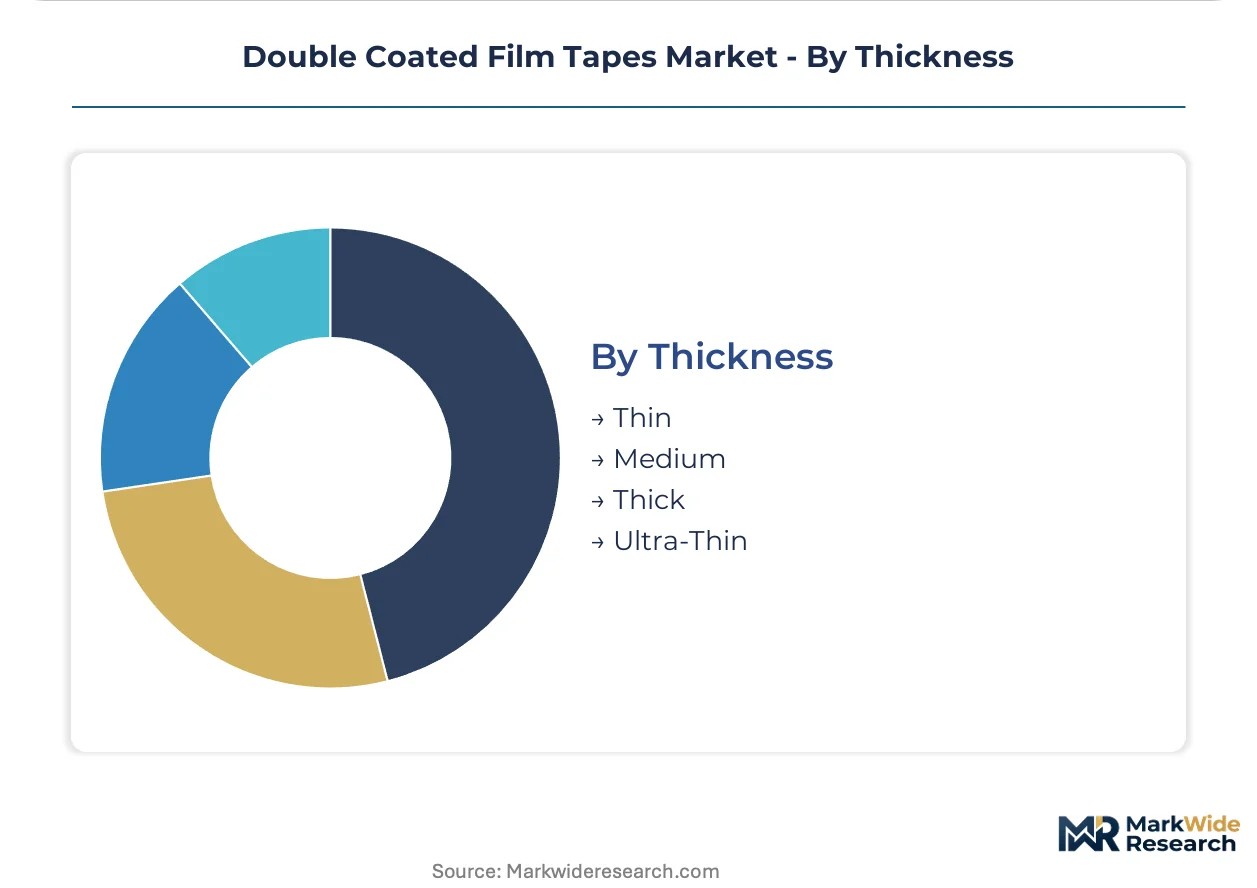
Medium thickness leads current volume, with ultra-thin constructions on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal manufacturing provinces concentrate the heaviest procurement volumes for polyester and polyimide tape variants. Electronics contract manufacturers in Guangdong and Jiangsu provinces drive specification requirements for sub-50-micrometer bonding interfaces. Regional regulatory frameworks and industrial cluster specialization create distinct procurement corridors across major producing economies.
China
Smartphone and tablet manufacturers in Shenzhen and Dongguan absorb premium-priced ultra-thin constructions for five-millimeter device architectures. GB standards govern flame retardancy and electrical insulation grades for domestic consumption and export-bound shipments. The Pearl River Delta hosts the densest concentration of converting operations, with Foxconn and Pegatron procurement desks demanding localized inventory hubs as baseline contract terms.
United States
Automotive electrification in Michigan and Tennessee assembly corridors specifies low-outgassing acrylic adhesives for cabin sensor integration. EPA's National Emission Standards for Hazardous Air Pollutants tighten volatile organic compound limits below twenty-five tons per year for major coating sources. Southeast adhesive coaters retrofit thermal oxidizers and switch to hot-melt chemistries to maintain operating permits under clean-room air exchange requirements.
Germany
German vehicle platforms integrate display bonding and thermal management layers under dashboard exposure up to eighty-five degrees Celsius. REACH substance restrictions through ECHA's evolving candidate list accelerate reformulation toward solvent-free acrylic adhesives in European-bound electronics. Bavarian automotive suppliers coordinate specification-setting with tape vendors for Class A interior surface applications.
South Korea
Semiconductor packaging corridors in Gyeonggi Province specify polyimide carriers for thermal interface bonding layers under fifty micrometers total thickness. MFDS and KATS standards intersect with export market requirements for dual-certified product lines. Samsung and SK Hynix backend processes drive demand for high-temperature stability above two hundred degrees Celsius continuous exposure.
Japan
Polyimide film substrate capacity clusters in Ibaraki and Shiga prefectures, supplying global semiconductor and flexible circuit lamination markets. METI oversees JIS specifications that govern precision thickness tolerances for clean-room qualified shipments. Tokyo and Osaka-based coaters maintain particulate control expertise below Class one thousand, a skill set concentrated domestically and limited elsewhere.
Double Coated Film Tapes Market Vendor Landscape
Strategic partnerships dominate the current landscape as suppliers synchronize adhesive rheology with automated die-attach equipment cycle times. The vendor base organizes around three tiers: integrated resin compounders with captive substrate supply, specialized thin-film coaters focused on clean-room qualification, and regional converters with slitting and logistics proximity to electronics clusters. Two archetypes command attention: technology licensors with patented carrier constructions, and scale operators with backward integration into petrochemical feedstocks. Geographic expansion and portfolio diversification represent the dominant competitive vectors as procurement desks compress approved vendor lists.
Within the integrated compounder tier, 3M Company and Nitto Denko Corporation exemplify divergent geographic anchoring strategies. 3M's North American electronics supply chain presence leverages captive resin production for margin control. Nitto Denko occupies a position calibrated to East Asian semiconductor backend demand. Among European specialists, tesa SE represents the automotive-interior specification vector. These three names anchor industry-level commentary on substrate chemistry, adhesive formulation, and end-use certification without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| 3M Company |
| Nitto Denko Corporation |
| tesa SE |
| Avery Dennison Corporation |
| Lintec Corporation |
| Shurtape Technologies, LLC |
| Intertape Polymer Group |
| Adchem Corporation |
| MACtac, LLC |
| Others |
Supply Flow & Price Mechanics
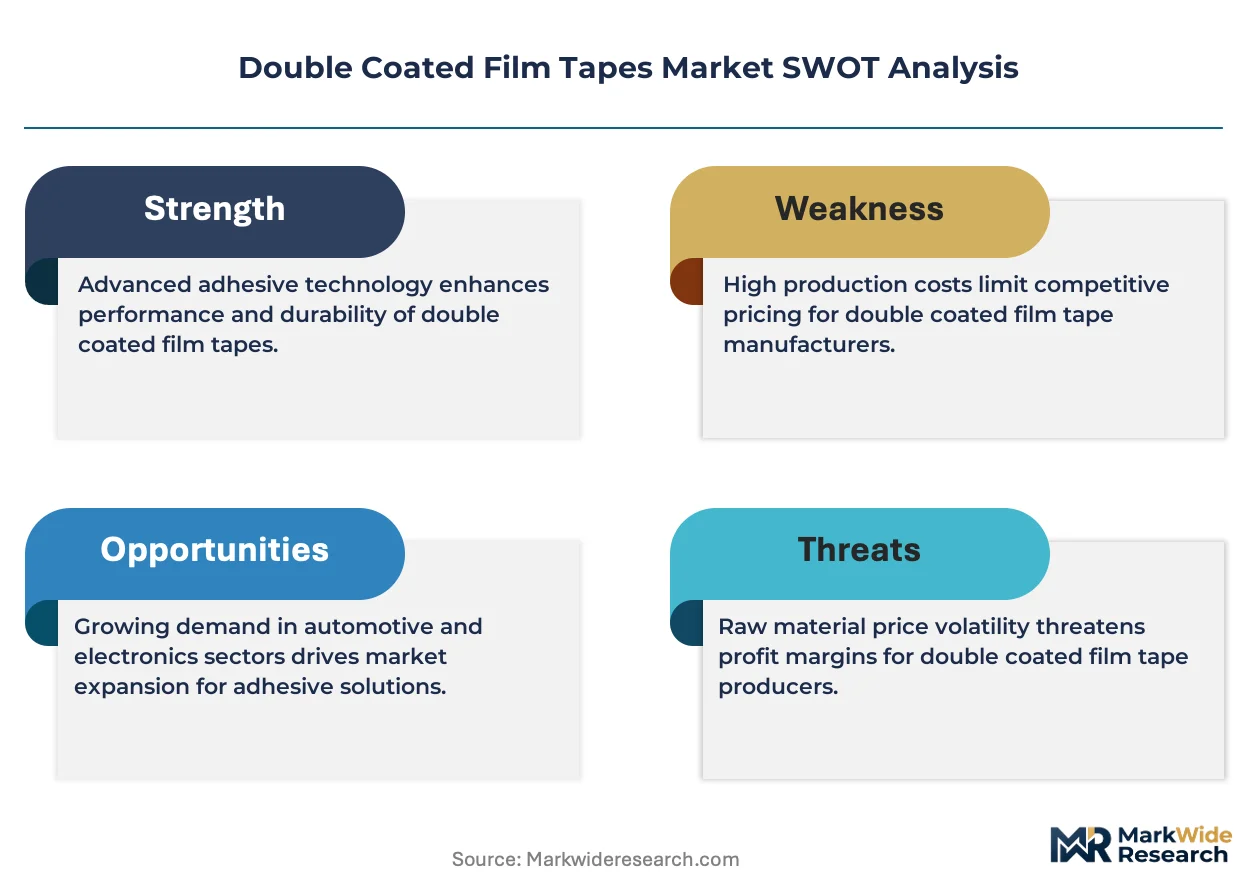
REACH substance restrictions and evolving EPA adhesive emissions standards gate qualified supply and premium-tier pricing access, forcing reformulation investments that separate solvent-free acrylic specialists from commodity coaters while electronics assemblers absorb residue-free clean-removal premiums.
Pricing Analysis
Petrochemical feedstock volatility passes through polyester film and silicone adhesive raw materials that track naphtha and siloxane monomer indices, compressing margin predictability for non-integrated coaters. Pricing stratifies across semiconductor-grade clean-room qualified, automotive low-outgassing certified, and general industrial tiers. Price differentiation hinges on UL recognition and VDE certification status plus volume scale commitments from Foxconn and Pegatron procurement desks. Cost compression in general industrial masking is intensifying because Chinese converters add slitting capacity faster than specification-intensive segments expand.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for semiconductor and mobile device assembly corridors in Gujarat and Tamil Nadu, pulling inventory hub localization requirements from Shenzhen and Kaohsiung procurement templates. Polyimide film substrate capacity clusters in Japan and South Korea, while polyester resin compounding anchors in North America and coastal China. Silicone adhesive monomer supply draws from German and US Gulf Coast petrochemical complexes. Single-source vulnerability concentrates in Japanese Class one thousand clean-room coating expertise. Distribution runs through tier-one electronics contract manufacturer consolidated procurement desks that compress approved vendor lists from twelve to three strategic partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in ultra-thin polyimide thermal interface bonding and battery cell stack lamination, where specification density outruns capacity addition and solvent-free acrylic reformulation commands premium-tier positioning.
For Market Incumbents: Deploy captive resin compounding to sustain margin control across North American electronics supply chains while accelerating clean-room coating capacity in the Pearl River Delta to match Foxconn and Pegatron twenty-four-hour technical response requirements. Defend against emerging Indian converters by pre-emptive qualification under GB standards and dual carbon goals compliance for export-bound shipments. Prioritize vapor-deposited metal grounding layer patents that absorb electromagnetic interference shielding functions from discrete component suppliers. For New Entrants and Emerging Players: Capture battery cell stack bonding specifications for lithium-ion pouch cell lamination in electric vehicle battery packs, a greenfield application with distinct pressure-sensitive adhesive performance requirements underserved by incumbent semiconductor-focused coaters. Target Indian electronics manufacturing corridors before local slitting operations mature, offering EU Battery Regulation traceability documentation as a bundled service. Position through specialized thin-film constructions for automotive interior assembly that tesa SE currently dominates. For Investors and Strategic Acquirers: Roll-up economics work for regional converters with slitting and logistics proximity to electronics clusters because procurement desk consolidation compresses approved vendor lists and rewards geographic coverage density over standalone technical performance. Five-to-ten-year viability favors operations with backward integration into petrochemical feedstocks or captive clean-room coating expertise below Class one thousand. Watch for inflection when Indian PLI scheme incentives trigger specification-setting windows that lock in first-mover adhesive rheology synchronization with automated die-attach equipment cycle times.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive silicone adhesive production insulates 3M Company from naphtha index volatility in Southeast coating operations. |
| Clean-Room Coating Capacity Expansion | Class one thousand particulate control protocols below fifty micrometer precision enable Samsung and SK Hynix backend process qualification. |
| Solvent-Free Acrylic Reformulation | ECHA SVHC candidate list compliance preserves European electronics shipment access without redundant testing burdens. |
| Localized Slitting Operations in India | Gujarat and Tamil Nadu inventory hubs meet Foxconn procurement baseline terms before domestic competitors achieve technical parity. |
| Thermal Management Integration Patents | Vapor-deposited metal grounding layers absorb electromagnetic interference functions from Taiwanese gasket suppliers. |
Methodological Framework
Direct dialogue with adhesive coating plant managers, electronics OEM procurement leads, semiconductor packaging engineers, distribution channel partners, and regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from EPA National Emission Standards for Hazardous Air Pollutants filings, ECHA SVHC candidate list updates, SEC 10-K disclosures from listed tape manufacturers, Japanese Ministry of Economy Trade and Industry JIS specification databases, and China customs trade data for polyester and polyimide film substrate flows. Bottom-up segment sizing triangulated against top-down electronics assembly and automotive production forecasts.
Segment-level projections across product type, end user, application, and thickness dimensions fed into an analytical framework spanning the projection horizon. CAGRs were derived from elasticity-adjusted demand curves that linked semiconductor packaging miniaturization mandates to bonding interface tolerance compression. Industry-specific inputs included die-attach equipment cycle time synchronization requirements and clean-room air exchange emission control cost structures.
Petrochemical feedstock volatility, East Asian export licensing delays, and multi-jurisdiction certification parallelism extending qualification timelines are the dominant revision risks that could shift volume and value trajectories. Forecasts reflect documented assumptions about continued device miniaturization and automotive interior electrification adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Carbon Tapes Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Twist Tube Market
Tapes
BOPP Packaging Tapes Market
Tapes
Replica Tapes Market
Tapes
Application Tapes Market
Tapes
Tape Backing Materials Market
Tapes
Differential Tapes Market
Tapes
Custom Printed Tape Market
Tapes
Removal Strips Market
Tapes
Europe Packaging Tapes Market
Tapes
Coding Foils and Tapes Market
Tapes
Washi Tapes Market
Tapes
Gaffers Tape Market
Tapes
Spacer Tapes Market
Tapes
Tapes Market