
 Battery Packaging Material Market | 2026-2036
Battery Packaging Material Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Packaging Material Market Intelligence
A divergence in capital investment for high-performance polymer synthesis versus standardized packaging fabrication is bifurcating the competitive landscape. Large chemical firms like Covestro AG leverage extensive R&D infrastructure to develop advanced polymer films. In contrast, packaging specialists such as NEFAB GROUP differentiate through custom-engineered solutions for logistics and safety. Söhner Kunststofftechnik GmbH occupies a niche by focusing on thermoformed plastic components for battery modules.
Battery packaging materials encompass a range of specialized films, foils, and plastics used to encase and protect individual battery cells and modules. These materials, including aluminum foil current collectors and polymer separators, must provide electrical insulation, thermal stability, and structural integrity. Within material types, aluminum and copper foils remain foundational, while advanced polymers like Polyvinylidene Fluoride gain share for high-performance applications. The Electric Vehicles application segment commands the majority of material volume, eclipsing traditional consumer electronics.
Regulatory frameworks governing the transport of dangerous goods, such as rules from the US Department of Transportation and UN recommendations, dictate packaging strength and labeling requirements. In Europe, directives related to battery safety and end-of-life management under the EU Green Deal influence material choices. These regulations mandate specific performance criteria for thermal runaway prevention and impact resistance. Navigating the trade-off between material performance, cost, and recyclability remains the central challenge for suppliers.
Market Dynamics
The central dynamic shaping the market is the intense pressure to reconcile conflicting demands from the electric vehicle sector. Automakers require lighter, safer, and higher-performing packaging to extend vehicle range, while regulators simultaneously impose stricter rules on material recyclability and end-of-life management.
Growth Catalysts
- Advanced Polymer Development:The synthesis of high-performance polymers, such as fire-retardant polycarbonates and advanced polyvinylidene fluoride (PVDF) films, provides superior thermal management and electrical insulation, enabling higher-density battery pack designs for electric vehicles.
- EU Battery Regulation:Mandates under the EU Green Deal regarding battery passports, recycled content quotas, and end-of-life collection are compelling producers to adopt new packaging materials and designs that facilitate easier disassembly and material recovery.
- EV Production in China:The immense concentration of global battery cell and pack manufacturing within China's industrial ecosystem creates a massive, centralized demand source for all types of packaging materials, from aluminum foils to thermoformed plastic casings.
Market Restraints
- Raw Material Volatility:The fluctuating costs of key inputs, particularly aluminum and copper for current collector foils, create significant price instability for packaging suppliers and can erode margins, especially in the more commoditized segments of the market.
- Thermal Management Trade-offs:A persistent technical restraint is the difficulty in developing materials that are simultaneously lightweight, cost-effective, and capable of preventing thermal runaway propagation, forcing compromises between safety performance and vehicle weight targets.
- Alternative Pack Architectures:The emergence of cell-to-pack and cell-to-chassis battery designs in the EV industry poses a substitution threat, as these integrated approaches can reduce or entirely eliminate the need for traditional module-level packaging components.
Strategic Opportunities
- Energy Storage Systems (ESS):The expansion of grid-scale and residential battery storage presents a significant opportunity for packaging materials optimized for stationary applications, which prioritize longevity, thermal stability, and cost over the lightweighting demands of the automotive sector.
- US Inflation Reduction Act (IRA):Tax credits and sourcing requirements within the IRA create a strong incentive for establishing a domestic battery packaging supply chain in North America, offering a key opening for regional material manufacturers.
- Bio-based and Recycled Polymers:There is a growing white-space opportunity for developing and commercializing high-performance, bio-based, or recycled-content polymers that meet stringent automotive safety standards while satisfying sustainability mandates and corporate ESG goals.
Industry Challenges
- Global Standards Harmonization:Suppliers face the operational complexity of designing and validating packaging that meets disparate and evolving international transport regulations for dangerous goods, including rules from the UN, the US Department of Transportation, and IATA.
- Specialized Synthesis Capacity:The high capital expenditure needed to build and operate facilities for advanced polymer synthesis and film extrusion creates a significant barrier to entry and a challenge for scaling production to meet surging EV demand.
- Lack of Form Factor Standardization:The wide variation in battery cell and module formats across different automotive OEMs prevents packaging suppliers from achieving economies of scale through standardized product lines, requiring costly custom-tooling for each new platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Packaging Material Market |
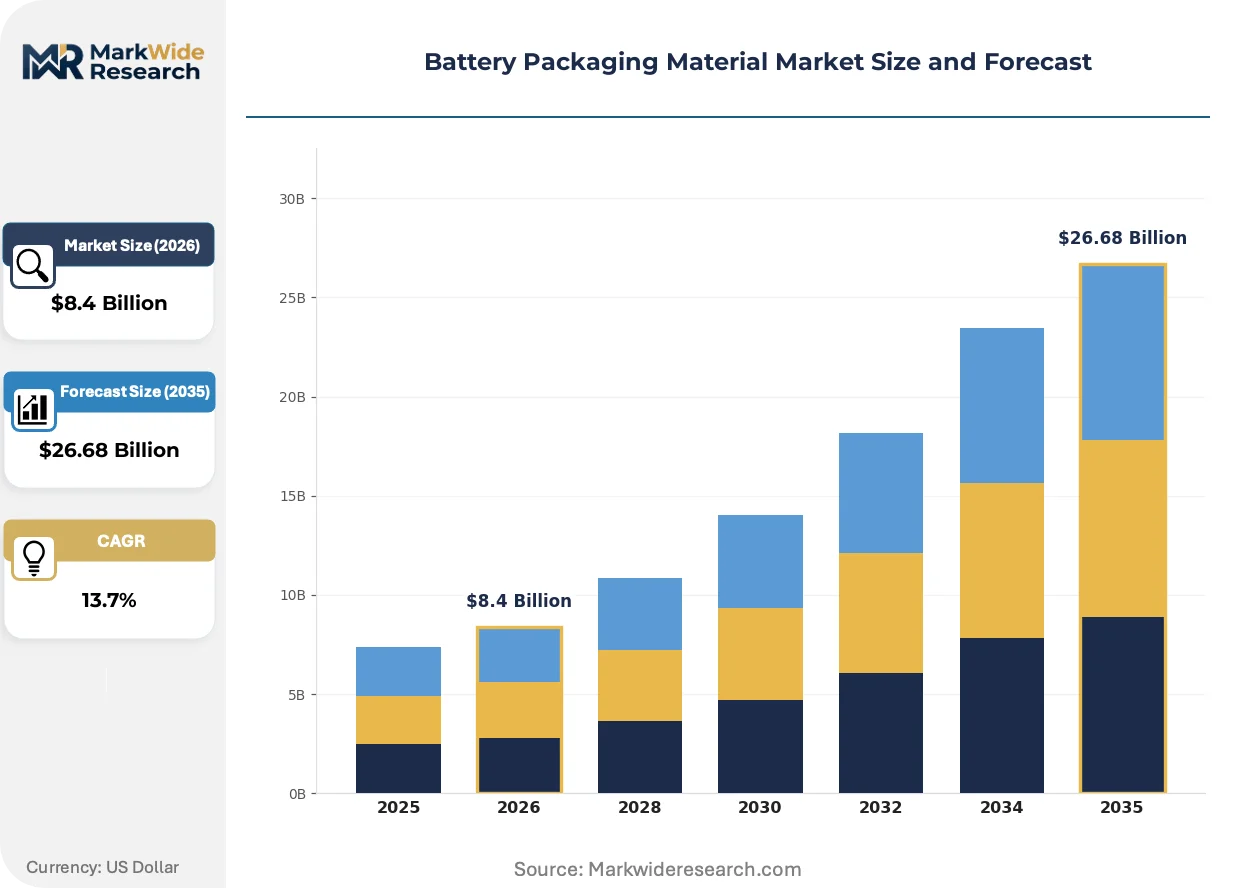
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Aluminum Foil, Copper Foil, Polyethylene Terephthalate, Nylon, Polyvinylidene Fluoride Packaging Form: Blister Packs, Pouch Bags, Vacuum Sealed Packs, Rigid Boxes, Shrink Wrap, Clamshell Packaging Application: Electric Vehicles, Consumer Electronics, Energy Storage Systems, Aerospace, Wearable Devices, Power Tools End User Industry: OEM Battery Manufacturers, Aftermarket Suppliers, Electronic Device Makers, Renewable Energy Providers, Power Equipment Industries, Tool Manufacturers |
| Companies Covered | DGM, GWP Protective, NEFAB GROUP, Covestro AG, Manika Plastech Pvt. Ltd., Wellplast AB, Söhner Kunststofftechnik GmbH, Labelmaster, C.L. Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Packaging Material Market Strategic Shifts & Innovations
Material science innovation is bifurcating along two distinct paths. One path pursues higher performance through advanced composites and integrated electronics for safety, while the other focuses on designing for disassembly and recyclability to align with circular economy principles and emerging regulations.
Integrated sensor films, which embed thermal monitoring capabilities directly into dielectric separator or insulation layers, are a key product evolution. High-performance battery designers in the electric vehicle and aerospace sectors are the primary adopters of this technology. The fusion of sensing and insulation functions is miniaturizing the external battery management system hardware, freeing up critical volume and weight within the battery pack.
China's GB standards governing electric vehicle safety now impose some of the world's most stringent thermal runaway propagation test requirements. This regulatory pressure is forcing material suppliers to incorporate higher concentrations of fire-retardant additives and develop novel ceramic-coated separator films. The policy directly impacts any supplier of polymer films, foams, and metal casings aiming to compete within China's dominant battery manufacturing ecosystem.
A shift toward total lifecycle cost analysis is altering material selection criteria among large-scale battery producers and automotive OEMs. This change moves procurement decisions beyond upfront price to weigh factors like ease of disassembly for repair, material recovery value, and compliance with end-of-life mandates. This trend is most pronounced in Europe, where the EU Battery Regulation provides a clear economic framework for prioritizing circular design.
Battery Packaging Material Market Segmentation
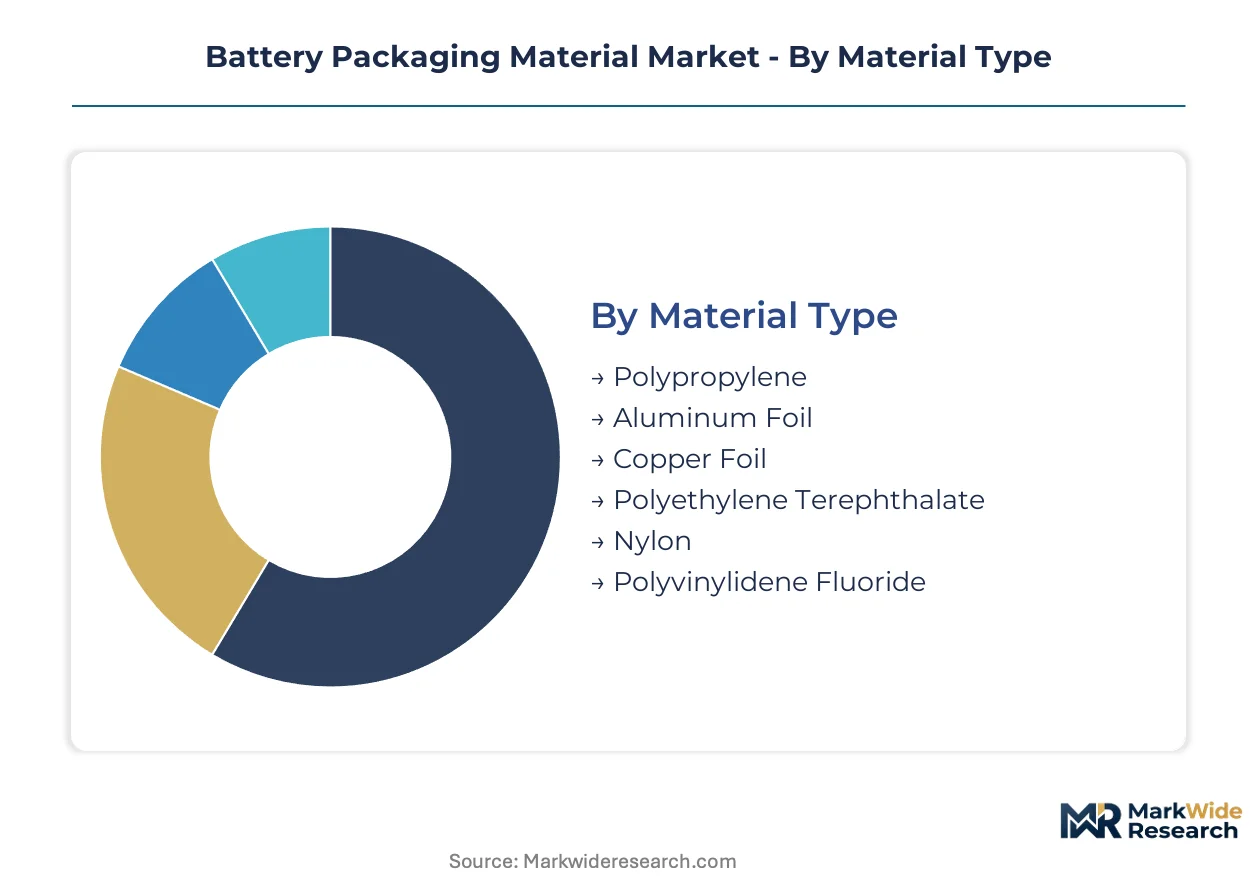
The Battery Packaging Material market is segmented to provide a granular view of material compositions, packaging formats, end-use applications, and the industries driving demand. Understanding these segments reveals specific growth pockets and evolving technical requirements across diverse battery technologies.
Material Type:
Material type segments exhibit varying levels of localized production versus global trade, influenced by raw material availability and processing infrastructure.
- Aluminum Foil:A lightweight metallic conductor, aluminum foil serves as a current collector and structural component in battery cells. Demand concentrates heavily within China's dominant battery manufacturing hubs, driven by cost-efficiency and large-scale cell production.
- Polyvinylidene Fluoride:PVDF is a high-performance fluoropolymer used for battery separators and binders, offering excellent chemical and thermal stability. Its adoption is accelerating in Europe and Japan for advanced EV battery designs requiring superior safety and longevity.
- Polypropylene:This thermoplastic polymer is widely used for battery casings and separators, valued for its chemical resistance and low cost in various cell formats.
- Copper Foil:Copper foil functions as a critical current collector in lithium-ion batteries, primarily sourced from specialized manufacturers in East Asia for global cell production.
- Polyethylene Terephthalate:PET films provide electrical insulation and structural support for battery modules, finding use in both consumer electronics and smaller EV packs.
- Nylon:Nylon polymers offer robust mechanical strength and impact resistance for structural battery components, particularly in demanding industrial applications.
Aluminum Foil holds the largest share; momentum sits with Polyvinylidene Fluoride.
Packaging Form:
Packaging forms are largely dictated by the specific battery chemistry and the end application's safety, weight, and thermal management requirements.
- Pouch Bags:Flexible, lightweight laminates that encase battery cells, offering excellent energy density and thermal dissipation for portable electronics and some EV applications. Their design facilitates compact module integration.
- Rigid Boxes:Robust enclosures, often made of plastic or metal, designed to protect battery modules and packs from external impact and thermal events. These are crucial for large EV battery systems and stationary energy storage.
- Blister Packs:Pre-formed plastic cavities with a cardboard backing, primarily used for retail packaging of individual consumer batteries.
- Vacuum Sealed Packs:Air-tight packaging solutions that prevent moisture ingress and oxidation, extending the shelf life of sensitive battery components and cells.
- Shrink Wrap:Thin polymer films that conform tightly to battery packs when heated, providing basic protection and containment for transport.
- Clamshell Packaging:Hinged, two-piece plastic containers that fully enclose a product, frequently used for consumer battery products requiring tamper-evident protection.
Pouch Bags demonstrate widespread use across portable devices, while Rigid Boxes show rapid expansion for high-capacity EV batteries.
Application:
Application segments reflect where the highest volume and value of battery packaging materials are consumed, driven by electrification trends.
- Electric Vehicles:This segment commands the largest share of battery packaging materials, demanding solutions for thermal management, impact resistance, and lightweighting. Regulations like the EU Battery Regulation heavily influence material selection for EVs.
- Energy Storage Systems:Stationary ESS require packaging materials optimized for long operational life, thermal stability, and cost-effectiveness in grid-scale and residential installations. The US Inflation Reduction Act incentives boost demand for these systems.
- Consumer Electronics:Devices like smartphones and laptops utilize compact, lightweight packaging materials that prioritize energy density and form factor.
- Aerospace:High-performance battery packaging in aerospace applications demands extreme thermal stability and lightweight composites for safety and efficiency.
- Wearable Devices:Ultra-compact and flexible packaging solutions are essential for the miniature batteries found in smartwatches and fitness trackers.
- Power Tools:Robust and impact-resistant packaging protects battery packs in demanding power tool environments, ensuring durability and user safety.
Electric Vehicles represent the primary demand driver; Energy Storage Systems are experiencing a significant surge in material consumption.
End User Industry:
End-user industries define the specific procurement channels and technical specifications for battery packaging materials within the supply chain.
- OEM Battery Manufacturers:These companies directly integrate packaging materials into their cell and module production lines, requiring high-volume, standardized, and custom-engineered solutions. Their demand is concentrated in China's vast manufacturing ecosystem.
- Electronic Device Makers:Manufacturers of consumer electronics and other devices procure packaged battery cells or modules, focusing on compact designs and aesthetic integration. They often work with specialized packaging suppliers for custom form factors.
- Aftermarket Suppliers:These entities provide replacement battery packs and components, requiring packaging that meets diverse specifications for older models.
- Renewable Energy Providers:Companies deploying solar and wind energy systems drive demand for packaging materials used in large-scale grid and residential battery storage.
- Power Equipment Industries:Manufacturers of industrial machinery and heavy equipment require robust battery packaging solutions for high-power applications.
- Tool Manufacturers:Producers of cordless power tools need durable, impact-resistant packaging for their removable and integrated battery packs.
OEM Battery Manufacturers exert the most influence on material specifications, while Renewable Energy Providers are a rapidly expanding customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for battery packaging materials varies significantly across applications. While consumer electronics packaging often prioritizes cost-efficiency, the electric vehicle sector demands higher performance and safety, driving less price-sensitive material selection. Stationary energy storage systems balance longevity with cost, creating distinct procurement dynamics.
China
China's vast electric vehicle production and battery cell manufacturing ecosystem generates immense demand for packaging materials. The country's GB standards impose stringent thermal runaway propagation test requirements, influencing material specifications. Battery manufacturing hubs within the Yangtze River Delta concentrate demand for aluminum foils and advanced polymer casings.
Germany
Germany, as a central European automotive hub, drives demand for high-performance battery packaging in advanced EV designs. The EU Battery Regulation and EU Green Deal directives significantly influence material choices, emphasizing recyclability. Chemical firms in regions like Bavaria are developing specialized polymer films for thermal management.
United States
The United States experiences demand for battery packaging materials driven by incentives for domestic battery production and energy storage systems. The US Inflation Reduction Act (IRA) encourages regional sourcing and manufacturing capabilities. New battery manufacturing facilities in the Southeast are increasing procurement of robust packaging solutions.
South Korea
South Korea's robust lithium-ion battery manufacturing sector fuels demand for specialized current collectors and high-performance separators. Local safety standards for battery packs mandate specific material properties for thermal stability and impact resistance. Major battery producers in Gyeonggi Province are investing in advanced packaging for next-generation cells.
Battery Packaging Material Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape for battery packaging materials. This market structure features a bifurcation between large chemical firms and niche packaging engineering companies. Archetypes include material innovators, custom solution providers, and specialized component manufacturers. Dominant competitive moves involve strategic partnerships for new material development and capacity expansion to meet surging EV demand.
Within the material innovation archetype, Covestro AG, a large chemical firm, exemplifies leveraging extensive R&D infrastructure for advanced polymer films. This company's global presence allows for significant investment in next-generation polymer synthesis, particularly for high-performance applications. NEFAB GROUP, a packaging specialist, represents custom-engineered solutions for logistics and safety across diverse applications, differentiating through bespoke design and supply chain integration. Söhner Kunststofftechnik GmbH occupies a niche by focusing on thermoformed plastic components for battery modules, anchoring its position in specialized manufacturing for specific battery form factors and thermal management. These players collectively illustrate the varied approaches to market engagement.
| Leading Market Players |
|---|
| DGM |
| GWP Protective |
| NEFAB GROUP |
| Covestro AG |
| Manika Plastech Pvt. Ltd. |
| Wellplast AB |
| Söhner Kunststofftechnik GmbH |
| Labelmaster |
| C.L. Smith |
| Others |
Cost & Logistics Intelligence
Large-scale battery cell manufacturing facilities drive significant economies of scale, concentrating demand for packaging materials and influencing price floors. This scale-driven procurement consolidates supply chains for foundational materials like aluminum foil and polypropylene.
Pricing Analysis
After-sales service contracts for battery pack repair and refurbishment drive significant lifetime value for packaging specialists. The dominant pricing model for high-performance materials is contract-based long-term offtake, with differentiation based on fire-retardancy and compliance with the EU Battery Regulation. Pricing softness across commoditized segments reflects raw material volatility for aluminum and copper foils. OEM Battery Manufacturers remain least price-sensitive for critical safety components, unlike consumer electronics makers.
Supply Chain Analysis
Specialized polymer synthesis capacity in Germany underpins the supply of advanced PVDF films for high-performance battery packaging. The supply chain concentrates heavily in China, South Korea, and Japan, reflecting their dominance in battery cell manufacturing and reliance on aluminum and copper foils. Single-source vulnerability for specialized chemical precursors represents a structural risk. Distribution channels primarily run through direct sales to OEM Battery Manufacturers and electronic device makers, often involving custom-engineered solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The battery packaging material market is experiencing a platform-economics inflection, driven by the emergence of integrated cell-to-pack and cell-to-chassis architectures. This shift demands new interoperability standards between material suppliers and battery designers.
For Market Incumbents: Shield existing market share by accelerating R&D into advanced polymer films that directly address thermal runaway prevention, a critical threat from evolving EV battery designs. Pursue strategic partnerships with major OEM Battery Manufacturers to co-develop packaging solutions for next-generation cell formats. Invest in capacity expansion for specialized synthesis in North America, leveraging the US Inflation Reduction Act incentives. This strategy mitigates substitution threats from alternative pack architectures.
For New Entrants and Emerging Players: Lifecycle material recovery and recyclability services represent a significant service-layer gap where incumbents under-serve. Target the Energy Storage Systems segment with bio-based and recycled polymer solutions, which aligns with sustainability mandates and offers a penetrable entry point. Develop modular, customizable packaging components that simplify disassembly and material separation for end-of-life processing. A direct-to-developer go-to-market angle for grid-scale projects could bypass established automotive supply chains.
For Investors and Strategic Acquirers: Specialized thermoforming and extrusion firms with proprietary material formulations offer compelling acquisition targets for long-term viability over the next decade. These companies often possess unique intellectual property in high-performance polymers or integrated sensor films. Prioritize targets demonstrating strong R&D pipelines for thermal runaway prevention and advanced recyclability. The signal to watch is the increasing adoption rate of integrated sensor films in new EV platforms, indicating a shift towards higher-value packaging components.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Polymer R&D Partnership | Co-developing next-generation fire-retardant polymers with OEM Battery Manufacturers directly addresses stringent thermal runaway standards. |
| Capacity Expansion in North America | Establishing new manufacturing facilities leverages US Inflation Reduction Act incentives and secures regional supply chains for battery producers. |
| Bio-based Material Commercialization | Introducing high-performance bio-based polymers meets EU Battery Regulation sustainability mandates and attracts environmentally conscious automotive OEMs. |
| Integrated Sensor Film Development | Embedding thermal monitoring capabilities into packaging layers reduces external BMS hardware, freeing critical volume for EV battery designers. |
| Disassembly-Optimized Design Investment | Prioritizing packaging designs that facilitate easier material recovery supports circular economy principles and end-of-life management directives. |
Research Approach
The analysis maps battery packaging material sub-sectors, including aluminum foil, PVDF, and rigid boxes, each validated through primary interviews with R&D directors, procurement leads, and regulatory compliance officers. Insights from battery cell manufacturers and automotive OEMs inform this. Secondary validation draws from UN transport regulations, EU Green Deal directives, and company financial filings. Bottom-up data aggregation and top-down market sizing ensure robust triangulation.
Outputs were consistently checked against external industry benchmarks, including EV production forecasts and energy storage deployment targets, to ensure accuracy across the analysis window. The analytical framework models market dynamics across material type, packaging form, application, and end-user industry. Compound annual growth rates derive from a weighted average of segment-specific expansion trajectories, with forecast inputs including projected battery cell manufacturing capacity and regulatory impacts.
Forecasts assume regulatory continuity in key regimes like the EU Battery Regulation and US Inflation Reduction Act; material policy shifts would require re-modeling. These projections reflect current technological trajectories. Practitioners should keep alternative scenarios live as battery chemistries and pack architectures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Liquid Encapsulation Market
Packaging Materials
Packaging Materials Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
Postal Packaging Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Die Cut Support Pads Market
Packaging Materials
Europe Consumer Packaging Market
Packaging Materials
Lid Laminates Market
Packaging Materials
Global Strapping Market
Packaging Materials
Single Dose Detergent Packaging Market
Packaging Materials
Plastic Strapping Materials Market