
 Food Packaging Machinery Market | 2026-2036
Food Packaging Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Food Packaging Machinery Market Analysis
Premium-grade sanitary specifications is rotating demand toward stainless-steel-intensive designs with IP69K washdown ratings. Ishida leverages its weighing technology leadership to anchor high-speed snack packaging lines across Asia-Pacific installations. Syntegon sustains its position through deep specialization in pharmaceutical-grade barrier systems now migrating into fresh dairy applications. Tetra Pak dominates aseptic carton filling with captive control over laminated packaging material supply, creating differentiated lock-in for beverage processors.
Food packaging machinery comprises electromechanical systems that form, fill, seal, label, and palletize consumable products within controlled atmospheres or vacuum conditions, typically operating at throughputs exceeding 200 units per minute with contamination prevention protocols. These systems serve commercial food manufacturers by extending shelf stability, ensuring portion accuracy, and enabling regulatory traceability across batch records. Horizontal flow wrapper configurations retain mature volume leadership in bakery and confectionery applications where product fragility demands gentle handling mechanisms. Robotic technology segments are expanding fastest in protein processing plants, where vision-guided pick-and-place modules address labor variability and ergonomic injury risks. Flexible packaging type machinery commands concentrated margin pools as film substrate innovations require constant retrofitting of sealing temperature profiles and tension controls.
CE marking under the EU Machinery Directive and FDA's 21 CFR Part 110 Good Manufacturing Practice regulations impose sanitary design mandates that filter non-compliant equipment from transatlantic market access. EFSA migration testing protocols for food-contact materials further constrain seal bar coating selections and lubricant specifications in European installations. Stakeholders must monitor how the EU Packaging and Packaging Waste Regulation's recyclability targets will force retrofit cycles on legacy forming and sealing equipment before compliance deadlines crystallize.
Market Dynamics
Fresh food processors are expanding automated line investments to meet shelf-life and traceability requirements, while EU Green Deal packaging waste directives accelerate machinery upgrades toward recyclable-compatible formats across European installations.
Growth Catalysts
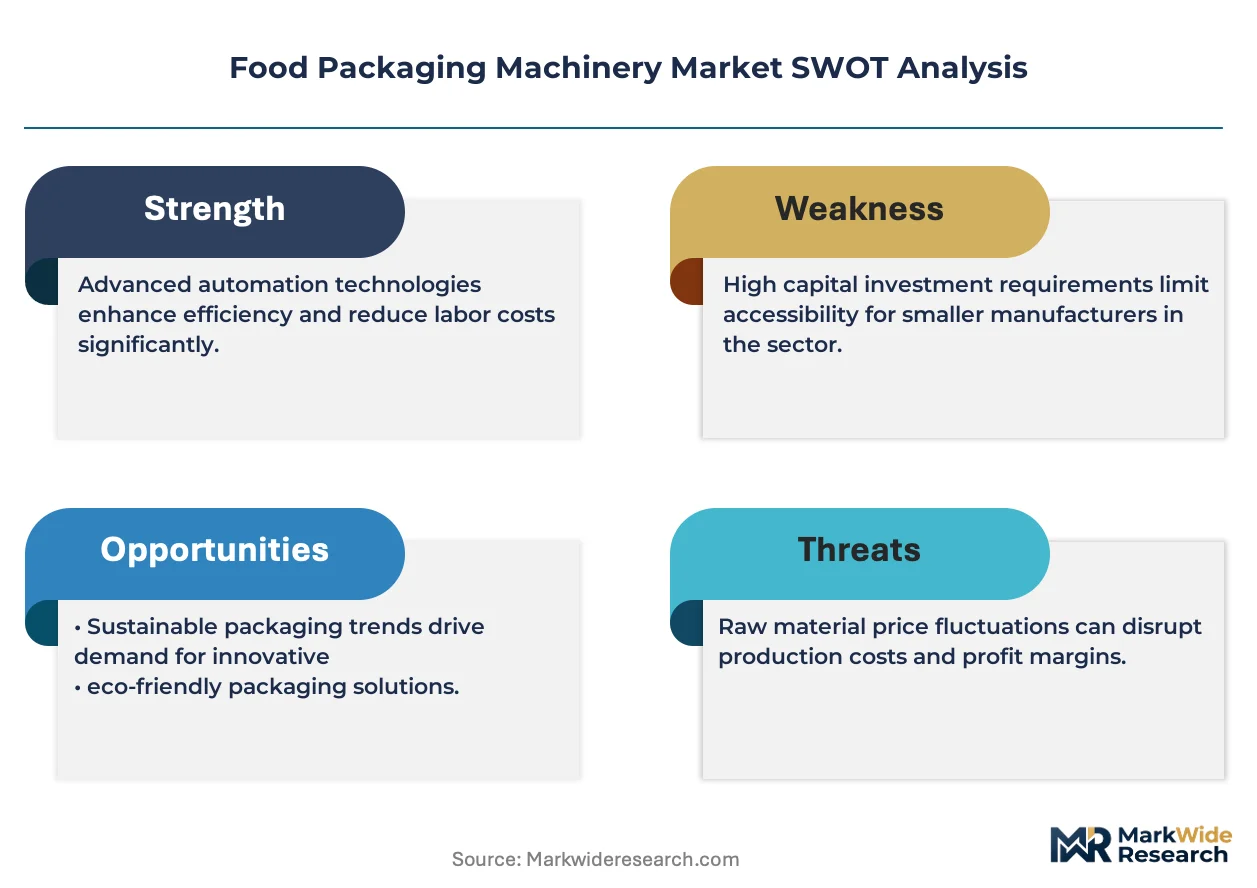
- EU Packaging and Packaging Waste Regulation:Recyclability targets for 2030 and 2035 force retrofit cycles on legacy forming and sealing equipment, creating sustained replacement demand across dairy and beverage processors.
- Robotic protein handling:Vision-guided pick-and-place modules address labor variability and ergonomic injury risks in meat and seafood processing plants, driving line automation investments.
- Stainless-steel IP69K specifications:Premium-grade sanitary designs with washdown ratings rotate demand toward corrosion-resistant electromechanical systems in ready-to-eat food manufacturing.
Market Restraints
- Specialized alloy supply concentration:High-grade stainless steel and seal bar coating materials face sourcing constraints from concentrated metallurgical suppliers, creating input cost volatility for machinery fabricators.
- EFSA migration testing protocols:Food-contact material compliance requirements constrain lubricant specifications and seal surface treatments, extending validation timelines for European market entry.
- Technical retrofit complexity:Legacy horizontal flow wrappers in bakery and confectionery applications require extensive mechanical reconfiguration to accommodate flexible film substrate innovations, limiting upgrade feasibility.
Strategic Opportunities
- Pharmaceutical-grade barrier migration:Barrier system technologies from pharmaceutical packaging are penetrating fresh dairy applications, opening margin-rich equipment categories for specialized vendors.
- Asia-Pacific snack automation:High-speed weighing and packaging line demand concentrates in snack manufacturing clusters across the region, offering expansion vectors for integrated system providers.
- Aseptic carton format diversification:Beverage processors seek alternatives to captive laminated material supply structures, creating openings for independent filling equipment with broader substrate compatibility.
Industry Challenges
- Electromechanical technician scarcity:Servo drive programming and vision system calibration skills lag demand in food manufacturing regions, constraining line commissioning and maintenance capacity.
- CE marking and FDA 21 CFR Part 110 dual compliance:Sanitary design mandates for transatlantic market access require parallel validation documentation, extending product development cycles for mid-scale equipment builders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Packaging Machinery Market |
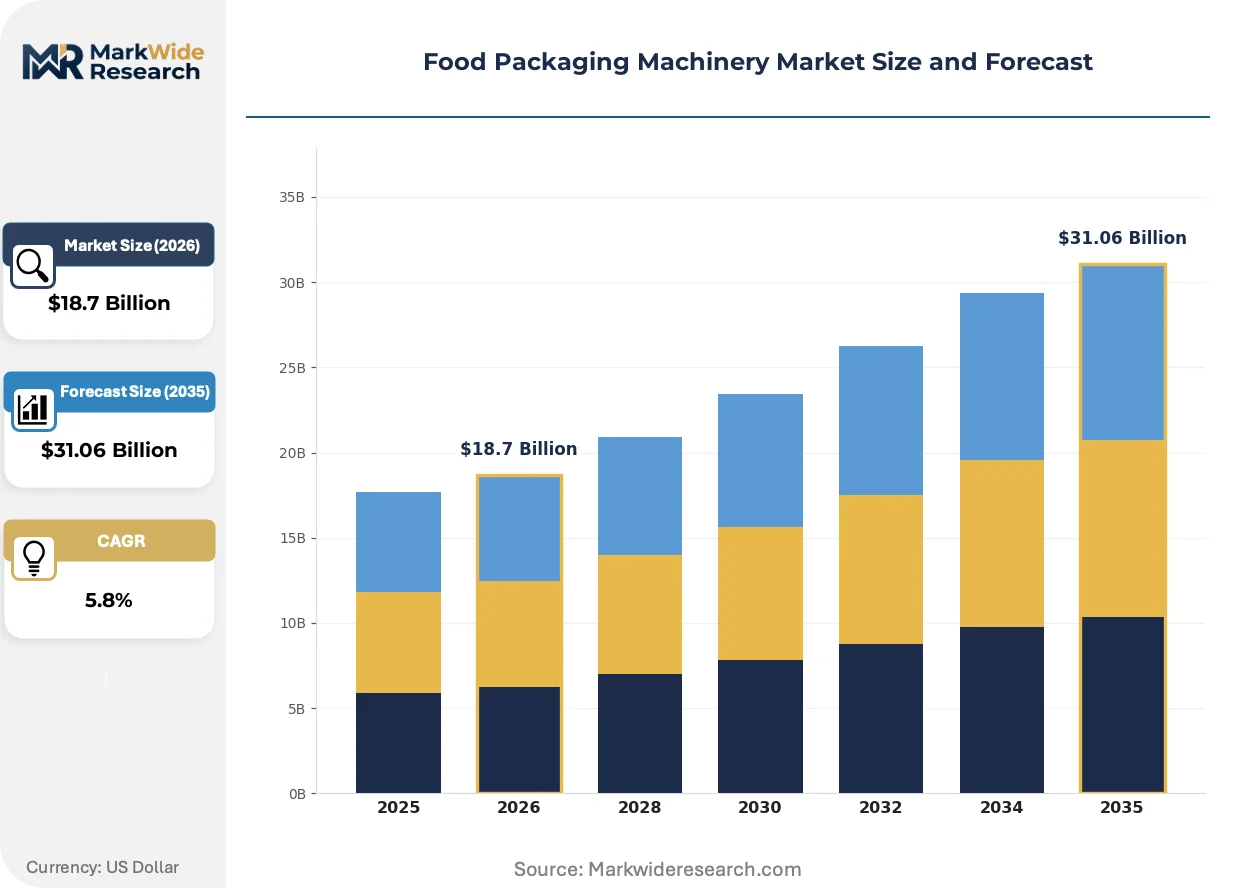
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Flow Wrapper, Vertical Form Fill Seal, Tray Sealing Machine, Labeling Machine Technology: Automatic, Semi-Automatic, Robotic, Manual End User: Food Manufacturers, Beverages, Snacks, Confectionery Packaging Type: Flexible, Rigid, Semi-Rigid, Others |
| Companies Covered | Ishida, IMA Group, Syntegon, ProMach, Coesia, Tetra Pak, Krones Group, Sidel, Multivac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Packaging Machinery Market Emerging Trajectories
Electromechanical architectures and control systems are undergoing fundamental redesign as food manufacturers pursue throughput acceleration alongside contamination prevention protocols.
Ultrasonic sealing technology is displacing conventional heat-bar systems in flexible packaging lines. Fresh produce and protein processors adopt these cold-seal mechanisms to preserve film barrier integrity and reduce energy consumption. The displacement of thermal sealing infrastructure is compressing retrofit timelines and forcing incumbent vendors to reengineer tension control subsystems.
CE marking under the EU Machinery Directive now incorporates extended producer responsibility provisions for packaging waste alignment. Industrial consequence includes mandatory design-for-recyclability documentation for forming and sealing equipment sold into member states. Fresh dairy and beverage packaging lines face the most acute compliance pressure, with German engineering clusters developing modular retrofit kits to preserve installed base value.
Buyer consolidation among pan-European food manufacturers concentrates procurement leverage with integrated line suppliers. Regional co-manufacturing networks and private-label specialists are displacing fragmented equipment purchasing through centralized capital planning. This concentration is most visible in Germany, where engineering clusters supply complete automated lines rather than standalone machines.
Food Packaging Machinery Market Segmentation
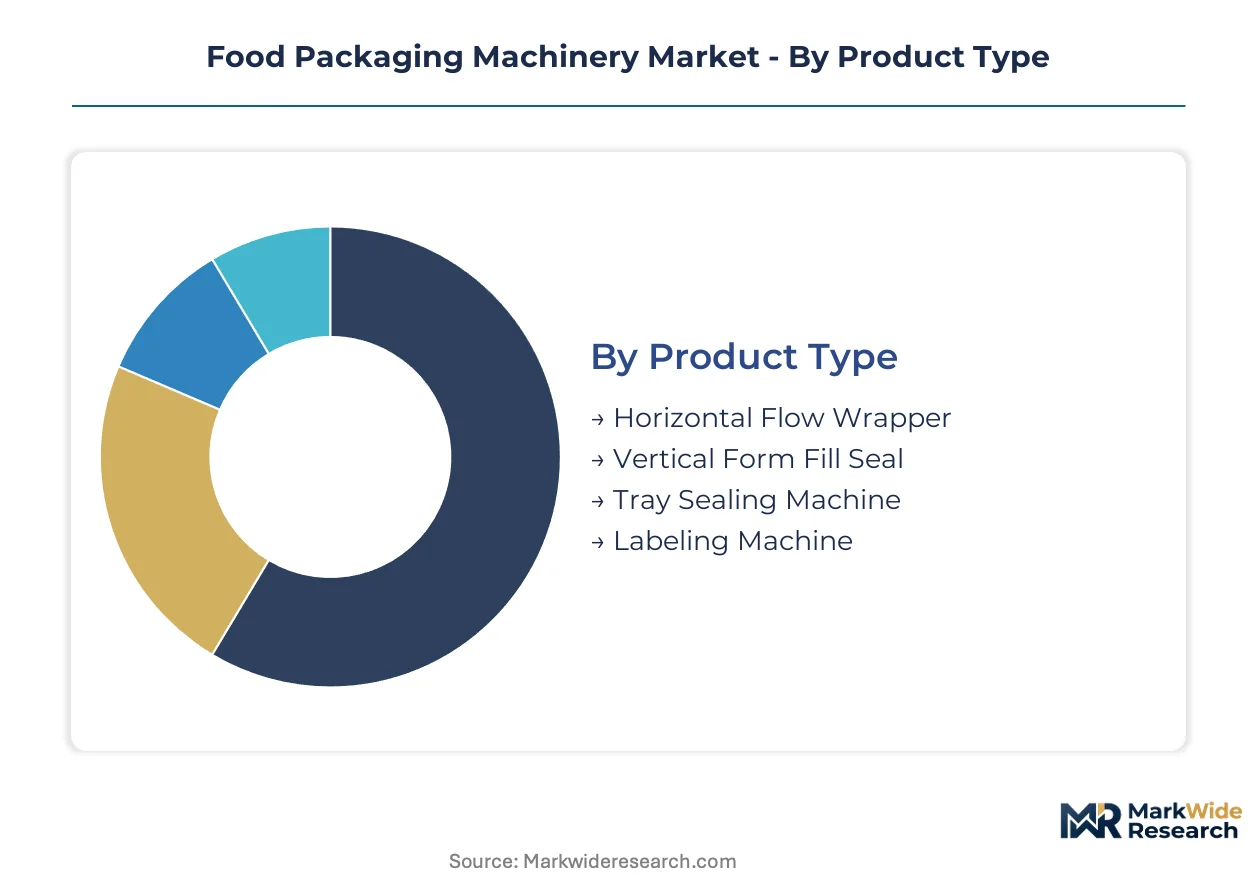
Food packaging machinery procurement channels diverge sharply by operational scale and compliance burden. Large processors favor integrated line suppliers for capital efficiency, while regional co-manufacturers source standalone units through specialized distributors.
Product Type:
Horizontal flow wrappers and vertical form fill seal systems anchor distinct channel strategies, with bakery and confectionery demand flowing through engineering clusters while protein processors direct procurement toward stainless-steel specialists.
- Horizontal Flow Wrapper:Electromechanical systems with rotary jaw sealing mechanisms and servo-driven film transport achieve throughputs exceeding 300 units per minute on fragile bakery products. German engineering clusters supply integrated wrapper-labeler-palletizer lines to pan-European confectionery manufacturers facing EU Green Deal retrofit deadlines.
- Vertical Form Fill Seal:Continuous-motion bagging systems with ultrasonic sealing heads accommodate film substrate innovations for fresh produce applications. Vision-guided tension controls address seal integrity requirements in protein processing plants where contamination protocols mandate IP69K washdown ratings.
- Tray Sealing Machine:Modified atmosphere packaging systems with vacuum-gas flush cycles extend shelf stability for ready-to-eat meals.
- Labeling Machine:Pressure-sensitive and shrink-sleeve applicators integrate serialization for regulatory traceability mandates.
Horizontal flow wrappers dominate installed base across mature bakery applications. Vertical form fill seal systems are where expansion concentrates in fresh protein and produce segments.
Technology:
Automation tier selection correlates with labor cost structures and batch complexity, with robotic modules commanding premium positioning in high-variability protein handling while semi-automatic units serve private-label specialists with shorter production runs.
- Automatic:Servo-driven electromechanical architectures with programmable logic controllers and human-machine interfaces enable changeover times under three minutes. Fresh dairy processors in Germany deploy automatic lines to meet EFSA migration testing protocols for food-contact materials.
- Robotic:Six-axis articulated arms with 3D vision systems execute pick-and-place operations in meat and seafood plants. These installations address ergonomic injury risks and labor variability while achieving placement accuracy within 0.5 millimeters.
- Semi-Automatic:Operator-assisted loading with automated sealing cycles suits regional co-manufacturers with multi-SKU flexibility requirements.
- Manual:Foot-pedal or hand-operated units serve artisanal producers and pilot-scale validation facilities.
Automatic systems anchor volume leadership in beverage and dairy applications. Robotic technology is climbing the fastest in protein processing installations.
End User:
End-use concentration shapes equipment specification divergence, with snack manufacturers prioritizing weighing accuracy and beverage processors demanding aseptic barrier integrity.
- Food Manufacturers:Integrated processing-packaging lines with CIP/SIP protocols and batch recording systems serve ready-to-eat meal producers. CE marking under the EU Machinery Directive and FDA 21 CFR Part 110 dual compliance requirements filter equipment selection for transatlantic suppliers.
- Beverages:Aseptic carton and bottle filling systems with hydrogen peroxide sterilization tunnels accommodate extended shelf-life requirements. These installations face acute pressure from EU Packaging and Packaging Waste Regulation recyclability targets.
- Snacks:Multi-head weighers with load cell arrays and vertical form fill seal baggers achieve portion accuracy within one gram.
- Confectionery:Gentle-handling horizontal flow wrappers with belt infeed systems preserve product integrity on fragile chocolate and baked items.
Food manufacturers hold the broadest installed base across format categories. Beverage processors are gaining share fastest in aseptic line investments.
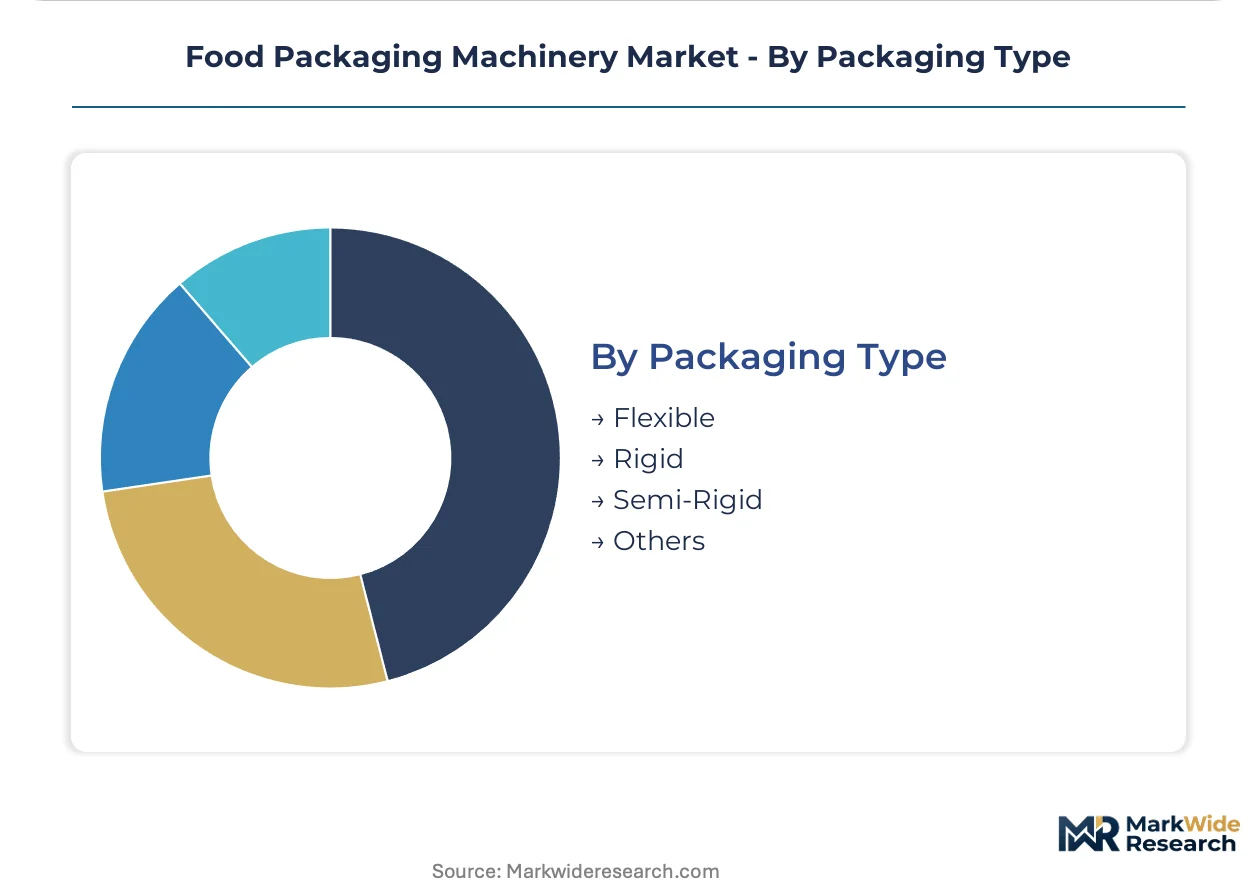
Packaging Type:
Substrate mechanics dictate sealing technology selection and retrofit urgency, with flexible film innovations forcing tension control upgrades while rigid formats concentrate margin in barrier coating applications.
- Flexible:Polymer and laminated film structures with oxygen barrier layers require constant recalibration of sealing temperature profiles and nip roller pressure. Ultrasonic cold-seal mechanisms are displacing thermal bar systems in fresh produce applications to preserve film integrity.
- Rigid:Thermoformed trays, bottles, and cartons with injection-molded closures provide structural protection for fragile and liquid products. These formats face concentrated compliance pressure from EFSA migration testing protocols on seal bar coatings.
- Semi-Rigid:Cup and tub formats with lidding film combinations balance protection with material efficiency for dairy and prepared foods.
- Others:Composite and emerging substrate formats including molded fiber and bio-based barriers.
Flexible packaging commands the deepest retrofit activity. Rigid formats are where margin concentration persists in barrier system specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented machinery fabricators in Germany and Italy supply integrated lines across European food manufacturers, while import-dependent processors in Southeast Asia and Latin America drive aftermarket service demand for Asian-built equipment.
Germany
Engineering clusters around Stuttgart and Munich supply stainless-steel-intensive lines with IP69K washdown ratings to pan-European dairy processors. CE marking under the EU Machinery Directive incorporates extended producer responsibility provisions for packaging waste alignment, forcing design-for-recyclability documentation. Bavarian fabricators develop modular retrofit kits to preserve installed base value amid EU Green Deal compliance deadlines.
United States
Protein processing plants in the Midwest and Southeast deploy robotic pick-and-place modules to address labor variability and ergonomic injury risks. FDA 21 CFR Part 110 Good Manufacturing Practice regulations impose sanitary design mandates that filter non-compliant equipment from market access. Chicago-area integrators concentrate on high-speed snack packaging lines serving private-label specialists.
China
Domestic food manufacturers accelerate automated line investments to meet shelf-life and traceability requirements in fresh produce and ready-to-eat segments. GB standards and SAMR regulations govern food-contact material compliance for machinery sold into domestic processing plants. Yangtze River Delta fabricators supply cost-optimized vertical form fill seal systems to Southeast Asian export markets.
India
Regional co-manufacturing networks in Maharashtra and Gujarat displace fragmented equipment purchasing through centralized capital planning for flexible packaging lines. FSSAI food safety regulations constrain seal bar coating selections and lubricant specifications in domestic installations. Ahmedabad-based distributors serve dairy processors with semi-automatic tray sealing machines for modified atmosphere applications.
Japan
Precision-engineered weighing and packaging systems from Chubu and Kansai regions maintain positioning in high-accuracy snack and confectionery applications. METI industrial standards and JIS specifications govern electromechanical system interoperability in food manufacturing environments. Osaka-area specialists supply ultrasonic sealing technology to fresh produce processors seeking cold-seal mechanisms for film barrier preservation.
Food Packaging Machinery Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and compliance documentation capabilities, creating a tiered structure where scale-driven integrators face off against application-focused boutiques. Publicly traded equipment builders leverage balance sheet capacity for multi-line integrated system deployments. Three archetypes dominate: stainless-steel sanitary specialists, robotic automation integrators, and aseptic barrier system providers. Consolidation pressure manifests through strategic partnerships for regional service coverage and technology licensing for ultrasonic sealing capabilities.
Among European engineering clusters, Syntegon GmbH and Tetra Pak exemplify divergent strategic positions—one representing pharmaceutical-grade barrier migration into fresh dairy, the other anchoring captive material supply structures in beverage aseptic filling. Ishida Co., Ltd. occupies a position within the high-speed weighing specialization tier. These three entities illustrate how geographic origin and corporate structure shape competitive archetype selection without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Ishida |
| IMA Group |
| Syntegon |
| ProMach |
| Coesia |
| Tetra Pak |
| Krones Group |
| Sidel |
| Multivac |
| Others |
Supply Flow & Price Mechanics
Ultrasonic sealing module adoption is displacing thermal bar systems in flexible packaging lines, simultaneously shifting component sourcing toward East Asian electronics clusters and compressing margin structures for European heat-seal subsystem vendors. This substitution dynamic concentrates pricing power with integrated line builders who control vision-guided tension calibration, while standalone sealing equipment fabricators face accelerated obsolescence cycles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in food packaging machinery procurement. Premium stainless-steel IP69K-rated lines from German engineering clusters command substantial premiums over Asian-built alternatives based on CE marking documentation depth and FDA 21 CFR Part 110 dual compliance validation. Cost compression in mid-tier automatic systems is intensifying because Yangtze River Delta fabricators are expanding servo drive manufacturing capacity. Regional co-manufacturers and private-label specialists exhibit highest price sensitivity, while pan-European dairy processors prioritize certification tier over acquisition cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for electromechanical components sourced from Chinese servo motor and programmable logic controller manufacturers. High-grade stainless steel feedstock draws from concentrated metallurgical suppliers in Germany, Sweden, and Japan, creating single-source vulnerability for IP69K washdown-rated fabrication. Seal bar coating materials and food-contact lubricants face regulatory restriction under EFSA migration testing protocols. Distribution runs through engineering clusters in Stuttgart, Munich, and Osaka that supply integrated wrapper-labeler-palletizer lines to pan-European food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food packaging machinery sits at an early-cycle expansion story justified by EU Packaging and Packaging Waste Regulation retrofit deadlines forcing replacement demand across dairy and beverage installed bases before recyclability targets crystallize.
For Market Incumbents: Consolidate position through captive supply of laminated packaging materials following the Tetra Pak model, and acquire ultrasonic sealing technology specialists before substrate innovation accelerates retrofit timelines. Threat from pharmaceutical-grade barrier system migration into fresh dairy applications demands defensive certification investment in EFSA-compliant surface treatments. Capacity addition in Bavarian engineering clusters preserves proximity to pan-European OEM buyers. For New Entrants and Emerging Players: Aftermarket service layer gaps in Southeast Asian protein processing plants offer white-space entry where incumbent vendors under-serve on vision system calibration and servo drive programming. Target semi-automatic tray sealing machine segments in Indian dairy co-manufacturing networks where FSSAI compliance requirements filter out unvalidated imports. Go-to-market through Ahmedabad-based distributors with localized lubricant specification documentation. For Investors and Strategic Acquirers: The market sits at a compliance-driven replacement phase that favors specialized stainless-steel sanitary fabricators with IP69K validation depth over commodity equipment builders. Long-term viability through the next decade hinges on recyclability-compatible format engineering capabilities. Acquisition target archetype: robotic pick-and-place module developers with 3D vision integration for protein handling. Signal to watch: EU Green Deal packaging waste directive enforcement acceleration triggering retrofit contract announcements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laminated Packaging Materials | Captive substrate supply locks beverage processors into aseptic filling equipment ecosystems. |
| Ultrasonic Sealing Technology Licensing | Cold-seal mechanisms preserve film barrier integrity for fresh produce applications under EFSA protocols. |
| Modular Retrofit Kit Development | German engineering clusters preserve installed base value amid EU Green Deal compliance deadlines. |
| Robotic Vision System Partnership | 3D pick-and-place modules address ergonomic injury risks in Midwest protein processing plants. |
| Pharmaceutical-Grade Barrier Migration | Syntegon-style specialization opens margin-rich fresh dairy equipment categories. |
Methodological Framework
Desk research of EU regulatory filings, machinery trade association technical specifications, and EFSA migration testing protocols preceded structured interviews with plant engineers at pan-European dairy processors, procurement leads at snack manufacturing clusters, and aftermarket service heads at Asian equipment distributors. Primary fieldwork with stainless-steel fabrication specialists and servo drive programmers was validated against secondary sources including CE marking documentation databases and FDA 21 CFR Part 110 inspection records. Bottom-up equipment shipment tracking and top-down food manufacturer capital expenditure analysis were triangulated to establish market sizing.
Variance decomposition across the projection horizon isolates volume drivers by product type, automation tier, end-use concentration, and packaging substrate mechanics. Segmentation modeling incorporated horizontal flow wrapper versus vertical form fill seal system demand divergence, robotic versus automatic versus semi-automatic technology adoption curves, and flexible versus rigid versus semi-rigid packaging format retrofit urgency. CAGRs were derived from replacement cycle analysis tied to EU regulatory compliance deadlines and protein processing labor automation penetration rates.
Material uncertainties — tariff exposure on Chinese electromechanical components, EFSA seal bar coating specification revisions, and EU Packaging and Packaging Waste Regulation enforcement timing — sit outside the modeled envelope. Forecasts reflect documented assumptions about stainless-steel alloy availability and vision system technician labor pool expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Pouch Sealing Machine Market
Packaging Machinery
Flow Wrap Machines Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Box Filling Machine Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Global Blister Packaging Machinery Market
Packaging Machinery
Binding & Lamination Machines Market
Packaging Machinery
Shrink Wrapping Machines Market
Packaging Machinery
North America Printing Machinery Market
Packaging Machinery
Face Mask Machines Market
Packaging Machinery
Side Load Case Packing Machines Market