
 Fiber Lids Market | 2026-2036
Fiber Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Lids Market Analysis
Single-source reliance on virgin plastic converters is decoupling as foodservice buyers diversify toward fiber substrate specialists. Huhtamaki Oyj leverages its molded fiber manufacturing footprint across multiple continents to secure volume contracts with global quick-service chains. Stora Enso Oyj anchors Nordic pulp-to-package integration, controlling raw fiber costs that competitors cannot match. Pactiv LLC competes through its established North American distribution network, extending shelf presence in convenience stores and stadium concessions.
Fiber lids are engineered covers manufactured from compressed cellulose pulp, plant fibers, or recycled paperboard, typically formed through thermoforming or press-molding processes to achieve liquid-tight seals across hot and cold beverage applications. Their primary commercial purpose centers on replacing polypropylene and polystyrene closures in foodservice environments where operators face mounting compliance obligations. Plant fiber formulations currently occupy the highest-margin tier within material type segmentation, as buyers pay premiums for agricultural residue substrates that carry compostability certifications. Takeaway solutions represent the fastest-expanding application category, driven by third-party delivery platforms that require spill-resistant packaging for transport.
The US FDA maintains contact-substance safety standards for fiber food-contact materials, while the EPA's waste reduction frameworks indirectly steer procurement toward compostable alternatives; in Europe, the EU Green Deal and F-Gas Regulation create parallel pressure on polymer-dependent supply chains. California's SB 54 and New York's extended producer responsibility laws add state-level compliance layers that fiber lid suppliers must navigate for market access. Stakeholders should monitor how composting infrastructure buildouts in target municipalities affect the realized environmental benefit of fiber lid conversions.
Market Dynamics
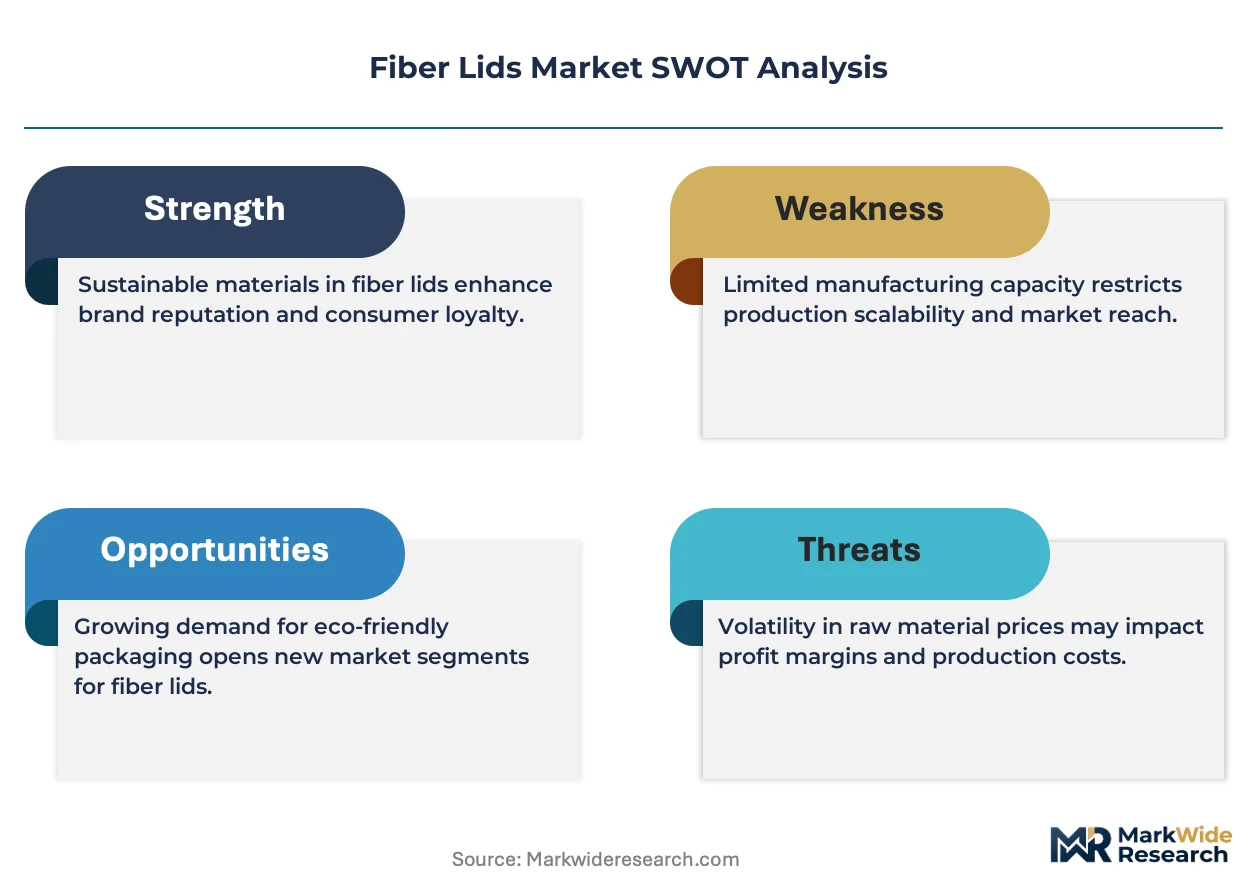
Regulatory mandates are forcing material substitution timelines across foodservice packaging faster than converter capacity can expand, creating supply bottlenecks for compliant fiber lid specifications.
Growth Catalysts
- EU Single-Use Plastics Directive:The directive bans polystyrene lids for takeaway beverages, compelling quick-service chains to secure fiber alternatives before enforcement deadlines.
- Third-party delivery platforms:Spill-resistant fiber lid designs are electrifying adoption as DoorDash and Uber Eats operators demand transport-ready packaging that maintains temperature integrity.
- Agricultural residue pulp:Wheat straw and bagasse formulations are displacing virgin wood pulp as buyers prioritize compostability certifications for waste diversion reporting.
Market Restraints
- Pulp cost volatility:Nordic softwood pulp prices swing with energy costs, compressing margins for converters without backward integration into forestry assets.
- Molded fiber equipment scarcity:Thermoforming press manufacturers in Germany and Finland carry 18-month order backlogs, throttling capacity expansion for new market entrants.
- Performance gaps in hot-fill applications:Fiber lids above 85°C liquid contact risk fiber swelling and seal failure, limiting penetration in specialty coffee segments.
Strategic Opportunities
- India quick-service expansion:Domino's and KFC franchise buildouts in tier-2 cities lack compliant local lid supply, creating first-mover openings for molded fiber specialists.
- Home composting certification:TÜV Austria's OK Compost HOME standard unlocks premium pricing from sustainability-focused café chains in Germany and the Netherlands.
- RFID-embedded traceability:Combining fiber substrates with printed electronics enables supply chain authentication for circular economy compliance tracking.
Industry Challenges
- Mold design engineering shortage:Fewer than 200 engineers globally possess deep expertise in fiber flow simulation for complex lid geometries with sip-hole integration.
- Multi-certification timelines:Achieving simultaneous FDA food-contact, BPI compostability, and FSC chain-of-custody approvals extends product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Lids Market |
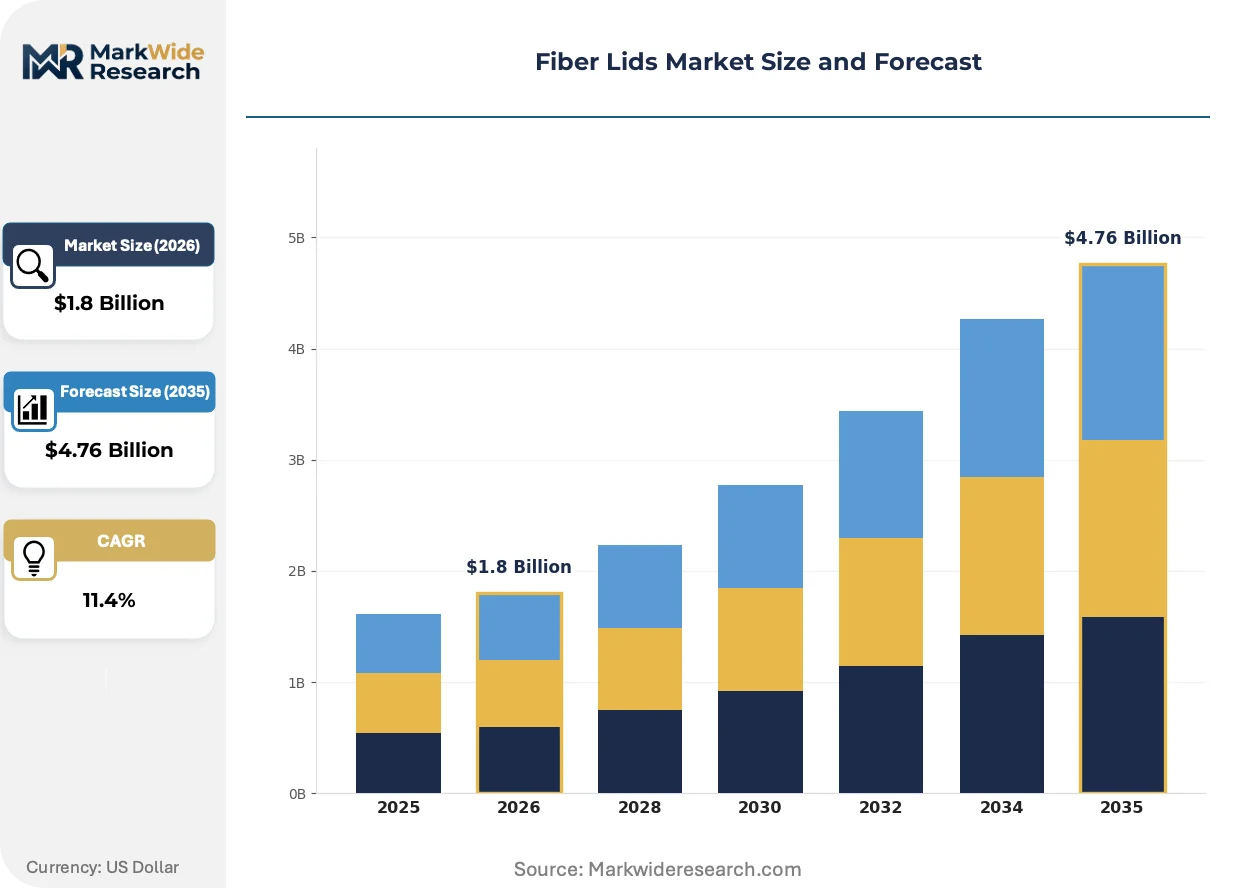
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
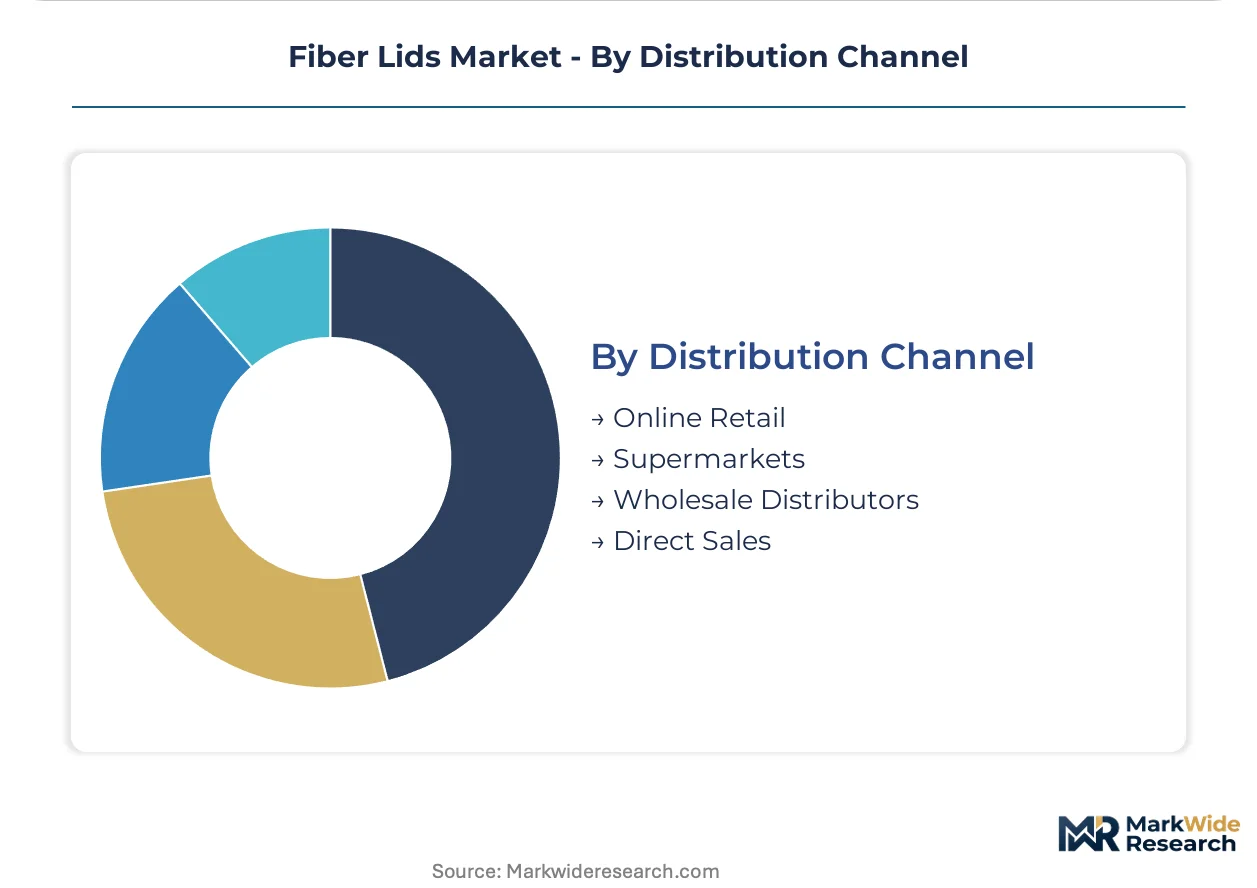
| Segmentation | Material Type: Paper, Biodegradable Plastic, Plant Fiber, Recycled Material Application: Food Packaging, Beverage Containers, Takeaway Solutions, Eco-friendly Products End User: Restaurants, Cafés, Catering Services, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Direct Sales |
| Companies Covered | Huhtamaki Oyj, Stora Enso Oyj, Pactiv LLC, Zume Inc., Liplid AB, Scandicore AB, Be Green Packaging, Pacqueen Industrial (Shanghai) Co., Ltd., WorldCentric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Lids Market Emerging Trajectories
Material science breakthroughs are compressing the performance gap between fiber and polymer lids while digital traceability tools reshape how buyers verify sustainability claims.
Barrier coating technology is electrifying competitive positioning. Per- and polyfluoroalkyl substance-free formulations using polylactic acid or alginate layers now achieve 24-hour liquid resistance, matching polypropylene in cold beverage applications. Major coffee chains in California and Washington are qualifying these specifications for rollout. The technology is electrifying margin structures by allowing converters to command 40-60% premiums over uncoated fiber alternatives.
Extended producer responsibility frameworks are restructuring procurement incentives. California's SB 54 imposes escalating fees on plastic packaging producers, while New York's pending EPR legislation creates parallel compliance obligations. Quick-service operators in both states are consolidating supplier relationships with fiber lid converters who assume end-of-life recovery responsibilities. The regulatory pressure is compressing plastic lid contract renewals into shorter terms.
Direct supplier relationships are displacing distributor intermediation. Large franchise operators now negotiate fiber lid specifications directly with molded fiber manufacturers, bypassing broadline foodservice distributors who historically controlled packaging procurement. This channel shift concentrates volume with converters who can guarantee multi-regional supply consistency. The pattern is most visible among US-based burger chains with 10,000-plus unit footprints.
Fiber Lids Market Segmentation
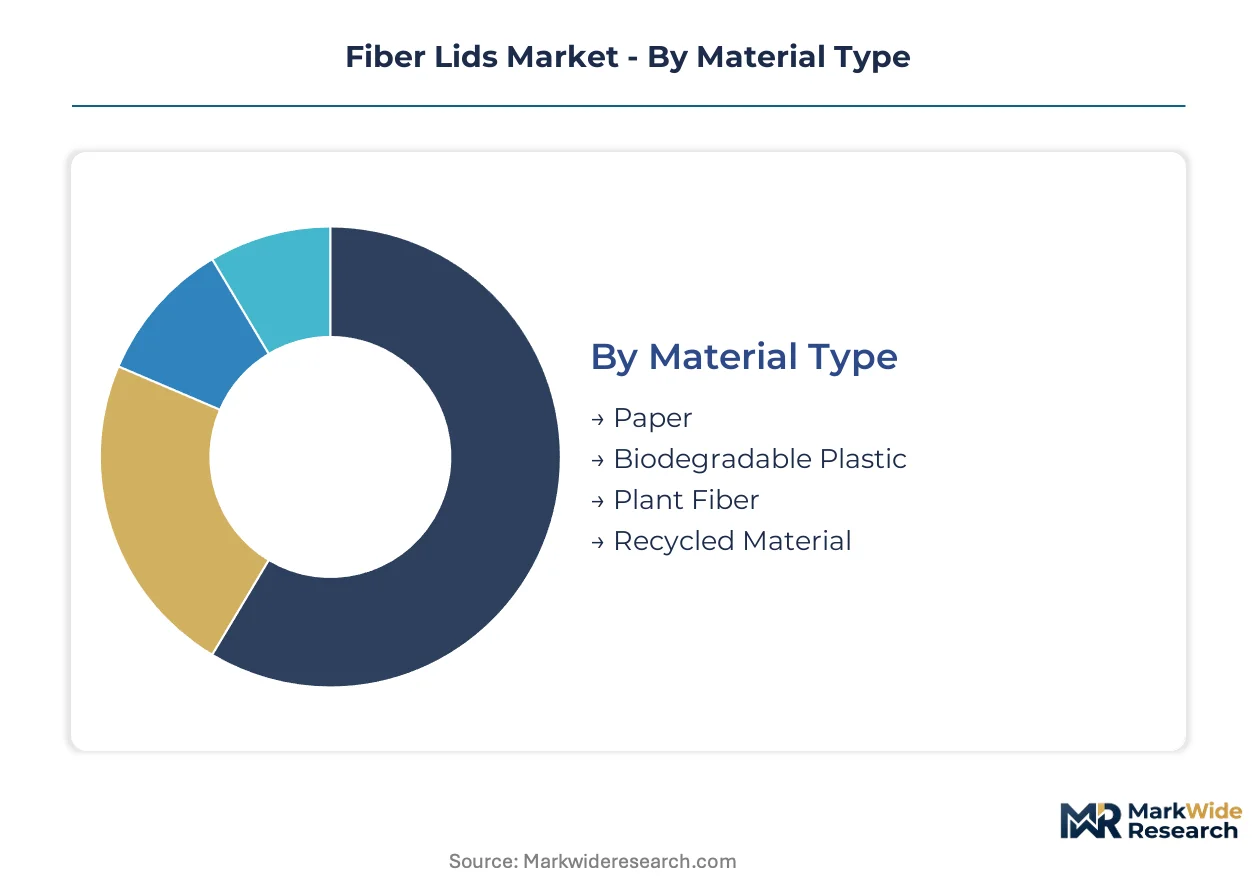
Fiber lid procurement decisions pivot on material certifications, application performance requirements, and end-user compliance obligations. Buyers segment suppliers across four dimensions that determine contract eligibility and pricing power.
Material Type:
Cost tier and sustainability credential intensity drive supplier selection across substrate categories.
- Plant Fiber:Compressed agricultural residues—wheat straw, bagasse, bamboo—deliver the highest compostability ratings. Quick-service chains in California and Washington pay premiums for TÜV Austria OK Compost HOME certification to meet SB 54 reporting requirements.
- Paper:Thermoformed molded fiber from virgin or recycled pulp dominates volume production. Nordic integrated producers control raw material costs through captive forestry assets, squeezing independent converters on margin.
- Biodegradable Plastic:Polylactic acid and polyhydroxyalkanoate formulations bridge fiber and polymer performance. Limited adoption due to higher unit costs and industrial composting infrastructure gaps in most US municipalities.
- Recycled Material:Post-consumer paperboard and agricultural waste blends target price-sensitive institutional buyers. FSC chain-of-custody documentation unlocks corporate sustainability procurement panels.
Plant fiber leads on scale; recycled material leads on momentum as EPR fees escalate virgin plastic penalties.
Application:
Performance specifications and spill-resistance demands determine lid geometry and barrier coating requirements.
- Takeaway Solutions:Third-party delivery platforms require transport-optimized designs with sip-hole integration and 24-hour liquid resistance. DoorDash and Uber Eats operators in New York and Los Angeles specify these for temperature integrity during transit.
- Beverage Containers:Hot-fill applications above 85°C demand specialized barrier coatings to prevent fiber swelling. Specialty coffee chains in Seattle and Portland are qualifying PFAS-free alginate layers for cold brew and iced beverage lines.
- Food Packaging:Clamshell and bowl lids for prepared meals prioritize stackability and microwave safety. Stadium concessions and corporate cafeterias specify these for high-volume service efficiency.
- Eco-friendly Products:Home compostable certifications target sustainability-focused café chains in Germany and the Netherlands. Premium pricing applies for products meeting multiple certification standards simultaneously.
Takeaway solutions lead on scale; beverage containers lead on momentum as hot-fill barrier technology advances.
End User:
Volume scale and compliance complexity shape procurement relationship structures.
- Restaurants:Quick-service chains with 10,000-plus unit footprints negotiate direct contracts with molded fiber manufacturers, bypassing broadline distributors. Burger chains dominate volume demand in the US market.
- Cafés:Specialty coffee operators prioritize aesthetic customization and home compostability certifications. Independent operators in Portland and Austin drive specification innovation.
- Catering Services:Event and institutional foodservice demands stackable, transport-optimized designs with cost efficiency at volume. Corporate and university contracts concentrate procurement.
- Food Manufacturers:Retail packaged food producers require extended shelf-life barrier properties and retail display compatibility. Frozen and refrigerated meal segments specify these for distribution durability.
Restaurants lead on scale; cafés lead on momentum as sustainability credential requirements intensify.
Distribution Channel:
Channel concentration reflects buyer scale and specification complexity.
- Direct Sales:Large franchise operators negotiate fiber lid specifications directly with converters for multi-regional supply consistency. This channel captures the highest-volume contracts in the US market.
- Wholesale Distributors:Broadline foodservice distributors serve mid-tier operators with standardized specifications. Pactiv LLC leverages this channel for convenience store and stadium concession penetration.
- Online Retail:E-commerce platforms target small independent operators and startup food brands with low minimum order quantities. Amazon Business and specialized packaging marketplaces compete on delivery speed.
- Supermarkets:Retail shelf presence for consumer-branded eco-friendly products reaches home composting enthusiasts. Whole Foods and regional co-ops curate certified sustainable packaging assortments.
Direct sales leads on scale; online retail leads on momentum as digital procurement platforms expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chicago metropolitan area anchors North American molded fiber manufacturing capacity, with converter facilities supplying quick-service chains across the Midwest and beyond. Demand concentrates where state-level plastic bans intersect with dense foodservice infrastructure.
United States
California's SB 54 and New York's extended producer responsibility laws are compressing plastic lid contract terms. The FDA maintains contact-substance safety standards that fiber lid converters must satisfy for interstate commerce. Los Angeles and New York City quick-service operators are consolidating supplier relationships with converters assuming end-of-life recovery obligations.
Germany
The EU Green Deal and F-Gas Regulation are redirecting procurement budgets toward compostable packaging alternatives. TÜV Austria's OK Compost HOME certification unlocks premium pricing from sustainability-focused café chains. The Rhine-Ruhr industrial corridor hosts thermoforming equipment manufacturers carrying 18-month order backlogs for molded fiber press capacity.
India
Domino's and KFC franchise buildouts in tier-2 cities lack compliant local lid supply, creating first-mover openings for molded fiber specialists. The Food Safety and Standards Authority of India regulates food-contact materials for imported and domestic packaging. Maharashtra and Karnataka are emerging as early adoption clusters where multinational quick-service operators pilot fiber lid specifications.
Netherlands
Amsterdam and Rotterdam café chains prioritize home compostability certifications for waste diversion reporting. The EU Single-Use Plastics Directive enforcement timeline is accelerating material substitution decisions among Dutch foodservice buyers. The Randstad region concentrates specification innovation for spill-resistant takeaway designs serving third-party delivery platforms.
China
Pacqueen Industrial and domestic converters are expanding thermoforming capacity to serve quick-service restaurant supply chains. The Ministry of Ecology and Environment's dual carbon goals are steering municipal procurement toward cellulose-based alternatives. The Yangtze River Delta manufacturing cluster is integrating barrier coating technology for 24-hour liquid resistance specifications.
Fiber Lids Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty certification and regional market penetration. The vendor base stratifies across integrated pulp-to-package conglomerates, independent molded fiber specialists, and diversified packaging conglomerates with fiber divisions. Three archetypes dominate: Nordic forestry-integrated multinationals, North American distribution-heavy converters, and Asia-Pacific equipment-scaled fabricators. Competitive moves center on backward integration into agricultural residue pulp sourcing and direct contracting relationships that bypass traditional distributor intermediation.
Among Nordic forestry-integrated multinationals, Huhtamaki Oyj and Stora Enso Oyj exemplify the backward-integrated archetype controlling raw fiber costs through captive supply chains. Pactiv LLC represents the North American distribution-heavy model, leveraging established networks for convenience store and stadium concession penetration. These three occupy distinct competitive positions based on geographic manufacturing footprint and customer relationship structure rather than product differentiation alone.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Stora Enso Oyj |
| Pactiv LLC |
| Zume Inc. |
| Liplid AB |
| Scandicore AB |
| Be Green Packaging |
| Pacqueen Industrial (Shanghai) Co., Ltd. |
| WorldCentric |
| Others |
Supply Flow & Price Mechanics
Nordic softwood pulp costs swing through three pricing tiers before reaching foodservice buyers, with integrated forestry conglomerates capturing margin that independent converters surrender to spot market volatility. California's SB 54 compliance premiums and EU Green Deal procurement mandates reshape how buyers evaluate total cost of ownership across fiber lid specifications.
Pricing Analysis
Input-cost pass-through from agricultural residue pulp suppliers operates on quarterly contract adjustments, with wheat straw and bagasse premiums widening against virgin wood pulp as compostability certification demand intensifies. Three-tier pricing structure across premium, standard, and economy levels separates TÜV Austria OK Compost HOME certified lids from BPI industrial compostable grades and uncertified molded fiber alternatives. Cost compression in the standard tier is intensifying because Nordic integrated producers leverage captive forestry assets to undercut independent converters on volume contracts. Quick-service chains with 10,000-plus unit footprints exhibit lowest price sensitivity, while independent cafés and catering operators in tier-2 cities drive hard bargains on per-unit pricing.
Supply Chain Analysis
India's domestic-content mandates for food-contact packaging are reshaping sourcing patterns as multinational quick-service operators seek compliant local lid supply for franchise buildouts in Maharashtra and Karnataka. Manufacturing concentrates in Finland, Germany, and China, with thermoforming press fabrication anchored in the Rhine-Ruhr corridor and Yangtze River Delta. Raw material supply draws from Nordic softwood forests, North American wheat straw agricultural residue networks, and Chinese bamboo pulp processing clusters. Single-source vulnerability runs through German and Finnish thermoforming equipment manufacturers carrying 18-month order backlogs. Distribution runs through direct sales contracts for large franchise operators, bypassing broadline foodservice distributors who historically controlled packaging procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU regulatory compliance premiums exceed Indian manufacturing cost advantages by sufficient margin to justify multi-regional production footprints.
For Market Incumbents: Deploy backward integration into agricultural residue pulp sourcing to defend margin position against Nordic forestry-integrated competitors. Secure thermoforming press capacity commitments with German and Finnish equipment manufacturers before order backlogs extend further. Channel control through direct contracting relationships with 10,000-plus unit quick-service chains locks out emerging molded fiber specialists. For New Entrants and Emerging Players: Enter via India's tier-2 city quick-service expansion where Domino's and KFC franchise buildouts lack compliant local lid supply. Target Maharashtra and Karnataka as first-mover geographies with Food Safety and Standards Authority of India certification pathways. Pursue home composting certification as the go-to-market angle for sustainability-focused café chains in Germany and the Netherlands willing to pay premium pricing. For Investors and Strategic Acquirers: Consolidation pressure builds where mold design engineering scarcity intersects with multi-certification timeline bottlenecks extending product launch cycles. Long-term viability favors acquiring molded fiber specialists with existing FDA food-contact and BPI compostability approvals rather than greenfield certification investments. The signal to watch is composting infrastructure buildout velocity in target municipalities, which determines realized environmental benefit and sustained buyer willingness to pay compliance premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Agricultural Residue Pulp Integration | Captive wheat straw and bagasse supply locks in compostability certification premiums against Nordic wood pulp competitors. |
| Thermoforming Capacity Expansion | Additional press installations in India and China serve quick-service franchise buildouts lacking compliant local lid supply. |
| Multi-Certification Acceleration | Simultaneous FDA, BPI, and FSC approvals compress 14-18 month launch cycles to capture regulatory deadline windows. |
| Direct Sales Channel Development | Bypassing broadline distributors concentrates volume with converters guaranteeing multi-regional supply consistency. |
| Barrier Coating R&D Investment | PFAS-free alginate and polylactic acid layers achieving 24-hour liquid resistance unlock specialty coffee segment penetration. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with quick-service restaurant procurement directors, molded fiber converter plant managers, foodservice distributor category buyers, and sustainability compliance officers informed demand-side and supply-side perspectives. Secondary sources included FDA food-contact substance filings, EU Single-Use Plastics Directive implementation timelines, BPI and TÜV Austria certification databases, and state-level extended producer responsibility legislation texts. Bottom-up volume modeling triangulated against top-down regulatory-driven substitution forecasts.
Granularity-level modeling operated at material type, application performance tier, end-user scale segment, and distribution channel dimensions across the projection horizon. CAGRs derived from regulatory enforcement timelines intersecting with converter capacity expansion curves. Industry-specific inputs incorporated thermoforming equipment order backlogs, agricultural residue pulp price indices, and municipal composting infrastructure development trajectories.
Inputs from certification body databases and equipment manufacturer order books were available through the study window; gaps in real-time municipal composting facility commissioning data introduce uncertainty bands around environmental benefit realization assumptions. Forecasts reflect documented regulatory enforcement schedules and modeled capacity expansion timelines. Pulp cost volatility, equipment delivery delays, and hot-fill performance gap resolution pace constitute primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
US Packaging Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Box and Carton Overwrap Films Market
Packaging Materials
PVC Packing Straps Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Construction Films Market
Packaging Materials
Bulb Packaging Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
MDO Films Market
Packaging Materials
Packaging Primers Market
Packaging Materials
Reel in Box Market
Packaging Materials
Heat Shrink Packaging Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Middle East and Africa Single-Use Packaging Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Global Liquid Packaging Market