
 Single Dose Detergent Packaging Market | 2026-2036
Single Dose Detergent Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Single Dose Detergent Packaging Market Analytics
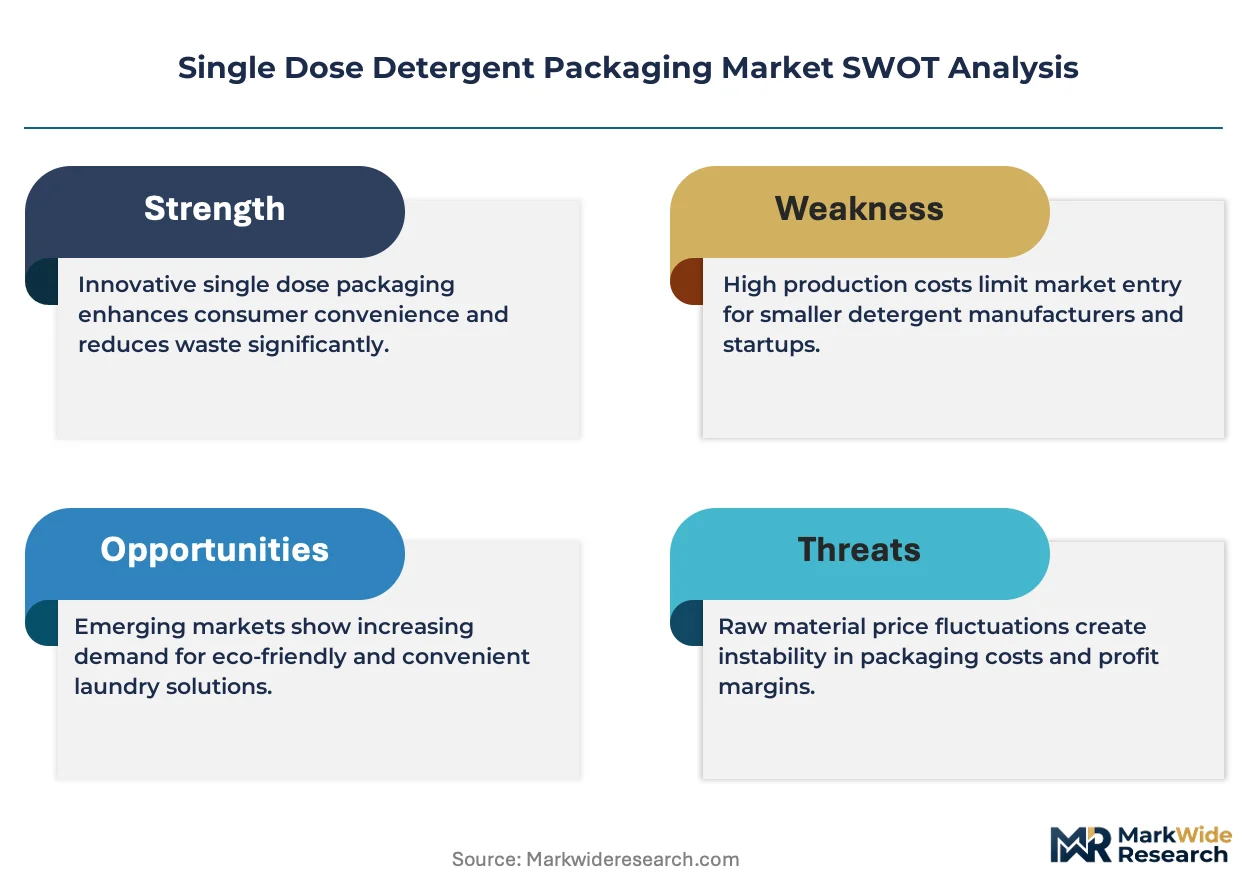
North American flexible packaging converters are expanding water-soluble film capacity to serve detergent brand owners shifting from multi-dose bottles. Procter & Gamble leverages its global manufacturing footprint to sustain pod-format dominance across mass retail channels. Henkel anchors European supply through specialized production lines for dishwasher and laundry tabs. Unilever competes on biodegradable film formulations targeting sustainability-driven retailers.
Single dose detergent packaging refers to pre-measured, individually sealed containers—typically pods, pouches, or sachets—designed to dissolve or dispense a fixed quantity of cleaning agent per use cycle, with water-soluble polyvinyl alcohol film representing the dominant technical substrate for laundry applications. These formats eliminate consumer dosing error, reduce chemical overuse, and minimize shipping volumes versus liquid concentrates. Pods command the largest value share among packaging types due to premium positioning and unit economics that favor brand owners, while biodegradable film is the fastest-expanding material category as retailers impose plastic-reduction mandates. Household end users generate the highest absolute volume, though commercial laundries and institutional buyers offer superior margin pools through contract-based procurement.
The EPA regulates surfactant discharge limits that indirectly shape detergent concentration levels and packaging efficiency targets in the United States. The EU REACH framework and F-Gas Regulation constrain solvent chemistry options while accelerating biodegradable material qualifications for single dose formats. California's extended producer responsibility laws and similar state measures are tightening post-consumer recovery obligations. Stakeholders must monitor evolving compostability certification requirements and regional chemical restriction lists to align R&D pipelines with divergent compliance timelines.
Market Dynamics
Material science breakthroughs in water-soluble polyvinyl alcohol films are compressing the cost gap between conventional plastic bottles and single-dose formats, forcing converters to reconfigure extrusion lines and brand owners to accelerate format transitions.
Growth Catalysts
- EU Single-Use Plastics Directive:The directive mandates reduction in virgin plastic packaging, compelling detergent manufacturers to qualify biodegradable film substrates for pod formats.
- Commercial laundry automation:Industrial laundries in Germany and the Netherlands are standardizing pre-measured dosing to eliminate operator error and reduce chemical waste in high-volume operations.
- Water-soluble film chemistry:Advances in cold-water dissolution kinetics are expanding pod viability into emerging markets with lower-temperature washing norms.
Market Restraints
- Ethylene vinyl alcohol resin supply concentration:Asian petrochemical producers control over 70% of specialized copolymer supply, exposing converters to input volatility and currency risk.
- Moisture sensitivity during distribution:Pods require climate-controlled logistics infrastructure that remains underdeveloped in Latin America and Southeast Asia.
- California extended producer responsibility laws:Post-consumer recovery obligations impose compliance costs that disproportionately burden mid-tier brands lacking scale for circular infrastructure.
Strategic Opportunities
- India household penetration:Urban middle-class expansion and washing machine adoption in tier-2 cities create first-mover advantage for pod-format education campaigns.
- Professional cleaning services:Contract janitorial and hospitality housekeeping segments remain underpenetrated by single-dose formats despite superior inventory control benefits.
- Compostability certification alignment:Early qualification with BPI and OK Compost HOME standards positions suppliers for retailer plastic-reduction mandates accelerating through 2025-2027.
Industry Challenges
- Polymer formulation expertise scarcity:The intersection of surfactant chemistry and film extrusion requires hybrid R&D talent pools that remain concentrated at European technical universities.
- Legacy bottling asset stranding:Major brand owners face write-down risk on multi-billion-liter liquid detergent production lines as format mix shifts accelerate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Dose Detergent Packaging Market |
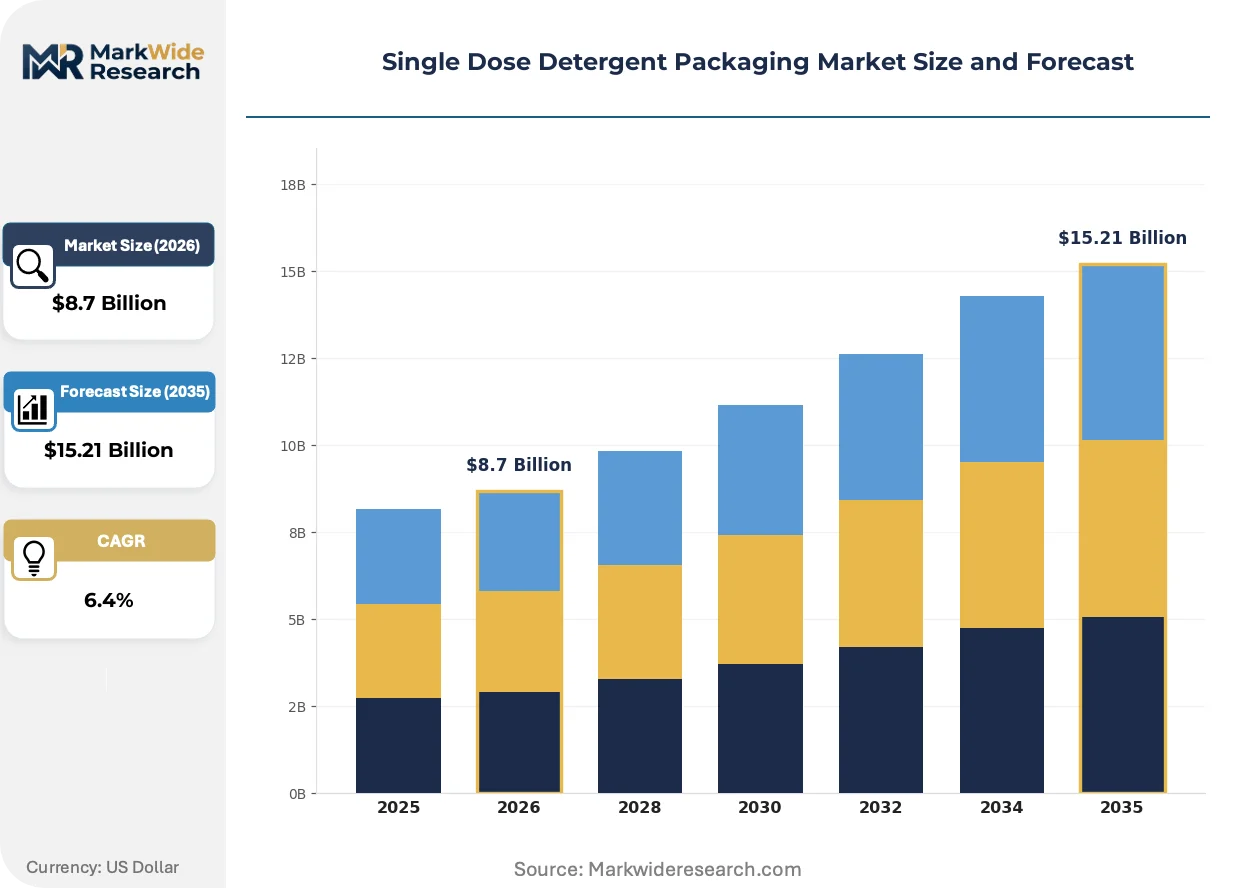
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Pods, Pouches, Sachets, Tubs Material: Plastic, Biodegradable Film, Paper, Aluminum End User: Household, Commercial, Industrial, Institutional Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Church & Dwight, Colgate-Palmolive, Procter & Gamble, Mondi Group, Bemis Company, Henkel, Clorox Company, Amcor, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Dose Detergent Packaging Market Evolving Landscape
Active material innovation and regulatory compression are converging to redefine competitive advantage around dissolution performance, carbon footprint verification, and channel-specific format optimization.
Barrier-coated water-soluble films are integrating oxygen and moisture resistance layers that extend pod shelf life without compromising dissolution speed. Hospitality procurement teams are adopting these enhanced formats for centralized linen services where storage duration exceeds residential purchase cycles. This integration is enabling geographic expansion into humid climates previously considered incompatible with pod distribution.
REACH substance restriction updates are systematically disqualifying legacy surfactant chemistries from single-dose qualification pathways. The European Chemicals Agency's 2024-2026 evaluation timeline for nonylphenol ethoxylates is forcing reformulation investments across dishwasher tab portfolios. German industrial laundries are responding by consolidating supplier relationships around converters with in-house toxicology testing capabilities.
Direct-to-institutional procurement platforms are compressing traditional distributor margins in the commercial cleaning segment. Large hotel chains are consolidating detergent purchasing through centralized sustainability officers who mandate granular carbon disclosure per wash cycle. This pattern is most pronounced in Nordic markets where corporate ESG reporting requirements exceed EU baseline obligations.
Single Dose Detergent Packaging Market Segmentation
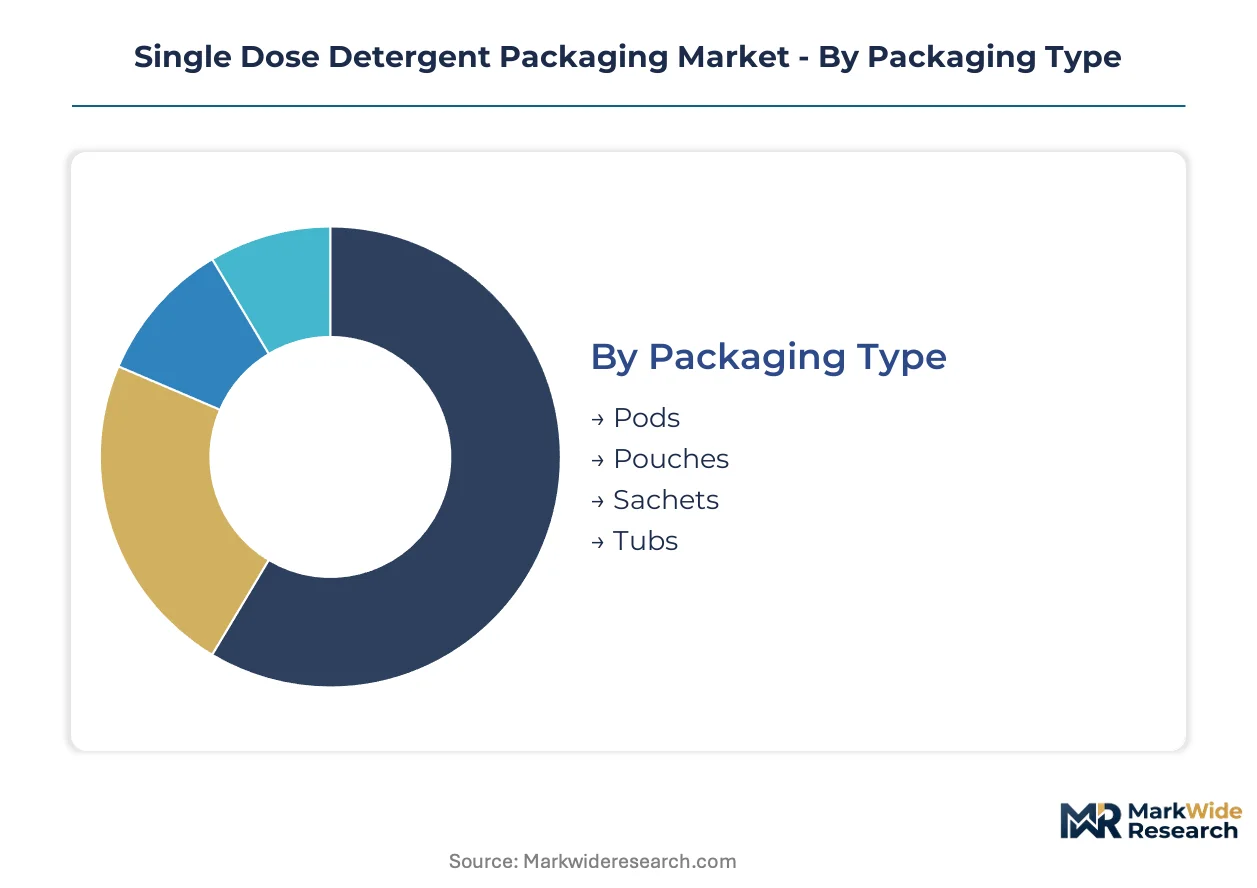
Single dose detergent packaging segments reflect divergent technical requirements across dissolution speeds, moisture barriers, and automation compatibility. Format selection directly determines supply chain configuration, from water-soluble film extrusion to climate-controlled distribution infrastructure.
Packaging Type:
Upgrade cycles in laundry automation are forcing brand owners to reassess which formats align with machine-fed dosing systems versus manual handling.
- Pods:Water-soluble polyvinyl alcohol film encloses pre-measured liquid or gel detergent in rigid, single-chamber or multi-chamber configurations. German industrial laundries and North American hospitality chains are standardizing pod formats to eliminate operator dosing error and reduce chemical waste in high-volume operations.
- Pouches:Flexible film sachets contain powder or liquid concentrate, requiring tear-open dispensing rather than full dissolution. Demand concentrates in emerging markets where cold-water washing norms and lower-price positioning favor simpler barrier constructions over full solubility.
- Sachets:Small-format sealed packets target single-use portability for travel and on-premise laundry services. Budget hotel chains in Southeast Asia favor sachets for guest amenity programs where cost-per-unit trumps dissolution performance.
- Tubs:Rigid multi-dose containers with dissolvable film lids or compartmentalized tablets. Commercial dishwashing operations in the Netherlands specify tub formats for automated dispensing systems in institutional kitchens.
Pods sit at the top of the volume ranking, with biodegradable film pods climbing the fastest as retailers impose plastic-reduction mandates.
Material:
Cost tiers separate converters serving premium sustainability credentials from commodity suppliers defending share on price.
- Plastic:Conventional polyethylene and polypropylene films dominate legacy production with lowest unit cost. California's extended producer responsibility laws and EU Single-Use Plastics Directive are forcing mid-tier brands to absorb compliance costs or accelerate material transitions.
- Biodegradable Film:Water-soluble polyvinyl alcohol and starch-based substrates qualify for industrial and home composting certifications. REACH substance restrictions and retailer plastic-reduction timelines are compressing qualification pathways for European brand owners.
- Paper:Barrier-coated cellulose formats target plastic-free positioning in Nordic markets with stringent corporate ESG reporting requirements. Moisture sensitivity limits distribution to climate-controlled channels in Northern Europe.
- Aluminum:Metallized barrier layers extend shelf life for enzyme-based formulations in humid climates. Hospitality procurement in Gulf Cooperation Council markets specifies aluminum-laminated sachets for centralized linen services with extended storage cycles.
Plastic retains the largest installed base, though biodegradable film is gaining share fastest as BPI and OK Compost HOME certifications become procurement prerequisites.
End User:
Application-specific performance requirements create distinct margin pools across consumer and professional segments.
- Household:Residential washing machine owners purchasing through retail channels. German consumers favor pre-measured formats for efficiency and waste reduction, driving pod penetration above regional averages.
- Commercial:Contract laundries, janitorial services, and hospitality housekeeping operations. Large hotel chains are consolidating detergent purchasing through centralized sustainability officers who mandate granular carbon disclosure per wash cycle.
- Industrial:High-volume automated laundry facilities with continuous batch processing. Industrial laundries in the Netherlands standardize pre-measured dosing to reduce chemical waste and labor costs.
- Institutional:Healthcare, education, and government facilities with procurement through distributor networks or direct-to-institutional platforms. Direct procurement is compressing traditional distributor margins as sustainability officers consolidate supplier relationships.
Household generates the highest absolute volume, with commercial climbing fastest as contract-based procurement expands in hospitality and healthcare.
Distribution Channel:
Customer type and purchase frequency determine channel economics, from bulk wholesale to impulse convenience.
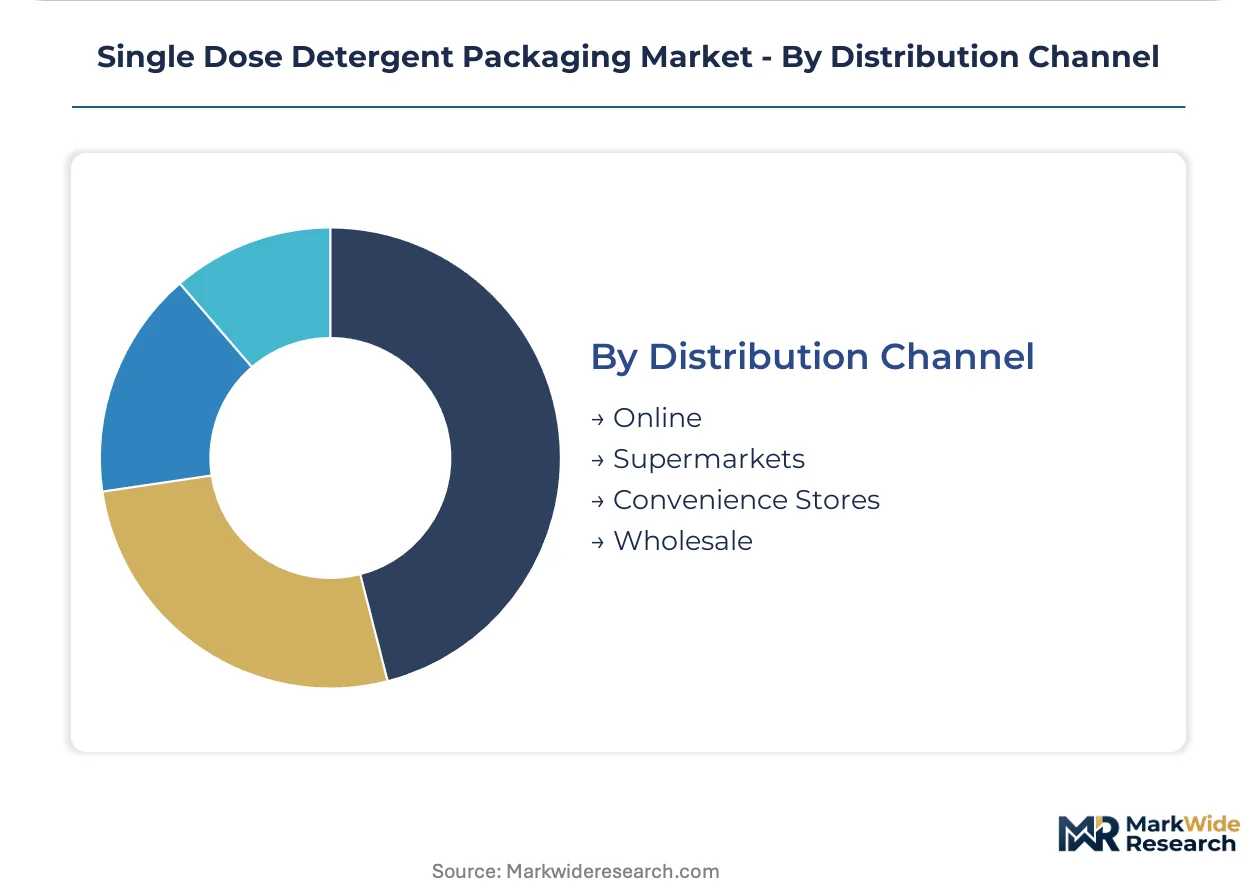
- Online:Direct-to-consumer and subscription replenishment models. Urban middle-class expansion in Indian tier-2 cities creates first-mover advantage for pod-format education campaigns through e-commerce platforms.
- Supermarkets:Mass retail shelf space competition drives premium positioning and multi-format assortment. Procter & Gamble leverages its global manufacturing footprint to sustain pod-format dominance across mass retail channels.
- Convenience Stores:Small-format retail for emergency and travel-size purchases. Sachet formats dominate this channel in Latin American markets where climate-controlled logistics for pods remain underdeveloped.
- Wholesale:Bulk procurement for commercial and institutional buyers. Contract janitorial and hospitality housekeeping segments source through wholesale distributors despite emerging direct-to-institutional platforms.
Supermarkets anchor volume, with online expanding most quickly as subscription models penetrate residential replenishment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as converters seek jurisdictions with favorable compliance costs and established water-soluble film expertise. Germany and the Netherlands attract specialized manufacturing due to REACH-aligned material science infrastructure, while Asian markets face distribution bottlenecks from moisture-sensitive logistics requirements.
United States
California's extended producer responsibility laws and emerging state-level packaging mandates are accelerating transitions from multi-dose bottles toward pod formats. The EPA regulates surfactant discharge limits that indirectly shape detergent concentration targets and packaging efficiency standards. Flexible packaging converters in the Midwest are expanding water-soluble film capacity to serve brand owners seeking compliance-ready substrates.
Germany
Industrial laundries and household consumers alike favor pre-measured detergent formats for operational efficiency and waste reduction, driving pod penetration above regional averages. The EU Single-Use Plastics Directive and REACH framework constrain solvent chemistry options while accelerating biodegradable material qualifications. Technical universities in North Rhine-Westphalia supply hybrid R&D talent pools bridging surfactant chemistry and film extrusion expertise.
Netherlands
Commercial dishwashing operations specify tub formats with dissolvable film lids for automated dispensing systems in institutional kitchens. The EU F-Gas Regulation and REACH substance restrictions compress qualification timelines for sustainable packaging formats. Rotterdam's logistics hub supports climate-controlled distribution infrastructure essential for moisture-sensitive pod formats.
India
Urban middle-class expansion and washing machine adoption in tier-2 cities create first-mover opportunity for pod-format education campaigns through e-commerce platforms. The Bureau of Indian Standards and DGFT oversee import and quality frameworks affecting film substrate availability. Mumbai-Pune industrial corridor hosts emerging flexible packaging capacity targeting domestic detergent brand requirements.
China
Asian petrochemical producers control over 70% of specialized ethylene vinyl alcohol copolymer supply, exposing converters to input volatility and currency risk. The Ministry of Ecology and Environment enforces discharge standards affecting surfactant formulation choices. Yangtze River Delta manufacturing clusters concentrate water-soluble film extrusion capacity serving both domestic and export markets.
Single Dose Detergent Packaging Market Competitive Landscape
German and Dutch producers anchor the premium tier with REACH-aligned material science capabilities; North American converters hold scale-driven positions through hospitality and mass retail procurement relationships. The vendor base separates into three strategic archetypes: multinational brand owners with captive film supply, specialized converters with toxicology testing capabilities, and regional flexible packaging suppliers defending on unit economics. Dominant competitive moves include capacity expansion in water-soluble film extrusion and strategic partnerships with industrial laundry automation providers.
Among diversified consumer goods manufacturers, Church & Dwight, Colgate-Palmolive, and Procter & Gamble occupy positions exemplifying the brand-owner archetype with integrated format development and global manufacturing footprints. These entities represent scale-driven competitive positioning through mass retail channel dominance and standardized procurement protocols across hospitality chains.
| Leading Market Players |
|---|
| Church & Dwight |
| Colgate-Palmolive |
| Procter & Gamble |
| Mondi Group |
| Bemis Company |
| Henkel |
| Clorox Company |
| Amcor |
| Unilever |
| Others |
Value Network & Pricing Analysis
Ethylene vinyl alcohol resin costs cascade through three pricing tiers as Asian petrochemical producers control specialized copolymer supply, forcing European converters to absorb currency volatility or pass through to hospitality procurement teams. Water-soluble film extrusion capacity constraints in Germany and the Netherlands create premium pricing power for REACH-aligned substrate qualifications, while mid-tier brands face margin compression from California's extended producer responsibility compliance burdens.
Pricing Analysis
Distributor margins in wholesale channels compress as direct-to-institutional procurement platforms consolidate hospitality and healthcare purchasing. Three-tier pricing structure across premium biodegradable film, standard water-soluble substrates, and economy plastic formats reflects certification grade differentiation. Pricing pressure stems from REACH substance restriction timelines forcing accelerated reformulation investments. Commercial laundries exhibit lowest price sensitivity due to chemical waste reduction ROI, while emerging market household segments prioritize unit economics over dissolution performance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Procter & Gamble and Henkel, bypassing traditional distributor networks. Raw material supply concentrates in China, Germany, and the Netherlands, with ethylene vinyl alcohol copolymer, polyvinyl alcohol resin, and barrier-coated cellulose as critical inputs. Single-source vulnerability runs through Asian petrochemical producers controlling over seventy percent of specialized copolymer feedstock. Distribution runs through climate-controlled logistics infrastructure anchored by Rotterdam's hub for moisture-sensitive pod formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converters can arbitrage fifteen to twenty percent cost differentials by locating water-soluble film extrusion in Germany versus importing from Asian suppliers subject to EU carbon border adjustment mechanisms. Regulatory misalignment between California's extended producer responsibility laws and EU REACH timelines creates procurement timing advantages for dual-qualified substrates.
For Market Incumbents: Anticipate margin erosion from biodegradable film qualification mandates by securing captive ethylene vinyl alcohol supply through backward integration into Asian petrochemical partnerships. Consolidate toxicology testing capabilities in-house to compress REACH compliance timelines for dishwasher tab reformulations. Channel control through direct-to-institutional platforms defends against procurement platform disintermediation in hospitality segments.
For New Entrants and Emerging Players: The premium-economy price-point gap in Indian tier-2 cities offers first-mover positioning through e-commerce pod-format education campaigns targeting washing machine adoption curves. Professional cleaning services remain underpenetrated despite superior inventory control benefits. Compostability certification alignment with BPI and OK Compost HOME standards unlocks retailer plastic-reduction mandate compliance faster than incumbent legacy asset transitions.
For Investors and Strategic Acquirers: Roll-up economics work for specialized converters with REACH-aligned material science capabilities because regulatory fragmentation favors consolidated toxicology testing and qualification infrastructure. Target mid-cap European flexible packaging suppliers with in-house film extrusion and established hospitality procurement relationships. The signal to watch is industrial laundry automation capex cycles in Germany and the Netherlands as pod-format standardization inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Soluble Film Capacity Expansion | Midwest converters serve California EPR compliance demand from mass retail brand owners. |
| Backward Integration into Copolymer Supply | Captive ethylene vinyl alcohol resin hedges Asian petrochemical producer currency volatility exposure. |
| Compostability Certification Investment | BPI and OK Compost HOME qualifications unlock retailer plastic-reduction mandate procurement preferences. |
| Direct-to-Institutional Platform Launch | Large hotel chains consolidate purchasing through centralized sustainability officers mandating carbon disclosure. |
| Industrial Laundry Automation Partnership | German and Dutch facilities standardize pre-measured dosing to eliminate operator error and chemical waste. |
Research Methodology
Bottom-up household and commercial modeling reconciled against top-down water-soluble film capacity tracking forms the analytical core. Primary interviews with brand owner procurement directors, flexible packaging plant managers, industrial laundry operations heads, and hospitality sustainability officers combined with secondary validation from EPA surfactant discharge filings, EU ECHA substance restriction updates, customs trade data, and SEC 10-K disclosures. Triangulation across supply-side capacity announcements and demand-side procurement contract visibility ensures segment-level consistency.
Input-output matrices map ethylene vinyl alcohol resin supply through extrusion capacity to end-use demand across pods, pouches, sachets, and tubs. Segmentation dimensions include packaging format, material substrate, end-user category, and distribution channel, with regional regulatory cluster as an industry-specific overlay. CAGRs derive from installed base growth rates, replacement cycles, and format transition curves across the projection horizon. Cold-water dissolution kinetics advancement and compostability certification penetration serve as key forecast sensitivity inputs.
Caveats apply where REACH substance restriction timeline acceleration or California EPR law expansion could materially shift the outlook for biodegradable film adoption curves. Raw material supply disruptions from Asian petrochemical producer consolidation represent additional revision triggers. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
PVC Packing Straps Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Window Packaging Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
Card Films Market
Packaging Materials
France Packaging Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
US Packaging Market
Packaging Materials
Desiccant Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Production Page Volume Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market