
 Postal Packaging Market | 2026-2036
Postal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Postal Packaging Market Outlook
Multi-sourced procurement of corrugated substrates is recalibrating how postal operators manage packaging economics across peak-season volumes. Smurfit Kappa Group leverages integrated containerboard mills across Europe to sustain cost-competitive supply for cross-border parcel flows. DS Smith Plc anchors its position through lightweight flute innovation that reduces dimensional weight charges for e-commerce shippers. Mondi Group Plc differentiates via kraft paper mailers engineered for automated sortation systems in high-throughput distribution centers.
Postal packaging comprises protective enclosures—corrugated boxes, paper envelopes, polymer bubble mailers, and fiber-padded bags—engineered to withstand compressive loads, moisture exposure, and mechanical sorting impacts during transit through postal and courier networks. These structures typically incorporate recycled fiber content ranging from 60% to 100% and are manufactured through flute lamination, extrusion coating, or thermal bonding processes to achieve specified burst strength and edge crush test ratings. Boxes and envelopes command the largest volume positions within product-type segmentation, though bubble mailers are gaining share in apparel and electronics fulfillment where puncture resistance outweighs material cost premiums. Paper-based materials lead the material split in Europe under EFSA-aligned food-contact and REACH-compliant coating restrictions, while plastic films retain dominance in moisture-critical pharmaceutical and perishable shipments where barrier properties are non-negotiable.
The EU Green Deal and its Packaging and Packaging Waste Regulation, enforced through ECHA and national environmental agencies, mandate minimum recycled content thresholds and extended producer responsibility schemes that reshape material selection across postal packaging supply chains. The US EPA and state-level extended producer responsibility frameworks in California and New York impose parallel compliance burdens on imported packaging substrates. Stakeholders must monitor divergence between European recyclability certification requirements and emerging US state-level labeling standards that could fragment material specifications and testing protocols for multinational postal operators.
Market Dynamics
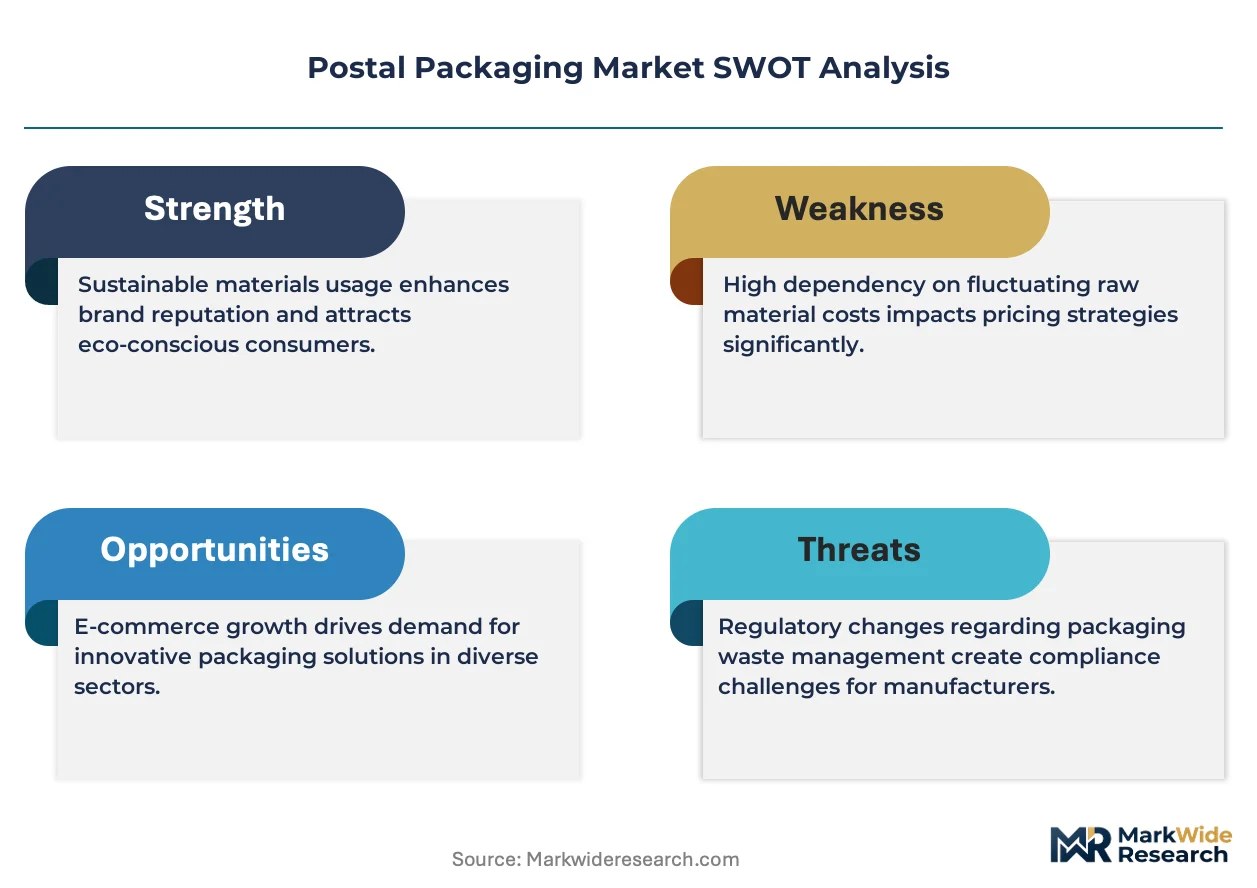
E-commerce fulfillment velocity is compressing packaging specification cycles as postal operators retrofit sortation infrastructure for smaller, lighter parcel formats. The EU Green Deal's recycled content mandates and China's GB standards for packaging recyclability are forcing material substitutions faster than supply chains can recalibrate.
Growth Catalysts
- India's postal modernization:Government digital commerce initiatives are accelerating logistics corridor development and expanding addressable volumes for protective mailers and corrugated solutions.
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility schemes and minimum recycled content thresholds are pulling fiber-based alternatives into applications previously dominated by plastic films.
- Automated sortation deployment:High-throughput distribution centers are specifying kraft paper mailers engineered for optical readability and mechanical handling at belt speeds exceeding three meters per second.
Market Restraints
- Old corrugated container supply concentration:Containerboard mill capacity imbalances in specific European regions are creating input cost volatility for integrated converters serving cross-border parcel flows.
- Barrier coating technical limitations:Water-based coatings compliant with EFSA food-contact standards still underperform extruded polyethylene for moisture-critical pharmaceutical shipments.
- California and New York EPR fragmentation:Divergent state-level extended producer responsibility frameworks are multiplying compliance burdens for substrates imported into the US market.
Strategic Opportunities
- India's underpenetrated tier-2 logistics:Postal infrastructure expansion into secondary cities creates first-mover positioning for localized corrugated converting capacity.
- Pharmaceutical cold-chain convergence:Integration of temperature-indicating inks with fiber-padded bags addresses regulatory documentation requirements for biologic shipments.
- EU Green Deal regulatory tailwind:Recyclability certification requirements are creating premium positioning for packaging substrates that qualify for ECHA-recognized recycling streams.
Industry Challenges
- Flute lamination technician scarcity:Specialized machine operators capable of calibrating lightweight board grades are concentrated in legacy manufacturing regions.
- Dual certification timeline compression:Simultaneous pursuit of FSC chain-of-custody and EU recyclability verification is extending product qualification cycles.
- Legacy warehouse management integration:Automated packaging dimensioning systems require API reconfiguration to communicate with existing postal operator sortation software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postal Packaging Market |
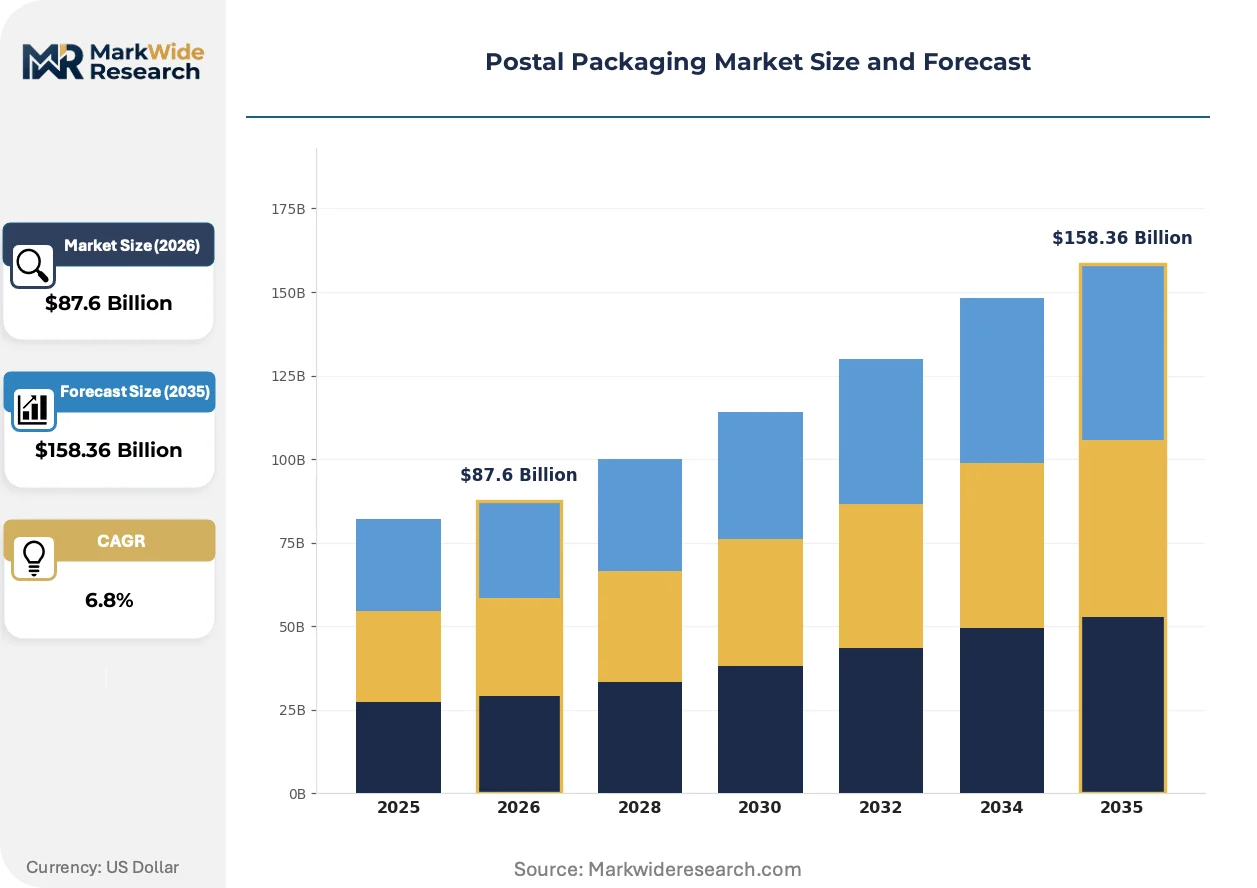
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Envelopes, Bubble Mailers, Padded Bags Material: Paper, Plastic, Cardboard, Styrofoam Size: Small, Medium, Large, Extra Large End User: E-commerce, Retail, Corporations, Individual Consumers |
| Companies Covered | Smurfit Kappa Group, DS Smith Plc, Mondi Group Plc, WestRock Company, Bong Group, Rengo Co. Ltd., Cenveo Corporation, Elite Envelopes & Graphics Inc., Poly Postal Packaging Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postal Packaging Market Strategic Shifts
Material science advances and regulatory stringency are converging to reshape substrate selection and manufacturing processes across postal packaging supply chains. Three developments are commanding strategic attention from converters and postal operators.
Machine vision-guided packaging dimensioning is automating the specification of right-size corrugated boxes at pack stations. E-commerce fulfillment centers in Germany and the Netherlands are deploying these systems to reduce void fill consumption and dimensional weight charges. The technology is automating the transition from standard stock-keeping units to on-demand box formats that minimize fiber usage per shipment.
The EU Green Deal's Packaging and Packaging Waste Regulation is mandating design-for-recycling protocols that disqualify multi-material laminates from extended producer responsibility fee reductions. Converters serving European postal networks are reengineering bubble mailers to monomaterial constructions that qualify for ECHA-aligned recycling streams. Pharmaceutical and perishable segments are responding by segregating moisture-critical shipments into dedicated plastic-film channels while migrating apparel and electronics into fiber-based alternatives.
Consolidated procurement of protective mailers is displacing fragmented purchasing across individual fulfillment nodes. Large e-commerce platforms are centralizing packaging specifications and negotiating direct mill relationships that bypass traditional distributor networks. This concentration is most visible in China's logistics corridors where platform-owned fulfillment networks are standardizing on GB-compliant kraft paper mailers across multiple provincial distribution centers.
Postal Packaging Market Segmentation
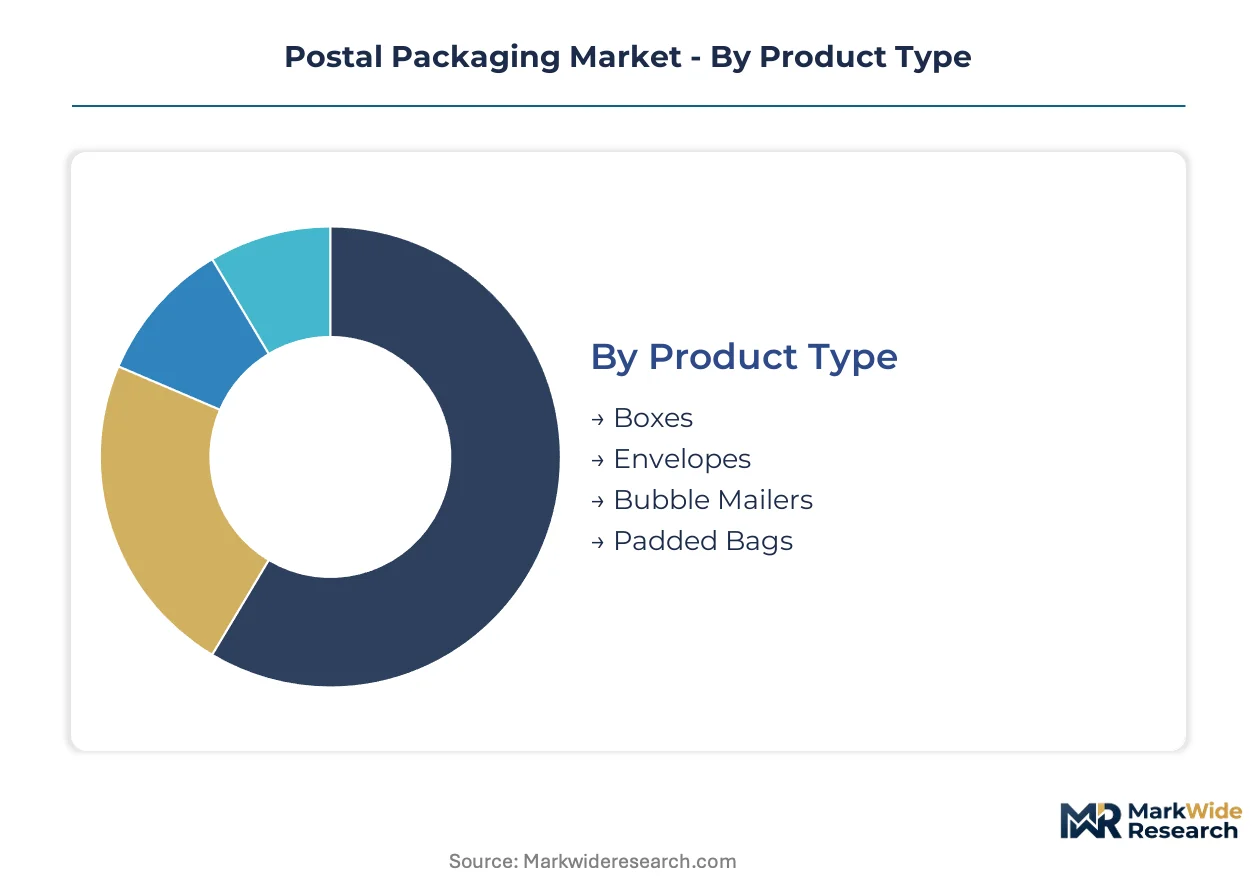
Postal packaging segmentation reflects divergent compliance burdens across substrate types and end-use channels. Material specifications trigger distinct certification pathways under EU Green Deal mandates, while product formats determine dimensional weight economics and sortation compatibility.
Product Type:
Certification requirements vary sharply: corrugated boxes demand FSC chain-of-custody for European postal networks, while bubble mailers face ECHA recyclability verification under monomaterial mandates.
- Boxes:Corrugated fiberboard structures with specified edge crush test ratings between 23 and 55 ECT. Demand concentrates in German and Dutch e-commerce fulfillment centers deploying machine vision-guided dimensioning systems to minimize void fill consumption.
- Envelopes:Kraft paper mailers engineered for optical readability at belt speeds exceeding three meters per second. India's logistics corridors under postal modernization initiatives are absorbing volumes for document and flat apparel shipments.
- Bubble Mailers:Reengineered monomaterial constructions replacing multi-material laminates to qualify for ECHA-aligned recycling streams and extended producer responsibility fee reductions.
- Padded Bags:Fiber-padded alternatives integrating temperature-indicating inks for biologic cold-chain documentation requirements.
Leading the category by volume: Boxes. Growing fastest: Bubble Mailers.
Material:
Cost tiers separate fiber-based substrates from polymer films, with barrier performance dictating premium positioning for moisture-critical applications.
- Paper:Recycled fiber content ranging from 60% to 100% manufactured through kraft pulping processes. European postal operators under EFSA-aligned coating restrictions are migrating apparel shipments from plastic films.
- Plastic:Extruded polyethylene and polypropylene films retaining dominance in pharmaceutical and perishable segments where moisture barrier properties remain non-negotiable despite regulatory pressure.
- Cardboard:Containerboard grades sourced from integrated mills across Europe, with Smurfit Kappa Group sustaining cost-competitive supply for cross-border parcel flows.
- Styrofoam:Expanded polystyrene protective inserts facing displacement under EU Green Deal design-for-recycling protocols that penalize non-recyclable multi-material assemblies.
Paper commands the volume lead. Plastic maintains the steepest expansion trajectory in cold-chain pharmaceutical applications.
Size:
Volume concentration tracks e-commerce parcel format standardization, with automated sortation infrastructure favoring dimensional ranges that minimize handling exceptions.
- Small:Formats under 2 kg dimensional weight optimized for letter mail streams and last-mile delivery density in urban logistics networks.
- Medium:Specifications aligning with automated packaging dimensioning system outputs in German fulfillment centers, reducing fiber usage per shipment through right-size box generation.
- Large:Corrugated solutions for home appliance and furniture e-commerce requiring reinforced burst strength ratings for mechanical sorting impacts.
- Extra Large:Specialized formats for B2B industrial shipments with custom flute lamination calibrations outside standard automated production lines.
Medium formats dominate automated fulfillment integration. Small formats are climbing fastest on last-mile density optimization.
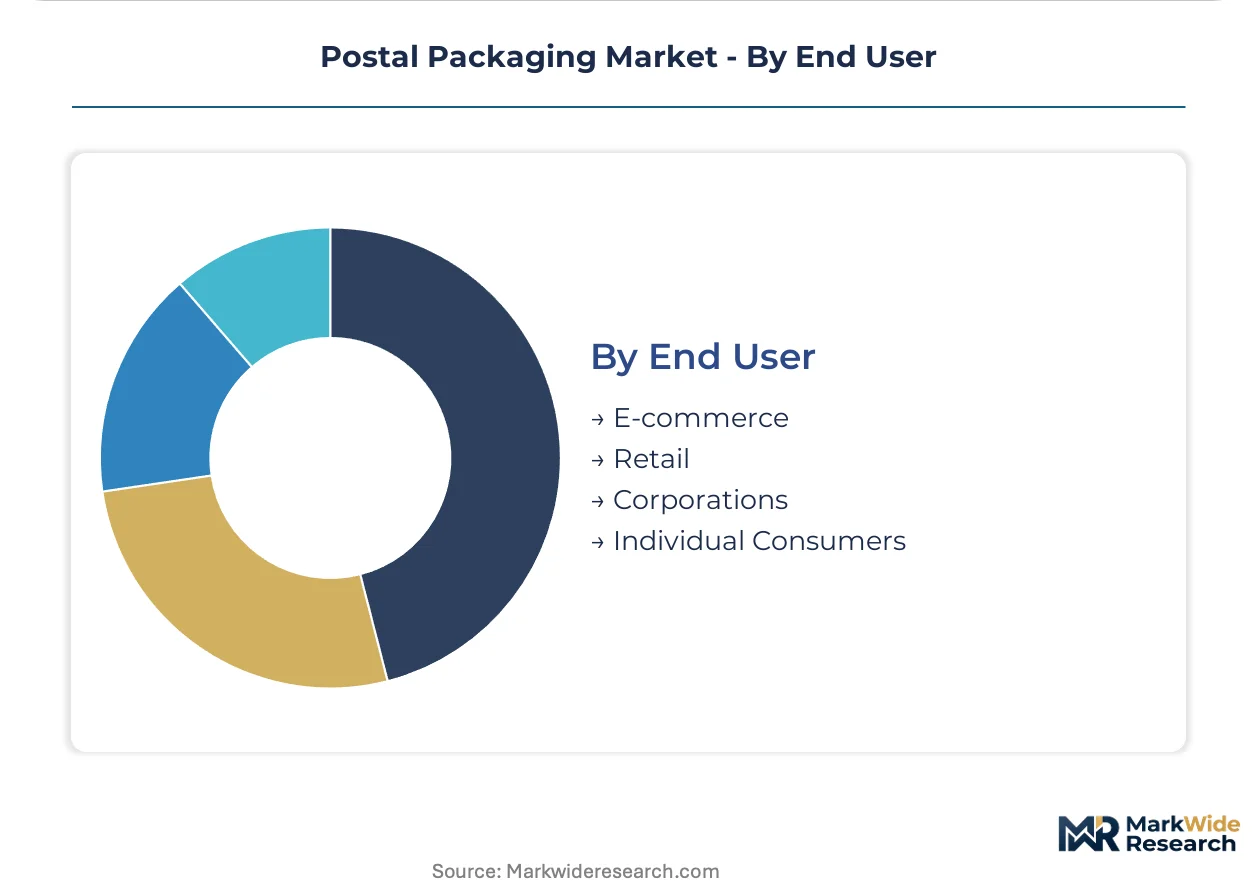
End User:
Customer type determines procurement centralization, with platform-owned fulfillment networks displacing fragmented purchasing across individual nodes.
- E-commerce:Consolidated procurement of protective mailers through direct mill relationships, most visible in China's logistics corridors where platform networks standardize on GB-compliant kraft paper mailers across provincial distribution centers.
- Retail:Omnichannel fulfillment requiring dual certification timelines for FSC chain-of-custody and EU recyclability verification, extending product qualification cycles.
- Corporations:B2B document and promotional material shipments with stable volume profiles and long-term converter contracts.
- Individual Consumers:Fragmented demand through postal service counters and retail packaging suppliers with limited specification control.
E-commerce leads procurement volume. Retail segments face the steepest compliance cost escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recycled fiber supply from European containerboard mills anchors cross-border parcel packaging economics, while Asia-Pacific logistics corridors absorb expanding volumes of kraft paper mailers and corrugated solutions under tightening recyclability mandates.
Germany
E-commerce fulfillment centers in the Rhine-Ruhr and Bavaria deploy machine vision-guided dimensioning systems to minimize void fill consumption. The EU Green Deal's Packaging and Packaging Waste Regulation enforces ECHA-aligned recyclability verification for substrates entering postal networks. Stuttgart-based converters calibrate lightweight flute grades for automated sortation at belt speeds exceeding three meters per second.
China
Platform-owned fulfillment networks in the Yangtze River Delta and Pearl River Delta standardize procurement of GB-compliant kraft paper mailers across provincial distribution centers. GB standards for packaging recyclability mandate material specifications that accelerate fiber-based substitutions. Zhejiang and Jiangsu logistics corridors concentrate converting capacity serving domestic e-commerce volumes.
United States
State-level extended producer responsibility frameworks in California and New York impose parallel compliance burdens on imported packaging substrates. The EPA coordinates with state environmental agencies on divergent labeling standards that fragment material specifications. Midwest containerboard mills supply integrated converters serving cross-border parcel flows to Canadian and Mexican postal networks.
India
Government digital commerce initiatives accelerate postal modernization across Maharashtra and Karnataka logistics corridors. The Bureau of Indian Standards monitors packaging quality specifications for protective mailers entering expanded postal networks. Gujarat and Tamil Nadu secondary cities attract first-mover corrugated converting capacity as tier-2 logistics penetration deepens.
Netherlands
Rotterdam and Amsterdam distribution centers specify kraft paper mailers engineered for optical readability in high-throughput automated sortation systems. EFSA-aligned coating restrictions push apparel shipments from plastic films into fiber-based alternatives. Randstad logistics clusters concentrate procurement consolidation for Benelux cross-border parcel flows.
Postal Packaging Market Competitive Environment
Capacity expansion dominates the current landscape as integrated containerboard mills recalibrate output for e-commerce parcel volume surges. The vendor base concentrates around three strategic archetypes: multinational integrated producers with captive fiber supply, regional specialists in lightweight flute innovation, and platform-integrated converters serving centralized procurement. M&A activity and geographic expansion represent the primary competitive vectors as operators defend margin positions amid input cost volatility.
Among European-based integrated producers, Smurfit Kappa Group, DS Smith Plc, and Mondi Group Plc occupy positions reflecting distinct strategic emphases. Smurfit Kappa exemplifies the scale-driven archetype through its mill network positioning for cross-border supply. DS Smith represents lightweight engineering specialization that reduces dimensional weight charges for high-velocity shippers. Mondi anchors the automated sortation tier with kraft paper mailer formats engineered for mechanical handling at distribution center belt speeds.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| DS Smith Plc |
| Mondi Group Plc |
| WestRock Company |
| Bong Group |
| Rengo Co. Ltd. |
| Cenveo Corporation |
| Elite Envelopes & Graphics Inc. |
| Poly Postal Packaging Ltd. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap converters across Germany and the Netherlands anchor pricing discipline through captive containerboard relationships, while their refusal to unbundle FSC certification from base pricing forces buyers into all-or-nothing procurement structures that protect margin structures amid input volatility.
Pricing Analysis
Warranty and compliance bundling shapes contract structures, with ECHA-aligned recyclability verification and automated sortation compatibility treated as standard inclusions rather than line-item add-ons. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates postal operators with EU Green Deal mandates from cost-focused regional distributors. Cost compression in economy tiers is intensifying because old corrugated container supply imbalances in specific European regions create input volatility. Regional distributors serving tier-2 Indian logistics corridors exhibit the highest price sensitivity, while German e-commerce fulfillment centers prioritize optical readability specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Swedish and Finnish containerboard mills supplying integrated converters serving cross-border Benelux parcel flows. Raw material dependencies center on recycled fiber pulp, starch-based adhesives, and water-based barrier coatings. Supply chains draw from Germany, China, and India for converting equipment and substrate inputs. Tariff exposure on imported kraft paper from Nordic regions threatens cost structures for UK-bound shipments. Distribution runs through platform-owned fulfillment networks in China's Yangtze River Delta that bypass traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Packaging and Packaging Waste Regulation constructs a cost-of-compliance moat that rewards incumbent converters with pre-certified substrate portfolios while excluding speculative entrants lacking ECHA-aligned verification infrastructure.
For Market Incumbents: Anticipate margin compression from platform-owned fulfillment networks consolidating procurement into direct mill relationships by securing captive containerboard supply through backward integration into Nordic pulp assets. Invest in lightweight flute calibration capabilities to defend positioning as machine vision-guided dimensioning systems proliferate across German and Dutch distribution centers.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for specialty converters offering rapid ECHA recyclability certification turnaround to e-commerce platforms facing extended product qualification cycles. Target India's underpenetrated tier-2 logistics corridors in Gujarat and Tamil Nadu secondary cities where localized corrugated capacity lags postal modernization velocity. Lead with pharmaceutical cold-chain documentation integration as a differentiated service layer.
For Investors and Strategic Acquirers: Consolidated procurement announcements from China's platform-owned fulfillment networks are the leading indicator that regional converter roll-ups will accelerate to meet centralized specification demands. Over the medium-term horizon, vertically integrated specialists with captive fiber supply and automated sortation-compatible mailer formats represent the most defensible acquisition profile. Watch for EU member state implementation divergence on extended producer responsibility fee structures as the signal for regulatory arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containerboard Mills | Captive pulp supply from Nordic integrated mills insulates Smurfit Kappa and DS Smith from OCC price volatility. |
| Lightweight Flute Innovation | DS Smith's engineered board grades reduce dimensional weight charges for high-velocity German e-commerce shippers. |
| Monomaterial Mailer Reengineering | Mondi's kraft paper constructions qualify for ECHA-aligned recycling streams under EU Green Deal mandates. |
| Automated Sortation Compatibility Investment | Optical readability engineering at belt speeds exceeding three meters per second secures Rotterdam distribution center contracts. |
| India Tier-2 Logistics Expansion | First-mover converting capacity in Gujarat secondary cities captures volumes from government digital commerce initiatives. |
Study Parameters
Document review covered EU regulatory filings, containerboard mill capacity databases, and e-commerce platform procurement disclosures, complemented by interviews with corrugated plant managers, postal operator packaging specification leads, and distribution center automation engineers. Secondary validation drew from trade customs data, BIS quality specification records, and SEC filings of integrated packaging producers. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Segmented outputs across product type, material substrate, parcel size tier, and end-user channel were generated over the projection horizon. CAGRs were derived from regression analysis against e-commerce penetration indices and regulatory implementation timelines. Forecast inputs incorporated EU Green Deal compliance cost curves, India's postal modernization expenditure schedules, and machine vision adoption rates in German fulfillment centers.
Caveats apply where EU member state divergence on extended producer responsibility fee structures or China's GB standard enforcement intensity could materially shift the outlook. Forecasts reflect assumptions on fiber substitution rates in moisture-critical applications and platform procurement consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Shrink Packaging Market
Packaging Materials
Cargo Moisture Control Products Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Mylar Market
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Lid Laminates Market