
 PE Coated Sack Kraft Paper Market | 2026-2036
PE Coated Sack Kraft Paper Market Size, Share, and Industry Trends Forecast 2026-2036
PE Coated Sack Kraft Paper Market Outlook
Asset-light leasing models for coating equipment is reconfiguring competitive entry barriers, allowing mid-tier converters to access PE lamination capacity without capital-heavy infrastructure. Mondi Group leverages integrated pulp-to-paper operations across European mills to sustain margin control in specialty grades. BillerudKorsnäs anchors its position through advanced fiber engineering for high-strength applications. Nordic Paper competes via concentrated Scandinavian production focused on certified food-contact kraft.
PE Coated Sack Kraft Paper consists of unbleached sulfate pulp sheets laminated with a polyethylene barrier layer, typically applied through extrusion coating at weights between 15 and 40 grams per square meter to achieve moisture resistance and heat-sealability for industrial bulk packaging. The material serves primarily as a protective container for hygroscopic commodities requiring controlled permeability during transport and storage. Valve bags dominate volume throughput in cement and chemical verticals where automated filling lines demand precise dimensional stability. High strength grade commands premium positioning in agricultural and building materials sectors where tear resistance directly reduces spillage losses during palletized distribution. Specialty grade occupies niche margin pools for food-industry applications requiring dual compliance with FDA and EU food-contact frameworks.
REACH restrictions on polymer additives and FDA Title 21 food-contact substance notifications are reshaping formulation requirements for PE coating layers across export-oriented supply chains. ECHA substance evaluation protocols are accelerating substitution timelines for legacy slip agents and antioxidants used in extrusion coatings. Stakeholders must monitor evolving EU Packaging and Packaging Waste Regulation implementation timelines alongside state-level extended producer responsibility mandates to anticipate compliance-driven specification changes.
Market Dynamics
REACH substance evaluation protocols and FDA Title 21 food-contact notifications are forcing simultaneous reformulation of PE coating layers across export supply chains, compressing substitution timelines for legacy polymer additives while opening specification gaps for compliant suppliers.
Growth Catalysts
- Emerging Infrastructure Procurement:Cement producers in India and Vietnam are accelerating valve bag adoption for moisture-sensitive bulk goods, lifting throughput requirements for high-strength grades.
- REACH Compliance Deadlines:ECHA substance evaluation protocols are tightening specifications for slip agents and antioxidants in extrusion coatings, creating replacement demand for compliant barrier formulations.
- Extrusion Coating Advancement:Equipment leasing models are lowering capital barriers for mid-tier converters seeking PE lamination capacity without mill-scale infrastructure investment.
Market Restraints
- Pulp Input Volatility:Unbleached sulfate pulp prices fluctuate with Nordic and Baltic softwood harvest cycles, squeezing converter margins during supply tightness.
- Scandinavian Mill Concentration:Specialty food-contact kraft production clusters in Sweden and Finland, creating geographic single-source risk for certified grades.
- Multi-layer Flexible Substitution:Polypropylene woven sacks with PE liners compete in fertilizer and chemical verticals where tear resistance requirements are moderate.
Strategic Opportunities
- Indian Agricultural Expansion:Fertilizer packaging demand in Maharashtra and Gujarat is outpacing domestic coated kraft capacity, creating import substitution openings.
- EU Packaging Waste Regulation:Extended producer responsibility mandates are incentivizing recyclable mono-material designs that favor PE-coated kraft over multi-layer alternatives.
- Bio-based Barrier Convergence:Integration of enzymatic fiber modification with conventional extrusion coating is enabling thinner PE layers without permeability loss.
Industry Challenges
- Food-Contact Certification Timelines:FDA substance notification reviews and EU 10/2011 compliance testing extend product qualification cycles by 12-18 months.
- Extrusion Coating Skill Scarcity:Melt temperature control and adhesion optimization require specialized technicians in short supply across Southeast Asian converter markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PE Coated Sack Kraft Paper Market |
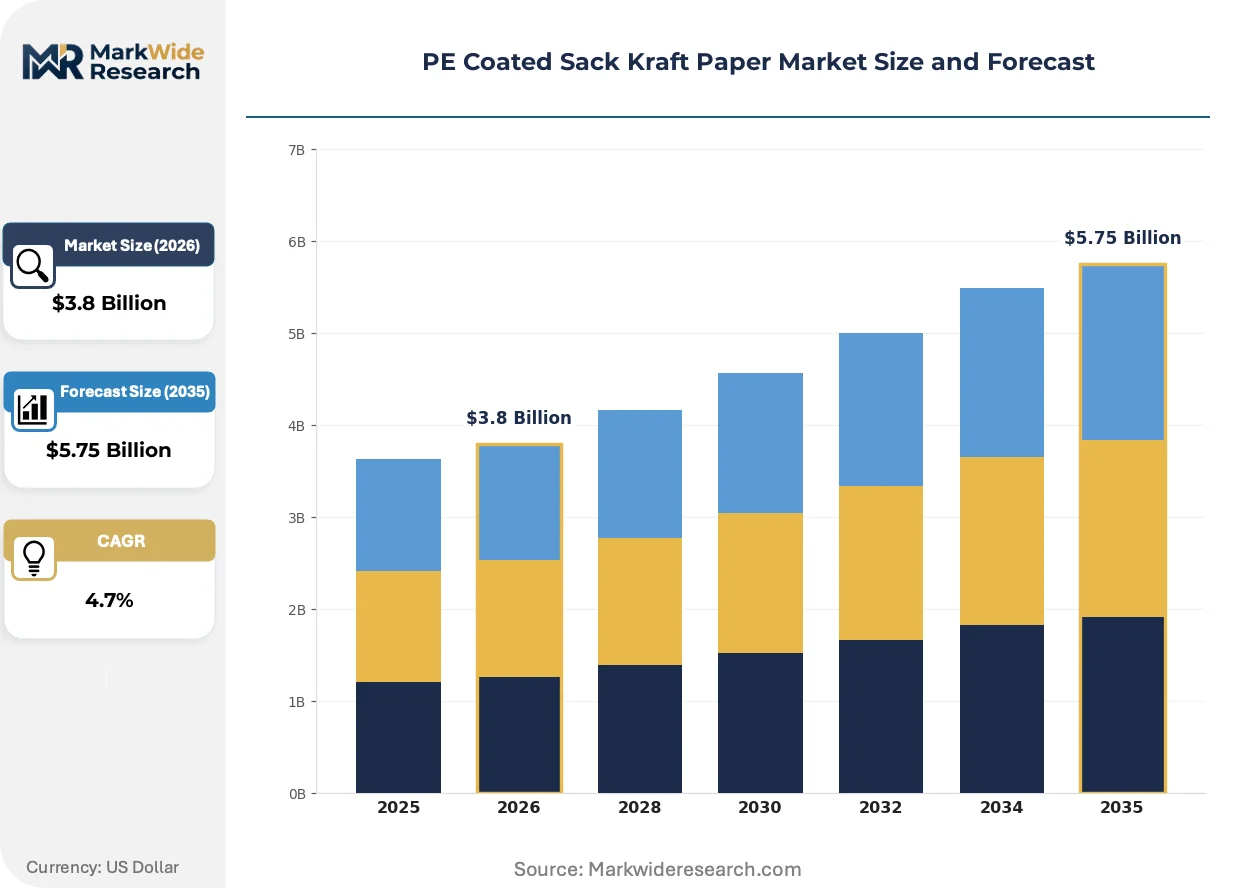
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Valve Bags, Open Mouth Bags, Pasted Valve Bags End User: Food Industry, Chemical Industry, Agriculture, Building Materials Application: Packaging, Shipping, Storage, Retail Grade: Standard Grade, High Strength Grade, Medium Grade, Specialty Grade |
| Companies Covered | Canfor, Gascogne Group, Mondi Group, Smurfit Kappa, BillerudKorsnäs, WestRock, Nordic Paper, International Paper, Segezha Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PE Coated Sack Kraft Paper Market Strategic Shifts
Formulation chemistry and equipment access models are restructuring competitive entry barriers, while regulatory fragmentation across export markets is fragmenting specification standards.
Water-based barrier coatings are migrating from niche food-contact applications toward cement and building materials packaging. Nordic Paper and specialty converters in Denmark are piloting starch-polymer hybrid layers at 8-15 gsm to replace conventional PE extrusion. The technology is migrating from premium organic certification segments into cost-sensitive industrial verticals where moisture resistance requirements are moderate but recyclability claims carry procurement weight.
EU Packaging and Packaging Waste Regulation implementation timelines are reshaping material specifications across export-oriented supply chains. The framework mandates recyclability-by-design criteria that disfavor multi-layer flexible packaging in favor of mono-material kraft structures. Cement and chemical distributors in Germany and the Netherlands are now requiring recyclability certifications that PE-coated kraft satisfies more readily than woven polypropylene alternatives.
Automated filling line integration is compressing dimensional tolerance requirements for valve bag suppliers. Cement producers in India and Turkey are specifying width tolerances of ±2mm to prevent jamming on high-speed rotary packers. This specification tightening favors integrated pulp-to-paper operations with in-house coating control over merchant converters sourcing base kraft from multiple mills.
PE Coated Sack Kraft Paper Market Segmentation
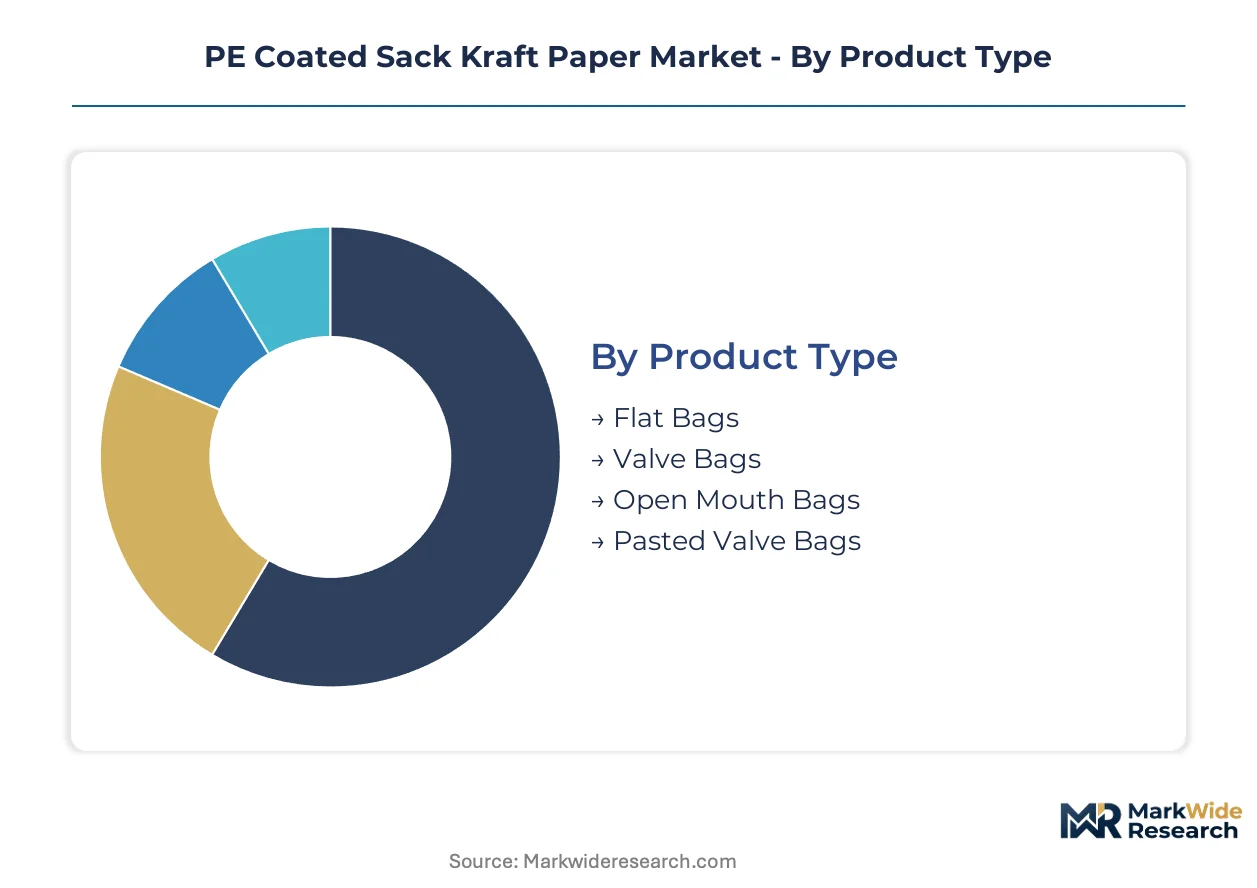
PE coated sack kraft paper serves distinct performance requirements across moisture-sensitive bulk commodities. Each segment category reflects divergent technical specifications, regulatory compliance thresholds, and automation compatibility demands that shape procurement patterns.
Product Type:
Bag construction determines filling line compatibility and sealing integrity across automated packaging environments.
- Valve Bags:Self-sealing tubular construction with integrated valve sleeves enables high-speed rotary filling without additional closure equipment. Cement producers in India and Vietnam specify valve bags for moisture-sensitive bulk goods where automated throughput exceeds 3,000 bags per hour.
- Flat Bags:Simple open-end construction requires manual or mechanical sealing after filling. Agricultural distributors in Maharashtra and Gujarat favor flat bags for fertilizer packaging where lower equipment investment outweighs speed requirements.
- Open Mouth Bags:Extended throat design accommodates shovel or scoop filling for small-batch chemical and food-grade applications.
- Pasted Valve Bags:Pre-applied adhesive closure eliminates heat-sealing equipment for converters lacking extrusion coating capacity.
Established volume favors Valve Bags; emerging adoption favors Pasted Valve Bags.
End User:
Industry verticals impose divergent barrier specifications and certification requirements on PE coating formulations.
- Building Materials:Cement and construction chemical producers demand high-strength grades with tear resistance exceeding 800 mN to survive palletized distribution. Infrastructure procurement in emerging economies concentrates volume here.
- Agriculture:Fertilizer and seed packaging requires moderate moisture resistance combined with UV stability for outdoor storage. Indian state-level agricultural subsidies are lifting consumption of coated kraft over woven polypropylene alternatives.
- Chemical Industry:Hygroscopic powder and granule packaging demands precise moisture vapor transmission rates below 5 g/m²/day.
- Food Industry:Dual FDA and EU food-contact compliance extends qualification cycles by 12-18 months but commands premium positioning.
Procurement scale concentrates in Building Materials; margin expansion concentrates in Food Industry.
Application:
Functional use case determines PE layer weight, heat-seal temperature requirements, and print surface specifications.
- Packaging:Primary containment function demands 25-40 gsm PE extrusion coating for moisture barrier integrity. Automated filling lines in Turkey and India specify width tolerances of ±2mm to prevent jamming.
- Shipping:Multi-drop handling resistance requires reinforced bottom construction and enhanced tear propagation resistance.
- Storage:Extended warehouse exposure prioritizes UV stabilization and stack-load compression strength over seal speed.
- Retail:Consumer-facing print quality and shelf appearance specifications favor bleached substrates with high-gloss PE surfaces.
Volume throughput dominates Packaging; specification complexity climbs fastest in Retail.
Grade:
Fiber engineering and coating sophistication stratify performance tiers and pricing structures.
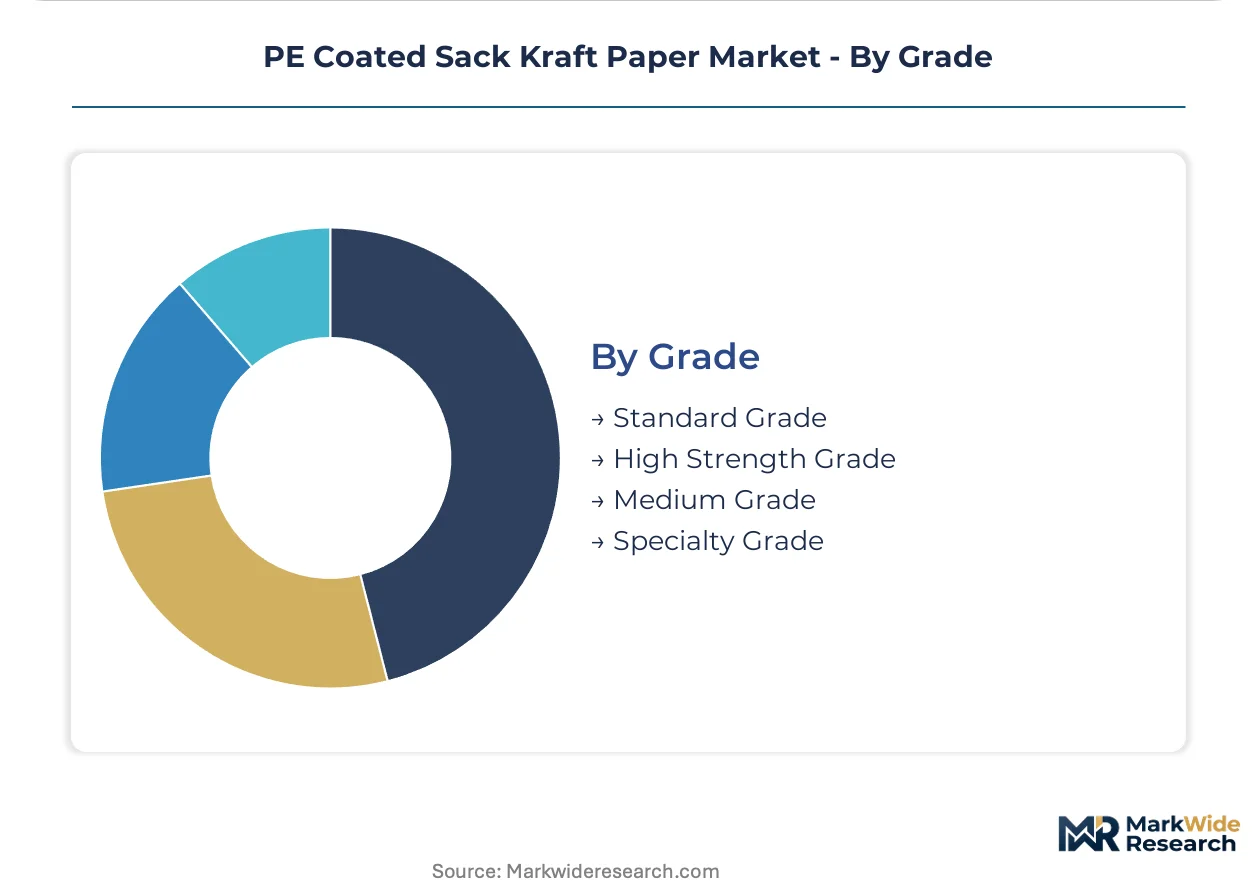
- High Strength Grade:Extended softwood fiber cooking and refined beating schedules achieve tear indices above 12 mN·m²/g. Building materials and agricultural sectors absorb this premium where spillage losses during distribution exceed material cost differentials.
- Specialty Grade:Custom fiber blends and food-contact certified PE formulations serve dual FDA/EU compliance requirements. Nordic Paper concentrates Scandinavian production here to exploit certified kraft scarcity.
- Standard Grade:Conventional unbleached sulfate pulp meets general-purpose moisture resistance for non-critical applications.
- Medium Grade:Intermediate fiber refinement balances cost and performance for chemical industry bulk packaging.
Margin pools concentrate in Specialty Grade; volume expansion concentrates in High Strength Grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance evaluation protocols and ECHA compliance deadlines are reshaping procurement specifications across European export supply chains. Infrastructure spending programs in emerging economies are accelerating valve bag adoption for moisture-sensitive bulk commodities.
India
Cement producers in Maharashtra and Gujarat are specifying high-strength grades with tear resistance exceeding 800 mN for palletized distribution. The Bureau of Indian Standards enforces packaging quality norms for fertilizer and agricultural commodities under BIS certification schemes. Converter clusters in Ahmedabad and Mumbai are expanding PE lamination capacity to serve domestic building materials demand.
Germany
Cement and chemical distributors in North Rhine-Westphalia now require recyclability certifications favoring mono-material kraft structures over woven polypropylene alternatives. The EU Packaging and Packaging Waste Regulation mandates recyclability-by-design criteria that PE-coated kraft satisfies more readily than multi-layer flexible packaging. Industrial packaging converters in the Ruhr region are upgrading extrusion coating lines to meet tightened width tolerances of ±2mm for automated filling lines.
United States
Building materials distributors in Texas and California are sourcing FDA food-contact certified grades for dual-use chemical and food-grade applications. FDA Title 21 substance notification reviews extend product qualification cycles by 12-18 months for export-oriented suppliers. Integrated pulp-to-paper operations in the Pacific Northwest sustain margin control through captive fiber supply and in-house coating capacity.
Sweden
Specialty food-contact kraft production clusters in Värmland and Västernorrland counties exploit certified kraft scarcity to command premium positioning. REACH restrictions on polymer additives are accelerating substitution timelines for legacy slip agents and antioxidants in extrusion coatings. Nordic mills concentrate Scandinavian production of dual FDA/EU compliant grades to serve export markets requiring extended qualification documentation.
Vietnam
Infrastructure procurement in Ho Chi Minh City and Hanoi is lifting throughput requirements for valve bags on high-speed rotary packers exceeding 3,000 bags per hour. State-level construction investment programs prioritize moisture-resistant packaging for cement exports to ASEAN markets. Converter operations in Binh Duong province are leasing extrusion coating equipment to access PE lamination capacity without capital-heavy mill infrastructure.
PE Coated Sack Kraft Paper Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. Integrated pulp-to-paper operations with in-house coating capacity dominate premium-grade supply, while merchant converters leasing extrusion equipment serve cost-sensitive industrial verticals. Three strategic archetypes define competitive positioning: captive fiber-coating integrators, specialty certification specialists, and asset-light regional converters. Dominant competitive moves include geographic expansion into Indian agricultural markets and strategic partnerships for bio-based barrier technology licensing.
Among integrated Scandinavian producers, Mondi Group and BillerudKorsnäs exemplify the captive fiber-coating archetype through European mill networks controlling specialty grade supply. Nordic Paper occupies a certification-specialist position concentrated in food-contact kraft scarcity. These three entities anchor the premium-tier vector where dual FDA and EU compliance extends qualification cycles and sustains margin pools.
| Leading Market Players |
|---|
| Canfor |
| Gascogne Group |
| Mondi Group |
| Smurfit Kappa |
| BillerudKorsnäs |
| WestRock |
| Nordic Paper |
| International Paper |
| Segezha Group |
| Others |
Value Chain & Pricing Dynamics
Converter undercapacity in Vietnam and Indonesia is forcing mid-tier suppliers into aggressive spot-market purchasing, eroding margin buffers and compressing contract pricing discipline across Southeast Asian PE lamination operations.
Pricing Analysis
Certification level (FDA food-contact versus industrial-grade) creates the primary spread between premium and base pricing tiers. Three-tier pricing structure across premium, standard, and economy levels dominates transactional flows, with dual FDA/EU compliance commanding substantial premiums over single-jurisdiction certification. Cost compression in standard grades is intensifying because pulp input volatility and extrusion coating skill scarcity are squeezing converter margins. Agricultural distributors in India exhibit highest price sensitivity due to state subsidy procurement frameworks, while food-industry buyers demonstrate lowest sensitivity given qualification cycle lock-in effects.
Supply Chain Analysis
Export-control regimes on advanced extrusion coating equipment from European and Japanese manufacturers are limiting technology transfer to emerging-market converters, constraining capacity expansion timelines. Supply concentrates in Sweden, Finland, and Germany for specialty food-contact grades, while India and Vietnam anchor high-strength industrial production. Raw material dependencies rest on Nordic softwood pulp, polyethylene resin, and specialty polymer additives. Single-source vulnerability from Scandinavian mill concentration for certified kraft grades poses structural risk. Distribution runs through building materials distributors, agricultural cooperatives, and chemical packaging converters with direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where dual FDA/EU qualification cycles create switching costs that entrench incumbent positions against merchant converter competition.
For Market Incumbents: Build certification-moat depth by accelerating dual-jurisdiction food-contact qualification pipelines before REACH additive restrictions tighten further. Secure backward integration into pulp supply through long-term offtake agreements with Nordic mills to defend against harvest-cycle volatility. Add extrusion coating capacity in Gujarat and Maharashtra to capture Indian agricultural demand growth before leasing models democratize access. For New Entrants and Emerging Players: Pursue equipment-leasing arbitrage in Vietnam and Indonesia where capital barriers are collapsing and skilled technician scarcity creates service-differentiation openings. Target pasted valve bag segments in Indian fertilizer distribution where automation requirements are moderate and import substitution demand is accelerating. Lead with water-based barrier coating pilots to exploit EU Packaging Waste Regulation recyclability mandates ahead of incumbent reformulation cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mid-tier converter operations as leasing models displace mill-scale infrastructure requirements. Long-term viability favors specialty certification specialists with captive Scandinavian pulp access over asset-light regional converters exposed to spot pulp markets. Acquisition targets should display integrated coating control and established FDA notification histories. Watch for REACH substance evaluation protocol acceleration as the signal forcing consolidation among additive-dependent extrusion coaters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive fiber access insulates margin control against Nordic harvest-cycle volatility. |
| Dual FDA/EU Certification Investment | Extended qualification cycles create switching-cost moats in food-contact segments. |
| Equipment Leasing Model Expansion | Lower capital barriers enable mid-tier converter entry without mill-scale infrastructure. |
| Water-Based Barrier Coating Pilot | Starch-polymer hybrid layers align with EU recyclability-by-design mandates. |
| Indian Regional Capacity Addition | Gujarat and Maharashtra clusters capture agricultural packaging demand outpacing domestic supply. |
Study Parameters
Operator-level perspectives from extrusion coating technicians, pulp procurement managers, cement plant packaging engineers, and agricultural cooperative buyers anchored the qualitative base. Primary fieldwork combined structured interviews across converter operations in India, Vietnam, and Germany with secondary validation from ECHA substance evaluation databases, FDA Title 21 food-contact substance notifications, BIS certification registries, and customs trade flows for unbleached sulfate pulp. Bottom-up volume modeling triangulated against top-down macroeconomic drivers including infrastructure spending indices and agricultural output forecasts.
Scenario-bracketing around REACH compliance timelines and FDA notification backlogs shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include bag construction type, end-use industry vertical, PE coating weight tier, and grade certification level. CAGRs were derived from elasticity-adjusted demand curves incorporating pulp price volatility and extrusion coating capacity expansion rates. Forecast inputs centered on Indian infrastructure procurement acceleration and EU Packaging Waste Regulation implementation pacing.
Sensitivities concentrate around ECHA additive restriction acceleration, Nordic softwood harvest disruption, and Indian state subsidy policy shifts. Forecasts reflect documented assumptions on qualification cycle durations and equipment leasing adoption curves. Material shifts in REACH substance evaluation protocols or FDA notification review timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Sublimation Paper Market
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Kraft Paper Mailer Market
Paper & Paperboard Packaging
Global Food Contact Papers Market
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
Anti-Slip Coated Paper Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market