
 Asia - Pacific Disposable Tableware Market | 2026-2036
Asia - Pacific Disposable Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
Asia - Pacific Disposable Tableware Market Outlook
GB standards compliance for food-contact materials is unwinding the competitive landscape across the Asia-Pacific disposable tableware sector. Taizhou Fuling Plastics leverages integrated resin-to-film manufacturing to dominate export channels into North American food service buyers. Oji Holdings anchors its position through captive pulp supplies and coated-paper R&D intensity in Japan. Nine Dragons Paper competes aggressively on kraft-based bowl and plate volumes, extending its packaging expertise into molded fiber tableware applications.
Asia-Pacific disposable tableware encompasses single-use serving vessels manufactured from plastic resins, paper substrates, biodegradable polymers, or expanded foam, typically featuring heat resistance thresholds of 80-120°C and grease-barrier coatings for wet food contact. These products serve commercial food service, institutional catering, and household consumption where washing infrastructure is absent or cost-prohibitive. The material segment splits sharply: plastic and foam lines face margin compression under regulatory phase-outs, while biodegradable alternatives capture premium positioning despite higher unit costs. Paper-based cups and plates sustain volume leadership across restaurants and catering services, though bowls are gaining fastest among cloud kitchen operators demanding stackable, leak-resistant formats.
China's SAMR enforces GB 4806 food-contact safety standards that dictate resin migration limits and additive prohibitions, while India's BIS certification mandates IS 9833 compliance for plastic articles in food applications. Japan's METI circular economy roadmap pressures manufacturers toward mono-material designs that simplify post-consumer sorting. Stakeholders must monitor regulatory divergence between national standards and emerging ASEAN harmonization frameworks to avoid fragmented compliance investments.
Market Dynamics
Food delivery platform procurement consolidation across Southeast Asia is compressing supplier margins while simultaneously accelerating volume throughput for compliant manufacturers. Cloud kitchen operators in India and China now specify stackable, leak-resistant bowl formats that force mold-fiber equipment upgrades across the supplier base.
Growth Catalysts
- India's BIS IS 9833 certification mandate:Food-contact plastic compliance requirements are filtering out informal producers and concentrating procurement among certified suppliers serving quick-service restaurant chains.
- Cloud kitchen network expansion:Delivery-native food preparation facilities across Jakarta, Bangkok, and Manila are generating sustained demand for single-use bowl and compartment-tray formats optimized for thermal retention.
- Biodegradable polymer R&D intensity:PLA and bagasse material processing advances are narrowing the performance gap with conventional plastics for hot-food applications above 100°C.
Market Restraints
- Pulp fiber input cost volatility:Kraft paper and bagasse pricing fluctuates with Indonesian and Thai agricultural harvest cycles, squeezing molded-fiber tableware margins unpredictably.
- GB 4806 resin migration testing backlog:SAMR certification queue delays in China extend product launch timelines by four to six months for new polypropylene formulations.
- Reusable container deposit schemes:Singapore and South Korea pilot programs threaten single-use volume in institutional catering segments where washing infrastructure exists.
Strategic Opportunities
- Vietnam's underpenetrated central region:Da Nang and Hue food service corridors lack established disposable tableware distribution, creating first-mover positioning for compliant suppliers.
- Dual carbon goals procurement preference:China's state-owned enterprise catering contracts now weight carbon footprint metrics, advantaging domestic bagasse and bamboo fiber producers.
- Direct-platform supplier integration:GrabFood and Foodpanda are experimenting with consolidated packaging procurement, bypassing traditional distributor markups for high-volume restaurant partners.
Industry Challenges
- Mono-material design engineering scarcity:Japan's METI circular economy roadmap demands simplified post-consumer sorting, yet few regional designers possess expertise in eliminating multi-layer barrier coatings.
- Molded-fiber capex intensity:Automated pulp-forming lines for leak-resistant bowls require capital deployment that mid-scale suppliers struggle to finance independently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia - Pacific Disposable Tableware Market |
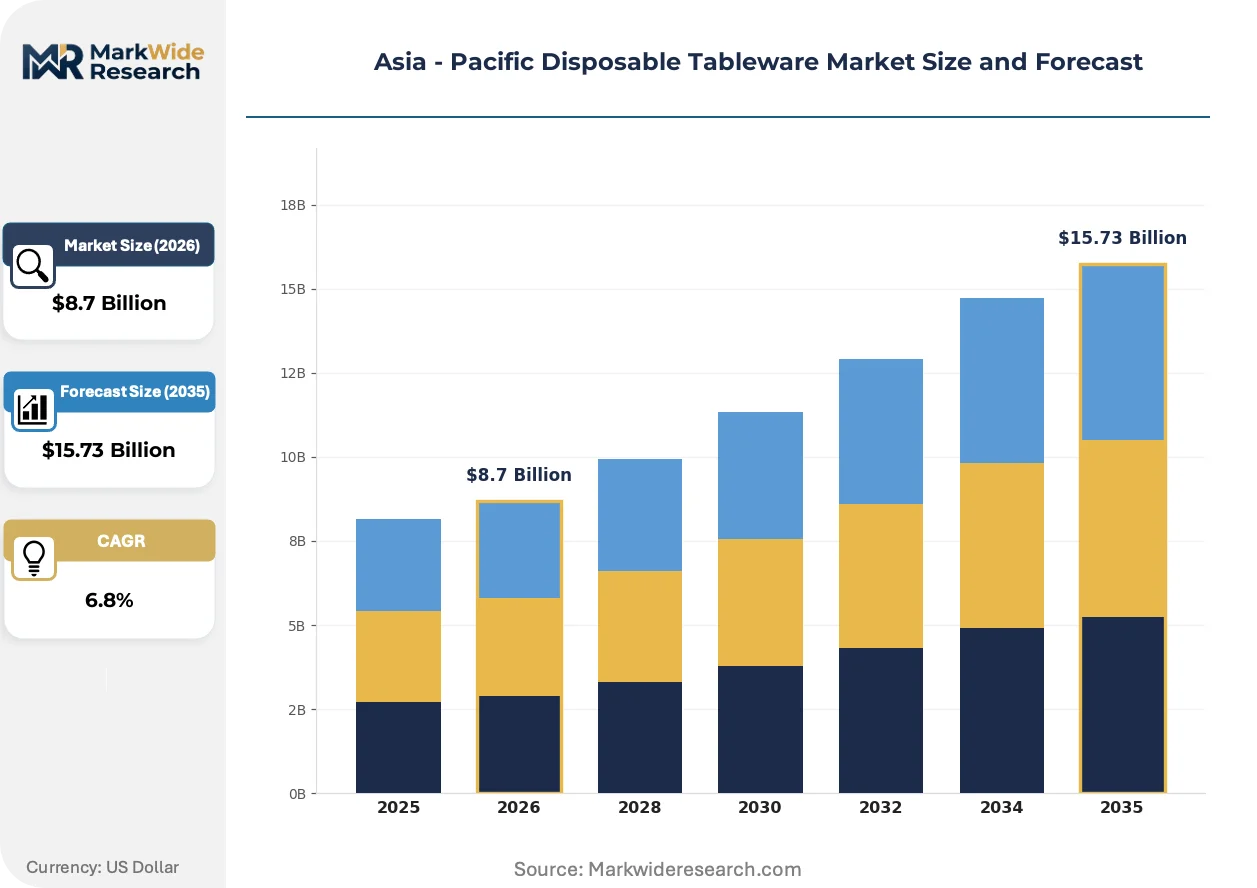
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Cups, Cutlery, Bowls Material: Plastic, Paper, Biodegradable, Foam End User: Restaurants, Catering Services, Retail Outlets, Households Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Taizhou Fuling Plastics, Guangdong Huasheng Meto, Oji Holdings, Nippon Paper, Nine Dragons Paper, Huhtamaki Oyj, Dart Container Corporation, Duni AB, Toyo Seikan, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia - Pacific Disposable Tableware Market Strategic Shifts
Material science breakthroughs and regulatory compliance automation are converging to redefine product specifications and manufacturing economics across Asia-Pacific disposable tableware production.
Polylactic acid barrier coatings are decomposing the traditional price-performance tradeoff between biodegradable and petroleum-based food containers. Quick-service chains in South Korea and Taiwan are specifying PLA-lined paper bowls for hot noodle applications previously reserved for polypropylene. The structural consequence is margin compression for conventional plastic extruders who lack biopolymer compounding capabilities.
China's SAMR is tightening GB 4806.7 additive prohibition lists and accelerating automated migration testing protocols. Manufacturers must now reformulate colorants and slip agents ahead of scheduled compliance windows or face delisting from food service procurement catalogs. Small-scale Guangdong and Zhejiang molders without in-house polymer laboratories are outsourcing testing to third-party certification bodies, adding cost layers.
Restaurant procurement consolidation through delivery platform vendor programs is displacing traditional cash-and-carry distributor relationships. Cloud kitchen operators in Mumbai and Bangalore now source tableware through Swiggy and Zomato negotiated supply agreements rather than independent packaging wholesalers. This channel shift concentrates volume with platform-approved suppliers who meet unified sustainability disclosure requirements.
Asia - Pacific Disposable Tableware Market Segmentation
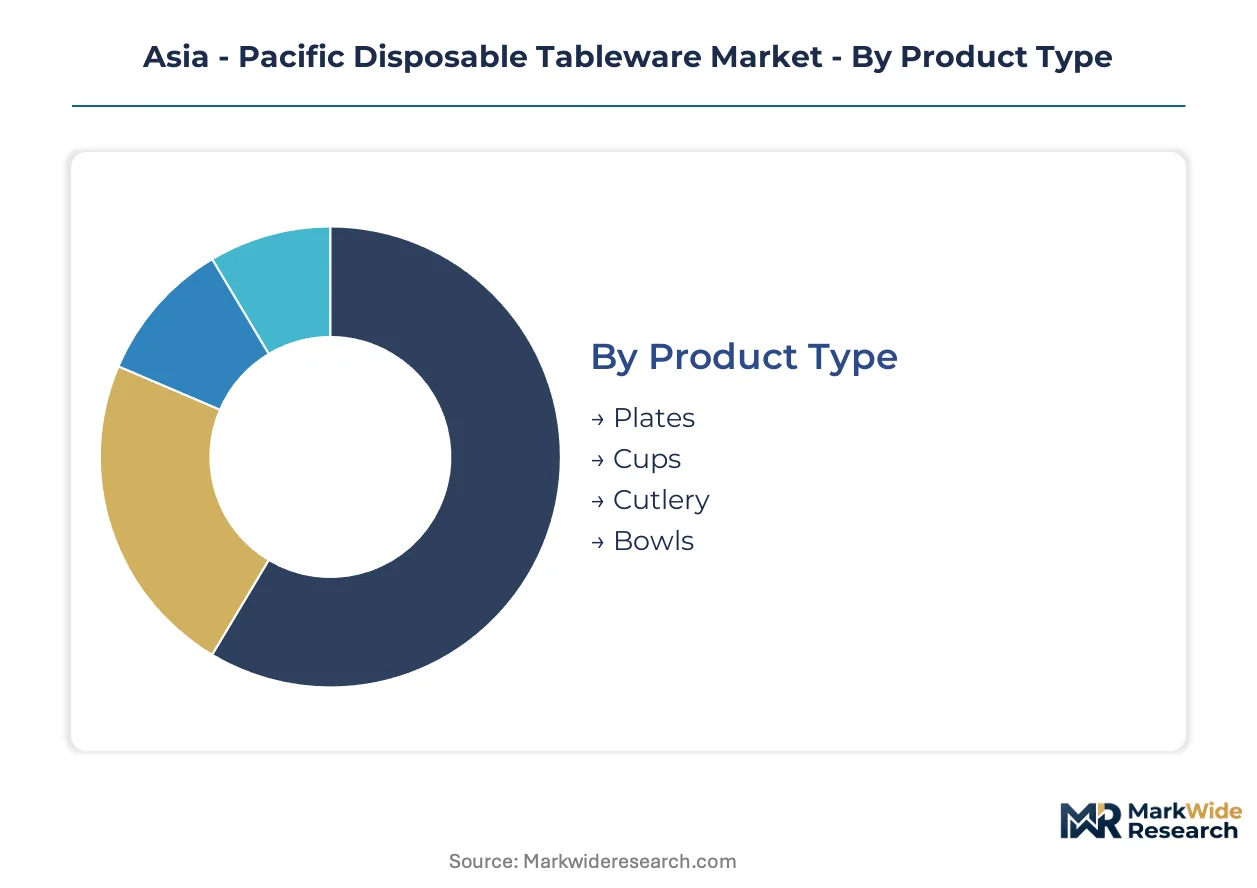
Disposable tableware procurement patterns across Asia-Pacific diverge sharply by material compliance grade and thermal performance specification. Food service operators segment their sourcing strategies around GB 4806 migration limits, BIS IS 9833 certification status, and platform-mandated sustainability disclosures.
Product Type:
Regulatory differentiation in food-contact safety standards reshapes competitive positioning across serving vessel formats. SAMR enforces distinct testing protocols for flatware versus depth-containing vessels, creating compliance cost asymmetries.
- Plates:Flat-surface designs in kraft paper and bagasse dominate institutional catering procurement across Indian quick-service chains. BIS certification mandates filter informal suppliers from restaurant procurement catalogs.
- Bowls:Depth-containing vessels with grease-barrier coatings capture premium positioning among cloud kitchen operators in Jakarta and Manila. Leak-resistant molded-fiber specifications force equipment upgrades across mid-scale suppliers.
- Cups:Hot-beverage formats face GB 4806.7 additive prohibitions on colorants and slip agents.
- Cutlery:Single-use utensils encounter phase-out pressures under Japan METI circular economy roadmaps.
Plates handle the majority of throughput; bowls are expanding most quickly on share.
Material:
Cost tier stratification separates premium biodegradable positioning from commodity plastic and foam volumes facing regulatory compression.
- Plastic:Polypropylene and polystyrene formats sustain volume leadership through heat resistance thresholds of 100-120°C. Margin compression accelerates as China's dual carbon goals and India's Plastic Waste Management Rules tighten procurement pathways.
- Paper:Kraft-based cups and plates anchor restaurant segment demand with established recycling infrastructure. Coated-paper R&D intensity at Japanese manufacturers advances grease-barrier performance for wet food contact.
- Biodegradable:PLA and bagasse alternatives narrow the price-performance gap with conventional plastics.
- Foam:Expanded polystyrene faces explicit phase-out schedules across multiple Asia-Pacific jurisdictions.
Paper commands the largest installed base; biodegradable alternatives are climbing the fastest on procurement preference.
End User:
Application-specific requirements drive specification divergence between commercial food service and household consumption patterns.
- Restaurants:Full-service and quick-service chains specify stackable, leak-resistant formats with unified sustainability disclosure requirements. Platform procurement consolidation through GrabFood and Foodpanda concentrates volume with certified suppliers.
- Catering Services:Event and institutional catering demands thermal retention properties for extended holding periods.
- Retail Outlets:Supermarket deli and prepared-food counters require retail-branded packaging compatibility.
- Households:Consumer-packaged goods channels serve washing-infrastructure-deficient residential segments.
Restaurants absorb the dominant procurement volume; catering services show the steepest expansion trajectory as event formats recover.
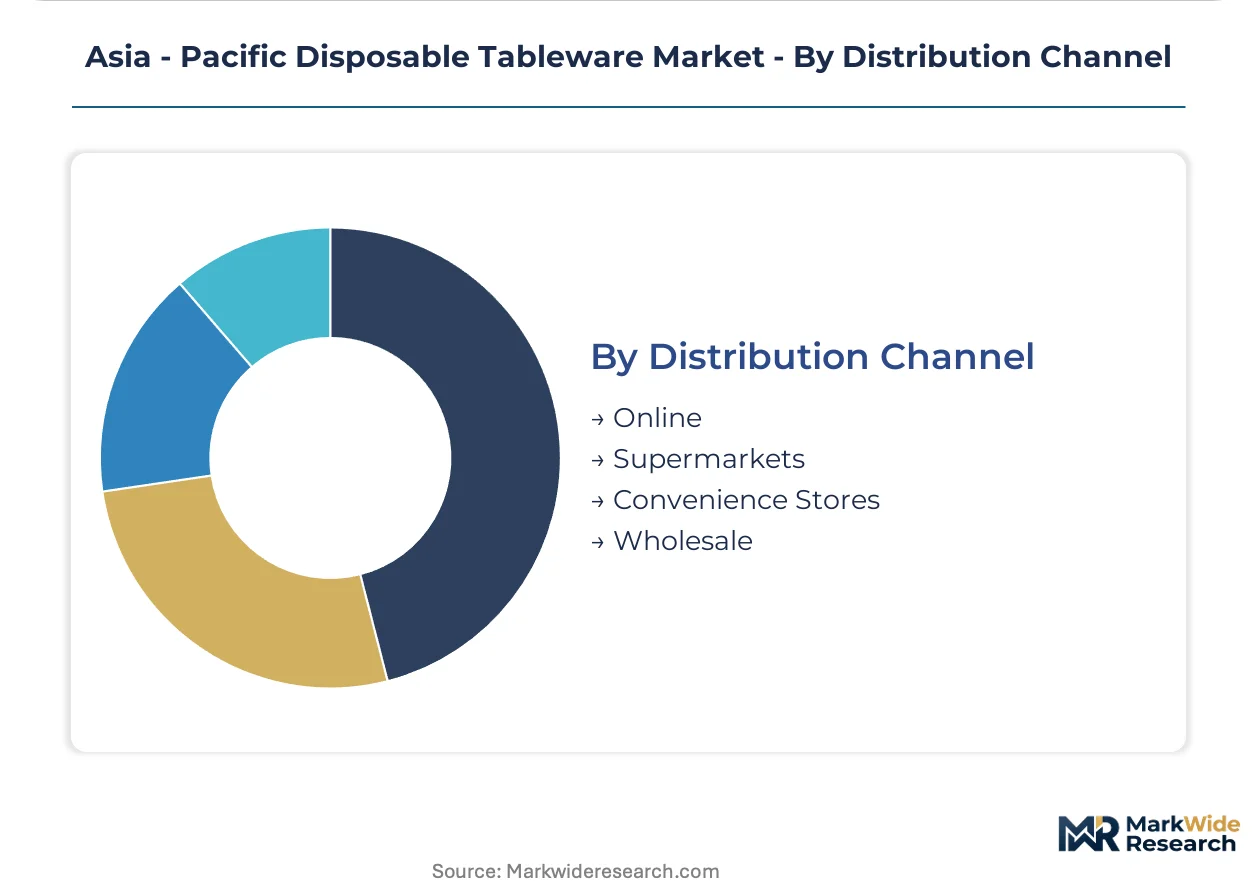
Distribution Channel:
Customer type stratification separates platform-integrated procurement from traditional wholesale and retail pathways.
- Online:Direct-platform supplier integration through Swiggy and Zomato vendor programs displaces cash-and-carry relationships. Consolidated packaging procurement experiments bypass traditional distributor markups for high-volume restaurant partners.
- Supermarkets:Retail shelf presence serves household and small commercial buyers with standardized SKU configurations.
- Convenience Stores:Proximity-based replenishment supports urban food service micro-operations.
- Wholesale:Traditional distributor networks retain penetration in Vietnam's underpenetrated central region and other emerging corridors.
Wholesale channels retain volume leadership; online distribution is gaining share fastest through platform procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and India's BIS certification mandates are reshaping procurement pathways across the Asia-Pacific disposable tableware sector. National regulatory divergence creates compliance cost asymmetries that favor certified suppliers with in-house testing capabilities. Food delivery platform consolidation accelerates volume concentration in urban corridors with established distribution infrastructure.
China
Cloud kitchen operators in Shanghai and Beijing now specify stackable, leak-resistant bowl formats that force equipment upgrades across mid-scale suppliers. SAMR enforces GB 4806.7 additive prohibitions on colorants and slip agents, extending product launch timelines by four to six months for new polypropylene formulations. The Pearl River Delta manufacturing cluster around Guangzhou and Shenzhen dominates export-oriented plastic and molded-fiber production.
India
Quick-service restaurant chains in Mumbai and Bangalore concentrate procurement among BIS IS 9833 certified suppliers as compliance requirements filter out informal producers. The Plastic Waste Management Rules tighten material pathways for conventional polypropylene formats. Gujarat's chemical manufacturing belt supplies resin feedstocks to domestic molders serving the Delhi-NCR food service corridor.
Japan
METI's circular economy roadmap pressures manufacturers toward mono-material designs that simplify post-consumer sorting. Coated-paper R&D intensity advances grease-barrier performance for wet food contact in Tokyo and Osaka catering networks. The Kanto region anchors domestic pulp-to-tableware integration through captive fiber supplies.
Vietnam
Da Nang and Hue food service corridors lack established disposable tableware distribution, creating first-mover positioning for compliant suppliers. Agricultural harvest cycles in the Mekong Delta generate bagasse feedstock volatility that squeezes molded-fiber margins unpredictably. Ho Chi Minh City serves as the primary import and redistribution hub for Southeast Asian procurement.
South Korea
PLA-lined paper bowl specifications for hot noodle applications displace conventional polypropylene in Seoul quick-service procurement. Pilot reusable container deposit schemes threaten single-use volume in institutional catering segments where washing infrastructure exists. Busan-Ulsan chemical complexes supply biopolymer resins to domestic converters.
Asia - Pacific Disposable Tableware Market Competitive Environment
Player mix skews toward integrated resin-to-film manufacturers and captive pulp suppliers with in-house barrier coating capabilities. The supplier base stratifies across three tiers: multinational packaging conglomerates with regional manufacturing footprints, domestic paper and plastics specialists with backward integration into raw materials, and emerging biopolymer compounders targeting premium sustainability positioning. Dominant competitive moves include automated mold-fiber equipment upgrades for leak-resistant bowl production and direct-platform supplier integration bypassing traditional distributor markups.
Among Asia-Pacific-based fabricators, Taizhou Fuling Plastics and Oji Holdings occupy distinct archetype positions. Taizhou Fuling exemplifies the integrated resin-to-film manufacturer serving export channels into North American food service buyers. Oji Holdings anchors the captive pulp supply tier through in-house fiber sourcing and coated-paper R&D intensity. Nine Dragons Paper sits within the packaging-to-tableware extension archetype, leveraging kraft-based expertise into molded fiber applications. Huhtamaki Oyj and Dart Container Corporation represent multinational conglomerates with regional manufacturing scale.
| Leading Market Players |
|---|
| Taizhou Fuling Plastics |
| Guangdong Huasheng Meto |
| Oji Holdings |
| Nippon Paper |
| Nine Dragons Paper |
| Huhtamaki Oyj |
| Dart Container Corporation |
| Duni AB |
| Toyo Seikan |
| Others |
Value Chain & Pricing Dynamics
GB 4806 certification status gates both supplier qualification and price differentiation across Asia-Pacific disposable tableware procurement, concentrating volume with certified manufacturers who command premium positioning over informal competitors. SAMR testing backlogs and BIS IS 9833 mandates create compliance cost asymmetries that reshape competitive economics.
Pricing Analysis
Certification level (BIS IS 9833/GB 4806-compliant versus uncertified) creates the primary spread between premium and commodity tiers. Three-tier pricing structure across certified premium, compliant standard, and informal economy levels tracks resin migration testing completion and platform sustainability disclosure status. Cost compression in plastic and foam segments is intensifying because China's dual carbon goals and India's Plastic Waste Management Rules tighten procurement pathways. Quick-service restaurant chains show highest price sensitivity; cloud kitchen operators demonstrate lowest sensitivity due to platform-negotiated supply agreements.
Supply Chain Analysis
Pearl River Delta manufacturing concentration around Guangzhou and Shenzhen anchors regional resin-to-tableware conversion capacity. Raw material flows draw from Indonesian and Thai bagasse harvest cycles, Saudi and UAE polypropylene resin shipments, and domestic Guangdong pulp supplies. Single-source vulnerability runs through SAMR-certified testing laboratory capacity, where queue delays extend product launch timelines unpredictably. Distribution runs through platform-integrated vendor programs displacing traditional cash-and-carry wholesaler relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific disposable tableware demand cycles with food delivery platform expansion and cloud kitchen network buildouts, positioning the sector for recovery as Southeast Asian urban food service corridors deepen penetration.
For Market Incumbents: Secure SAMR pre-certification for next-generation polypropylene formulations ahead of scheduled GB 4806.7 additive prohibition windows. Capture backward integration into bagasse pulp supplies to offset Indonesian harvest cycle volatility squeezing molded-fiber margins. Defend against emerging biopolymer compounders by accelerating coated-paper R&D intensity for hot-food barrier performance. For New Entrants and Emerging Players: BIS IS 9833 fast-track certification unlocks procurement access to Mumbai and Bangalore quick-service restaurant chains filtering informal suppliers. Vietnam's underpenetrated Da Nang and Hue corridors offer first-mover positioning with minimal established distribution competition. Pursue direct-platform supplier integration through GrabFood and Foodpanda vendor programs bypassing traditional distributor markups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated mold-fiber equipment for leak-resistant bowl production. Five-to-ten year viability favors suppliers with captive pulp supplies and in-house polymer laboratories. Target acquisition archetype: mid-scale Guangdong molders with SAMR testing relationships and export channel relationships. Signal to watch: platform procurement consolidation rate as Swiggy and Zomato expand vendor program coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bagasse Pulp | Captive supply of Mekong Delta agricultural residue insulates margins from harvest cycle volatility. |
| Automated Mold-Fiber Equipment Upgrade | Leak-resistant bowl production capability captures cloud kitchen procurement specifications in Jakarta and Manila. |
| Direct-Platform Supplier Integration | GrabFood and Foodpanda vendor program access concentrates volume with approved certified suppliers. |
| GB 4806 Pre-Certification Investment | SAMR additive prohibition compliance ahead of scheduled windows prevents delisting from procurement catalogs. |
| Coated-Paper R&D Intensification | Grease-barrier performance advances for wet food contact defend against PLA-lined paper bowl substitution. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with procurement directors at quick-service chains, cloud kitchen operators, platform vendor program managers, and molded-fiber equipment manufacturers; and secondary validation through SAMR GB 4806 filing databases, BIS certification registries, Indonesian and Thai agricultural harvest statistics, and food delivery platform sustainability disclosure reports. Bottom-up volume triangulation across product type, material grade, and end-user segment intersected with top-down macroeconomic anchoring.
Across the projection horizon, the analytical framework modeled demand drivers including food delivery platform procurement consolidation, cloud kitchen network expansion, and regulatory compliance cost pass-through. Segmentation dimensions spanned product type (plates, bowls, cups, cutlery), material (plastic, paper, biodegradable, foam), end user (restaurants, catering services, retail, households), and distribution channel (online, supermarkets, convenience stores, wholesale). CAGRs were derived from elasticity-adjusted volume projections incorporating pulp fiber input cost volatility and certification timeline delays.
Decision-makers should treat outputs as directional under base assumptions of sustained food delivery platform growth and phased regulatory tightening; material deviation in agricultural harvest cycles or SAMR testing capacity expansion would warrant model refresh. Practitioners should keep alternative scenarios live as ASEAN harmonization frameworks and reusable container deposit pilot programs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Collapsible Tube Packaging Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Thermal Transfer Roll Market
Packaging Materials
Textile Packaging Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Face Stock Films Market
Packaging Materials
Finish Foils Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Composite Packaging Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Packaging Reel Market
Packaging Materials
Coconut Wraps Market