
 Global Strapping Market | 2026-2036
Global Strapping Market Size, Share, and Industry Trends Forecast 2026-2036
Global Strapping Market Outlook
Germany is reshaping competitive dynamics in the European strapping equipment segment through precision-engineered automation investments. FROMM Group leverages its Swiss-German engineering heritage to sustain leadership in battery-powered handheld tools. Signode anchors North American demand through integrated steel strapping systems for heavy industrial applications. Mosca competes aggressively on automated arch-type machines with real-time tension control.
Strapping comprises elongated bands of PET, PP, steel, or nylon, typically extruded or rolled to tensile strengths between 300 and 1,500 megapascals, applied to secure palletized goods, bundles, or corrugated containers against transit stress. PET strapping dominates logistics applications due to its strength-to-weight ratio and compatibility with automatic tooling, while steel strapping retains structural priority in construction and metalworking where extreme load rigidity is non-negotiable. Food and beverage end users are shifting toward embossed PP solutions to meet downstream recycling protocols without sacrificing throughput speeds.
FDA regulations in the United States govern direct-contact food packaging strapping under 21 CFR, while the EU REACH framework restricts certain phthalate plasticizers in polymer formulations. Germany's national packaging ordinance, transposing EU directives, mandates minimum recycled content thresholds that reshape raw material procurement for producers serving European customers. Stakeholders must monitor evolving extended producer responsibility schemes and calibrate material portfolios before compliance deadlines harden into market access barriers.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material recovery requirements upward, compelling strapping producers to reconfigure supply chains around recycled PET feedstock and bio-based polypropylene alternatives before compliance deadlines crystallize into market access barriers.
Growth Catalysts
- E-commerce logistics expansion:Automated fulfillment centers in Germany and the Netherlands are standardizing polyester strapping for palletized unit loads, driving specification harmonization across 3PL networks.
- REACH framework adaptation:ECHA restrictions on phthalate plasticizers in polymer formulations are accelerating R&D investment in compliant embossed PP solutions for food-contact applications.
- Automotive component automation:German OEM supplier parks are deploying arch-type strapping systems with real-time tension control, compressing replacement cycles for legacy equipment.
Market Restraints
- Steel input cost volatility:Scrap metal price swings and energy-intensive rolling mill operations in China compress margin stability for heavy-duty strapping producers serving construction and metalworking end uses.
- PET feedstock concentration:Virgin and recycled PET resin supply clusters in the US Gulf Coast and Rotterdam-Antwerp corridor create geographic vulnerability for European and North American strapping extruders.
- Biodegradable polymer performance gap:PLA and starch-blend alternatives lack the tensile strength and automatic tooling compatibility required for high-speed logistics applications, limiting substitution penetration.
Strategic Opportunities
- India warehouse automation:PLI scheme incentives for logistics infrastructure and cold chain expansion are opening specification windows for battery-powered handheld strapping tools in pharmaceutical distribution.
- Closed-loop recycling systems:Extended producer responsibility schemes in France and Italy are creating revenue streams for strapping producers offering take-back programs with verified recycled content certificates.
- RFID-embedded smart strapping:Convergence of polymer extrusion with printed electronics enables pallet-level tracking for high-value pharmaceutical and electronics shipments.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA 21 CFR compliance for US food contact and EU REACH registration for polymer additives extends product launch cycles by 18-24 months.
- Legacy system integration friction:Automated strapping line retrofits in mature automotive plants require custom mechanical interfaces with existing conveyor architectures, inflating deployment costs.
- Skilled technician scarcity:Maintenance of precision tension control systems demands mechatronics expertise that outpaces vocational training pipeline output in Central European manufacturing regions.
Report Scope
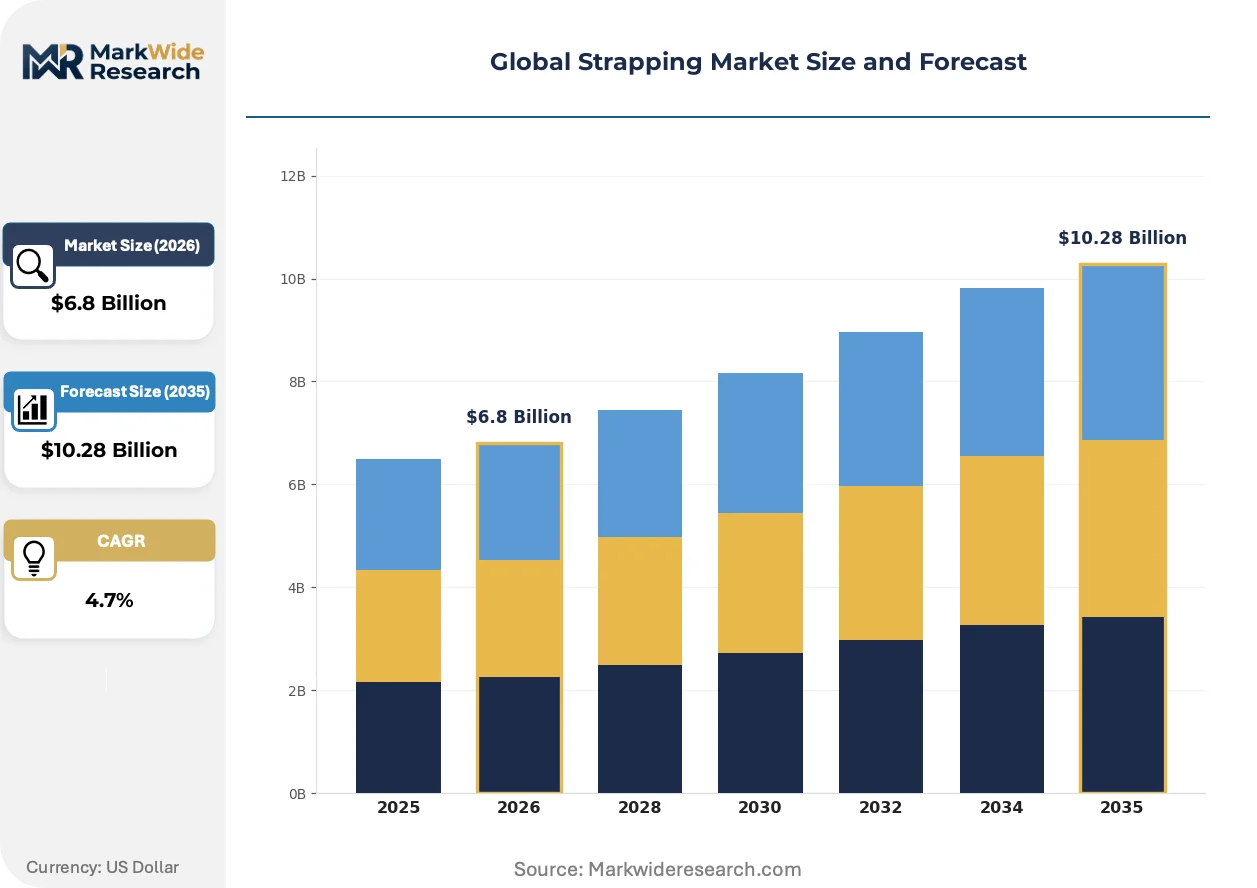
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Strapping Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PET, PP, Steel, Nylon Application: Packaging, Construction, Manufacturing, Logistics End User: Food & Beverage, Pharmaceuticals, Electronics, Retail Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Mosca, FROMM Group, Signode, Strapack, Polychem, Baosteel, Scientex Berhad, Teufelberger, Samuel Strapping, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Strapping Market Strategic Shifts
Sensor-integrated strapping equipment and AI-driven tension algorithms are compressing operational variance in high-volume logistics environments, while regulatory pressure on material circularity accelerates formulation innovation across polymer categories.
Machine vision-guided strapping heads with predictive maintenance algorithms are digitizing quality assurance protocols in automated packaging lines. Major 3PL operators in Germany and the US Midwest are deploying these systems to eliminate human inspection stations. The technology is digitizing throughput optimization by enabling real-time tension adjustment based on load weight sensors.
REACH Annex XVII restrictions on microplastic release are tightening testing requirements for strapping used in outdoor construction applications. Industrial users must now document degradation behavior under UV exposure and mechanical stress. The regulation is compressing demand for conventional PP solutions in Scandinavian infrastructure projects while elevating certified biodegradable alternatives.
Consolidated procurement through integrated packaging suppliers is displacing direct OEM relationships for strapping consumables. Large food and beverage manufacturers in the Netherlands and Belgium are centralizing purchasing decisions at the corporate level, demanding volume-tiered pricing and consolidated invoicing. This pattern is visible most acutely in dairy and brewing verticals where pallet standardization enables specification rationalization.
Global Strapping Market Segmentation
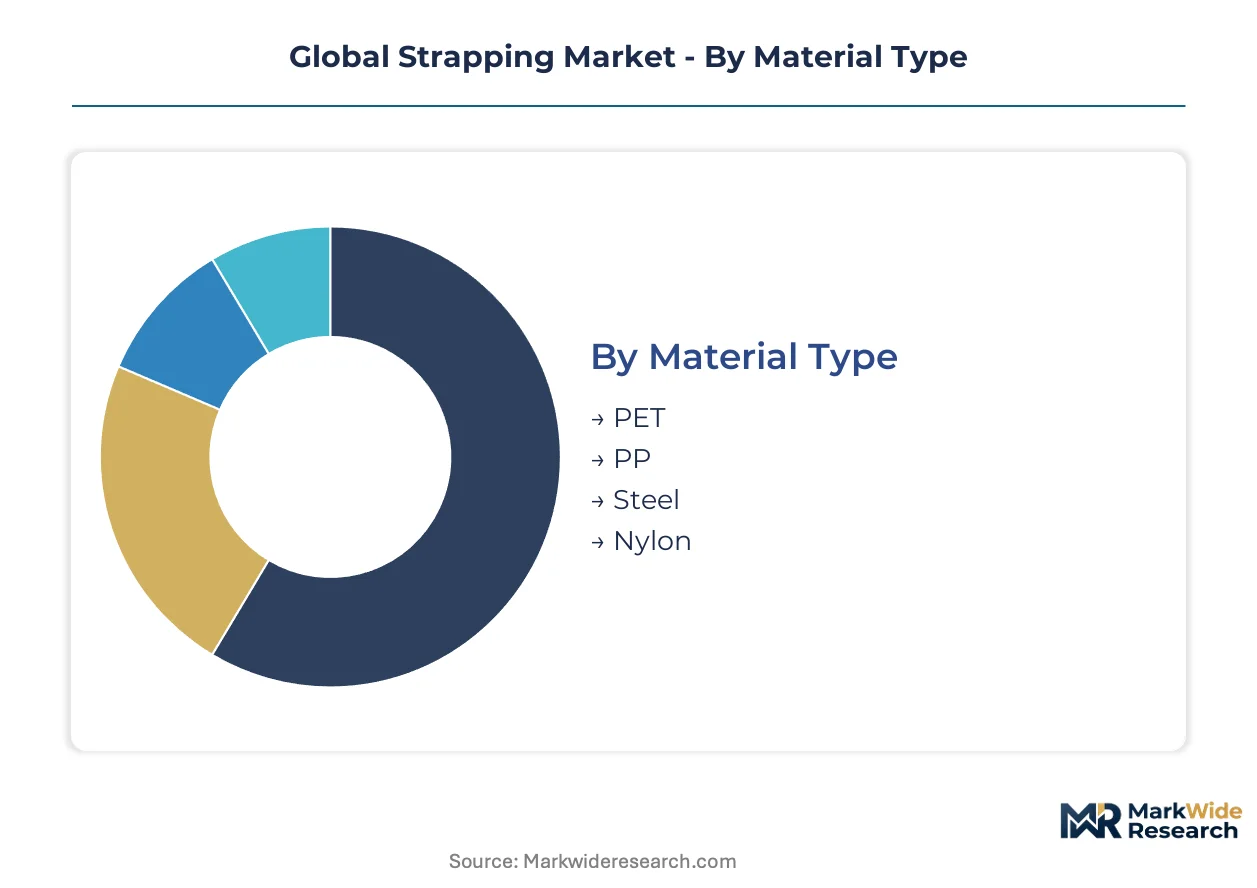
Material composition and application context determine equipment compatibility, regulatory exposure, and margin structure across strapping procurement decisions. Segmentation reveals where specification standardization clashes with end-use customization requirements.
Material Type:
Mature extrusion technologies dominate commodity grades while emerging formulations target circularity mandates.
- PET:Extruded polyester delivers tensile strength between 300 and 1,500 megapascals with superior elongation recovery. Demand concentrates in German automotive supplier parks where automated arch-type systems require consistent feedstock geometry. REACH recycled content thresholds are compressing virgin resin procurement windows.
- PP:Embossed polypropylene offers lower density and food-contact compliance under FDA 21 CFR and EFSA frameworks. Food and beverage manufacturers in the Netherlands are standardizing embossed grades to satisfy downstream recycling protocols without sacrificing throughput speeds.
- Steel:Cold-rolled carbon steel strapping retains structural priority where extreme load rigidity is non-negotiable.
- Nylon:Moisture-resistant synthetic delivers chemical stability for specialized pharmaceutical and electronics applications.
PET retains volume leadership; PP holds the steepest expansion curve.
Application:
Cost tier separation runs from high-automation logistics to labor-intensive construction sites.
- Logistics:Automated fulfillment centers standardize polyester strapping for palletized unit loads, driving specification harmonization across 3PL networks in Germany and the Netherlands. Real-time tension control systems compress operational variance in high-volume environments.
- Packaging:Corrugated container securing demands compatibility with high-speed bundling equipment. Dairy and brewing verticals in Belgium are centralizing procurement decisions at corporate levels.
- Construction:Heavy-duty steel strapping withstands outdoor UV exposure and mechanical stress for infrastructure projects.
- Manufacturing:Component bundling in metalworking requires load rigidity that polymer alternatives cannot replicate.
Logistics commands the premium automation tier; Packaging is gaining share fastest through consolidated procurement.
End User:
Customer type determines certification burden and specification complexity.
- Food & Beverage:Direct-contact applications trigger FDA 21 CFR and EU REACH dual compliance timelines extending product launches.
- Pharmaceuticals:Cold chain integrity requirements in India are opening specification windows for battery-powered handheld tools.
- Electronics:High-value shipments enable RFID-embedded smart strapping with pallet-level tracking capabilities.
- Retail:E-commerce logistics operations are expanding polyester and polypropylene use for palletized unit loads.
Food & Beverage carries the heaviest regulatory load; Pharmaceuticals is climbing the fastest on cold chain investment.
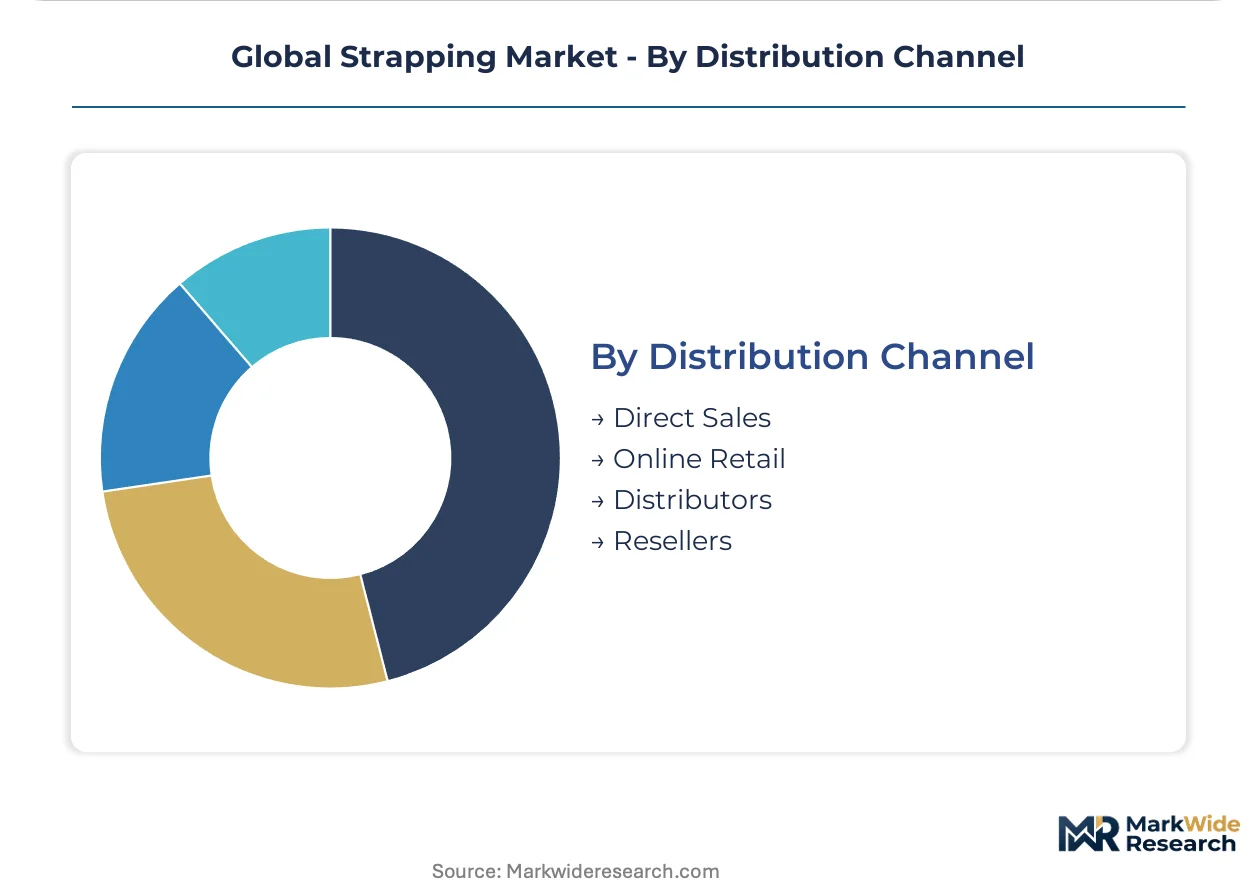
Distribution Channel:
Supply concentration varies from captive direct relationships to fragmented reseller networks.
- Direct Sales:Integrated packaging suppliers are displacing OEM relationships for large manufacturers demanding volume-tiered pricing.
- Distributors:Regional inventory positioning serves mid-tier automotive plants requiring custom mechanical interfaces.
- Online Retail:Battery-powered handheld tools reach small-scale operations through digital procurement platforms.
- Resellers:Local service networks address maintenance scarcity for precision tension control systems.
Direct Sales retains margin leadership; Online Retail is expanding most quickly through tool accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance deadlines are compressing procurement windows across German automotive supplier parks. FDA 21 CFR dual-certification timelines extend product launches for food-contact applications serving North American markets. India's PLI scheme for logistics infrastructure is opening specification windows for battery-powered handheld tools in pharmaceutical cold chains.
Germany
Automated arch-type strapping systems with real-time tension control are accelerating replacement cycles in Bavarian automotive component plants. The national packaging ordinance transposes EU directives mandating minimum recycled content thresholds. Stuttgart and Munich supplier clusters are standardizing PET strapping specifications across integrated packaging lines.
United States
FDA 21 CFR governs direct-contact food packaging strapping for dairy and brewing verticals in Wisconsin and California. EPA regulations intersect with state-level extended producer responsibility schemes in Oregon and Maine. The US Gulf Coast PET resin supply cluster creates geographic concentration for extrusion operations serving Midwest 3PL networks.
China
MIIT standards and dual carbon goals are reshaping polymer formulation requirements for construction-grade steel strapping. GB standards govern tensile strength certifications for export-oriented extrusion facilities. Yangtze River Delta manufacturing hubs are consolidating procurement for corrugated container bundling equipment.
India
PLI scheme incentives for cold chain expansion are driving battery-powered handheld tool adoption in Maharashtra pharmaceutical distribution. CDSCO regulations intersect with FSSAI packaging requirements for temperature-sensitive shipments. Gujarat logistics parks are standardizing embossed PP specifications for downstream recycling compliance.
Netherlands
Consolidated procurement through integrated packaging suppliers is displacing direct OEM relationships for dairy and brewing operations. ECHA REACH restrictions on phthalate plasticizers are compressing demand for conventional polymer solutions. Rotterdam-Antwerp corridor PET feedstock concentration creates supply vulnerability for extrusion operations serving Belgian corrugated container manufacturers.
Global Strapping Market Competitive Environment
Capability concentration sits with precision-engineered automation specialists; scale advantage sits with integrated steel and polymer producers. The vendor base organizes around three strategic archetypes: Swiss-German engineering heritage firms dominating battery-powered handheld tools, North American integrated systems providers anchoring heavy industrial applications, and automated arch-type machine specialists competing on real-time tension control. Dominant competitive moves include backward integration into recycled PET feedstock and geographic expansion through distributor network densification.
Among German automation specialists, Mosca and FROMM Group exemplify the precision-engineered tier, while Signode anchors the North American integrated systems segment. These three occupy positions that map directly to the material-type segmentation: polyester logistics automation, battery-powered portable tooling, and heavy-duty steel applications. Their collective presence illustrates how engineering heritage and geographic origin crystallize into defensible positioning against commodity extrusion competitors.
| Leading Market Players |
|---|
| Mosca |
| FROMM Group |
| Signode |
| Strapack |
| Polychem |
| Baosteel |
| Scientex Berhad |
| Teufelberger |
| Samuel Strapping |
| Others |
Value Chain & Pricing Dynamics
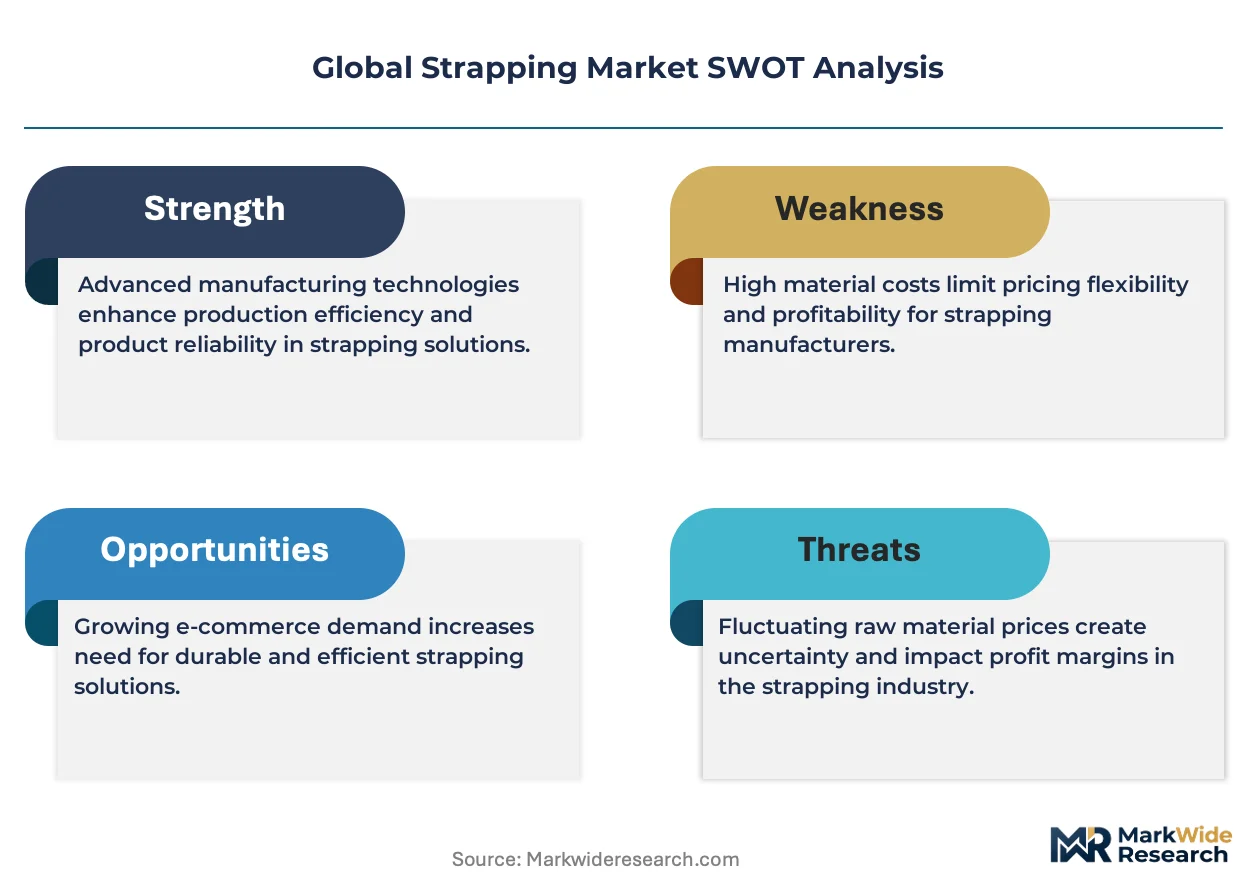
The Rotterdam-Antwerp corridor's freight cost volatility compresses margin buffers for European extruders while simultaneously amplifying price differentiation between virgin and recycled PET feedstock tiers across German automotive supplier parks.
Pricing Analysis
Geographic price spreads between US Gulf Coast and Rotterdam-Antwerp resin clusters exceed normalized freight differentials by meaningful margins. Pricing stratifies across premium certified-recycled, standard virgin-PET, and economy blended-content tiers for automotive logistics applications. Cost compression in steel strapping runs through energy-intensive rolling mill operations in China. Small-scale construction contractors exhibit acute price sensitivity, while German OEM supplier parks prioritize specification consistency over unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates strategic planning for construction-grade steel strapping producers. Virgin and recycled PET resin supply clusters in the United States, Belgium, and the Netherlands create geographic concentration for extrusion operations. Feedstock procurement draws from petrochemical complexes and post-industrial recycling streams. Single-source vulnerability in specialized polymer additives for food-contact grades persists. Distribution runs through integrated packaging suppliers displacing direct OEM relationships in dairy and brewing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision mechatronics expertise for real-time tension control systems remains chronically undersupplied against automated strapping line deployment timelines, compressing service revenue capture for maintenance-capable vendors.
For Market Incumbents: Entrench position through backward integration into recycled PET feedstock certification and captive technician training academies serving Bavarian automotive clusters. Battery-powered handheld tool margins face erosion from Asian electronics assemblers; defend through Swiss-German engineering heritage branding and aftermarket service bundling. For New Entrants and Emerging Players: India's Maharashtra pharmaceutical cold chain offers underpenetrated specification windows for battery-powered handheld strapping tools. Target Gujarat logistics parks with embossed PP solutions compliant with FSSAI downstream recycling mandates. Lead with digital procurement platform accessibility rather than distributor network density. For Investors and Strategic Acquirers: Automated arch-type machine specialists with real-time tension control IP represent the priority acquisition archetype for packaging automation platforms. Long-term viability hinges on circularity-compliant formulation pipelines rather than commodity extrusion scale. Watch ECHA REACH Annex XVII microplastic restriction enforcement as demand inflection signal for certified biodegradable alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | Secures REACH-compliant resin supply for German automotive supplier parks. |
| Technician Training Academy Establishment | Addresses mechatronics scarcity compressing maintenance response times in Central Europe. |
| RFID-Embedded Smart Strapping Launch | Enables pallet-level tracking for high-value pharmaceutical shipments in India. |
| Closed-Loop Take-Back Program Deployment | Generates verified recycled content certificates under French extended producer responsibility schemes. |
| Digital Procurement Platform Expansion | Reaches small-scale operations underserved by traditional distributor networks. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, OEM procurement leads, aftermarket service heads, and logistics infrastructure planners; and secondary validation through customs trade records, SEC filings of listed packaging equipment manufacturers, ECHA REACH registration databases, and automotive production statistics. Bottom-up extrusion capacity modeling and top-down end-use demand estimation were triangulated against operating metrics disclosed by integrated packaging suppliers.
Forecast inputs encompassed material type segmentation by tensile strength grade and recycled content tier, application segmentation by automation intensity, and end-user segmentation by regulatory certification burden across the analysis window. CAGRs were derived from elasticity-adjusted demand projections calibrated to historical replacement cycle patterns in German automotive supplier parks and PLI scheme infrastructure buildout timelines in India.
Practitioners should monitor ECHA microplastic restriction enforcement, FDA 21 CFR interpretation shifts, and Indian PLI scheme disbursement velocity for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Europe Airless Packaging Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Production Page Volume Market
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Construction Films Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Child Resistant Zipper Market
Packaging Materials
Wooden and Plywood Packaging Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Foam Bottle Technology Market
Packaging Materials
Cash Management Supplies Packaging Market
Packaging Materials
Anti-Static Liners Market