
 Microwave Packaging Market | 2026-2036
Microwave Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Microwave Packaging Market Intelligence
EU Packaging and Packaging Waste Regulation is pivoting the cost-of-entry calculus toward recyclable and fiber-based formats. Amcor leverages its global manufacturing footprint to supply dual-ovenable paperboard solutions across European retail networks. Huhtamaki Group anchors its position through susceptor technology leadership in ready-meal lidding applications. Mondi Group competes with integrated pulp-to-paper operations that reduce raw material exposure.
Microwave packaging encompasses engineered containers, trays, lids, and pouches designed to withstand dielectric heating while maintaining food safety and sensory quality. These structures incorporate susceptor films, venting mechanisms, or barrier coatings to manage moisture migration and surface browning during electromagnetic exposure at 2.45 GHz. Plastic containers dominate current volume due to cost efficiency and seal integrity, though paper-based trays are gaining structural share as retailers enforce single-use plastic reduction commitments. Pouches represent the fastest-expanding format, driven by shelf-stable ethnic meal kits and steam-venting innovations that eliminate puncture requirements.
FDA food contact substance notifications govern material migration limits in the United States, while EFSA evaluates novel barrier coatings under updated EU food contact framework conditions. BIS certification requirements in India and China's GB standards for composite food packaging add compliance layers for exporters targeting Asia-Pacific manufacturing hubs. Stakeholders must monitor evolving extended producer responsibility schemes and susceptor material reclassification debates that could reshape formulation roadmaps.
Market Dynamics
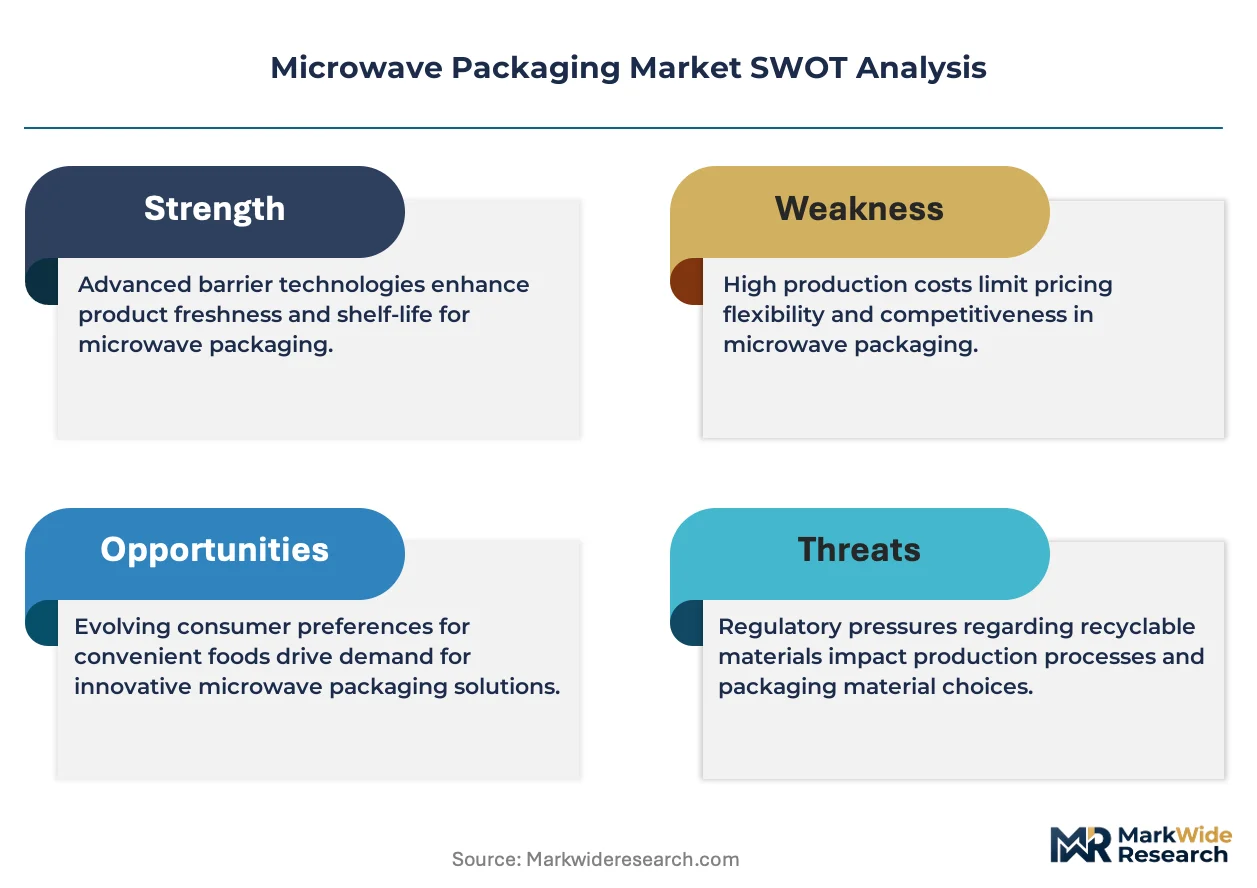
The EU's Packaging and Packaging Waste Regulation is compressing design cycles for microwave packaging suppliers, forcing rapid migration from multilayer plastics to fiber-based susceptor formats that satisfy material recovery targets without sacrificing heating performance.
Growth Catalysts
- EFSA food contact framework updates:The revised EU evaluation protocols for novel barrier coatings are accelerating approval timelines for cellulose-based susceptor films, enabling faster commercialization of paper alternatives.
- Frozen food manufacturer expansion:Ready-meal producers in Germany are retrofitting production lines for dual-ovenable trays, creating pull-through demand for susceptor-equipped lidding and base structures.
- Steam-venting pouch technology:Self-venting film innovations eliminate consumer puncture steps, driving adoption in shelf-stable ethnic meal kits across urban retail networks.
Market Restraints
- Pulp price volatility:Integrated paperboard suppliers face margin pressure from fluctuating softwood pulp contracts, compressing returns on susceptor tray investments.
- Aluminum susceptor reclassification risk:Pending debates in Brussels over metalized film waste stream categorization threaten existing inventory valuations and reformulation costs.
- Seal integrity limitations:Fiber-based trays still exhibit higher leak rates than polypropylene equivalents in high-moisture frozen applications, restricting full plastic substitution.
Strategic Opportunities
- Extended producer responsibility schemes:Germany's packaging fee modulation for recyclable formats creates cost advantages for suppliers achieving DIN CERTCO compostability certification.
- Smart susceptor integration:Convergence of RFID temperature tracking with susceptor films enables premium positioning in healthcare meal delivery and institutional catering channels.
- Direct-to-retail channel expansion:Private-label ready-meal programs at Aldi Süd and REWE are bypassing traditional distributor tiers, shortening qualification cycles for qualified converters.
Industry Challenges
- Susceptor engineering talent scarcity:The specialized knowledge base for dielectric heating optimization and metallization pattern design concentrates among retiring cohorts at legacy European research institutes.
- Dual-certification timeline compression:Simultaneous BfR and FDA food contact notifications for export-bound products extend validation cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwave Packaging Market |
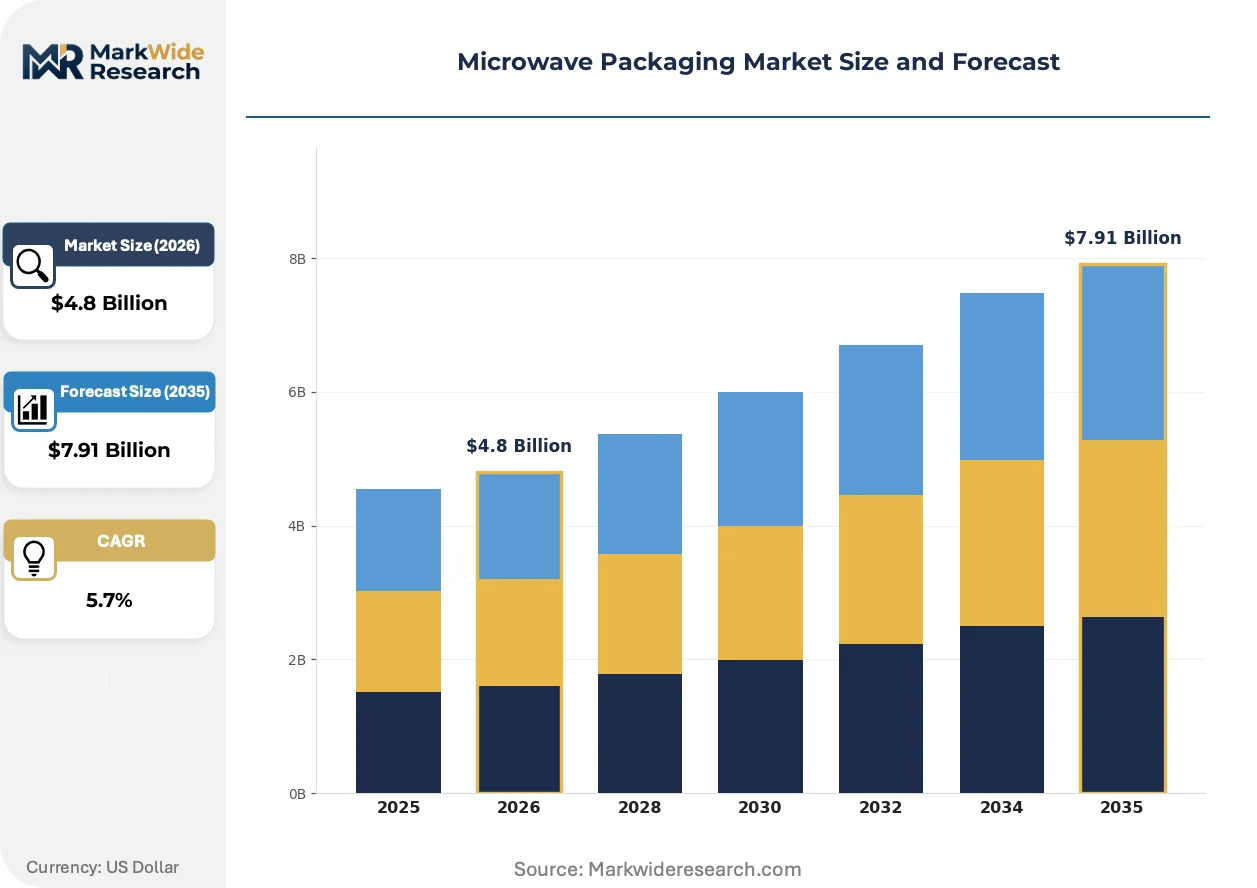
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Metal, Glass Product Type: Containers, Trays, Lids, Pouches End User: Food Manufacturers, Retailers, Restaurants, Distributors Application: Ready Meals, Snacks, Vegetables, Desserts |
| Companies Covered | Amcor, Berry Global Group, Graphic Packaging International, Sealed Air Corporation, Huhtamaki Group, Mondi Group, Sonoco Products Company, Dart Container Corporation, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwave Packaging Market Strategic Shifts & Innovations
Active susceptor patterning and intelligent venting mechanisms are displacing static packaging designs, enabling precise thermal management that was previously achievable only through active oven controls.
Laser-scribed susceptor films are automating browning control in ready-meal applications. Retail chains in France and Belgium are specifying these patterned metallized layers for premium private-label ranges. The technology is automating quality consistency that previously required manual oven calibration by consumers.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant coatings from microwaveable paperboard. German converters are accelerating migration to polylactic acid and bio-wax barrier systems. Frozen pizza and bakery segments are absorbing the reformulation costs fastest due to retailer plastic reduction mandates.
Meal-kit subscription services are consolidating procurement around modular pouch formats that collapse for outbound shipping and self-vent during microwave heating. HelloFresh and its competitors in the Netherlands and UK are specifying these structures for single-portion ethnic cuisine lines. Urban fulfillment centers with constrained cold storage footprint are driving this specification shift most aggressively.
Microwave Packaging Market Segmentation
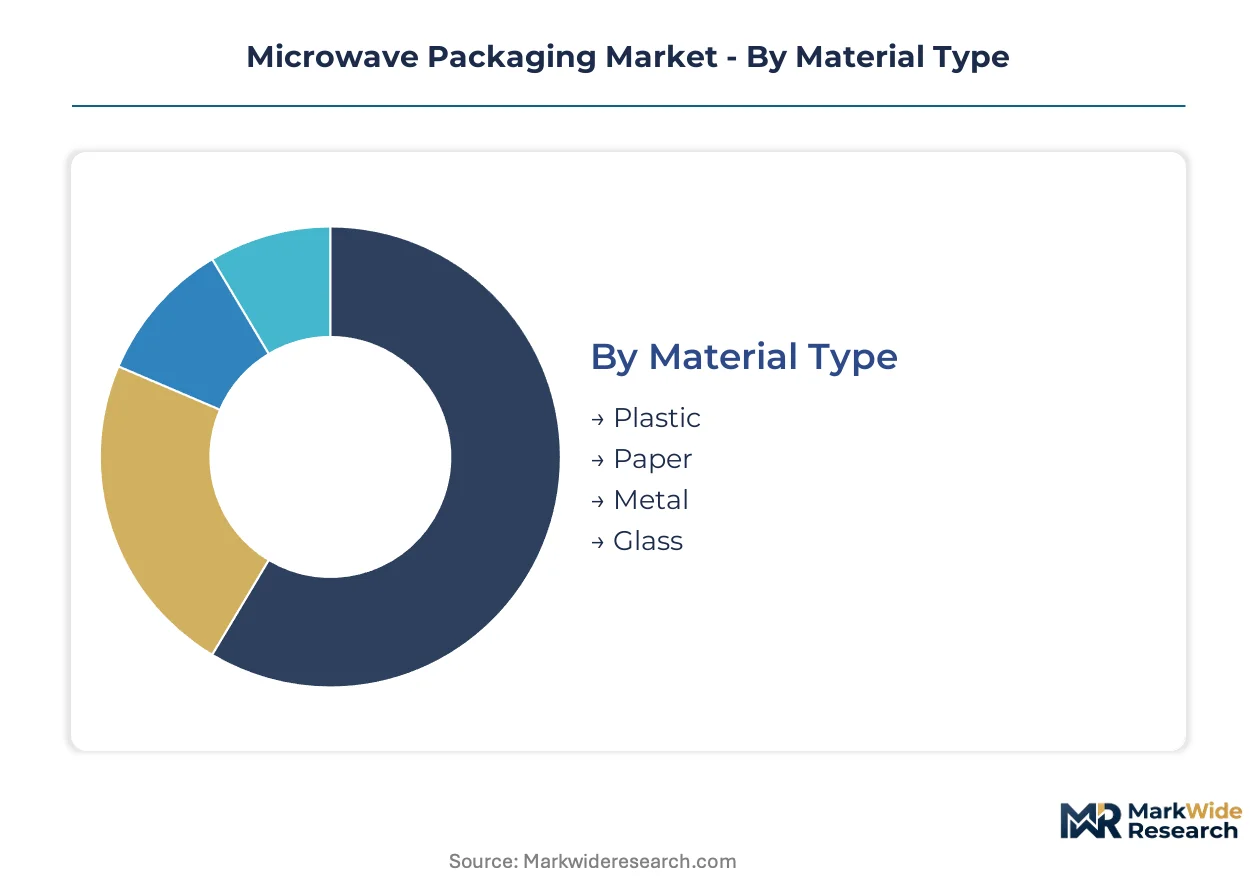
Microwave packaging structures must balance dielectric heating performance against material recovery mandates. Each segmentation axis reveals distinct technical trade-offs between susceptor functionality, seal integrity, and end-of-life compliance.
Material Type:
Polypropylene and paperboard formulations compete on susceptor integration capability and pulp cost exposure.
- Plastic:Polypropylene and crystallized polyethylene terephthalate trays dominate frozen ready-meal applications due to superior moisture barrier performance and heat-seal reliability. German retailers are phasing out these formats under single-use plastic reduction commitments, forcing converters to absorb reformulation costs for fiber-based alternatives.
- Paper:Susceptor-equipped paperboard structures incorporate metallized polyester films laminated to molded fiber bases, achieving surface browning control previously limited to plastic containers. Demand concentrates in France and Belgium where private-label programs specify laser-scribed susceptor patterns for premium ready-meal ranges.
- Metal:Aluminum trays serve institutional catering and airline meal segments requiring structural rigidity under high-temperature hold conditions.
- Glass:Borosilicate containers occupy niche premium segments for reusable meal-prep applications with limited microwave penetration.
Plastic leads on scale; paper leads on momentum.
Product Type:
Format selection determines venting mechanism complexity and supply chain tooling requirements.
- Pouches:Self-venting film structures with laser-perforated membranes eliminate consumer puncture steps while maintaining shelf stability. HelloFresh and comparable meal-kit operators in the Netherlands specify these formats for ethnic cuisine lines to reduce fulfillment center footprint.
- Trays:Dual-ovenable paperboard bases with susceptor lidding dominate frozen pizza and bakery segments where EFSA-approved barrier coatings replace legacy fluorinated chemistries.
- Containers:Round polypropylene tubs with vented lids serve soup and sauce applications requiring liquid containment during pressure cycling.
- Lids:Laminated film structures with peel-reseal adhesives enable staged consumption for multi-portion ready meals.
Trays command volume share; pouches gain share fastest.
End User:
Procurement authority is shifting from distributors toward direct retail specifications.
- Food Manufacturers:Nestlé and Unilever frozen divisions retrofit production lines for dual-ovenable formats to meet Aldi Süd and REWE plastic reduction timelines.
- Retailers:Private-label programs at Carrefour and Albert Heijn bypass traditional distributor tiers, shortening qualification cycles for qualified converters.
- Restaurants:Ghost kitchen operators specify collapsible pouch formats to minimize outbound shipping cube.
- Distributors:Broadline foodservice distributors consolidate SKUs around modular tray sizes to reduce inventory fragmentation.
Food manufacturers anchor volume; retailers dictate specification momentum.
Application:
Thermal profile requirements vary sharply across food categories, driving susceptor pattern customization.
- Ready Meals:Multi-component trays require zoned susceptor metallization to prevent sauce overheating while achieving protein surface browning.
- Snacks:Popcorn and chip applications prioritize rapid steam venting to preserve texture crispness.
- Vegetables:Steam-in-bag pouches with directional venting preserve nutrient retention and color stability.
- Desserts:Molten cake and custard formats demand precise temperature control to prevent curdling or structural collapse.
Ready meals dominate revenue contribution; desserts expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized susceptor engineering talent concentrates in German research institutes and Dutch polymer science clusters, anchoring European innovation capacity for microwave packaging formats.
Germany
Aldi Süd and REWE are accelerating private-label ready-meal specifications that mandate dual-ovenable paperboard trays with susceptor lidding. The Packaging Act implements strict extended producer responsibility fees that favor DIN CERTCO-certified compostable formats. Converters in North Rhine-Westphalia are retrofitting production lines to supply these retailer-driven transitions.
France
Carrefour's premium private-label ranges are specifying laser-scribed susceptor patterns for controlled browning in chilled ready meals. ANSM oversees food contact compliance for novel barrier coatings replacing legacy fluorinated chemistries. Industrial activity clusters around Paris-Saclay research corridors where metallization pattern design expertise resides.
Netherlands
HelloFresh and comparable meal-kit operators are consolidating procurement around self-venting pouch formats for ethnic cuisine lines. REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from paperboard applications. Eindhoven-region film converters are scaling laser-perforated membrane production for these subscription service specifications.
United States
Frozen food manufacturers are expanding microwaveable packaging lines as convenience food sales rise in urban retail networks. FDA food contact substance notifications govern material migration limits for susceptor-equipped structures. Graphic Packaging International anchors manufacturing capacity in the Southeast for dual-ovenable paperboard supply to national retail chains.
India
Urban retail chains in Mumbai and Delhi are introducing susceptor-equipped formats for frozen snack and ready-meal segments. BIS certification requirements add compliance layers for composite food packaging targeting domestic and export markets. Maharashtra-based converters are investing in metallization capabilities to serve quick-service restaurant and airline catering procurement.
Microwave Packaging Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across microwave packaging supply tiers. Amcor and Mondi leverage integrated pulp-to-paper operations and global manufacturing footprints against susceptor-technology specialists like Huhtamaki. Three archetypes dominate: integrated paperboard multinationals, susceptor engineering specialists, and regional tray converters. Competitive moves concentrate on backward integration into metallization capacity and strategic partnerships with frozen food manufacturers for co-development of dual-ovenable formats.
Among integrated paperboard suppliers, WestRock Company and Graphic Packaging International represent scale-driven archetypes with captive fiber supply and converting infrastructure. Huhtamaki Group occupies a specialist position focused on susceptor technology leadership for ready-meal lidding applications. These three companies exemplify the strategic segmentation between diversified materials conglomerates and focused technology players that characterizes competitive dynamics in microwave packaging supply.
| Leading Market Players |
|---|
| Amcor |
| Berry Global Group |
| Graphic Packaging International |
| Sealed Air Corporation |
| Huhtamaki Group |
| Mondi Group |
| Sonoco Products Company |
| Dart Container Corporation |
| WestRock Company |
| Others |
Cost & Logistics Intelligence
Captive metallization capacity in German and Dutch research clusters anchors both supply security and pricing leverage for susceptor-equipped formats serving Aldi Süd and REWE private-label programs. This backward integration into pattern-design expertise insulates converters from pulp price volatility while commanding premium positioning against outsourced competitors.
Pricing Analysis
Bundled susceptor engineering services with tray supply command 15-25% premia over unbundled component sourcing, while standalone metallized film pricing faces compression from Asian substrate imports. Three-tier pricing structure across susceptor-integrated premium, standard barrier-coated, and economy polypropylene tiers separates EFSA-certified cellulose formats from legacy plastic alternatives. Pricing pressure stems from REACH-driven reformulation costs for fluorine-free barrier coatings, with frozen pizza manufacturers absorbing margin erosion fastest. Private-label retailers exhibit highest price sensitivity, while healthcare meal delivery channels tolerate premium positioning for RFID-integrated smart susceptors.
Supply Chain Analysis
DIN CERTCO compostability certification gates supply relationships with German retail chains, filtering qualified converters to those with validated fiber sourcing and metallization traceability. Supply concentrates in Germany, the Netherlands, and Finland, drawing from softwood pulp contracts, metallized polyester film imports, and laser-scribing equipment dependencies. Single-source vulnerability runs through specialized susceptor pattern engineering talent concentrated at legacy European research institutes. Distribution runs through direct-to-retail channels at Aldi Süd and REWE, bypassing traditional distributor tiers and shortening qualification cycles for approved converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's Packaging and Packaging Waste Regulation imposes stricter material recovery fees in Germany than comparable EPR schemes in France, creating a geographic-arbitrage opportunity for converters with cross-border DIN CERTCO certification.
For Market Incumbents: To counter aluminum susceptor reclassification risk in Brussels, Amcor and Mondi should accelerate cellulose-based susceptor film R&D while securing captive pulp supply through long-term softwood contracts in Nordic regions. Backward integration into laser-scribing equipment manufacturing reduces exposure to single-source machinery dependencies. For New Entrants and Emerging Players: The EU Packaging and Packaging Waste Regulation in Germany opens a window for fiber-based tray specialists to capture share from plastic incumbents phasing out polypropylene formats under retailer mandates. Target self-venting pouch specifications for HelloFresh and comparable meal-kit operators in the Netherlands, leveraging collapsible format demand from urban fulfillment centers with constrained cold storage footprint. For Investors and Strategic Acquirers: Roll-up economics work for regional tray converters with DIN CERTCO certification because EPR fee modulation creates sustainable cost advantages for compostable formats over multilayer plastic alternatives. Susceptor engineering specialists with metallization pattern IP represent priority acquisition targets. Watch for Brussels susceptor material reclassification decisions as inflection indicators for inventory valuation risk and reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallization Capacity | Captive susceptor film production insulates margins from Asian substrate import volatility. |
| DIN CERTCO Compostability Certification | Germany's EPR fee modulation rewards certified converters with structural cost advantages. |
| Smart Susceptor RFID Integration | Temperature-tracking films unlock premium positioning in healthcare meal delivery channels. |
| Direct-to-Retail Channel Expansion | Aldi Süd and REWE private-label programs bypass distributor tiers for faster qualification. |
| Laser-Scribed Pattern Automation | Automated browning control replaces manual consumer oven calibration in premium ranges. |
Research Approach
Direct dialogue with frozen food manufacturer procurement directors, retail category buyers at Aldi Süd and REWE, susceptor engineering specialists at Dutch polymer science clusters, and BfR regulatory affairs consultants grounded qualitative findings. Secondary validation drew from EFSA food contact framework updates, EU Packaging and Packaging Waste Regulation impact assessments, DIN CERTCO certification databases, and pulp futures trading data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across material type, product format, and end-user channel dimensions.
Segment-level value outputs trace demand trajectories across plastic, paperboard, and metal material categories through the projection horizon, with susceptor integration intensity and EPR fee exposure as cross-cutting variables. CAGRs derive from regression analysis against frozen food retail sales indices, pulp price volatility bands, and regulatory compliance cost curves. Forecast inputs incorporate BIS certification timeline assumptions for India market entry and REACH restriction implementation schedules for fluorinated coating phase-outs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum susceptor reclassification scenarios or sustained softwood pulp contract spikes. Model outputs reflect documented assumptions regarding EFSA approval timelines for novel barrier coatings and retailer plastic reduction commitment acceleration. A model refresh is warranted upon material change in Brussels susceptor waste stream categorization debates or German Packaging Act fee modulation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Face Stock Films Market
Packaging Materials
Cash Management Supplies Packaging Market
Packaging Materials
Urn Liners Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
VCI Packaging Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Card Films Market
Packaging Materials
Strip Pack Market
Packaging Materials
Liquid Encapsulation Market
Packaging Materials
Thermal Transfer Roll Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
Thailand Packaging Market