
 Direct Thermal Labels Market | 2026-2036
Direct Thermal Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Thermal Labels Market Analysis
The capital-intensity divergence between integrated coating specialists and merchant converters is collapsing as thermal face-stock manufacturing migrates toward regional scale. Avery Dennison Corporation leverages captive resin compounding to sustain margin structures across North American distribution. SATO Holdings Corporation anchors its position through precision die-cutting automation serving Japanese electronics supply chains. Constantia Flexibles GmbH competes via backward integration into specialty paper sourcing for European pharmaceutical serialization.
Direct thermal labels are pressure-sensitive constructions coated with leuco dye-crystal developer chemistry that darkens under controlled heat application without ribbon or ink, typically specified at 48-58 gram per square meter basis weight for desktop printers. Their primary commercial purpose is variable-information marking in high-velocity environments where print speed and equipment simplicity outweigh archival durability requirements. Synthetic substrates represent the fastest-expanding product type as cold-chain logistics and chemical exposure tolerate paper failure, while permanent adhesives dominate volume due to their lock-in effect on retail apparel and shipping carton applications. The ticketing segment commands premium positioning through thermal topcoats enabling extended UV resistance for event and transportation credentials.
FDA 21 CFR Part 201 labeling rules and the EU MDR serialization mandates shape pharmaceutical demand by requiring tamper-evident, lot-traceable direct thermal formats across primary and secondary packaging. EPA VOC emission guidelines and REACH substance restrictions on bisphenol-A developers are forcing reformulation of thermal chemistry toward phenol-free alternatives. Stakeholders must monitor adhesive migration testing protocols under evolving food-contact regulations while positioning coating capacity near emerging biologics distribution hubs.
Market Dynamics
Thermal coating chemistry reformulation under EU F-Gas Regulation pressure is collapsing legacy supply structures while e-commerce logistics volume concentrates demand in specific industrial corridors.
Growth Catalysts
- E-commerce logistics velocity:Parcel sortation hubs in Germany's industrial corridor are consuming direct thermal labels at rates that outpace traditional retail replenishment cycles, with automated print-and-apply stations driving specification standardization.
- EU MDR serialization mandates:Pharmaceutical secondary packaging requirements for lot-traceable, tamper-evident formats are pulling high-grade thermal topcoats into medical device distribution channels.
- Synthetic substrate migration:Cold-chain logistics operators are specifying polyethylene and polypropylene face-stocks to survive condensation and chemical exposure that destroys paper constructions.
Market Restraints
- Leuco dye feedstock concentration:Crystal developer precursors for thermal coatings originate from a narrow base of Asian chemical manufacturers, creating single-source vulnerability for European converters.
- Bisphenol-A developer phase-out:ECHA REACH substance restrictions are forcing costly phenol-free chemistry transitions before alternative formulations achieve cost parity.
- Archival durability ceiling:Direct thermal image fade limits shelf-life documentation to under five years, excluding the format from regulated records retention in financial and legal verticals.
Strategic Opportunities
- Biologics distribution hub proximity:Coating capacity positioned near emerging cell-and-gene therapy cold-chain nodes in Switzerland and Singapore captures pharmaceutical serialization demand.
- UV-resistant thermal topcoat penetration:Event ticketing and transportation credential applications command premium positioning through extended outdoor durability specifications.
- Digital printing convergence:Hybrid thermal-inkjet production lines enable short-run variable data jobs that pure thermal or pure inkjet systems cannot execute profitably.
Industry Challenges
- Adhesive migration protocol compliance:Evolving FDA 21 CFR Part 201 food-contact testing requirements demand specialized analytical chemistry capabilities that merchant converters lack in-house.
- Precision die-cutting automation capex:Electronics supply chain specifications for sub-millimeter registration tolerance require capital equipment upgrades that strain mid-scale operations.
- Captive resin compounding skill scarcity:Integrated coating specialists require polymer chemistry expertise that regional labor markets rarely supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Thermal Labels Market |
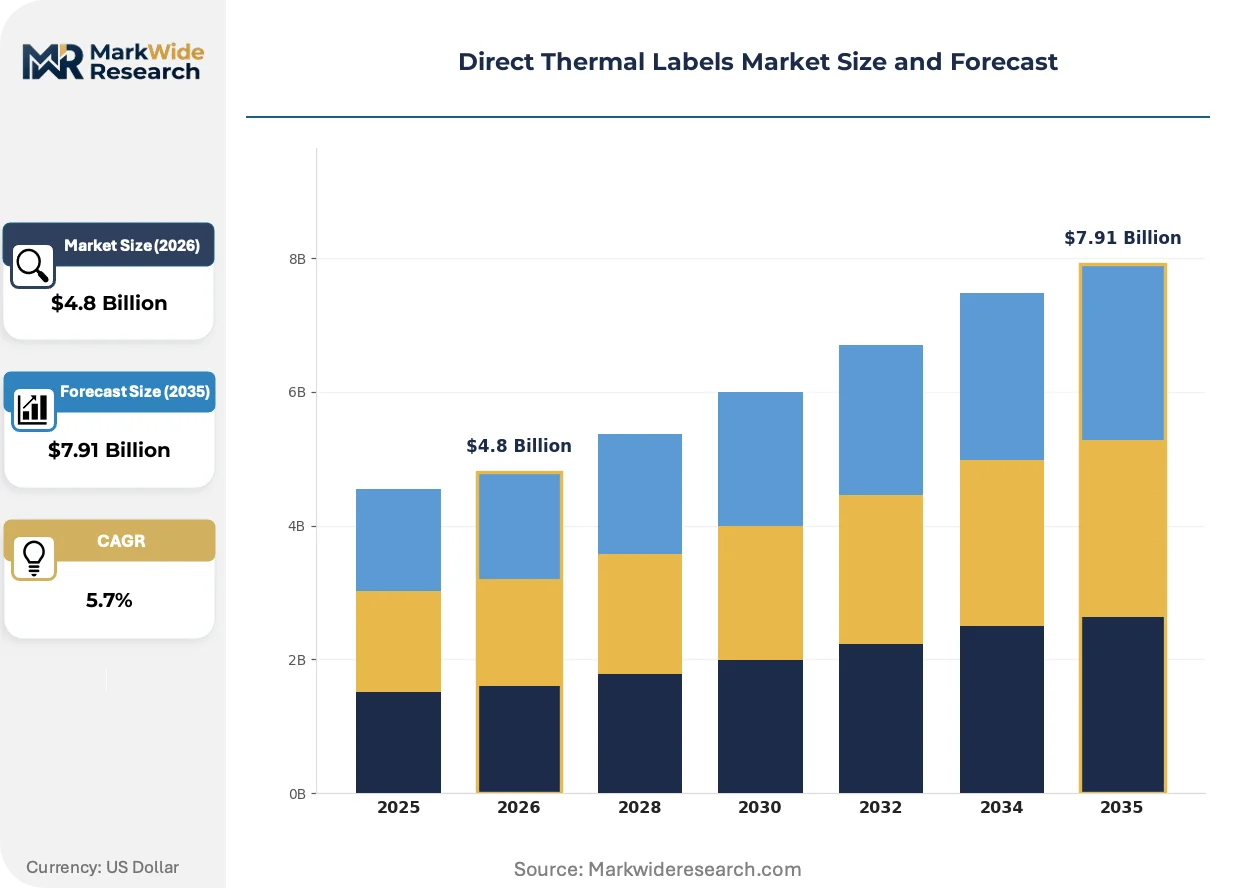
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper, Synthetic, Eco-friendly, Specialty End User: Retail, Healthcare, Logistics, Manufacturing Application: Shipping, Inventory Management, Barcode Printing, Ticketing Adhesive Type: Permanent, Removable, Freezer, Special |
| Companies Covered | UPM Raflatac, SATO Holdings Corporation, Avery Dennison Corporation, Label Makers Group Pty Ltd., Constantia Flexibles GmbH, 3M Company, CCL Industries Inc., Blanco Inc., Brady Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Thermal Labels Market Emerging Trajectories
Phenol-free thermal chemistry migration is disrupting established coating supply relationships while synthetic substrate adoption accelerates in demanding logistics environments.
Water-based thermal coating systems are fragmenting the developer chemistry landscape as converters seek VOC emission reductions ahead of EPA guideline enforcement. Cold-chain pharmaceutical distributors are specifying these formulations for primary packaging at premium cost positions. The shift is compressing margins for solvent-based coating specialists while rewarding early reformulators with pharmaceutical qualification pipelines.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon elimination in thermal coating production processes. Converters serving German automotive and electronics supply chains face compressed timelines for process requalification. The regulatory friction is concentrating coating capacity among operators with captive solvent recovery infrastructure.
Consolidated procurement by multinational third-party logistics providers is compressing supplier rosters to tier-one converters with multi-continent certification. Regional merchant label operations are losing specification access to integrated specialists offering synchronized global supply contracts. The pattern is most visible in transatlantic e-commerce fulfillment networks where single-source accountability reduces vendor management overhead.
Direct Thermal Labels Market Segmentation
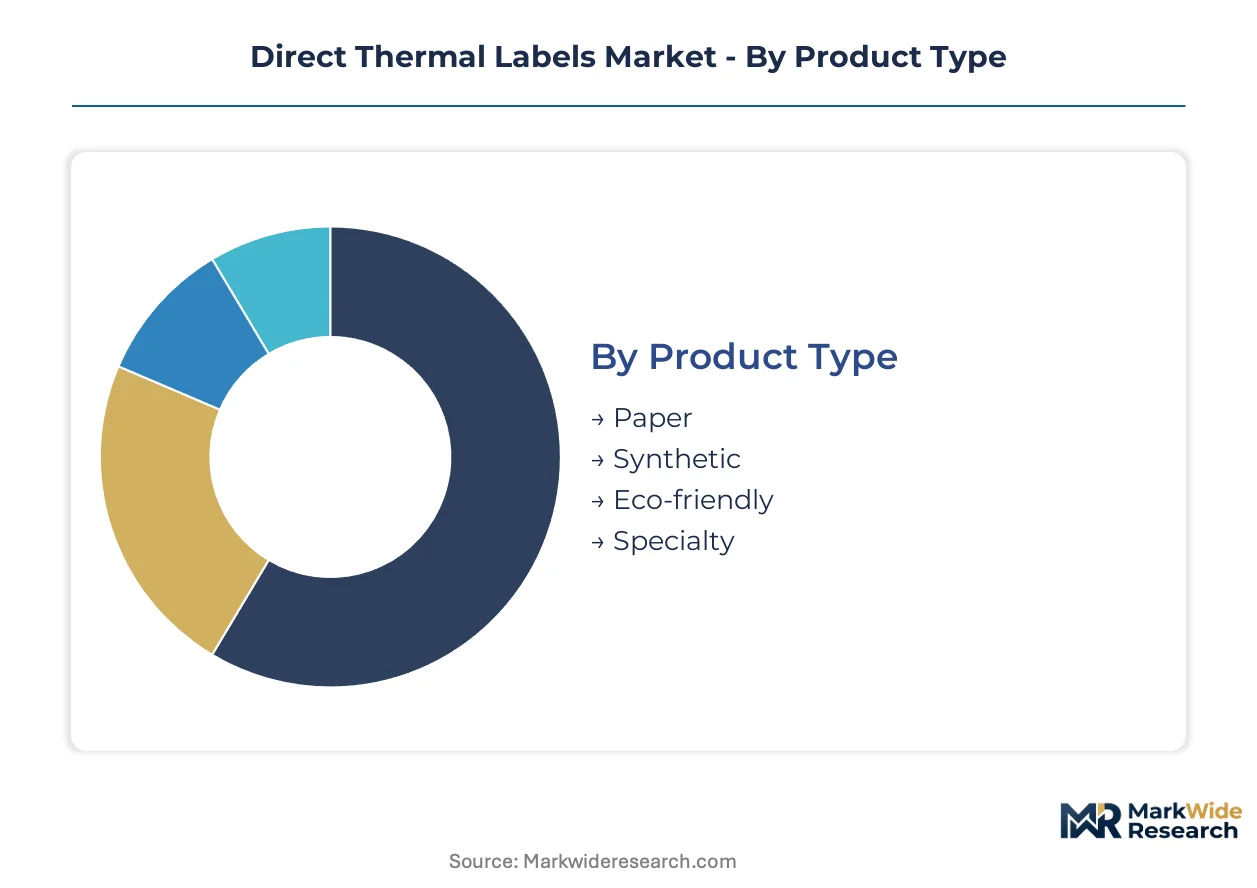
Direct thermal label specifications diverge sharply across end-use environments, with substrate chemistry and adhesive formulation determining survival in extreme conditions. Segmentation discipline separates commodity volume plays from premium positioning in regulated verticals.
Product Type:
Premium margin pools concentrate in synthetic and specialty substrates where cold-chain tolerance and chemical resistance command price premiums over commodity paper grades.
- Paper:Standard wood-pulp constructions at 48-58 gram per square meter basis weight dominate desktop printer specifications. Retail apparel tagging and short-life shipping applications in Germany's industrial corridor consume this grade at volume scale despite humidity sensitivity.
- Synthetic:Polyethylene and polypropylene face-stocks survive condensation, chemical exposure, and sub-zero temperatures that destroy paper. Cold-chain pharmaceutical distributors in Switzerland and Singapore specify these formulations for biologics primary packaging at substantial markups.
- Eco-friendly:FSC-certified substrates and recycled-content face-stocks address EU Green Deal procurement criteria. E-commerce fulfillment networks targeting carbon-neutral logistics specify these grades for consumer-facing packaging.
- Specialty:Thermal topcoats with extended UV resistance serve event ticketing and transportation credential applications. Outdoor durability specifications command the highest per-unit margins in the product matrix.
Paper holds installed capacity. Synthetic is rotating up the share rankings.
End User:
Customer concentration patterns separate high-volume standardized procurement from specification-intensive regulated segments.
- Retail:Apparel tagging and point-of-sale labeling drive standardized 4x6 inch shipping formats. Automated print-and-apply stations in transatlantic e-commerce fulfillment networks consume this segment at velocity scale.
- Healthcare:FDA 21 CFR Part 201 and EU MDR mandates require tamper-evident, lot-traceable formats with specialized adhesive migration testing. Pharmaceutical serialization demand pulls high-grade thermal topcoats into medical device distribution channels.
- Logistics:Parcel sortation hubs and third-party distribution centers specify durability grades matched to handling intensity. Consolidated procurement by multinational 3PLs compresses supplier rosters to tier-one converters.
- Manufacturing:Work-in-process tracking and asset labeling in automotive and electronics supply chains demand sub-millimeter die-cutting precision. Japanese electronics manufacturers anchor specifications for precision automation.
Logistics commands volume leadership. Healthcare is climbing the fastest on value contribution.
Application:
Use-case durability requirements stratify pricing from disposable shipping formats to multi-year credential applications.
- Shipping:Pressure-sensitive constructions for carton and parcel identification represent the volume base. E-commerce logistics velocity in Germany's industrial corridor drives specification standardization at scale.
- Inventory Management:Warehouse location labeling and cycle-count tags require scuff-resistant topcoats for repeated handling. Synthetic substrates are displacing paper in high-touch environments.
- Barcode Printing:Variable-information marking for supply chain traceability demands consistent print contrast across temperature ranges. Cold-chain operators specify premium grades to prevent scan failures.
- Ticketing:Event access and transportation credentials require extended UV resistance and archival stability. Thermal topcoats enabling five-year outdoor durability command the steepest premium positioning.
Shipping anchors volume throughput. Ticketing delivers the highest margin per square meter.
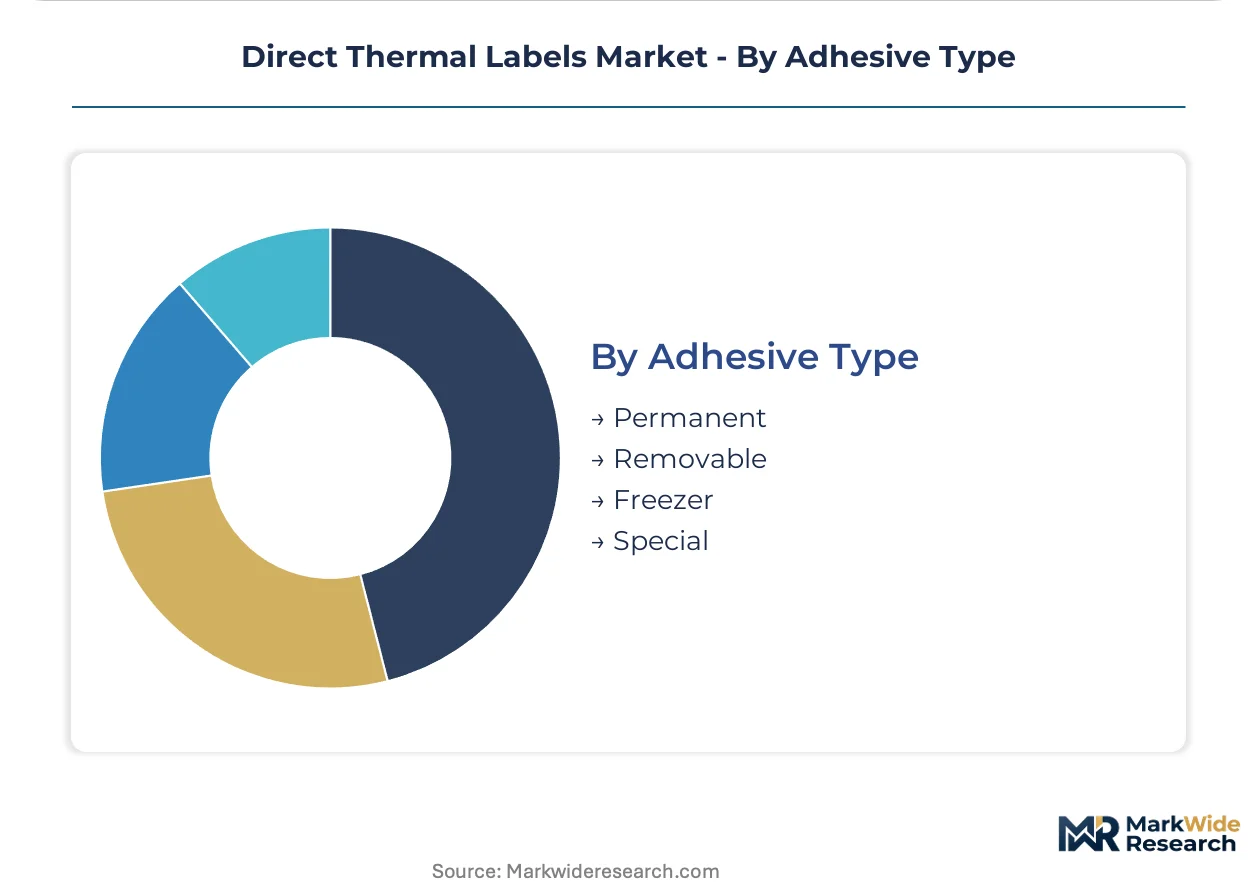
Adhesive Type:
Adhesive chemistry complexity separates commodity permanent formulations from specialized grades with regulatory qualification barriers.
- Permanent:Acrylic and rubber-based formulations with aggressive tack dominate retail apparel and shipping carton applications. The lock-in effect creates recurring demand with minimal switching.
- Removable:Low-tack adhesives enable clean removal from glass, plastics, and painted surfaces. Electronics and automotive manufacturers specify these for temporary process labeling.
- Freezer:Specialized formulations maintain adhesion at temperatures below minus 20 degrees Celsius. Cold-chain pharmaceutical and food distributors require these for primary packaging integrity.
- Special:Food-contact compliant and dissolvable adhesives address evolving FDA and EFSA testing protocols. Biologics distribution hubs near emerging cell-and-gene therapy nodes drive qualification demand.
Permanent adhesives hold capacity dominance. Special formulations are gaining share on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial corridors where EU F-Gas Regulation compliance costs filter through coating supply chains, while Southeast Asian converters compete on undifferentiated volume without regulatory premium capture.
Germany
E-commerce fulfillment hubs in the Ruhr industrial corridor consume direct thermal labels at velocity scale through automated print-and-apply stations. The EU F-Gas Regulation phase-down schedules compress timelines for hydrofluorocarbon elimination in thermal coating production. Bavaria's automotive supply chains anchor precision die-cutting specifications for work-in-process tracking applications.
United States
Parcel sortation infrastructure expansion drives standardized 4x6 inch shipping format procurement across transatlantic distribution networks. FDA 21 CFR Part 201 labeling rules mandate tamper-evident thermal formats for pharmaceutical secondary packaging. The Midwest industrial belt concentrates coating capacity near biologics distribution nodes serving cell-and-gene therapy cold chains.
China
Domestic e-commerce logistics operators specify synthetic substrates for condensation-prone warehouse environments. The national pharmaceutical regulator enforces serialization traceability standards aligned with global harmonization initiatives. The Yangtze River Delta anchors converter capacity serving electronics manufacturers with sub-millimeter registration tolerance requirements.
Japan
Electronics supply chain specifications demand precision die-cutting automation for component tracking and asset labeling. METI industrial standards shape thermal coating chemistry disclosure requirements for domestic procurement. The Kanto region around Tokyo concentrates SATO Holdings Corporation's integrated production serving semiconductor and automotive manufacturers.
Switzerland
Biologics distribution hubs near Basel and Zurich drive pharmaceutical-grade thermal topcoat demand for cold-chain primary packaging. Swissmedic serialization mandates require lot-traceable formats with specialized adhesive migration testing protocols. The country's pharmaceutical corridor captures premium positioning through qualification-intensive supply relationships with global drug manufacturers.
Direct Thermal Labels Market Vendor Landscape
Concentration sits with integrated coating specialists possessing captive resin compounding capabilities and multi-continent certification portfolios. Merchant converters without backward integration face specification exclusion as multinational third-party logistics providers consolidate procurement rosters. Three archetypes dominate: integrated specialists with in-house chemistry control, precision automation specialists serving electronics supply chains, and regional volume converters competing on undifferentiated shipping formats. Competitive moves center on phenol-free chemistry reformulation ahead of ECHA REACH enforcement and synthetic substrate capacity expansion for cold-chain pharmaceutical applications.
Within the integrated specialist tier, Avery Dennison Corporation and Constantia Flexibles GmbH exemplify archetypes with upstream control over thermal face-stock manufacturing and specialty paper sourcing respectively. SATO Holdings Corporation anchors the precision automation vector through its Japanese electronics supply chain positioning. These three occupy positions that regional merchant operators cannot replicate without capital equipment upgrades and regulatory qualification investments.
| Leading Market Players |
|---|
| UPM Raflatac |
| SATO Holdings Corporation |
| Avery Dennison Corporation |
| Label Makers Group Pty Ltd. |
| Constantia Flexibles GmbH |
| 3M Company |
| CCL Industries Inc. |
| Blanco Inc. |
| Brady Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts between tier-one converters and multinational 3PLs lock in supply access while anchoring price visibility for synthetic substrate grades across transatlantic e-commerce networks. These arrangements concentrate procurement power among integrated specialists with captive resin compounding, forcing merchant converters into spot-market exposure for leuco dye precursors.
Pricing Analysis
The customization-premium spread separates configured-to-order pharmaceutical serialization formats from standard 4x6 inch shipping labels. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity, with FDA 21 CFR Part 201 and EU MDR compliance tiers commanding substantial markups over undifferentiated retail apparel grades. Cost compression in commodity paper segments is intensifying because consolidated 3PL procurement squeezes supplier margins. Logistics operators show highest price sensitivity due to volume scale, while biologics distributors accept premium positioning for cold-chain validated formats.
Supply Chain Analysis
Crystal developer precursor manufacturing in China, Japan, and South Korea creates single-source vulnerability for European coating specialists facing ECHA REACH reformulation deadlines. Thermal face-stock production draws from specialty paper pulp, synthetic resin pellets, and leuco dye feedstocks. Tariff exposure on Asian chemical imports compounds margin pressure for converters without backward integration. Distribution runs through regional coating hubs positioned near pharmaceutical and automotive industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
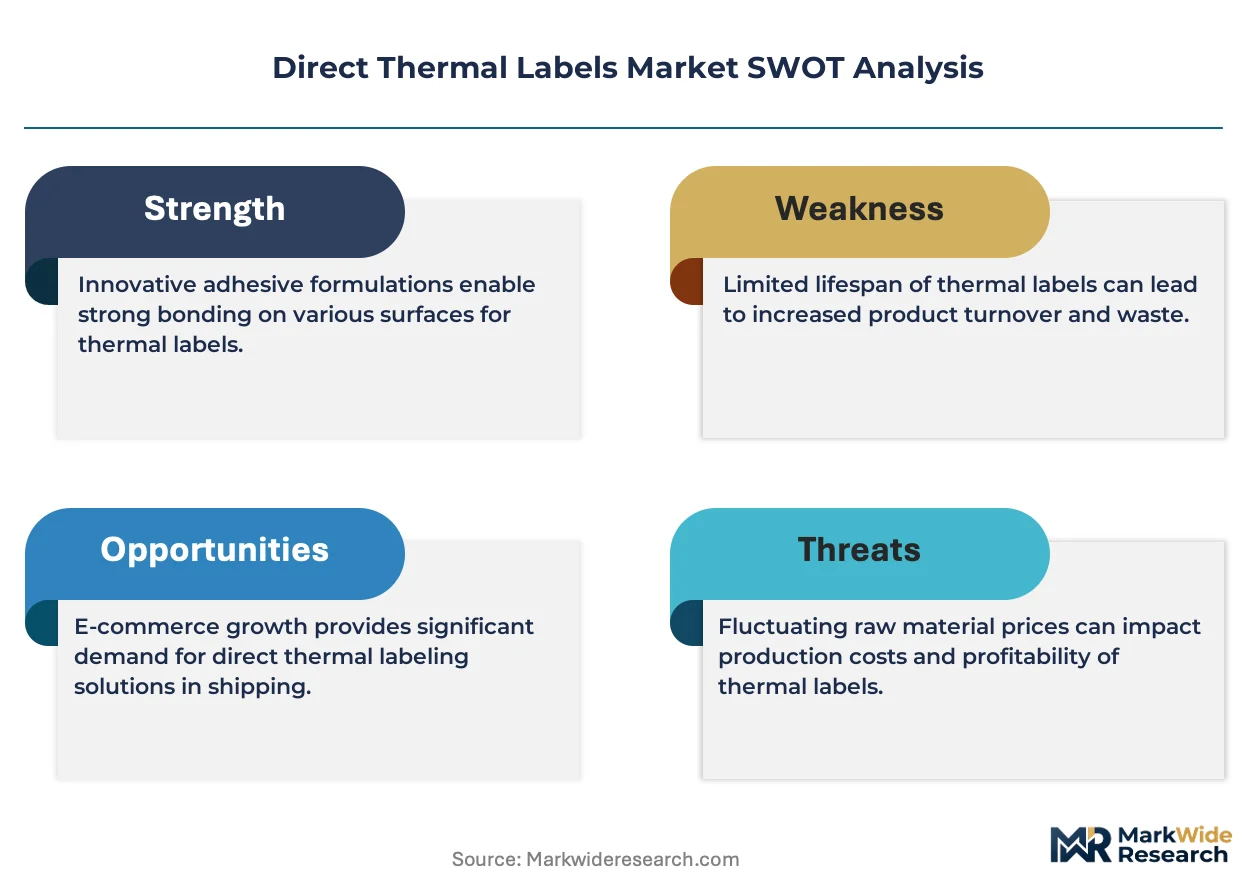
This market functions as a defensive-moat story anchored in regulatory entrenchment. EU F-Gas and REACH compliance costs create insurmountable qualification barriers that protect incumbent positions from price-based competition.
For Market Incumbents: Shield margin structures through captive phenol-free chemistry qualification ahead of ECHA enforcement deadlines. Expand synthetic substrate capacity near Swiss and Singapore biologics hubs to capture pharmaceutical serialization demand. Consolidate procurement relationships with multinational 3PLs through synchronized global supply contracts that exclude regional merchant competitors. For New Entrants and Emerging Players: Lead with UV-resistant thermal topcoat specialization for event ticketing and transportation credential applications where premium positioning offsets scale disadvantages. Target eco-friendly substrate segments serving EU Green Deal procurement criteria with FSC-certified offerings. Pursue digital printing convergence partnerships enabling hybrid thermal-inkjet production for short-run variable data jobs. For Investors and Strategic Acquirers: Precision automation specialists with sub-millimeter die-cutting capabilities represent the most defensible acquisition targets. Long-term viability hinges on coating chemistry control rather than volume scale. Watch ECHA REACH enforcement timing as the inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Phenol-Free Chemistry Reformulation | ECHA REACH compliance creates qualification barriers protecting early reformulators from price competition. |
| Synthetic Substrate Capacity Expansion | Cold-chain pharmaceutical demand in Switzerland and Singapore commands premium positioning over paper grades. |
| Backward Integration into Resin Compounding | Captive polymer chemistry control insulates margin structures from Asian feedstock price volatility. |
| Precision Die-Cutting Automation Investment | Japanese electronics supply chain specifications require sub-millimeter registration tolerance for component tracking. |
| Biologics Hub Proximity Positioning | Coating capacity near cell-and-gene therapy distribution nodes captures serialization demand with minimal logistics friction. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with coating plant managers, pharmaceutical packaging procurement leads, 3PL logistics directors, thermal chemistry R&D specialists, and regulatory affairs consultants. Secondary validation drew from FDA 21 CFR filings, ECHA REACH substance registrations, EU F-Gas Regulation implementation schedules, and customs trade data for thermal face-stock imports. Bottom-up volume modeling triangulated against top-down market sizing across substrate chemistry, adhesive formulation, and end-use verticals.
Across the analysis window, the forecasting framework segmented by product type, end user, application, and adhesive chemistry while modeling regional production hub dynamics. CAGRs were derived from trend extrapolation of e-commerce logistics velocity, pharmaceutical serialization mandate implementation, and synthetic substrate adoption curves. Industry-specific inputs included automated print-and-apply station deployment rates and cold-chain pharmaceutical distribution infrastructure buildout.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce logistics expansion and regulatory enforcement timelines would require recalibration. Forecasts reflect assumptions regarding phenol-free chemistry cost parity achievement and hydrofluorocarbon phase-down adherence. Practitioners should keep alternative scenarios live as ECHA REACH enforcement intensity and biologics cold-chain investment cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Linerless Labels Market
Labels
Syringe Labels Market
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
Hang Tags Market
Labels
Global QR Code Labels Market
Labels
Freshness Indicator Label Market
Labels
Kraft Labels Market
Labels
Coated Wet Glue Label Market
Labels
Self-Adhesive Labels Market
Labels
Sleeve Label Market
Labels
Ampoule Sticker Labeling Machine Market
Labels
Glue-Applied Labels Market
Labels
Direct Thermal Linerless Labels Market
Labels
Global Label Adhesive Market
Labels
Wet Glue Labels Market
Labels
Self-Laminating Tags Market