
 Liquid Encapsulation Market | 2026-2036
Liquid Encapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Encapsulation Market Outlook
Software-defined process control for encapsulation dosing and curing is rebalancing how equipment vendors package value around material sales. Shin-Etsu Chemical leverages captive silicone supply chains to dominate high-purity semiconductor encapsulant tiers. Henkel AG and Co. KGaA anchors European automotive electronics demand with thermally conductive liquid encapsulation systems. Sumitomo Bakelite Co., Ltd. specializes in epoxy novolac formulations that sustain market position in legacy IC packaging segments.
Liquid encapsulation is the controlled deposition of polymeric or resinous materials around active pharmaceutical ingredients, electronic dies, or agrochemical cores to achieve barrier protection, modified release, or environmental isolation; typical formulations employ epoxy resins, acrylics, or silicone polymers cured through thermal or UV-initiated crosslinking mechanisms. Microencapsulation leads pharmaceutical applications where controlled release kinetics determine therapeutic efficacy, while nanoencapsulation occupies the fastest-expanding tier in nutraceuticals driven by bioavailability enhancement demands. Spray drying sustains volume leadership in food and beverage applications where cost-efficient flavor and probiotic stabilization remains paramount.
EPA chemical safety evaluations under TSCA govern encapsulant resin compositions in US electronics manufacturing, while REACH registration requirements in Europe constrain phthalate and bisphenol-based formulation options. Japan's METI oversees chemical substance reporting that shapes regional product development priorities for Panasonic Corporation and Kyocera Corporation. Stakeholders must monitor evolving biocompatibility standards from ISO and national pharmaceutical regulators as healthcare and nutraceutical end users tighten encapsulant purity specifications.
Market Dynamics
Semiconductor packaging demand is concentrating liquid encapsulant procurement around high-purity silicone and epoxy novolac formulations, with equipment vendors bundling software-defined dosing control into material supply contracts to capture recurring revenue streams.
Growth Catalysts
- Advanced Packaging Nodes:Chiplet architectures and 3D stacking in high-performance computing are consuming specialized low-alpha particle encapsulants at volumes that justify dedicated production lines.
- REACH Chemical Registration:European manufacturers accelerating compliant resin substitutions ahead of 2027 reauthorization deadlines are pulling reformulated epoxy systems through qualification pipelines faster than historical replacement cycles.
- Automotive Electronics Clustering:Power module encapsulation for electric vehicle inverters is generating thermal conductivity specifications that standard industrial grades cannot satisfy, opening premium formulation tiers.
Market Restraints
- Organosilicone Feedstock Volatility:Methyl chlorosilane price swings tied to Chinese chlor-alkali capacity constrain margin predictability for silicone encapsulant producers.
- Japan Supply Concentration:Shin-Etsu Chemical and Hitachi Chemical control substantially all semiconductor-grade liquid encapsulant capacity for sub-10nm node applications, creating single-source vulnerability.
- Epoxy Curing Energy Intensity:Thermal crosslinking requirements consume 40-60% more energy per kilogram than UV-curable acrylic alternatives, exposing producers to carbon border adjustment mechanisms.
Strategic Opportunities
- Indian Electronics Manufacturing:Production-linked incentive schemes for semiconductor assembly and testing are attracting encapsulant distributors to establish local blending operations near Gujarat and Tamil Nadu clusters.
- Biodegradable Agrochemical Microcapsules:EPA registration pathways for starch-based wall materials are shortening approval timelines relative to synthetic polymer alternatives, opening crop protection formulations.
- UV-LED Curing Convergence:Wavelength-tuned photoinitiator systems paired with high-speed jetting equipment are enabling in-line encapsulation for flexible electronics that thermal curing cannot address.
Industry Challenges
- Formulation Chemist Scarcity:Cross-disciplinary expertise spanning polymer rheology, semiconductor reliability physics, and regulatory toxicology commands compensation premiums that mid-tier producers struggle to match.
- Cleanroom Capital Intensity:ISO Class 5 encapsulant compounding facilities require 18-24 month construction timelines and qualification protocols that delay capacity response to demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Encapsulation Market |
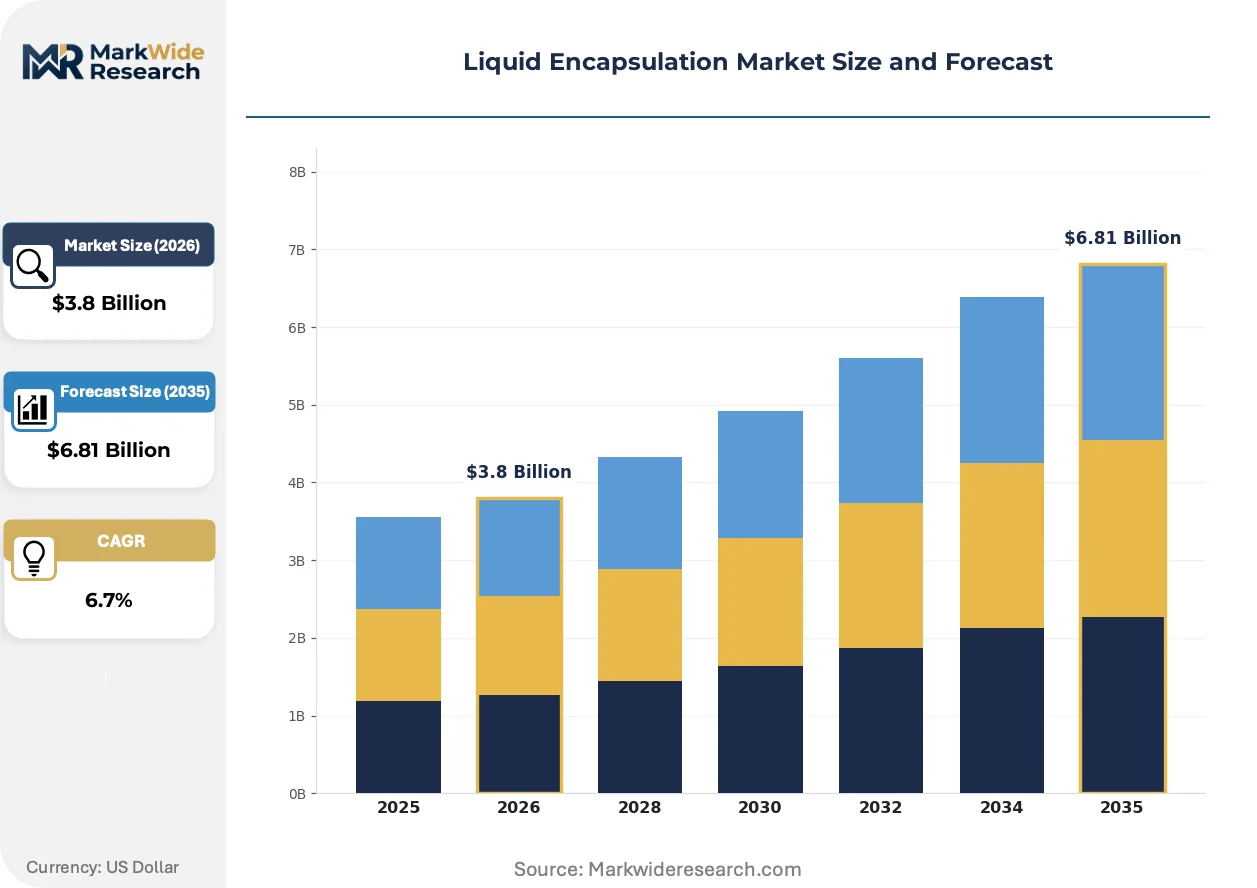
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microencapsulation, Macroencapsulation, Nanoencapsulation, Spray Drying Application: Pharmaceuticals, Food & Beverages, Cosmetics, Agriculture Technology: Electrospraying, Coacervation, Extrusion, Solvent Evaporation End User: Healthcare, Nutraceuticals, Personal Care, Animal Feed |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Sumitomo Bakelite Co., Ltd., Henkel AG and Co. KGaA, Nitto Denko Corporation, Hitachi Chemical Co. Ltd., Panasonic Corporation, Kyocera Corporation, Nagase & Co., Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Encapsulation Market Strategic Shifts
Process instrumentation and materials science are converging to displace batch-wise encapsulation with continuous manufacturing architectures that compress cycle times and reduce in-process inventory exposure.
Precision jetting deposition systems with real-time viscosity feedback are automating die-level encapsulant placement in advanced packaging operations. OSATs in Taiwan and South Korea are retrofitting legacy transfer molding lines with these modular dispensing heads at conversion rates exceeding prior equipment replacement cycles. The technology is automating labor-intensive encapsulation steps that previously required manual dam-and-fill operations, compressing unit economics for heterogeneous integration packages.
EPA chemical safety evaluations under TSCA Section 6 are narrowing the acceptable substance inventory for electronics encapsulants through systematic prioritization of bisphenol-A epoxy alternatives. Industrial consequence includes accelerated reformulation timelines and redundant qualification testing across multiple end-use certifications. Semiconductor packaging facilities in the US are responding by dual-sourcing Japanese and European resin suppliers to mitigate single-jurisdiction regulatory exposure.
Automotive Tier-1 suppliers are consolidating liquid encapsulant procurement through direct material qualification rather than delegating specification to subcontract assemblers. The practice shifts technical risk retention and inventory carrying costs upstream while compressing the number of approved resin grades per vehicle platform. This concentration is most visible in German and Japanese automotive electronics supply chains where power module reliability requirements have tightened joint-venture specifications.
Liquid Encapsulation Market Segmentation
Liquid encapsulation technologies serve distinct performance requirements across pharmaceutical dosing, semiconductor protection, and agrochemical delivery. Segment boundaries reflect formulation chemistry, processing equipment, and regulatory pathway differences that determine supplier qualification timelines.
Product Type:
Standalone encapsulation systems operate in batch pharmaceutical manufacturing, while embedded nanoencapsulation integrates directly into continuous food and nutraceutical processing lines.
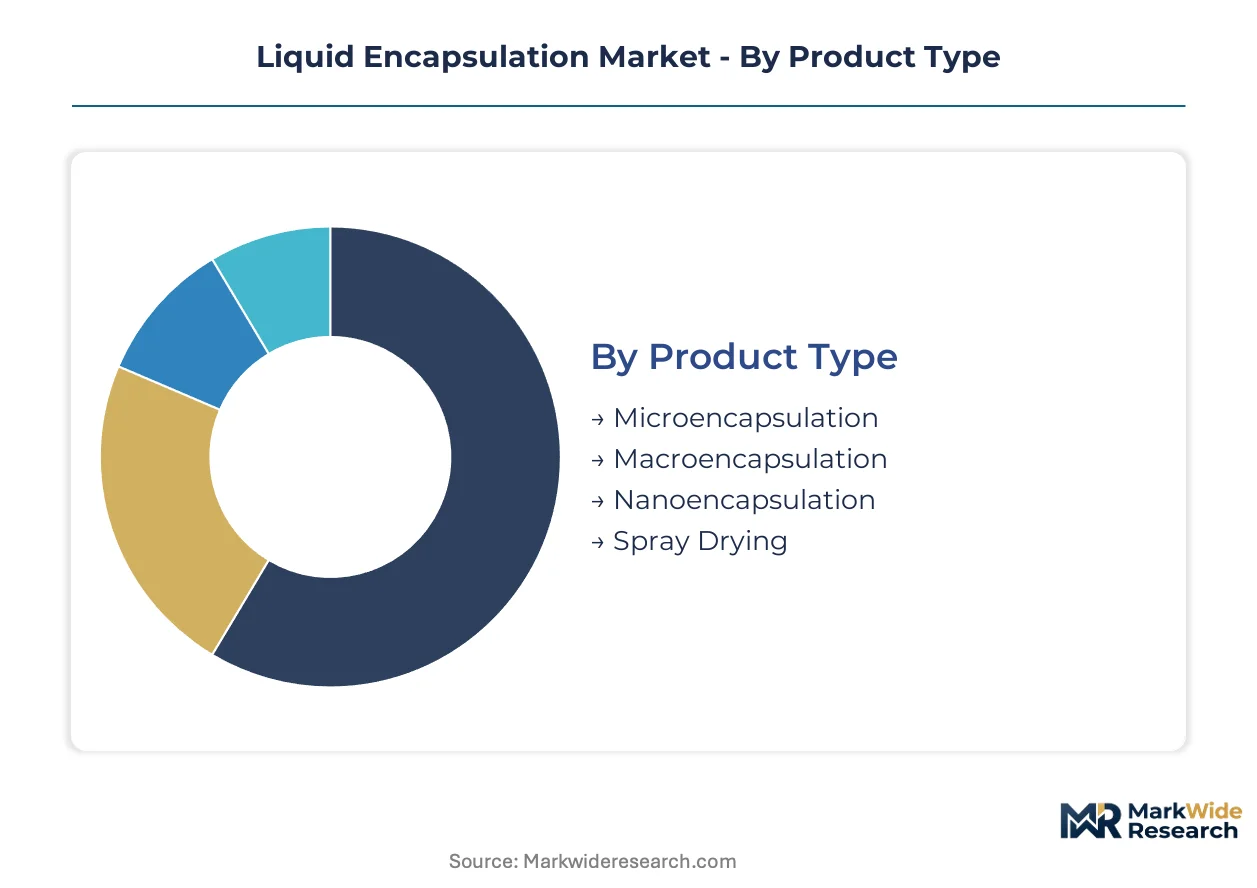
- Microencapsulation:Core-shell architectures with 1-1000 micron diameters employ gelatin, gum arabic, or modified starches as wall materials. Controlled release kinetics for pharmaceutical APIs drive demand concentration in US and European oral dosage manufacturing where FDA and EMA bioequivalence standards apply.
- Nanoencapsulation:Sub-micron particle systems enhance bioavailability of lipophilic actives through lipid-based or polymeric carriers. Nutraceutical applications in South Korea and Japan are climbing the fastest as MFDS and PMDA tighten purity specifications for functional food ingredients.
- Macroencapsulation:Millimeter-scale encapsulation protects probiotic cultures and enzyme preparations in animal feed applications.
- Spray Drying:Cost-efficient dehydration converts liquid feeds into stable powders for flavor and vitamin stabilization in food processing.
Microencapsulation leads volumes today; nanoencapsulation is gaining share fastest.
Application:
Cost tiers separate validated pharmaceutical systems from commodity food-grade encapsulation where formulation flexibility outweighs documentation burden.
- Pharmaceuticals:Enteric coatings and sustained-release matrices comply with USP dissolution standards and ICH stability guidelines. FDA validation requirements for cGMP manufacturing concentrate procurement among suppliers with dedicated pharmaceutical facilities.
- Food & Beverages:Probiotic encapsulation in dairy alternatives and functional beverages employs cheaper gum-based wall materials. FSSAI registration in India and EFSA novel food assessments in Europe shape regional formulation preferences.
- Cosmetics:Liposome and niosome carriers deliver active ingredients through dermal barriers.
- Agriculture:Microencapsulated pesticides and fertilizers enable controlled release that reduces environmental runoff.
Food & Beverages generates the highest unit volumes; Pharmaceuticals commands the steepest expansion trajectory.
Technology:
Process maturity determines equipment capital requirements and scale-up risk for encapsulation technology selection.
- Coacervation:Liquid-liquid phase separation using gelatin-gum arabic complexes achieves high payload efficiency for volatile flavors and oils. Established pharmaceutical applications in Germany and Switzerland leverage decades of process optimization at industrial scale.
- Electrospraying:Electrically driven jet breakup produces monodisperse particles with narrow size distributions. Research-stage adoption in academic and startup settings is expanding most quickly as equipment costs decline.
- Extrusion:Mechanical forcing through dies suits high-viscosity melts and hot-melt encapsulation of sensitive actives.
- Solvent Evaporation:Oil-in-water emulsion methods for polymeric nanoparticle formation serve injectable drug delivery applications.
Coacervation dominates commercial throughput; electrospraying shows the strongest technology momentum.
End User:
Customer type segmentation reflects divergent specification intensity between regulated healthcare applications and consumer-driven personal care markets.
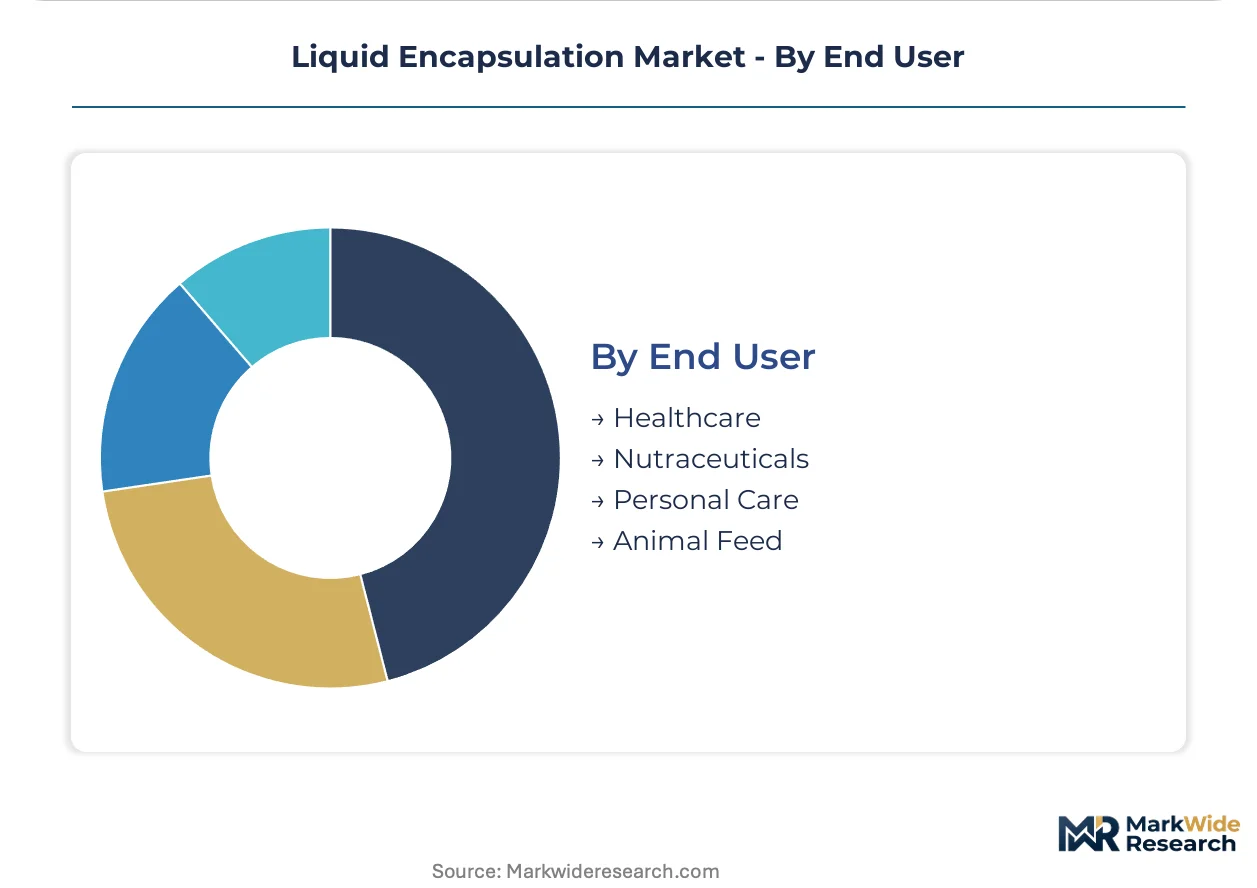
- Healthcare:Hospital and clinical settings demand sterile, pyrogen-free encapsulation for parenteral and implantable drug delivery. ISO 13485 quality system certification filters supplier pools in US and European medical device markets.
- Nutraceuticals:Dietary supplement manufacturers prioritize cost-efficient bioavailability enhancement over pharmaceutical-grade documentation. India's PLI scheme for food processing is accelerating local encapsulation capacity installation near Mumbai and Bangalore clusters.
- Personal Care:Cosmetic formulators seek sensory-optimized encapsulation for fragrance release and active protection.
- Animal Feed:Livestock and aquaculture producers use protected nutrients and enzymes to improve feed conversion ratios.
Healthcare anchors premium pricing tiers; nutraceuticals is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands semiconductor-grade liquid encapsulant production, while the United States concentrates pharmaceutical microencapsulation demand. Germany anchors European automotive electronics encapsulation. India attracts contract manufacturing investment. South Korea drives advanced packaging adoption.
Japan
Shin-Etsu Chemical and Hitachi Chemical supply sub-10nm node encapsulants for heterogeneous integration packages. METI chemical substance reporting shapes product development timelines for Panasonic and Kyocera. The Kanto region around Tokyo hosts ISO Class 5 compounding facilities serving OSATs in Taiwan and South Korea.
United States
Pharmaceutical microencapsulation for controlled-release oral dosages sustains demand concentration in New Jersey and North Carolina manufacturing corridors. EPA TSCA Section 6 evaluations are narrowing acceptable bisphenol-A epoxy alternatives, accelerating reformulation cycles. Boston-area biotech clusters are adopting nanoencapsulation for lipid-based drug delivery systems.
Germany
Automotive power module encapsulation for electric vehicle inverters generates thermal conductivity specifications exceeding standard industrial grades. REACH 2027 reauthorization deadlines are pulling reformulated epoxy systems through qualification pipelines. Bavaria's automotive electronics supply chains are consolidating procurement through direct material qualification rather than subcontract delegation.
India
Production-linked incentive schemes for semiconductor assembly and testing are attracting encapsulant distributors to establish local blending operations. FSSAI registration requirements shape regional formulation preferences for food-grade microencapsulation. Gujarat and Tamil Nadu clusters near Mumbai and Bangalore are installing encapsulation capacity for nutraceutical and food processing applications.
South Korea
OSATs are retrofitting legacy transfer molding lines with precision jetting deposition systems for chiplet architectures and 3D stacking. MFDS tightening purity specifications for functional food ingredients is climbing nanoencapsulation demand. Seoul Capital Area packaging facilities are automating die-level encapsulant placement that previously required manual dam-and-fill operations.
Liquid Encapsulation Market Competitive Environment
Top-tier vendors anchor semiconductor-grade silicone and epoxy novolac formulations, while mid-tier specialists occupy pharmaceutical and food-grade encapsulation segments. The market structure reflects captive supply chain advantages among Japanese chemical conglomerates alongside European automotive-focused material suppliers. Three archetypes dominate: vertically integrated resin producers with in-house monomer supply, equipment-integrated solution vendors bundling software-defined dosing control, and application-specific formulators serving regulated healthcare verticals. Competitive moves concentrate on strategic partnerships between encapsulant suppliers and precision dispensing equipment manufacturers, plus geographic expansion through local blending operations in emerging electronics manufacturing clusters.
Among Japanese chemical conglomerates, Shin-Etsu Chemical Co., Ltd. and Hitachi Chemical Co. Ltd. exemplify the vertically integrated archetype with substantial semiconductor-grade production capacity. Sumitomo Bakelite Co., Ltd. occupies a position specializing in epoxy novolac formulations for legacy IC packaging segments. Henkel AG and Co. KGaA represents the European automotive electronics vector with thermally conductive system development. These three entities anchor distinct competitive positions without overlapping core specializations.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Sumitomo Bakelite Co., Ltd. |
| Henkel AG and Co. KGaA |
| Nitto Denko Corporation |
| Hitachi Chemical Co. Ltd. |
| Panasonic Corporation |
| Kyocera Corporation |
| Nagase & Co., Ltd. |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Methyl chlorosilane feedstock costs cascade through semiconductor-grade silicone encapsulant pricing tiers, with Japanese producers commanding premium spreads over European and North American blenders due to captive chlor-alkali integration and ISO Class 5 qualification overhead.
Pricing Analysis
Capacity additions in India are reshaping price floors for food-grade microencapsulation while semiconductor-grade formulations sustain three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on METI chemical substance reporting compliance and thermal conductivity certification for automotive power modules. Cost compression in standard epoxy novolac tiers is intensifying because REACH 2027 reformulation cycles are accelerating redundant qualification testing. Pharmaceutical buyers exhibit lowest price sensitivity due to FDA validation lock-in, while nutraceutical contract manufacturers negotiate aggressively on volume scale.
Supply Chain Analysis
ISO 13485 and semiconductor-grade purity certifications gate supplier pools more stringently than production capacity, concentrating qualified resin compounding in Japan, Germany, and the United States. Raw material sourcing draws from Chinese chlor-alkali networks for methyl chlorosilane, Saudi petrochemical complexes for epoxy precursors, and Indian gum arabic harvests for pharmaceutical wall materials. Single-source vulnerability around Shin-Etsu Chemical's sub-10nm node capacity creates structural risk for advanced packaging supply chains. Distribution runs through authorized distributors with qualified blending operations rather than spot-market commodity channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid encapsulation market compounds steadily as semiconductor packaging node advancement sustains structural demand for high-purity formulations across electronics, pharmaceutical, and agrochemical verticals.
For Market Incumbents: Extend formulation chemist teams into software-defined dosing control partnerships to capture recurring equipment-integrated revenue streams and defend against equipment vendors bundling material supply contracts. Deepen captive silicone supply chains through backward integration into chlor-alkali inputs to secure margin predictability against Chinese feedstock volatility. Prioritize dual-jurisdiction regulatory qualification across EPA TSCA and REACH frameworks to mitigate single-market exposure. For New Entrants and Emerging Players: Launch via local blending operations adjacent to Indian semiconductor assembly clusters in Gujarat and Tamil Nadu, exploiting production-linked incentive scheme timing windows before incumbent distributors establish regional presence. Target biodegradable agrochemical microcapsule formulations where EPA registration pathways for starch-based wall materials shorten approval timelines relative to synthetic polymer incumbents. Pursue precision jetting equipment partnerships to differentiate on continuous manufacturing architectures versus legacy batch-wise competitors. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier pharmaceutical formulators lack ISO Class 5 capital intensity to match healthcare purity specification tightening. Five-to-ten year viability favors vertically integrated resin producers with in-house monomer supply and dedicated pharmaceutical facilities over pure-play equipment vendors. Monitor EPA Section 6 prioritization announcements for bisphenol-A epoxy alternatives as inflection signal for reformulation cycle acceleration and redundant qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Feedstock | Shin-Etsu Chemical's captive methyl chlorosilane supply anchors margin stability against Chinese price volatility. |
| Software-Defined Dosing Control Partnership | Equipment vendors bundling real-time viscosity feedback systems capture recurring revenue from OSAT retrofit cycles. |
| Dual-Jurisdiction Regulatory Qualification | Simultaneous EPA TSCA and REACH compliance filters supplier pools and extends contract duration with automotive Tier-1 buyers. |
| Local Blending Operations in India | Gujarat and Tamil Nadu proximity to semiconductor assembly clusters reduces logistics exposure and PLI scheme qualification timelines. |
| Biodegradable Agrochemical Formulation Development | Starch-based wall materials accelerate EPA registration pathways versus synthetic polymer alternatives in crop protection applications. |
Study Parameters
Multiple input streams — formulation chemist interviews, semiconductor packaging engineer consultations, regulatory affairs director surveys, and procurement lead discussions — were reconciled against secondary validation from EPA TSCA Section 6 dockets, ECHA REACH registration databases, METI chemical substance reports, and SEC 10-K resin segment disclosures. Bottom-up encapsulant volume modeling by application and grade tier was cross-checked against top-down electronics manufacturing value chain estimates.
Segment-level CAGRs across the projection horizon were derived from semiconductor packaging capital expenditure trajectories, pharmaceutical controlled-release pipeline data, and agrochemical microcapsule registration timelines. The analytical framework modeled technology adoption curves for precision jetting deposition, UV-LED curing convergence, and continuous manufacturing architectures alongside formulation chemistry shifts driven by regulatory prioritization.
Forecast precision tightens around the base case; tail outcomes carry wider variance under organosilicone feedstock price spike scenarios or accelerated REACH authorization withdrawals. Deviation in EPA Section 6 bisphenol-A epoxy restriction timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Middle East and Africa Single-Use Packaging Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Cardboard Trays Market
Packaging Materials
Foil Laminates Market
Packaging Materials
Construction Films Market
Packaging Materials
Bulb Packaging Market
Packaging Materials
VCI Films Market
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Floppy Disk Liner Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Face Stock Films Market
Packaging Materials
Coconut Wraps Market
Packaging Materials
Packaging Reel Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Postal Packaging Market