
 Cupcake Wrappers Market | 2026-2036
Cupcake Wrappers Market Size, Share, and Industry Trends Forecast 2026-2036
Cupcake Wrappers Market Outlook
Modular wrapper-and-liner bundling is repositioning how commercial buyers configure their packaging spend. Reynolds Consumer Products leverages its paper manufacturing scale to dominate North American parchment supply. Novacart competes through specialized European baking mold exports. Wilton Brands anchors the home baking segment with craft-oriented distribution through mass retail channels.
Cupcake wrappers are thin, shaped barriers placed between batter and baking tin, typically composed of grease-resistant parchment, aluminum foil, or food-grade silicone with heat tolerance exceeding 200°C, designed to prevent sticking and enable individual portion handling. Parchment paper wrappers sustain the largest volume position due to biodegradability alignment with foodservice sustainability mandates, while silicone variants register the fastest expansion as home bakers prioritize reusable kitchen tools. Foil wrappers occupy premium event and catering applications where metallic presentation drives purchasing decisions.
The FDA governs direct food contact substances under 21 CFR 175-178, compelling domestic manufacturers to validate extraction limits and migration thresholds for coated papers and polymer films. State-level extended producer responsibility frameworks in California and New York are reshaping how suppliers document recyclability claims and material recovery pathways. Stakeholders must monitor evolving compostability certification requirements from the Biodegradable Products Institute and assess whether silicone reuse rates justify higher unit economics against single-use alternatives.
Market Dynamics
Modular wrapper-and-liner bundling is compressing procurement cycles as commercial buyers consolidate supplier relationships, while state-level extended producer responsibility mandates force packaging redesigns ahead of federal standardization.
Growth Catalysts
- California's SB 54 EPR framework:Mandatory recyclability documentation accelerates compostable parchment adoption among foodservice distributors serving West Coast accounts.
- Specialty bakery expansion:Custom wrapper programs for wedding and corporate events pull premium foil and printed parchment volumes through regional cake chains.
- Silicone reuse economics:Home baking enthusiasts in premium suburbs calculate per-use cost advantages, driving repeat purchase cycles for multi-pack silicone sets.
Market Restraints
- Fluorochemical coating supply concentration:Three specialty chemical producers control grease-resistant barrier formulations, exposing wrapper manufacturers to input price volatility.
- FDA 21 CFR 175.300 migration thresholds:Extended validation timelines for new coating chemistries delay product launches by 18-24 months.
- Uncoated paper substitution:Muffin tin liners and direct greasing protocols retain share among price-sensitive institutional foodservice operations.
Strategic Opportunities
- India FSSAI packaging safety harmonization:Unified national standards for food-contact materials create export pathways for certified parchment producers.
- Subscription baking kit channels:Curated monthly boxes featuring themed wrapper assortments bypass traditional retail shelf competition.
- EU Green Deal packaging waste targets:Mandatory reuse quotas for foodservice operators position silicone wrapper rental models for institutional adoption.
Industry Challenges
- BPI compostability certification backlog:Testing facility capacity constraints extend commercialization timelines for biodegradable coated papers.
- Legacy printing press retrofit costs:Food-safe ink migration compliance requires capital expenditure on aqueous coating lines for established converter operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cupcake Wrappers Market |
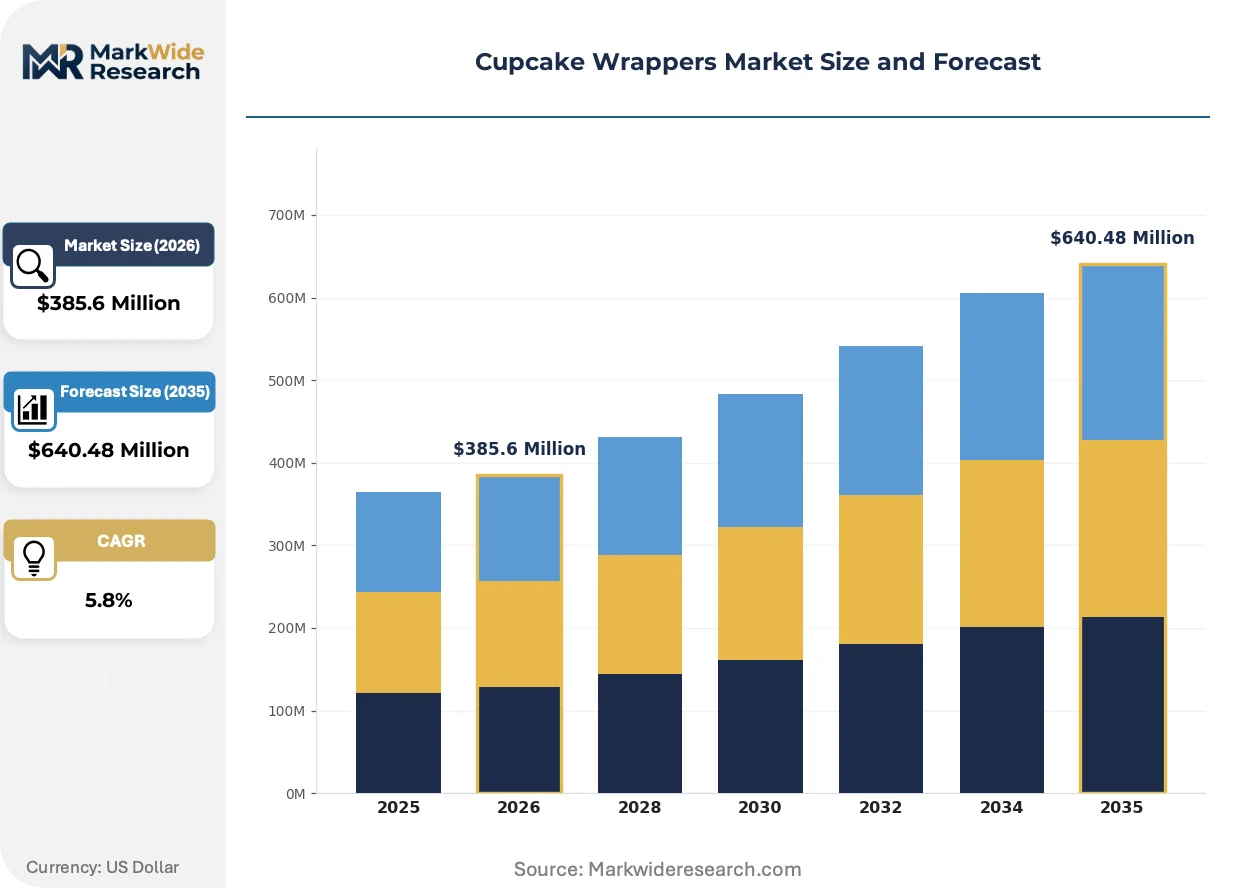
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Parchment Paper, Foil, Plastic, Silicone, Rice Paper Color & Design: Solid Colors, Prints, Metallics, Pastels, Transparent End Use: Bakeries, Confectioners, Home Bakers, Catering Services, Event Planners Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Wholesale Suppliers, Direct Sales |
| Companies Covered | Reynolds Consumer Products, Novacart, Wilton Brands, PaperChef, Simply Baked, Rockline Industries, Welcome Home Brands, Hoffmaster Group, Temmashiki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cupcake Wrappers Market Strategic Shifts
Active material science and distribution model experimentation are compressing traditional wrapper procurement patterns. Three forces merit attention: coating chemistry evolution, regulatory harmonization pressures, and channel restructuring.
Plant-based barrier coatings are decentralizing grease-resistance technology away from fluorochemical dependence. Mid-size converters in the Netherlands and California pilot algae-derived and lignin-based formulations. Specialty bakeries with sustainability mandates now specify these alternatives in RFPs, fragmenting what was a consolidated coating supply tier.
REACH SVHC candidate list expansion is forcing coating reformulation across EU-exporting wrapper manufacturers. Substances including certain PFAS precursors face authorization sunset dates. Parchment converters serving dual US-EU markets are consolidating SKUs around compliant chemistries, compressing product line complexity.
Direct-to-bakery digital platforms are shortening wrapper procurement cycles from quarterly to monthly replenishment. Cloud-based inventory management tools enable smaller commercial bakeries to reduce safety stock. This pattern concentrates most visibly in the United Kingdom's independent bakery sector, where distributor consolidation has reduced alternative sourcing options.
Cupcake Wrappers Market Segmentation
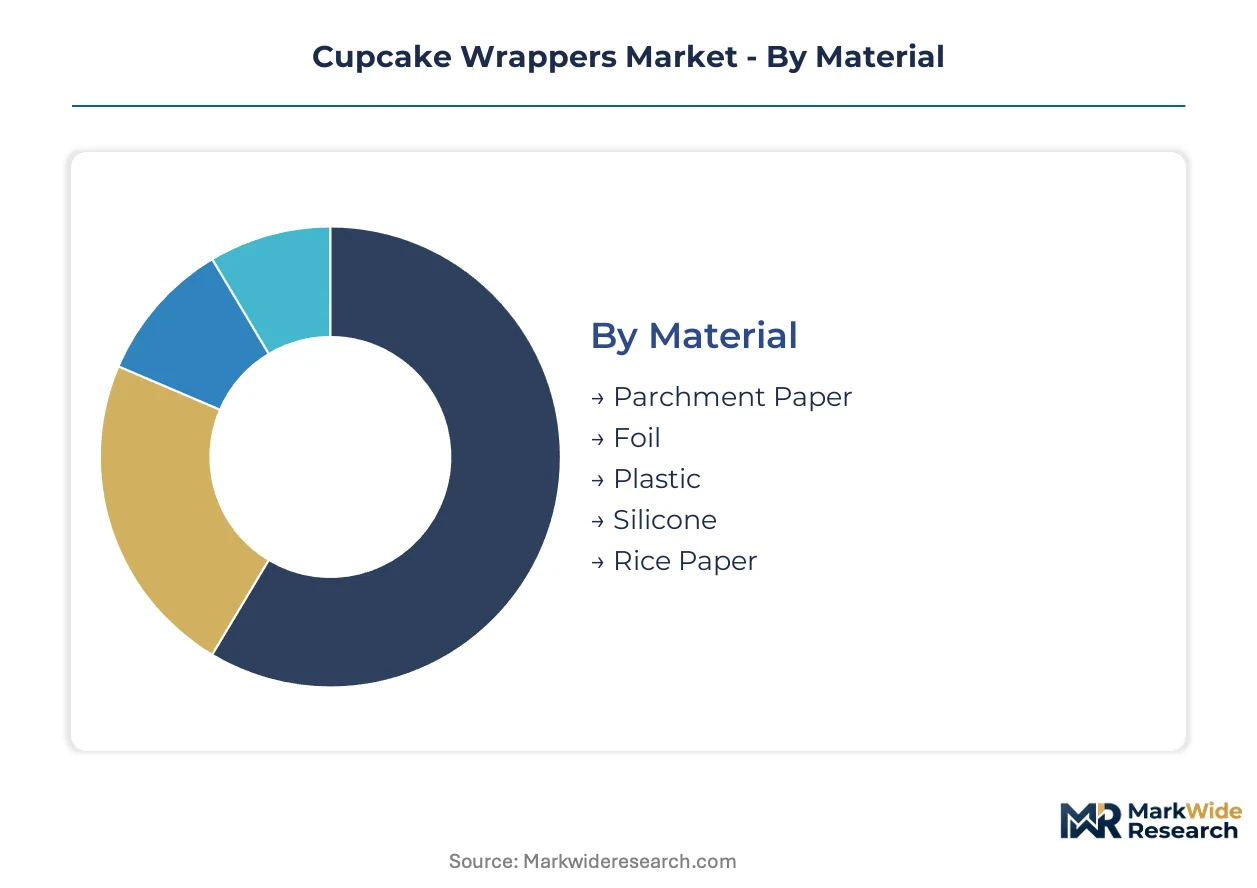
Wrapper procurement patterns diverge sharply across material chemistry and end-use application. Supply concentration in barrier coating technology creates tiered performance expectations that reshape how buyers evaluate cost-per-bake economics.
Material:
Grease-resistant barrier supply concentrates among fluorochemical specialists, forcing converters to qualify alternative formulations.
- Parchment Paper:Cellulose-based sheets treated with silicone or quilon for heat resistance above 200°C. Foodservice distributors in California prioritize compostable variants to satisfy SB 54 documentation requirements.
- Silicone:Food-grade elastomer molds withstand 500+ bake cycles. Premium suburbs in the United States drive multi-pack purchases as home bakers calculate per-use cost advantages against disposables.
- Foil:Aluminum laminates deliver metallic presentation for wedding and corporate events. Regional cake chains specify embossed patterns for premium tier differentiation.
- Plastic:PET and polypropylene films serve cold-display applications where heat tolerance is unnecessary. Confectioners favor clarity for product visibility.
- Rice Paper:Edible starch-based sheets dissolve during baking for seamless cake integration. Specialty Asian bakeries in urban clusters specify these for traditional dessert formats.
Parchment paper absorbs the bulk of installed capacity; silicone is expanding most quickly.
Color & Design:
Converter capital allocation tilts toward aqueous coating lines that enable food-safe ink migration compliance.
- Prints:Rotogravure and flexographic patterns featuring seasonal motifs, licensed characters, and custom branding. Wedding planners in the United States commission bespoke designs for coordinated event aesthetics.
- Metallics:Vacuum-metallized films and foil laminates refract light for luxury positioning. Catering services specify these for corporate galas where presentation drives per-piece pricing.
- Solid Colors:Single-pigment coatings match brand palettes for retail bakery chains. Standardization reduces SKU complexity for high-volume converters.
- Pastels:Soft-tone palettes target spring events and children's parties. Home baking enthusiasts in suburban markets favor these for Instagram-optimized presentation.
- Transparent:Uncoated cellulose or clear films showcase wrapper-cake contrast. Confectioners use these for layered dessert visibility.
Prints dominate current converter throughput; metallics command the steepest expansion trajectory among premium tiers.
End Use:
Procurement scale and customization tolerance separate institutional buyers from fragmented consumer segments.
- Bakeries:Regional cake chains and independent operations source wrapper-and-liner bundles through consolidated distributor relationships. Monthly replenishment cycles compress safety stock requirements.
- Catering Services:Event-focused operators demand foil and metallic variants for presentation-critical applications. Corporate account retention depends on rapid custom print turnaround.
- Home Bakers:Premium suburb enthusiasts prioritize reusable silicone and compostable parchment. Subscription baking kit channels bypass traditional retail for curated monthly assortments.
- Confectioners:Chocolate and candy specialists specify transparent and rice paper formats for product visibility. Cold-chain display requirements limit heat-tolerant material relevance.
- Event Planners:Wedding and corporate coordinators commission bespoke print programs with 6-8 week lead times. Direct-to-bakery digital platforms shorten specification cycles.
Bakeries anchor volume demand; home bakers are climbing the fastest as silicone reuse economics penetrate suburban markets.
Distribution Channel:
Channel restructuring concentrates procurement power while fragmenting last-mile access.
- Wholesale Suppliers:Distributor consolidation in the United Kingdom's independent bakery sector reduces alternative sourcing options. Cloud-based inventory tools enable smaller commercial buyers to reduce safety stock.
- Online Retailers:Amazon and specialty baking platforms aggregate silicone multi-pack and themed wrapper assortments. Subscription channels bypass shelf competition entirely.
- Specialty Stores:Craft-oriented retailers like Michaels and Jo-Ann anchor Wilton Brands' home baking distribution. In-store merchandising drives impulse purchases of seasonal print collections.
- Supermarkets:Mass retail placement captures occasional bakers through parchment paper multipacks. Private label programs compete on price against branded alternatives.
- Direct Sales:Converter relationships with large bakery chains eliminate distributor margins. Minimum order quantities restrict access to mid-tier operations.
Wholesale suppliers retain the largest share of commercial volume; online retailers are gaining share fastest through subscription model expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in North American and European converter networks while consumption concentrates in premium home baking segments across suburban United States and United Kingdom markets. Regulatory divergence between FDA migration thresholds and EU REACH SVHC restrictions fragments formulation standardization. Distribution infrastructure varies sharply by geography, with direct-to-bakery digital platforms penetrating Anglo-Saxon markets faster than continental European wholesale consolidation.
United States
California's SB 54 extended producer responsibility framework accelerates compostable parchment adoption among foodservice distributors serving West Coast accounts. FDA 21 CFR 175.300 governs direct food contact substance migration thresholds, compelling domestic manufacturers to validate extraction limits for coated papers. Premium suburbs in Connecticut and New Jersey drive silicone multi-pack purchases as home bakers calculate per-use cost advantages against disposables.
Germany
REACH SVHC candidate list expansion forces coating reformulation across parchment converters serving dual US-EU markets. ECHA authorization sunset dates for certain PFAS precursors compress product line complexity around compliant chemistries. Industrial clusters in North Rhine-Westphalia host mid-size converters piloting algae-derived and lignin-based barrier formulations for sustainability-mandated specialty bakeries.
United Kingdom
Independent bakery sector distributor consolidation reduces alternative sourcing options and concentrates procurement power. Cloud-based inventory management tools enable smaller commercial bakeries to reduce safety stock requirements. London and Southeast England anchor direct-to-bakery digital platform penetration, shortening wrapper procurement cycles from quarterly to monthly replenishment.
India
FSSAI packaging safety harmonization creates export pathways for certified parchment producers meeting unified national standards for food-contact materials. Maharashtra and Gujarat industrial corridors attract converter investments targeting domestic bakery expansion and Middle East re-export. Mumbai-based specialty Asian bakeries specify rice paper formats for traditional dessert formats requiring seamless cake integration.
Netherlands
EU Green Deal packaging waste targets position silicone wrapper rental models for institutional foodservice adoption. Mid-size converters in Randstad pilot plant-based barrier coatings decentralizing grease-resistance technology away from fluorochemical dependence. Amsterdam and Rotterdam distribution hubs facilitate European baking mold export logistics for specialized converter operations.
Cupcake Wrappers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across material chemistry and distribution channel vectors. Consolidation pressures concentrate among parchment converters facing coating supply constraints, while fragmentation persists in silicone mold fabrication serving home baking niches. Three archetypes dominate: paper manufacturing conglomerates leveraging scale economies, specialized European baking mold exporters, and craft-oriented brands anchoring mass retail distribution. Competitive moves center on backward integration into coating supply and strategic partnerships with subscription baking kit channels.
Among North American conglomerates, Reynolds Consumer Products exemplifies scale-driven parchment supply dominance through paper manufacturing integration. Novacart occupies a position within specialized European export archetypes focused on baking mold sophistication. Wilton Brands anchors the craft-oriented mass retail tier through specialty store distribution relationships. These three represent distinct strategic postures rather than direct substitutability, with each archetype capturing value from different buyer segments and procurement modalities.
| Leading Market Players |
|---|
| Reynolds Consumer Products |
| Novacart |
| Wilton Brands |
| PaperChef |
| Simply Baked |
| Rockline Industries |
| Welcome Home Brands |
| Hoffmaster Group |
| Temmashiki |
| Others |
Value Chain & Pricing Dynamics
Pulp futures volatility on the Chicago Mercantile Exchange cascades through parchment converter operations into three-tier pricing structure across premium, standard, and economy levels, with fluorochemical coating shortages amplifying spreads between compliant and legacy formulations.
Pricing Analysis
Margin tightening in foodservice parchment traces to California SB 54 compliance premiums and BPI certification bottlenecks. Three-tier pricing structure across premium, standard, and economy levels separates compostable certified stock from conventional quilon-coated alternatives from uncoated economy grades. Price differentiation rests on migration test documentation and volume commitment scale. Institutional foodservice buyers exhibit highest price sensitivity; wedding catering operators show lowest sensitivity to per-unit premiums for custom metallics.
Supply Chain Analysis
FDA 21 CFR 175.300 compliance documentation gates supplier qualification for US-bound parchment, extending validation timelines. Manufacturing concentrates in the United States, Germany, and China for barrier-coated papers; silicone molding clusters in South Korea and Malaysia. Raw material dependencies include specialty fluorochemicals from Belgium and Japan, food-grade silicone elastomers from Germany, and bleached kraft pulp from Canada and Scandinavia. Single-source vulnerability concentrates in grease-resistant coating formulations. Distribution runs through consolidated foodservice distributors and direct-to-bakery digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into coating chemistry represents the decisive vertical-integration race, with parchment converters pursuing captive fluorochemical-alternative production to escape supply concentration and price volatility.
For Market Incumbents: Extend barrier coating R&D partnerships with Dutch and California-based plant-based formulation pioneers to preempt REACH SVHC authorization sunset impacts. Secure multi-year pulp offtake agreements with Scandinavian suppliers to defend margin position against input cost spikes. Prioritize aqueous coating line retrofit completion ahead of FDA migration threshold enforcement tightening.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in compostable parchment offers white-space entry for mid-size converters with BPI pre-certification. Target California and New York foodservice distributors with SB 54-compliant SKUs ahead of federal EPR harmonization. Deploy subscription baking kit channel partnerships to bypass entrenched wholesale supplier relationships.
For Investors and Strategic Acquirers: The window for entry favors specialized European baking mold exporters with REACH-compliant chemistry portfolios and established Middle East re-export logistics. Long-term viability hinges on coating technology diversification beyond fluorochemical dependence. Monitor FSSAI harmonization progress in India as inflection signal for certified parchment export volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Chemistry | Captive plant-based barrier production reduces fluorochemical supply concentration exposure for parchment converters. |
| Compostability Certification Pre-Investment | BPI pipeline positioning accelerates commercialization timelines ahead of state EPR mandate expansion. |
| Direct-to-Bakery Digital Platform Launch | Cloud-based inventory tools compress procurement cycles and disintermediate consolidated distributor relationships. |
| Silicone Rental Model Pilot | EU Green Deal reuse quotas position institutional foodservice adoption for wrapper-as-service economics. |
| India FSSAI Export Certification | Unified national standards create Middle East re-export pathways for Maharashtra and Gujarat converter investments. |
Study Parameters
Multi-period observation of pulp futures pricing, coating chemistry patent filings, and state EPR regulatory dockets anchored the trend analysis, supplemented by interviews with parchment converter plant managers, foodservice distributor procurement leads, specialty bakery operations directors, and FDA regulatory affairs consultants. Secondary validation drew from customs trade data, SEC 10-K disclosures of paper manufacturing conglomerates, BPI certification databases, and ECHA SVHC candidate list updates. Bottom-up volume modeling triangulated against top-down spending pattern analysis across end-use segments.
Input-output matrices mapped material chemistry, end-use application, and distribution channel interactions across the projection horizon. Segmentation dimensions modeled include material type, color and design tier, end-use buyer archetype, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating silicone reuse rate assumptions and parchment substitution dynamics. Industry-specific forecast inputs included fluorochemical coating supply concentration indices and compostability certification backlog estimates.
Underlying measurement precision varies by segment; silicone volume forecasts carry tighter precision than rice paper niche estimates due to subscription channel data availability. Forecasts reflect assumptions regarding EPR mandate adoption timing and coating chemistry substitution rates. A model refresh is warranted upon material change in REACH SVHC authorization sunset schedules or FDA migration threshold enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Squeeze Tube Market
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
North America Stick Packaging Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Lidding Foil Market
Packaging Materials
Urn Liners Market
Packaging Materials
Textile Packaging Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Corrugated Wrap Around Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Insulated Thermal Box Liners Market