
 Graphene Infused Packaging Market | 2026-2036
Graphene Infused Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Graphene Infused Packaging Market Foresight
Barrier-grade specification tiers is collapsing the gap between conventional multilayer films and single-layer graphene-reinforced alternatives, forcing incumbents to recalibrate R&D spend. Global Graphene Group leverages its Ohio-based production assets to control raw material quality from mine to masterbatch. Xiamen Knano Graphene Technology Co. anchors supply across East Asian electronics packaging channels with ISO-certified flake consistency. NanoXplore Inc. differentiates through in-house exfoliation methods that sustain pricing power in North American pharmaceutical barrier applications.
Graphene infused packaging incorporates atomically thin carbon lattices—typically 1-10 layers thick at 0.3-3 nanometer thickness—dispersed into polymer matrices to enhance tensile strength, thermal conductivity, and gas barrier performance for sensitive goods protection. Films leads product type demand as brand owners prioritize oxygen transmission rate reductions below 0.1 cc/m²/day for protein-based foods. Antimicrobial packaging within the application dimension captures accelerating margin pools as healthcare and fresh-produce sectors validate ISO 22196 bacterial reduction standards. Electronics packaging competes for capacity with semiconductor shipment protocols requiring electrostatic discharge shielding below 10³ ohms per square.
FDA food contact substance notifications govern graphene-polyethylene composites in US distribution, while EFSA novel food and material assessments create parallel compliance pathways for European market entry. China's SAMR GB standards for plastic food packaging and REACH Article 7 nanomaterial registration obligations in Europe collectively raise technical documentation burdens for importers. Stakeholders must monitor evolving toxicity data requirements from OECD Test Guideline 318 before committing to multi-year supply agreements with flake suppliers.
Market Dynamics
Barrier-grade graphene composites are collapsing the performance gap between conventional multilayer films and single-layer reinforced alternatives, forcing incumbents to recalibrate R&D spend toward masterbatch consistency and flake dispersion control.
Growth Catalysts
- EU Green Deal packaging waste directives:Biodegradable polymer substitution mandates accelerate material transition toward graphene-infused barrier films in food and beverage applications.
- Antimicrobial film validation:ISO 22196 bacterial reduction standards unlock healthcare and fresh-produce sector procurement for shelf-life extension technologies.
- Germany's industrial packaging clusters:Food safety regulators and premium barrier-grade demand concentrate in Baden-Württemberg and Bavaria manufacturing corridors.
Market Restraints
- Flake supply concentration:High-purity graphite mining and exfoliation capacity clusters in China create import dependency for European and North American compounders.
- REACH Article 7 nanomaterial registration:ECHA documentation burdens for graphene-polyethylene composites extend European market entry timelines by 18-24 months.
- Conventional multilayer film cost base:Ethylene-vinyl alcohol and polyamide barrier layers retain price advantage at scale for oxygen-sensitive protein packaging.
Strategic Opportunities
- Electronics packaging channel expansion:Semiconductor shipment protocols requiring electrostatic discharge shielding below 10³ ohms per square displace metallized films in Asian logistics hubs.
- Pharmaceutical barrier certification:US FDA food contact substance notifications for graphene-polyethylene composites open dosage protection applications previously served by glass and aluminum.
- India's PLI scheme for advanced materials:Domestic graphene production incentives under the chemicals and petrochemicals mission reduce import duty exposure for packaging converters.
Industry Challenges
- Masterbatch dispersion engineering talent:Atomically thin carbon lattice uniform distribution at 0.3-3 nanometer thickness requires rare polymer rheology and nanomaterial handling expertise.
- OECD Test Guideline 318 toxicity data gaps:Evolving ecotoxicity documentation requirements for multi-year flake supply agreements create procurement uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphene Infused Packaging Market |
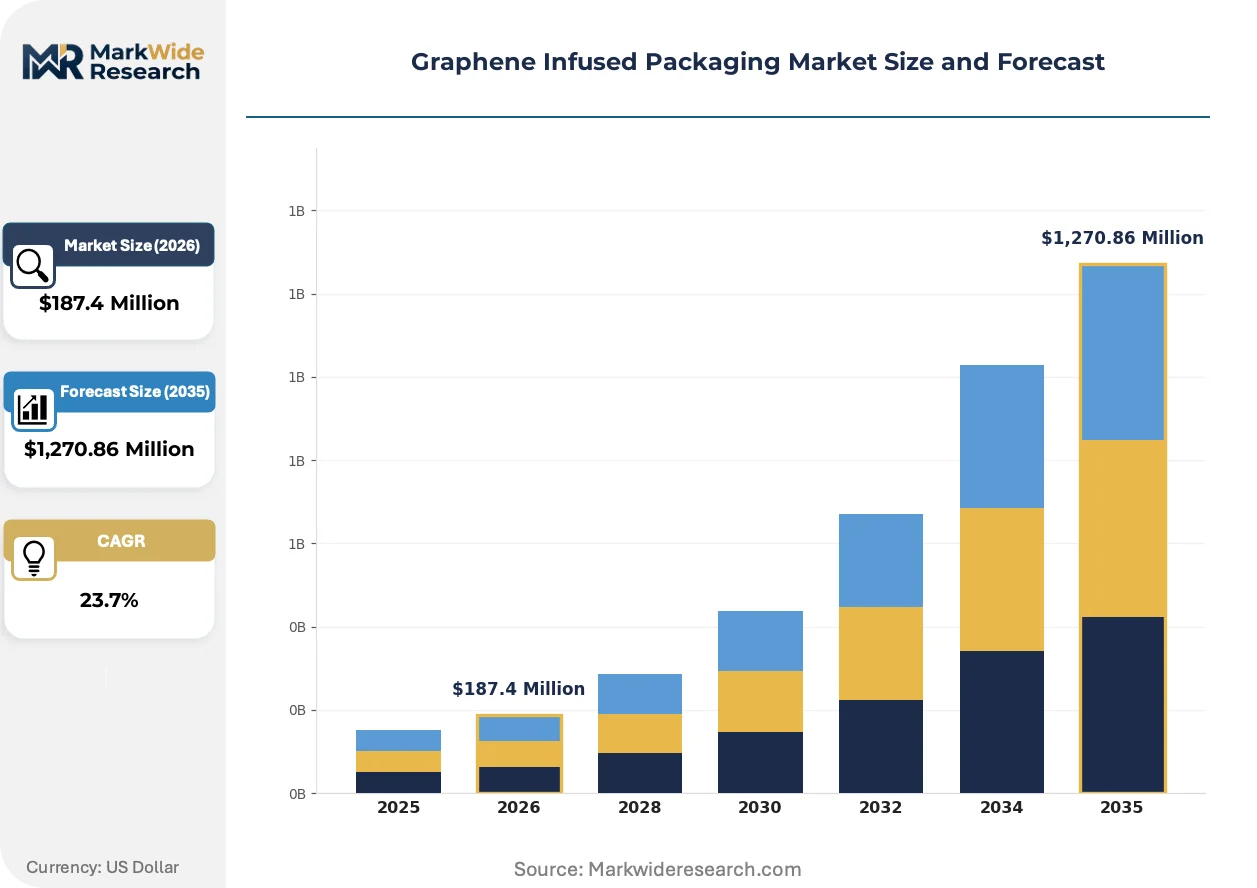
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Films, Containers, Labels End User: Food & Beverage, Pharmaceuticals, Electronics, Consumer Goods Material: Polyethylene, Polypropylene, Paper, Biodegradable Polymers Application: Barrier Coatings, Antimicrobial Packaging, Electronics Packaging, Smart Packaging |
| Companies Covered | Global Graphene Group, Xiamen Knano Graphene Technology Co., NanoXplore Inc., Directa Plus S.p.A, Grolltex Inc., Universal Matter GBR Ltd, ACS Material, Thomas Swan & Co. Ltd., Graphenea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphene Infused Packaging Market Shifts & Advancements
Active reshaping of this market centers on atomic-scale material engineering, regulatory compliance automation, and procurement model compression across sensitive goods protection value chains.
Atomically thin carbon lattice integration at 1-10 layer thickness is miniaturizing barrier performance into single-ply polymer substrates. Food and beverage brand owners in Germany and the Netherlands adopt these films at pilot scale for oxygen transmission rates below 0.1 cc/m²/day. The structural consequence compresses coextrusion equipment requirements and reduces packaging line complexity for protein-based product manufacturers.
EFSA novel food and material assessments are creating parallel compliance pathways alongside FDA food contact substance notifications. Dual-track regulatory documentation raises technical staffing requirements but accelerates transatlantic market access for qualified compounders. Pharmaceutical barrier applications in North America and fresh-produce antimicrobial films in Europe face the steepest certification investment curves.
Brand-owner technical audits of flake provenance are displacing traditional resin-grade specifications in procurement contracts. Electronics packaging buyers in South Korea and Taiwan now require ISO-certified exfoliation method documentation and mine-to-masterbatch traceability. This behavioral shift concentrates supplier qualification pools and extends contract negotiation cycles for non-vertically integrated compounders.
Graphene Infused Packaging Market Segmentation
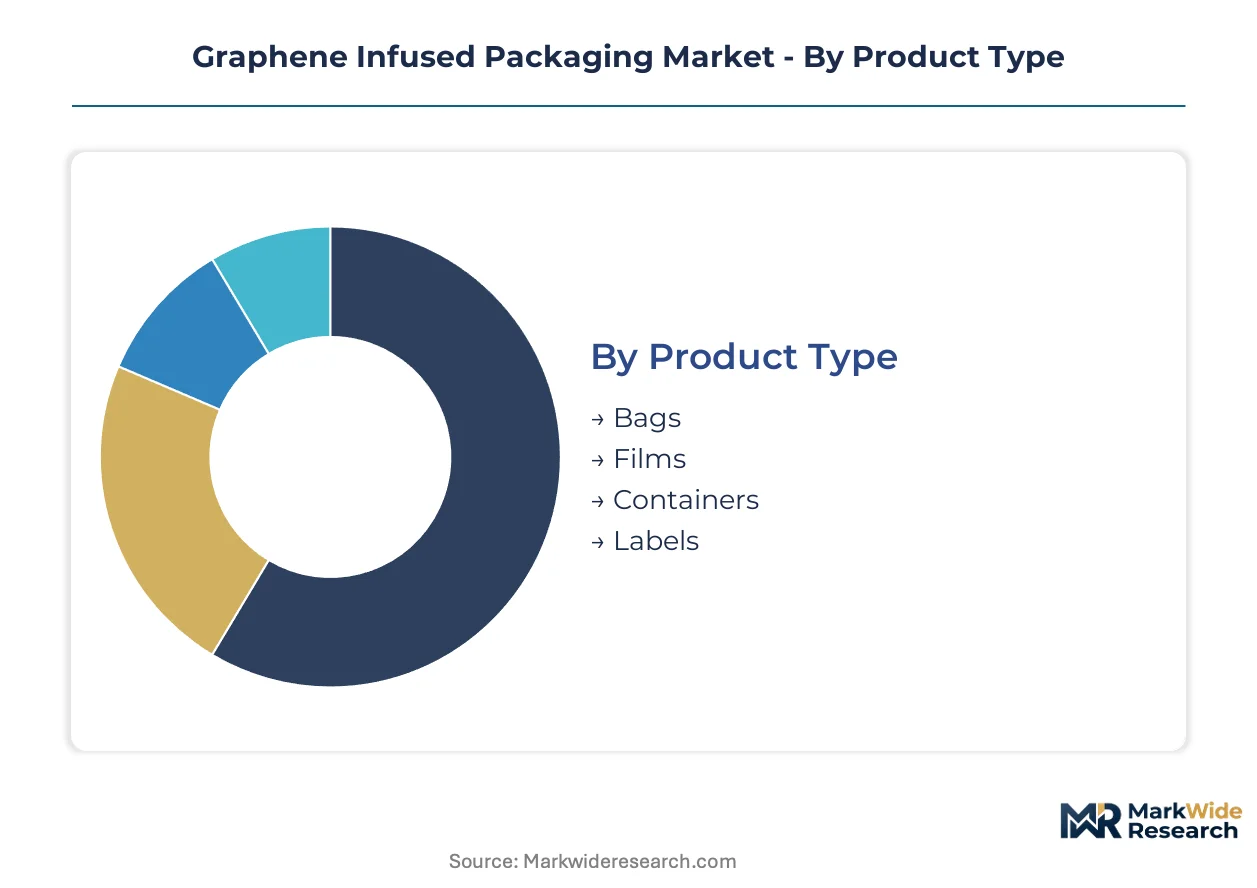
Segmentation in graphene infused packaging reveals how atomically thin carbon lattice integration varies by substrate compatibility, regulatory pathway, and performance specification. Each dimension exposes distinct commercialization timelines and margin structures for compounders and converters.
Product Type:
FDA food contact substance notifications and EFSA novel material assessments create divergent certification burdens across physical formats, with flexible films facing shorter approval cycles than rigid containers.
- Films:Single-ply and multilayer flexible substrates incorporate 1-10 layer graphene dispersions at 0.3-3 nanometer thickness for oxygen transmission rates below 0.1 cc/m²/day. German food safety regulators in Baden-Württemberg drive premium uptake for protein-based shelf-life extension, though masterbatch dispersion engineering costs constrain mid-volume converters.
- Containers:Rigid packaging formats utilize graphene-reinforced polyethylene and polypropylene for thermal conductivity and structural integrity in pharmaceutical dosage protection. US FDA notification pathways for food contact applications extend development timelines versus flexible alternatives, limiting near-term adoption to healthcare segments with higher margin tolerance.
- Bags:Pouch and sack formats deploy lower graphene loadings for cost-sensitive fresh-produce logistics.
- Labels:Adhesive-backed substrates integrate conductive traces for authentication and track-and-trace functionality.
Established volume favors Films; emerging adoption favors Containers.
End User:
Customer procurement sophistication determines specification tiering, with semiconductor logistics protocols and pharmaceutical barrier requirements commanding premium pricing over commodity food packaging.
- Food & Beverage:Brand owners prioritize antimicrobial films validated to ISO 22196 bacterial reduction standards for fresh-produce shelf-life extension. EU Green Deal packaging waste directives accelerate substitution toward biodegradable polymer matrices in Netherlands pilot programs, though conventional multilayer ethylene-vinyl alcohol films retain cost advantages at scale.
- Electronics:Semiconductor shipment protocols mandate electrostatic discharge shielding below 10³ ohms per square, displacing metallized films in South Korean and Taiwanese logistics hubs. Samsung and TSMC supplier qualification requirements concentrate demand among ISO-certified exfoliation providers with mine-to-masterbatch traceability.
- Pharmaceuticals:Dosage protection applications require US FDA food contact substance notifications for graphene-polyethylene composites.
- Consumer Goods:Cosmetics and personal care packaging utilizes lower barrier specifications with faster procurement cycles.
Electronics climbs the fastest on semiconductor supply chain reshoring; Food & Beverage maintains the deepest installed base.
Material:
Substrate chemistry dictates exfoliation method compatibility and dispersion stability, with polyolefins offering mature masterbatch infrastructure versus biodegradable polymers requiring novel compounding approaches.
- Polyethylene:Linear low-density and high-density grades dominate food contact applications with established FDA notification precedents. Global Graphene Group's Ohio-based production assets supply consistent masterbatch quality for North American converters, though REACH Article 7 nanomaterial registration extends European market entry timelines.
- Biodegradable Polymers:Polylactic acid and polyhydroxyalkanoate matrices align with EU Green Deal mandates for packaging waste reduction. EFSA novel food and material assessments create parallel compliance pathways that raise technical documentation burdens but accelerate transatlantic market access for qualified compounders.
- Polypropylene:Higher thermal stability suits hot-fill and retort applications with specialized grafting requirements.
- Paper:Cellulosic substrates enable fiber-based barrier coatings for premium positioning in Scandinavian markets.
Polyethylene commands current volume leadership; biodegradable polymers gain share fastest on regulatory tailwinds.
Application:
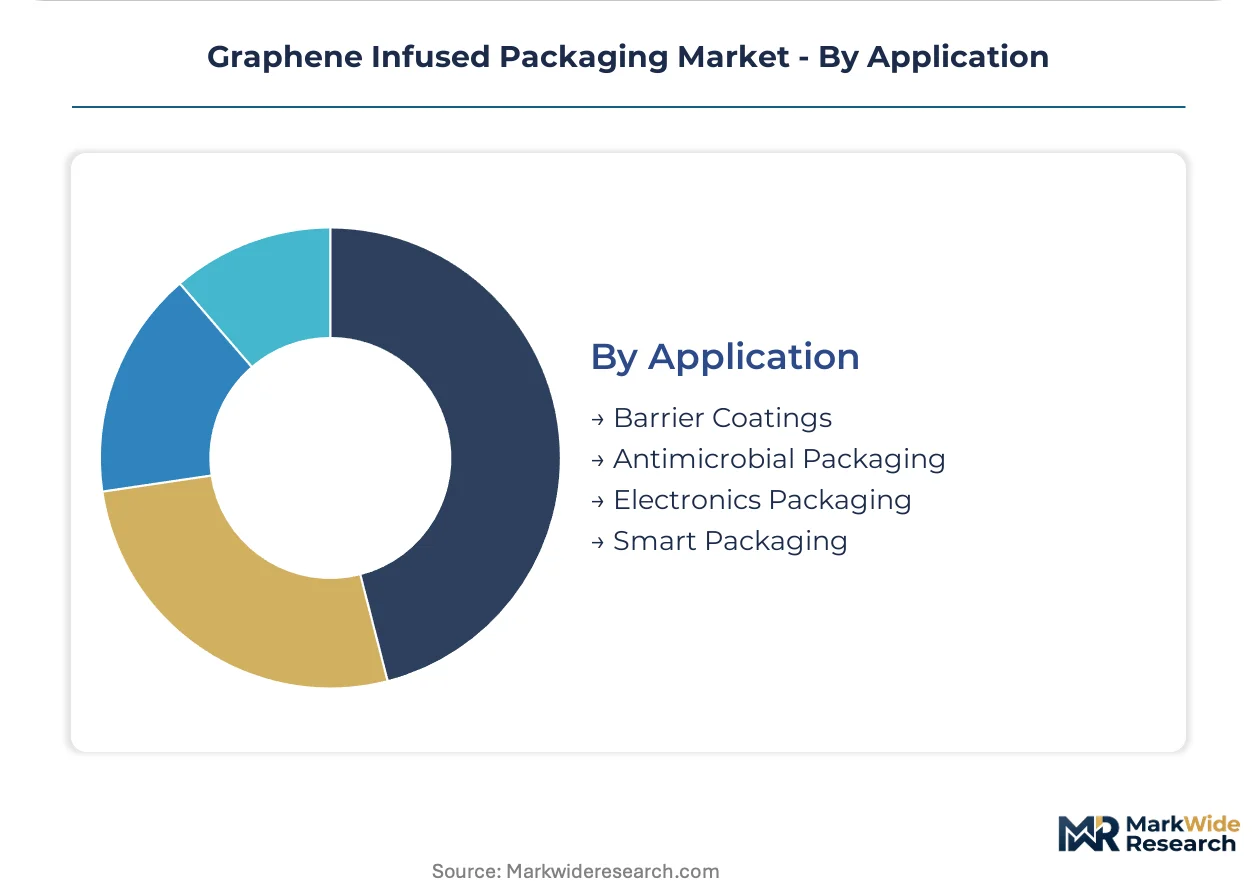
Functional performance requirements stratify pricing tiers, with passive barrier coatings competing on cost and active antimicrobial systems capturing margin through validated efficacy claims.
- Barrier Coatings:Oxygen and moisture barrier layers at sub-micron thickness displace conventional multilayer coextrusion for protein-based food protection. Xiamen Knano anchors East Asian electronics packaging channels with ISO-certified flake consistency, while NanoXplore's in-house exfoliation methods sustain pricing power in North American pharmaceutical applications.
- Antimicrobial Packaging:ISO 22196 bacterial reduction validation unlocks healthcare and fresh-produce procurement with documented shelf-life extension. OECD Test Guideline 318 toxicity data gaps create procurement uncertainty for multi-year flake supply agreements, favoring vertically integrated compounders with captive ecotoxicity documentation.
- Electronics Packaging:Electrostatic discharge and electromagnetic interference shielding specifications serve semiconductor logistics.
- Smart Packaging:Conductive and sensing functionalities integrate RFID and freshness indicators for authentication applications.
Barrier Coatings represent the largest addressable base; antimicrobial packaging shows the steepest expansion trajectory on healthcare validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for high-purity flake concentrates supply in China while Germany and the United States build domestic compounding capacity. Export flows of masterbatch from Ohio-based production assets serve North American converters. European compounders face 18-24 month ECHA registration timelines that advantage early REACH Article 7 filers.
Germany
Baden-Württemberg and Bavaria manufacturing corridors concentrate food safety regulator-driven demand for barrier-grade graphene composites. EU Green Deal packaging waste directives accelerate biodegradable polymer substitution mandates. Industrial packaging clusters in Stuttgart and Munich pilot oxygen transmission rates below 0.1 cc/m²/day for protein-based shelf-life extension.
United States
FDA food contact substance notifications govern graphene-polyethylene composites in distribution across food and pharmaceutical channels. Ohio-based production assets control raw material quality from mine to masterbatch for North American converters. Electronics packaging demand in Austin and Phoenix semiconductor corridors competes for capacity with barrier film applications.
China
SAMR GB standards for plastic food packaging create domestic compliance pathways separate from Western regulatory frameworks. Xiamen and Shenzhen anchor East Asian electronics packaging channels with ISO-certified flake consistency requirements. Yangtze River Delta compounders supply semiconductor logistics hubs in South Korea and Taiwan with electrostatic discharge shielding materials.
South Korea
Semiconductor shipment protocols mandate electrostatic discharge shielding below 10³ ohms per square for Samsung and TSMC supplier qualifications. MFDS pharmaceutical packaging regulations create parallel certification tracks for dosage protection applications. Busan-Ulsan logistics corridors displace metallized films with graphene-reinforced alternatives for chip export packaging.
India
PLI scheme incentives for advanced materials under the chemicals and petrochemicals mission reduce import duty exposure for packaging converters. Maharashtra and Gujarat industrial zones develop domestic graphene production to serve food and beverage brand owners. BIS standards for plastic food packaging align with FSSAI safety requirements for antimicrobial film validation.
Graphene Infused Packaging Market Competitive Landscape
Listed leaders compete with private specialists across exfoliation method control and masterbatch dispersion engineering. The vendor base stratifies between vertically integrated mine-to-masterbatch operators and compounders dependent on merchant flake supply. Three archetypes dominate: captive graphite asset holders, ISO-certified exfoliation specialists, and polymer rheology engineering boutiques. Capacity expansion and strategic partnerships constitute the dominant competitive moves as registration timelines lengthen in Europe.
Within the captive supply tier, Global Graphene Group anchors North American positioning through Ohio-based production assets. Xiamen Knano Graphene Technology Co. exemplifies the ISO-certified exfoliation specialist archetype serving East Asian electronics channels. NanoXplore Inc. occupies a position among North American compounders with in-house production methods for pharmaceutical barrier applications.
| Leading Market Players |
|---|
| Global Graphene Group |
| Xiamen Knano Graphene Technology Co. |
| NanoXplore Inc. |
| Directa Plus S.p.A |
| Grolltex Inc. |
| Universal Matter GBR Ltd |
| ACS Material |
| Thomas Swan & Co. Ltd. |
| Graphenea |
| Others |
Supply & Pricing Matrix
REACH Article 7 nanomaterial registration gates both European supply qualification and price differentiation simultaneously, as ECHA documentation burdens extend market entry timelines while concentrating premium pricing power among early filers with captive flake production.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in graphene infused packaging. Price differentiation hinges on ISO-certified exfoliation method documentation and mine-to-masterbatch traceability for semiconductor logistics buyers, while volume scale drives negotiation leverage for food and beverage converters. Cost compression in standard-grade barrier films is intensifying because conventional multilayer ethylene-vinyl alcohol alternatives retain cost advantages at scale. Fresh-produce logistics segments exhibit highest price sensitivity, whereas pharmaceutical barrier applications show least sensitivity due to FDA notification requirements and glass-aluminum displacement premiums.
Supply Chain Analysis
China and the United States anchor high-purity graphite mining and exfoliation capacity for graphene infused packaging supply. Masterbatch compounders in Germany and South Korea draw from Chinese flake feedstock while building domestic dispersion engineering capabilities. Single-source vulnerability concentrates in Yangtze River Delta mining clusters subject to export licensing variability. Distribution runs through qualified converter networks in Baden-Württemberg, Ohio, and Busan-Ulsan corridors with ISO-certified handling protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical audit and certification services represent a service-attach opportunity expanding faster than hardware, as brand owners now require documented flake provenance and ecotoxicity compliance alongside physical product delivery.
For Market Incumbents: Fortify backward integration into captive graphite assets to offset import dependency risks from Chinese flake concentration. Deepen ISO 22196 bacterial reduction certification investment to defend margin position against emerging biodegradable polymer compounders with novel dispersion methods. Priority lever rests on controlling exfoliation method documentation demanded by Samsung and TSMC supplier qualification protocols. For New Entrants and Emerging Players: Anchor in India's PLI scheme incentives for domestic graphene production under the chemicals and petrochemicals mission. Target Maharashtra and Gujarat industrial zones serving food and beverage brand owners with antimicrobial film validation gaps. Go-to-market angle emphasizes BIS standards alignment with FSSAI safety requirements for faster procurement cycles than import-dependent competitors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across masterbatch dispersion engineering boutiques with in-house ecotoxicity documentation capabilities. Five-to-ten year viability favors vertically integrated mine-to-masterbatch operators with early REACH Article 7 filing status. Acquisition target archetype includes ISO-certified exfoliation specialists with established semiconductor channel relationships. Signal to watch is OECD Test Guideline 318 toxicity data completion rates among flake suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphite Assets | Captive mining and exfoliation capacity insulates compounders from Chinese export licensing volatility. |
| ISO 22196 Certification Investment | Antimicrobial validation unlocks healthcare and fresh-produce procurement with documented shelf-life extension claims. |
| EFSA Novel Material Assessment Filing | Early European compliance accelerates transatlantic market access ahead of REACH Article 7 registration backlogs. |
| Semiconductor Channel Qualification | Samsung and TSMC supplier protocols concentrate demand among traceability-documented exfoliation providers. |
| Biodegradable Polymer Masterbatch Development | EU Green Deal packaging waste directives accelerate substitution mandates for polylactic acid and polyhydroxyalkanoate matrices. |
Research Methodology
The analysis maps barrier-grade films, antimicrobial packaging, and electronics shielding substrates, each validated through compounder technical directors, brand-owner packaging engineers, and regulatory affairs specialists. Primary interviews with FDA notification consultants, EFSA material assessors, and semiconductor logistics procurement managers combined with secondary validation from SAMR GB standards filings, ECHA registration databases, and SEC 10-K supply chain disclosures. Bottom-up volume builds from qualified converter capacity and top-down cross-checks against trade flow data enable triangulation.
Consistency checks against customs records and industrial cluster production surveys validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product format, end-use industry, substrate chemistry, and functional application tier. CAGRs derived from annualized growth rate analysis across material adoption curves and regulatory approval timelines. Industry-specific forecast inputs incorporate EU Green Deal implementation pace and semiconductor reshoring investment flows.
Underlying assumptions cover biodegradable polymer substitution rates and flake supply concentration stability, with deviation risk concentrated in OECD Test Guideline 318 toxicity data requirements and REACH enforcement intensity. Recalibration cycles align with material shifts in EU packaging waste directive implementation and SAMR GB standards revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
PET Strap Market
Packaging Materials
Lidding Foil Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Non-Breathable Films Market
Packaging Materials
Stick Packaging Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Cargo Moisture Control Products Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Europe Airless Packaging Market