
 United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market | 2026-2036
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market Analytics
Food service is recalibrating the UAE disposables landscape as hotel chains and cloud kitchens expand their procurement of single-use tableware. Hotpack Packaging LLC leverages its manufacturing scale across the Gulf to supply rigid containers and cups to quick-service restaurants. Al Bayader International LLC anchors the premium segment through specialized product lines for hospitality clients. Falcon Pack Industries LLC differentiates via channel control in the northern emirates, where it operates extensive distribution networks for flexible packaging formats.
Disposables (single-use) packaging encompasses containers, plates, cups, cutlery, and wraps engineered from plastic resins, paperboard, biodegradable polymers, or expanded polystyrene foam, manufactured through thermoforming, injection molding, or extrusion processes to provide sanitary, cost-efficient food and goods containment for one-time use. The food service end-user segment leads volume consumption across the Emirates, driven by tourism-driven catering and delivery-platform growth, while biodegradable material categories are expanding fastest as operators respond to evolving disposal regulations and corporate sustainability mandates. Rigid packaging types command stronger margin pools due to higher barrier specifications and customization requirements for hot-food applications.
MOHAP governs food-contact safety standards for disposable packaging materials across the UAE, while municipal waste authorities in Dubai and Abu Dhabi enforce segregation and landfill diversion protocols that shape product specifications. The Emirates Authority for Standardization and Metrology (ESMA) implements conformity assessment schemes that control market access for imported and locally manufactured single-use items. Stakeholders must monitor how federal sustainability commitments and emirate-level plastic reduction timelines will reshape material specifications and supplier qualification criteria.
Market Dynamics
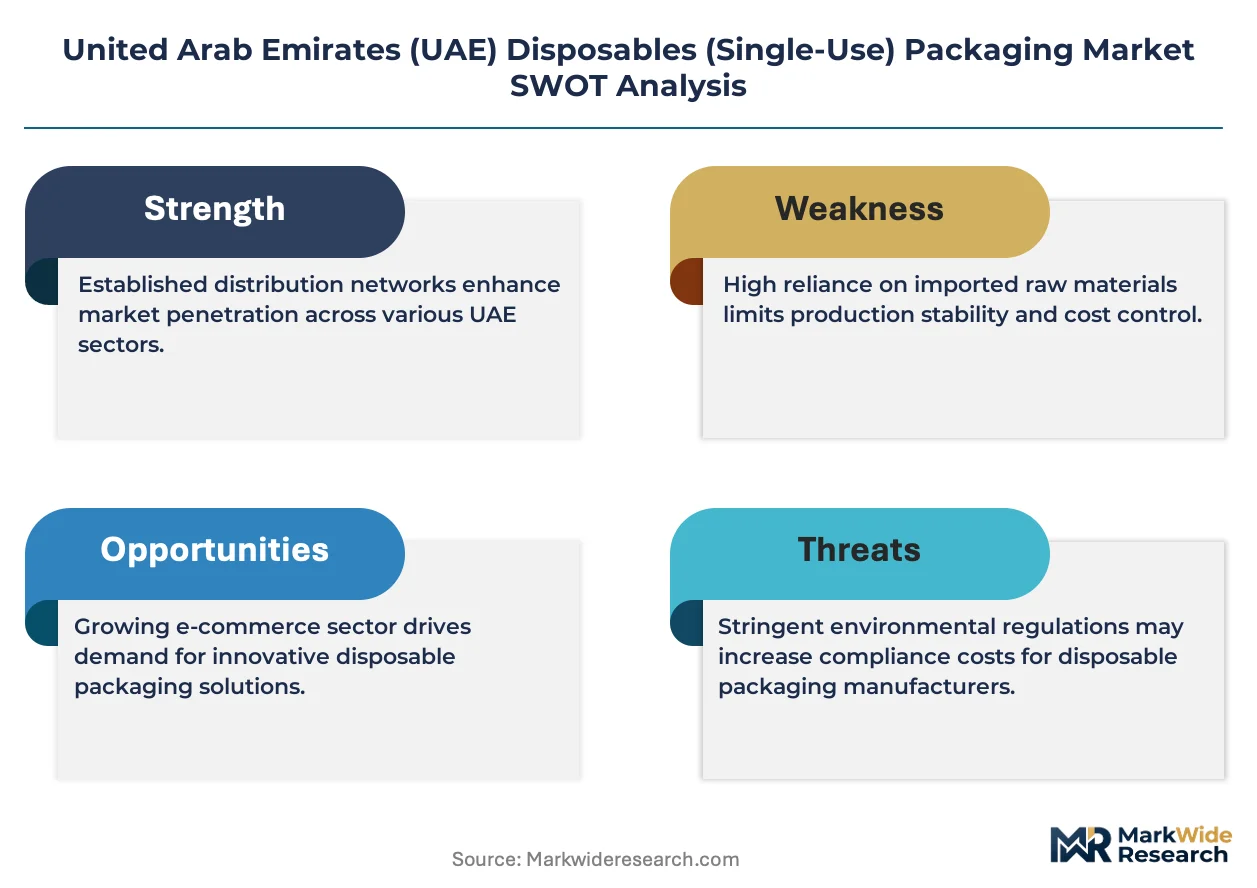
MOHAP's tightening food-contact material rules are compressing supplier qualification timelines across Dubai and Abu Dhabi, forcing food service operators to accelerate biodegradability certifications while reconfiguring procurement contracts around compostable specifications.
Growth Catalysts
- Emirate-level plastic reduction mandates:Dubai and Abu Dhabi municipal waste authorities are enforcing landfill diversion protocols that specify compostable packaging for hospitality procurement, creating immediate demand pull from hotel chains and catering operators.
- Cloud kitchen expansion:Delivery-platform growth across Sharjah and Ras Al Khaimah is generating volume consumption of rigid containers engineered for hot-food barrier performance, with operators prioritizing single-use solutions over reusable alternatives for hygiene assurance.
- Tourism-driven catering volume:Dubai's hospitality corridor is experiencing concentrated procurement of disposable tableware sets as international visitor arrivals sustain elevated food service throughput, particularly in beachfront and downtown hotel clusters.
Market Restraints
- Biodegradable polymer input cost volatility:PLA and bagasse feedstock prices fluctuate with agricultural commodity cycles, compressing margin pools for converters serving price-sensitive quick-service restaurant segments in the northern emirates.
- Import dependency for specialty resins:Local manufacturing capacity for food-grade biodegradable polymers remains concentrated in European and Asian supply bases, exposing UAE converters to freight cost spikes and extended lead times.
- Technical limitation in high-heat applications:Current compostable materials exhibit barrier degradation above 85°C, restricting penetration into hot-oil food categories and maintaining EPS foam incumbent positions in specific quick-service formats.
Strategic Opportunities
- Ras Al Khaimah industrial zone expansion:Underpenetrated northern emirate geographies present white space for localized thermoforming operations serving hospitality developments along the emirate's coastal tourism corridor.
- ESMA conformity assessment streamlining:Federal standardization reforms are reducing certification timelines for imported biodegradable packaging, enabling faster market access for innovative material formulations from Asian manufacturing bases.
- Quick-commerce channel integration:Dark store and micro-fulfillment center networks are creating dedicated packaging specification requirements, opening direct supplier relationships bypassing traditional food service distributor intermediaries.
Industry Challenges
- Composting infrastructure coordination gap:Industrial composting facility availability lags behind packaging biodegradability certification, creating disposal pathway uncertainty that complicates operator sustainability claims and customer communication.
- Food-contact safety testing backlog:MOHAP laboratory capacity constraints are extending migration testing timelines for novel biodegradable formulations, delaying product launches and compressing commercialization windows for material innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market |
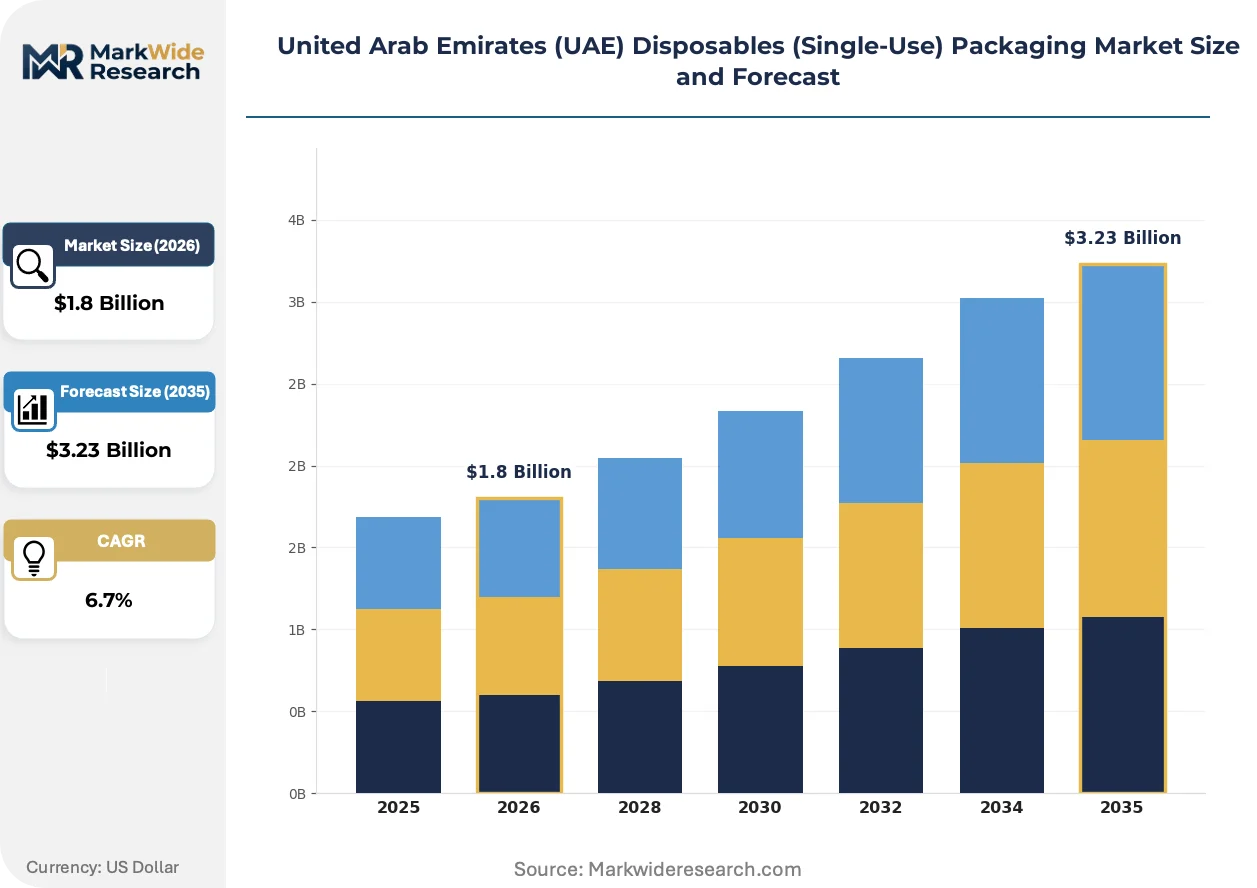
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Cups, Cutlery, Containers Material: Plastic, Paper, Biodegradable, Foam End User: Food Service, Healthcare, Retail, Event Management Packaging Type: Flexible, Rigid, Clamshell, Tray |
| Companies Covered | Jebel Pack LLC, Hotpack Packaging LLC, Al Bayader International LLC, Falcon Pack Industries LLC, Detpak (Detmold Group) Pty Ltd, Precision Plastic Products Co. LLC, Gulf East Paper and Plastic Industries LLC, International Food Services (IFS), Huhtamaki Oyj, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market Evolving Landscape
Material science advances and regulatory compression are converging to restructure competitive advantage around certification speed and composting infrastructure alignment rather than traditional scale economies.
Thermoforming equipment is modularizing production setups for biodegradable polymers, enabling mid-scale converters to switch between PLA, bagasse, and emerging seaweed-based formulations with minimal retooling downtime. Hotel procurement teams in Dubai are piloting multi-material container programs that match substrate selection to food temperature and moisture profiles. This flexibility is compressing minimum order quantities and enabling smaller hospitality groups to access customized biodegradable specifications previously reserved for multinational chains.
ESMA's updated conformity assessment schemes for single-use food contact materials are mandating enhanced migration testing documentation for imported biodegradable products. The industrial consequence is a filtering effect favoring suppliers with established UAE testing relationships and local representative offices. Quick-service restaurant chains are responding by consolidating supplier bases around converters with demonstrated ESMA approval track records, reducing vendor counts by approximately half in recent procurement cycles.
Cloud kitchen operators are consolidating purchasing through specialized food service platforms that bundle packaging with ingredient and equipment procurement. This channel consolidation is displacing traditional distributor relationships in Abu Dhabi's delivery-dense zones, with platform-specific packaging specifications becoming de facto standards for affiliated kitchen facilities. The shift is most visible in Dubai's Al Quoz industrial zone, where dark store density has concentrated demand for standardized container formats optimized for platform branding and thermal retention performance.
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market Segmentation
UAE disposables packaging procurement fragments across material certifications, temperature performance requirements, and end-use compliance protocols. Each segmentation dimension carries distinct margin structures and regulatory qualification timelines that reshape supplier positioning.
Product Type:
Supply concentration in rigid formats favors converters with thermoforming scale across Dubai's industrial corridors.
- Plates:Flat-bottomed dishware engineered from bagasse or molded fiber for dine-in hospitality and catering buffet lines. Dubai hotel procurement teams specify plate diameters and rim strengths for outdoor beachfront service where wind resistance matters.
- Cups:Cylindrical containers with rolled rims for hot and cold beverage service, ranging from 4-ounce espresso formats to 32-ounce smoothie vessels. Abu Dhabi's quick-service coffee chains drive cup specification innovation around lid interoperability and stack density for delivery optimization.
- Cutlery:Single-use utensils including forks, knives, spoons, and sporks manufactured through injection molding or pressed fiber processes. Northern emirate cloud kitchens prioritize lightweight cutlery kits with napkin integration to reduce per-order packaging weight.
- Containers:Lidded vessels for prepared food transport, spanning round bowls to rectangular meal-prep formats. MOHAP's food-contact migration testing requirements create qualification bottlenecks for container importers serving Sharjah's food manufacturing sector.
Today's leader: Containers. Tomorrow's challenger: Cups.
Material:
Cost tier stratification separates premium biodegradable certifications from commodity resin grades.
- Plastic:Polypropylene and PET resins dominate rigid applications requiring clarity and microwave tolerance. Dubai Municipality's plastic reduction mandates are compressing conventional polymer procurement windows for hospitality operators.
- Paper:Bleached and unbleached kraft stocks with polyethylene or PLA barrier coatings for moisture resistance. Paperboard cup demand concentrates in Abu Dhabi's corporate catering sector where print branding compatibility drives specification.
- Biodegradable:PLA, bagasse, and emerging seaweed-based polymers certified for industrial composting. Ras Al Khaimah's coastal tourism developments specify biodegradable tableware for beachfront dining venues aligning with emirate sustainability positioning.
- Foam:Expanded polystyrene retains position in high-volume, price-sensitive quick-service formats despite environmental pressure. Technical performance in hot-oil food containment above 85°C sustains EPS incumbent status in specific fried-food categories.
Biodegradable materials are gaining share fastest. Foam holds residual volume in cost-constrained segments.
End User:
Application intensity varies sharply across hygiene protocols and consumption velocity.
- Food Service:Restaurants, hotels, catering operators, and cloud kitchens consuming the majority of UAE disposables volume. Dubai's hospitality corridor procurement teams specify compostable sets for international visitor-facing operations.
- Healthcare:Hospitals and clinics utilizing sterile single-use packaging for patient meals and medical supply containment. MOHAP infection control standards mandate specific barrier properties for healthcare food-contact applications.
- Retail:Supermarkets and convenience stores offering prepared food and grab-and-go packaging solutions. Retail private-label packaging specifications increasingly mirror food service biodegradability requirements.
- Event Management:Temporary catering infrastructure for exhibitions, weddings, and corporate functions. Event operators in Abu Dhabi's exhibition district prioritize lightweight, stackable formats for rapid deployment and breakdown logistics.
Food service commands current volume leadership. Healthcare offers margin expansion through certification premiums.
Packaging Type:
Volume throughput and barrier performance requirements segment converter capabilities.
- Flexible:Films, wraps, and pouches for lightweight containment with minimal material usage. Flexible formats serve Sharjah's food manufacturing sector for secondary packaging of bulk ingredients.
- Rigid:Thermoformed and injection-molded containers with structural integrity for stackability and thermal retention. Rigid packaging carries stronger margin pools due to customization complexity for hot-food applications.
- Clamshell:Hinged-lid containers for sandwich, salad, and combo meal presentation. Clamshell demand concentrates in Dubai's dark store networks where platform-specific branding requirements drive specification.
- Tray:Open or lidded platforms for compartmentalized meal service and buffet presentation. Hotel catering procurement in Abu Dhabi specifies tray formats with lid compatibility for room service and event applications.
Rigid formats anchor supplier revenue. Clamshell configurations are expanding most quickly through delivery-platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns across the Gulf Cooperation Council reflect divergent compliance cost structures, with UAE-based converters capturing premium hospitality contracts while manufacturers in lower-regulation jurisdictions supply commodity-grade disposables for price-sensitive segments.
Dubai
Dubai's hospitality corridor drives concentrated demand for certified compostable tableware, with hotel procurement teams specifying MOHAP-compliant containers for beachfront and downtown venues. Dubai Municipality enforces landfill diversion protocols that mandate biodegradable packaging for government-catered events. Industrial clusters in Al Quoz and Jebel Ali host thermoforming operations serving cloud kitchen networks and dark store fulfillment centers.
Abu Dhabi
Abu Dhabi's quick-service restaurant chains generate volume consumption of rigid containers engineered for hot-food barrier performance, with operators prioritizing single-use solutions for delivery-platform hygiene assurance. The emirate's waste management authority implements segregation requirements that shape supplier qualification criteria. Yas Island and Saadiyat Island tourism developments concentrate procurement of premium disposable sets for international visitor-facing operations.
Sharjah
Sharjah's food manufacturing sector consumes flexible packaging formats for secondary containment of bulk ingredients, with processors navigating ESMA conformity assessment timelines for imported biodegradable films. The emirate's industrial zones attract mid-scale converters seeking lower operational costs than Dubai or Abu Dhabi. Hamriyah Free Zone hosts distribution networks serving northern emirate cloud kitchen expansion.
Ras Al Khaimah
Ras Al Khaimah's coastal tourism corridor presents white space for localized thermoforming operations, with hospitality developers specifying biodegradable tableware to align with emirate sustainability positioning. The emirate's waste authority lags Dubai and Abu Dhabi in composting infrastructure deployment. Al Marjan Island and Mina Al Arab developments concentrate demand for outdoor dining-optimized disposable specifications.
Northern Emirates
Ajman, Umm Al Quwain, and Fujairah collectively represent underpenetrated geographies where price-sensitive quick-service formats sustain conventional polymer procurement. Municipal waste regulations in these emirates remain less prescriptive than Dubai or Abu Dhabi counterparts. Fujairah's port infrastructure supports import-dependent supply chains for specialty resins serving converters across the northern tier.
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospitality-facing operators consolidating procurement around converters with demonstrated ESMA approval track records while commodity segments fragment across import-dependent distributors. Three archetypes dominate: Gulf-based integrated manufacturers with thermoforming scale, international specialists leveraging global material science capabilities, and regional distributors controlling channel access in underpenetrated emirates. Capacity expansion and certification speed represent the dominant competitive moves, as MOHAP testing backlogs compress commercialization windows for material innovators.
Among UAE-based fabricators, Hotpack Packaging LLC, Al Bayader International LLC, and Falcon Pack Industries LLC occupy positions across distinct market tiers. Hotpack exemplifies scale-driven manufacturing with Gulf-wide distribution infrastructure. Al Bayader represents premium-segment specialization through hospitality-focused product positioning. Falcon Pack anchors channel control archetypes in northern emirate geographies where extensive distribution networks for flexible formats create defensive positioning.
| Leading Market Players |
|---|
| Jebel Pack LLC |
| Hotpack Packaging LLC |
| Al Bayader International LLC |
| Falcon Pack Industries LLC |
| Detpak (Detmold Group) Pty Ltd |
| Precision Plastic Products Co. LLC |
| Gulf East Paper and Plastic Industries LLC |
| International Food Services (IFS) |
| Huhtamaki Oyj |
| Others |
Value Network & Pricing Analysis
Dubai's hotel procurement teams and cloud kitchen operators concentrate purchasing power, forcing a contract-based pricing model where volume commitments secure preferential rates for biodegradable certifications. This buyer consolidation enables tiered pricing stratification across premium hospitality, standard food service, and economy quick-service segments.
Pricing Analysis
Distributor margins of 15-25% separate converter ex-works pricing from end-user landed costs across the Emirates. Price differentiation hinges on MOHAP certification tier and customization level for hot-food barrier performance. Cost compression in the economy segment is intensifying because bagasse and PLA feedstock volatility squeezes converter margins serving northern emirate quick-service chains. Quick-service restaurant operators exhibit highest price sensitivity, while Dubai hotel procurement teams accept premium positioning for compostable tableware aligned with corporate sustainability mandates.
Supply Chain Analysis
Freight costs from European and Asian specialty resin suppliers add 12-18% to landed input costs for UAE converters. Manufacturing capacity for food-grade biodegradable polymers draws from Germany, Thailand, and China, with local thermoforming operations concentrated in Dubai's Al Quoz and Jebel Ali industrial zones. Single-source vulnerability persists for PLA resin grades certified to ESMA migration testing standards. Distribution runs through food service platforms and traditional hospitality distributors serving emirate-level procurement clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE disposables packaging market functions as a stable compounder, with emirate-level plastic reduction mandates and tourism-driven food service throughput delivering predictable demand expansion across the forecast window.
For Market Incumbents: Extend certification capabilities to capture MOHAP testing backlog advantages, accelerating biodegradability approvals ahead of smaller competitors. Deepen backward integration into bagasse and PLA compounding operations to offset agricultural commodity price volatility threatening margin pools in quick-service segments. Channel control investments in Ras Al Khaimah and Sharjah distribution networks defend against platform-driven disintermediation. For New Entrants and Emerging Players: Seaweed-based polymer formulations offer a technology-first wedge into Dubai's premium hospitality procurement, where beachfront venues seek differentiated sustainability credentials beyond conventional PLA. Target Ras Al Khaimah's coastal tourism corridor as the most penetrable geography, with localized thermoforming operations serving under-supplied hospitality developments. Partner with quick-commerce platforms for direct dark store relationships bypassing established distributor intermediaries. For Investors and Strategic Acquirers: Gulf-based food service conglomerates are the most active acquirer in this space, consolidating converter assets to secure captive packaging supply for expanding cloud kitchen networks. The market supports 5-10 year holding periods given regulatory tailwinds and infrastructure buildout requirements. Target mid-scale converters with demonstrated ESMA approval track records and established MOHAP laboratory relationships. Monitor industrial composting facility deployment timelines across Dubai and Abu Dhabi as the critical inflection signal for biodegradable packaging demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Certification Acceleration | Fast-tracked food-contact approvals compress competitor commercialization windows for novel biodegradable formulations. |
| Backward Integration into Biopolymer Compounding | In-house PLA and bagasse processing reduces exposure to agricultural commodity price cycles squeezing converter margins. |
| Quick-Commerce Platform Partnership | Direct dark store relationships displace traditional distributors in Abu Dhabi's delivery-dense zones. |
| Ras Al Khaimah Manufacturing Footprint | Localized thermoforming captures coastal tourism corridor demand for beachfront-optimized biodegradable specifications. |
| Industrial Composting Infrastructure Alignment | Partnerships with emirate waste authorities close disposal pathway gaps complicating operator sustainability claims. |
Research Methodology
Multiple input streams — primary interviews with packaging procurement managers, converter operations directors, and MOHAP regulatory affairs specialists; secondary validation through ESMA conformity assessment databases, Dubai Municipality waste authority filings, and hospitality sector procurement disclosures — were reconciled using bottom-up volume triangulation against top-down market sizing. Trade data from UAE customs authorities and Gulf Cooperation Council industrial production indices provided cross-reference benchmarks.
Historical volume trajectories were cross-referenced against panel input from thermoforming equipment suppliers and biodegradable resin distributors to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include material certification tier, temperature performance specification, end-use application intensity, and emirate-level regulatory compliance cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating tourism arrival patterns and cloud kitchen network expansion rates.
The model holds under sustained emirate-level enforcement of landfill diversion protocols; deviation in industrial composting facility deployment timelines or MOHAP testing capacity expansion would shift biodegradable material adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Construction Films Market
Packaging Materials
Disposable Icepacks Market
Packaging Materials
Single-Use Packaging Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Lidding Foil Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Expendable Packaging Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Stick Packaging Market
Packaging Materials
Global Thin Wall Packaging Market