
 Child Resistant Packaging Market | 2026-2036
Child Resistant Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Child Resistant Packaging Market Analysis
Pharmaceutical buyer consolidation is realigning procurement leverage toward large drug manufacturers with centralized packaging specifications. Amcor plc leverages its global converting footprint to serve consolidated pharma accounts with certified child-resistant formats. AptarGroup specializes in precision closure engineering for compliance-critical applications. Berry Global Group anchors North American supply through integrated resin-to-finish manufacturing.
Child resistant packaging denotes engineered containers and closures requiring adult dexterity to access contents while resisting manipulation by children under five years, typically incorporating dual-action mechanisms, torque thresholds, or cognitive barriers tested against ASTM D3475 and ISO 8317 protocols. Plastic containers dominate volume due to cost scalability and design flexibility, while flexible pouches represent the fastest-growing format as cannabis and nutraceutical brands seek differentiated shelf presence. Closure type segmentation concentrates margin pools in child-resistant caps and double-lock configurations where patent-protected designs command tooling premiums.
The US Consumer Product Safety Commission enforces Poison Prevention Packaging Act compliance through testing protocols that create barrier-to-entry for uncertified suppliers. EMA and FDA alignment on pediatric safety labeling reinforces demand for validated packaging across transatlantic pharmaceutical supply chains. Stakeholders must monitor evolving state-level cannabis packaging rules and material restriction proposals under REACH and state environmental mandates that could force resin transitions ahead of specification cycles.
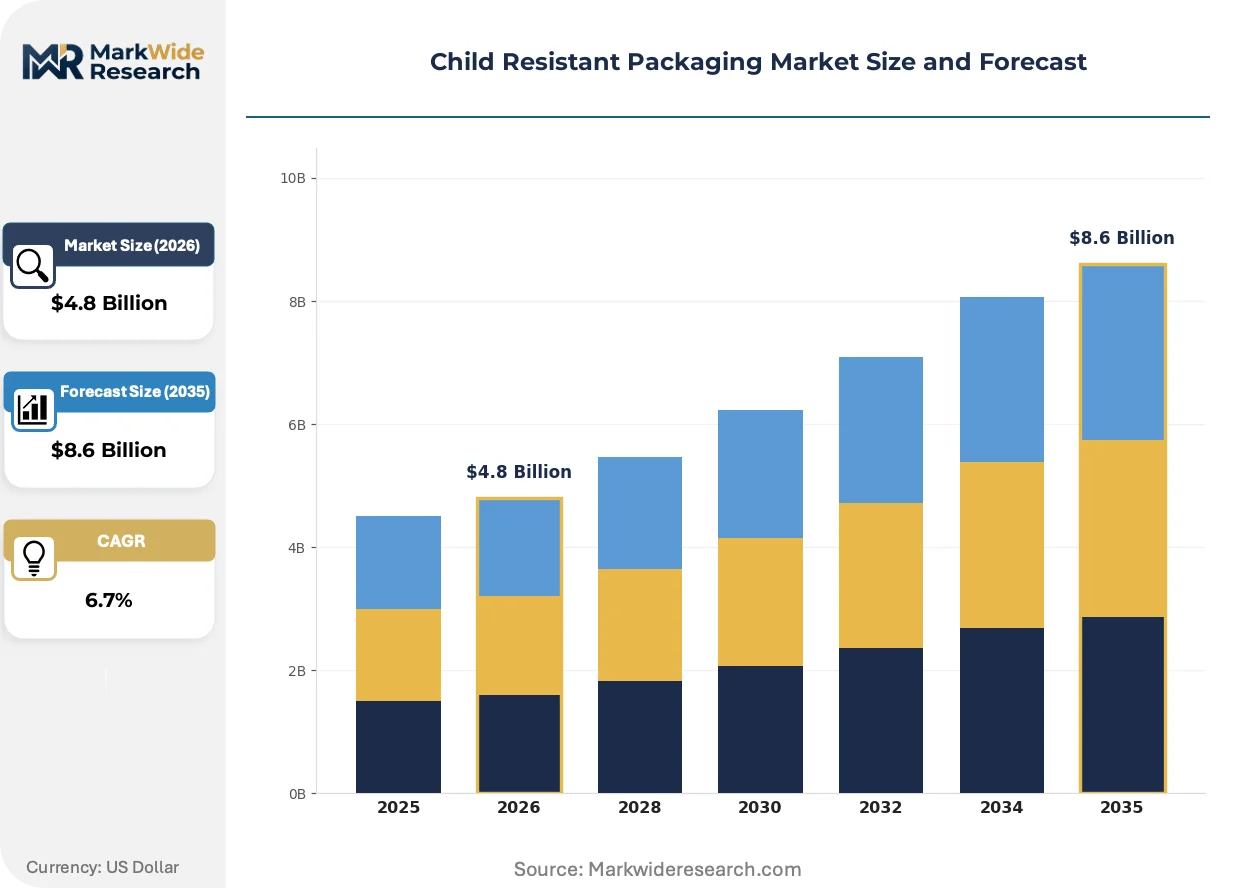
Market Dynamics
Pharmaceutical buyer consolidation is compressing supplier margins while elevating certification requirements, forcing converters to absorb compliance costs upfront or exit validated supply chains entirely.
Growth Catalysts
- US Poison Prevention Packaging Act enforcement:FDA-aligned testing protocols mandate certified closures for prescription and over-the-counter medications, eliminating uncertified competitors from pharmaceutical supply chains.
- Cannabis legalization waves:State-level dispensary regulations in multiple US jurisdictions require child-resistant formats for edibles and concentrates, opening incremental volume pools beyond traditional pharma.
- Flexible pouch adoption:Nutraceutical brands seeking shelf differentiation are converting from rigid bottles to child-resistant flexible formats, expanding addressable substrate demand.
Market Restraints
- Resin price volatility:Polypropylene and polyethylene feedstock fluctuations compress converter margins on fixed-price pharmaceutical contracts with annual renegotiation cycles.
- Certification concentration risk:Only three US laboratories hold CPSC-recognized testing status for ASTM D3475 protocols, creating bottlenecks during product launch windows.
- Technical limitation of flexible barriers:Multi-layer films struggle to achieve consistent torque thresholds across temperature ranges, limiting cold-chain pharmaceutical applications.
Strategic Opportunities
- Emerging cannabis markets:Germany's phased legalization under BfArM oversight creates demand for EU-compliant child-resistant formats in Europe's largest economy.
- Technology convergence:Smart packaging integrating NFC authentication with mechanical child-resistance is commanding premium positioning in high-value pharmaceutical segments.
- Direct-to-patient distribution:Mail-order pharmacy growth is reshaping packaging specifications toward ship-ready child-resistant formats that eliminate secondary overbox requirements.
Industry Challenges
- Tooling capex intensity:Multi-cavity injection molds for certified closures require six-figure capital commitments with 18-month payback horizons, straining mid-tier converters.
- IP licensing complexity:Patent-protected dual-action mechanisms from closure specialists impose per-unit royalties that erode margin on high-volume generic drug contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child Resistant Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Containers, Glass Bottles, Metal Cans, Flexible Pouches End User: Pharmaceutical Companies, Food Manufacturers, Chemical Industries, Cannabis Producers Material: Polyethylene, Polypropylene, Aluminum, Glass Closure Type: Child-Resistant Caps, Push Down Caps, Screw Caps, Double-Lock Closures |
| Companies Covered | AptarGroup, Constantia Flexibles, Berry Global Group, Mold-Rite Plastics, Winpak Ltd, Amcor plc, WestRock Company, Origin Pharma Packaging, Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child Resistant Packaging Market Emerging Trajectories
Material science advances and regulatory harmonization pressures are compressing development cycles while fragmenting specification requirements across end-use verticals.
Modular closure systems combining standardized base components with application-specific inserts are modularizing pharmaceutical packaging lines. Generic drug manufacturers facing SKU proliferation are adopting these platforms to reduce changeover downtime without sacrificing ASTM D3475 compliance. The approach is modularizing converter business models toward component supply rather than finished assembly.
REACH candidate list expansions targeting phthalates and bisphenol derivatives are forcing resin transitions ahead of specification cycles for European pharmaceutical suppliers. ECHA's SVHC notification requirements are accelerating substitution of legacy PVC blister formats toward PP and PET alternatives. Pediatric formulation specialists are responding with accelerated stability testing protocols to validate material switches.
Centralized procurement by pharmacy benefit managers is consolidating specification authority toward three national US buyers. Regional contract packagers are losing direct supplier relationships as PBMs mandate pre-approved vendor lists with certified child-resistant formats. The concentration is most visible in mail-order fulfillment operations serving Medicare Part D populations.
Child Resistant Packaging Market Segmentation
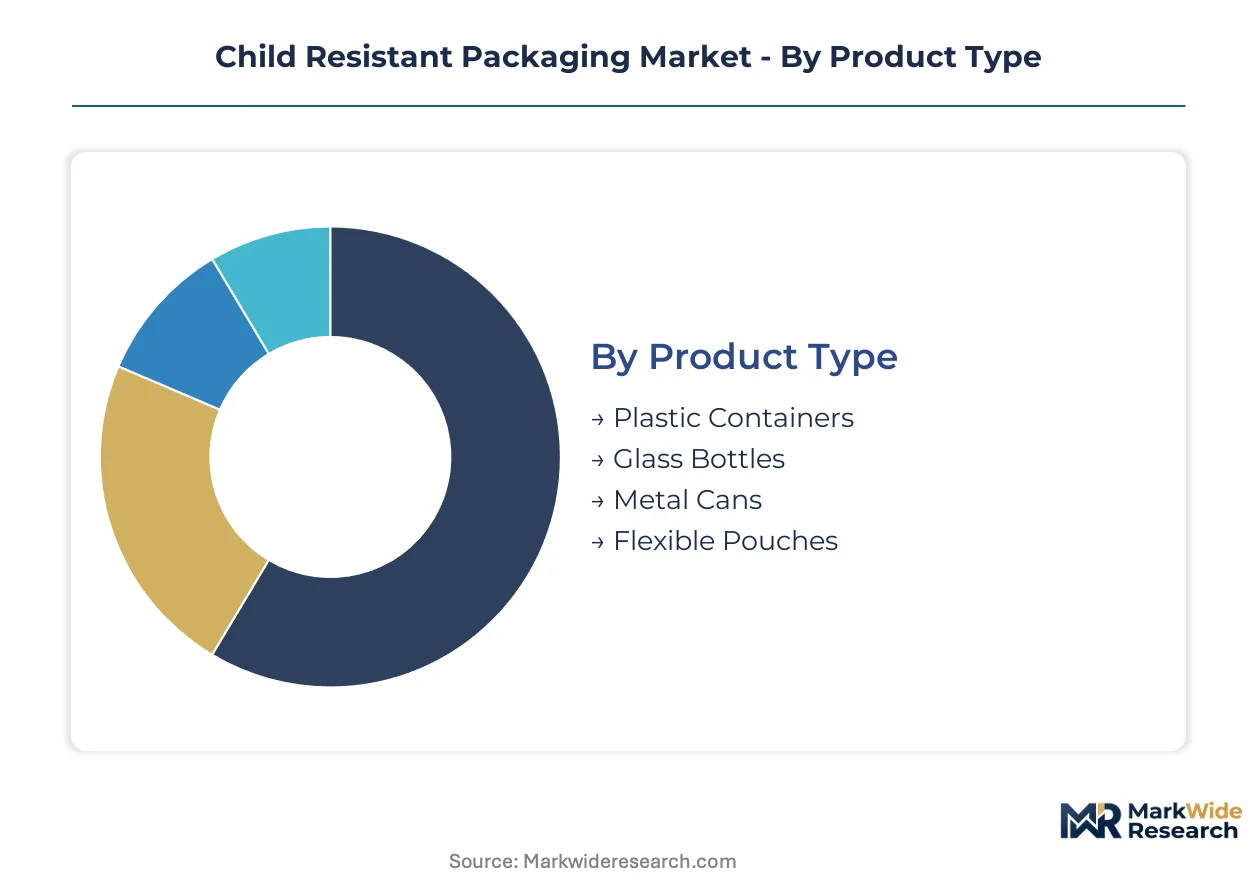
Child resistant packaging specifications diverge sharply across end-use verticals, with pharmaceutical applications demanding ASTM D3475 certification while cannabis and chemical segments navigate evolving state-level mandates. Understanding these segmentation boundaries clarifies where compliance investments concentrate and which substrate-conversion combinations unlock margin expansion.
Product Type:
Certification burden varies by structural rigidity, with rigid formats requiring torque-based ASTM validation and flexible formats pursuing alternative protocol recognition.
- Plastic Containers:Injection-molded HDPE and PP vessels dominate prescription pharmaceutical volume due to cost scalability and established CPSC testing pathways. Demand concentrates in North American mail-order pharmacy fulfillment, where shippable rigidity reduces secondary packaging costs.
- Flexible Pouches:Multi-layer barrier films with heat-sealed child-resistant zippers are expanding most quickly in cannabis edibles and nutraceuticals, though cold-chain torque consistency remains a technical constraint for pharmaceutical adoption.
- Glass Bottles:Amber and cobalt glass formats serve light-sensitive pediatric formulations requiring inert contact surfaces.
- Metal Cans:Tinplate and aluminum formats persist in solvent and adhesive chemical applications where permeation resistance outweighs premium pricing.
Plastic containers sit at the top of the volume ranking, with flexible pouches climbing the fastest.
End User:
Procurement authority is consolidating toward centralized buyers with pre-approved vendor lists and certified format requirements.
- Pharmaceutical Companies:Prescription and OTC drug manufacturers represent the certification anchor, with FDA-aligned testing eliminating uncertified suppliers from contracted supply chains.
- Cannabis Producers:State-dispensary regulations in multiple US jurisdictions mandate child-resistant formats for edibles and concentrates, creating incremental volume pools with fragmented specification requirements.
- Food Manufacturers:Nutraceutical and supplement brands seeking shelf differentiation are adopting child-resistant flexible formats for gummy and powder products.
- Chemical Industries:Household cleaner and solvent producers face OSHA and CPSC dual compliance, with concentrated formulations driving closure torque specifications.
Pharmaceutical companies command the largest procurement scale, while cannabis producers are gaining share fastest as legalization expands.
Material:
Resin selection determines REACH compliance trajectory and stability testing burden for European pharmaceutical submissions.
- Polyethylene:HDPE dominates pharmaceutical bottle production due to moisture barrier properties and established regulatory filing databases.
- Polypropylene:Clarified PP formats serve OTC visibility requirements, though ECHA SVHC notifications are accelerating substitution timelines away from legacy additives.
- Aluminum:Lightweight metal formats persist in aerosol and pressurized chemical applications.
- Glass:Type III borosilicate and soda-lime formats anchor parenteral and high-value oral solid dose packaging.
Polyethylene holds the volume lead, with polypropylene facing the steepest substitution pressure from regulatory expansion.
Closure Type:
Patent-protected dual-action mechanisms impose per-unit royalties that reshape margin structures on high-volume generic drug contracts.
- Child-Resistant Caps:Standardized push-and-turn formats capture the majority of pharmaceutical volume, with tooling amortization across billion-unit annual production runs.
- Double-Lock Closures:Patent-protected designs combining squeeze-and-lift with torque resistance command premium positioning in compliance-critical applications.
- Push Down Caps:Single-action formats serve cost-sensitive OTC segments with reduced dexterity requirements.
- Screw Caps:Conventional threaded closures persist in chemical and industrial applications where child resistance is secondary to sealing integrity.
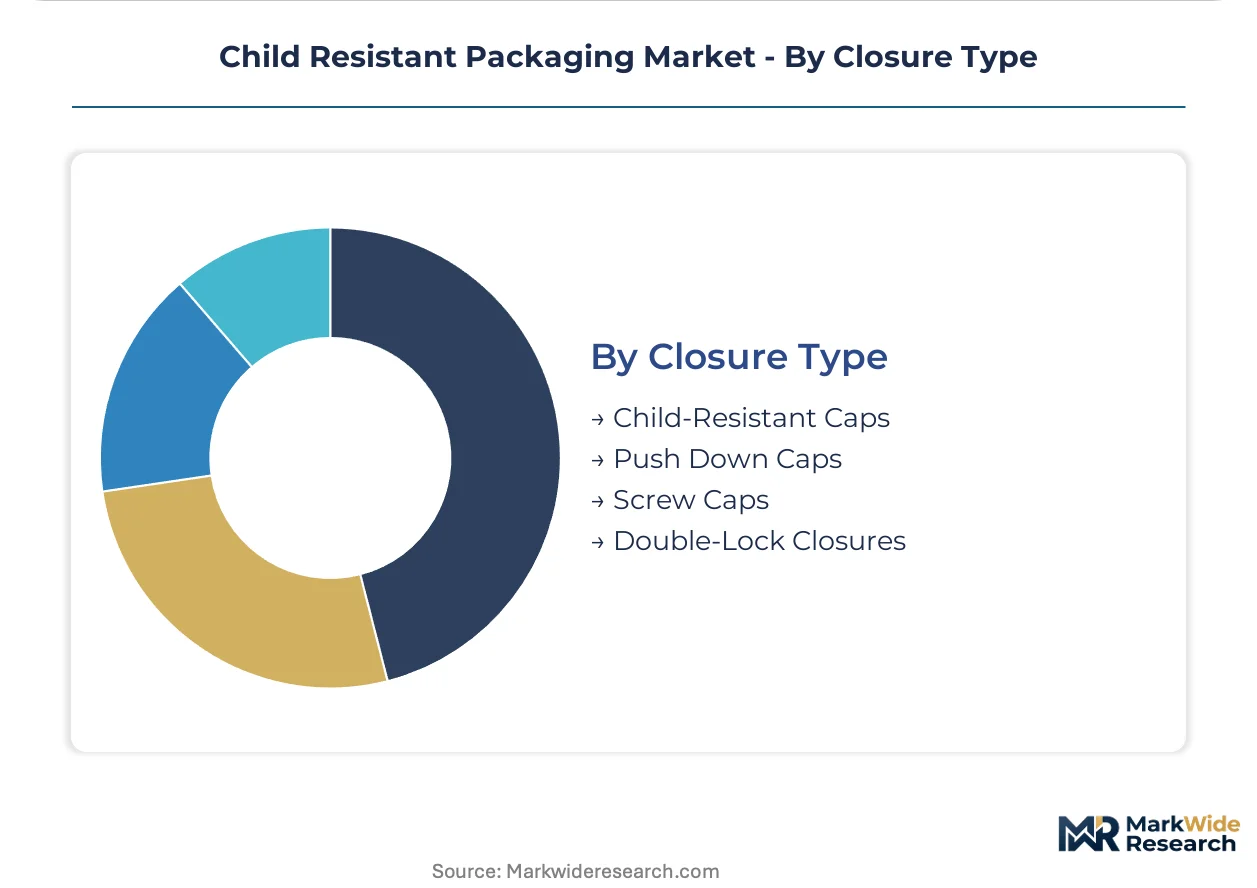
Child-resistant caps dominate unit volume, while double-lock closures are expanding most quickly in high-value pharmaceutical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized packaging engineers and polymer chemists cluster in pharmaceutical manufacturing corridors where regulatory certification requirements create talent moats around compliant production.
United States
Mail-order pharmacy fulfillment networks and state-level cannabis dispensary mandates drive format demand. The Consumer Product Safety Commission enforces Poison Prevention Packaging Act testing protocols that eliminate uncertified converters. New Jersey and Pennsylvania host dense concentrations of FDA-registered contract packagers serving consolidated pharmaceutical buyers.
Germany
BfArM oversight of phased cannabis legalization creates demand for EU-compliant child-resistant formats. ECHA REACH candidate list expansions accelerate resin transitions away from legacy additives. The Rhine-Main industrial corridor anchors pharmaceutical packaging innovation clusters near Frankfurt's logistics hub.
China
Domestic pharmaceutical contract manufacturing growth and export-oriented nutraceutical production expand substrate demand. NMPA alignment with international pediatric safety standards pressures local converters toward ISO 8317 certification. The Yangtze River Delta concentrates injection-molding capacity serving both domestic and export markets.
India
Generic drug export growth and domestic OTC market expansion sustain rigid container demand. CDSCO pediatric safety labeling requirements reinforce compliance investments for EU and US-bound shipments. Gujarat and Maharashtra host integrated pharmaceutical packaging corridors with resin-to-finish capabilities.
Canada
Health Canada and PMRA alignment with US FDA standards facilitates cross-border pharmaceutical supply chains. Provincial cannabis retail frameworks mandate child-resistant formats for edibles and concentrates. Ontario's Golden Horseshoe anchors contract packaging capacity serving North American distribution networks.
Child Resistant Packaging Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers. The market structure concentrates procurement authority toward large converters with global laboratory networks and CPSC-recognized testing capabilities. Three strategic archetypes dominate: integrated resin-to-finish manufacturers, precision closure engineering specialists, and flexible packaging converters pursuing pharmaceutical validation. Competitive moves center on M&A to acquire certified facility footprints and strategic partnerships with testing laboratories to compress product launch timelines.
Within the diversified multinational tier, Amcor plc and Berry Global Group exemplify scale-driven positions anchored by global converting footprints and pharmaceutical certification depth. AptarGroup occupies a specialized niche in precision closure engineering where patent-protected dual-action mechanisms command tooling premiums. These three companies represent the competitive spectrum from integrated substrate control through application-specific component specialization.
| Leading Market Players |
|---|
| AptarGroup |
| Constantia Flexibles |
| Berry Global Group |
| Mold-Rite Plastics |
| Winpak Ltd |
| Amcor plc |
| WestRock Company |
| Origin Pharma Packaging |
| Gerresheimer AG |
| Others |
Supply Flow & Price Mechanics
Polypropylene resin feedstock flows from Gulf Coast petrochemical complexes through three distinct pricing tiers downstream, with certified closure converters capturing margin premiums while uncertified competitors face exclusion from pharmaceutical procurement lists.
Pricing Analysis
Unbundled testing and certification services separate from molded component supply, creating a two-tier structure where ASTM D3475 validation commands substantial premiums over uncertified alternatives. Price differentiation hinges on CPSC-recognized laboratory status and dual-action mechanism patent licensing. Pricing pressure intensifies in generic drug contracts as pharmacy benefit managers consolidate vendor lists and demand volume discounts. Small regional converters exhibit highest price sensitivity, while multinational pharmaceutical buyers prioritize compliance assurance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with CPSC-recognized testing laboratories concentrated in the United States, where only three facilities hold approved status for ASTM D3475 protocol validation. Raw material supply draws from Saudi Arabia, South Korea, and the US Gulf Coast for high-density polyethylene and polypropylene resins. Supply chain risk centers on regulatory restriction exposure from REACH candidate list expansions forcing accelerated resin transitions. Distribution runs through FDA-registered contract packagers clustered in New Jersey and Pennsylvania, with secondary nodes in Germany's Rhine-Main corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Child resistant packaging has matured into a late-cycle quality market where pharmaceutical buyers prioritize validated formats over cost minimization, with mail-order pharmacy growth amplifying demand for ship-ready certified solutions.
For Market Incumbents: Anticipate margin compression from pharmacy benefit manager consolidation by deepening captive resin supply and expanding CPSC-recognized testing capacity. Patent-protected dual-action closure licensing offers defensive moats against generic mechanism suppliers. Certification investment in EU BfArM-aligned protocols captures German cannabis legalization demand.
For New Entrants and Emerging Players: Smart packaging integration combining NFC authentication with mechanical child-resistance offers technology-first wedge into high-value pharmaceutical segments. White-space targets include mail-order pharmacy ship-ready formats and EU-compliant flexible pouches for German cannabis edibles. Go-to-market positioning should emphasize compressed product launch timelines through strategic testing laboratory partnerships.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters lack CPSC-recognized testing capabilities and face exclusion from pharmaceutical vendor lists. Long-term viability favors integrated resin-to-finish manufacturers with global certification depth. Acquisition target archetype: regional converters with FDA-registered facilities and untapped laboratory accreditation potential. Signal to watch: state-level cannabis packaging rule harmonization creating scalable format demand.
| Strategic Initiative | Industry Significance |
|---|---|
| CPSC-Recognized Testing Laboratory Acquisition | Eliminates product launch bottlenecks and captures ASTM D3475 certification premiums from pharmaceutical buyers. |
| Modular Closure Platform Development | Reduces changeover downtime for generic drug manufacturers facing SKU proliferation pressures. |
| REACH-Compliant Resin Transition | Preempts ECHA SVHC restrictions and secures European pharmaceutical supply chain positioning. |
| Smart Packaging Technology Integration | Commands premium positioning through NFC-enabled authentication combined with mechanical child-resistance. |
| Mail-Order Pharmacy Format Specialization | Captures growth from Medicare Part D distribution networks requiring ship-ready certified solutions. |
Methodological Framework
Direct dialogue with pharmaceutical packaging procurement directors, CPSC-recognized testing laboratory technical leads, contract packager operations managers, and resin supplier account executives grounded this analysis. Secondary validation drew from FDA 483 inspection observations, ECHA SVHC notification databases, ASTM D3475 protocol documentation, and pharmaceutical vendor qualification records. Bottom-up segment sizing triangulated against top-down market consolidation trends.
Segment-level projections across plastic containers, flexible pouches, glass bottles, and metal cans combined with closure type disaggregation and end-use vertical splits. Modeled inputs incorporated pharmacy benefit manager vendor list consolidation rates, state-level cannabis regulatory adoption timelines, and REACH candidate list expansion trajectories. CAGRs derived from regression analysis of historical certification volume against regulatory enforcement intensity.
The model holds under continued CPSC enforcement of Poison Prevention Packaging Act compliance and stable pharmaceutical buyer consolidation; deviation in federal cannabis scheduling or ECHA accelerated restriction timelines would shift volume trajectories materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Decorative Mylar Balloons Market
Specialty Packaging
Luxury Packaging Market
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Holographic Foils Market
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Global in Store Theater Packaging Market
Specialty Packaging
Promotion Bins Market
Specialty Packaging
Luxury Boxes Market
Specialty Packaging
Europe Child Resistant Packaging Market
Specialty Packaging
Mil-Spec Packaging Market