
 Die Cut Support Pads Market | 2026-2036
Die Cut Support Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Die Cut Support Pads Market Outlook
Electronics contract manufacturers is collapsing as the dominant buyer archetype for die cut support pads as automotive tier-one suppliers expand their specifications for EV battery module protection. International Paper leverages its North American containerboard infrastructure to backward-integrate into custom die cutting operations. High Win Industrial anchors its competitive position through polyurethane formulation expertise serving Asian electronics clusters. Progressive Packaging differentiates via rapid-turn prototyping capabilities for furniture and appliance OEMs.
Die cut support pads are engineered cushioning components fabricated through steel-rule or rotary die cutting processes, typically manufactured from polyethylene, polyurethane, neoprene, or silicone substrates with thickness tolerances ranging from 0.5 mm to 25 mm depending on load-bearing requirements. These pads function primarily as shock absorption and vibration damping interfaces between products and their shipping containers or assembly fixtures. Foam pads occupy the largest volume share across consumer electronics and white-goods applications where low-cost, lightweight protection remains paramount. Composite pads represent the fastest-expanding material category as multi-layer constructions combining adhesive films with energy-absorbing cores gain traction in automotive battery packaging where thermal insulation properties carry premium value. Rubber pads sustain stable demand in heavy machinery and industrial equipment segments where compression set resistance determines replacement cycles.
REACH substance restrictions and RoHS material declarations from European regulators constrain silicone and neoprene formulations, pushing compounders toward halogen-free alternatives. The EPA and OSHA jointly influence U.S. manufacturing through volatile organic compound emission limits in adhesive lamination processes and workplace exposure thresholds for isocyanate-based polyurethane curing. Stakeholders must monitor how evolving battery transport regulations from UN 38.3 testing protocols and country-specific hazardous material classifications reshape automotive pad specifications before committing to capacity expansion or material platform investments.
Market Dynamics
EV battery module packaging specifications are collapsing legacy foam specifications across automotive supply chains, forcing die cut pad manufacturers to engineer multi-layer thermal-barrier constructions that satisfy UN 38.3 transport protocols.
Growth Catalysts
- UN 38.3 Testing Mandates:Lithium-ion battery transport regulations now require vibration-damping interfaces with documented thermal runaway containment, expanding specification scope for automotive tier-one suppliers.
- Electronics Manufacturing Reshoring:Precision component protection demand is concentrating in Germany, South Korea, and the United States where semiconductor packaging facilities require sub-millimeter thickness tolerances.
- REACH Substance Restrictions:ECHA's evolving halogen-free material requirements are accelerating compounder R&D into silicone and neoprene alternatives with equivalent compression set resistance.
Market Restraints
- Petrochemical Feedstock Volatility:Polyethylene and polyurethane resin prices fluctuate with crude oil indices, compressing margin predictability for high-volume foam pad producers.
- Asian Supply Concentration:Rotary die cutting equipment and precision steel-rule tooling fabrication concentrates in Chinese and Taiwanese machine shops, creating import dependency for Western converters.
- Compression Set Limitations:Standard polyethylene foams degrade under sustained load in heavy machinery applications, limiting replacement cycle extension and lifetime value capture.
Strategic Opportunities
- Indian Electronics Manufacturing:PLI scheme incentives for semiconductor and mobile device assembly are creating first-mover advantage for pad suppliers establishing local die cutting operations.
- Adhesive Film Convergence:Pressure-sensitive adhesive lamination combined with aerogel cores enables thermal management integration previously requiring separate material stacks.
- Direct OEM Contracting:E-commerce fulfillment centers for furniture and appliance brands are bypassing traditional packaging distributors, enabling margin capture through rapid-turn prototyping capabilities.
Industry Challenges
- Multi-Physics Simulation Expertise:Battery pack engineers now require coupled thermal-mechanical finite element analysis for pad specification, a skill set scarce among traditional foam converters.
- Cross-Border Certification Lag:Dual REACH and FDA material declarations for medical device shipping applications extend qualification timelines by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Cut Support Pads Market |
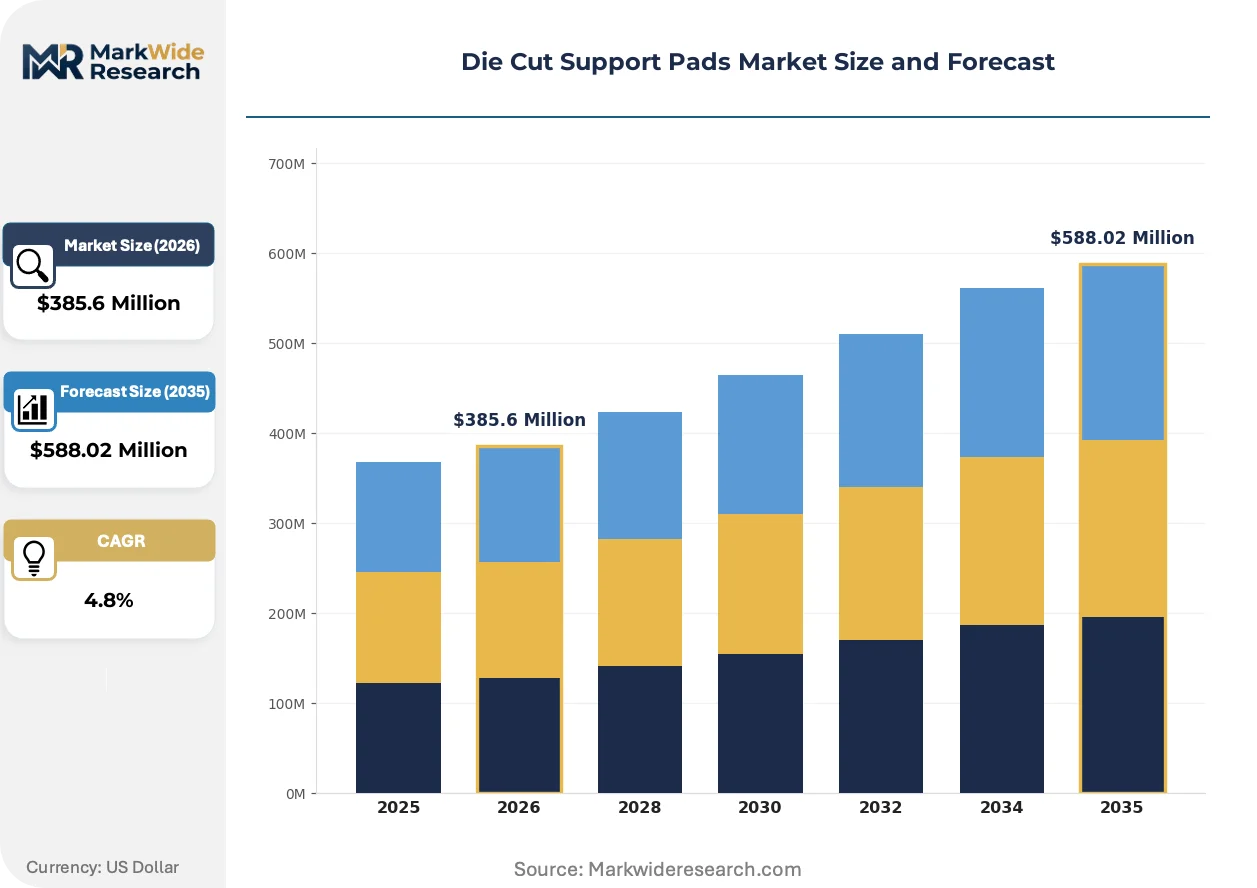
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Pads, Rubber Pads, Adhesive Pads, Composite Pads End User: Packaging Industry, Automotive Sector, Electronics Manufacturing, Furniture Production Material: Polyethylene, Polyurethane, Neoprene, Silicone Application: Shock Absorption, Vibration Damping, Surface Protection, Insulation |
| Companies Covered | International Paper, High Win Industrial, Toitsu Package, Innerpak of Wisconsin, Progressive Packaging, United Packaging Industries, Premier Packaging Products, Wall Family Enterprise, Box Captain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Cut Support Pads Market Strategic Shifts
Material science convergence with digital manufacturing is collapsing traditional specification boundaries, enabling functionally graded pads with spatially varying density profiles.
Multi-layer composite constructions combining adhesive films with aerogel or phase-change material cores are displacing monolithic foam pads in EV battery packaging. Automotive thermal engineers specify these hybrids for simultaneous vibration damping and thermal runaway containment. Tier-one battery suppliers in South Korea and Germany now mandate documented thermal impedance values alongside mechanical performance metrics.
REACH substance restrictions and RoHS material declarations from ECHA constrain silicone and neoprene formulations in European supply chains. Compounders redirect R&D spending toward halogen-free polyurethane systems with equivalent compression set resistance. Electronics contract manufacturers serving EU markets now require full material disclosure documentation upstream of component qualification.
Consolidated procurement through automotive OEM direct material specifications is fragmenting legacy distributor relationships. Battery pack engineering teams issue pad specifications tied to specific thermal-mechanical performance envelopes rather than generic foam grades. This pattern concentrates most visibly in Germany and the United States where EV platform engineering decisions flow from integrated vehicle development centers.
Die Cut Support Pads Market Segmentation
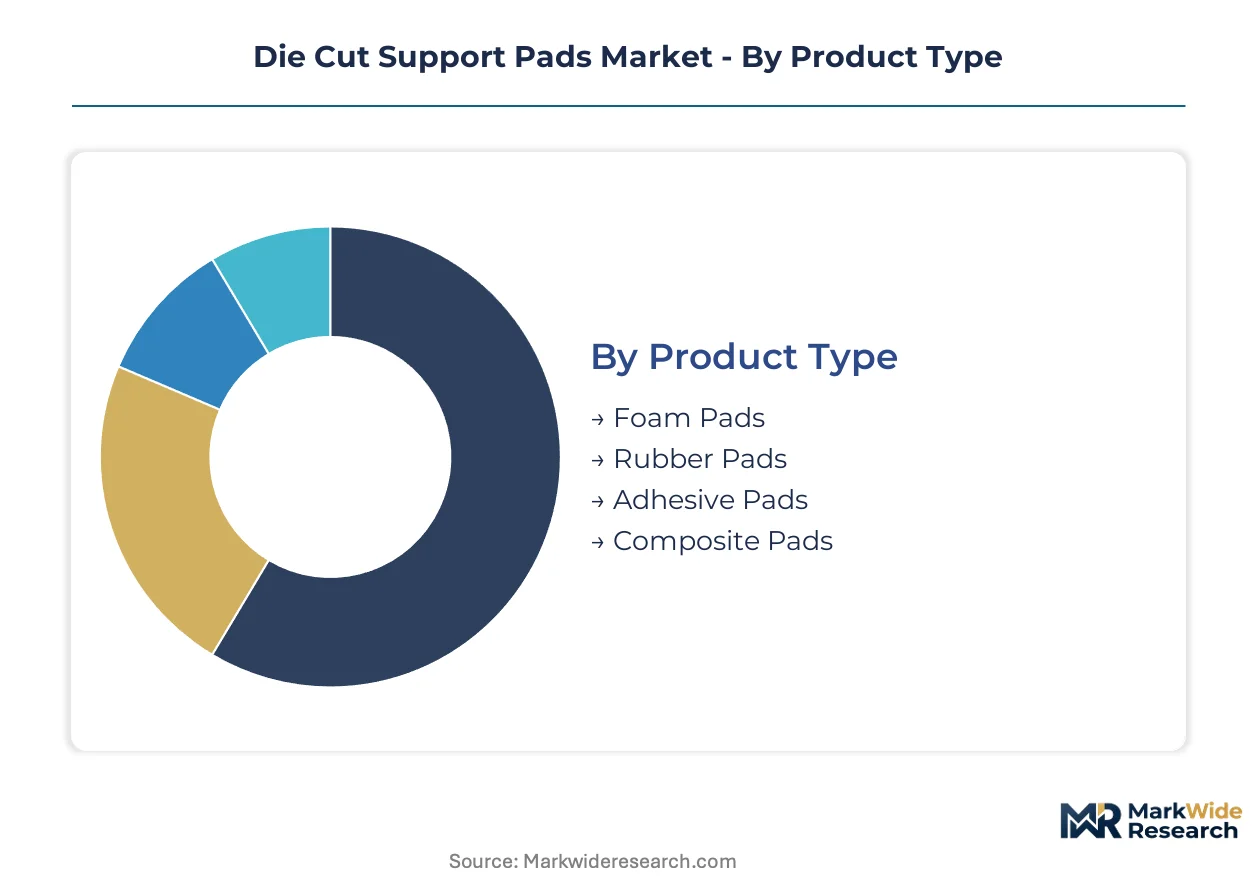
Margin pools in die cut support pads concentrate where specification complexity intersects with regulatory compliance. Understanding how product architecture, end-use requirements, and material chemistry fragment demand enables targeted capacity allocation and R&D prioritization.
Product Type:
Margin concentration sits with multi-layer constructions that combine mechanical performance with thermal or adhesive functionality, commanding premium positioning over commodity foam grades.
- Composite Pads:Multi-layer constructions integrate adhesive films with aerogel or phase-change material cores. Automotive battery suppliers in South Korea and Germany now specify these for simultaneous vibration damping and thermal runaway containment under UN 38.3 protocols.
- Foam Pads:Polyethylene and polyurethane substrates dominate volume across consumer electronics and white-goods applications. German and United States precision manufacturing clusters drive sub-millimeter thickness tolerance requirements for semiconductor packaging protection.
- Rubber Pads:Neoprene and silicone formulations serve heavy machinery segments where compression set resistance determines replacement cycles.
- Adhesive Pads:Pressure-sensitive lamination enables rapid fixture mounting without secondary fastening hardware.
Foam pads hold installed capacity. Composite pads are rotating up the share rankings.
End User:
Application complexity and qualification timelines separate pricing tiers, with automotive and electronics commanding specification premiums over packaging commodities.
- Automotive Sector:EV battery module packaging mandates multi-physics performance envelopes combining thermal impedance documentation with mechanical damping. Tier-one suppliers in Germany issue direct material specifications that bypass legacy distributor channels.
- Electronics Manufacturing:Contract manufacturers require REACH-compliant halogen-free alternatives with full material disclosure documentation upstream of component qualification.
- Packaging Industry:E-commerce fulfillment centers for furniture and appliance brands increasingly source direct from converters with rapid-turn prototyping capabilities.
- Furniture Production:Surface protection during transit and assembly fixture cushioning sustain steady demand for cost-optimized foam grades.
Electronics manufacturing holds installed capacity. Automotive sector is climbing the fastest.
Material:
Feedstock chemistry and regulatory compliance burden determine margin architecture, with specialty polymers outperforming commodity polyethylene on value per kilogram.
- Polyurethane:Formulation expertise anchors competitive positioning for Asian electronics clusters, with halogen-free systems gaining share as REACH restrictions constrain legacy silicone and neoprene options.
- Polyethylene:Lightweight, low-cost substrates occupy volume leadership in consumer goods protection despite compression set limitations under sustained heavy machinery loads.
- Neoprene:Oil resistance and weathering stability sustain industrial equipment applications.
- Silicone:Temperature extremes and biocompatibility requirements support medical device and aerospace niches.
Polyethylene holds installed capacity. Polyurethane is gaining share fastest.
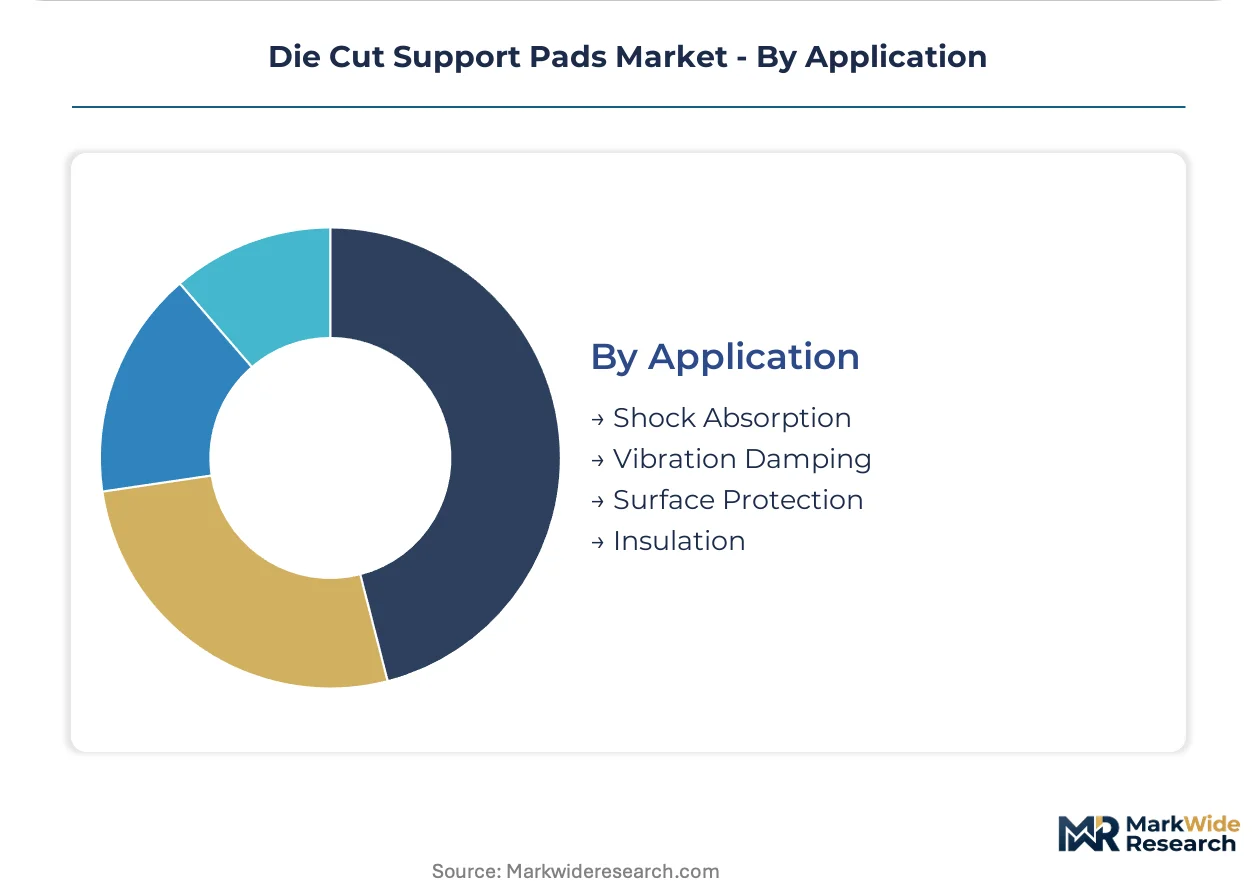
Application:
Functional integration requirements separate premium specifications from commodity grades, with thermal-mechanical coupling commanding highest value capture.
- Thermal Insulation:Phase-change and aerogel core integration enables battery pack thermal management previously requiring separate material stacks.
- Vibration Damping:Frequency-tuned constructions serve precision electronics and automotive modules where resonance control prevents component fatigue.
- Shock Absorption:Energy-dissipating foams protect consumer durables through distribution chain impacts.
- Surface Protection:Scratch prevention and cosmetic preservation drive furniture and appliance OEM specifications.
Shock absorption holds installed capacity. Thermal insulation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics contract manufacturers and automotive tier-one suppliers concentrate procurement in precision manufacturing clusters across Germany, South Korea, and the United States. These buyer archetypes drive sub-millimeter tolerance requirements and multi-physics thermal-mechanical specifications. Geographic demand patterns reflect EV battery engineering centers and semiconductor packaging facility locations.
United States
Automotive OEM direct material specifications for EV battery modules bypass legacy distributor channels. EPA volatile organic compound emission limits and OSHA isocyanate exposure thresholds constrain adhesive lamination processes. Detroit and Austin engineering centers issue pad specifications tied to specific thermal impedance performance envelopes.
Germany
Integrated vehicle development centers mandate documented thermal runaway containment under UN 38.3 protocols. ECHA REACH substance restrictions and RoHS material declarations accelerate halogen-free polyurethane R&D. Stuttgart and Munich precision manufacturing clusters require full material disclosure documentation upstream of component qualification.
South Korea
Battery pack engineering teams specify multi-layer thermal-barrier constructions with coupled thermal-mechanical finite element analysis. MFDS and transport ministry hazardous material classifications reshape automotive pad specifications. Seoul and Busan electronics clusters anchor regional demand for sub-millimeter thickness tolerances.
China
Rotary die cutting equipment and precision steel-rule tooling fabrication concentrates in Chinese machine shops, creating supply concentration for Western converters. MIIT dual carbon goals and GB standards influence material selection. Shenzhen and Shanghai electronics manufacturing bases drive volume demand for consumer electronics protection.
India
PLI scheme incentives for semiconductor and mobile device assembly create first-mover advantage for pad suppliers establishing local die cutting operations. BIS certification requirements and DGFT import regulations shape procurement patterns. Karnataka and Tamil Nadu electronics manufacturing clusters attract precision component protection investment.
Die Cut Support Pads Market Competitive Environment
Player mix skews toward regional specialists with formulation expertise and rapid-turn prototyping capabilities. The vendor base distributes across three tiers: integrated paperboard converters with backward capacity, polyurethane compounders serving Asian electronics clusters, and rapid-turn prototyping specialists for furniture and appliance OEMs. Dominant competitive moves include captive supply of die cutting operations and pressure-sensitive adhesive lamination technology licensing.
Within the integrated converter tier, International Paper leverages North American containerboard infrastructure. Among Asian compounders, High Win Industrial anchors positioning through polyurethane formulation expertise. On the rapid-turn vector, Progressive Packaging exemplifies prototyping capabilities for direct OEM contracting. These three represent distinct strategic archetypes: scale-driven vertical integration, materials science specialization, and speed-to-market service models.
| Leading Market Players |
|---|
| International Paper |
| High Win Industrial |
| Toitsu Package |
| Innerpak of Wisconsin |
| Progressive Packaging |
| United Packaging Industries |
| Premier Packaging Products |
| Wall Family Enterprise |
| Box Captain |
| Others |
Value Chain & Pricing Dynamics
Rotary die cutting equipment fabrication at scale in Chinese and Taiwanese machine shops creates capacity utilization advantages that compress price floors for Western converters while elevating margin capture for integrated compounders with captive formulation expertise.
Pricing Analysis
Cost-plus contracts with crude oil indexation dominate polyethylene and polyurethane foam pad procurement, linking converter margins directly to petrochemical feedstock volatility. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with REACH-compliant halogen-free formulations commanding tier-one automotive premiums. Cost compression in standard foam grades is intensifying because of Asian import competition. Furniture OEMs exhibit highest price sensitivity, while EV battery suppliers prioritize thermal-mechanical performance over unit cost.
Supply Chain Analysis
China and Taiwan anchor rotary die cutting equipment fabrication and precision steel-rule tooling production, creating geographic concentration that Western converters draw from for production assets. Raw material inputs rest on polyethylene resin, polyurethane prepolymers, and pressure-sensitive adhesive films. Single-source vulnerability concentrates in aerogel core supply for multi-layer thermal barriers. Distribution runs through automotive tier-one suppliers, electronics contract manufacturers, and direct OEM contracting for e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UN 38.3 battery transport mandates and REACH substance restrictions are accelerating material platform turnover, creating high-growth disruption as legacy foam specifications collapse under multi-physics performance requirements.
For Market Incumbents: Secure backward integration into polyurethane formulation to defend against Asian compounder encroachment. Capture channel control through direct OEM contracting relationships that bypass legacy distributors. Invest in multi-physics simulation capabilities to meet battery pack engineering team specifications for coupled thermal-mechanical finite element analysis.
For New Entrants and Emerging Players: Differentiate on rapid-turn prototyping capabilities for furniture and appliance OEMs pursuing direct converter relationships. Target Indian electronics manufacturing clusters where PLI scheme incentives are concentrating semiconductor and mobile device assembly demand. Pursue go-to-market angles through adhesive film convergence with aerogel core integration.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among polyurethane compounders serving Asian electronics clusters with formulation expertise and long-term supply agreements. Five-to-ten year viability favors specialists with halogen-free R&D pipelines and automotive qualification track records. Watch for inflection signals in Indian BIS certification timelines and local die cutting operation establishment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Formulation | Captive supply of halogen-free systems secures REACH-compliant positioning for European automotive procurement. |
| Multi-Physics Simulation Capability Buildout | Coupled thermal-mechanical FEA expertise satisfies battery pack engineering team specification requirements under UN 38.3. |
| Direct OEM Contracting Channel | Bypassing legacy distributors captures margin from furniture and appliance brands seeking rapid-turn prototyping. |
| Indian Manufacturing Footprint Establishment | Local die cutting operations exploit PLI scheme incentives concentrating semiconductor and mobile device assembly demand. |
| Adhesive Film Convergence R&D | Pressure-sensitive lamination with aerogel cores enables thermal management integration previously requiring separate material stacks. |
Study Parameters
A standing panel of automotive tier-one supplier procurement managers, electronics contract manufacturing executives, polyurethane compounder R&D directors, and rotary die cutting equipment fabricators provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation through customs trade data, EPA volatile organic compound emission filings, ECHA REACH substance restriction updates, and SEC 10-K disclosures from integrated paperboard converters. Bottom-up demand modeling triangulated against top-down capacity assessments from machine shop surveys.
Consistency checks validated volume and value outputs against external benchmarks including regional manufacturing cluster production indices and petrochemical feedstock price series. Segmentation dimensions spanned product architecture, material chemistry, end-use application, and geographic regulatory cluster across the modeling period. CAGRs derived from time-series regression of demand drivers including EV battery production volumes, electronics manufacturing reshoring announcements, and regulatory compliance timeline shifts.
Decision-makers should treat outputs as directional under base assumptions of sustained UN 38.3 enforcement and REACH substance restriction expansion; material deviation in battery transport protocol adoption or halogen-free formulation cost curves would warrant model refresh. Recalibration cycles align with material shifts in automotive OEM direct material specification patterns and Indian PLI scheme incentive disbursement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Chemical Packaging Market
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Face Stock Films Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
Heat Shrink Packaging Market
Packaging Materials
Wooden and Plywood Packaging Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Standard Liner Market