
 Packaging Materials Market | 2026-2036
Packaging Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Materials Market Analysis
E-commerce fulfillment networks is unwinding the historical dominance of brick-and-retail buyer archetypes in corrugated and flexible packaging procurement. Amcor leverages its global film and flexible packaging platform to serve pharmaceutical and food-grade barrier requirements across multiple continents. International Paper sustains unmatched North American containerboard capacity and integrated box plant networks. Smurfit Kappa anchors European corrugated supply through its recycled fiber infrastructure and pan-regional plant footprint.
Packaging materials encompass substrates engineered to contain, protect, preserve, and transport goods through supply chains, with specifications spanning basis weight, tensile strength, moisture vapor transmission rates, and seal integrity parameters. Plastic films and barrier laminates dominate pharmaceutical serialization and extended shelf-life food applications where oxygen ingress below 0.1 cc/m²/day proves critical. Paper and corrugated segments command the largest volume share but face margin compression from recovered fiber cost volatility, while flexible packaging captures faster growth in pouches and resealable formats driven by convenience-oriented food and cosmetics brands. Glass packaging retains premium positioning in spirits and perfumery despite higher logistics costs, with metal cans competing aggressively in beverage categories through lightweighting and decorated ends.
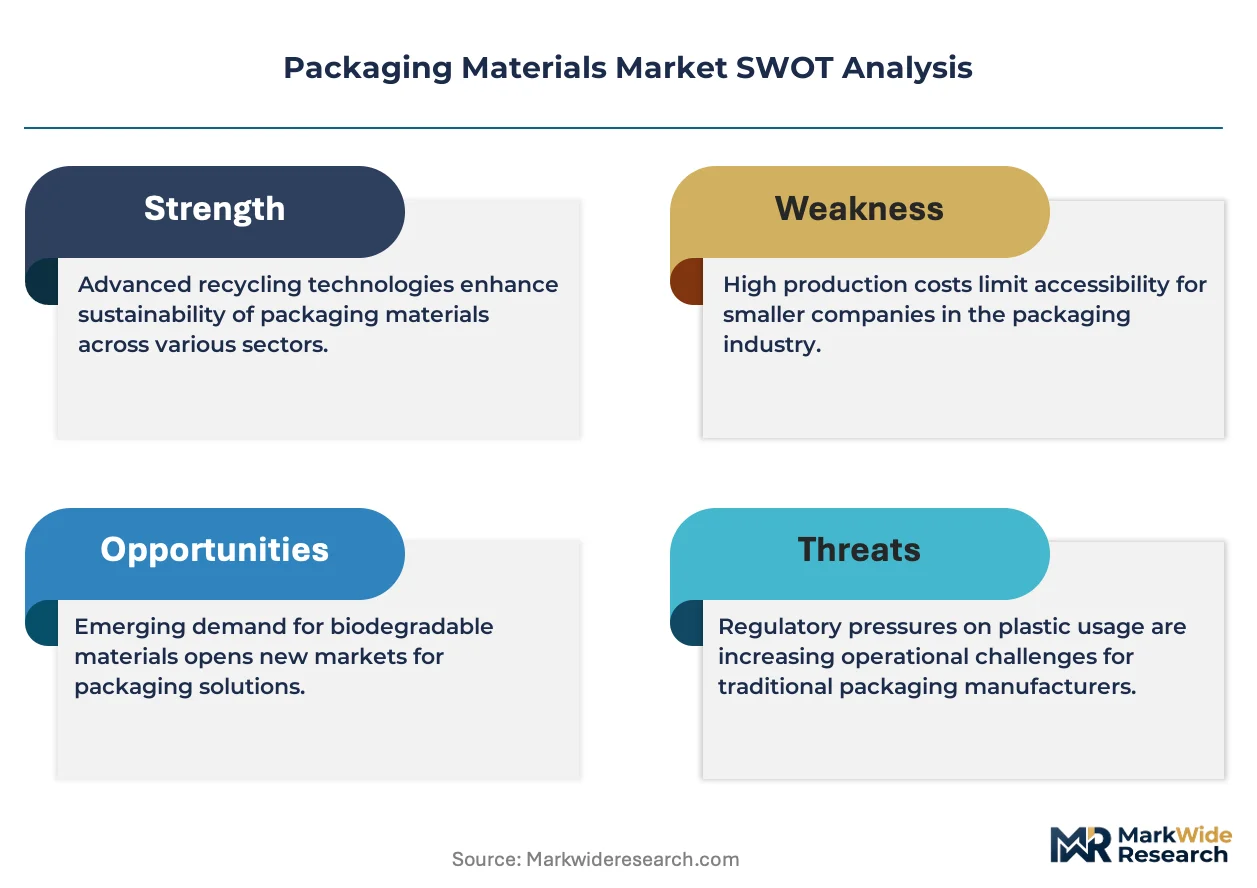
The EU Packaging and Packaging Waste Regulation and REACH frameworks mandate recycled content thresholds and restrict certain additive chemistries, compelling material substitutions and compliance investments across the value chain. FDA food contact notification requirements and EPA emissions standards for pulp and paper mills shape product approval timelines and mill-level capital allocation in the United States. Stakeholders must monitor evolving extended producer responsibility schemes and recyclability labeling mandates to anticipate which material formats will retain market access across major economies.
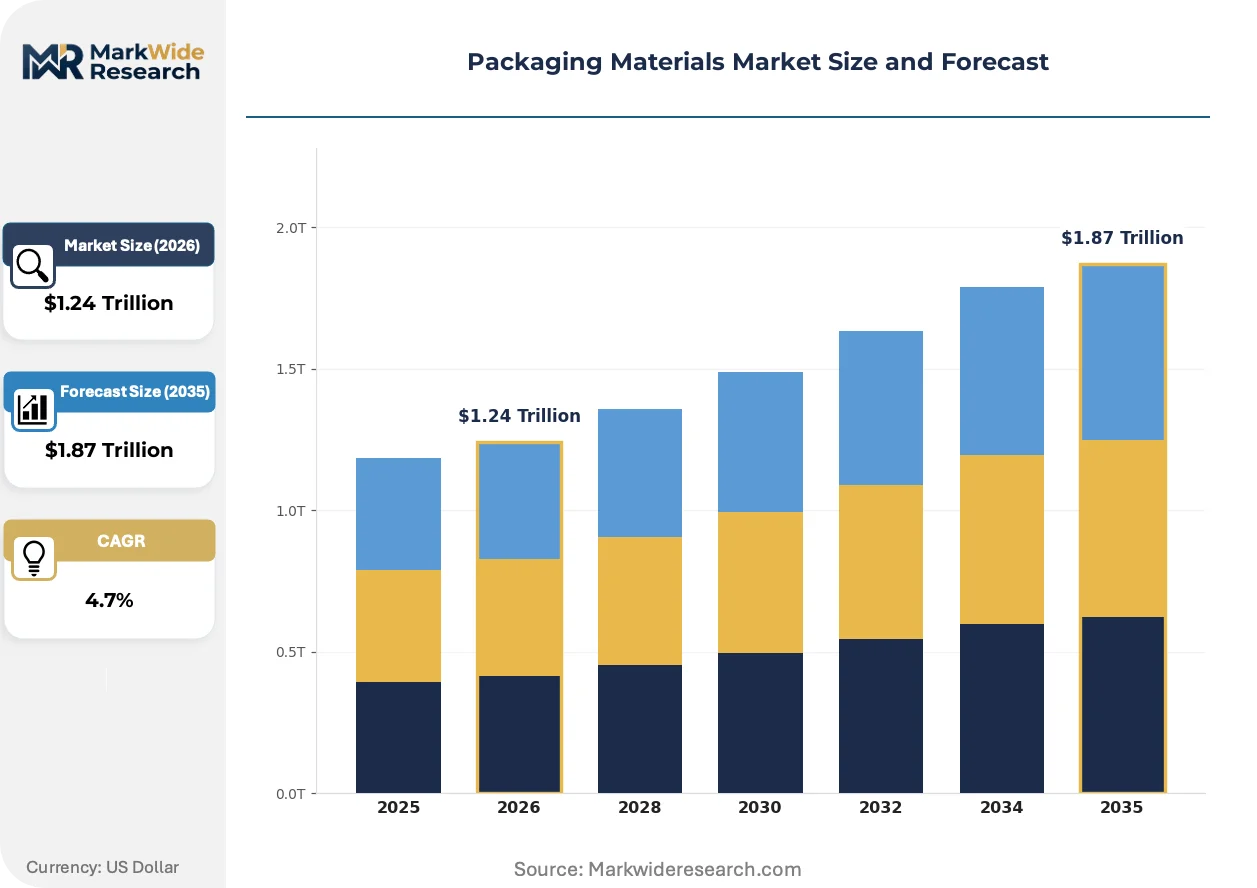
Market Dynamics
E-commerce fulfillment networks are compressing traditional corrugated procurement cycles while EU Packaging and Packaging Waste Regulation mandates force material substitutions across pharmaceutical and food-grade barrier applications. Recovered fiber cost volatility and extended producer responsibility schemes now determine capital allocation priorities for integrated producers.
Growth Catalysts
- EU recycled content mandates:The Packaging and Packaging Waste Regulation compels converters to source post-consumer recycled resins and fibers, accelerating investment in sorting infrastructure and chemical recycling capacity across member states.
- Pharmaceutical serialization requirements:Oxygen barrier films below 0.1 cc/m²/day are capturing expanded share of unit-dose and blister packaging for temperature-sensitive biologics.
- German industrial packaging clusters:Central European manufacturing corridors concentrate demand for heavy-duty corrugated and returnable transit packaging serving automotive and machinery supply chains.
Market Restraints
- Recovered fiber cost volatility:Old corrugated container price swings compress margins for integrated box plants dependent on external furnish sourcing.
- Glass logistics burden:Higher dimensional weight and breakage rates constrain spirits and perfumery brands from expanding distribution into e-commerce channels.
- REACH additive restrictions:ECHA scrutiny of certain plasticizers and stabilizers forces reformulation cycles that extend food contact notification timelines.
Strategic Opportunities
- Flexible pouch penetration in cosmetics:Resealable spouted formats are displacing rigid jars and tubes in premium skin care, reducing shipping cube and shelf footprint.
- IRA clean manufacturing credits:US pulp and paper mills can capture investment incentives for emissions reduction retrofits and biomass boiler upgrades.
- India cold-chain expansion:Temperature-controlled pharmaceutical distribution is driving demand for insulated box liners and phase-change material panels.
Industry Challenges
- Barrier film technical talent scarcity:Coextrusion die design and multilayer lamination expertise concentrates among aging specialists in European and Japanese equipment suppliers.
- Recyclability certification delays:How2Recycle and OPRL label approvals require 12-18 month validation cycles that stall new format launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Materials Market |
| Market Size in 2026 | $1.24 Trillion |
| Market Size in 2035 | $1.87 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Metal, Glass End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Form Type: Flexible, Rigid, Semi-Rigid, Resealable Packaging Type: Cartons, Bottles, Pouches, Wraps |
| Companies Covered | Amcor, Ball Corporation, International Paper, WestRock, Crown Holdings, Mondi, Smurfit Kappa, Berry Global, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Materials Market Emerging Trajectories
Active and intelligent packaging systems are converging with sustainability mandates to reshape specification priorities across food, pharmaceutical, and industrial end-uses. Material science advances and regulatory pressure are compressing traditional format lifecycles.
Mono-material barrier films are replacing multi-layer laminates in snack and pet food pouches. Nestlé and Unilever procurement teams are accelerating qualification timelines for polyethylene-based structures compatible with existing store-drop recycling streams. This substitution is miniaturizing the specialty adhesive and tie-layer supplier base while expanding resin compounder influence over final package performance.
REACH authorization requirements for per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical treatments from molded fiber foodservice containers. ECHA sunset dates are forcing fast-casual chains and meal-kit providers to switch to clay-coated or bio-based alternatives ahead of 2025 compliance deadlines. Paperboard suppliers with in-house barrier coating capabilities are capturing specification authority previously held by separate film converters.
Brand owners are consolidating corrugated suppliers to reduce qualification overhead and secure volume commitments for seasonal surge capacity. Regional grocery and mass merchant chains are replacing fragmented local box plant relationships with national contracts tied to integrated containerboard mills. This concentration is most visible in North American e-commerce fulfillment, where Amazon and Walmart packaging engineering teams now mandate common flute profiles and print specifications across their supplier bases.
Packaging Materials Market Segmentation
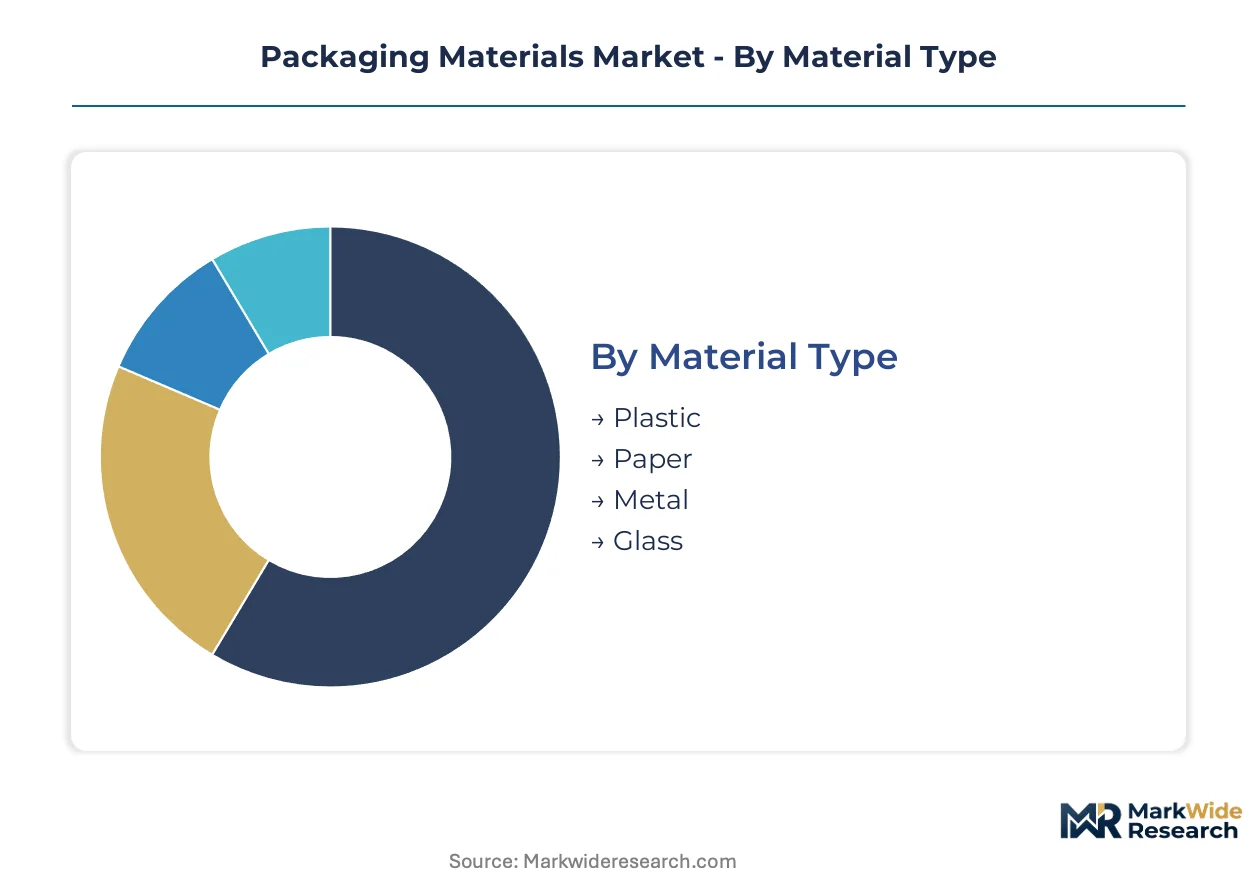
Packaging materials segment along four intersecting dimensions that determine specification priorities, regulatory exposure, and margin structure. Material chemistry dictates recyclability pathways and REACH compliance burdens, while end-use application sets barrier performance thresholds and sterilization requirements.
Material Type:
REACH additive restrictions and ECHA substance authorizations create divergent compliance costs across substrate categories, reshaping converter procurement strategies.
- Plastic:Polyethylene, polypropylene, and polyester films dominate oxygen barrier applications below 0.1 cc/m²/day for pharmaceutical blisters and extended shelf-life foods. German automotive suppliers are expanding polypropylene returnable transit packaging to serve Central European manufacturing corridors under tightened recycled content mandates.
- Paper:Containerboard and kraft grades command the largest shipment volumes but face margin pressure from old corrugated container price volatility. Swedish and Finnish integrated mills are capturing specification authority as brand owners consolidate supplier bases to reduce qualification overhead for seasonal surge capacity.
- Metal:Aluminum and steel cans compete through lightweighting and decorated ends in beverage categories, with two-piece aluminum drawing technology reducing metal content per unit.
- Glass:Soda-lime and borosilicate formats retain premium positioning in spirits and perfumery despite dimensional weight penalties that constrain e-commerce distribution expansion.
Established volume favors paper; emerging adoption favors plastic barrier films.
End Use Industry:
Customer procurement patterns concentrate demand in food and pharmaceutical segments where serialization and shelf-life extension command specification authority.
- Food & Beverage:Convenience-oriented brands are accelerating qualification timelines for mono-material polyethylene pouches compatible with store-drop recycling streams, displacing multi-layer laminates in snacks and pet food. Nestlé procurement teams are consolidating corrugated suppliers to secure volume commitments for seasonal surge capacity.
- Pharmaceuticals:Temperature-sensitive biologics are driving oxygen barrier film specifications below 0.1 cc/m²/day for unit-dose and blister formats, with serialization requirements mandating track-and-trace integration.
- Cosmetics:Resealable spouted pouches are displacing rigid jars and tubes in premium skin care, reducing shipping cube and retail shelf footprint for direct-to-consumer channels.
- Electronics:Anti-static films and molded fiber cushioning serve semiconductor and consumer device distribution, with ESD protection specifications tightening for wafer-level packaging.
Food & Beverage anchors current procurement volume; Pharmaceuticals commands the steepest expansion trajectory as cold-chain infrastructure proliferates.
Form Type:
Logistics cost compression and dimensional weight pricing are rebalancing format preferences across fulfillment networks.
- Flexible:Films, pouches, and wraps minimize shipping cube and material weight, capturing expanded share in e-commerce fulfillment where Amazon and Walmart engineering teams mandate common specifications across supplier bases.
- Rigid:Bottles, jars, and containers provide structural protection for fragile goods, with glass formats retaining premium positioning despite breakage rates that constrain direct-to-consumer expansion.
- Semi-Rigid:Thermoformed trays and blister packs bridge protection and material efficiency in pharmaceutical and food applications.
- Resealable:Zipper-equipped and spouted formats command premium positioning in cosmetics and food, with convenience features justifying higher unit economics.
Flexible formats gain share fastest in fulfillment optimization; Rigid formats defend position in premium spirits and perfumery.
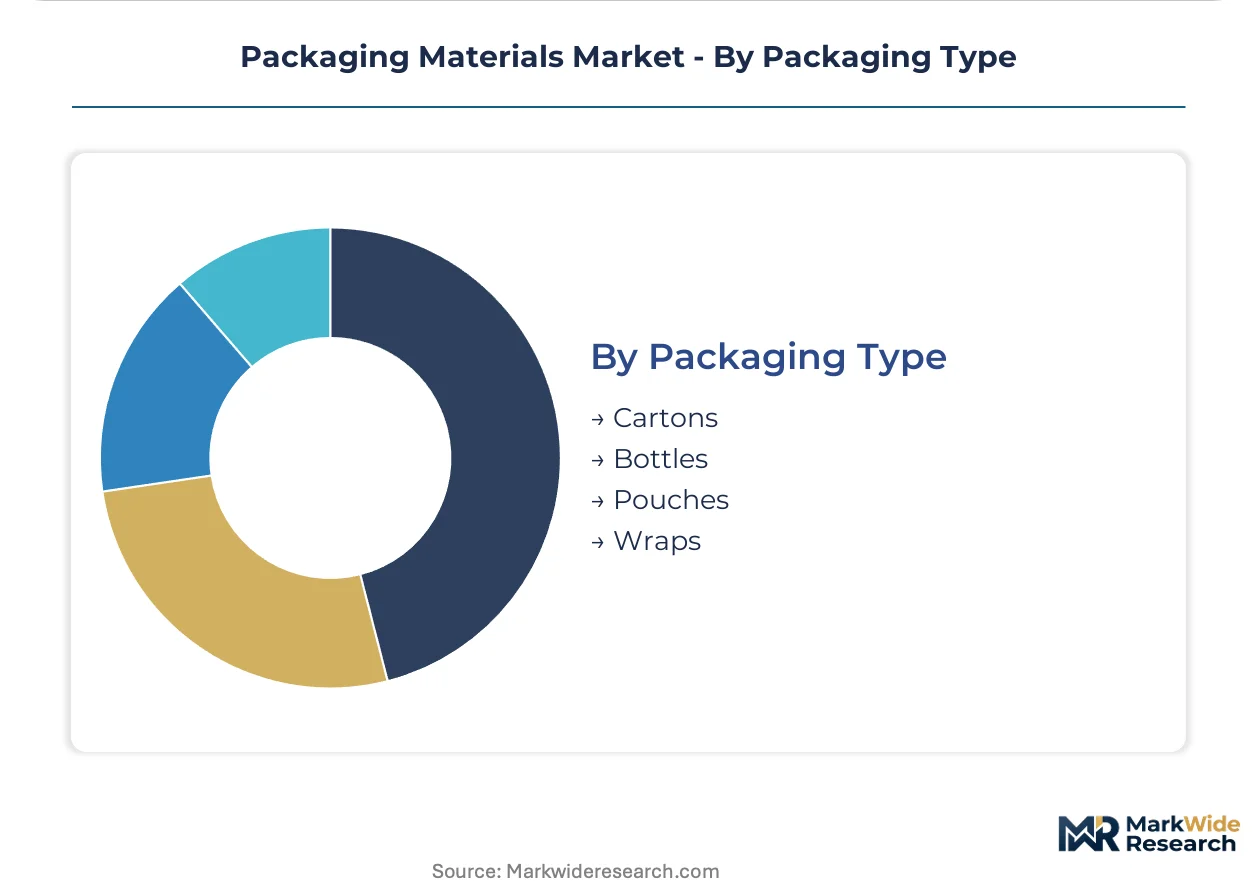
Packaging Type:
Equipment compatibility and line speed requirements lock in format selection across high-volume production environments.
- Cartons:Folding carton and corrugated box formats serve the broadest end-use spectrum, with integrated containerboard mills capturing volume concentration as regional grocery chains replace fragmented local plant relationships with national contracts.
- Bottles:Blow-molded and stretch-blown formats dominate beverage and personal care liquids, with lightweighting technology reducing resin content per unit.
- Pouches:Stand-up and flat pouch formats are displacing rigid alternatives in snacks, pet food, and cosmetics, with spouted variants capturing premium positioning.
- Wraps:Stretch film and shrink wrap formats secure palletized loads and individual unit protection, with pre-stretch technology reducing material consumption per wrapped load.
Cartons retain volume leadership through integrated mill networks; Pouches represent the fastest-climbing format as brand owners prioritize shipping efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial packaging clusters export heavy-duty corrugated and returnable transit systems into Central European manufacturing corridors, while Chinese substrate producers supply flexible barrier films to pharmaceutical and food brands across Southeast Asian fulfillment networks.
Germany
Automotive and machinery supply chains drive demand for heavy-duty corrugated and reusable plastic transit packaging. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that accelerate chemical recycling investments. The Rhine-Main industrial corridor concentrates specification authority for Central European distribution networks.
United States
E-commerce fulfillment networks compress corrugated procurement cycles while demanding common flute specifications across supplier bases. FDA food contact notification requirements and EPA emissions standards for pulp mills shape capital allocation timelines. Integrated containerboard mills in the Southeast capture volume concentration as national retailers consolidate supplier relationships.
China
Domestic cold-chain expansion and pharmaceutical distribution infrastructure drive oxygen barrier film specifications. NMPA serialization requirements and MIIT industrial standards mandate track-and-trace integration for temperature-sensitive biologics. The Yangtze River Delta hosts coextrusion equipment suppliers serving flexible packaging converters.
India
Temperature-controlled pharmaceutical distribution creates demand for insulated box liners and phase-change material panels. FSSAI food safety standards and CDSCO drug packaging regulations tighten barrier performance documentation. Maharashtra's industrial corridors concentrate flexible film converting capacity for domestic and export markets.
Japan
Pharmaceutical blister and unit-dose formats require oxygen barrier films below 0.1 cc/m²/day for biologics stability. METI circular economy guidelines and PMDA serialization mandates accelerate mono-material qualification timelines. The Kanto region maintains coextrusion die design expertise concentrated among specialized equipment suppliers.
Packaging Materials Market Vendor Landscape
Player mix skews toward integrated fiber-based producers and multinational flexible film specialists. The market structures around three tiers: integrated containerboard mills with captive box plant networks, global flexible packaging platforms with pharmaceutical barrier capabilities, and regional converters serving fragmented local demand. Two competitive moves dominate: consolidation of corrugated suppliers to reduce buyer qualification overhead, and backward integration into recycled resin and fiber sourcing to secure compliance with EU recycled content mandates.
Among the integrated fiber-based tier, International Paper and WestRock exemplify scale-driven positions anchored in North American containerboard capacity. Smurfit Kappa occupies a comparable archetype across European recycled fiber infrastructure. Amcor sits within the multinational flexible packaging specialist tier, representing global film and barrier laminate capabilities. These three anchors illustrate how geographic integration and substrate specialization stratify competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Amcor |
| Ball Corporation |
| International Paper |
| WestRock |
| Crown Holdings |
| Mondi |
| Smurfit Kappa |
| Berry Global |
| DS Smith |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between integrated containerboard mills and national retail chains lock in both fiber supply access and price visibility across volatile old corrugated container markets. These agreements compress spot market participation while concentrating procurement leverage among buyers with seasonal surge capacity requirements.
Pricing Analysis
Prior-generation recycled fiber grades trade at persistent discounts to virgin pulp benchmarks, while next-generation chemical recycling outputs command emerging premiums under EU recycled content mandates. Three-tier pricing structure across pharmaceutical-grade barrier films, food-contact compliant laminates, and industrial wrap formats reflects certification tier and oxygen transmission rate performance. Cost compression in standard corrugated runs through external furnish dependency as OCC price swings compress integrated box plant margins. Pharmaceutical serialization buyers exhibit lowest price sensitivity due to regulatory compliance imperatives, while commodity food brands maximize volume leverage.
Supply Chain Analysis
Rhine-Main corridor logistics chokepoints constrain heavy-duty corrugated distribution into Central European manufacturing corridors during peak automotive production cycles. Raw material sourcing draws from Swedish and Finnish integrated pulp mills, German recycled fiber collection networks, and Yangtze River Delta coextrusion equipment suppliers. Single-source vulnerability concentrates in European specialty adhesive and tie-layer compounders serving multilayer lamination requirements. Distribution runs through pan-regional containerboard mill networks with captive box plant footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Packaging materials procurement is consolidating toward platform-economics dynamics where Amazon and Walmart engineering teams mandate interoperable flute specifications across fragmented supplier bases, collapsing traditional qualification overhead.
For Market Incumbents: Consolidate corrugated supplier relationships to reduce buyer qualification cycles and secure volume commitments for seasonal surge capacity. Smurfit Kappa and International Paper should deepen backward integration into recycled resin sourcing to defend margin position against EU Packaging and Packaging Waste Regulation compliance costs. Chemical recycling capacity investments represent the priority lever for meeting tightening post-consumer recycled content thresholds. For New Entrants and Emerging Players: FDA food contact notification fast-tracks enable qualification acceleration for bio-based barrier coatings displacing REACH-restricted fluorochemical treatments in molded fiber foodservice containers. White-space targets include insulated box liners for India cold-chain expansion and mono-material polyethylene pouches for Nestlé and Unilever procurement qualification. Direct engagement with Amazon packaging engineering teams offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated fiber-based producers with captive box plant networks and multinational flexible packaging platforms with pharmaceutical barrier capabilities. Long-term viability hinges on chemical recycling infrastructure ownership and coextrusion die design expertise concentration. Monitor ECHA sunset date enforcement for per- and polyfluoroalkyl substances as inflection indicator for material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Sourcing | Secures post-consumer furnish supply against EU Packaging and Packaging Waste Regulation mandates. |
| Chemical Recycling Capacity Buildout | Enables food-grade recycled resin qualification for pharmaceutical and barrier film applications. |
| Mono-Material Barrier Film Qualification | Captures Nestlé and Unilever procurement share for store-drop recycling stream compatibility. |
| Consolidated Supplier Base Contracts | Reduces Amazon and Walmart packaging engineering qualification overhead across seasonal surge cycles. |
| Coextrusion Die Design Expertise Acquisition | Addresses barrier film technical talent scarcity concentrated among aging European and Japanese equipment suppliers. |
Methodological Framework
The analysis maps plastic barrier films, paper and corrugated substrates, metal cans, and glass formats, each validated through procurement directors at multinational food and pharmaceutical brand owners. Primary interviews with containerboard mill operations managers, flexible packaging converter technical directors, and retail chain packaging engineers combined with secondary validation against ECHA substance authorization databases, FDA food contact notification filings, EU Packaging and Packaging Waste Regulation implementation texts, and trade flow data from German and US customs authorities. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Consistency checks validated model outputs against external benchmarks including integrated mill capacity utilization disclosures and flexible packaging trade association shipment reports. The analytical framework segments by material chemistry, end-use application, form type, and packaging format across the projection horizon, with CAGRs derived from regression analysis of historical volume trends and elasticity-adjusted demand drivers. Forecast inputs incorporate EU recycled content mandate compliance timelines and pharmaceutical serialization infrastructure buildout rates.
Decision-makers should treat outputs as directional under assumptions of sustained e-commerce fulfillment network expansion and stable REACH additive restriction enforcement schedules; material deviation in regulatory implementation velocity or fiber cost volatility would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA per- and polyfluoroalkyl substance sunset dates and IRA clean manufacturing credit allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Book Wraps Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Strip Pack Laminates Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Single-Use Packaging Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
MDO Films Market
Packaging Materials
Box and Carton Overwrap Films Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Europe Airless Packaging Market
Packaging Materials
Packaging Reel Market
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Finish Foils Market
Packaging Materials
Battery Packaging Material Market