
 Europe Consumer Packaging Market | 2026-2036
Europe Consumer Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Consumer Packaging Market Foresight
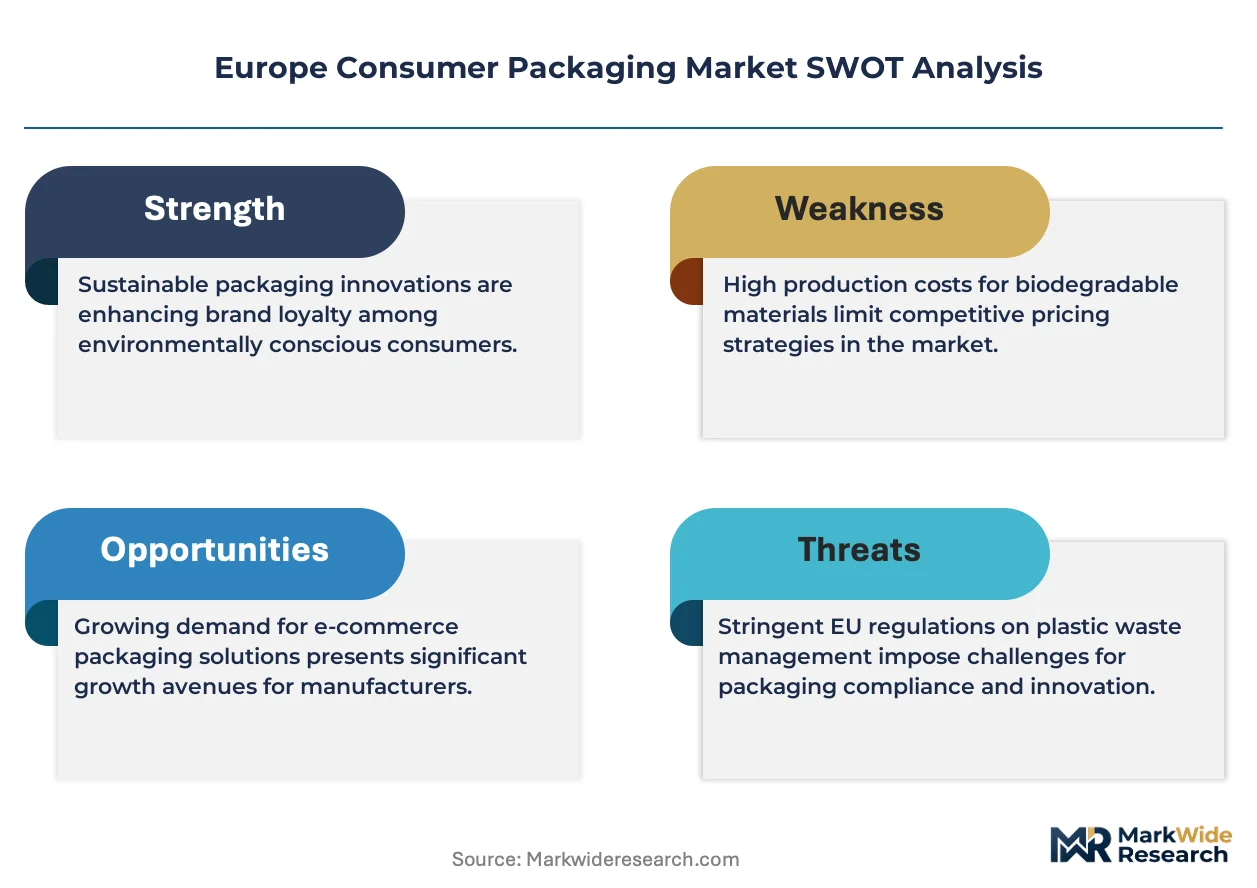
CE marking under the EU Packaging and Packaging Waste Regulation is rotating supplier eligibility toward circular-economy-compliant producers. Mondi Group leverages its integrated paper and recycling infrastructure across Central European mills. Amcor sustains flexible film leadership through polymer innovation labs in the Netherlands. Berry Global anchors rigid container supply for personal care brands with manufacturing scale in France and Italy.
Europe consumer packaging encompasses primary and secondary containment systems engineered from plastics, glass, paper, and metal, designed to protect goods through distribution while communicating brand identity and enabling shelf-stable preservation. Functional parameters include barrier properties against oxygen and moisture, seal integrity, and compatibility with automated filling lines at speeds exceeding 1,000 units per minute. Flexible packaging captures expanding margin pools in food and beverage as pouch formats replace rigid alternatives for sauces and ready-to-eat meals. Paper-based packaging leads volume in e-commerce secondary containment but faces pressure to match plastic's moisture resistance. Biodegradable packaging types remain niche due to limited industrial composting infrastructure across Eastern Europe.
The EU Packaging and Packaging Waste Regulation, REACH chemical compliance, and F-Gas Regulation for foamed insulation materials collectively reshape material selection and recyclability design rules. ECHA restrictions on per- and polyfluoroalkyl substances force reformulation of grease-resistant paper coatings used in fast-food applications. Stakeholders must monitor implementation timelines for extended producer responsibility fee structures and decide whether to internalize recycling operations or contract with licensed compliance schemes.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing design cycles across European converters, forcing simultaneous reformulation of barrier coatings and recycling-stream compatibility.
Growth Catalysts
- Recycled content mandates:The EU Packaging and Packaging Waste Regulation requires minimum recycled thresholds for plastic packaging by 2030, pulling investment toward chemical recycling infrastructure in Germany and the Netherlands.
- Fresh food retail expansion:Discounters across Poland and Romania are adopting modified-atmosphere packaging for proteins, accelerating demand for high-barrier films.
- Corrugated e-commerce surge:Benelux fulfillment centers are specifying FSC-certified board grades, tightening supply allocation for kraft liner mills.
Market Restraints
- Natural gas cost volatility:Glass furnace operations in Italy face input cost swings that compress margin visibility for container producers serving beverage brands.
- PFAS coating phaseout:ECHA restrictions on per- and polyfluoroalkyl substances eliminate existing grease-resistant paper formulations, forcing costly R&D pivots without drop-in replacements.
- Aluminum supply concentration:Primary metal sourcing for rigid cans clusters with Nordic smelters, exposing converters to energy-certificate price spikes.
Strategic Opportunities
- Industrial composting gaps:Biodegradable flexible packaging holds minimal share in Eastern Europe due to infrastructure absence, creating first-mover terrain for compostable film producers.
- Reusable packaging systems:France's anti-waste law incentivizes deposit-return schemes for personal care, opening B2B service models for rigid container pooling.
- Digital watermark integration:HolyGrail 2.0 sorting technology converging with printed electronics enables automated material identification, unlocking premium pricing for traceable packaging.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for bio-based barrier resins concentrates with retiring specialists in German research institutes.
- Extended producer responsibility fees:Compliance scheme registration timelines vary across member states, fragmenting financial planning for pan-European brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Consumer Packaging Market |
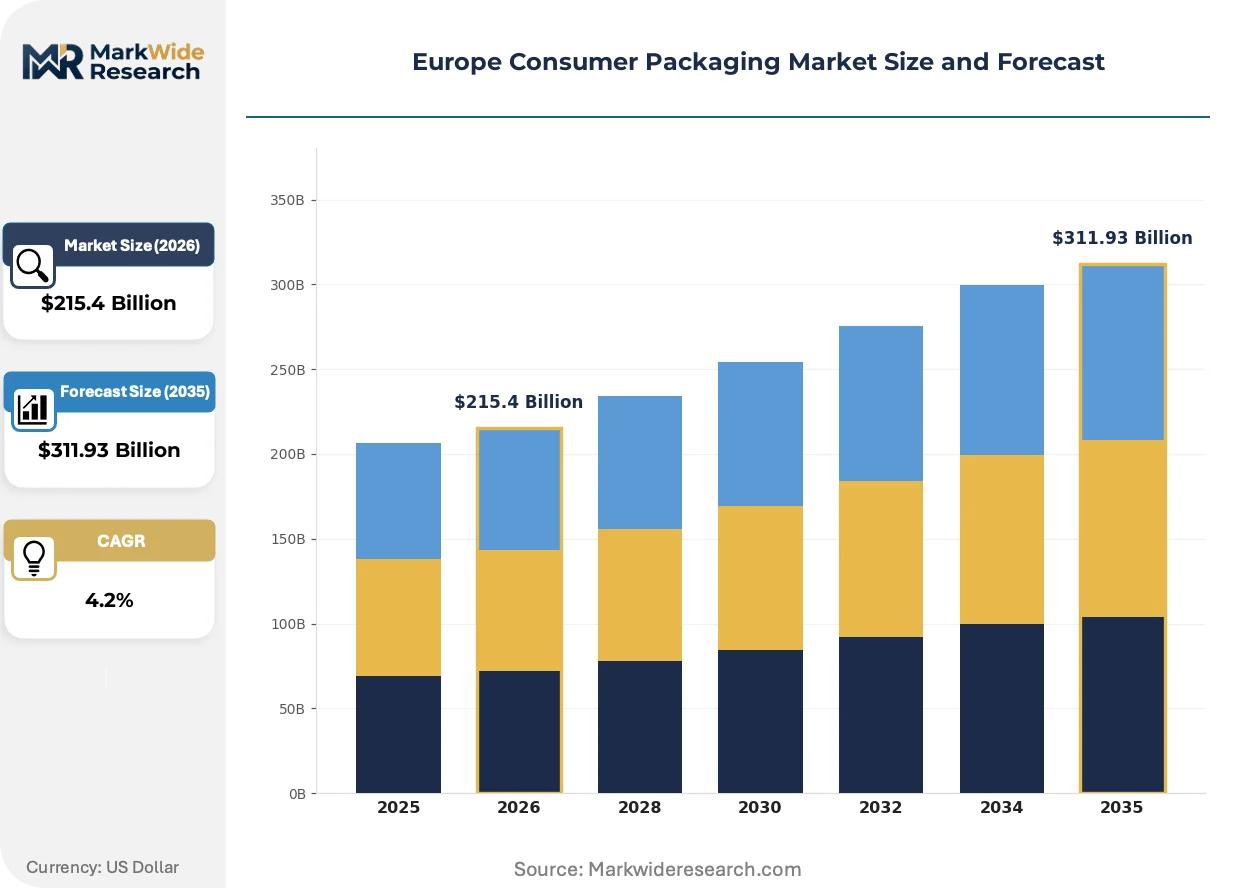
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $311.93 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Cans, Boxes, Pouches Material: Plastic, Glass, Paper, Metal End User: Food and Beverage, Personal Care, Household, Pharmaceuticals Packaging Type: Flexible, Rigid, Resealable, Biodegradable |
| Companies Covered | Berry Global, Mondi Group, Amcor, Huhtamaki Oyj, Tetra Pak, Smurfit Kappa, DS Smith, International Paper Company, Ardagh Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Consumer Packaging Market Shifts & Advancements
Material science breakthroughs and sorting infrastructure investments are collapsing traditional barriers between mechanical and chemical recycling pathways across European packaging value chains.
Mono-material flexible films engineered for polyethylene or polypropylene homogeneity are fragmenting established multilayer laminate supply chains. Food processors in Spain and Portugal are accelerating adoption for dry goods, collapsing the addressable market for aluminum-foil barrier layers and forcing adhesive suppliers to reformulate for single-substrate bonding.
REACH chemical compliance is extending reporting obligations to nanomaterial additives in food-contact applications. Packaging converters must now document safety data for antimicrobial silver particles and clay nanocomposites, with specialty pharmaceutical blisters in Switzerland and Austria facing the steepest documentation burdens.
Direct-to-store replenishment models are compressing secondary packaging specifications. Major grocery retailers in Sweden and Denmark are rejecting pre-printed corrugated displays in favor of generic brown boxes with applied labels, shifting value capture from converter graphics capabilities to in-house print operations at distribution centers.
Europe Consumer Packaging Market Segmentation
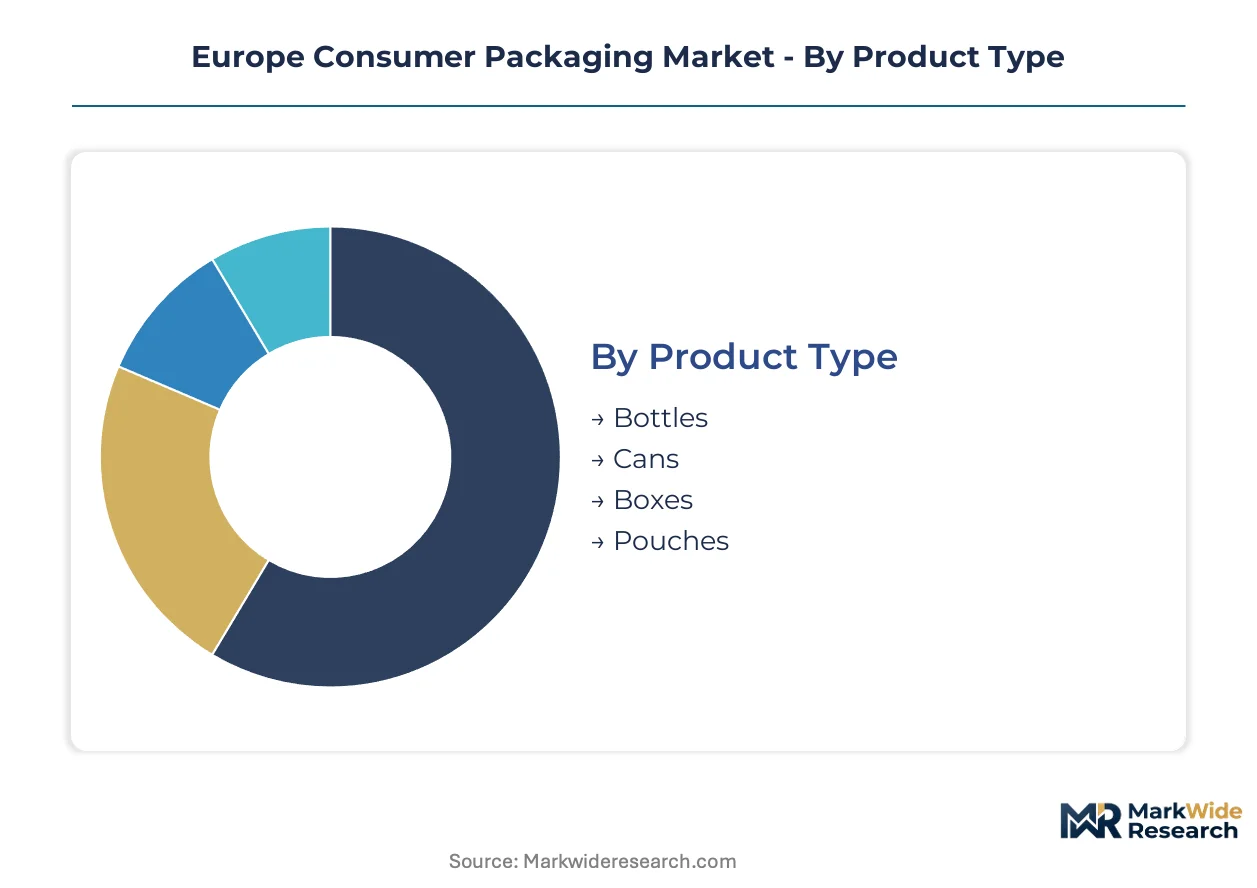
Packaging converters across Europe optimize production allocation by matching material capabilities to end-use barrier requirements. Segmentation clarity determines where chemical recycling investments yield compliant feedstock versus where mechanical pathways suffice.
Product Type:
Margin pools concentrate in formats that integrate high-barrier functionality with automated filling line compatibility at speeds exceeding 1,000 units per minute.
- Bottles:PET and HDPE extrusion blow-molded containers dominate beverage and personal care applications across Germany and France. Pharmaceutical-grade copolyester bottles for liquid prescriptions in Switzerland command specification premiums due to EMA extractables testing requirements.
- Cans:Two-piece aluminum beverage cans and three-piece steel food cans anchor metal packaging volume. Nordic smelter energy-certificate pricing volatility compresses converter margins for standard-diameter beverage formats.
- Boxes:Folding carton and corrugated formats span dry goods secondary containment through e-commerce primary shipping. Benelux fulfillment centers are tightening FSC-certified kraft liner specifications.
- Pouches:Spouted and fitment-equipped flexible formats displace rigid alternatives for sauces and ready-to-eat meals. Mono-material polyethylene homogeneity is fragmenting established multilayer laminate supply chains in Spain and Portugal.
Bottles hold installed capacity. Pouches are rotating up the share rankings.
Material:
Cost tier stratification separates commodity resin applications from specialty barrier substrates requiring REACH-compliant additive packages.
- Plastic:Polyethylene, polypropylene, and PET resins constitute volume leadership across flexible films and rigid containers. EU Packaging and Packaging Waste Regulation recycled content thresholds are pulling investment toward chemical recycling infrastructure in Germany and the Netherlands.
- Glass:Soda-lime container glass furnaces in Italy face natural gas input cost swings that compress margin visibility for beverage brand supply contracts. Amber and flint color specifications segment pharmaceutical from food-contact applications.
- Paper:Kraft liner and folding boxboard grades lead e-commerce secondary containment volume. ECHA restrictions on per- and polyfluoroalkyl substances eliminate existing grease-resistant coatings, forcing costly R&D pivots without drop-in replacements.
- Metal:Aluminum and tinplate substrates deliver oxygen and light barrier performance for shelf-stable proteins and beverages. Primary aluminum sourcing concentrates with Nordic smelters, exposing converters to energy-certificate price spikes.
Plastic holds installed capacity. Paper is rotating up the share rankings.
End User:
Application-specific barrier requirements drive material selection divergence between moisture-sensitive pharmaceuticals and oxygen-critical food preservation.
- Food and Beverage:Modified-atmosphere packaging for proteins and high-barrier films for dry goods dominate flexible format demand. Discounters across Poland and Romania are accelerating pouch adoption for private-label ready-to-eat meals.
- Personal Care:Rigid containers for creams and lotions prioritize aesthetic surface finish and pump-actuated dispensing precision. France's anti-waste law incentivizes deposit-return schemes, opening B2B service models for rigid container pooling.
- Household:Trigger-spray bottles and refill pouches balance chemical resistance with lightweighting targets. Concentrate and dilutable formats are compressing secondary packaging specifications for major grocery retailers in Sweden and Denmark.
- Pharmaceuticals:Blister packs, vials, and compliance-enabled containers demand extractables documentation and child-resistant closure integration. REACH reporting obligations for nanomaterial additives impose steepest documentation burdens in Switzerland and Austria.
Food and Beverage holds installed capacity. Pharmaceuticals is rotating up the share rankings.
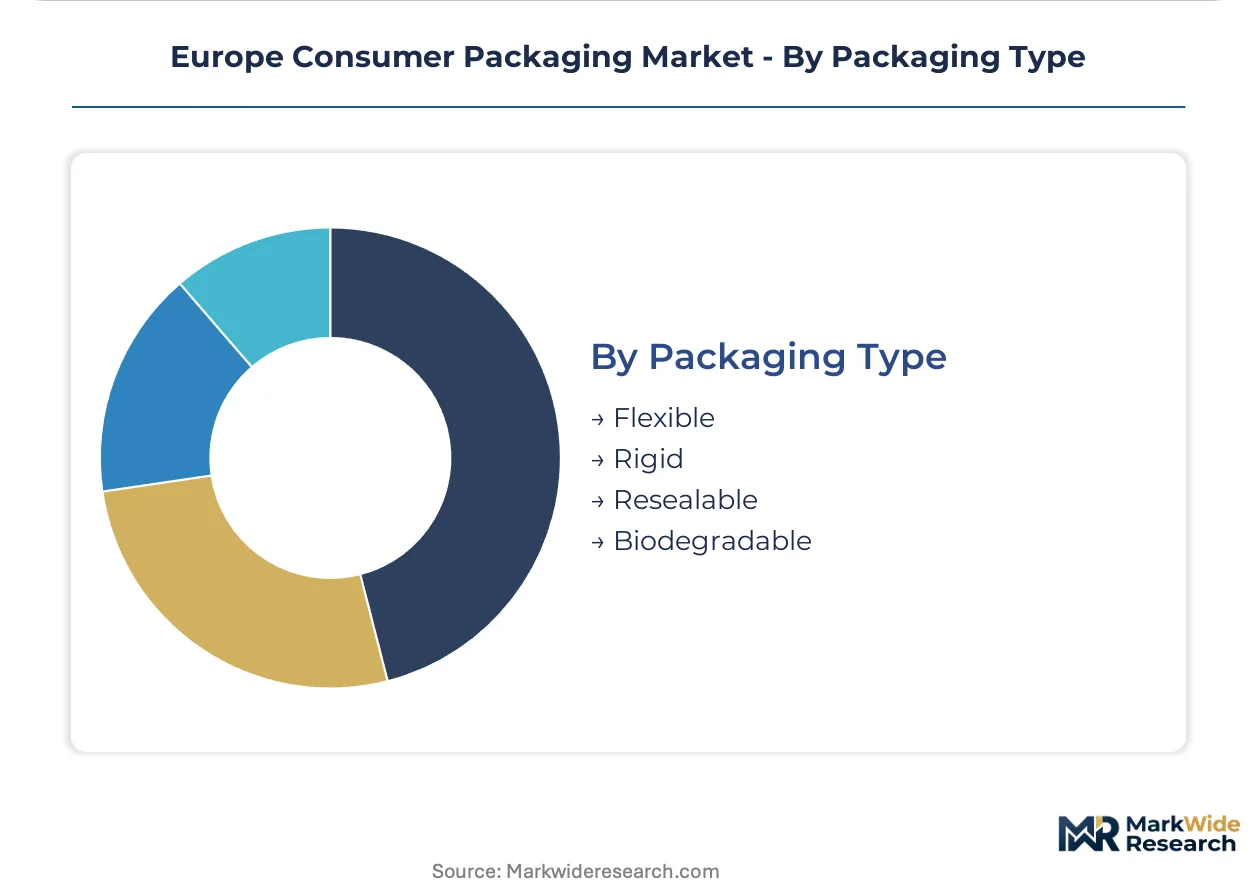
Packaging Type:
Volume concentration favors established flexible and rigid categories while emerging formats face infrastructure-dependent adoption constraints.
- Flexible:Films, pouches, and wraps capture expanding margin pools as pouch formats replace rigid alternatives. Mono-material polyethylene and polypropylene homogeneity is collapsing the addressable market for aluminum-foil barrier layers.
- Rigid:Bottles, jars, and containers maintain structural integrity for stacking and display requirements. Manufacturing scale in France and Italy anchors supply for personal care brands with short lead-time requirements.
- Resealable:Zipper-equipped pouches and threaded closures extend product shelf life after initial opening. Convenience positioning commands specification premiums in snack and prepared food segments across German retail chains.
- Biodegradable:Industrial compostable films and molded pulp formats remain niche due to limited composting infrastructure across Eastern Europe. First-mover terrain exists for producers establishing collection and processing partnerships.
Flexible holds installed capacity. Biodegradable is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Discounters and e-commerce fulfillment operators concentrate procurement power across Northern and Western Europe, while regulatory enforcement tightens recycled content thresholds in Germany and France.
Germany
Modified-atmosphere packaging for proteins and chemical recycling infrastructure investments dominate converter activity. The EU Packaging and Packaging Waste Regulation mandates minimum recycled plastic thresholds by 2030, pulling capital toward pyrolysis facilities in the Rhine-Ruhr industrial corridor. Berlin-Brandenburg logistics clusters are piloting reusable container pooling for personal care brands under the national packaging act.
France
Deposit-return schemes for personal care rigid containers and anti-waste law compliance reshape B2B service models. The AGEC law incentivizes packaging reduction targets that exceed EU baselines. The Lyon-Saint-Étienne manufacturing belt anchors rigid container supply for cosmetic brands with short lead-time requirements.
Netherlands
Polymer innovation labs and flexible film leadership concentrate near Rotterdam petrochemical feedstock access. REACH chemical compliance documentation obligations extend to nanomaterial additives in food-contact applications. The Eindhoven-Tilburg corridor houses pilot facilities for HolyGrail 2.0 digital watermark sorting technology integration.
Italy
Glass furnace operations for beverage containers face natural gas input cost volatility that compresses margin visibility. Amber and flint color specifications segment pharmaceutical from food-contact applications. The Veneto glassmaking district around Venice anchors specialty container supply for premium wine and spirits brands.
Poland
Discounter expansion accelerates pouch adoption for private-label ready-to-eat meals and modified-atmosphere packaging for proteins. Extended producer responsibility fee structures lag Western implementation timelines, fragmenting financial planning for pan-European brand owners. The Warsaw-Łódź corridor concentrates flexible film converting capacity for Central European distribution.
Europe Consumer Packaging Market Competitive Landscape
Player mix skews toward integrated paper-and-packaging conglomerates with captive recycling infrastructure and specialized flexible film innovators with polymer formulation depth. Market structure consolidates around three strategic archetypes: vertically integrated fiber-based packaging groups controlling pulp-to-box value chains, multinational flexible packaging specialists leveraging polymer science platforms, and regional rigid container fabricators serving personal care and beverage niches. Dominant competitive moves include chemical recycling infrastructure partnerships and mono-material film platform acquisitions that collapse multilayer laminate supply chains.
Among integrated paper-and-packaging groups, Mondi Group and Smurfit Kappa exemplify the fiber-based archetype with captive recycling infrastructure and corrugated board leadership. Amcor occupies a position within the flexible packaging tier, representing multinational polymer science capabilities. These three anchors illustrate how scale and material integration separate tier-one positioning from regional competitors.
| Leading Market Players |
|---|
| Berry Global |
| Mondi Group |
| Amcor |
| Huhtamaki Oyj |
| Tetra Pak |
| Smurfit Kappa |
| DS Smith |
| International Paper Company |
| Ardagh Group |
| Others |
Supply & Pricing Matrix
Mono-material polyethylene substitution for multilayer laminates simultaneously redistributes converting capacity toward Central European polymer hubs and compresses pricing premiums previously captured by aluminum-foil barrier layers. This displacement dynamic tightens margin pools for incumbent laminate suppliers while rewarding converters with extrusion blow-molding scale in Germany and the Netherlands.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate glass container supply agreements for Italian beverage producers. Three-tier pricing structure across pharmaceutical-grade copolyester, food-contact PET, and standard HDPE separates specification premiums by EMA extractables testing requirements and barrier performance tiers. Pricing pressure stems from Nordic smelter energy-certificate volatility feeding aluminum can sheet costs. Private-label discounters in Poland exhibit highest price sensitivity; Swiss pharmaceutical brands demonstrate lowest.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for kraft liner imports serving Benelux e-commerce fulfillment centers. Primary supply concentrates in Germany, France, and Italy for rigid containers; Nordic countries for primary aluminum; and Poland for flexible film converting. Raw material dependencies encompass polyethylene resins, soda-lime glass batch, and FSC-certified pulp. Single-source vulnerability runs through Nordic smelter energy-certificate availability. Distribution runs through pan-European brand owner procurement hubs coordinating converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as mono-material flexible films displace established multilayer barrier structures. Incumbents must navigate polymer formulation expertise scarcity while repositioning chemical recycling assets as compliance-enabling infrastructure.
For Market Incumbents: Consolidate chemical recycling partnerships in the Rhine-Ruhr corridor to secure EU Packaging and Packaging Waste Regulation-compliant feedstock ahead of 2030 thresholds. Acquire mono-material film platform capabilities in Spain and Portugal to offset collapsing aluminum-foil laminate demand. Backward integration into pyrolysis operations anchors margin defense against polymer resin volatility.
For New Entrants and Emerging Players: Lead with industrial compostable film production targeting Eastern European markets where infrastructure gaps create first-mover terrain. Establish collection and processing partnerships in Poland and Romania before Western competitors extend compliance schemes eastward. Position around HolyGrail 2.0 digital watermark integration as a premium sorting-enabling service for brand owners.
For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation recycled content mandates reshape the acquisition landscape toward chemical recycling infrastructure and mono-material formulation platforms. Long-term viability centers on converters with captive recycling operations and polymer science depth. Target integrated paper-and-packaging groups with FSC-certified kraft liner supply chains. Watch ECHA PFAS restriction implementation timelines as margin inflection signals for grease-resistant paper coating reformulation.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Infrastructure Partnership | Pyrolysis facilities in Germany and the Netherlands secure EU-compliant plastic feedstock. |
| Mono-Material Film Platform Acquisition | Polyethylene homogeneity expertise collapses multilayer laminate supply chain relevance in Iberia. |
| Digital Watermark Technology Integration | HolyGrail 2.0 sorting enables automated material identification for premium traceability pricing. |
| Reusable Container Pooling Service Launch | France's anti-waste law incentivizes deposit-return schemes for personal care rigid packaging. |
| Backward Integration into Captive Recycling | In-house pulp-to-box operations defend fiber-based packaging margins against virgin pulp volatility. |
Research Methodology
A spread of perspectives from packaging procurement directors at major retail chains, polymer R&D leads at flexible film converters, corrugated plant managers, and regulatory compliance officers converged on the working assumptions. Primary fieldwork combined with secondary validation against EU Packaging and Packaging Waste Regulation implementation documents, ECHA restriction dossiers, FSC certification databases, and customs trade data for kraft liner and polymer resin flows. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Segmentation dimensions modeled encompass product type, material substrate, end-use application, and packaging format flexibility across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and substitution elasticity parameters. Industry-specific forecast inputs included chemical recycling capacity buildout schedules and mono-material film adoption curves by food processor segment.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or alternative material breakthrough timelines would require recalibration. Forecasts reflect documented assumptions regarding recycled content mandate implementation and natural gas price normalization for glass furnace operations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Myanmar Packaging Market
Packaging Materials
Crimped End Mailing Tubes Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Flow Wraps Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Absorbent Tray Liners Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Non-Breathable Films Market
Packaging Materials
Packaging Materials Market
Packaging Materials
Global Anti-Static Films Market