
 Saudi Arabia Flexible Plastic Packaging Market | 2026-2036
Saudi Arabia Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Flexible Plastic Packaging Market Insights
Food and beverage demand is decoupling from rigid formats as dairy, snack, and ready-meal producers shift toward lightweight flexible solutions. Napco National leverages integrated film extrusion and printing capabilities to anchor supply for domestic FMCG brands. Zamil Plastic Industries competes through scale in polyethylene and polypropylene conversion across Gulf markets. Sealed Air Corporation differentiates via barrier technology leadership for modified-atmosphere food packaging.
Saudi Arabia flexible plastic packaging comprises polymer-based films, laminates, and formed pouches typically manufactured through blown film extrusion, cast extrusion, or lamination processes, with thicknesses ranging from twenty micrometers to several hundred micrometers depending on barrier requirements. These materials serve primarily to extend shelf life, reduce transport weight, and enable unit-dose or portion-control formats across consumer and industrial supply chains. Stand-up pouches capture expanding share in food and beverage as brand owners prioritize shelf differentiation and material reduction. Polyethylene dominates material demand due to cost position and recyclability alignment with emerging producer responsibility frameworks. E-commerce providers represent the fastest-growing end-user channel as last-mile delivery requirements reshape primary and secondary packaging specifications.
SFDA mandates govern direct food-contact materials, while SASO technical regulations enforce labeling and compositional standards for plastics placed on the Saudi market. The Saudi Green Initiative and circular economy policy signals are forcing converters to certify recyclability pathways and reduce multi-material complexity. Stakeholders must monitor evolving extended producer responsibility implementation and decide between mono-material redesign investments versus chemical recycling partnerships before compliance deadlines harden.
Market Dynamics
SFDA packaging safety mandates and the Saudi Green Initiative are forcing converters to abandon multi-layer laminates in favor of mono-material structures, compressing design cycles and rewiring supplier relationships across the value chain.
Growth Catalysts
- SFDA food-contact compliance deadlines:Safety certification requirements for direct-contact materials are pulling domestic converters toward certified barrier films and documented migration testing.
- E-commerce fulfillment expansion:Last-mile delivery networks in Riyadh and Jeddah are specifying lightweight, damage-resistant pouch formats over corrugated secondary packaging.
- Polyethylene recyclability alignment:Mono-material PE structures are capturing share as the Saudi Green Initiative signals extended producer responsibility implementation.
Market Restraints
- Ethylene feedstock volatility:Crude-linked naphtha pricing transmits directly to polyethylene resin costs, squeezing converter margins without pass-through mechanisms.
- Barrier film import dependence:High-performance oxygen and moisture barrier substrates concentrate among GCC petrochemical complexes outside Saudi borders.
- Multi-material legacy infrastructure:Existing lamination and solvent-based adhesive capacity resists rapid mono-material retrofit without substantial capital redeployment.
Strategic Opportunities
- Western Province dairy processing:Jeddah-based yogurt and laban producers are specifying aseptic pouch formats previously served by rigid HDPE bottles.
- Digital printing convergence:HP Indigo and EFI single-pass systems are enabling run-length flexibility and SKU proliferation for regional FMCG brands.
- Reverse logistics channel innovation:Loop-style refillable pouch pilots are testing consumer acceptance for personal care concentrates in Riyadh metropolitan zones.
Industry Challenges
- Mono-material re-engineering talent:Formulation chemists capable of matching barrier performance without ethylene-vinyl alcohol layers command scarcity premiums.
- SFDA certification timeline compression:Migration testing and safety dossier preparation for novel structures extends commercialization cycles beyond brand owner launch windows.
- Legacy solvent recovery systems:Converters with established adhesive lamination lines face stranded asset risk as water-based and extrusion lamination displace incumbent processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Flexible Plastic Packaging Market |
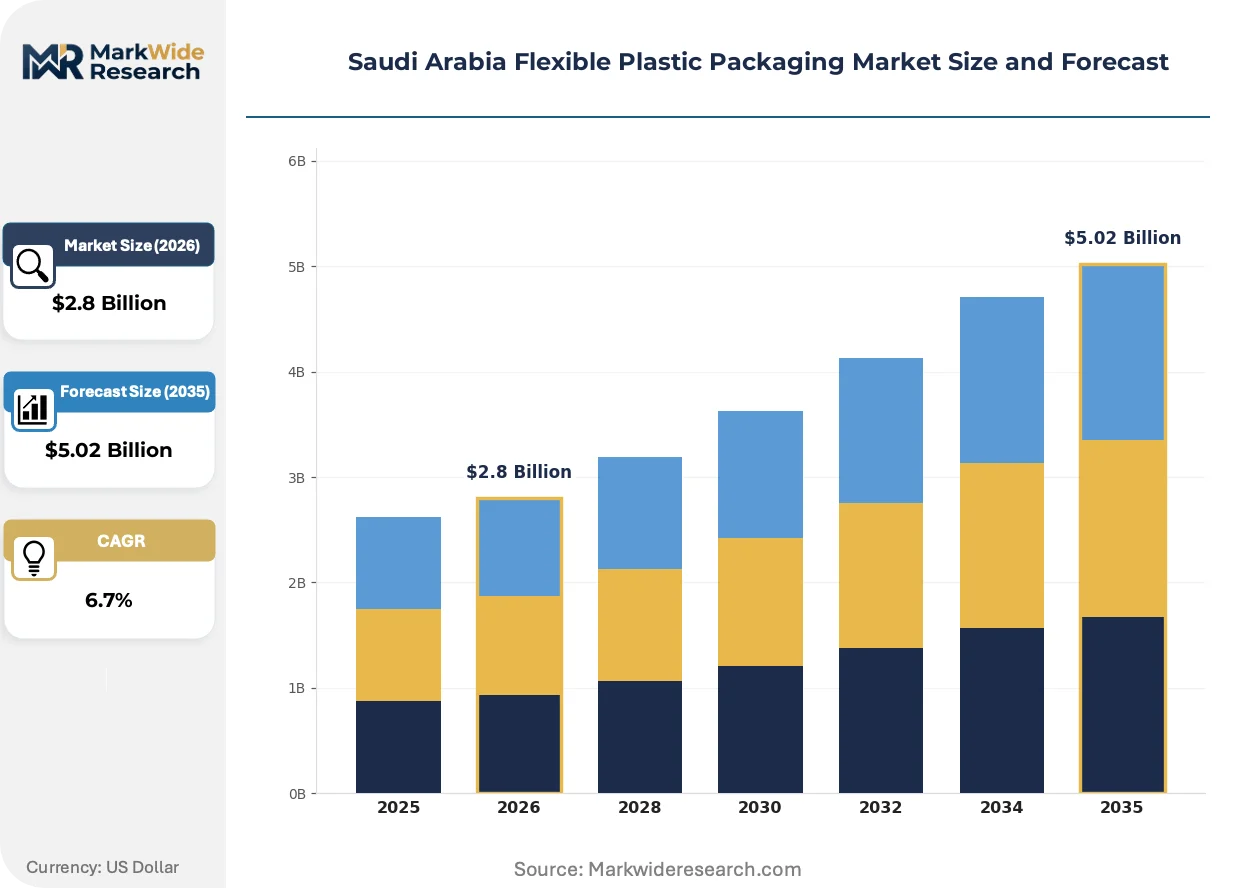
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Stand-Up Pouches, Roll Stock, Shrink Films Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester Application: Food and Beverage, Healthcare, Personal Care, Household Supplies End User: Manufacturers, Retailers, Wholesalers, E-commerce Providers |
| Companies Covered | Napco National, Zamil Plastic Industries, Sealed Air Corporation, National Plastic Factory, Saudi Plastic Factory Company, Obeikan Investment Group, ENPI Group, Sonoco Products Company, ASPCO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Flexible Plastic Packaging Market Trends and Innovations
Digital manufacturing and regulatory compliance technologies are compressing product development cycles while sustainability imperatives force material science breakthroughs across the Saudi packaging base.
Blown film extrusion with in-line thickness gauging and automated profile control is automating gauge consistency and reducing resin giveaway in high-volume polyethylene production. Dairy and snack converters in Riyadh industrial zones are adopting these systems at replacement-cycle pace. Quality variance and manual inspection labor are compressing as closed-loop control becomes standard.
SFDA technical regulations for food-contact plastics are hardening documentation requirements for migration testing and substance inventories. Converters must now maintain batch-level traceability and supplier certification dossiers. Stand-up pouch formats for ready-to-eat meals face the steepest compliance burden as direct-contact surface area ratios intensify regulatory scrutiny.
Brand owners are consolidating supplier panels and specifying certified recyclable structures ahead of formal extended producer responsibility mandates. Procurement teams at major FMCG houses are disqualifying multi-material laminates from new product briefs. This preference shift is most visible in Jeddah-based beverage and condiment categories where shelf differentiation must now align with circular economy credentials.
Saudi Arabia Flexible Plastic Packaging Market Segmentation
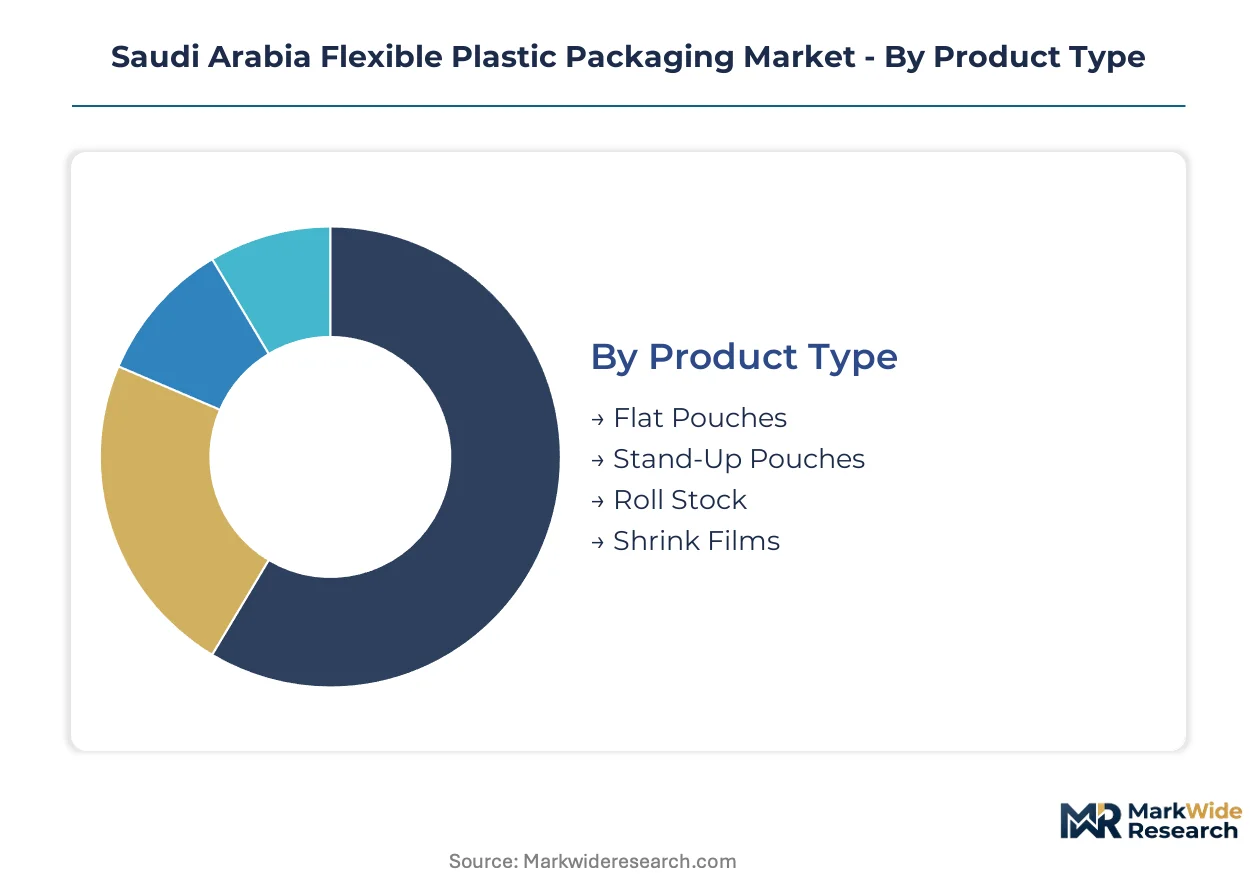
Flexible plastic packaging in Saudi Arabia fragments across four axes that determine specification requirements, cost structures, and regulatory exposure. Product geometry dictates machinery compatibility and shelf presence. Material chemistry governs recyclability compliance under the Saudi Green Initiative.
Product Type:
Blown and cast extrusion capabilities across Riyadh and Jeddah industrial zones shape which formats converters can deliver at scale.
- Flat Pouches:Two-dimensional sealed bags manufactured through horizontal or vertical form-fill-seal lines. Dairy portion packs and condiment sachets in Jeddah food processing clusters specify high-clarity polyethylene variants to meet SFDA migration limits.
- Stand-Up Pouches:Gusseted bottom structures with integrated reseal features. Riyadh-based snack and ready-meal producers are specifying these for shelf differentiation in modern trade formats, though the bottom weld geometry complicates mono-material redesign for recyclability certification.
- Roll Stock:Unformed film supplied to downstream converters and brand-owner packaging lines. Industrial bakeries in the Western Province represent concentrated demand for printed roll stock with modified atmosphere barrier properties.
- Shrink Films:Biaxially oriented or blown polyethylene formulations that contract under heat application. Beverage multipacks for retail distribution in Jeddah and Dammam use printed shrink bundling to replace corrugated secondary packaging.
Flat pouches lead on scale; stand-up pouches lead on momentum.
Material:
Polymer selection balances barrier performance against circular economy compliance timelines.
- Polyethylene:Dominant flexible packaging polymer spanning LDPE, LLDPE, and HDPE grades. SFDA food-contact certification and Saudi Green Initiative recyclability alignment are pulling converters toward mono-material PE structures for dairy and snack applications.
- Polypropylene:Higher temperature resistance and stiffness versus polyethylene. Retort pouch specifications for ambient-stable ready meals in Riyadh specify cast PP or oriented PP when sterilization protocols exceed PE thermal limits.
- Polyvinyl Chloride:Clarity and shrink performance advantages offset by halogen content and mechanical recycling contamination risks. Pharmaceutical blister and personal care applications in Jeddah represent residual demand pockets.
- Polyester:Biaxially oriented PET films provide oxygen barrier and print surface quality. Premium condiment and specialty food segments specify PET-containing laminates despite multi-material complexity penalties under emerging extended producer responsibility frameworks.
Polyethylene dominates installed volume; polypropylene is climbing the fastest as retort-capable formats expand.
Application:
End-use sector requirements determine barrier specifications, sterilization protocols, and regulatory documentation burdens.
- Food and Beverage:Largest application sector spanning ambient, chilled, and frozen supply chains. SFDA migration testing and shelf-life extension requirements are forcing laminated structures toward certified barrier films with documented substance inventories.
- Healthcare:Sterile barrier systems for medical devices and pharmaceutical primary packaging. SFDA medical device regulations and Gulf harmonization initiatives are tightening validation requirements for form-fill-seal operations in Dammam industrial zones.
- Personal Care:Unit-dose and refill pouch formats for shampoo, conditioner, and skincare concentrates. Riyadh metropolitan consumers are testing Loop-style refillable pilots that reverse logistics requirements back to converters.
- Household Supplies:Detergent pods, surface cleaner refills, and air care products. E-commerce fulfillment specifications from Jeddah-based platforms are driving puncture-resistant film development for liquid concentrate shipping.
Food and beverage anchors revenue; personal care shows steepest expansion trajectory.
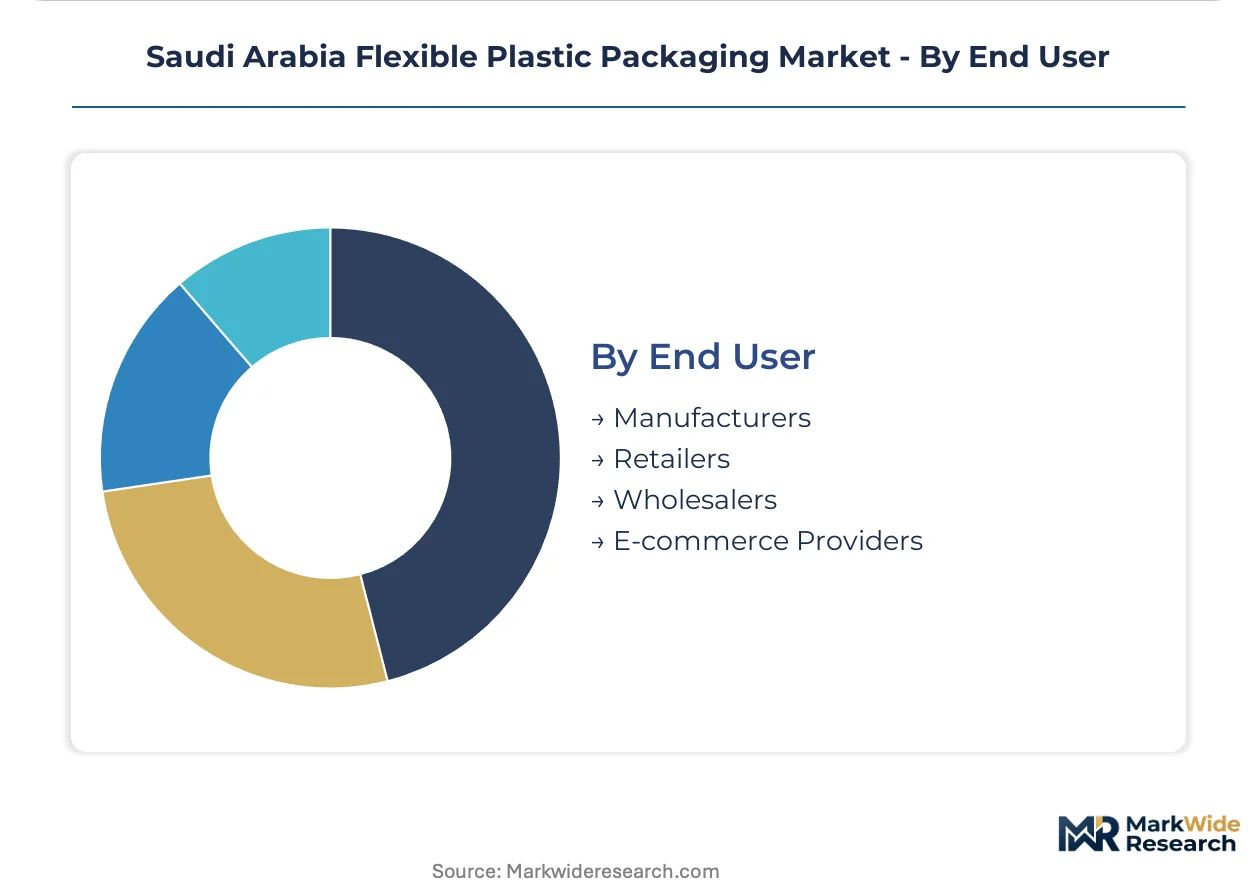
End User:
Channel structure determines order characteristics, print complexity, and service requirements.
- Manufacturers:Brand-owner packaging operations with integrated or toll-based converting relationships. Saudi dairy processors in Al Kharj and Al Qassim specify long-term supply agreements with dedicated extrusion capacity.
- Retailers:Private label and controlled-brand packaging procurement teams. Hypermarket chains in Riyadh and Jeddah are consolidating supplier panels and specifying certified recyclable structures for shelf-ready formats.
- Wholesalers:Intermediate distribution of unprinted or generically printed stock. Traditional trade coverage in secondary cities relies on wholesale channel flexibility for fragmented SKU demand.
- E-commerce Providers:Platform-controlled packaging specifications for last-mile delivery. Noon and Amazon.sa fulfillment centers are specifying lightweight, damage-resistant pouch formats that displace corrugated secondary packaging.
Manufacturers retain volume concentration; e-commerce providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters are relocating extrusion capacity toward jurisdictions with lighter compliance burdens, though SFDA migration-testing requirements and Saudi Green Initiative timelines are compressing that arbitrage window. Domestic producers in Riyadh and Jeddah industrial zones are absorbing volume that might otherwise migrate to lower-cost GCC neighbors.
Riyadh
Dairy processors in Al Kharj and snack manufacturers in the capital district are specifying mono-material polyethylene pouches ahead of extended producer responsibility implementation. SFDA food-contact certification requirements are pulling converters toward documented barrier-film supply chains. The Riyadh industrial corridor hosts the densest concentration of blown-film extrusion lines serving domestic FMCG brands.
Eastern Province
Petrochemical feedstock integration gives Dammam-based converters cost advantages in resin procurement for high-volume polyethylene production. The Saudi Green Initiative recyclability mandates are accelerating transitions from multi-layer laminates toward certified mono-material structures. Industrial bakeries and ambient-food processors in the Dammam metropolitan zone represent concentrated demand for modified-atmosphere roll stock.
Western Region
Jeddah-based yogurt and laban producers are displacing rigid HDPE bottles with aseptic flexible pouches for portion-control formats. E-commerce fulfillment platforms including Noon and Amazon.sa are specifying lightweight damage-resistant pouch formats for last-mile delivery. The Jeddah Islamic Port logistics corridor enables barrier-film import flows that domestic extrusion capacity cannot yet match.
NEOM Northwest
Circular-economy pilot programs in the giga-project zone are testing closed-loop packaging return systems for personal care concentrates. SFDA regulatory harmonization with Gulf standards is simplifying cross-border certification for converters supplying the zone. NEOM procurement specifications are disqualifying multi-material laminates from packaging tenders ahead of formal mandates.
Saudi Arabia Flexible Plastic Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as converters add blown-film lines to capture mono-material demand ahead of compliance deadlines. The vendor base clusters around three tiers: integrated petrochemical-to-film producers with captive resin supply, mid-scale converters with extrusion and printing capabilities, and specialized barrier-film importers serving premium segments. Strategic archetypes include feedstock-integrated conglomerates, regional FMCG-dedicated suppliers, and multinational technology licensors. Competitive intensity concentrates on M&A activity targeting extrusion assets and strategic partnerships with brand owners for certified recyclable structure development.
Among domestic integrated producers, Napco National and Zamil Plastic Industries exemplify the feedstock-advantaged archetype with extrusion and printing capabilities spanning polyethylene and polypropylene conversion. Sealed Air Corporation occupies the multinational technology-licensor position, anchoring the premium barrier-film segment through modified-atmosphere packaging expertise. These three represent the competitive poles around which mid-scale converters and regional specialists are repositioning.
| Leading Market Players |
|---|
| Napco National |
| Zamil Plastic Industries |
| Sealed Air Corporation |
| National Plastic Factory |
| Saudi Plastic Factory Company |
| Obeikan Investment Group |
| ENPI Group |
| Sonoco Products Company |
| ASPCO |
| Others |
Pricing and Supply Chain Analysis
Blown-film extrusion operators in Riyadh industrial zones command wage premiums that compress pricing spreads between commodity-grade polyethylene roll stock and certified mono-material barrier films. SFDA migration-testing requirements and Saudi Green Initiative recyclability mandates are widening tier differentials as certified converters capture margin from uncertified competitors.
Pricing Analysis
Distributor margins on imported barrier substrates absorb the steepest compression as domestic extrusion capacity expands. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-certified mono-material structures from legacy multi-layer laminates and generic polyethylene commodity grades. Price differentiation hinges on certification tier and volume scale, with bulk dairy processors extracting favorable terms against fragmented personal care brands. Cost compression in standard-tier polyethylene is intensifying because ethylene feedstock volatility transmits directly without pass-through mechanisms. E-commerce fulfillment platforms exhibit lowest price sensitivity, prioritizing damage-resistant specifications over unit cost.
Supply Chain Analysis
Returns of multi-material laminate scrap face mounting friction as recyclability certification hardens, forcing converters to re-engineer collection flows or absorb disposal premiums. Resin supply concentrates in Saudi Arabia, Qatar, and Kuwait, with GCC petrochemical complexes feeding domestic extrusion lines. Raw material dependencies center on naphtha-derived polyethylene, imported ethylene-vinyl alcohol barrier resins, and specialty adhesive formulations. Single-source vulnerability runs through high-performance oxygen barrier substrates concentrated among complexes outside Saudi borders. Distribution runs through direct mill relationships with Riyadh and Jeddah dairy processors, supplemented by wholesale channels serving traditional trade in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Saudi flexible packaging rests on mono-material redesign execution that converts regulatory compliance burden into premium-tier pricing power ahead of formal extended producer responsibility implementation.
For Market Incumbents: Deploy backward integration into captive resin compounding to lock in polyethylene supply security against GCC feedstock competition. Consolidate extrusion assets in Riyadh and Jeddah industrial zones to capture scale efficiencies as SFDA certification timelines compress. Multi-material legacy infrastructure represents stranded asset risk; accelerate water-based and extrusion lamination retrofit before compliance deadlines harden. For New Entrants and Emerging Players: Regional FMCG brands with limited technical packaging staff represent the most penetrable buyer archetype, underserved by incumbent converter technical service capabilities. Target white-space in digital-printed short-run pouch formats for SKU-proliferating snack startups in Riyadh metropolitan zones. Partner with HP Indigo or EFI single-pass system distributors for equipment-light market entry without capital-intensive extrusion investment. For Investors and Strategic Acquirers: Integrated petrochemical conglomerates are the most active acquirer in this space, seeking downstream film extrusion assets to capture value chain margin. Long-term viability favors converters with demonstrated mono-material barrier performance and established SFDA certification dossiers. Watch for Loop-style refillable pouch pilot expansion signals as inflection indicator for reverse-logistics infrastructure investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Redesign Investment | SFDA certification and Saudi Green Initiative alignment convert compliance burden into premium-tier pricing power. |
| Digital Printing Capability Addition | HP Indigo and EFI single-pass systems enable run-length flexibility for SKU-proliferating regional FMCG brands. |
| Backward Integration into Resin Compounding | Captive polyethylene supply security mitigates ethylene feedstock volatility transmission to converter margins. |
| Reverse Logistics Channel Partnership | Loop-style refillable pouch pilots test consumer acceptance and infrastructure requirements for personal care concentrates. |
| SFDA Certification Dossier Acceleration | Documented migration testing and substance inventories compress commercialization cycles for novel barrier structures. |
Research Methodology
Coverage spans Riyadh, Jeddah, Dammam, and NEOM Northwest zones, with primary inputs from each. The analysis combines structured interviews with blown-film extrusion plant managers, procurement leads at dairy and snack processors, SFDA regulatory affairs specialists, and e-commerce fulfillment operations directors with secondary validation. Sources include SASO technical regulations, SFDA food-contact guidance documents, Saudi Customs trade data, and GCC petrochemical industry disclosures. Bottom-up capacity and demand estimates triangulate against top-down value chain spend analysis.
Rate-of-change decomposition separates volume growth from mix-shift and price-tier migration effects across the projection horizon. Segmentation dimensions span product geometry, polymer chemistry, end-use application, and channel structure, with additional granularity on certification status and digital-print adoption. CAGRs derive from fitted growth curves calibrated to historical capacity expansion patterns and announced extrusion line investments. Industry-specific inputs include ethylene-naphtha spread trajectories and SFDA compliance timeline assumptions.
Underlying measurement precision varies by segment; polyethylene commodity grades and established food-contact applications carry tighter precision than emerging mono-material barrier structures and personal care refill formats. Forecasts reflect assumptions on regulatory implementation pace, feedstock cost transmission mechanisms, and consumer acceptance of sustainable packaging premiums. Practitioners should monitor SFDA guidance publication timing, extended producer responsibility draft regulations, and Loop pilot expansion signals for early indicators of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
Canada Flexible Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
Latin America Flexible Plastic Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Flexible Intermediate Bulk Container Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market