
 Asia-Pacific Airless Packaging Market | 2026-2036
Asia-Pacific Airless Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Airless Packaging Market Outlook
Refill subscription programs for premium skincare is realigning how airless packaging gets monetized in the Asia-Pacific region. AptarGroup Inc leverages its pump technology leadership to anchor long-term supply relationships with Korean beauty conglomerates. Silgan Holdings Inc sustains manufacturing scale across multiple Asian production hubs. Albea S.A. differentiates through specialized decorative finishing capabilities that command premium positioning in Japanese cosmetic markets.
Asia-Pacific airless packaging employs evacuated chamber designs, piston-driven dispensing mechanisms, or collapsible inner bags to eliminate air contact with product contents, typically achieving oxygen exclusion rates critical for preserving oxidation-sensitive formulations like retinoids and vitamin C serums. Cosmetic containers dominate current volume shipments across the region, while pharmaceutical bottles represent the fastest-expanding application as India's CDSCO tightens stability requirements for topical drug delivery systems. Vacuum technology leads installed capacity, though bag-on-valve formats are gaining share in aerosol-alternative personal care segments where propellant-free dispensing carries regulatory and consumer preference advantages.
China's SAMR enforces GB standards for plastic contact materials that directly determine which airless pump assemblies qualify for domestic cosmetic distribution. India's BIS certification requirements for imported packaging components create compliance thresholds that filter supplier participation in its rapidly formalizing beauty market. Japan's METI chemical substance regulations under the Act on the Evaluation of Chemical Substances shape material selection for brands serving its precision-oriented consumer base. Stakeholders must monitor how diverging national material safety frameworks affect cross-border component sourcing strategies and localized mold-investment decisions.
Market Dynamics
Refillable airless systems are compressing traditional single-use packaging economics across the Asia-Pacific region, forcing contract manufacturers to retool mold investments toward modular pump architectures that accommodate cartridge replacement mechanisms.
Growth Catalysts
- CDSCO stability mandates:India's tightened requirements for topical pharmaceutical packaging are accelerating qualified airless bottle adoption by domestic generic drug manufacturers seeking export certification.
- Guangdong contract manufacturing cluster:Concentrated production capacity in China's southern province enables rapid prototyping turnaround for Korean beauty brands launching limited-edition serum lines.
- Bag-on-valve technology:Propellant-free dispensing formats are capturing aerosol-alternative segments in Australian and Japanese personal care markets where environmental labeling carries shelf-positioning weight.
Market Restraints
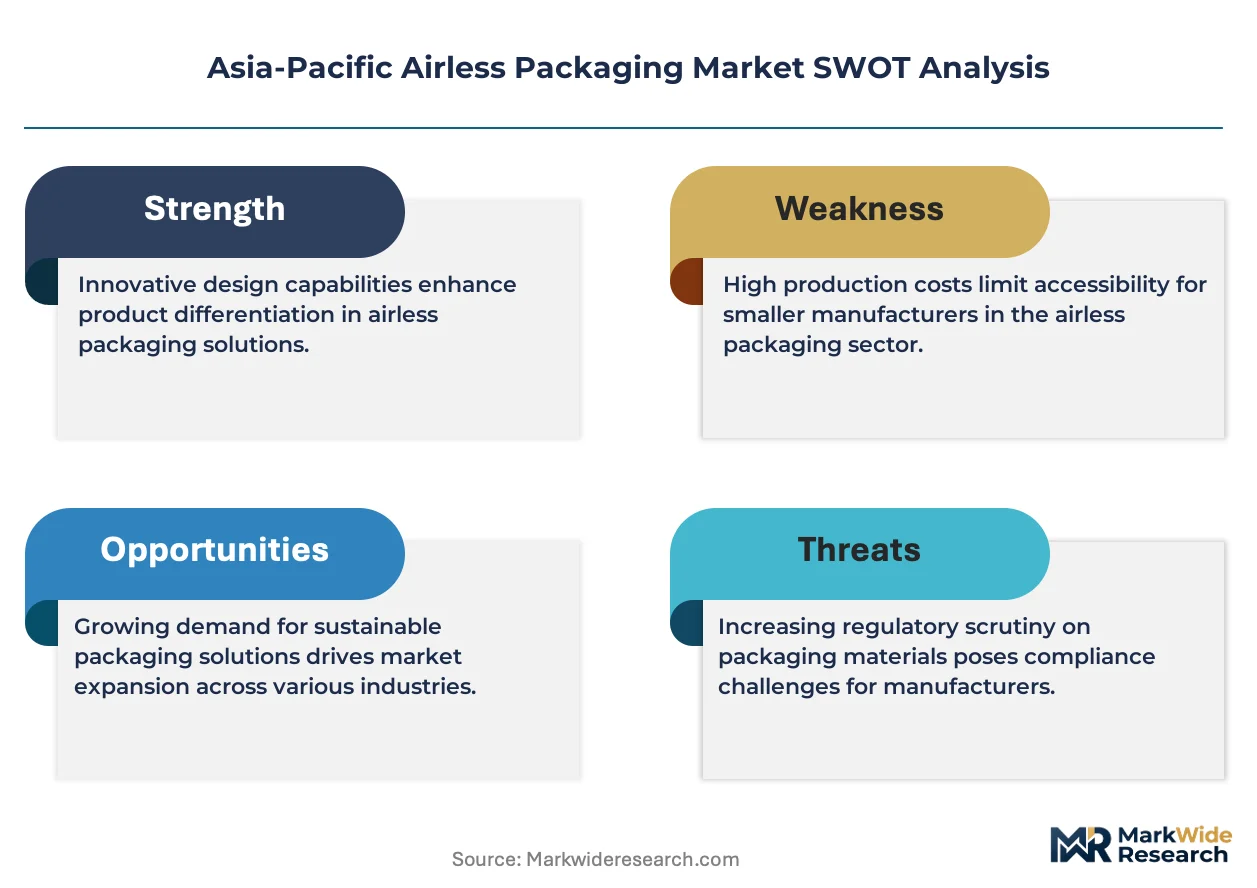
- Engineering polymer cost volatility:Specialized PP and POM resins for piston mechanisms face price pressure from regional petrochemical supply disruptions.
- Guangdong mold-making concentration:Over-reliance on a single province for high-precision injection tooling creates bottleneck risk during peak cosmetic launch cycles.
- GB standard compliance friction:China's SAMR material safety codes require costly third-party testing for each pump assembly variant, filtering smaller component suppliers from qualification.
Strategic Opportunities
- India's formalizing beauty retail:Organized modern trade expansion in tier-2 cities creates first-mover positioning for airless dispensers targeting emerging middle-class skincare routines.
- Dual carbon alignment:China's national emissions targets are incentivizing lightweight mono-material pump designs that reduce polymer mass per unit while maintaining vacuum integrity.
- Subscription refill platforms:Direct-to-consumer skincare services in South Korea and Japan are normalizing cartridge-return logistics that reward standardized pump interfaces.
Industry Challenges
- Precision molding talent scarcity:Micro-tolerance piston seal production requires specialized tool-and-die expertise concentrated in aging workforces across Taiwan and Japan.
- Cross-border certification lag:BIS import approval timelines for packaging components often misalign with Indian brand launch schedules, forcing buffer inventory commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Airless Packaging Market |
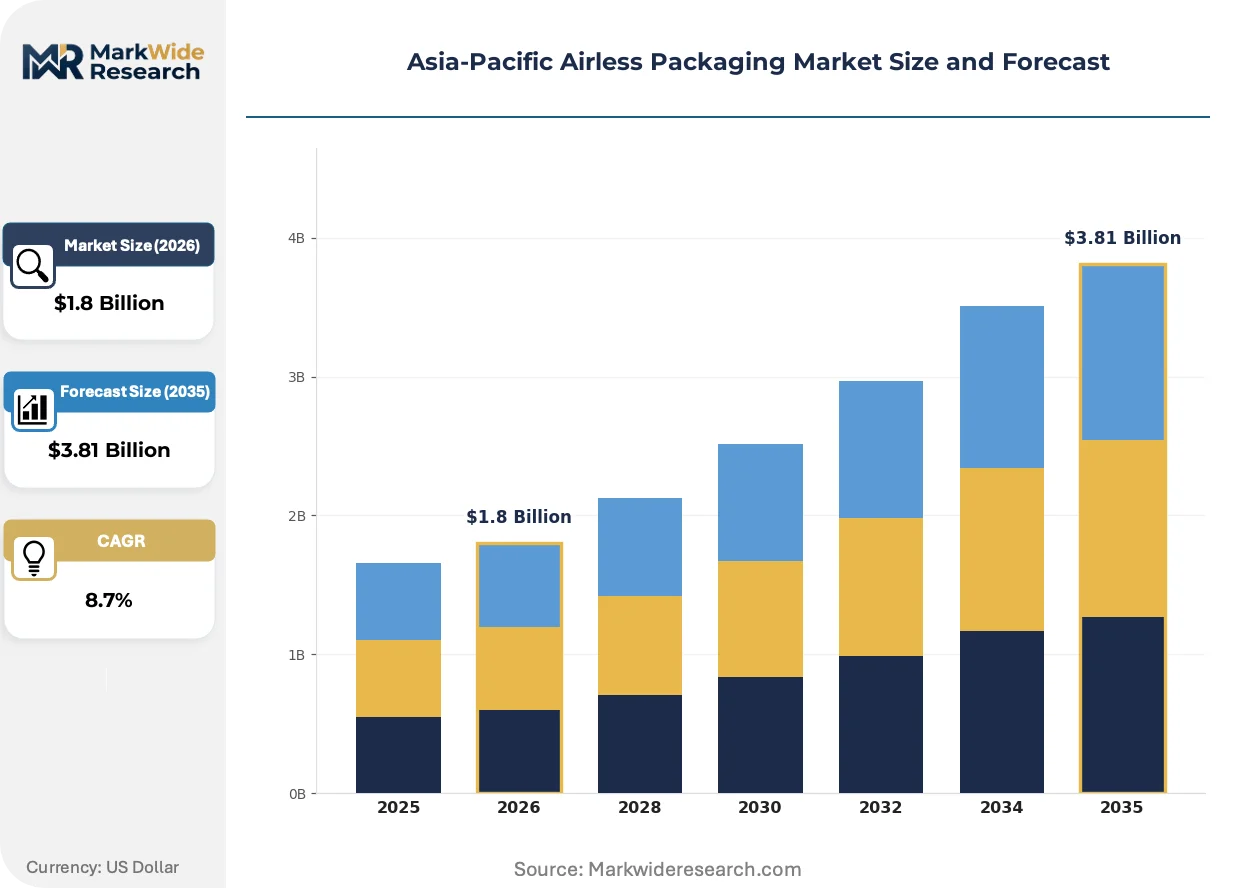
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Containers, Food Packaging, Pharmaceutical Bottles, Industrial Packaging Material: Plastic, Glass, Metal, Composite End User: Personal Care, Pharmaceuticals, Food & Beverage, Household Products Technology: Vacuum Technology, Pressure Technology, Piston Technology, Bag-on-Valve |
| Companies Covered | AptarGroup Inc, Silgan Holdings Inc, Albea S.A., HCP Packaging, Quadpack, Berry Global Group, Inc., APackaging Group, Zhejiang Cosme Industry Co., Ltd., Evergreen Resources, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Airless Packaging Market Strategic Shifts
Digital printing integration and mono-material pump architectures are converging to collapse minimum order quantities and accelerate cosmetic brand versioning cycles across Asia-Pacific manufacturing hubs.
Mono-material all-PP pump assemblies are decentralizing supply chain dependencies previously locked to multi-resin component sourcing. Japanese precision cosmetic brands are piloting these systems for recycling-stream compatibility. The technology is decentralizing mold investment decisions away from complex multi-cavity tooling toward modular single-material platforms.
China's SAMR enforcement of GB standards for plastic contact materials is hardening compliance thresholds for imported cosmetic containers. Domestic brands now prioritize locally certified pump suppliers to avoid customs detention risk. Korean exporters serving the Chinese market are accelerating dual-qualification strategies for both KFDA and SAMR testing protocols.
Refill subscription models are compressing traditional wholesale procurement cycles for premium skincare packaging. Korean beauty conglomerates now negotiate annual pump supply agreements tied to cartridge replenishment volumes rather than primary container shipments. This shift is most visible in Seoul's Gangnam district, where flagship stores operate closed-loop return stations integrated with brand loyalty programs.
Asia-Pacific Airless Packaging Market Segmentation
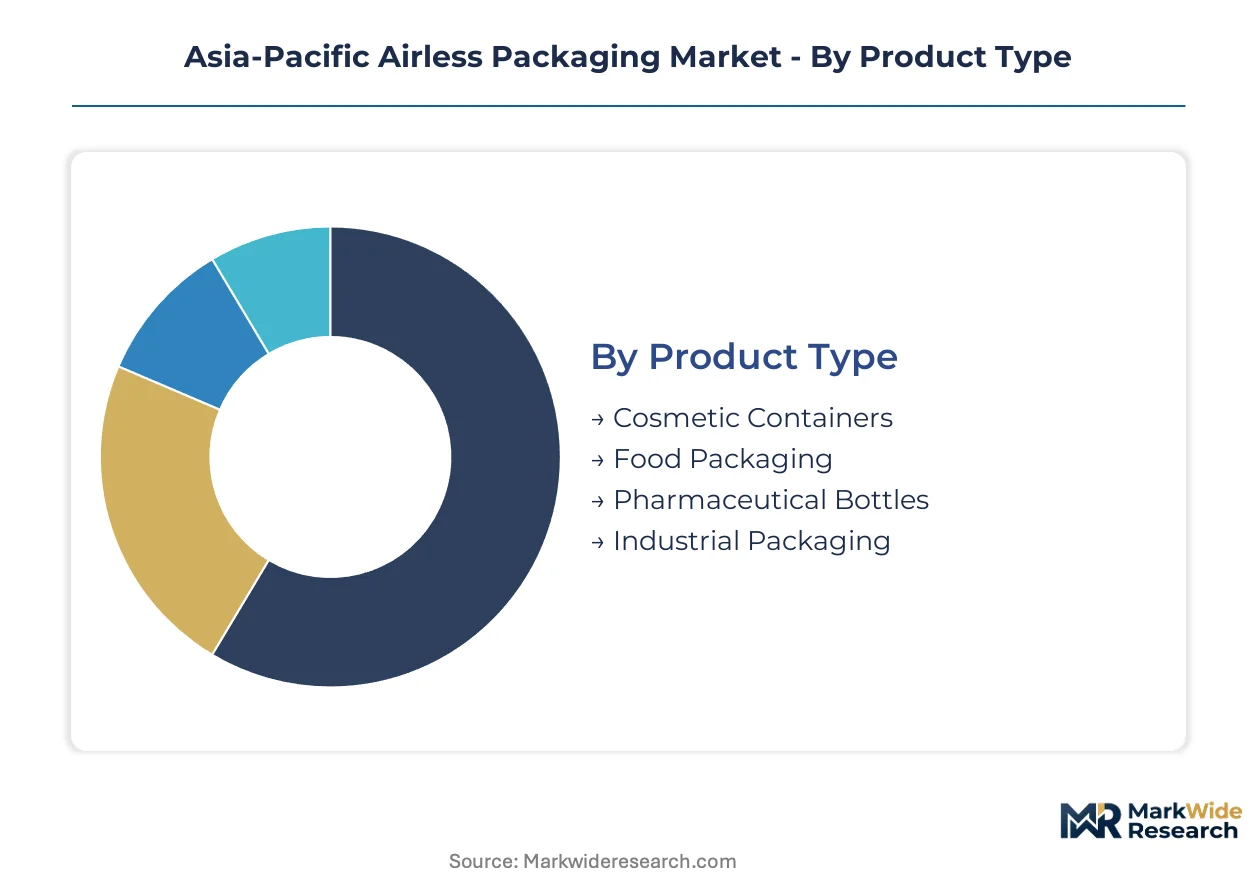
Airless packaging configurations vary sharply in oxygen exclusion rates and dispensing precision, forcing brands to match technical specifications against formulation sensitivity and regulatory compliance requirements. Segmentation choices determine mold investment priorities, material certification pathways, and refill-system compatibility for Asia-Pacific manufacturers.
Product Type:
Standalone primary containers dominate procurement volumes, while embedded pump mechanisms in multi-component systems command premium engineering margins.
- Cosmetic Containers:Evacuated chamber and piston-driven assemblies preserve oxidation-sensitive actives like retinoids and vitamin C serums. Korean beauty conglomerates in Seoul's Gangnam district anchor demand for precision-molded dispensers with decorative finishing capabilities.
- Pharmaceutical Bottles:CDSCO-mandated stability requirements for topical drug delivery systems are accelerating qualified airless adoption by Indian generic manufacturers seeking export certification. These systems achieve the stringent oxygen exclusion rates required for preservative-free formulations.
- Food Packaging:Oxygen barrier properties extend shelf life for sensitive nutritional products and specialty sauces across Japanese and Australian premium food segments.
- Industrial Packaging:High-viscosity dispensing applications in adhesives and sealants utilize reinforced piston mechanisms for controlled extrusion.
Cosmetic containers lead volumes today; pharmaceutical bottles are gaining share fastest.
Material:
Cost tiers separate commodity resin applications from specialized engineering polymers requiring precision tolerance control.
- Plastic:Polypropylene and POM resins dominate piston mechanism production, though Guangdong manufacturers face price pressure from regional petrochemical supply disruptions. Mono-material all-PP pump assemblies are decentralizing supply chain dependencies for recycling-stream compatibility.
- Glass:Premium skincare brands specify borosilicate and flint glass for UV-sensitive formulations where aesthetic clarity commands shelf positioning. Japanese precision cosmetic brands pilot these systems for METI-aligned chemical substance compliance.
- Metal:Aluminum barrier layers and collapsible tubes serve aerosol-alternative segments where propellant-free dispensing carries regulatory weight in Australian environmental labeling frameworks.
- Composite:Multi-layer coextrusions combine oxygen barrier properties with structural durability for extended shelf-life requirements.
Plastic leads volumes today; glass is climbing the fastest among premium positioning tiers.
End User:
Application maturity separates established personal care procurement from emerging pharmaceutical qualification pathways.
- Personal Care:Serum and essence dispensers drive the majority of airless pump shipments across South Korean and Chinese beauty markets. Refill subscription programs in Seoul are normalizing cartridge-return logistics that reward standardized pump interfaces.
- Pharmaceuticals:India's CDSCO tightening of topical drug stability requirements is filtering supplier participation through BIS certification thresholds for imported packaging components.
- Food & Beverage:Specialty sauce and nutritional product segments in Japan and Australia utilize bag-on-valve formats for propellant-free dispensing with environmental labeling advantages.
- Household Products:Concentrated formula dispensers for cleaning applications employ piston mechanisms for controlled dosing.
Personal care leads volumes today; pharmaceuticals show the steepest expansion trajectory.
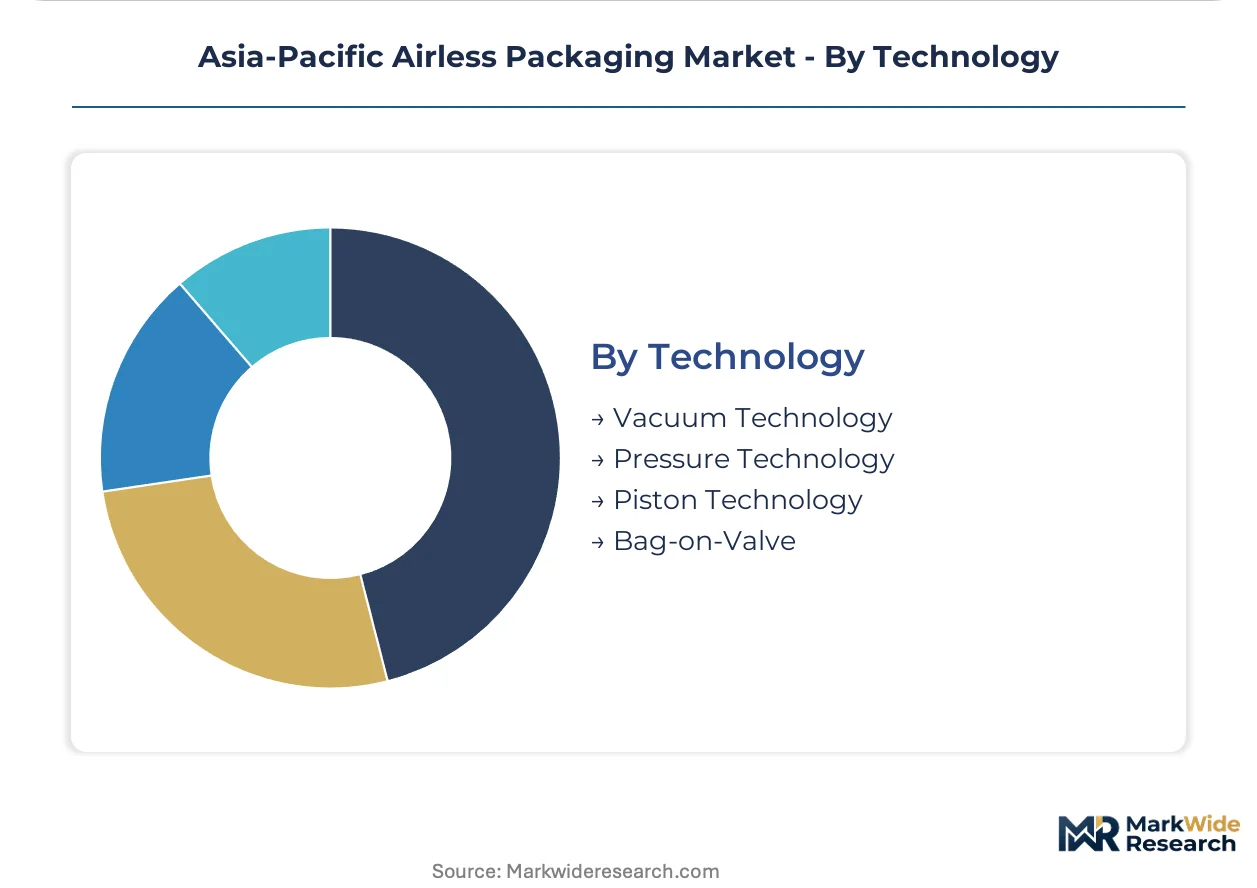
Technology:
Supply concentration in Guangdong mold-making clusters favors vacuum and piston architectures over emerging bag-on-valve formats.
- Vacuum Technology:Evacuated chamber designs achieve the highest oxygen exclusion rates for oxidation-sensitive formulations. Guangdong contract manufacturers maintain concentrated production capacity for rapid prototyping turnaround.
- Bag-on-Valve:Propellant-free dispensing formats capture aerosol-alternative segments in Australian and Japanese personal care markets where environmental labeling carries shelf-positioning weight. These systems separate product from propellant for improved evacuation rates.
- Piston Technology:Precision-molded seal mechanisms enable controlled dispensing for high-viscosity formulations across cosmetic and pharmaceutical applications.
- Pressure Technology:Compressed gas systems serve industrial and household product segments requiring forceful product expulsion.
Vacuum technology leads volumes today; bag-on-valve is expanding most quickly in aerosol-alternative segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands manufacturing scale while South Korea drives premium formulation demand, creating divergent sourcing patterns across the Asia-Pacific airless packaging landscape.
China
Guangdong province hosts concentrated contract manufacturing capacity serving both domestic beauty brands and Korean exporters. SAMR enforces GB standards for plastic contact materials that determine pump assembly qualification for cosmetic distribution. Shenzhen and Dongguan mold-making clusters enable rapid prototyping turnaround for limited-edition serum launches.
South Korea
Seoul's Gangnam district anchors demand for precision-molded dispensers with decorative finishing capabilities among premium skincare conglomerates. MFDS testing protocols align with KFDA requirements for brands pursuing dual certification strategies. Refill subscription programs in the capital normalize cartridge-return logistics that reward standardized pump interfaces.
India
Domestic generic drug manufacturers accelerate qualified airless bottle adoption to meet CDSCO-mandated stability requirements for topical pharmaceutical packaging. BIS certification thresholds for imported components filter supplier participation in the formalizing beauty market. Mumbai and Ahmedabad production hubs serve tier-2 city modern trade expansion targeting emerging middle-class skincare routines.
Japan
Precision cosmetic brands pilot mono-material all-PP pump assemblies for METI-aligned chemical substance compliance under the Act on the Evaluation of Chemical Substances. Osaka and Nagoya manufacturing bases supply bag-on-valve formats for propellant-free dispensing in environmental labeling-sensitive personal care segments. Technical specifications emphasize oxygen exclusion rates for oxidation-sensitive formulations.
Australia
Environmental labeling frameworks drive bag-on-valve adoption in aerosol-alternative personal care markets where propellant-free dispensing carries shelf-positioning weight. TGA alignment with international stability standards supports pharmaceutical packaging qualification for export-oriented manufacturers. Sydney and Melbourne distribution channels prioritize lightweight mono-material designs that reduce polymer mass per unit.
Asia-Pacific Airless Packaging Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pump technology leaders anchoring long-term supply relationships while decorative finishers command premium positioning. The vendor base organizes around three archetypes: technology-driven pump specialists, scale-oriented multi-hub manufacturers, and design-focused premium finishers. Consolidation pressure intensifies as refill subscription models compress traditional wholesale procurement cycles and force mold investment retooling toward modular architectures. Geographic expansion and portfolio diversification represent the dominant competitive moves as players seek to reduce Guangdong concentration risk.
Among technology-driven specialists, AptarGroup Inc exemplifies pump engineering leadership through its supply relationships with Korean beauty conglomerates. Silgan Holdings Inc occupies a position within the scale-oriented tier, sustaining manufacturing presence across multiple Asian production hubs. Albea S.A. anchors the decorative finishing archetype, commanding premium positioning in Japanese cosmetic markets through specialized aesthetic capabilities. These three players represent distinct strategic vectors that competitors must navigate.
| Leading Market Players |
|---|
| AptarGroup Inc |
| Silgan Holdings Inc |
| Albea S.A. |
| HCP Packaging |
| Quadpack |
| Berry Global Group, Inc. |
| APackaging Group |
| Zhejiang Cosme Industry Co., Ltd. |
| Evergreen Resources |
| Others |
Value Chain & Pricing Dynamics
Polypropylene resin spot prices in Asian petrochemical markets cascade through Guangdong mold-making clusters into three distinct pricing tiers for airless pump assemblies, with mono-material designs commanding premiums over multi-resin configurations.
Pricing Analysis
Capacity additions in Vietnam and Thailand are reshaping price floors for standard-grade piston mechanisms, compressing margins for legacy Guangdong producers. Three-tier pricing structure across premium, standard, and economy levels separates KFDA-SAMR dual-certified assemblies from single-market qualified units. Pricing pressure stems from engineered polymer cost volatility as regional petrochemical supply disruptions feed through to specialized PP and POM resins. Domestic Chinese brands exhibit highest price sensitivity due to SAMR compliance testing burdens, while Korean beauty conglomerates prioritize specification adherence over unit cost.
Supply Chain Analysis
GB standard compliance testing acts as a qualification gate that filters smaller component suppliers from China's domestic cosmetic distribution network. Manufacturing gravity centers on China's Guangdong province, South Korea's Seoul-Incheon corridor, and India's Mumbai-Ahmedabad belt. Raw material sourcing draws from Saudi and Singaporean petrochemical feedstocks, Japanese precision steel for mold cavities, and German servo-drive components for automated assembly lines. Single-province concentration in Guangdong mold-making creates bottleneck risk during peak cosmetic launch cycles. Distribution runs through contract manufacturer direct relationships with beauty brand procurement teams, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific airless packaging represents a late-cycle quality story as refill subscription programs concentrate procurement power among specifications-obsessed Korean beauty conglomerates demanding dual-certification pump assemblies.
For Market Incumbents: Anticipate margin compression from modular pump architectures that commoditize traditional precision-molding advantages. Defensive consolidation into Vietnamese and Thai production bases reduces Guangdong concentration exposure. Backward integration into polymer compounding secures supply continuity against regional petrochemical disruptions. For New Entrants and Emerging Players: Capture India's tier-2 city modern trade expansion where BIS certification barriers filter incumbent participation. Pharmaceutical bottles for CDSCO-mandated topical drug stability requirements represent the most penetrable segment given qualification bottlenecks. Partner with Mumbai-based contract manufacturers for shared mold investment and accelerated BIS approval timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with mono-material pump specialists possessing METI-aligned chemical substance compliance capabilities. Long-term viability hinges on recycling-stream compatibility as China's dual carbon targets harden material specifications. Watch for cartridge-return logistics normalization in Seoul's Gangnam district as inflection signal for refill platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | Simultaneous KFDA and SAMR qualification opens access to Korean exporters serving Chinese beauty markets. |
| Mono-Material Platform Development | All-PP pump assemblies align with METI chemical substance regulations and China's recycling infrastructure investments. |
| Cartridge-Return Logistics Integration | Closed-loop return stations in Seoul normalize subscription refill economics and lock in annual supply agreements. |
| Guangdong Diversification | Vietnamese and Thai mold-making capacity reduces single-province bottleneck risk during peak launch cycles. |
| Pharmaceutical Qualification Pathway | CDSCO-mandated stability requirements for topical drugs create qualified supplier scarcity in Indian generic manufacturing. |
Study Parameters
Direct dialogue with pump technology engineers, cosmetic brand procurement directors, pharmaceutical packaging qualification specialists, and Guangdong contract manufacturing executives grounded qualitative findings. Secondary validation drew from SAMR GB standard filings, CDSCO stability requirement circulars, Korean MFDS cosmetic ingredient databases, and customs records of polypropylene resin imports. Bottom-up pump shipment estimates triangulated against top-down beauty market value projections.
Bottom-up modeling aggregated individual country-level demand by product type, material grade, and technology configuration across the analysis window. Segmentation dimensions included cosmetic versus pharmaceutical end-use, vacuum versus bag-on-valve versus piston technology, and mono-material versus multi-resin construction. CAGRs derived from regression analysis of historical shipment patterns against formulation sensitivity trends and regulatory tightening trajectories. Forecast inputs incorporated refill subscription penetration rates and CDSCO qualification timeline compression.
Underlying measurement precision varies by segment; vacuum technology and cosmetic containers carry tighter precision than emerging bag-on-valve formats and pharmaceutical applications. Forecasts reflect assumptions about regulatory enforcement continuity and petrochemical supply normalization. A model refresh is warranted upon material change in China's dual carbon policy implementation or India's BIS certification reciprocity agreements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Cavitated Films Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Single-Use Packaging Market
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
France Packaging Market
Packaging Materials
Punnet Packaging Market
Packaging Materials
Organic Substrate Packaging Material Market
Packaging Materials
Europe Consumer Packaging Market
Packaging Materials
PET Strap Market
Packaging Materials
Twist Tie Market
Packaging Materials
Thermal Insulation Packaging Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Brazil Packaging Market