
 Global Lithium Ion Battery Packaging Solutions Market | 2026-2036
Global Lithium Ion Battery Packaging Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lithium Ion Battery Packaging Solutions Market Outlook
Direct-to-cell-factory supply contracts are reshaping how packaging converters serve battery producers. Amcor Limited leverages its multilayer film expertise to secure long-term pouch supply agreements with Asian cell makers. DS Smith Plc anchors its position through corrugated-based thermal insulation systems designed for module-level shipment. Smurfit Kappa Group competes by embedding fire-retardant coatings into paper-based formats for secondary packaging of cylindrical cells.
Lithium ion battery packaging solutions encompass engineered enclosures, barrier films, and structural supports that maintain electrochemical stability, prevent thermal propagation, and satisfy UN 38.3 transportation testing for hazardous materials. These systems employ aluminum-laminated polymers, coated papers, or metallized composites to control moisture ingress below 0.1 grams per square meter per day while dissipating heat from 18650, 2170, and prismatic cell geometries. Pouch formats command the largest volume share due to their adoption in automotive prismatic modules, while rigid trays capture premium margins by integrating cell-to-pack structural functions. Composite materials represent the fastest-expanding material category as manufacturers combine mica-paper layers with polymer substrates to meet elevated thermal runaway containment standards.
The EU Battery Regulation, China's GB/T standards, and the UN Manual of Tests and Criteria collectively mandate flame-retardant performance, recyclability quotas, and transport safety documentation that packaging suppliers must embed at the design stage. The US DOT and IATA Dangerous Goods Regulations further constrain air-freight configurations, pushing converters toward certified modular formats. Stakeholders should monitor how solid-state cell transitions alter form factor requirements and whether European recyclability mandates force material substitutions ahead of compliance deadlines.
Market Dynamics
Cell-to-pack architecture adoption by automotive OEMs is compressing module-level packaging volumes while elevating thermal containment specifications for direct cell housings. This structural shift forces converters to reengineer material stacks for single-component structural-fire barrier integration rather than multi-layer module assemblies.
Growth Catalysts
- EU Battery Regulation recyclability mandates:The regulation's 2030 recovery targets for lithium and cobalt are compelling packagers to design aluminum-laminated films for clean separation, creating pull for mono-material pouch constructions.
- Electric vehicle prismatic cell demand:Automotive OEMs in Germany, South Korea, and the United States are scaling gigafactory output, concentrating procurement of high-barrier pouch formats with integrated cell-to-pack structural functions.
- Aluminum-laminated polymer advances:Improved pinhole resistance in 40-micron barrier layers is extending shelf life for high-nickel cathode chemistries, supporting longer supply chains for cylindrical cell exports.
Market Restraints
- Aluminum foil supply concentration:Primary foil rolling capacity concentrates in Chinese and South Korean mills, exposing converters to input cost volatility and tariff exposure on laminated substrates.
- UN 38.3 certification timelines:Extended testing protocols for new composite barrier configurations delay product commercialization by 8-14 months, freezing capital in development pipelines.
- Rigid tray substitution pressure:Injection-molded thermoplastic structural housings with embedded mica sheets are capturing module-level applications previously served by corrugated-thermal systems.
Strategic Opportunities
- Solid-state cell form factor transition:Next-generation sulfide and oxide electrolyte cells require hermetic metal-ceramic sealing incompatible with current polymer lamination, opening design contracts for novel enclosure architectures.
- India PLI scheme localization:The country's production-linked incentive program for advanced chemistry cell manufacturing is attracting packaging converters to establish foil lamination and pouch forming operations near emerging cell plants in Gujarat and Tamil Nadu.
- Second-life battery logistics:End-of-life electric vehicle packs require UN-certified shipping formats for remanufacturing and recycling flows, creating demand for reusable, fire-rated transport containers.
Industry Challenges
- Thermal runaway simulation expertise:Finite-element modeling of cell-to-cell propagation at 800°C-plus temperatures requires specialized combustion engineering talent scarce among traditional packaging R&D teams.
- Multi-standard compliance synchronization:Simultaneous adherence to China's GB/T standards, EU Battery Regulation flame-retardancy tiers, and US DOT hazmat configurations fragments quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lithium Ion Battery Packaging Solutions Market |
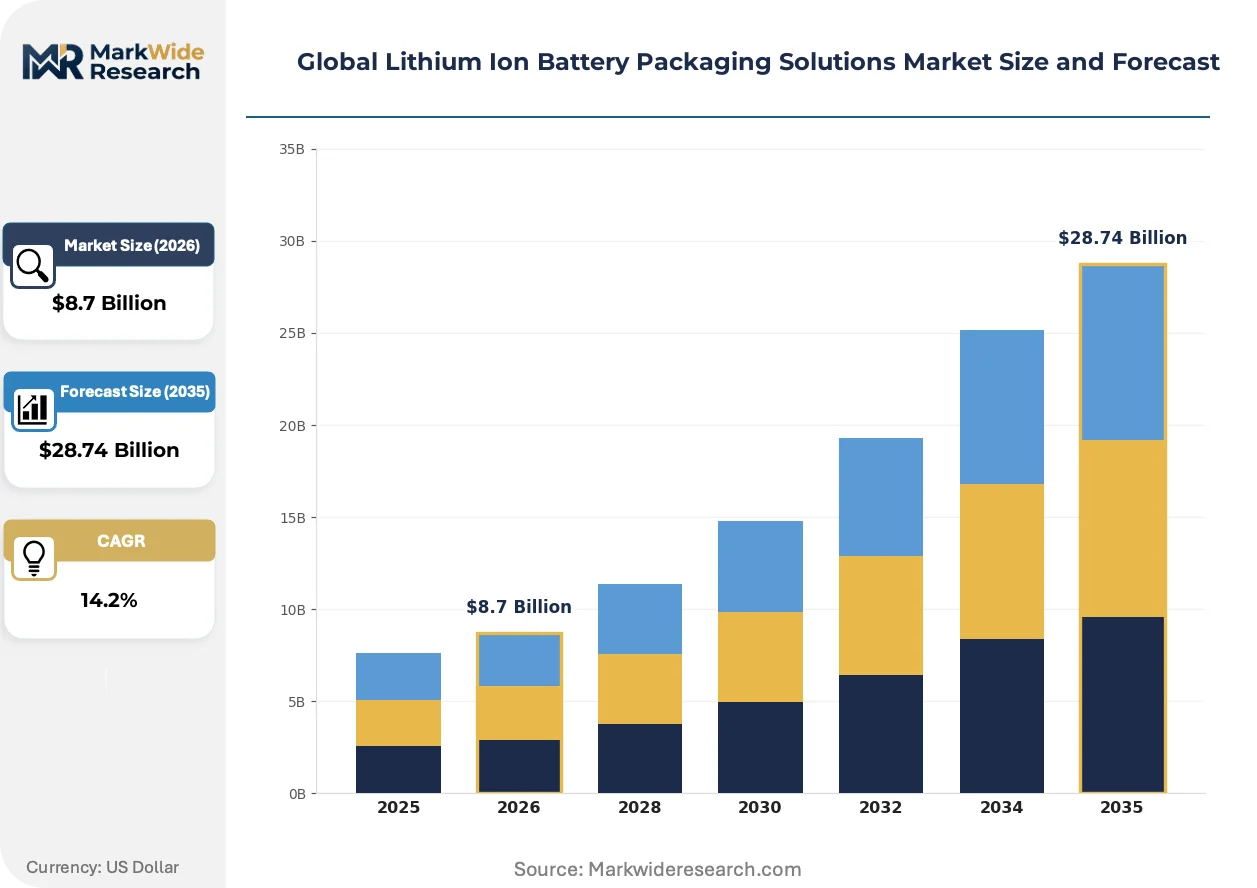
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Boxes, Trays Material: Plastic, Metal, Paper, Composite End User: Consumer Electronics, Automotive, Industrial, Telecom Form Factor: Flexible, Rigid, Semi-rigid, Modular |
| Companies Covered | Amcor Limited, DS Smith Plc, Smurfit Kappa Group, WestRock Company, Mondi Group, International Paper, Berry Global, Schur Packaging Group, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lithium Ion Battery Packaging Solutions Market Strategic Shifts
Thermal barrier engineering is pivoting from passive insulation to active propagation interruption, with material scientists embedding intumescent coatings and phase-change layers directly into cell-facing surfaces. This evolution demands closer collaboration between packaging converters and cell chemistry developers.
Mica-paper polymer composites are rendering obsolete conventional ceramic fiber wraps for cylindrical cell module assemblies. Battery module suppliers in South Korea and Japan are qualifying these thinner, lighter barriers for 2170 cell configurations. The technology is compressing pack height by 12-18 millimeters while maintaining UL 94 V-0 flame ratings, enabling tighter cell stacking densities.
China's GB standards for battery safety are mandating nail penetration and overcharge testing at the cell level that exceeds UN 38.3 transport requirements. The MIIT certification framework now requires documented thermal runaway containment for 5 minutes post-trigger, forcing packagers to validate multi-layer aluminum-polymer stacks under abusive mechanical conditions. Cylindrical cell formats for energy storage applications face the steepest compliance cost escalation.
Automotive OEMs are consolidating supplier bases around cell-factory co-location, bypassing traditional distributor networks for direct mill-to-foil-to-pouch contracts. Tier 1 battery makers in Germany and the United States are requiring packaging partners to maintain 48-hour finished goods inventory within 150 kilometers of gigafactory gates. This geographic compression is most visible in the Great Lakes region of the United States, where pouch laminators are leasing warehouse space adjacent to planned cell plants.
Global Lithium Ion Battery Packaging Solutions Market Segmentation
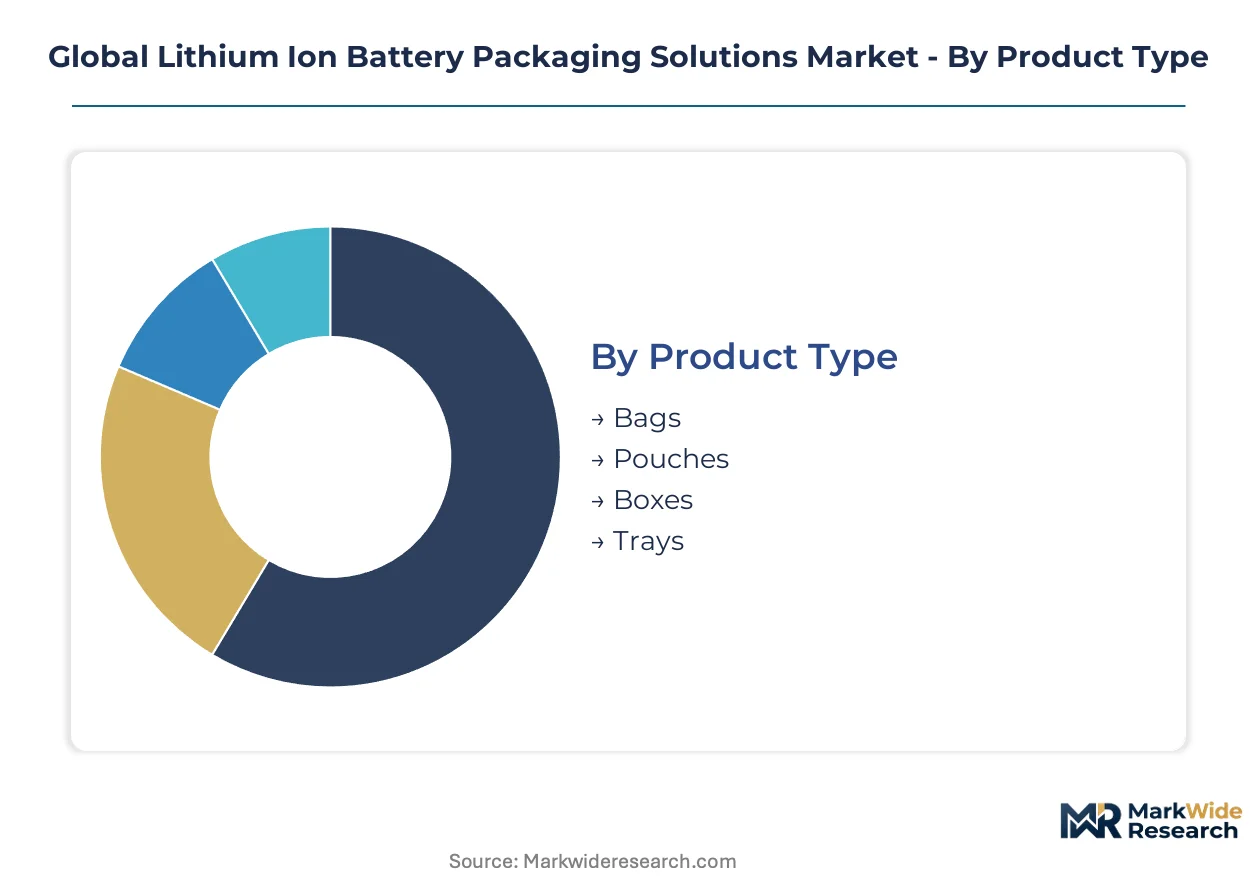
Packaging configurations for lithium ion batteries diverge sharply by electrochemical format, thermal management requirements, and transportation regulatory class. Each segment demands distinct material engineering approaches to satisfy UN 38.3 hazmat certification while optimizing pack density for specific cell geometries.
Product Type:
Use cases span from individual cell protection through module-level thermal containment to pack-scale structural integration.
- Pouches:Aluminum-laminated polymer multilayer films form the dominant format for prismatic automotive cells, with 40-micron barrier layers achieving moisture ingress below 0.1 g/m²/day. German and South Korean gigafactories concentrate procurement of these formats for cell-to-pack architectures requiring direct cell housing with integrated structural functions.
- Trays:Injection-molded or thermoformed structural housings with embedded mica or ceramic layers serve module-level and pack-level applications where dimensional stability under thermal load is critical. Automotive OEMs in the United States specify these for 2170 cylindrical cell configurations where pack height compression enables tighter stacking densities.
- Bags:Secondary containment formats for cylindrical cell shipment and storage, typically employing metallized polymer or coated paper constructions. Consumer electronics distributors in Japan utilize these for 18650 cell logistics to satisfy IATA dangerous goods configurations.
- Boxes:Corrugated-based thermal insulation systems designed for module-level shipment, often integrating intumescent coatings or phase-change materials for propagation interruption. DS Smith Plc anchors market position through these formats for European automotive supply chains.
Established volume favors pouches; emerging adoption favors trays.
Material:
Cost tiers separate commodity substrates from engineered multi-layer stacks with active thermal management properties.
- Composite:Mica-paper polymer laminates and aluminum-ceramic hybrid constructions represent the steepest expansion trajectory, driven by China's GB standards mandating 5-minute thermal runaway containment post-trigger. South Korean and Japanese module suppliers qualify these for 2170 configurations to compress pack height while maintaining UL 94 V-0 ratings.
- Metal:Aluminum foil laminates and stamped aluminum housings provide hermetic sealing and electromagnetic shielding for high-voltage automotive packs. Chinese and South Korean foil rolling mills concentrate primary capacity, exposing converters to input cost volatility.
- Plastic:Monolayer and multilayer polymer films for secondary containment and moisture barrier applications in consumer electronics and telecom backup power. Indian packaging converters are establishing foil lamination capacity near Gujarat cell plants under the PLI scheme.
- Paper:Fire-retardant coated and corrugated formats for secondary packaging and shipping containment of cylindrical cells. Smurfit Kappa Group competes through embedded intumescent coatings in these constructions.
Commodity substrates dominate unit volumes; engineered composites capture margin expansion.
End User:
Customer type determines certification intensity, volume scale, and geographic concentration of procurement.
- Automotive:Direct cell-factory supply contracts with tier 1 battery makers in Germany, South Korea, and the United States drive demand for high-barrier pouches with cell-to-pack structural integration. OEMs require 48-hour finished goods inventory within 150 kilometers of gigafactory gates.
- Consumer Electronics:High-volume, lower-unit-value procurement of bags and small-format pouches for 18650 and 2170 cells in power tools, laptops, and portable electronics. Japanese and Taiwanese electronics manufacturers concentrate demand.
- Industrial:Energy storage system packaging for grid-scale and commercial installations, facing steep compliance cost escalation under China's GB/T standards for cylindrical formats. UN-certified shipping formats for second-life battery logistics create emerging demand.
- Telecom:Backup power and base station applications requiring long shelf-life barrier performance for stationary installations. Indian and Southeast Asian network expansion drives regional procurement.
Automotive commands premium pricing; industrial applications face steepest compliance cost escalation.
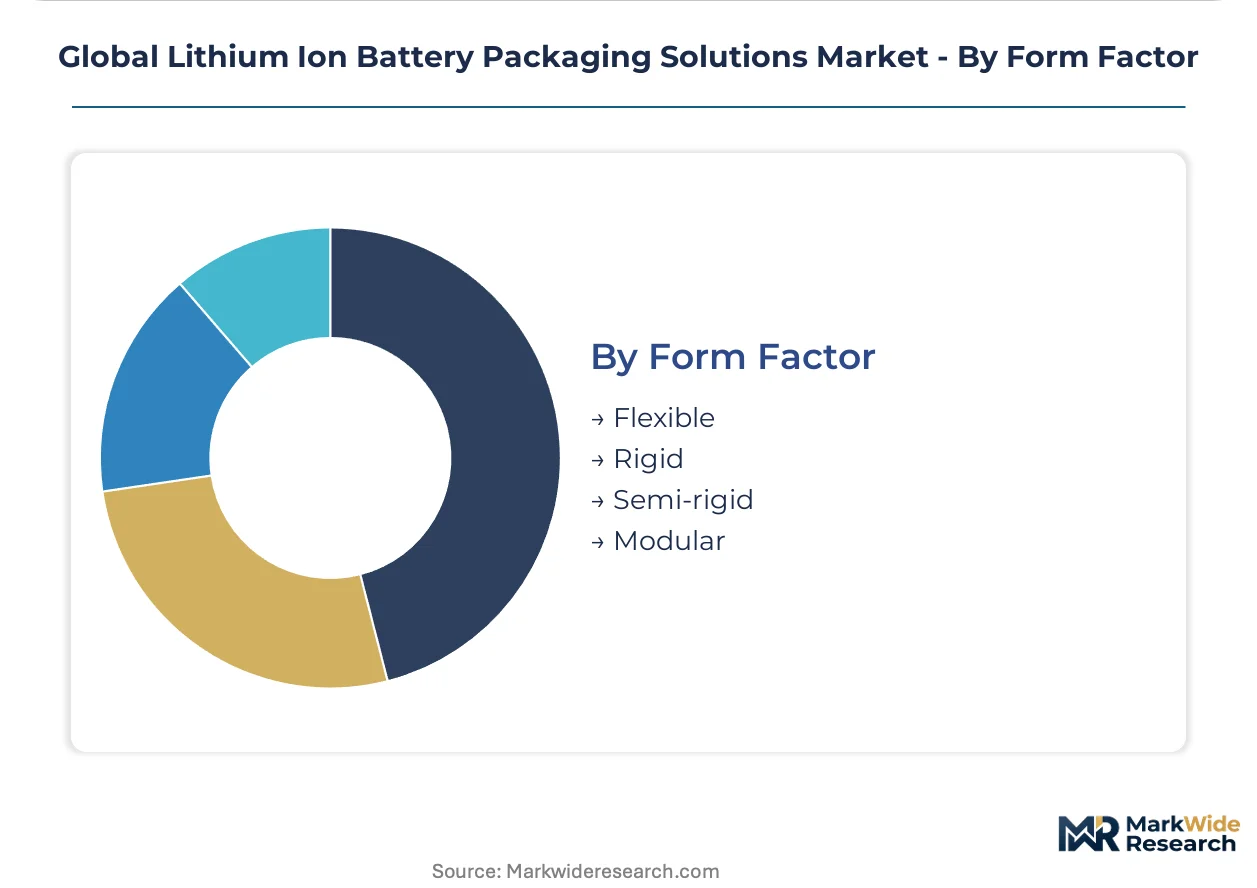
Form Factor:
Supply concentration patterns mirror the geographic clustering of cell manufacturing technology.
- Flexible:Pouch and bag formats dominating prismatic cell applications with highest volume share in automotive. Asian cell makers in South Korea and China drive specifications for aluminum-laminated polymer constructions.
- Rigid:Trays and structural housings capturing premium margins through cell-to-pack integration, with US and German automotive OEMs consolidating supplier bases around co-location requirements.
- Semi-rigid:Hybrid constructions combining flexible barrier layers with structural frames for modular battery configurations in commercial vehicles and industrial equipment.
- Modular:Certified reusable transport containers for end-of-life electric vehicle pack logistics, with European recyclability mandates under the EU Battery Regulation driving design for disassembly.
Flexible formats dominate cell-level volumes; modular formats gain traction in circular economy logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container terminals handle the densest concentration of European battery packaging imports, underwriting Germany's central role in continental supply chains. Rail corridors from this hub feed directly into gigafactory clusters across the North German Plain.
United States
Automotive OEMs in Michigan and Ohio are consolidating supplier bases around 48-hour inventory requirements. The US DOT hazmat regulations constrain air-freight configurations for lithium ion cells. The Great Lakes region hosts pouch laminators leasing warehouse space adjacent to planned cell plants.
Germany
Cell-to-pack architecture adoption by automotive OEMs compresses module-level packaging volumes. The EU Battery Regulation's 2030 recovery targets compel aluminum-laminated film designs for clean separation. Bavarian and Baden-Württemberg gigafactories concentrate procurement of high-barrier pouches.
China
Primary aluminum foil rolling capacity concentrates in Chinese mills, exposing converters to input cost volatility. MIIT certification under GB standards mandates 5-minute thermal runaway containment post-trigger. Yangtze River Delta cell makers drive specifications for barrier layer constructions.
South Korea
Module suppliers in Seoul Capital Area and Busan-Ulsan are qualifying mica-paper polymer composites for 2170 configurations. The country's national industrial regulator enforces flame-retardancy tiers exceeding baseline transport requirements. Gyeonggi-do pouch converters secure long-term supply agreements with tier 1 battery makers.
India
The PLI scheme for advanced chemistry cell manufacturing attracts packaging converters to establish foil lamination operations. Central Electricity Authority guidelines shape backup power packaging specifications for telecom applications. Gujarat and Tamil Nadu cell plants drive regional procurement of moisture barrier formats.
Global Lithium Ion Battery Packaging Solutions Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The supplier base segments between multinational converters with multilayer film expertise and regional fabricators serving secondary containment niches. Three archetypes dominate: aluminum-laminated pouch specialists, corrugated-thermal insulation engineers, and fire-retardant coating formulators. Competitive moves concentrate on direct-to-cell-factory supply contracts and geographic co-location with gigafactory gates.
Among packaging converters with listed public status, Amcor Limited, DS Smith Plc, and Smurfit Kappa Group occupy positions spanning pouch, tray, and secondary containment tiers respectively. These entities exemplify the strategic pivot toward automotive-direct supply relationships and integrated thermal management functions. Their positioning reflects broader industry consolidation around cell-to-pack architectural requirements and escalating regulatory compliance burdens across multiple jurisdictions.
| Leading Market Players |
|---|
| Amcor Limited |
| DS Smith Plc |
| Smurfit Kappa Group |
| WestRock Company |
| Mondi Group |
| International Paper |
| Berry Global |
| Schur Packaging Group |
| Huhtamaki Oyj |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese aluminum foil rolling mills is compressing converter margins while amplifying buyer negotiating leverage across laminated pouch contracts. This utilization imbalance forces Asian cell makers to demand extended payment terms and indexed raw-material clauses that shift price volatility risk upstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automotive-certified pouches with MIIT validation from industrial-grade formats and secondary containment bags. Price differentiation hinges on UN 38.3 certification tier and volume scale, with automotive direct contracts commanding 40-60% premiums over distributor-sourced equivalents. Cost compression in standard-grade laminates is intensifying because South Korean foil suppliers are absorbing tariff exposure to defend market share. Consumer electronics distributors exhibit highest price sensitivity, while German automotive OEMs prioritize thermal performance over unit cost.
Supply Chain Analysis
Extended payment terms from tier 1 battery makers in Germany and South Korea are straining working capital for mid-size laminators, forcing reliance on supply-chain finance facilities. Primary aluminum foil capacity draws from China, South Korea, and Japan, with converter operations clustering near Yangtze River Delta and Gyeonggi-do cell plants. Raw material dependencies rest on biaxially-oriented polypropylene, electrolytic-grade aluminum, and mica-paper substrates. Single-source vulnerability concentrates in Chinese foil rolling mills exposed to export control fluctuations. Distribution runs through direct mill-to-foil-to-pouch contracts that bypass traditional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where EU Battery Regulation compliance costs and UN 38.3 certification timelines create structural barriers to challenger entry. Switching costs for automotive OEMs escalate as cell-to-pack architectures embed packaging specifications into platform designs.
For Market Incumbents: Entrench position through backward integration into aluminum foil lamination capacity in the Great Lakes region and Gujarat to satisfy co-location mandates. Lock in multi-year direct supply agreements with tier 1 battery makers before solid-state cell transitions obsolete current polymer lamination expertise. Defend against rigid tray substitution by embedding mica-paper composites into pouch formats for cell-to-pack structural integration. For New Entrants and Emerging Players: Pursue second-life battery logistics as the most penetrable white space, where UN-certified reusable transport containers face limited incumbent competition. Target India's PLI scheme localization requirements for foil lamination operations near Tamil Nadu cell plants. Establish go-to-market credibility through MIIT pre-certification partnerships with Yangtze River Delta module suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pouch laminators with locked automotive direct contracts and indexed raw-material pass-through clauses. Five-to-ten-year viability favors converters with combustion engineering talent for thermal runaway simulation and multi-jurisdiction compliance capabilities. The acquisition archetype to monitor combines aluminum-laminated film expertise with geographic co-location leases near planned gigafactory gates. Watch for solid-state cell pilot production announcements as the signal for packaging form factor disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foil Lamination | Captures margin compression from Chinese mill concentration and satisfies automotive co-location mandates. |
| MIIT Pre-Certification Investment | Accelerates market access for GB-standard pouch formats in Yangtze River Delta supply chains. |
| Thermal Runaway Simulation Capability Buildout | Addresses scarce combustion engineering talent and differentiates proposals for automotive OEMs. |
| Second-Life Logistics Container Development | Opens circular economy revenue streams as EU Battery Regulation drives end-of-life pack recovery. |
| Solid-State Cell Enclosure R&D Partnership | Positions for hermetic metal-ceramic sealing requirements as sulfide electrolyte cells mature. |
Study Parameters
Desk research of trade customs data, MIIT certification filings, and SEC 10-K supply chain disclosures preceded structured interviews with pouch laminator operations directors, automotive OEM platform engineers, and foil rolling mill procurement managers. Primary fieldwork combined with secondary validation from UN Manual of Tests and Criteria documentation, EU Battery Regulation impact assessments, and IATA dangerous goods configuration guidelines. Bottom-up cell factory capacity builds and top-down packaging spend-per-kWh estimates were triangulated to derive volume and value outputs.
Assumptions held fixed include current cell-to-pack architecture penetration rates and existing GB standard thermal containment timelines, while solid-state cell commercialization pace and aluminum tariff trajectories were modeled as scenario variables. Segmentation dimensions spanned product type, material stack composition, end-user certification intensity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves tied to gigafactory construction announcements. Forecast inputs incorporated foil rolling capacity utilization rates and automotive inventory co-location requirements.
Sensitivities concentrate around solid-state cell form factor transitions, EU recyclability mandate enforcement timing, and Chinese export control fluctuations on electrolytic-grade aluminum. Forecasts reflect documented assumptions regarding thermal runaway containment standard harmonization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Strawless Lids Market
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
United States Contract Packaging Market
Packaging Solutions
Europe Temperature Controlled Packaging Solutions Market
Packaging Solutions
Package Drop Box Market
Packaging Solutions
FMCG Packaging Market
Packaging Solutions
Global Bespoke Packaging Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
Suspension and Retention Packaging Market
Packaging Solutions
Middle East and Africa Contract Packaging Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Anti-Counterfeiting Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Topical Dispenser Market