
 Basal Cell Carcinoma Treatment Market | 2026-2036
Basal Cell Carcinoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Basal Cell Carcinoma Treatment Market Intelligence
The shift in treatment delivery from general hospitals to specialized dermatology clinics is rebalancing the market's service infrastructure, favoring outpatient and minimally invasive procedures. F. Hoffmann-La Roche Ltd. leverages its leadership in targeted therapies like hedgehog pathway inhibitors for advanced cases. Regeneron Pharmaceuticals Inc. competes with its immunotherapy pipeline, while Sanofi specializes in developing treatments that address specific genetic markers of the disease.
Basal cell carcinoma treatment encompasses medical interventions designed to remove or eradicate the most common form of skin cancer. Therapies target abnormal cell proliferation, which is often driven by mutations in the hedgehog signaling pathway. Surgical procedures remain the primary treatment for most nodular and infiltrative lesions due to high cure rates. However, topical therapies are gaining preference for superficial lesions, offering a non-invasive alternative for eligible patients.
Regulatory bodies like the U.S. FDA and the European Medicines Agency (EMA) set stringent efficacy and safety standards for new drug approvals. Australia's TGA also influences protocols in a high-incidence region. These frameworks govern market access for novel immunotherapies and topical agents. The key decision for clinicians and providers centers on balancing the efficacy of surgical excision against the cosmetic outcomes and convenience of non-surgical options.
Market Dynamics
The central dynamic is the rebalancing between surgical efficacy and the patient-driven demand for non-invasive options with superior cosmetic outcomes. This tension shapes investment in topical therapies and targeted drugs, challenging the long-standing dominance of surgical excision.
Growth Catalysts
- Targeted Drug Development:The advancement of hedgehog pathway inhibitors and immunotherapies provides effective options for advanced or difficult-to-treat cases, expanding the therapeutic arsenal beyond surgery.
- Demographic Pressures:An aging global population and heightened sun exposure in regions like Australia increase the incidence of basal cell carcinoma, directly stimulating demand for all treatment modalities.
- Service Infrastructure Shift:The migration of procedures to specialized dermatology clinics and ambulatory surgical centers improves patient access and supports the use of minimally invasive techniques.
Market Restraints
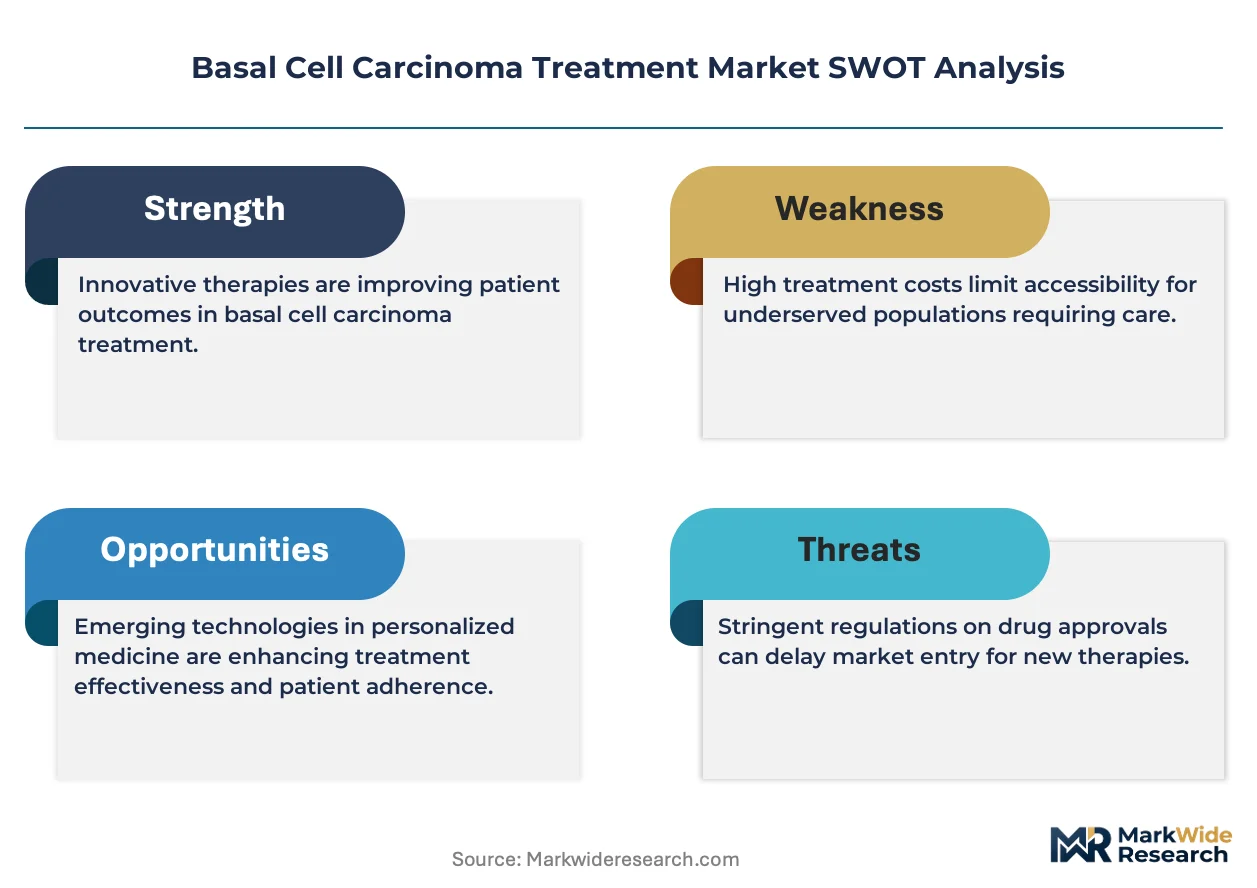
- High Treatment Costs:The premium pricing of novel immunotherapies and targeted oral medications limits accessibility for patients in healthcare systems with restrictive reimbursement policies.
- Surgical Necessity:For high-risk, nodular, or infiltrative subtypes, surgical excision remains the gold standard with the highest cure rate, limiting the applicability of non-surgical alternatives.
- Stringent Regulatory Hurdles:The rigorous efficacy and safety data required by agencies like the FDA and EMA for new drug approvals can create long and costly development timelines.
Strategic Opportunities
- Combination Therapy Regimens:Developing and validating treatment protocols that combine topical agents with systemic immunotherapies could improve efficacy and reduce recurrence rates for aggressive lesions.
- Emerging Market Penetration:Expanding access to diagnostic tools and affordable treatments in Latin American and Southeast Asian countries with growing healthcare infrastructure presents a significant opportunity.
- Prophylactic Innovations:Research into preventative treatments for high-risk individuals, such as those with Gorlin syndrome, opens a new market segment focused on disease prevention rather than cure.
Industry Challenges
- Specialized Training Requirements:The effective use of advanced therapies, including Mohs surgery and complex immunotherapies, requires specialized physician training, creating a potential bottleneck in care delivery.
- Reimbursement Complexity:Navigating disparate and often inadequate reimbursement codes for newer, more expensive non-surgical treatments across different national and private payer systems is a major operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Basal Cell Carcinoma Treatment Market |
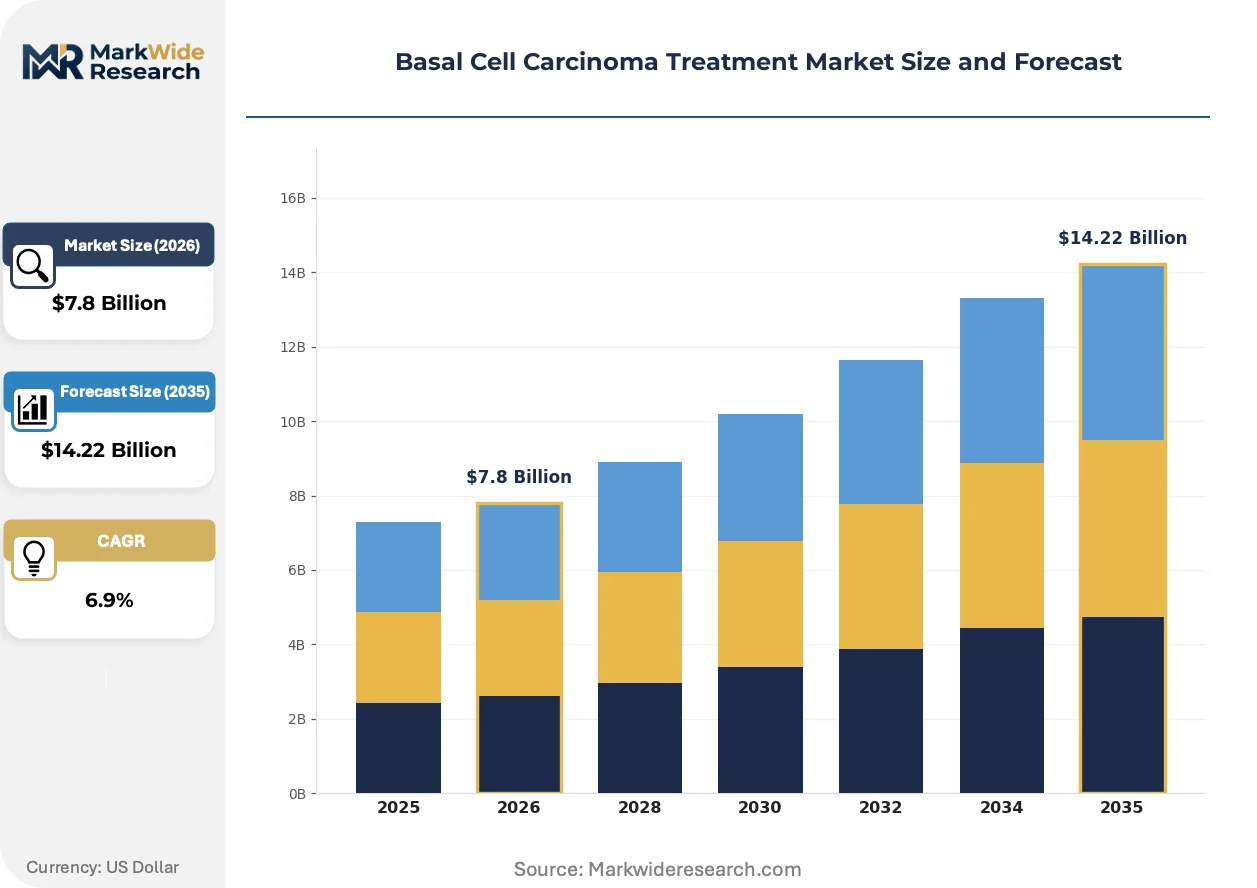
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $14.22 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Therapies, Surgical Procedures, Radiation Therapy, Immunotherapy, Photodynamic Therapy Therapy Area: Early-Stage Lesions, Superficial Lesions, Nodular Lesions, Infiltrative Lesions, Morpheaform Lesions End User: Dermatology Clinics, Oncology Centers, Dermatopathology Labs, Specialized Skin Institutes, Ambulatory Surgical Centers Delivery Mode: Topical Application, Intralesional Injection, External Beam, Laser Treatment, Oral Administration |
| Companies Covered | Bausch Health Companies Inc., F. Hoffmann-La Roche Ltd., Merck & Co., Inc., Sun Pharmaceuticals Ltd., Novartis AG, Regeneron Pharmaceuticals Inc., Sanofi, Viatris, Genentech, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Basal Cell Carcinoma Treatment Market Strategic Shifts & Innovations
The evolution of basal cell carcinoma treatment is defined by a move toward precision and patient-centricity. This transition prioritizes molecular-level intervention and less invasive procedures, fundamentally altering clinical decision-making and the competitive landscape.
Targeted therapies like hedgehog pathway inhibitors function by selectively blocking the molecular signals that fuel tumor proliferation. Oncologists and dermatologists are increasingly adopting these drugs for patients with locally advanced or metastatic BCC for whom surgery is inappropriate. This biological approach is rewriting the treatment paradigm for complex cases, shifting the focus from physical removal to molecular control.
Regulatory bodies, including the U.S. FDA and Australia's TGA, are placing greater emphasis on long-term safety data and patient-reported outcomes for new dermatological therapies. This requirement compels drug developers to demonstrate not only tumor clearance but also sustained cosmetic results and quality of life benefits. The topical and immunotherapy segments are most affected, as their value proposition is tied to these non-clinical endpoints.
A clear behavioral shift shows patients increasingly prioritizing cosmetic outcomes and reduced recovery time in treatment selection. This preference is eroding the automatic selection of surgical excision for eligible superficial lesions, steering demand toward topical therapies and photodynamic therapy administered in outpatient settings. The trend is most visible in affluent markets with high aesthetic awareness, such as the United States and parts of Europe.
Basal Cell Carcinoma Treatment Market Segmentation
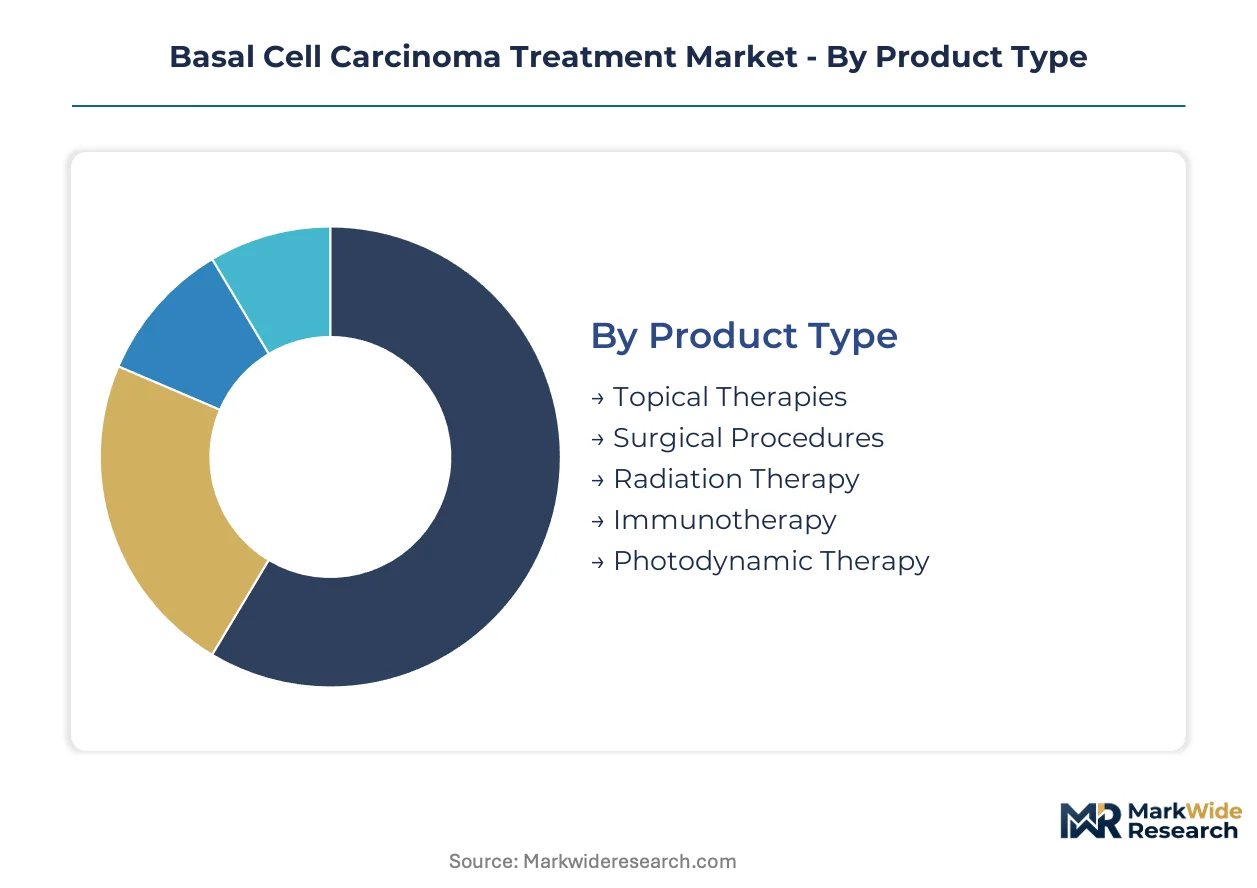
The basal cell carcinoma treatment market's diverse segmentation reflects varied patient needs and clinical approaches. Understanding these distinctions helps stakeholders identify key growth areas and optimize therapeutic strategies. Treatment choices often depend on tumor characteristics, patient health, and desired cosmetic outcomes.
Product Type:
Patient preference and physician guidance drive the selection among various product types for basal cell carcinoma treatment.
- Surgical Procedures:These remain the primary treatment for most lesions, offering high cure rates through physical removal. Demand concentrates in advanced healthcare systems like the United States, where specialized facilities support complex excisions.
- Immunotherapy:Systemic treatments harness the body's immune system to target cancer cells, particularly for advanced or metastatic cases. Usage expands in countries with robust R&D investment, such as Germany.
- Topical Therapies:Non-invasive creams or gels applied directly to superficial lesions, often preferred for cosmetic outcomes.
- Radiation Therapy:A non-surgical option using high-energy rays to destroy cancer cells, suitable for specific lesion types or elderly patients.
- Photodynamic Therapy:This involves light-sensitive drugs and a light source to kill cancer cells, often used for superficial lesions.
Volume sits with Surgical Procedures; growth tilts toward Immunotherapy.
Therapy Area:
Clinical focus dictates the appropriate therapy area, aligning treatment modalities with specific lesion characteristics.
- Superficial Lesions:These affect the top layer of the skin, often managed with topical agents or photodynamic therapy. Demand for non-invasive options is high in affluent markets like Australia.
- Nodular Lesions:Presenting as a raised, pearly nodule, these typically require surgical excision for complete removal. These lesions drive significant surgical procedure volumes in countries with high incidence, such as the United States.
- Early-Stage Lesions:Small, newly diagnosed tumors that benefit from a range of treatment options, including minimally invasive techniques.
- Infiltrative Lesions:Aggressive tumors with irregular borders that extend deeper into the dermis, often necessitating extensive surgical removal.
- Morpheaform Lesions:This subtype is characterized by a scar-like appearance and indistinct borders, posing diagnostic and treatment challenges.
The prevalence of Nodular Lesions drives current demand, while Superficial Lesions represent an expanding treatment frontier.
End User:
The evolving service infrastructure shapes the primary end-user settings for basal cell carcinoma treatment delivery.
- Dermatology Clinics:These provide comprehensive skin cancer diagnosis, treatment, and follow-up care, increasingly handling outpatient procedures. Patient preference for specialized care boosts their role in countries like Canada.
- Ambulatory Surgical Centers:These offer cost-effective outpatient surgical options for basal cell carcinoma excisions and reconstructions. Their efficiency attracts patients seeking convenient care in the United Kingdom.
- Oncology Centers:These manage advanced or metastatic basal cell carcinoma cases, often involving systemic therapies and multidisciplinary care.
- Dermatopathology Labs:Essential for accurate diagnosis and margin assessment of basal cell carcinoma specimens, supporting treatment decisions.
- Specialized Skin Institutes:These focus on complex dermatological conditions, including advanced skin cancer management and research.
Efficiency and specialization define the growth trajectory, with Dermatology Clinics gaining share from Oncology Centers.
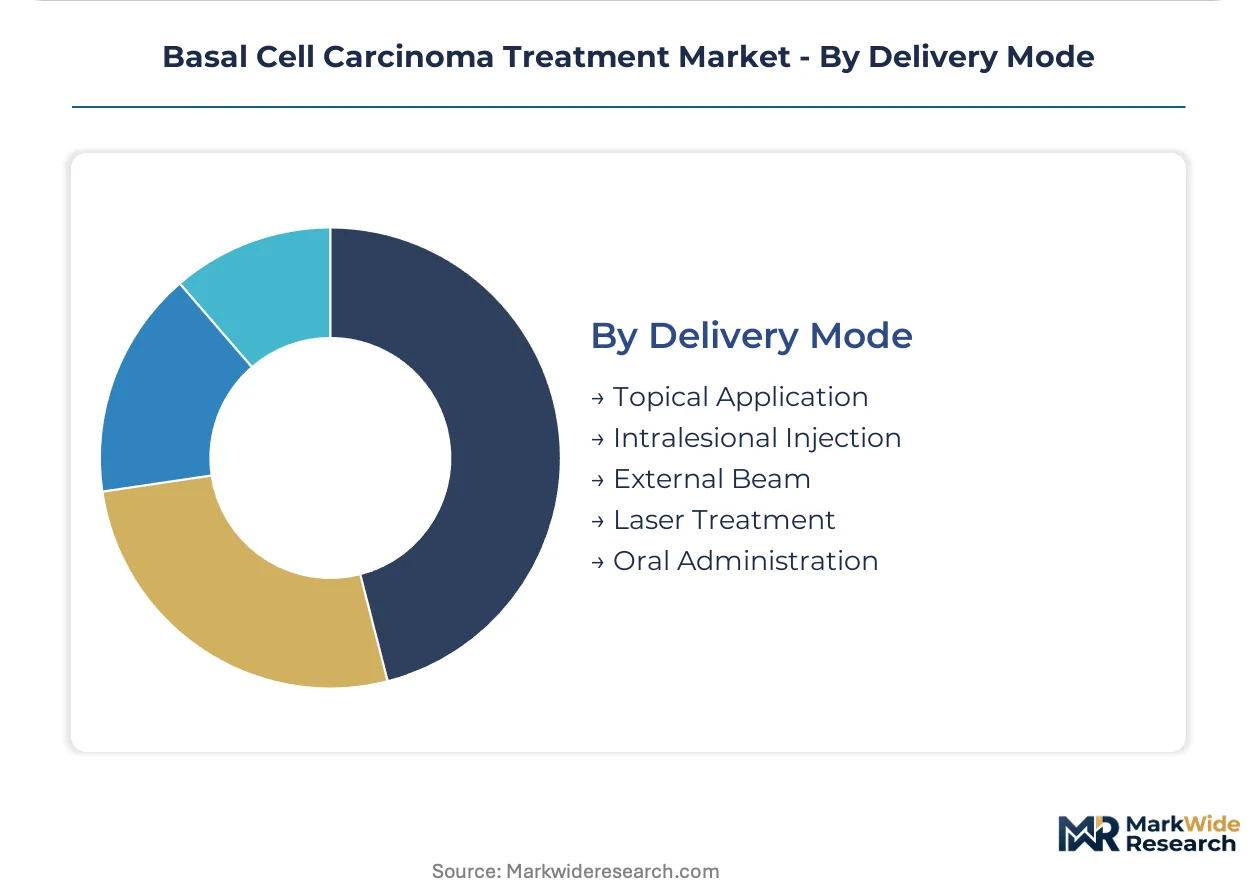
Delivery Mode:
Patient convenience and lesion characteristics influence the selection of basal cell carcinoma treatment delivery modes.
- Topical Application:This non-invasive method for superficial lesions offers ease of use and good cosmetic outcomes. Demand for this mode is high in European countries prioritizing aesthetic results.
- Oral Administration:This involves systemic delivery of targeted therapies like hedgehog pathway inhibitors for advanced cases. This mode is crucial in markets with advanced drug development, such as the United States.
- Intralesional Injection:Direct injection of therapeutic agents into the tumor, used for specific lesion types or as an adjunct therapy.
- External Beam:A form of radiation therapy where radiation is delivered from outside the body, precise and non-invasive.
- Laser Treatment:This uses focused light energy to remove or destroy cancer cells, often for superficial lesions or cosmetic refinement.
Non-invasive options like Topical Application are expanding rapidly, while Oral Administration remains critical for systemic intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regions characterized by high sun exposure and advanced healthcare infrastructure are concentrating basal cell carcinoma treatment demand. These areas benefit from established specialized dermatology clinics and robust regulatory frameworks supporting novel therapies. The market's growth trajectory is strongly influenced by demographic shifts and patient preferences in these key geographies.
United States
High incidence rates, an aging population, and advanced healthcare systems drive significant demand for basal cell carcinoma treatments. The U.S. FDA sets stringent efficacy and safety standards for new drug approvals, influencing market access for immunotherapies. Major research hubs like Boston and San Francisco are centers for biotechnology innovation, fostering new therapeutic developments.
Australia
Australia's high sun exposure and sophisticated healthcare system contribute to a pronounced demand for both surgical and non-surgical treatments. The TGA influences protocols, ensuring high standards for dermatological therapies in this high-incidence region. Specialized skin institutes in cities like Melbourne and Sydney lead in advanced skin cancer management and research.
Germany
Robust R&D investment and a strong focus on advanced medical technologies propel the adoption of targeted immunotherapies in Germany. The European Medicines Agency (EMA) governs drug approvals, ensuring high safety and efficacy for new treatments across the continent. Pharmaceutical clusters in regions like Bavaria and Hesse are key to developing innovative oncology solutions.
Canada
Patient preference for specialized care and accessible dermatology clinics boosts the utilization of various basal cell carcinoma treatment modalities. Health Canada regulates pharmaceutical products, ensuring safe and effective options are available to patients. Medical centers in Vancouver and Toronto are increasingly handling outpatient procedures and specialized dermatological services.
Basal Cell Carcinoma Treatment Market Key Industry Players
Top-tier vendors anchor the innovative pharmaceutical segment, while specialized biotech firms and generic manufacturers compete in other market areas. This structure combines established players with emerging innovators focusing on targeted solutions. Strategic archetypes include large pharmaceutical innovators, specialized immunotherapy developers, and topical therapy providers. Competitive actions frequently involve R&D investment, portfolio diversification, and strategic partnerships to expand therapeutic reach.
Within the large pharmaceutical innovators tier, F. Hoffmann-La Roche Ltd. exemplifies leadership in targeted therapies, particularly hedgehog pathway inhibitors. Regeneron Pharmaceuticals Inc. occupies a position among firms advancing immunotherapy pipelines for advanced cases. Sanofi sits within the group of companies specializing in treatments addressing specific genetic markers of the disease.
| Leading Market Players |
|---|
| Bausch Health Companies Inc. |
| F. Hoffmann-La Roche Ltd. |
| Merck & Co., Inc. |
| Sun Pharmaceuticals Ltd. |
| Novartis AG |
| Regeneron Pharmaceuticals Inc. |
| Sanofi |
| Viatris |
| Genentech, Inc. |
| Others |
Cost & Logistics Intelligence
Highly specialized dermatologists and Mohs surgeons in advanced healthcare systems like the United States contribute to significant labor-cost differentials, which influence pricing tiers for complex surgical procedures. This concentration of expertise shapes the overall market's value proposition.
Pricing Analysis
Premium pricing for rapid access to novel immunotherapies, reflecting high development costs and specialized administration, drives a value-based model for innovative targeted therapies, contrasting with fee-for-service for surgical procedures. Efficacy data and regulatory approvals from the U.S. FDA and European EMA drive price differentiation and brand premium. Pricing pressure for novel agents trends upward due to extensive R&D investments. Healthcare payers exhibit high price sensitivity for expensive systemic treatments, balancing cost-effectiveness with patient outcomes.
Supply Chain Analysis
Pharmaceutical distribution networks, involving specialized wholesalers and direct-to-clinic channels, ensure delivery of basal cell carcinoma treatments to end-users. Supply for advanced therapies concentrates in countries with robust pharmaceutical manufacturing like the United States, Germany, and Switzerland. The market draws from complex raw material dependencies, particularly for active pharmaceutical ingredients (APIs) and specialized excipients. Single-source vulnerability for proprietary novel drugs represents a structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The basal cell carcinoma treatment market is poised for consolidation, driven by the escalating costs of novel drug development. This pressure compels smaller players to seek partnerships or acquisition by larger pharmaceutical innovators.
For Market Incumbents: Hedge against the reimbursement challenges for novel therapies by investing in next-generation hedgehog pathway inhibitors and immunotherapies. Incumbents should deepen vertical integration into specialized diagnostic tools to support precision medicine approaches. Securing exclusive distribution agreements with dermatology clinics strengthens channel control and market share. Strategic partnerships with academic research institutions can accelerate pipeline development, mitigating competitive threats.
For New Entrants and Emerging Players: Specialized dermatology clinics represent a crucial channel for new entrants to penetrate the market for non-surgical basal cell carcinoma treatments. Focus on developing innovative topical therapies for superficial lesions, an expanding treatment frontier with high patient demand for cosmetic outcomes. Targeting emerging markets in Southeast Asia with affordable, accessible solutions offers significant white-space opportunity. Academic collaborations for clinical validation provide credibility and accelerate market acceptance.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized biotech firms given the continuous innovation in targeted therapies and immunotherapies. The market offers long-term viability, driven by sustained high incidence rates and patient demand for less invasive options. Acquisition targets include companies with strong intellectual property in hedgehog pathway inhibitors or novel topical agents. Watch for regulatory approvals of combination therapy regimens as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Validates novel immunotherapies for advanced basal cell carcinoma. |
| Regulatory Approval Pathway | Secures market access for new topical agents via the U.S. FDA. |
| Manufacturing Scale-Up | Ensures broad availability of hedgehog pathway inhibitors for patients. |
| Strategic Partnership | Expands distribution networks for non-surgical treatments in Canada. |
| Pipeline Diversification | Reduces reliance on single-therapy approaches for complex lesions. |
Research Approach
ClinicalTrials.gov, U.S. FDA filings, and European Medicines Agency (EMA) submissions formed the secondary backbone for this analysis. Insights from drug development executives, regulatory affairs leads, and dermatologists were integrated through primary interviews. This approach combined bottom-up market sizing with top-down validation. The data triangulation ensured comprehensive coverage of basal cell carcinoma treatment modalities.
Historical trendline analysis provided the foundation for projecting market expansion across the analysis window. The model segmented by product type, therapy area, end user, delivery mode, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth patterns and projected market penetration rates. Incidence rates and treatment adoption curves for novel therapies served as key forecast inputs.
Caveats apply where unforeseen regulatory changes or new clinical trial outcomes could materially shift the outlook. Forecasts reflect assumptions regarding treatment adoption and market access. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Brain Tumor Treatment Market
Medical Treatment
Surgical Procedures Volume Market
Medical Treatment
Bromhidrosis Disease Treatment Market
Medical Treatment
Myasthenia Gravis Treatment Market
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market
Medical Treatment
Lysosomal Storage Disease Treatment Market
Medical Treatment
Penile Cancer Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market
Medical Treatment
Transplantation Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market