
 Advanced Basal Cell Carcinoma Market | 2026-2036
Advanced Basal Cell Carcinoma Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Basal Cell Carcinoma Market Outlook
Biopharmaceutical manufacturing capacity in Switzerland is rebalancing toward precision oncology assets as blockbuster portfolios mature. Novartis AG leverages its Basel-based production network to sustain supply continuity for targeted dermatologic therapies. F. Hoffmann-La Roche Ltd. anchors its position through companion diagnostic integration with therapeutic platforms. Merck & Co., Inc. competes on immuno-oncology breadth, extending its reach into combination regimens for refractory cases.
Advanced basal cell carcinoma denotes a non-melanoma skin malignancy that has progressed beyond superficial resection boundaries, exhibiting local tissue invasion, metastatic dissemination, or recurrence following prior intervention. The condition arises from UV-induced mutational burden in basaloid epidermal cells, with sonic hedgehog pathway dysregulation serving as the principal oncogenic driver in the majority of molecularly characterized cases. Targeted therapy commands the most favorable margin profile among product categories, reflecting premium pricing for hedgehog pathway inhibitors and limited therapeutic alternatives in locally advanced disease. Immunotherapy represents the fastest-expanding treatment modality, though its addressable population remains constrained to subsets with PD-L1 expression or mismatch repair deficiency. The metastatic treatment stage absorbs disproportionate R&D investment relative to incidence, driven by unmet need and orphan drug incentive structures.
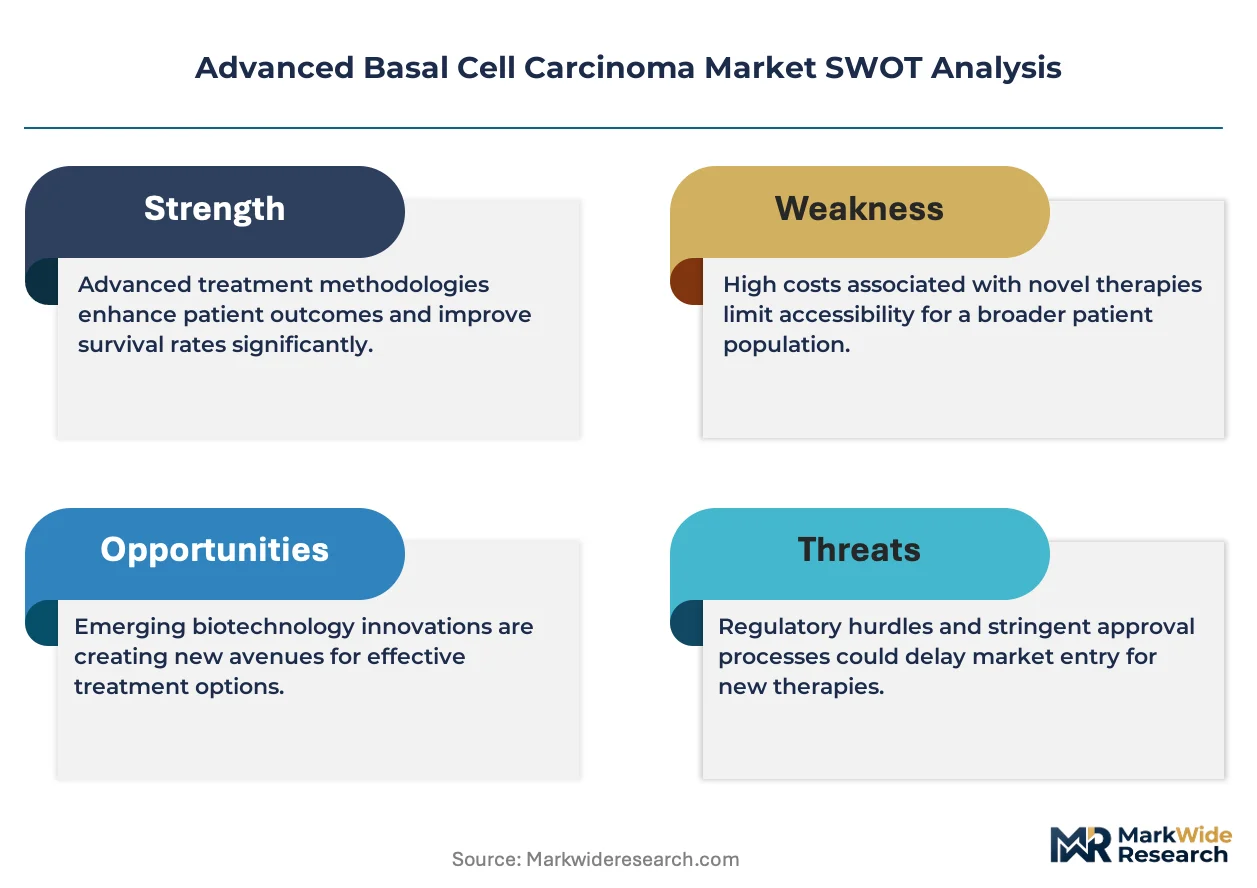
The FDA's Breakthrough Therapy designation and the EMA's PRIME eligibility framework compress development timelines for novel basal cell carcinoma agents, altering competitive dynamics for market entrants. REACH compliance and EU MDR requirements impose escalating toxicology documentation burdens on topical formulation suppliers, filtering smaller manufacturers from European distribution channels. Stakeholders must monitor pipeline readouts in the locally advanced segment, where label expansion potential could redistribute value across administration route categories and reshape hospital formulary positioning.
Market Dynamics
The FDA's accelerated approval pathways for breakthrough therapies are compressing development timelines and intensifying competitive entry velocity for hedgehog pathway inhibitors and immuno-oncology combinations.
Growth Catalysts
- EMA PRIME Eligibility:The European Medicines Agency's priority medicines framework grants enhanced scientific advice and accelerated assessment to novel basal cell carcinoma agents, reducing time-to-market for sponsors targeting the locally advanced segment.
- Oncology Clinic Expansion:Academic medical centers in the United States are scaling dedicated dermatologic oncology units, creating concentrated demand nodes for premium targeted therapy protocols and companion diagnostic integration.
- Orphan Drug Incentives:The FDA's orphan drug designation for metastatic basal cell carcinoma delivers tax credits, waived fees, and market exclusivity extensions that redirect R&D investment toward high-unmet-need subsets.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Hedgehog pathway inhibitor synthesis depends on specialized contract manufacturers clustered in Switzerland and Germany, exposing supply continuity to single-site production risks.
- REACH Toxicology Burdens:The European Chemicals Agency's escalating documentation requirements for topical formulation components filter smaller suppliers from EU distribution channels, reducing competitive pressure on incumbent pricing.
- Primary Resistance Mechanisms:SMO mutations and bypass pathway activation limit durable response rates to vismodegib and sonidegib, constraining addressable populations for targeted monotherapy.
Strategic Opportunities
- India CDSCO Fast-Track:The Central Drugs Standard Control Organisation's expedited approval pathway for oncology therapies with global reference approvals offers reduced review timelines for multinational sponsors entering the subcontinent.
- PD-1/CTLA-4 Combination Expansion:Checkpoint inhibitor pairing in PD-L1 positive refractory disease represents an underexploited label opportunity with premium pricing potential relative to single-agent immunotherapy.
- Telemedicine Triage Integration:Dermatology-focused virtual care platforms are embedding AI-assisted lesion assessment, creating new patient identification channels for referral to academic treatment centers.
Industry Challenges
- Companion Diagnostic Harmonization:Discordant PD-L1 assay platforms across FDA-cleared and laboratory-developed test categories complicate patient selection and reimbursement adjudication for immuno-oncology prescribing.
- Clinical Trial Recruitment Saturation:Competing protocols for locally advanced and metastatic populations strain patient availability at anchor sites, extending enrollment timelines and inflating per-patient acquisition costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Basal Cell Carcinoma Market |
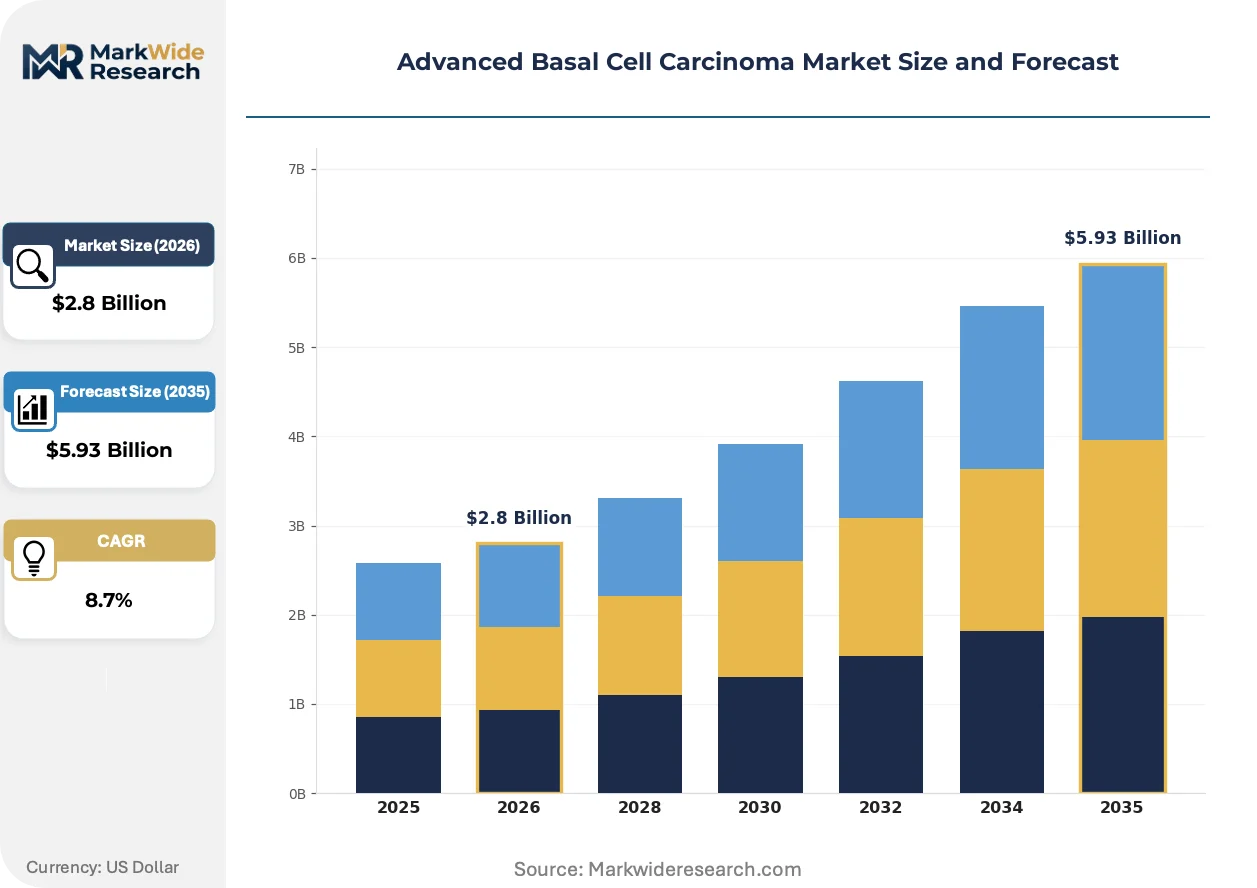
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy Treatment Stage: Early Stage, Locally Advanced, Metastatic, Recurrence Administration Route: Oral, Intravenous, Topical, Subcutaneous End User: Hospitals, Clinics, Home Care, Research Institutions |
| Companies Covered | Novartis AG, F. Hoffmann-La Roche Ltd., Merck & Co., Inc., Sun Pharmaceutical Industries Ltd., Bausch Health Companies Inc., Allergan plc, Taro Pharmaceutical Industries Ltd., Perrigo Company plc, AiViva BioPharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Basal Cell Carcinoma Market Strategic Shifts
Precision oncology platforms are displacing empirical treatment selection across the basal cell carcinoma continuum, with molecular stratification now dictating therapy allocation and trial eligibility criteria.
Artificial intelligence-powered histopathology analysis is automating margin assessment and subtyping classification in dermatopathology workflows. Community pathology laboratories are adopting these tools to reduce specialist consultation dependency. The technology is automating diagnostic throughput expansion without proportional workforce scaling, compressing time-to-treatment initiation.
REACH compliance and EU MDR requirements are escalating toxicology documentation burdens on topical formulation suppliers. Manufacturers are consolidating regulatory affairs functions and exiting lower-margin product lines to absorb compliance costs. European distribution channels are contracting toward vertically integrated sponsors with dedicated pharmacovigilance infrastructure.
Patient advocacy organizations are reshaping trial design expectations through direct engagement with FDA and EMA review divisions. These groups are demanding expanded geographic access and decentralized participation options. The United States exhibits the most organized advocacy infrastructure, with the Skin Cancer Foundation anchoring policy dialogue and reimbursement appeals support.
Advanced Basal Cell Carcinoma Market Segmentation
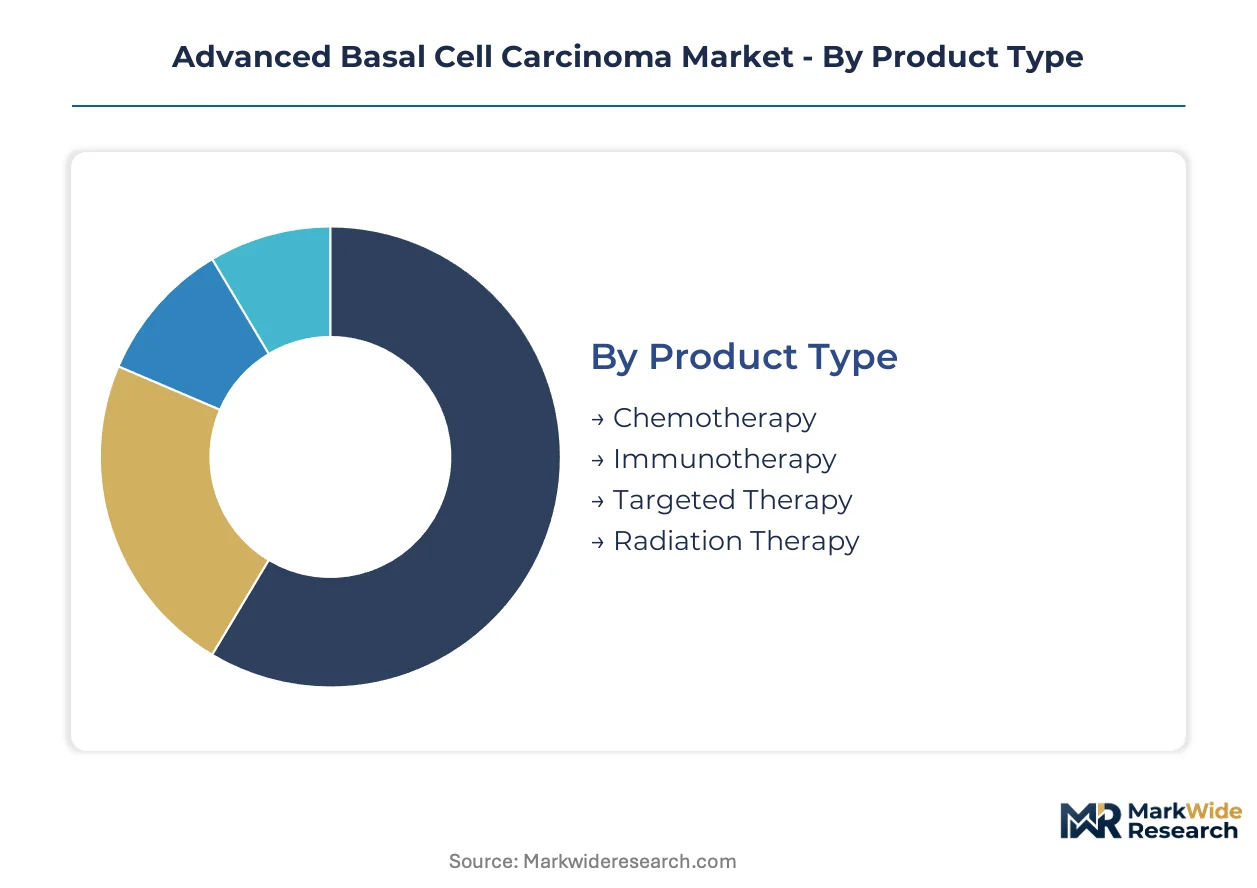
Molecular stratification and treatment modality selection reshape commercial architecture in advanced basal cell carcinoma. Segmentation reveals where capital deployment, regulatory investment, and margin capture concentrate across the therapeutic continuum.
Product Type:
Capital intensity peaks where biologics manufacturing and companion diagnostic integration converge, demanding specialized infrastructure and toxicology documentation.
- Targeted Therapy:Hedgehog pathway inhibitors require multi-step synthesis with specialized contract manufacturing. Demand concentrates in academic medical centers across the United States, where premium reimbursement and FDA breakthrough designation pathways accelerate adoption.
- Immunotherapy:Checkpoint inhibitors and combination regimens command the steepest R&D investment per patient. PD-L1 expression testing creates diagnostic-therapeutic bundling opportunities in oncology clinics scaling dedicated dermatologic units.
- Chemotherapy:Conventional cytotoxic agents retain residual utility in combination protocols with constrained development pipelines.
- Radiation Therapy:External beam and brachytherapy approaches serve localized disease with capital equipment intensity in hospital-based delivery networks.
Most installed capacity flows through targeted therapy. Expansion is steepest in immunotherapy.
Treatment Stage:
Orphan drug incentives and unmet need severity drive investment allocation toward later-stage populations with compressed survival timelines.
- Metastatic:Disseminated disease attracts disproportionate pipeline investment relative to incidence through FDA orphan designation tax credits and market exclusivity extensions. Academic medical centers anchor trial recruitment for novel agents in this subset.
- Locally Advanced:Inoperable tumors with local tissue invasion present label expansion opportunities for hedgehog inhibitors and emerging immunotherapy combinations. EMA PRIME eligibility compresses development timelines for sponsors targeting this segment.
- Recurrence:Post-intervention relapse populations require salvage protocols with resistance mechanism profiling.
- Early Stage:Superficial and nodular variants prior to progression remain dominated by surgical resection with limited pharmaceutical penetration.
Clinical trial infrastructure concentrates in metastatic populations. Patient identification technology is climbing fastest in locally advanced disease.
Administration Route:
Patient convenience and site-of-care economics determine competitive positioning across delivery modalities with divergent reimbursement structures.
- Oral:Small-molecule hedgehog inhibitors enable outpatient management with pharmacy benefit coverage. Switzerland and Germany anchor API synthesis for vismodegib and sonidegib with single-site production risk exposure.
- Intravenous:Infusion-dependent biologics require oncology clinic infrastructure with buy-and-bill reimbursement. Academic medical centers in the United States concentrate demand for checkpoint inhibitor administration.
- Topical:Localized formulations face REACH toxicology documentation burdens filtering smaller suppliers from European distribution channels.
- Subcutaneous:Self-administration potential reduces clinic burden with emerging formulation development in immuno-oncology combinations.
Revenue concentration favors oral agents. Formulation innovation is gaining share fastest in subcutaneous delivery.
End User:
Care site selection reflects disease complexity, reimbursement intensity, and clinical trial access requirements across the patient journey.
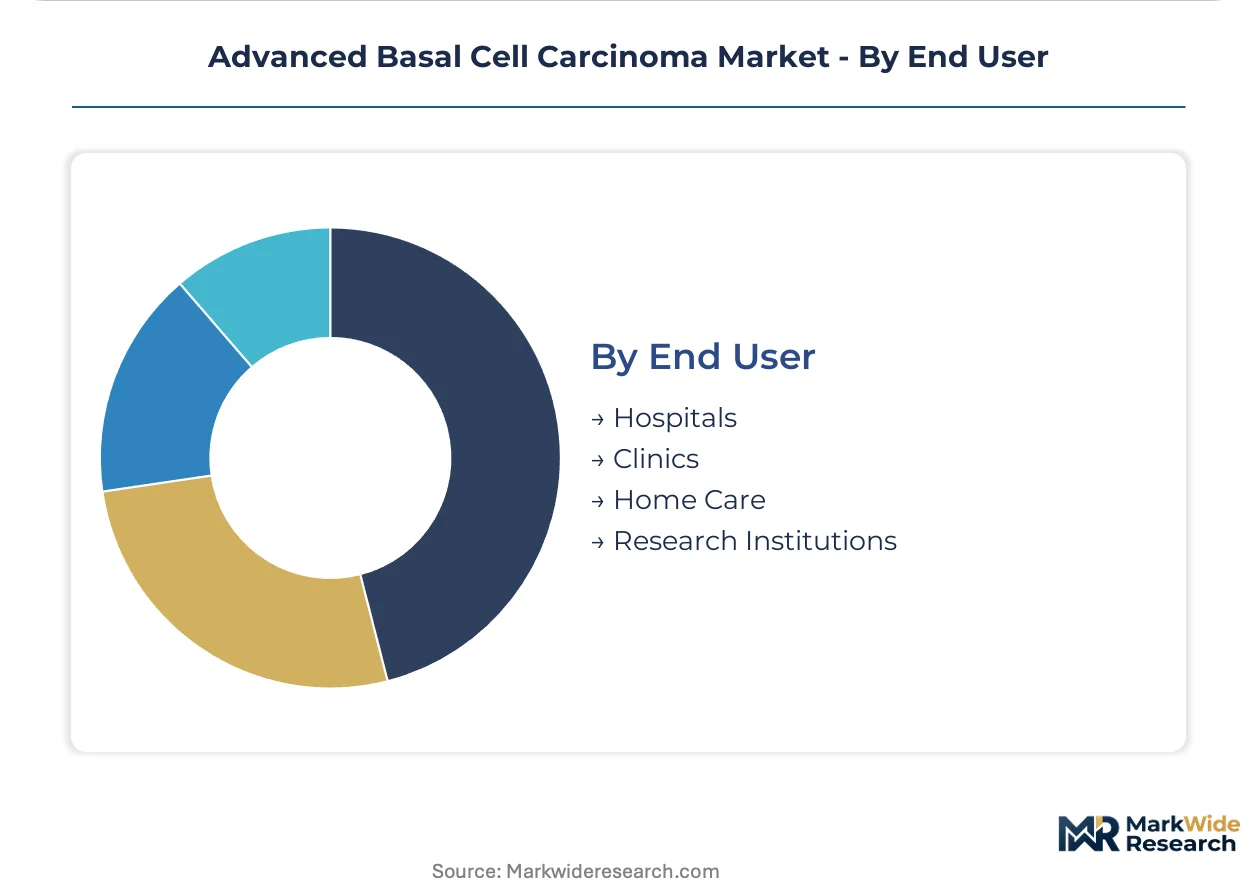
- Hospitals:Inpatient and comprehensive cancer centers manage metastatic cases with multidisciplinary coordination. The United States exhibits concentrated demand at NCI-designated centers with premium targeted therapy protocols.
- Clinics:Community and academic oncology clinics scale dermatologic oncology units for locally advanced disease. Telemedicine triage integration creates new referral channels to these sites.
- Home Care:Oral therapy administration and remote monitoring expand with patient advocacy organization pressure for decentralized participation options.
- Research Institutions:Anchor sites strain under competing protocol recruitment demands, extending enrollment timelines and inflating per-patient acquisition costs.
Prescription volume concentrates in hospitals. Service expansion is climbing fastest in clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in active pharmaceutical ingredient manufacturing is redrawing production maps, with Switzerland and Germany absorbing capacity from jurisdictions facing steeper REACH compliance burdens. Sponsors now site hedgehog inhibitor synthesis where toxicology documentation infrastructure already exists.
United States
FDA breakthrough therapy designations compress development timelines for hedgehog pathway inhibitors, drawing Novartis and Roche toward accelerated approval submissions. The Orphan Drug Act delivers tax credits and market exclusivity extensions that concentrate metastatic disease R&D in Boston and San Francisco anchor sites. NCI-designated cancer centers in these metros anchor clinical trial recruitment for refractory populations.
Switzerland
Swissmedic's alignment with EMA centralized procedures enables parallel FDA-EMA submission strategies that shorten time-to-market for Basel-based sponsors. The country's specialized contract manufacturing ecosystem sustains vismodegib and sonidegib API production with single-site concentration risks. Novartis leverages its Basel production network to maintain supply continuity for targeted dermatologic therapies.
Germany
EMA PRIME eligibility frameworks attract sponsors seeking accelerated assessment for locally advanced disease indications, with Munich and Frankfurt hosting regulatory affairs hubs. The country's REACH compliance infrastructure supports topical formulation suppliers facing escalating toxicology documentation requirements. Baden-Württemberg clusters anchor companion diagnostic development partnerships with therapeutic platforms.
India
CDSCO fast-track pathways for oncology therapies with global reference approvals offer reduced review timelines for multinational sponsors entering the subcontinent. Sun Pharmaceutical Industries leverages domestic manufacturing scale to supply emerging markets with cost-optimized formulations. Maharashtra and Gujarat states concentrate API synthesis and finished dose production for export-oriented dermatologic portfolios.
United Kingdom
MHRA post-Brexit recognition pathways maintain access for EMA-approved hedgehog inhibitors while streamlining national assessment timelines. London-based academic medical centers concentrate patient identification technology trials for locally advanced disease. The country's AI-assisted histopathology startups are automating margin assessment workflows for dermatopathology laboratories.
Advanced Basal Cell Carcinoma Market Competitive Environment
Swiss and German producers anchor the precision oncology manufacturing tier; United States and Indian specialists hold formulation and commercialization positions. The vendor base concentrates around three strategic archetypes: vertically integrated multinational pharmaceutical conglomerates, mid-cap dermatology-focused generics manufacturers, and emerging biotech platforms pursuing orphan indications. Competitive dynamics revolve around companion diagnostic bundling and accelerated regulatory pathway navigation rather than price-based displacement.
Within the integrated pharmaceutical tier, Novartis AG and F. Hoffmann-La Roche Ltd. exemplify archetypes combining Basel-based manufacturing infrastructure with companion diagnostic integration capabilities. Merck & Co., Inc. occupies a position emphasizing immuno-oncology breadth and combination regimen development. Sun Pharmaceutical Industries Ltd. represents the emerging market access archetype, leveraging Indian manufacturing scale for cost-optimized supply. These three anchors collectively illustrate how geographic specialization in API synthesis, diagnostic development, and commercial distribution now determines competitive positioning more than therapeutic modality differentiation alone.
| Leading Market Players |
|---|
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Merck & Co., Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Bausch Health Companies Inc. |
| Allergan plc |
| Taro Pharmaceutical Industries Ltd. |
| Perrigo Company plc |
| AiViva BioPharma |
| Others |
Value Chain & Pricing Dynamics
Specialized organic chemists concentrated in Basel and Munich command wage premiums that widen spreads between originator hedgehog inhibitors and emerging biosimilar entrants. Labor-cost differentials between Swiss precision-synthesis facilities and Indian contract research organizations translate directly into three-tier pricing stratification across premium, standard, and economy market levels.
Pricing Analysis
Hospital and oncology clinic procurement channels absorb manufacturer list prices through buy-and-bill reimbursement structures with limited distributor intermediation. Price differentiation hinges on FDA breakthrough therapy designation status and companion diagnostic bundling with therapeutic platforms. Cost compression in the standard tier intensifies as Indian API manufacturers scale GMP-compliant production for emerging market supply. Academic medical centers in the United States exhibit lowest price sensitivity due to premium reimbursement protocols and trial access requirements.
Supply Chain Analysis
Direct-to-hospital channels handle concentrated demand from NCI-designated cancer centers with specialized cold-chain and controlled-substance handling requirements. Active pharmaceutical ingredient synthesis draws from Switzerland, Germany, and India, with multi-step hedgehog inhibitor production resting on specialized contract manufacturing clusters in Basel and Munich. Single-site concentration risk in Swiss vismodegib API production exposes continuity to localized disruption. Distribution runs through oncology-focused specialty pharmacies with limited wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where sponsors exploit the gap between FDA breakthrough designation timelines and EMA PRIME eligibility compressions versus REACH compliance cost burdens that filter smaller European competitors.
For Market Incumbents: Extend companion diagnostic integration capabilities to lock in formulary positioning at academic medical centers facing competing protocol recruitment demands. Anchor manufacturing scale in Swiss and German clusters with existing REACH infrastructure to absorb toxicology documentation costs that exclude emerging rivals. Deepen backward integration into specialized API synthesis to mitigate single-site production risk exposure. For New Entrants and Emerging Players: Telemedicine triage platforms present the most penetrable channel for patient identification and referral capture in locally advanced disease segments. Target CDSCO fast-track pathways in India to exploit reduced review timelines for therapies with global reference approvals. Pursue white-space positioning in subcutaneous formulation development for immuno-oncology combinations with self-administration potential. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap dermatology-focused generics manufacturers with GMP infrastructure and emerging market distribution networks. Long-term viability framing centers on pipeline depth in PD-1/CTLA-4 combinations and resistance mechanism profiling capabilities. Watch for inflection signals in decentralized clinical trial participation rates as patient advocacy organizations reshape enrollment expectations.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | FDA-cleared PD-L1 assay bundling with checkpoint inhibitors locks in oncology clinic formulary positioning. |
| EMA PRIME Eligibility Pursuit | Accelerated assessment pathways compress time-to-market for locally advanced disease label expansions. |
| API Manufacturing Scale-Up | Swiss and German GMP capacity expansion absorbs REACH compliance costs that filter smaller competitors. |
| Telemedicine Triage Partnership | AI-assisted lesion assessment platforms create new patient identification channels for academic center referral. |
| CDSCO Fast-Track Navigation | Expedited Indian approval pathways with global reference enable cost-optimized emerging market entry. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at NCI-designated centers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored value estimates.
Segment-weighting approaches distributed value across treatment stage, product type, administration route, and end-user site-of-care categories throughout the projection horizon. CAGRs derived from fitted growth curves incorporating orphan drug incentive structures, regulatory pathway velocity differentials, and molecular stratification penetration rates. Modeled inputs included hedgehog inhibitor resistance mechanism prevalence and PD-L1 expression testing adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to breakthrough therapy designation revocation rates and REACH toxicology documentation escalation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Stuttering Therapeutics Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Malignant Glioma Therapeutics Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Global Cancer Therapy Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Adult Malignant Glioma Therapeutics Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Global Laryngeal Cancer Therapeutics Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Polyarticular Juvenile Idiopathic Market