
 North American Dental Software Market | 2026-2036
North American Dental Software Market Size, Share, and Industry Trends Forecast 2026-2036
North American Dental Software Market Analytics
Modular bundling of practice management with imaging and billing tools is hardening as the standard procurement format across dental groups. Henry Schein One leverages its distribution network to anchor comprehensive suite offerings. Carestream Dental LLC competes through specialized imaging workflows that integrate with third-party management platforms. Planet DDS sustains growth by focusing on cloud-native architecture for multi-site operators.
North American dental software encompasses clinical and administrative applications that manage patient records, schedule appointments, process insurance claims, and archive diagnostic images using DICOM-compliant storage protocols. These systems serve the operational backbone of dental practices, orthodontics departments, and oral surgery clinics. Cloud-based deployment leads segment momentum as practices prioritize remote accessibility and reduced IT overhead, while on-premise installations retain share among institutions with legacy infrastructure investments. Patient management solutions capture expanding budgets as consumer expectations for digital engagement reshape front-office priorities.
FDA oversight of diagnostic imaging modules, HIPAA security rule enforcement by the Office for Civil Rights, and provincial privacy commissioners in Canada govern data handling, interoperability standards, and breach notification protocols across the market. State dental boards in California, Texas, and New York impose additional documentation and retention requirements that shape vendor product roadmaps. Stakeholders must monitor evolving interoperability mandates and cybersecurity audit expectations as regulatory complexity becomes a decisive procurement filter.
Market Dynamics
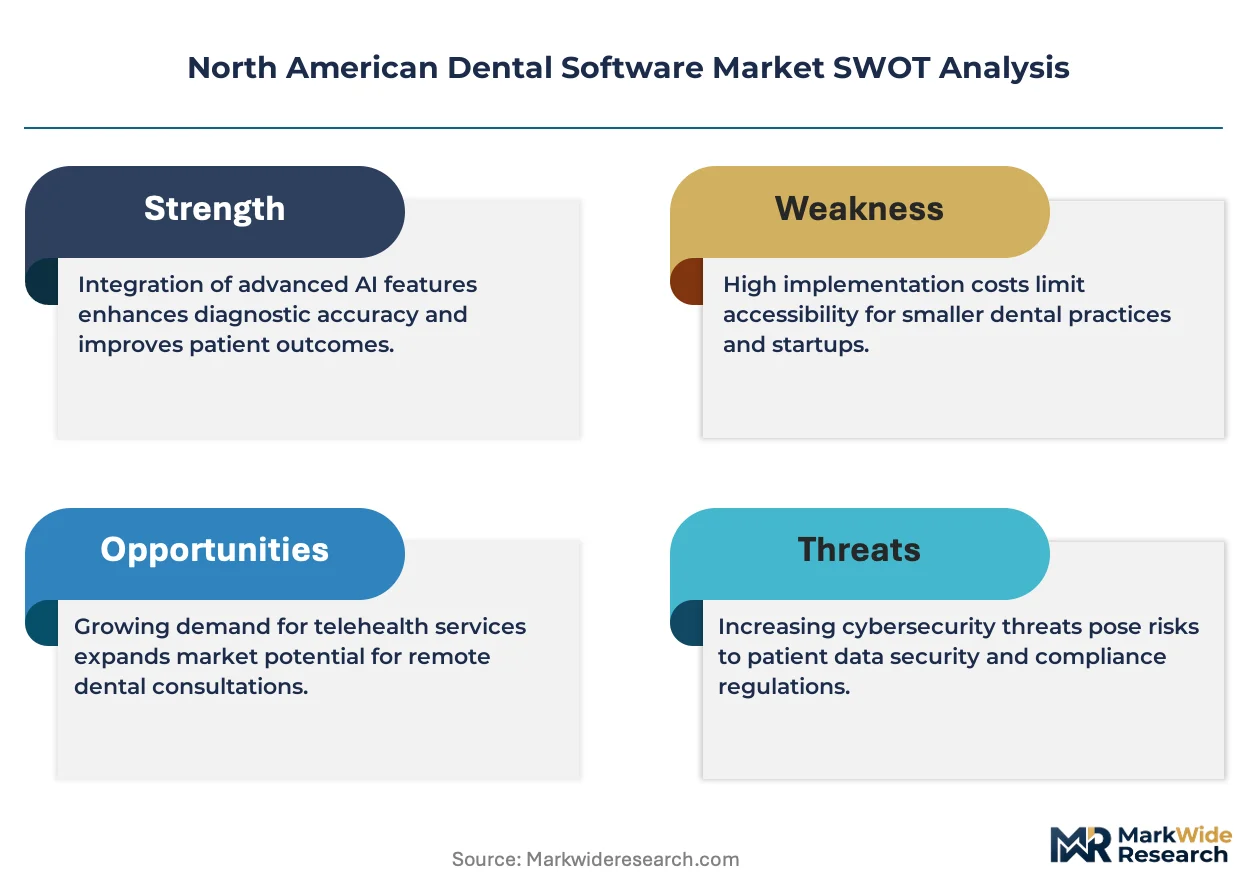
Multi-location dental service organizations are consolidating procurement power and mandating cloud-native architectures, forcing vendors to abandon perpetual licensing models in favor of subscription-based delivery that satisfies HIPAA and provincial Canadian privacy frameworks simultaneously.
Growth Catalysts
- HIPAA Security Rule Enforcement:The Office for Civil Rights is intensifying audit frequency for dental practices, accelerating replacement cycles for legacy on-premise systems that lack modern encryption protocols and automated breach detection capabilities.
- DSO Expansion:Dental service organizations across Texas, Florida, and Georgia are acquiring independent practices and standardizing on unified practice management platforms to achieve centralized scheduling, billing, and imaging workflows.
- Interoperability Mandates:The 21st Century Cures Act is compelling vendors to implement FHIR-based data exchange, creating upgrade urgency among practices still operating siloed patient record systems.
Market Restraints
- Cloud Migration Costs:Small practices in rural Ontario and the US Mountain West face prohibitive bandwidth infrastructure investments and recurring subscription burdens that strain cash-flow-dependent operations.
- Limited Vendor Pool:Specialized imaging workflow expertise concentrates among a handful of developers, creating supply concentration risk for practices seeking DICOM-compliant diagnostic archives with integrated AI-assisted radiology.
- State Documentation Variability:California, New York, and Texas dental boards impose divergent record retention periods and consent documentation standards, fragmenting product development roadmaps and delaying feature rollouts.
Strategic Opportunities
- Teledentistry Integration:Post-pandemic patient expectations for remote consultation are creating white space for platforms that embed synchronous video, asynchronous image review, and e-prescription workflows within core practice management suites.
- AI-Assisted Diagnostics:Machine learning algorithms for caries detection and periodontal assessment are converging with intraoral scanning hardware, enabling preventive care protocols that differentiate fee-for-service practices in competitive urban markets.
- Provincial Canadian Markets:Quebec and British Columbia privacy commissioners are issuing cloud-specific guidance that lags US HIPAA maturity, creating first-mover advantage for vendors with pre-built provincial compliance configurations.
Industry Challenges
- Cybersecurity Talent Scarcity:Dental practices lack in-house expertise to configure zero-trust network architectures and conduct penetration testing, forcing reliance on vendor-managed security that varies widely in sophistication.
- Legacy System Integration:Decades-old practice management databases with proprietary data formats resist migration to modern SQL-based cloud platforms, requiring expensive custom extraction and validation protocols.
- AI Diagnostic Liability:Unclear FDA guidance on software-as-a-medical-device classification for AI-powered radiographic analysis is delaying commercial deployment and creating malpractice insurance uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North American Dental Software Market |
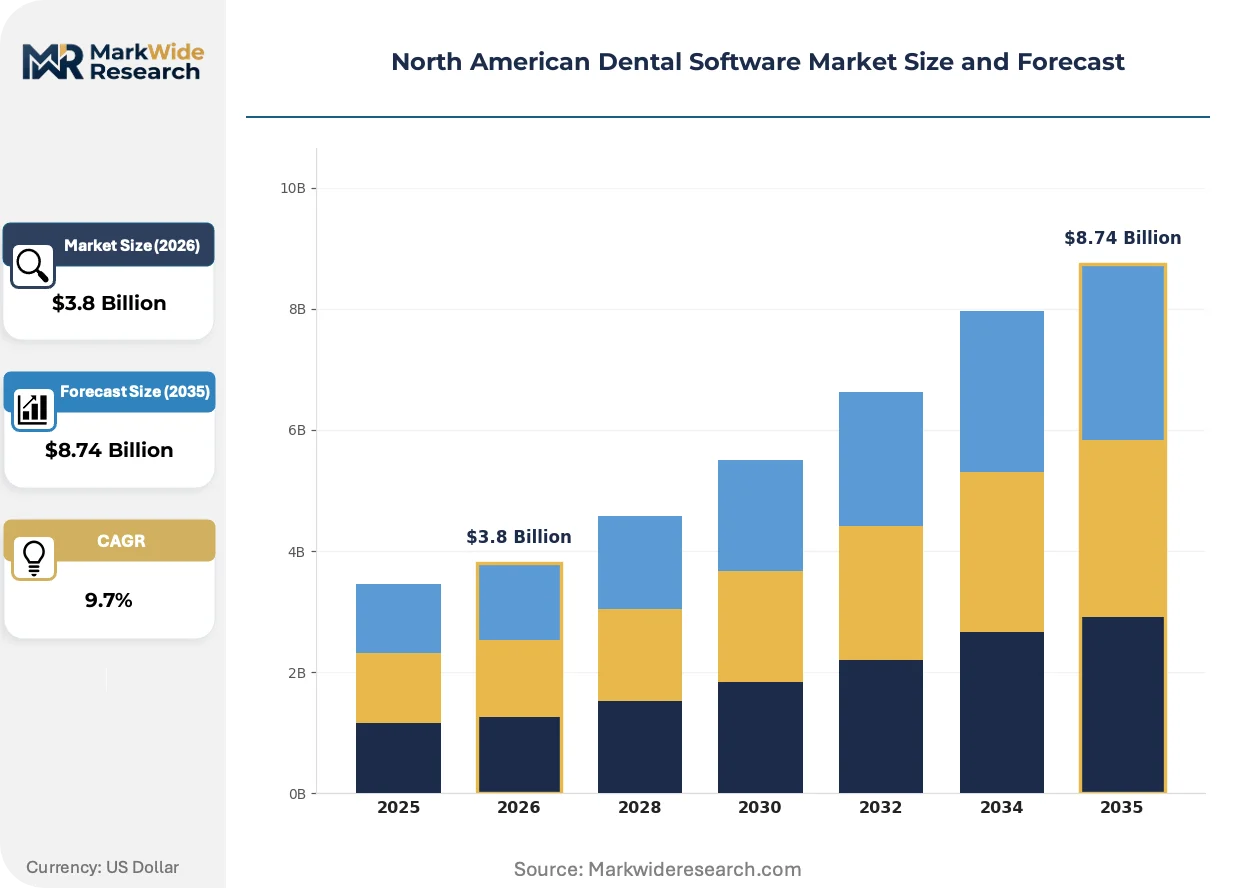
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Dentists, Dental Clinics, Hospitals, Orthodontists Solution: Practice Management, Imaging Software, Billing Software, Patient Management Feature: Appointment Scheduling, Patient Records, Inventory Management, Reporting Tools |
| Companies Covered | Carestream Dental LLC, Henry Schein One, Open Dental Software, ABELDent Inc., DentiMax, Planet DDS, CD Newco, LLC, ACE Dental, Veradigm LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North American Dental Software Market Evolving Landscape
Cloud-native architectures are absorbing capital that previously flowed to on-premise server infrastructure, while regulatory pressure and patient expectations are compressing development cycles for integrated clinical and administrative platforms.
Artificial intelligence modules for radiographic interpretation are absorbing feature development resources across the vendor landscape. These tools flag caries, bone loss, and pathology for dentist review, reducing diagnostic time per patient. Multi-site operators in the southeastern United States are adopting these capabilities fastest, drawn by throughput gains in high-volume Medicaid practices.
Health Canada and provincial privacy commissioners in Ontario and Alberta are issuing cloud-specific guidance that tightens data residency requirements for diagnostic images. This regulatory friction is fragmenting vendor deployment strategies, forcing separate Canadian infrastructure instances. Practices in Toronto and Calgary are selecting vendors with pre-certified provincial compliance to avoid audit exposure.
Subscription pricing is displacing perpetual licenses as the dominant procurement model for practice management software. Dental service organizations with 50-plus locations are negotiating enterprise agreements that bundle imaging, billing, and patient engagement tools. This concentration of buying power is most visible in Florida and Texas, where DSOs now control one-third of chair capacity in major metropolitan markets.
North American Dental Software Market Segmentation
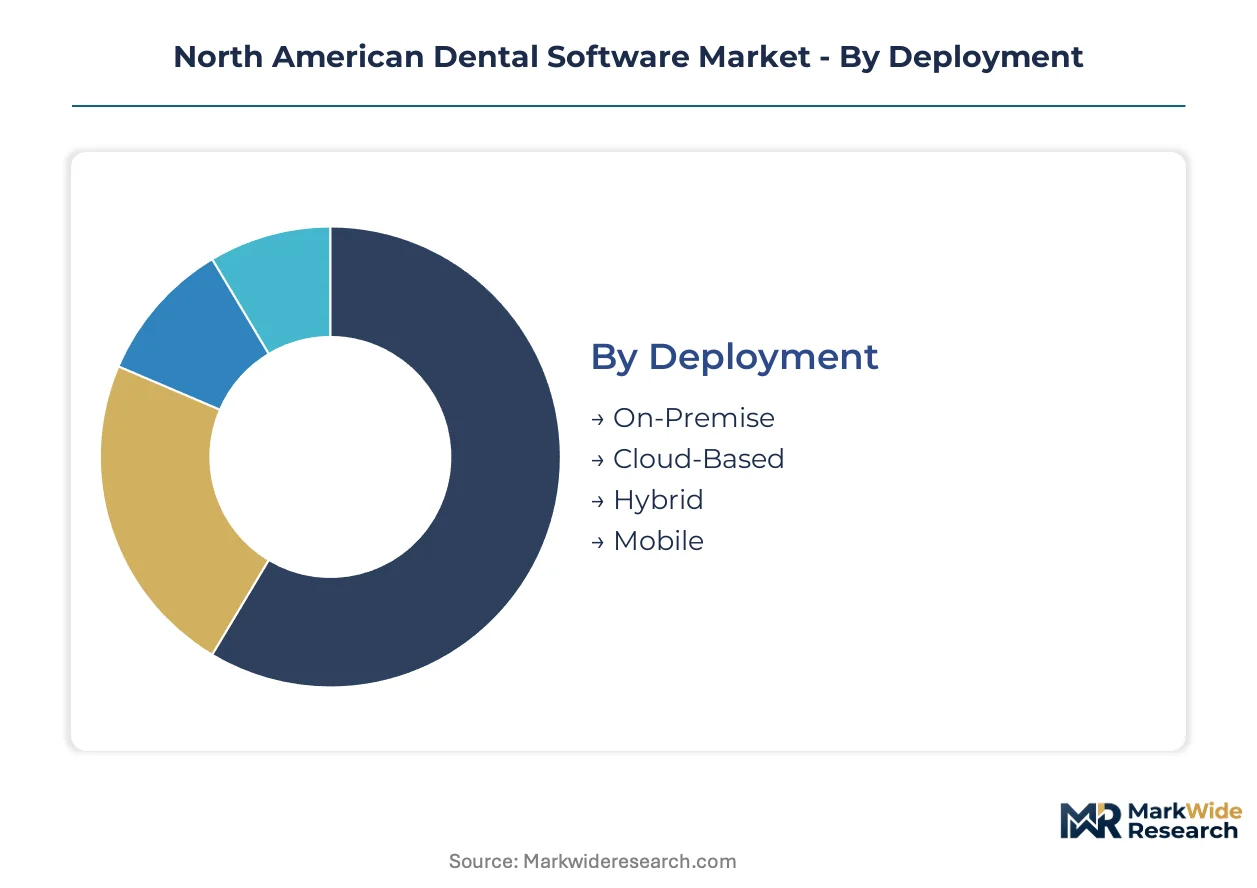
Dental software procurement in North America follows distinct decision hierarchies. Deployment architecture determines total cost of ownership and compliance posture. End-user scale dictates feature depth and integration complexity.
Deployment:
IT infrastructure maturity and HIPAA audit exposure shape deployment preferences across practice types.
- Cloud-Based:Multi-tenant SaaS platforms with automated encryption, breach detection, and geographic redundancy. Dental service organizations in Texas and Florida mandate this architecture to centralize compliance across 50-plus locations under single-instance management.
- On-Premise:Local server installations with direct hardware control and legacy database continuity. Rural practices in the US Mountain West and Ontario retain this model due to bandwidth constraints and sunk capital in physical infrastructure.
- Hybrid:Split workloads with clinical data on-site and administrative functions in cloud. Appeals to mid-size groups transitioning incrementally.
- Mobile:Native iOS and Android applications for chairside charting and image capture. Gaining traction among orthodontists with high patient throughput.
Cloud-Based leads on scale; Mobile leads on momentum.
End User:
Operational complexity and reimbursement mix create divergent software requirements across care settings.
- Dental Clinics:General practice facilities with 1-10 chairs requiring integrated scheduling, billing, and imaging. Southeastern US consolidation is concentrating demand here as DSOs standardize platforms across acquired practices.
- Dentists:Solo and small-group practitioners prioritizing cost efficiency and minimal IT overhead. Subscription fatigue is pushing this segment toward modular, best-of-breed procurement.
- Hospitals:Academic medical centers and health systems with enterprise EHR integration requirements. Demand concentrates where dental schools anchor oral surgery departments.
- Orthodontists:Specialty practices with treatment planning software, 3D model management, and extended patient engagement cycles. California and New York house the densest concentration of high-volume operators.
Dental Clinics capture the largest installed base; Orthodontists show the steepest expansion trajectory for AI-assisted treatment planning tools.
Solution:
Procurement bundling patterns reflect whether buyers prioritize clinical workflow depth or administrative efficiency.
- Practice Management:Core platforms handling scheduling, billing, claims submission, and basic reporting. DSO procurement mandates are hardening around cloud-native suites with API extensibility.
- Imaging Software:DICOM-compliant diagnostic archives with AI-assisted radiographic interpretation. Integration with intraoral scanners and CBCT hardware drives upgrade cycles.
- Billing Software:Revenue cycle management with automated eligibility verification and denial tracking. Critical for Medicaid-dependent practices in high-volume markets.
- Patient Management:Digital engagement tools including portals, automated reminders, and teledentistry modules. Front-office priorities are reshaping budget allocation here.
Practice Management anchors procurement decisions; Patient Management is gaining share fastest as consumer expectations reshape practice operations.
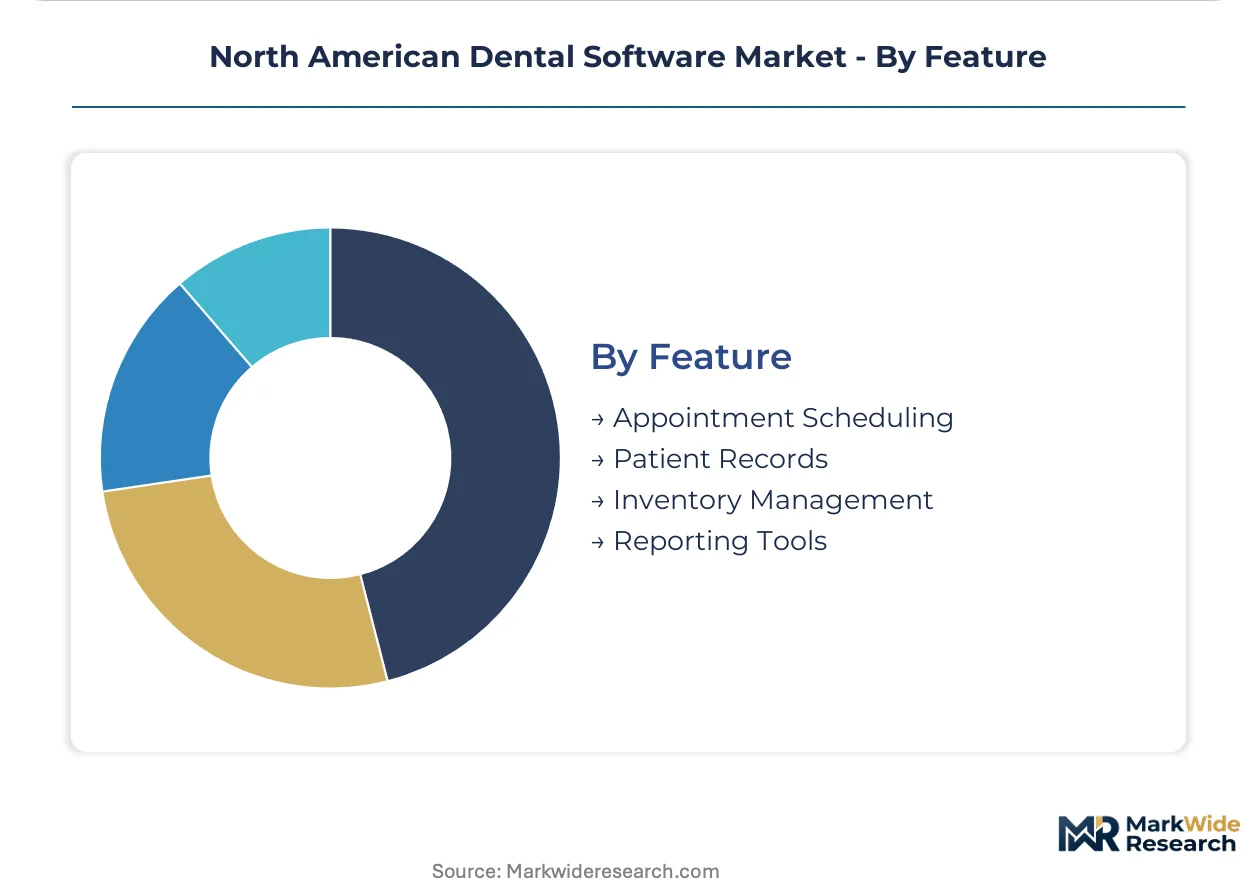
Feature:
Feature adoption correlates with staff-to-patient ratios and regulatory documentation burdens.
- Patient Records:Electronic health records with periodontal charting, treatment history, and consent documentation. State dental boards in California, Texas, and New York impose divergent retention rules that fragment vendor roadmaps.
- Appointment Scheduling:Calendar optimization with automated reminders and waitlist management. Essential for high-volume Medicaid practices in the southeastern United States.
- Inventory Management:Supply tracking with automated reorder points and expiration alerts. Gains priority in multi-site operations seeking procurement leverage.
- Reporting Tools:Analytics dashboards for production metrics, payer mix analysis, and compliance audit trails. DSOs use these for centralized performance management.
Patient Records commands the deepest integration requirements; Reporting Tools are climbing fastest as data-driven practice management spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American dental software industry traces its commercial roots to the United States, where early practice management systems emerged from university dental schools and imaging research centers during the 1980s.
United States
Dental service organizations across Texas, Florida, and Georgia are consolidating procurement power and mandating cloud-native architectures. HIPAA Security Rule enforcement by the Office for Civil Rights accelerates replacement cycles for legacy systems lacking modern encryption. Atlanta and Dallas house the densest concentration of multi-site operators standardizing unified platforms.
Canada
Provincial privacy commissioners in Ontario, Quebec, and British Columbia are issuing cloud-specific guidance that tightens data residency requirements for diagnostic images. Health Canada oversight of diagnostic imaging modules shapes vendor deployment strategies. Toronto and Calgary practices prioritize vendors with pre-certified provincial compliance configurations.
Southeastern United States
Dental practice consolidation concentrates most intensely across Florida, Georgia, and the Carolinas, where DSOs now control significant metropolitan chair capacity. State dental boards impose documentation requirements that fragment vendor product roadmaps. Miami and Charlotte serve as hubs for high-volume Medicaid practices adopting AI-assisted radiographic tools.
Southwestern United States
Texas anchors demand expansion as independent practices convert to DSO-affiliated operations requiring centralized management platforms. Bandwidth infrastructure investments strain rural operators in the Mountain West adjacent to this region. Houston and Austin dental groups negotiate enterprise agreements bundling imaging, billing, and patient engagement tools.
Northeastern United States
Academic medical centers in New York and Massachusetts drive enterprise EHR integration requirements for hospital-affiliated dental departments. State dental boards in New York impose divergent record retention periods that complicate vendor compliance engineering. Boston and New York City house the densest concentration of high-volume orthodontists adopting 3D treatment planning software.
North American Dental Software Market Competitive Landscape
The competitive structure tilts toward distribution-anchored suite providers and cloud-native specialists. Henry Schein One leverages its healthcare supply chain footprint to bundle practice management with imaging and billing tools. Carestream Dental LLC competes through specialized imaging workflows. Planet DDS sustains growth by targeting multi-site operators with cloud-native architecture. Consolidation pressure from DSO procurement mandates is forcing vendors to abandon perpetual licensing for subscription models.
Among distribution-anchored incumbents, Henry Schein One occupies a position exemplifying comprehensive suite offerings. Carestream Dental LLC and Planet DDS represent contrasting archetypes: the former anchors specialized imaging expertise, while the latter exemplifies cloud-native architecture for multi-location deployment. These three companies collectively illustrate the strategic divergence between hardware-integrated imaging specialists and software-native platform builders reshaping vendor selection criteria across dental service organizations.
| Leading Market Players |
|---|
| Carestream Dental LLC |
| Henry Schein One |
| Open Dental Software |
| ABELDent Inc. |
| DentiMax |
| Planet DDS |
| CD Newco, LLC |
| ACE Dental |
| Veradigm LLC |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure costs cascade through subscription tiers as data center capacity in Virginia and Oregon feeds SaaS platforms priced by chair count and feature depth. HIPAA-compliant hosting premiums concentrate in enterprise agreements negotiated by Dental Service Organizations across Texas and Florida, compressing margins for vendors serving solo practitioners in bandwidth-constrained rural markets.
Pricing Analysis
Per-seat subscription models with volume-scaled enterprise tiers dominate procurement across North American dental software. Price differentiation rests on DSO chair count thresholds and provincial Canadian compliance certification. Pricing pressure intensifies as Henry Schein One bundles imaging and billing tools at discounted rates, forcing pure-play vendors toward feature unbundling. Solo practitioners in the US Mountain West exhibit highest price sensitivity, while multi-site operators in Atlanta and Dallas prioritize total cost of ownership over per-seat rates.
Supply Chain Analysis
Software engineering talent scarcity in Austin and Toronto constrains development velocity for cloud-native platforms competing with legacy migration projects. Vendor engineering operations draw from India and Eastern European talent pools for quality assurance and FHIR interoperability modules. Single-source vulnerability concentrates in DICOM imaging codec licensing from German and Japanese specialty developers. Distribution runs through Henry Schein's healthcare supply chain for on-premise hardware bundles, while direct SaaS provisioning bypasses traditional channels for cloud-native vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American dental software market compounds steadily as DSO procurement consolidation mandates platform standardization across hundreds of acquired practices annually.
For Market Incumbents: Anticipate margin compression from cloud infrastructure cost pass-through and DSO buying power concentration. Defensive moves require backward integration into AI-assisted diagnostic modules and captive data center capacity in Canadian provinces with tightening residency requirements. Certification investment in Quebec and British Columbia privacy configurations preserves pricing power in enterprise segments. For New Entrants and Emerging Players: Capture white space in teledentistry-native platforms for orthodontists and oral surgery practices in California and New York. The most penetrable segment comprises mid-size groups with 10-30 chairs seeking modular procurement outside DSO procurement umbrellas. Go-to-market execution should emphasize API-first architecture enabling rapid EHR integration with hospital-affiliated dental departments. For Investors and Strategic Acquirers: Consolidation pressure builds where imaging workflow expertise concentrates among developers with FDA 510(k) clearance and Health Canada device licenses. Long-term viability favors platforms with proven multi-tenant scalability and provincial Canadian compliance pre-certification. Acquisition targets should demonstrate recurring revenue above industry median and FHIR-native data exchange capabilities. Watch DSO bankruptcy filings and private equity roll-up pace as inflection indicators for vendor pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | HIPAA Security Rule enforcement by the Office for Civil Rights accelerates replacement cycles for encryption-deficient legacy systems. |
| Provincial Compliance Pre-Certification | Ontario and British Columbia privacy commissioners' data residency mandates favor vendors with pre-built Canadian infrastructure instances. |
| AI-Assisted Diagnostic Integration | FDA software-as-a-medical-device classification uncertainty delays commercial deployment but creates differentiation for cleared algorithms. |
| DSO Enterprise Agreement Expansion | Texas and Florida DSOs controlling one-third of metropolitan chair capacity negotiate bundled imaging, billing, and patient engagement suites. |
| Teledentistry Module Development | Post-pandemic patient expectations for remote consultation reshape front-office budget allocation toward synchronous video and asynchronous image review. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with dental practice IT directors, DSO procurement officers, platform engineering leads at software vendors, and provincial Canadian privacy compliance consultants. Secondary validation drew from HIPAA breach notification databases, Health Canada medical device licenses, state dental board documentation requirements, and DSO M&A transaction records. Bottom-up practice-level demand estimation triangulated against top-down vendor revenue aggregation across deployment models and end-user segments.
Historical reference periods anchored the projection horizon to pre-pandemic baseline growth, pandemic disruption trough, and post-pandemic recovery trajectory. The analytical framework modeled deployment architecture, end-user scale, solution bundling patterns, and geographic regulatory clusters across the analysis window. CAGRs derived from segment-level growth rate distributions weighted by installed base migration velocity and replacement cycle acceleration from HIPAA audit intensity. Forecast inputs incorporated DSO acquisition pace, cloud infrastructure cost curves, and AI diagnostic module regulatory clearance timelines.
DSO bankruptcy waves, provincial Canadian privacy commissioner enforcement actions, and FDA software-as-a-medical-device reclassification are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about sustained HIPAA audit frequency and stable DSO capital availability for practice acquisition. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
Healthcare IT Consulting Services Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
Global Dental Software Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Epharmacy Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
US Revenue Cycle Management Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market