
 Paresthesia Treatment Market | 2026-2036
Paresthesia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Paresthesia Treatment Market Analysis
Asset-light leasing models for spinal cord stimulators and peripheral nerve stimulation devices is reconfiguring competitive dynamics, allowing smaller clinics to offer advanced paresthesia interventions without capital-intensive equipment purchases. Medtronic plc leverages its integrated neuromodulation portfolio to sustain leadership across implantable device categories. Abbott Laboratories anchors its position through proprietary dorsal root ganglion stimulation technology that differentiates its offering from conventional spinal cord platforms. Pfizer Inc. competes in the pharmacologic segment with established neuropathic pain formulations that occupy broad prescriber mindshare.
Paresthesia treatment encompasses pharmacologic, interventional, and rehabilitative modalities targeting abnormal spontaneous sensations—tingling, numbness, burning—resulting from peripheral or central nervous system dysfunction, with nerve stimulation systems delivering precisely calibrated electrical impulses at frequencies of 10-120 Hz to interrupt aberrant signaling pathways. Medications and nerve stimulation represent the dominant product categories, with the former capturing mature margin pools through genericized oral agents and the latter generating premium returns via implantable pulse generators requiring recurring programming services. The peripheral neuropathy indication segment leads volume due to diabetes-related etiologies, while multiple sclerosis-associated paresthesia commands higher per-patient treatment intensity.
The FDA's Breakthrough Device Designation and premarket approval pathways govern neuromodulation market access in the United States, while the European Medicines Agency coordinates centralized marketing authorization for pharmacologic agents under the EU Medical Device Regulation framework. These regulatory structures elevate clinical evidence requirements, concentrating commercial viability among organizations with robust trial infrastructure and post-market surveillance capabilities. Stakeholders must monitor evolving reimbursement thresholds for non-pharmacologic interventions as payors recalibrate coverage policies against functional outcome metrics.
Market Dynamics
Asset-light leasing models for spinal cord stimulators are collapsing capital barriers for smaller clinics, enabling mid-tier pain management centers to deploy advanced neuromodulation without multi-million dollar equipment commitments.
Growth Catalysts
- FDA Breakthrough Device Designation:The FDA's accelerated pathway compresses premarket timelines for novel neuromodulation systems, channeling venture funding toward paresthesia-specific hardware development.
- Diabetes-related peripheral neuropathy:Rising diabetic populations in Germany and the United States are expanding the addressable patient base for nerve stimulation interventions.
- Closed-loop stimulation algorithms:Real-time adaptive programming reduces manual titration visits, improving clinic throughput and patient adherence metrics.
Market Restraints
- Implantable pulse generator costs:Titanium enclosures and biocompatible battery chemistries concentrate manufacturing in Swiss and German precision metalwork clusters, exposing margins to raw material volatility.
- EMA MDR compliance burdens:The EU Medical Device Regulation's clinical evidence requirements extend certification timelines for peripheral nerve stimulators beyond 24 months.
- Oral generic substitution:Gabapentin and pregabalin commoditization pulls prescribing away from interventional modalities in cost-sensitive health systems.
Strategic Opportunities
- India's underserved pain clinics:The country's CDSCO is streamlining medical device registration, opening entry for dorsal root ganglion stimulation platforms in tier-2 cities.
- Home-based transcutaneous devices:Bluetooth-enabled wearable stimulators bypass implantation risks while capturing chronic paresthesia patients earlier in disease progression.
- Japan's aging reimbursement expansion:METI and PMDA coordination is broadening national health insurance coverage for non-pharmacologic neuropathy management.
Industry Challenges
- Electrophysiologist training pipelines:Surgical implantation of spinal cord stimulators requires specialized fellowship programs that produce fewer than 200 qualified specialists annually in the United States.
- Legacy EMR integration:Programming software from incumbent device manufacturers lacks interoperability with hospital electronic medical record systems, forcing manual data re-entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paresthesia Treatment Market |
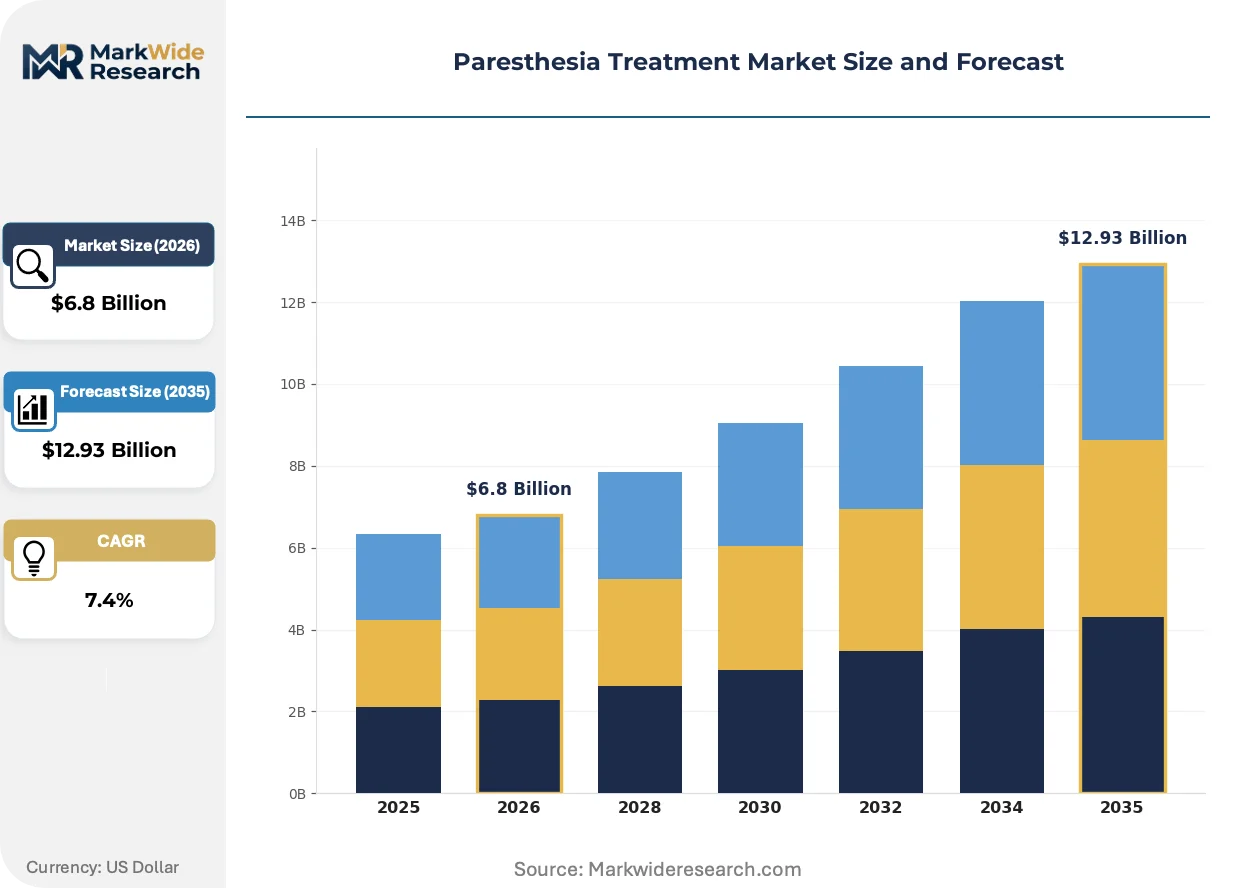
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Physiotherapy, Surgery, Nerve Stimulation Indication: Peripheral Neuropathy, Multiple Sclerosis, Stroke, Diabetes End User: Hospitals, Clinics, Rehabilitation Centers, Homecare Delivery Mode: Intravenous, Oral, Transdermal, Injections |
| Companies Covered | Medtronic plc, Abbott Laboratories, Pfizer Inc., AstraZeneca plc, AbbVie Inc., Novartis AG, Boston Scientific Corporation, Eli Lilly and Company, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paresthesia Treatment Market Emerging Trajectories
Neuromodulation hardware and service delivery models are undergoing simultaneous transformation, with software-defined therapy parameters and remote monitoring capabilities displacing static implantable systems.
Closed-loop adaptive stimulation is collapsing the distinction between initial programming and long-term device management. These systems automatically adjust electrical output based on real-time neural feedback, eliminating quarterly clinic visits for parameter tuning. Academic medical centers in the United States and university hospitals in Germany are piloting these platforms for multiple sclerosis-associated paresthesia, compressing total cost-of-care calculations for payors.
The EU Medical Device Regulation's post-market surveillance requirements are forcing manufacturers to maintain active implant registries. EMA-coordinated vigilance obligations now mandate 10-year follow-up data for Class III neuromodulation devices, elevating documentation costs but creating competitive moats against undercapitalized entrants. German notified bodies are processing certification applications with particular scrutiny for novel electrode materials.
Subscription-based device access is replacing outright capital purchase in North American pain management networks. Hospital systems in Texas and California are contracting for spinal cord stimulator hardware as operational expenses rather than balance-sheet assets, transferring obsolescence risk to manufacturers. This procurement evolution favors vendors with integrated service capabilities over pure hardware suppliers.
Paresthesia Treatment Market Segmentation
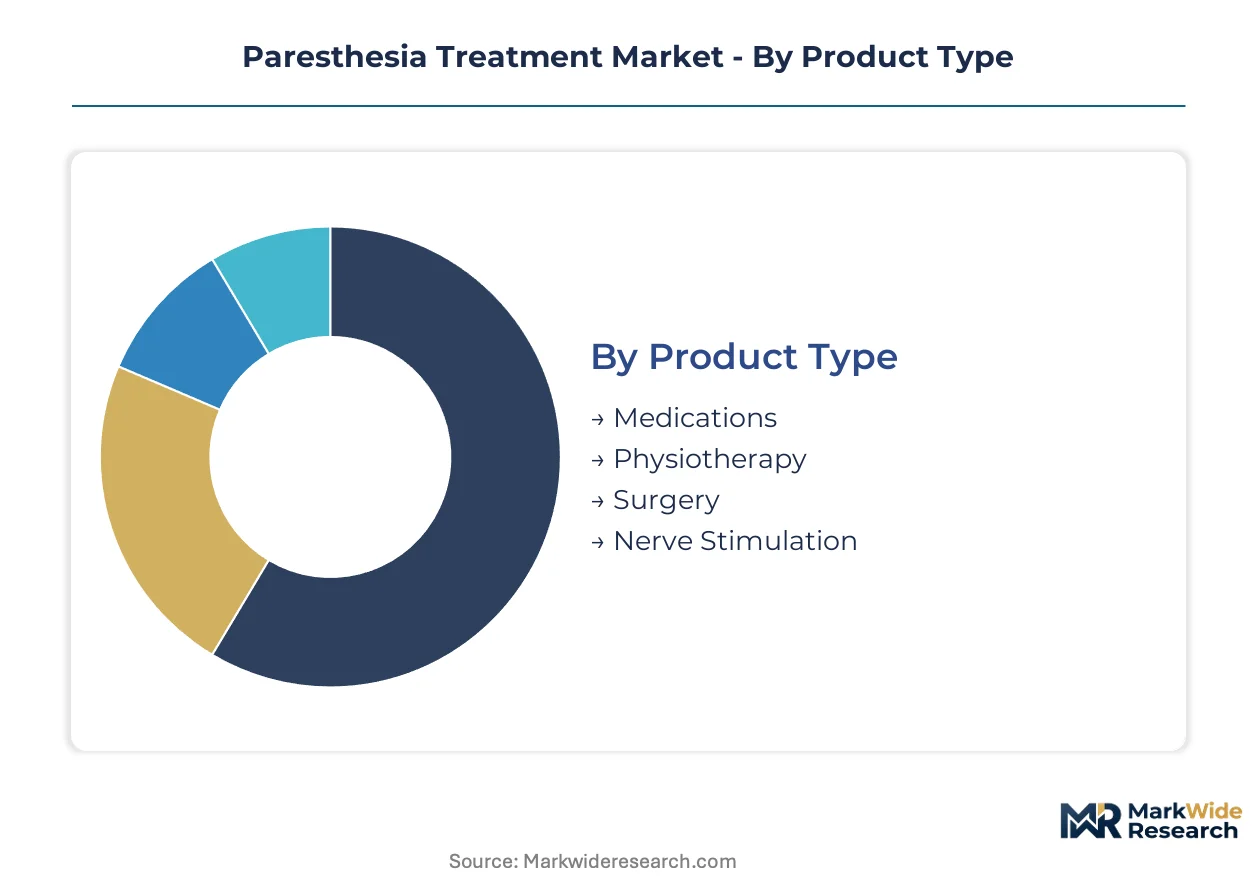
Treatment modality selection in paresthesia management hinges on etiology severity, reimbursement coverage, and patient candidacy for invasive intervention. Segmentation reveals how pharmacologic, interventional, and rehabilitative approaches partition the addressable population across acute and chronic care settings.
Product Type:
Cost tier stratification separates commodity oral agents from premium implantable hardware requiring surgical placement and recurring programming services.
- Medications:Oral gabapentinoids and topical lidocaine formulations constitute the first-line pharmacologic approach for peripheral neuropathy presentations. Demand concentrates in Medicare-covered populations across Florida and Arizona, where polypharmacy management protocols favor established agents with predictable adverse event profiles over novel mechanisms.
- Nerve Stimulation:Implantable pulse generators and external transcutaneous units deliver calibrated electrical impulses at 10-120 Hz to interrupt aberrant sensory signaling. German pain management clinics in Munich and Hamburg are integrating spinal cord stimulators into standard diabetic neuropathy protocols, driven by statutory health insurance reimbursement expansion for non-pharmacologic interventions.
- Physiotherapy:Targeted desensitization protocols and neuromuscular re-education address residual functional impairment following nerve injury resolution.
- Surgery:Decompression procedures and nerve grafting reserve for compressive etiologies refractory to conservative management, requiring microsurgical expertise concentrated in academic medical centers.
Medications hold installed capacity. Nerve stimulation is rotating up the share rankings.
Indication:
Application severity determines treatment intensity, with progressive neurodegenerative conditions demanding multimodal intervention compared to reversible metabolic etiologies.
- Peripheral Neuropathy:Distal symmetric polyneuropathy from diabetes, chemotherapy, or alcohol-related toxicity generates the highest procedure volume for nerve conduction studies and stimulation trials. United States endocrinology practices in Texas and California are co-locating neuromodulation screening within diabetes care workflows.
- Multiple Sclerosis:Central demyelination produces dysesthesia requiring disease-modifying therapy alongside symptomatic management. University hospitals in Germany and the United Kingdom are piloting closed-loop spinal cord stimulation for MS-associated paresthesia, compressing total cost-of-care through reduced programming visits.
- Stroke:Post-thalamic pain syndrome and spasticity-related sensory disturbance respond to combined pharmacologic and rehabilitative protocols.
- Diabetes:Distinct from generalized peripheral neuropathy, this segment captures isolated mononeuropathies and radiculopathies with targeted intervention potential.
Peripheral neuropathy commands current volume leadership. Multiple sclerosis is climbing the fastest as adaptive stimulation algorithms mature.
End User:
Customer type dictates capital deployment models, with institutional purchasing power contrasting against distributed home-based delivery economics.
- Hospitals:Academic medical centers and community hospital systems anchor implantable device volume through bundled payment arrangements for spinal cord stimulator placement. North American health systems in Illinois and Ohio are expanding dedicated neuromodulation suites with intraoperative neurophysiological monitoring capabilities.
- Clinics:Ambulatory pain management centers leverage asset-light leasing models to deploy peripheral nerve stimulators without balance-sheet equipment commitments. Pain clinics in Bavaria and Baden-Württemberg are capturing German statutory insurance reimbursement for outpatient stimulation trials.
- Rehabilitation Centers:Post-acute facilities integrate transcutaneous electrical nerve stimulation into functional recovery protocols for stroke and trauma patients.
- Homecare:Bluetooth-enabled wearable stimulators and medication adherence platforms extend chronic management beyond facility walls, capturing patients earlier in disease progression.
Hospitals retain procedural revenue concentration. Homecare is gaining share fastest as remote monitoring platforms mature.
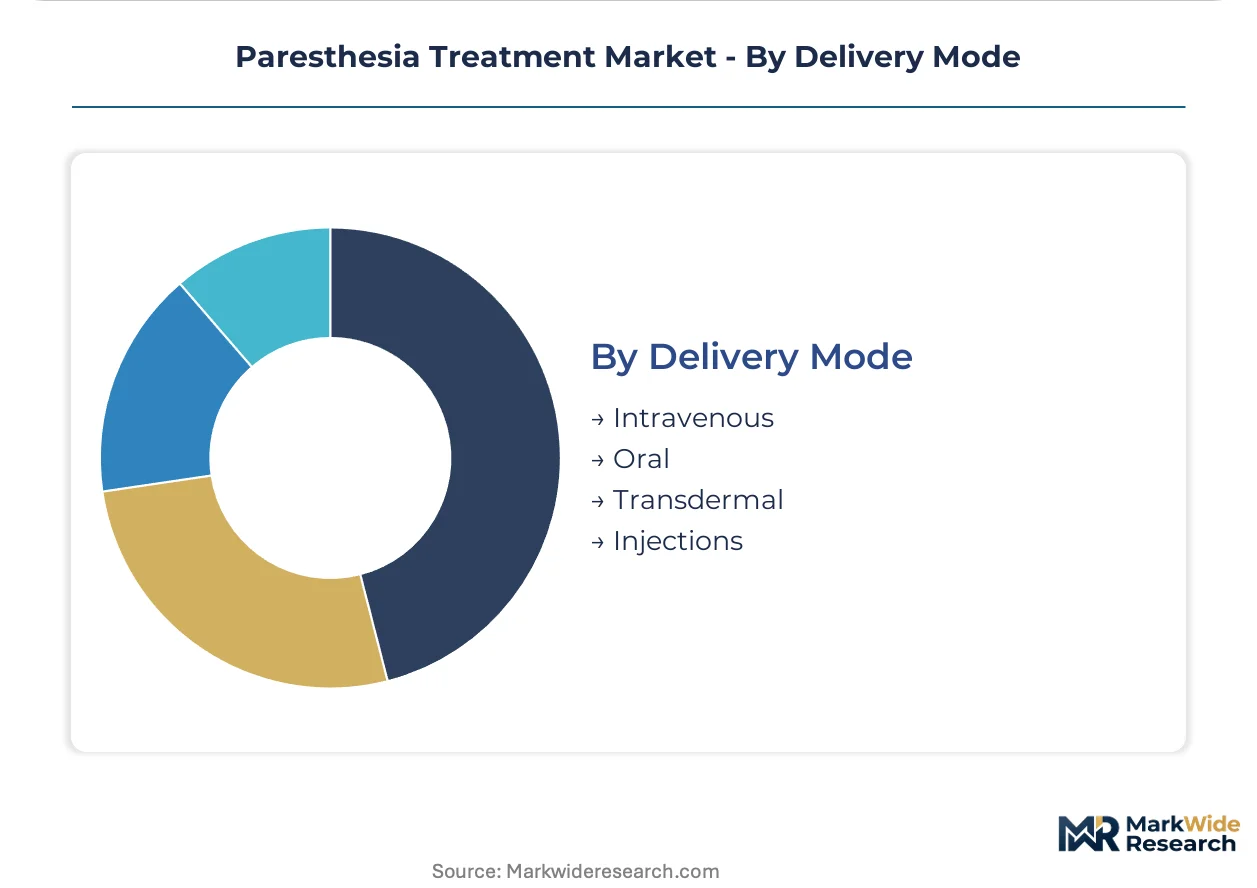
Delivery Mode:
Administration route shapes pharmacokinetic profiles, patient compliance, and manufacturing margin structures across the therapeutic portfolio.
- Oral:Immediate-release and extended-release gabapentinoid formulations dominate chronic neuropathic pain maintenance, with generic competition compressing margins on mature molecules. United States pharmacy benefit managers in Pennsylvania and New Jersey are tightening prior authorization criteria for branded alternatives.
- Transdermal:Lidocaine patches and capsaicin formulations provide localized relief without systemic exposure, appealing to polypharmacy patients in geriatric populations. German long-term care facilities are standardizing 5% lidocaine patch protocols for diabetic foot paresthesia.
- Injections:Nerve blocks and depot corticosteroid preparations address acute exacerbations and diagnostic localization.
- Intravenous:Infusion therapies reserve for inpatient acute presentations and breakthrough pain management in oncology settings.
Oral formulations hold installed capacity. Transdermal delivery is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways and statutory reimbursement expansion are redirecting capital toward neuromodulation infrastructure. Germany, the United States, Japan, India, and the United Kingdom concentrate device deployment and pharmacologic consumption.
United States
Hospital systems in Texas and Illinois are expanding dedicated neuropathy units with intraoperative neurophysiological monitoring capabilities. The FDA's Breakthrough Device Designation compresses premarket timelines for novel spinal cord stimulators. Medicare-covered populations in Florida and Arizona drive oral gabapentinoid demand through polypharmacy management protocols.
Germany
Specialized pain management clinics in Munich and Hamburg are integrating nerve stimulation into standard diabetic neuropathy care workflows. The EMA's MDR framework governs centralized marketing authorization for implantable pulse generators. Bavarian and Baden-Württemberg pain clinics capture statutory health insurance reimbursement for outpatient stimulation trials.
Japan
Aging demographics are expanding the addressable patient base for non-pharmacologic neuropathy interventions. METI and PMDA coordination is broadening national health insurance coverage for neuromodulation devices. University hospitals in the Kanto region pilot closed-loop adaptive stimulation for multiple sclerosis-associated paresthesia.
India
Tier-2 cities present entry opportunities for dorsal root ganglion stimulation platforms as chronic disease burdens rise. The CDSCO is streamlining medical device registration timelines for foreign manufacturers. Maharashtra and Karnataka host emerging pain clinic networks adopting asset-light leasing models for peripheral nerve stimulators.
United Kingdom
NHS bundled payment arrangements are reshaping procurement economics for implantable devices. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR clinical evidence standards. London and Southeast England academic medical centers concentrate surgical implantation expertise for spinal cord stimulator placement.
Paresthesia Treatment Market Vendor Landscape
On the supply side, the industry is bifurcated between diversified medical technology conglomerates and specialized neuromodulation pure-plays. Consolidation pressures favor organizations with integrated service capabilities over pure hardware suppliers. Three archetypes dominate: implantable device manufacturers with recurring programming revenue streams, established pharmaceutical houses with genericized neuropathic pain portfolios, and emerging wearable stimulator developers targeting home-based delivery. Competitive moves center on subscription-based hardware access arrangements and backward integration into electrode material supply.
Within the diversified medical technology tier, Medtronic plc and Abbott Laboratories exemplify scale-driven positioning through integrated neuromodulation portfolios. Boston Scientific Corporation occupies a specialist position in interventional pain management devices. Among pharmaceutical incumbents, Pfizer Inc. and Eli Lilly and Company represent established prescriber relationships in neuropathic pain therapeutics. These named entities anchor archetype boundaries rather than exhaust competitive taxonomy.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Pfizer Inc. |
| AstraZeneca plc |
| AbbVie Inc. |
| Novartis AG |
| Boston Scientific Corporation |
| Eli Lilly and Company |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Swiss precision metalwork clusters in Solothurn and Jura anchor titanium enclosure production for implantable pulse generators, concentrating upstream capacity and feeding downstream pricing power to device manufacturers with captive supply relationships. Battery chemistry sourcing from German specialty chemical producers tightens cost control for neuromodulation hardware, while procurement managers at North American hospital systems negotiate subscription-based access that transfers obsolescence risk upstream.
Pricing Analysis
Certification level (FDA Breakthrough Device versus standard 510(k) versus CE-marked MDR Class III) creates the primary spread between premium implantable systems and commoditized external stimulators. Three-tier pricing structure across premium adaptive closed-loop platforms, standard programmable generators, and economy fixed-parameter devices stratifies the market. Pricing pressure stems from generic gabapentinoid substitution pulling prescribing toward oral agents in Medicare Advantage plans. Cost-sensitive health systems in Florida and Arizona exhibit highest price sensitivity, while German statutory insurers demonstrate lowest sensitivity due to bundled reimbursement for functional outcomes.
Supply Chain Analysis
Export-control restrictions on advanced battery chemistries and biocompatible electrode alloys limit technology flows from Switzerland and Germany toward non-allied manufacturing jurisdictions. Titanium feedstock concentrates in Swiss precision forges, German specialty metallurgy, and select Japanese suppliers. Lithium-thionyl chloride cell production and platinum-iridium electrode fabrication constitute critical component dependencies. Single-source vulnerability in Swiss titanium enclosure machining creates structural risk. Distribution runs through regional device distributors with hospital system contracting authority in North America, direct manufacturer-to-clinic relationships in Germany, and emerging leasing intermediaries in tier-2 Indian cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
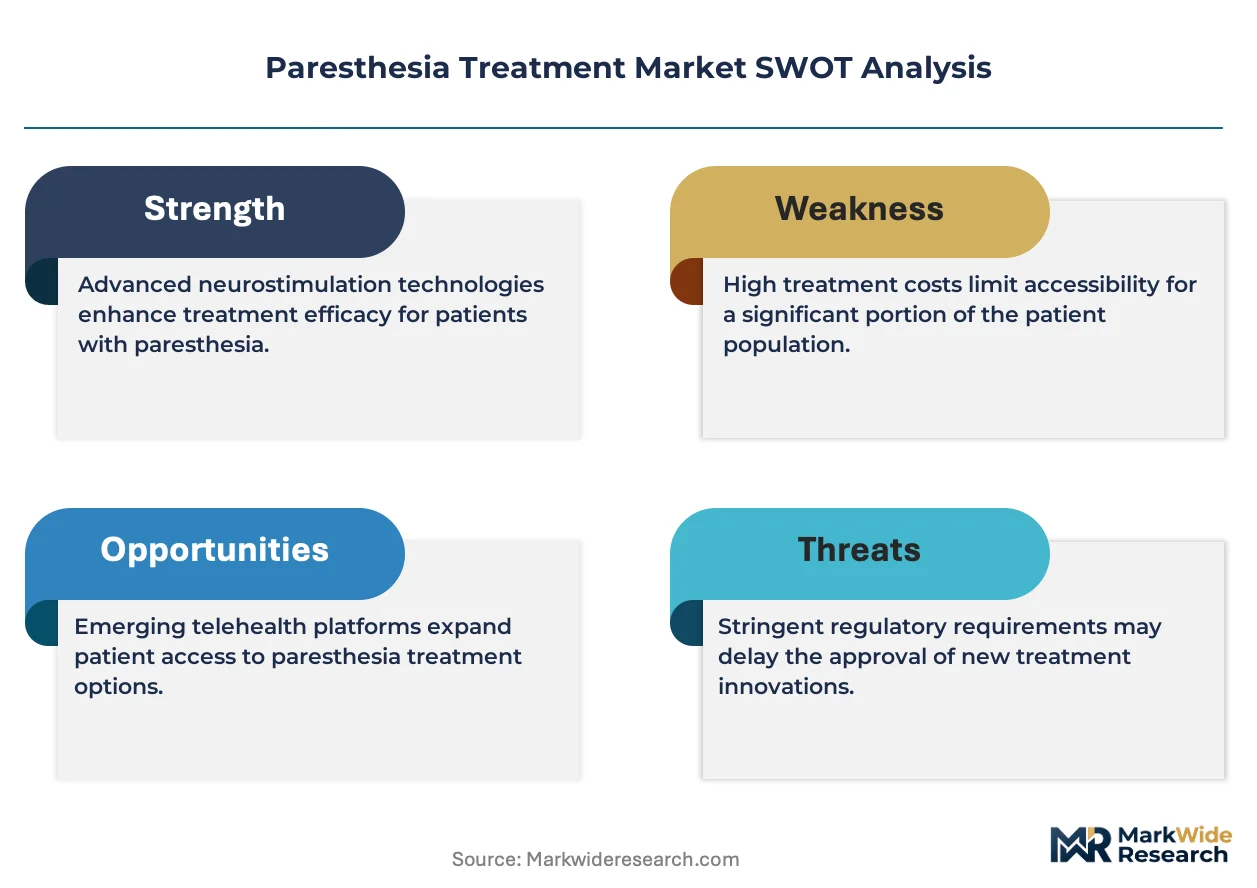
The paresthesia treatment market operates as a defensive-moat industry where regulatory entrenchment through FDA Breakthrough Device pathways and EMA MDR clinical evidence requirements erects structural barriers against undercapitalized entrants.
For Market Incumbents: Build switching-cost moats through proprietary programming software that lacks EMR interoperability, forcing manual data re-entry that raises replacement costs for hospital systems. Deepen backward integration into electrode material supply to secure platinum-iridium alloy sourcing against raw material volatility. Counter the threat from wearable transcutaneous entrants by accelerating closed-loop algorithm deployment that compresses total cost-of-care for payors. For New Entrants and Emerging Players: Build out home-based delivery capabilities in India's tier-2 cities where CDSCO registration streamlining opens white-space for dorsal root ganglion stimulation platforms. Target Japan's aging reimbursement expansion as the most penetrable geography, where METI-PMDA coordination broadens national health insurance coverage for non-pharmacologic interventions. Pursue Bluetooth-enabled wearable stimulator development as the primary go-to-market angle, capturing chronic paresthesia patients earlier in disease progression before surgical candidacy. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors neuromodulation pure-plays with adaptive stimulation algorithms over diversified medtech conglomerates dependent on legacy hardware revenue. Long-term viability over the coming decade rests on software-defined therapy parameters displacing static implantable systems. Acquisition target archetype: specialized closed-loop developers with active implant registries satisfying EMA 10-year surveillance mandates. Watch FDA premarket approval timeline compression as the inflection indicator signaling regulatory pathway maturation for novel entrants.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Accelerated premarket timelines channel venture funding toward paresthesia-specific hardware development. |
| Closed-Loop Algorithm Development | Real-time adaptive programming reduces manual titration visits, improving clinic throughput metrics for payors. |
| Asset-Light Leasing Model Expansion | Subscription-based hardware access transfers obsolescence risk to manufacturers while enabling smaller clinic deployment. |
| Backward Integration into Electrode Supply | In-house production of platinum-iridium alloys secures margins against Swiss and German raw material volatility. |
| Homecare Remote Monitoring Platform Launch | Bluetooth-enabled wearable stimulators capture chronic paresthesia patients earlier in disease progression trajectories. |
Methodological Framework
A spread of perspectives from pain management physicians, hospital purchasing committee members, biomedical engineers specializing in neuromodulation implantation, and GPO contracts managers converged on the working assumptions that shape this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) and PMA filings, EMA centralized marketing authorization databases, ClinicalTrials.gov intervention records, and CMS Medicare reimbursement schedules. Bottom-up patient-volume modeling and top-down market sizing triangulated on segment-level estimates across the analysis window.
Demand-supply balance dynamics anchored the forecast framework, with patient prevalence projections for diabetic peripheral neuropathy and multiple sclerosis-associated paresthesia cross-referenced against electrophysiologist training pipeline constraints and implantable device manufacturing capacity. Segmentation dimensions modeled include treatment modality, indication severity, end-user facility type, and delivery mode. CAGRs derived from logistic growth curve fitting to historical procedure volumes and pharmacologic consumption patterns. Industry-specific inputs incorporated statutory health insurance reimbursement expansion trajectories in Germany and METI-PMDA coordination timelines in Japan.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified medtech conglomerates acquiring closed-loop algorithm developers would shift outcomes beyond modeled ranges. Material shifts in FDA Breakthrough Device designation criteria or EMA MDR post-market surveillance enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Tauopathies Treatment Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Allergic Rhinitis Treatment Market
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Beta Thalassemia Treatment Market
Medical Treatment
Hyperammonemia Treatment Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Peripheral Nerve Injuries Market