
 Postoperative Nausea and Vomiting (PONV) Management Market | 2026-2036
Postoperative Nausea and Vomiting (PONV) Management Market Size, Share, and Industry Trends Forecast 2026-2036
Postoperative Nausea and Vomiting (PONV) Management Market Analytics
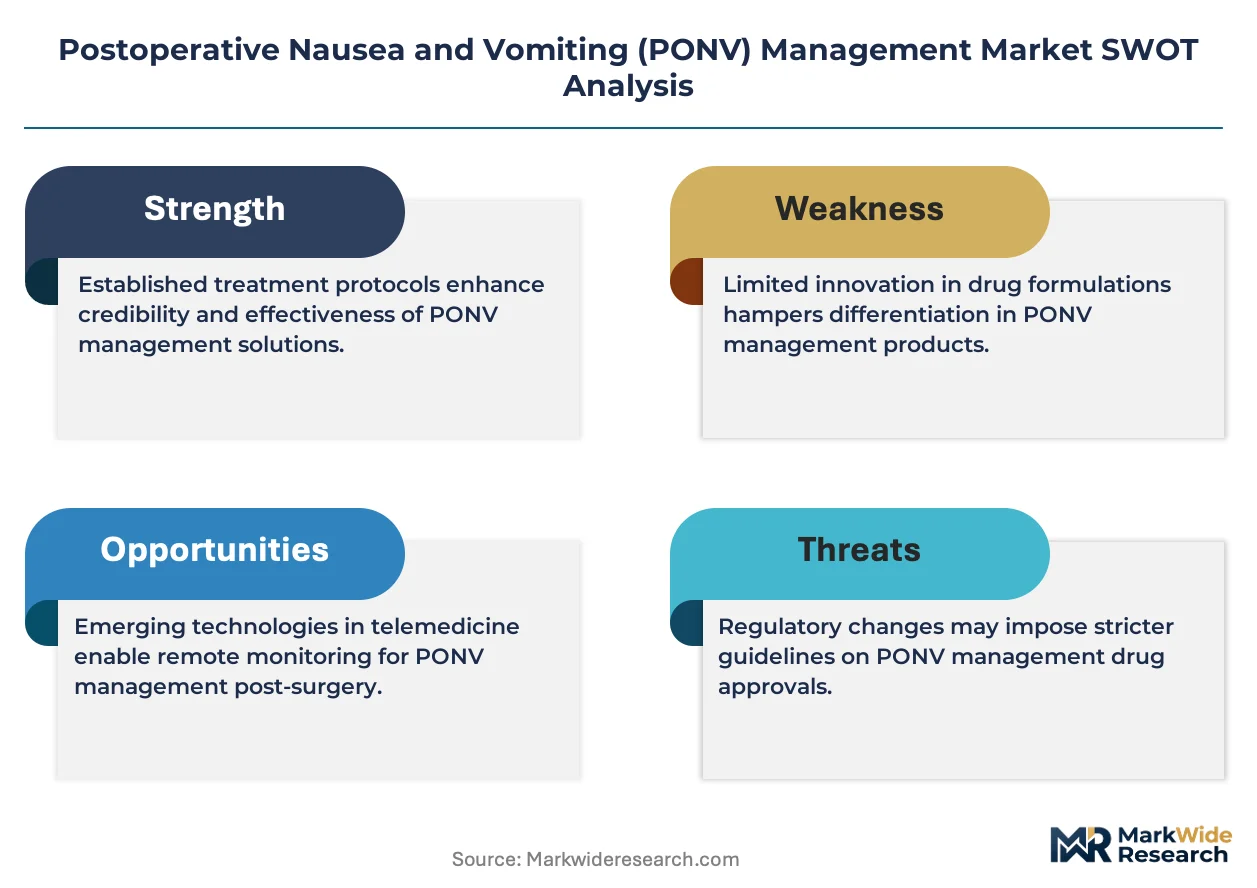
Anesthesiologist workforce shortages in perioperative settings is reorganizing how hospitals deploy PONV management resources, pushing automated risk scoring and pharmacy-driven protocols to the forefront. Merck and Co. leverages its established 5-HT3 receptor antagonist portfolio to sustain hospital formulary dominance across North American academic medical centers. Helsinn Holding S.A. anchors its position through specialized NK1 receptor antagonist formulations designed for high-risk surgical populations. Acacia Pharma competes by differentiating its intravenous amisulpride delivery for rescue therapy in failed prophylaxis cases.
Postoperative nausea and vomiting management encompasses pharmacological interventions targeting the chemoreceptor trigger zone, vestibular nuclei, and gastrointestinal tract through serotonergic, dopaminergic, neurokinin, and corticosteroid pathways, with intravenous ondansetron maintaining bioavailability above sixty percent within thirty minutes of administration. The primary purpose centers on reducing aspiration risk, preventing wound dehiscence, shortening post-anesthesia care unit stays, and improving patient-reported satisfaction scores in surgical recovery. Among delivery modes, intravenous administration occupies the largest share due to immediate onset in ambulatory surgical centers where rapid turnover pressures dominate operational metrics. Transdermal scopolamine patches represent the fastest-expanding segment for gynecological and orthopedic procedures where PONV incidence exceeds forty percent in female patients. The 5-HT3 receptor antagonist class retains mature volume leadership though margin compression from generic ondansetron is redirecting R&D investment toward NK1 combination therapies.
FDA guidance on perioperative antiemetic combinations shapes clinical trial endpoints and label expansion pathways for combination therapies seeking prophylaxis indications. EMA's MDR framework and pharmacovigilance requirements for implantable and drug-device combinations influence European market access timelines for novel transdermal delivery systems. The Joint Commission's surgical care improvement project standards in the United States tie reimbursement to documented PONV risk assessment, directly linking regulatory compliance to product utilization rates. Stakeholders must monitor how anesthesia society guideline revisions incorporate genetic polymorphism testing for CYP2D6 metabolizer status, as this could fragment first-line therapy selection and reshape competitive positioning across receptor antagonist classes.
Market Dynamics
Anesthesiologist workforce shortages are forcing hospitals to restructure perioperative resource deployment, accelerating automated risk scoring systems and pharmacy-driven protocols that reduce physician-dependent decision points.
Growth Catalysts
- The Joint Commission's surgical care improvement project standards:These reimbursement-linked documentation requirements for PONV risk assessment directly elevate product utilization rates across US hospital systems.
- Ambulatory surgical centers:Same-day procedure volume expansion drives prophylaxis adoption as rapid turnover pressures dominate operational metrics.
- Genetic polymorphism testing for CYP2D6 metabolizer status:Anesthesia society guideline revisions incorporating this pharmacogenomic data are fragmenting first-line therapy selection and expanding addressable patient populations.
Market Restraints
- Generic ondansetron margin compression:Patent expiration has collapsed pricing power across the 5-HT3 receptor antagonist class, redirecting R&D budgets toward combination therapies.
- EMA MDR framework pharmacovigilance requirements:Enhanced scrutiny for drug-device combinations extends European market access timelines for novel transdermal delivery systems.
- Intravenous formulation dominance:Established clinical familiarity with IV administration creates switching friction against emerging transdermal and oral disintegrating tablet formats.
Strategic Opportunities
- Gynecological and orthopedic procedures:Transdermal scopolamine patches address PONV incidence exceeding forty percent in female patients, an underpenetrated application segment.
- FDA perioperative antiemetic combination guidance:Enhanced regulatory clarity on clinical trial endpoints accelerates label expansion pathways for NK1 receptor antagonist combinations.
- Integrated anesthesia care pathways:Protocol standardization in academic medical centers creates formulary consolidation opportunities for vendors with comprehensive receptor-target portfolios.
Industry Challenges
- Anesthesiologist workforce scarcity:Perioperative staffing gaps force reliance on automated systems that may misstratify high-risk patients without clinical oversight.
- Combination therapy validation complexity:Demonstrating non-inferiority against established single-agent prophylaxis requires larger trial populations and extended follow-up periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postoperative Nausea and Vomiting (PONV) Management Market |
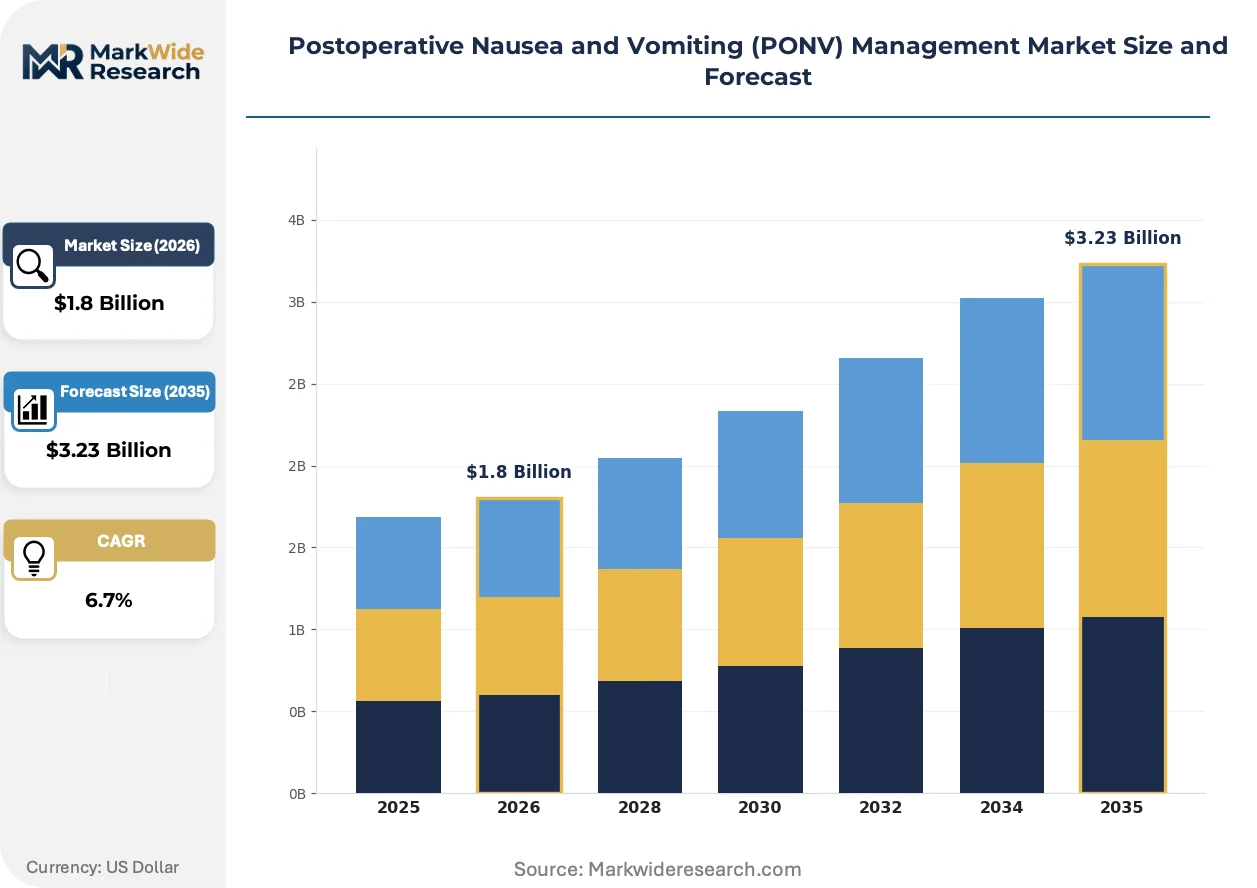
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiemetics, Corticosteroids, 5-HT3 Receptor Antagonists, NK1 Receptor Antagonists Delivery Mode: Oral, Intravenous, Transdermal, Rectal End User: Hospitals, Ambulatory Surgical Centers, Outpatient Clinics, Home Care Therapy Area: General Surgery, Gynecological Surgery, Orthopedic Surgery, Urological Surgery |
| Companies Covered | Helsinn Holding S.A., Merck and Co., Acacia Pharma, Ani Pharmaceuticals, GlaxoSmithKline, Novartis AG, Eisai Corporation, Camurus AB, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postoperative Nausea and Vomiting (PONV) Management Market Evolving Landscape
Digital health integration and pharmacogenomic stratification are reconfiguring how PONV risk is assessed and managed, shifting from reactive rescue therapy toward predictive, patient-specific prophylaxis protocols.
Wearable biosensor technology for real-time nausea biomarker detection is miniaturizing. Ambulatory surgical centers in the United States are piloting these devices for immediate post-discharge monitoring. This capability is compressing the window between symptom onset and rescue intervention, reducing emergency department bounce-backs.
REACH compliance requirements for chemical substance safety in transdermal patch adhesives are tightening formulation standards across European manufacturing. Patch suppliers are reformulating acrylate-based matrices to eliminate CMR-classified compounds. German and French contract manufacturers are absorbing certification costs to maintain EMA market access.
Hospital purchasing cooperatives are consolidating antiemetic procurement under single-source contracts with performance guarantees. Integrated delivery networks in the United States are replacing fragmented pharmacy buying with system-wide formularies tied to outcomes metrics. This concentration is visible most acutely in the southeastern states where hospital consolidation has accelerated.
Postoperative Nausea and Vomiting (PONV) Management Market Segmentation
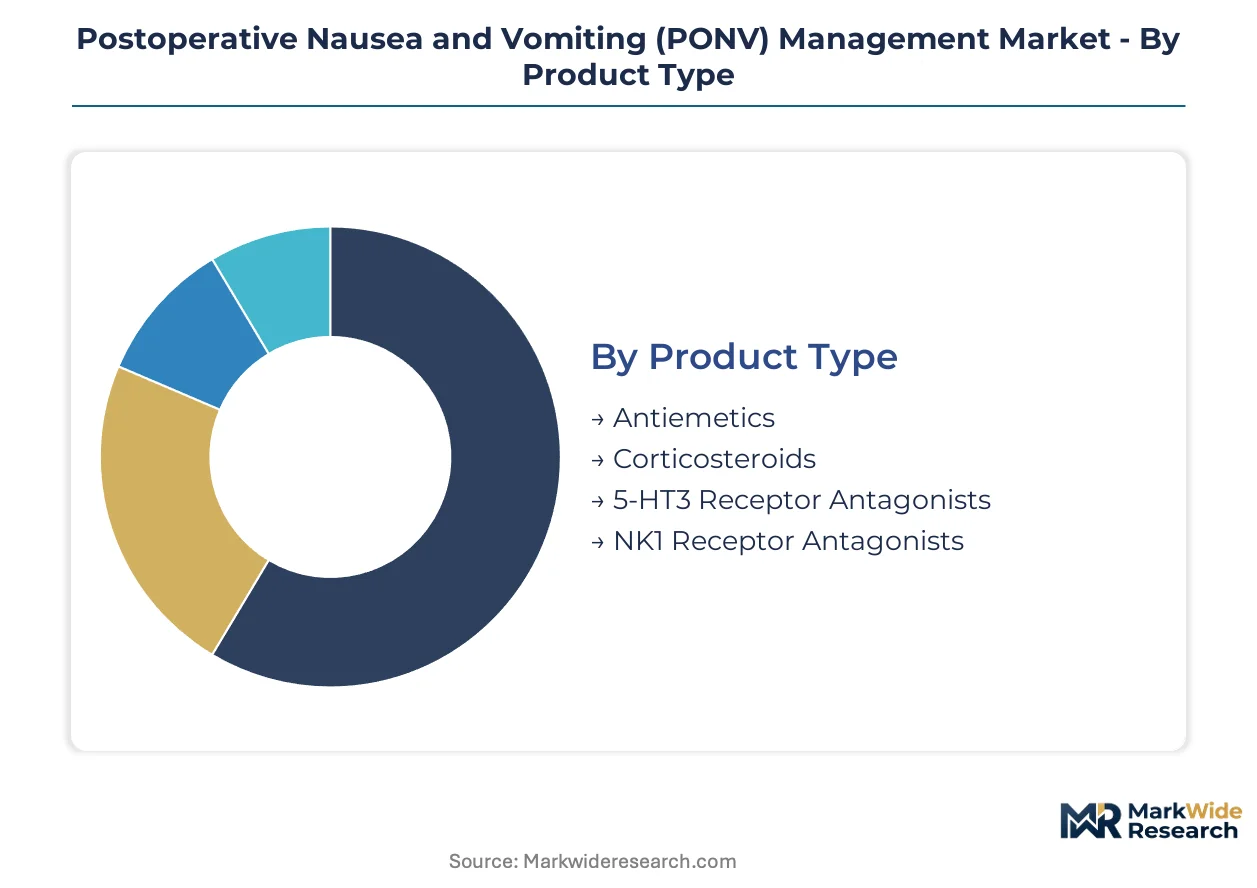
PONV management segmentation reveals how pharmacological innovation, delivery technology, and care setting economics intersect. Distinct patient risk profiles and procedural volumes across surgical specialties create heterogeneous demand patterns that reward targeted portfolio positioning.
Product Type:
Geographic concentration varies sharply across receptor-targeting classes, with 5-HT3 antagonists dominating hospital formularies in the United States while NK1 combinations gain traction in European prophylaxis protocols.
- 5-HT3 Receptor Antagonists:Serotonergic pathway blockers such as ondansetron and palonosetron achieve rapid chemoreceptor trigger zone suppression with intravenous bioavailability exceeding sixty percent within thirty minutes. United States academic medical centers anchor demand through integrated anesthesia care pathways that standardize first-line prophylaxis. Generic ondansetron entry has collapsed pricing power and redirected manufacturer R&D investment toward combination therapies.
- NK1 Receptor Antagonists:Neurokinin-1 pathway inhibitors including aprepitant and fosaprepitant target substance-P mediated delayed-phase emesis through blood-brain barrier penetration. European surgical centers in Germany and France drive adoption as EMA guidance on perioperative combination regimens clarifies reimbursement pathways. High acquisition costs relative to 5-HT3 agents constrain penetration in cost-sensitive health systems.
- Antiemetics:Broad-spectrum agents such as metoclopramide and droperidol provide dopaminergic and mixed-receptor antagonism for rescue therapy scenarios.
- Corticosteroids:Dexamethasone formulations deliver cost-effective prophylaxis through anti-inflammatory and central antiemetic mechanisms, particularly valued in resource-limited settings.
5-HT3 Receptor Antagonists command the established base. The steepest expansion runs through NK1 Receptor Antagonists.
Delivery Mode:
Route selection reflects operational pressures in ambulatory versus inpatient settings, with immediate-release intravenous formats capturing high-turnover surgical volume and transdermal systems addressing adherence in extended recovery.
- Intravenous:Direct vascular administration ensures predictable pharmacokinetics and rapid onset for intraoperative and post-anesthesia care unit dosing. Ambulatory surgical centers in the United States specify IV formats for ninety percent of PONV prophylaxis to support same-day discharge protocols. Manufacturing concentration among sterile injectable specialists in India and Ireland shapes supply security considerations.
- Transdermal:Scopolamine patches provide continuous anticholinergic delivery over seventy-two hours through rate-controlled membrane diffusion. Gynecological and orthopedic procedures in female patients with elevated PONV risk drive United States demand, particularly in southeastern hospital systems with consolidated purchasing cooperatives. REACH compliance requirements for acrylate adhesive reformulation are elevating European manufacturing costs.
- Oral:Tablet and disintegrating formulations serve preoperative dosing and outpatient rescue therapy with lower unit economics than parenteral alternatives.
- Rectal:Suppository delivery addresses postoperative patients with compromised gastrointestinal motility or vomiting that precludes oral administration.
Intravenous administration retains volume leadership across hospital and ambulatory settings. Transdermal delivery is climbing the fastest as patch technology advances and female-specific risk stratification improves.
End User:
Care setting economics determine protocol sophistication, with academic medical centers deploying multimodal prophylaxis while ambulatory centers prioritize rapid-turnover single-agent strategies.
- Hospitals:Inpatient surgical units with extended recovery capacity implement risk-stratified combination protocols incorporating 5-HT3, NK1, and corticosteroid agents. The Joint Commission's surgical care improvement project standards in the United States mandate documented PONV risk assessment, directly linking compliance to product utilization. Anesthesiologist workforce shortages are accelerating automated risk scoring deployment.
- Ambulatory Surgical Centers:Same-day procedure facilities prioritize rapid-onset intravenous prophylaxis to minimize post-anesthesia care unit length of stay and prevent admission conversion. United States volume expansion in outpatient joint replacement and hysterectomy procedures is elevating addressable procedure counts. Pharmacy-driven protocols reduce physician-dependent decision points.
- Outpatient Clinics:Preoperative assessment sites initiate prophylaxis for high-risk patients prior to surgical scheduling.
- Home Care:Post-discharge rescue therapy management is emerging with wearable biosensor pilot programs for symptom monitoring.
Hospitals maintain the deepest protocol penetration. Ambulatory Surgical Centers are gaining share fastest as procedure migration accelerates.
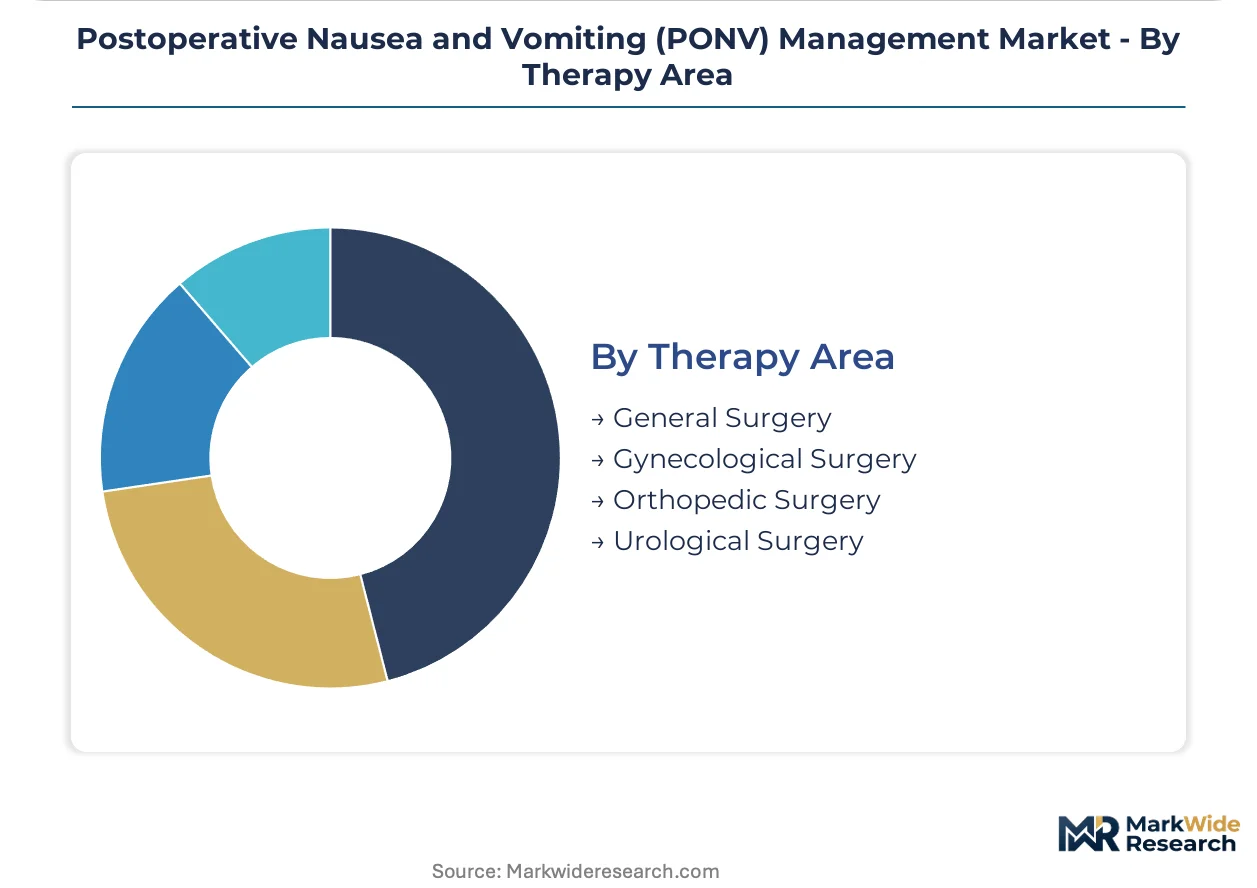
Therapy Area:
Surgical specialty risk profiles create divergent prophylaxis intensity, with female-predominant procedures and opioid-intensive recoveries demanding higher therapeutic investment.
- Gynecological Surgery:Hysterectomy, laparoscopic sterilization, and fertility procedures exhibit PONV incidence exceeding forty percent in female patients due to estrogen interaction with vestibular nuclei and chemoreceptor trigger zone sensitivity. United States ambulatory surgical centers specify transdermal scopolamine patches as standard prophylaxis for this population. Opioid-sparing anesthesia techniques are partially offsetting antiemetic demand.
- Orthopedic Surgery:Joint replacement and arthroscopic procedures combine general anesthesia exposure, opioid analgesia, and female demographic concentration to elevate emetic risk. German and French hospital systems are piloting pharmacogenomic stratification for CYP2D6 metabolizer status to guide 5-HT3 antagonist selection. Enhanced recovery after surgery protocols are compressing length of stay and intensifying prophylaxis efficacy requirements.
- General Surgery:Abdominal and laparoscopic procedures across diverse patient populations utilize standardized multimodal protocols.
- Urological Surgery:Prostate and renal procedures in male-predominant populations exhibit lower baseline PONV incidence, reducing per-procedure antiemetic intensity.
General Surgery commands procedure volume leadership. Gynecological Surgery is expanding most quickly as outpatient migration and female-specific risk recognition advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets, with the United States driving protocol standardization through integrated care pathways while European systems emphasize pharmacogenomic stratification and Japan pursues miniaturized delivery innovation.
United States
The Joint Commission's surgical care improvement project standards mandate documented PONV risk assessment, directly tying reimbursement to product utilization across hospital systems. FDA guidance on perioperative antiemetic combinations accelerates label expansion for NK1 receptor antagonist therapies. The southeastern states concentrate purchasing power through hospital cooperatives consolidating antiemetic procurement under single-source contracts.
Germany
EMA's MDR framework and pharmacovigilance requirements for drug-device combinations extend market access timelines for novel transdermal delivery systems. German hospital systems pilot CYP2D6 metabolizer testing to guide 5-HT3 antagonist selection in orthopedic procedures. The Baden-Württemberg region anchors manufacturing concentration for sterile injectable specialists serving European distribution.
France
ANSM oversight of perioperative drug combinations shapes clinical trial design for rescue therapy indications. French surgical centers drive adoption of NK1 receptor antagonists as EMA guidance clarifies reimbursement pathways for combination regimens. The Île-de-France region clusters academic medical centers deploying multimodal prophylaxis protocols with automated risk scoring systems.
Japan
PMDA review standards for novel antiemetic formulations emphasize bioequivalence data for intravenous and transdermal delivery modes. Japanese manufacturers pioneer wearable biosensor technology for real-time nausea biomarker detection in ambulatory settings. The Kanto region surrounding Tokyo concentrates pharmaceutical R&D investment toward miniaturized patch delivery systems.
United Kingdom
NICE technology appraisals influence formulary placement for high-cost NK1 receptor antagonists against generic 5-HT3 alternatives. UK anesthesia societies incorporate genetic polymorphism guidance into perioperative protocols, fragmenting first-line therapy selection. The Greater London area dominates procurement consolidation as integrated care systems replace fragmented pharmacy buying.
Postoperative Nausea and Vomiting (PONV) Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational pharmaceutical corporations commanding hospital formulary access through comprehensive receptor-target portfolios while mid-cap developers concentrate on rescue therapy differentiation and novel delivery formats. Competitive dynamics center on M&A activity consolidating 5-HT3 and NK1 assets under single ownership, alongside strategic partnerships pairing established antiemetic compounds with digital health platforms for automated risk stratification.
Within the integrated pharmaceutical tier, Merck and Co. and Novartis AG occupy positions anchored by established hospital relationships across North American and European academic medical centers. Helsinn Holding S.A. exemplifies the specialized developer archetype, concentrating resources on NK1 receptor antagonist formulations for high-risk surgical populations. Acacia Pharma represents the rescue therapy specialist segment, differentiating through intravenous amisulpride delivery for failed prophylaxis scenarios.
| Leading Market Players |
|---|
| Helsinn Holding S.A. |
| Merck and Co. |
| Acacia Pharma |
| Ani Pharmaceuticals |
| GlaxoSmithKline |
| Novartis AG |
| Eisai Corporation |
| Camurus AB |
| Roche |
| Others |
Value Network & Pricing Analysis
Generic ondansetron substitution for branded 5-HT3 receptor antagonists has collapsed pricing power across mature hospital formularies while simultaneously shifting active pharmaceutical ingredient sourcing from Western European manufacturers toward Indian and Chinese suppliers, compressing margins throughout the value chain.
Pricing Analysis
Long-term offtake agreements between hospital purchasing cooperatives and sterile injectable manufacturers anchor pricing stability for intravenous antiemetics, while spot procurement for rescue therapy agents fluctuates with API availability. Three-tier pricing structure across premium NK1 combinations, standard 5-HT3 generics, and economy corticosteroid prophylaxis reflects reimbursement tiering and clinical indication breadth. Pricing pressure stems from patent cliff erosion in the 5-HT3 class and consolidated buyer power in southeastern United States hospital systems. Ambulatory surgical centers exhibit highest price sensitivity due to per-procedure cost accounting, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
India and Ireland anchor sterile injectable manufacturing for intravenous antiemetics serving North American and European distribution, while China and Germany concentrate active pharmaceutical ingredient synthesis for scopolamine and corticosteroid precursors. Supply security draws from acrylate adhesive feedstocks for transdermal patches, glass vial supply for parenteral formulations, and cold-chain logistics capacity for temperature-sensitive biologics. Single-source vulnerability in scopolamine API production creates exposure to botanical harvest variability and extraction capacity constraints. Distribution runs through hospital GPO contracts, specialty pharmaceutical distributors, and direct-to-ambulatory-center channels with varying service-level requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from digital health platforms deploying predictive PONV risk algorithms that reduce pharmacological prophylaxis intensity, requiring portfolio repositioning toward integrated drug-device combinations.
For Market Incumbents: Shield market position by deepening backward integration into NK1 receptor antagonist API production to offset margin compression from generic 5-HT3 erosion. Prioritize FDA combination therapy label expansions that create switching friction against single-agent alternatives. Secure exclusive formulary placement through outcomes-based contracting with southeastern United States purchasing cooperatives. For New Entrants and Emerging Players: Pharmacogenomic testing service gaps in perioperative anesthesia protocols present white-space entry points where incumbents under-serve CYP2D6 metabolizer stratification. Target ambulatory surgical centers in high-turnover gynecological procedures with transdermal patch formulations differentiated by extended-release kinetics. Pursue partnership pathways with digital health platforms for automated risk scoring integration rather than direct pharmaceutical sales force buildout. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap developers with rescue therapy assets in Phase III development and established European reimbursement pathways. Long-term viability hinges on combination therapy validation against single-agent standards of care. Monitor anesthesia society guideline revision timelines as inflection indicators for pharmacogenomic stratification adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Combination therapy non-inferiority studies against ondansetron monotherapy accelerate FDA label expansion pathways. |
| Regulatory Approval Pathway | EMA MDR compliance for transdermal drug-device combinations determines European market access timelines. |
| Manufacturing Scale-Up | Sterile injectable capacity expansion in Ireland and India secures supply continuity for ambulatory surgical center demand. |
| Strategic Partnership | Digital health platform alliances embed automated PONV risk scoring into anesthesia information management systems. |
| Reimbursement Strategy | The Joint Commission surgical care improvement project alignment ties product utilization to hospital reimbursement compliance. |
Research Methodology
Initial hypotheses were tested against primary input from anesthesia department chairs, hospital formulary directors, GPO contract managers, and ambulatory surgical center administrators and refined through secondary validation across FDA 510(k) filings, EMA centralized procedure assessments, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up demand modeling triangulated against top-down epidemiological procedure volume projections.
Variance-decomposition across the projection horizon isolates volume drivers (ambulatory surgery migration rates, female procedure demographics) from price drivers (generic entry timing, purchasing cooperative consolidation). Segmentation dimensions span receptor-target class, delivery mode, care setting, and surgical specialty risk profile. CAGRs derive from procedure volume elasticity to antiemetic intensity and reimbursement policy scenario analysis.
Forecasts assume regulatory continuity in FDA perioperative guidance and EMA MDR enforcement; material policy shifts in pharmacogenomic testing mandates or transdermal patch safety standards would require re-modeling. Recalibration cycles align with material shifts in anesthesia society guideline revisions and hospital consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Scabies Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Scoliosis Management Market
Medical Treatment
Giardiasis Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Ventral Hernia Treatment Market