
 Surgical Procedures Volume Market | 2026-2036
Surgical Procedures Volume Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Procedures Volume Market Outlook
Procedure bundling into episode-based payment models is expanding buyer choice across orthopedic and cardiac service lines. Medtronic leverages its integrated spine and navigation platforms to capture bundled contracts with large hospital systems. Johnson & Johnson anchors its position through broad DePuy Synthes portfolios that span implants, instruments, and digital planning tools. Intuitive Surgical dominates robotic-assisted procedural volumes with installed base expansion and surgeon training ecosystems that lock in recurring system utilization.
Surgical procedures volume encompasses the aggregate count and value of operative interventions performed across institutional and ambulatory settings, measured by procedure codes, site of service, and reimbursement classification. The metric functions as a demand indicator for medical devices, consumables, staffing, and facility capacity planning across healthcare systems. Orthopedic surgery and cardiothoracic surgery represent the largest procedure value pools, with orthopedic volumes sustained by joint replacement demand and cardiac volumes concentrated in coronary revascularization. Minimally invasive technology generates premium pricing per procedure while robotic-assisted platforms command capital-intensive site commitments that reshape competitive dynamics.
FDA 510(k) clearance pathways and CMS outpatient prospective payment system updates directly determine site-of-service economics and technology adoption timelines for device manufacturers and surgical facilities. EMA medical device regulation and national health technology assessment bodies in Germany, France, and England gate market access for novel surgical technologies across European systems. Stakeholders must monitor reimbursement parity between inpatient and outpatient settings, as payer policy shifts will determine where procedural volume growth materializes and which technology configurations capture margin.
Market Dynamics
Episode-based payment models are consolidating purchasing authority across orthopedic and cardiac service lines, forcing device manufacturers to bundle implants with navigation systems and post-acute monitoring services to win system-wide contracts.
Growth Catalysts
- CMS outpatient payment parity:Medicare reimbursement codes now match inpatient rates for select spine and joint procedures, accelerating site-of-service migration to ambulatory surgical centers.
- Aging joint replacement demand:Demographic pressure from Medicare-eligible populations in the United States sustains procedural volume expansion for knee and hip arthroplasty.
- Robotic platform training ecosystems:Proprietary surgeon certification programs lock in recurring system utilization and consumable attachment revenue streams.
Market Restraints
- Capital intensity of robotic systems:Da Vinci and competing platforms require $1.5–2.5 million upfront commitments plus annual service contracts, limiting adoption to well-capitalized health systems.
- Implant price compression:Hospital procurement consortiums and group purchasing organizations extract standardized pricing across commoditized orthopedic hardware categories.
- Surgeon training bottlenecks:Procedural volume requirements for robotic credentialing create capacity constraints that slow technology diffusion.
Strategic Opportunities
- Same-day discharge protocols:Enhanced recovery after surgery pathways enable joint replacement migration to freestanding ambulatory centers, opening new site-of-service revenue pools.
- Digital surgical planning convergence:Preoperative CT-to-implant matching software integrates with navigation platforms to reduce operative time and revision rates.
- Remote patient monitoring integration:Post-discharge wearable analytics reduce readmission penalties and support bundled payment performance guarantees.
Industry Challenges
- Robotic system interoperability gaps:Proprietary instrument interfaces and data formats complicate multi-vendor operating room configurations and legacy equipment integration.
- Surgeon workforce distribution:Rural and exurban facility networks face recruitment shortfalls for fellowship-trained specialists capable of complex minimally invasive techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Procedures Volume Market |
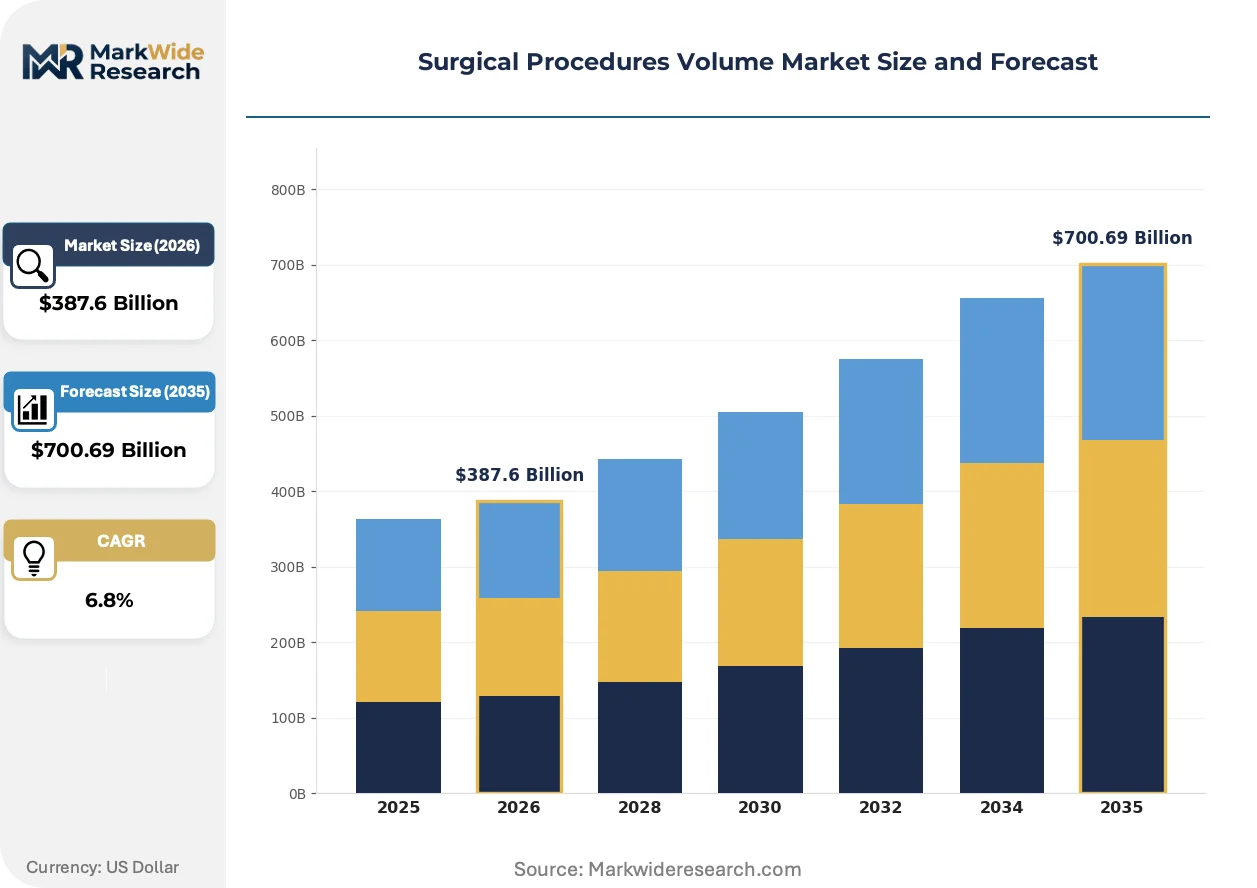
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Orthopedic Surgery, Cardiothoracic Surgery, Neuro Surgery, General Surgery Technology: Minimally Invasive, Robotic-Assisted, Traditional Open Surgery, Laparoscopic End User: Public Hospitals, Private Clinics, Surgical Centers, Specialty Hospitals Delivery Mode: Inpatient, Outpatient, Emergency, Elective |
| Companies Covered | Medtronic, Intuitive Surgical, Stryker Corporation, Johnson & Johnson, Zimmer Biomet, Allergan PLC, Cutera Inc., Lumenis Ltd., AMSURG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Procedures Volume Market Strategic Shifts
Digital workflow integration and site-of-service economics are compressing traditional boundaries between preoperative planning, intraoperative execution, and postoperative surveillance across surgical delivery systems.
Fluorescence-guided perfusion assessment is electrifying tissue viability verification in colorectal and gastric procedures. Academic medical centers in Germany and Japan are standardizing near-infrared angiography for anastomotic leak prevention. This technology is electrifying the shift toward definitive same-day discharge protocols by reducing return-to-OR rates.
EMA Medical Device Regulation transition deadlines are forcing manufacturers to consolidate technical documentation and clinical evidence packages. Small-to-midscale implant suppliers face Notified Body capacity constraints that delay CE mark renewals. European orthopedic distributors are pruning supplier portfolios to concentrate on MDR-compliant device families with established quality management systems.
Health system procurement consolidation is concentrating implant purchasing decisions within centralized value analysis committees. Independent ambulatory surgery centers are ceding vendor selection authority to management company networks that negotiate system-wide pricing tiers. This concentration is most visible in Florida and Texas markets where private equity-backed facility rollups dominate outpatient surgical capacity.
Surgical Procedures Volume Market Segmentation
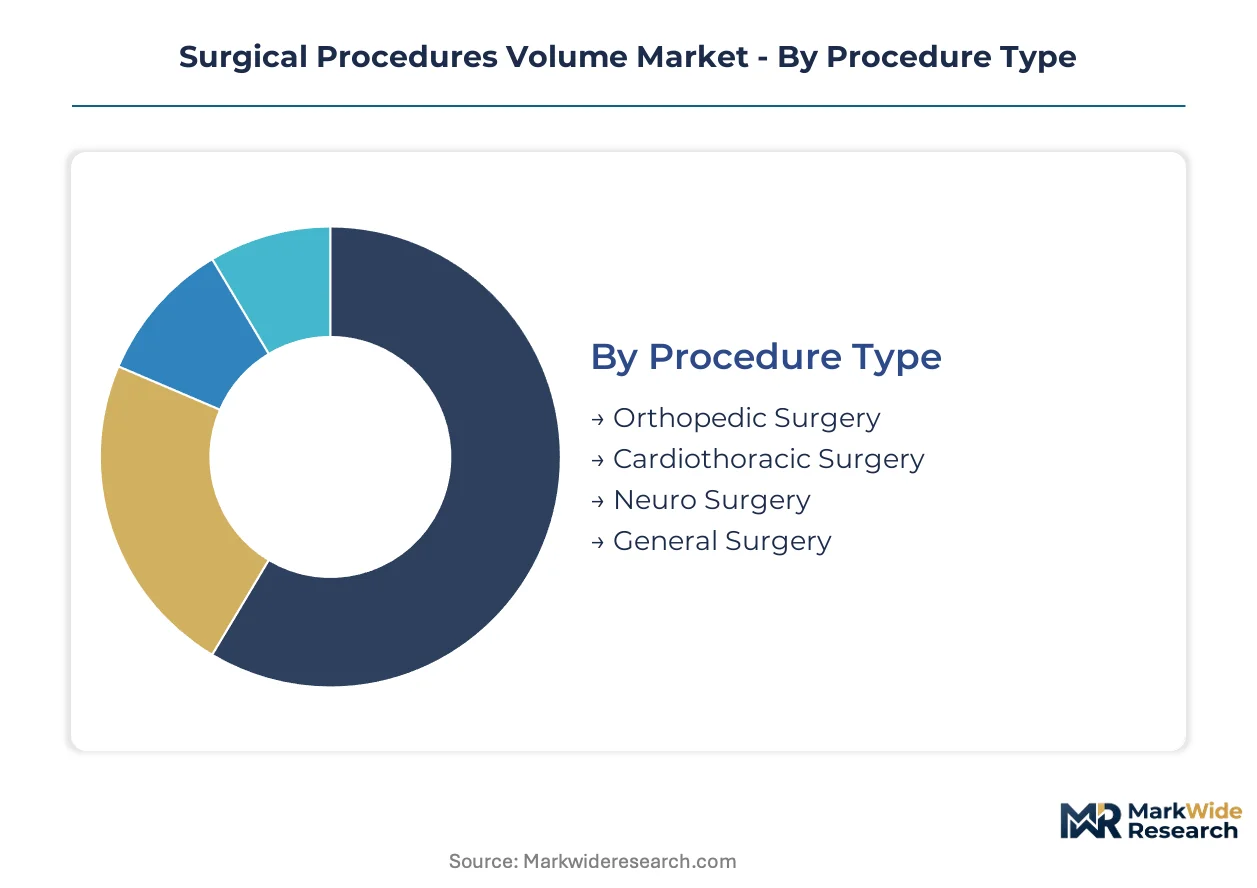
Surgical procedure volumes fragment across multiple axes that determine reimbursement rates, capital requirements, and technology adoption curves. Understanding these divides reveals where margin pools concentrate and which configurations command premium pricing.
Procedure Type:
Standardization varies sharply across this category, from protocol-driven joint replacements to highly customized cranial interventions.
- Orthopedic Surgery:Joint arthroplasty and spine fusion procedures follow reproducible pathways that enable same-day discharge protocols. Demand clusters in Florida and Texas where Medicare Advantage penetration supports bundled payment contracts for knee and hip volumes.
- Cardiothoracic Surgery:Coronary revascularization and valve repair demand specialized perfusion teams and hybrid operating suites. Academic medical centers in Germany and Japan anchor training pipelines for minimally invasive cardiac techniques that reduce ICU utilization.
- Neuro Surgery:Cranial and spinal interventions require navigation integration and intraoperative imaging. Volumes concentrate at tertiary referral centers with 24/7 neurocritical care coverage.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair constitute high-frequency, lower-acuity procedures migrating rapidly to ambulatory settings.
Leading the category by volume: Orthopedic Surgery. Expanding most quickly: Cardiothoracic Surgery as transcatheter techniques broaden patient eligibility.
Technology:
Cost tiers separate capital-intensive platforms from instrument-based approaches across this dimension.
- Minimally Invasive:Laparoscopic and thoracoscopic techniques reduce tissue trauma and length of stay. Community hospitals in the United States prioritize this tier for gallbladder and colorectal volumes to meet CMS quality metrics.
- Robotic-Assisted:Multi-arm platforms with 3D visualization enable suturing precision in confined anatomical spaces. Health systems in California and New York amortize system costs across high-volume prostate and gynecologic service lines.
- Traditional Open Surgery:Remains necessary for trauma, revision cases, and oncologic resections requiring direct manual palpation. Rural facilities maintain open capabilities where robotic infrastructure is uneconomical.
- Laparoscopic:Single-incision and reduced-port configurations compete with robotic systems for cholecystectomy and bariatric volumes. European centers leverage reusable instrument sets to control per-procedure costs.
Highest volume share: Laparoscopic. Steepest expansion trajectory: Robotic-Assisted as FDA 510(k) clearances proliferate for general surgery applications.
End User:
Customer type determines procurement authority and technology refresh cycles across this category.
- Public Hospitals:Government-funded institutions in England and France operate under fixed global budgets that constrain capital expenditure for robotic platforms. Volumes concentrate in emergency and trauma service lines with limited elective scheduling flexibility.
- Private Clinics:Physician-owned facilities in the United States optimize throughput through dedicated block scheduling and direct-to-employer contracting. Orthopedic and ophthalmic volumes dominate revenue mix.
- Surgical Centers:Medicare-certified ambulatory facilities in Texas and Florida exploit site-of-service differentials for joint replacement and spine procedures. Private equity consolidation creates multi-facility purchasing leverage.
- Specialty Hospitals:Cardiac and orthopedic-focused institutions in Germany and Switzerland command premium reimbursement for complex cases requiring extended monitoring.
Fastest volume growth: Surgical Centers. Largest procedure base: Public Hospitals serving universal coverage populations.
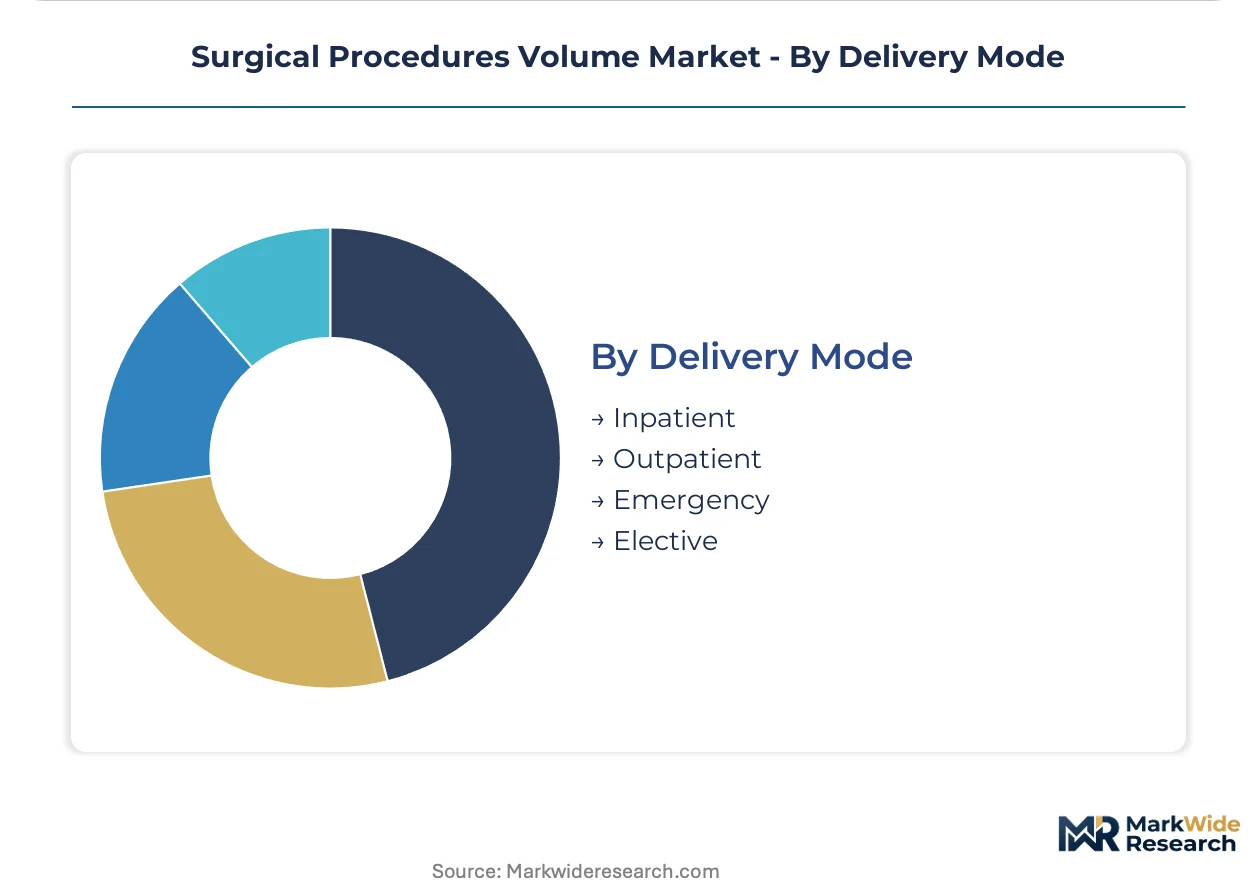
Delivery Mode:
Maturity gradients separate established reimbursement pathways from emerging site-of-service migrations.
- Inpatient:Traditional hospital admission with overnight stay remains required for complex cardiac, neurosurgical, and oncologic procedures. CMS diagnosis-related group payments set baseline economics for this mode.
- Outpatient:Same-day discharge protocols now encompass joint replacement and spine fusion at ambulatory surgical centers. Medicare payment parity rulings accelerated migration from hospital-based settings.
- Emergency:Trauma, acute abdomen, and vascular compromise demand 24/7 operating room availability. Level I trauma centers in the United States anchor regional referral networks for these volumes.
- Elective:Scheduled procedures with preoperative optimization enable predictable throughput and supply chain planning. Bariatric and cosmetic volumes concentrate in private clinic and surgical center settings.
Dominant volume share: Inpatient. Gaining share fastest: Outpatient as enhanced recovery protocols expand same-day eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Puerto Rico concentrate contract manufacturing for surgical instruments, drawing investment through tariff exemptions and streamlined FDA inspection protocols.
United States
Medicare Advantage penetration in Florida and Texas drives bundled payment contracts for joint replacement volumes. CMS outpatient prospective payment system updates now match inpatient rates for select spine procedures, accelerating ambulatory surgical center migration. The Dallas-Fort Worth metroplex anchors private equity-backed facility rollups that consolidate vendor selection authority across multi-site networks.
Germany
EMA Medical Device Regulation transition deadlines force manufacturers to consolidate technical documentation for CE mark renewals. National health technology assessment bodies gate market access for novel navigation platforms and robotic systems. The Baden-Württemberg cluster around Stuttgart concentrates precision engineering suppliers serving orthopedic and neurosurgical instrument demand.
Japan
PMDA streamlined review pathways for robotic-assisted surgical systems reduce time-to-market for manufacturers with prior FDA clearance. METI funding for surgical AI integration supports digital workflow adoption in academic medical centers. Tokyo and Osaka anchor training pipelines for minimally invasive cardiac techniques that reduce ICU utilization and enable same-day discharge protocols.
United Kingdom
NHS England fixed global budgets constrain capital expenditure for robotic platforms in public hospital networks. NICE technology appraisals determine reimbursement eligibility for novel surgical devices across integrated care systems. The Oxford-Cambridge-London golden triangle concentrates medtech R&D and early-stage clinical validation for fluorescence-guided perfusion systems.
Switzerland
Swissmedic expedited review procedures for breakthrough surgical devices attract manufacturers seeking parallel European and global market entry. Premium reimbursement rates at cardiac and orthopedic-focused specialty hospitals support complex case volumes requiring extended monitoring. The Basel-Zurich corridor hosts headquarters for major implant manufacturers and precision component suppliers serving EU and Middle Eastern markets.
Surgical Procedures Volume Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across capital-intensive robotic platforms and commoditized implant categories. Medtronic and Johnson & Johnson anchor the consolidated tier through integrated spine, navigation, and digital planning portfolios. Strategic archetypes include bundled contract aggregators, surgeon training ecosystem operators, and precision instrument component suppliers. Dominant competitive moves encompass vertical integration into navigation software and geographic expansion through management company network partnerships.
Within the diversified conglomerate tier, Medtronic and Johnson & Johnson occupy positions spanning implants, instruments, and digital infrastructure. Intuitive Surgical exemplifies the pure-play robotic platform archetype through installed base expansion and proprietary certification programs. Stryker Corporation sits within the orthopedic-focused specialist category, representing consolidation-driven portfolio breadth across joint replacement and spine segments.
| Leading Market Players |
|---|
| Medtronic |
| Intuitive Surgical |
| Stryker Corporation |
| Johnson & Johnson |
| Zimmer Biomet |
| Allergan PLC |
| Cutera Inc. |
| Lumenis Ltd. |
| AMSURG |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up ambulatory surgical center networks in Florida and Texas anchor procurement consolidation that compresses implant pricing while concentrating supplier selection authority within centralized value analysis committees.
Pricing Analysis
Margin tightening in commoditized orthopedic hardware reflects group purchasing organization standardization across hospital procurement consortiums. Three-tier pricing structure across premium navigation-integrated, standard instrument-based, and economy generic implant levels separates robotic platform bundles from conventional laparoscopic sets. Cost-down pressure on spinal and joint implants accelerates because Medicare outpatient payment parity eliminates site-of-service reimbursement differentials. Ambulatory surgical centers exhibit highest price sensitivity as they amortize capital equipment across lower procedural volumes than hospital systems.
Supply Chain Analysis
Regional distribution centers in Memphis and Louisville feed hub-and-spoke replenishment patterns to surgical facilities across the United States. Manufacturing concentration in Costa Rica, Puerto Rico, and Baden-Württemberg supplies precision-machined instruments and navigation components. Supply chains draw from titanium alloy feedstock, sterile barrier packaging, and optical sensor arrays. Single-source vulnerability around robotic arm servo motors creates procurement risk. Distribution runs through manufacturer-direct field inventory specialists co-located at major hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over navigation software and post-acute monitoring data determines bundled contract capture.
For Market Incumbents: Anticipate ambulatory surgical center procurement consolidation by embedding disposable instrument subscriptions within multi-year system leases. Lock in surgeon training pipelines through proprietary certification ecosystems that raise switching costs. Counter emerging pure-play robotic entrants by bundling navigation software with implant hardware in episode-based payment contracts.
For New Entrants and Emerging Players: Launch via management company network partnerships that aggregate purchasing across private-equity-backed facility rollups in Texas and Florida. Target underpenetrated rural surgical centers lacking robotic infrastructure with laparoscopic instrument sets featuring digital workflow integration. Capture volume through direct-to-employer contracting that bypasses hospital procurement committees.
For Investors and Strategic Acquirers: Distressed-cycle entries favor MDR-compliant European implant suppliers facing Notified Body capacity constraints in Germany and France. Long-term viability hinges on software-enabled recurring revenue streams rather than transactional implant sales. Monitor FDA 510(k) clearance velocity for general surgery robotic applications as inflection indicator for platform competition intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures bundled payment contracts with Medicare Advantage networks in Florida and Texas. |
| Software Companion Development | Integrates preoperative CT-to-implant matching with intraoperative navigation platforms. |
| Reimbursement Strategy | Aligns CMS outpatient prospective payment system codes with same-day discharge protocols. |
| CE Marking Pathway | Accelerates European market entry through EMA Medical Device Regulation technical documentation. |
| Surgeon Training Ecosystem | Locks in recurring system utilization through proprietary certification programs. |
Study Parameters
FDA 510(k) filings, CMS Medicare claims data, and EMA medical device registration databases formed the secondary backbone of this analysis. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and ambulatory surgical center administrators validated procedural volume estimates and pricing dynamics. Bottom-up facility-level volume aggregation and top-down manufacturer revenue reconciliation enabled triangulation across data sources.
Historical trendline analysis of procedure code migration from inpatient to outpatient settings anchored the projection framework. Segmentation modeling incorporated procedure type, technology tier, site of service, and geographic regulatory cluster dimensions across the analysis window. CAGRs derived from surgeon workforce pipeline data, Medicare demographic projections, and capital equipment replacement cycles. Forecast inputs included ambulatory surgical center certification trends and enhanced recovery after surgery protocol adoption rates.
Regulatory approval delays, reimbursement policy reversals, and robotic platform interoperability failures are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding site-of-service migration velocity and surgeon training capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Precocious Puberty Treatment Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Iron Deficiency Anemia Treatment Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Europe Platelet Rich Plasma (PRP) Market
Medical Treatment
Urea Cycle Disorders Treatment Market
Medical Treatment
Babesiosis Treatment Market
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Skin Grafts Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Stereotactic Radiation Therapy Market
Medical Treatment
Radiation Therapy Market