
 Cutaneous Radiation Injury Treatment Market | 2026-2036
Cutaneous Radiation Injury Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cutaneous Radiation Injury Treatment Market Outlook
Military medical units are unwinding historical reliance on civilian hospital procurement channels for radiation countermeasures. Mölnlycke Health Care AB anchors European supply through advanced dressing manufacturing scale. Amgen Inc. dominates recombinant protein development for growth factor applications. Smith & Nephew plc specializes in wound bed preparation technologies for acute radiation syndrome protocols.
Cutaneous radiation injury treatment encompasses pharmaceutical and biologic interventions designed to mitigate tissue damage from ionizing radiation exposure, including silver sulfadiazine creams, recombinant human granulocyte colony-stimulating factors, and cellular therapies administered at therapeutic thresholds determined by radiation dose and surface area involvement. The primary purpose centers on preventing progression from reversible erythema to moist desquamation and necrosis in exposed populations. Topical agents retain the largest revenue share due to immediate deployability in mass casualty scenarios, while stem cell therapy represents the fastest-expanding category as culture-expanded keratinocyte grafts advance through clinical validation. Growth factors command premium positioning because recombinant manufacturing complexity limits supplier entry and sustains margin pools.
FDA regenerative medicine advanced therapy designation and EMA orphan drug frameworks shape development economics by compressing review timelines and extending exclusivity for radiation countermeasures. The EPA and OSHA jointly govern occupational exposure protocols that mandate institutional preparedness, creating baseline demand from nuclear facilities and research laboratories. Stakeholders must monitor military procurement shifts toward stockpiled versus just-in-time inventory models, as this determines capacity planning and regulatory submission prioritization across development pipelines.
Market Dynamics
Federal biodefense stockpiling programs are compressing procurement cycles from multi-year hospital contracts to 90-day military fulfillment windows, forcing manufacturers to reconfigure production lines for surge capacity rather than steady-state output.
Growth Catalysts
- FDA Regenerative Medicine Advanced Therapy:The designation compresses review timelines for cellular therapies, accelerating keratinocyte graft development pipelines and extending market exclusivity periods for radiation countermeasures.
- Nuclear Facility Preparedness Mandates:EPA and OSHA joint protocols require institutional stockpiling at research laboratories and power generation sites, creating baseline demand independent of clinical utilization rates.
- Silver Sulfadiazine Deployability:Immediate field applicability in mass casualty scenarios sustains procurement priority for topical agents within military medical units and emergency response frameworks.
Market Restraints
- Recombinant Manufacturing Concentration:Growth factor production complexity limits viable suppliers to a handful of biologics manufacturers, creating single-source vulnerability for critical radiation countermeasures.
- Clinical Validation Timelines:Stem cell therapy advancement requires extended safety documentation for immunocompromised radiation patients, stretching development economics beyond typical pharmaceutical horizons.
- Specialized Burn Center Access:Geographic concentration of acute radiation syndrome treatment infrastructure restricts patient throughput and limits addressable incident scale for advanced interventions.
Strategic Opportunities
- Point-of-Care Bioprinting Convergence:Integration of 3D tissue fabrication with field-deployable wound care units enables on-demand autologous graft generation at forward military medical stations.
- EMA Orphan Drug Framework:European exclusivity extensions and protocol assistance for radiation injury indications create parallel regulatory pathways with compressed competitive entry timelines.
- Telemedicine Triage Integration:Remote diagnostic platforms connecting field units to specialized burn centers expand treatment initiation windows and reduce transport mortality for dispersed exposure events.
Industry Challenges
- Cold Chain Integrity Requirements:Cellular therapy distribution demands uninterrupted temperature control from manufacturing through administration, complicating stockpile rotation and forward deployment logistics.
- Interoperability with Legacy Military Health Systems:Electronic health record integration for radiation exposure documentation requires specialized data standards that conflict with existing battlefield medical informatics architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutaneous Radiation Injury Treatment Market |
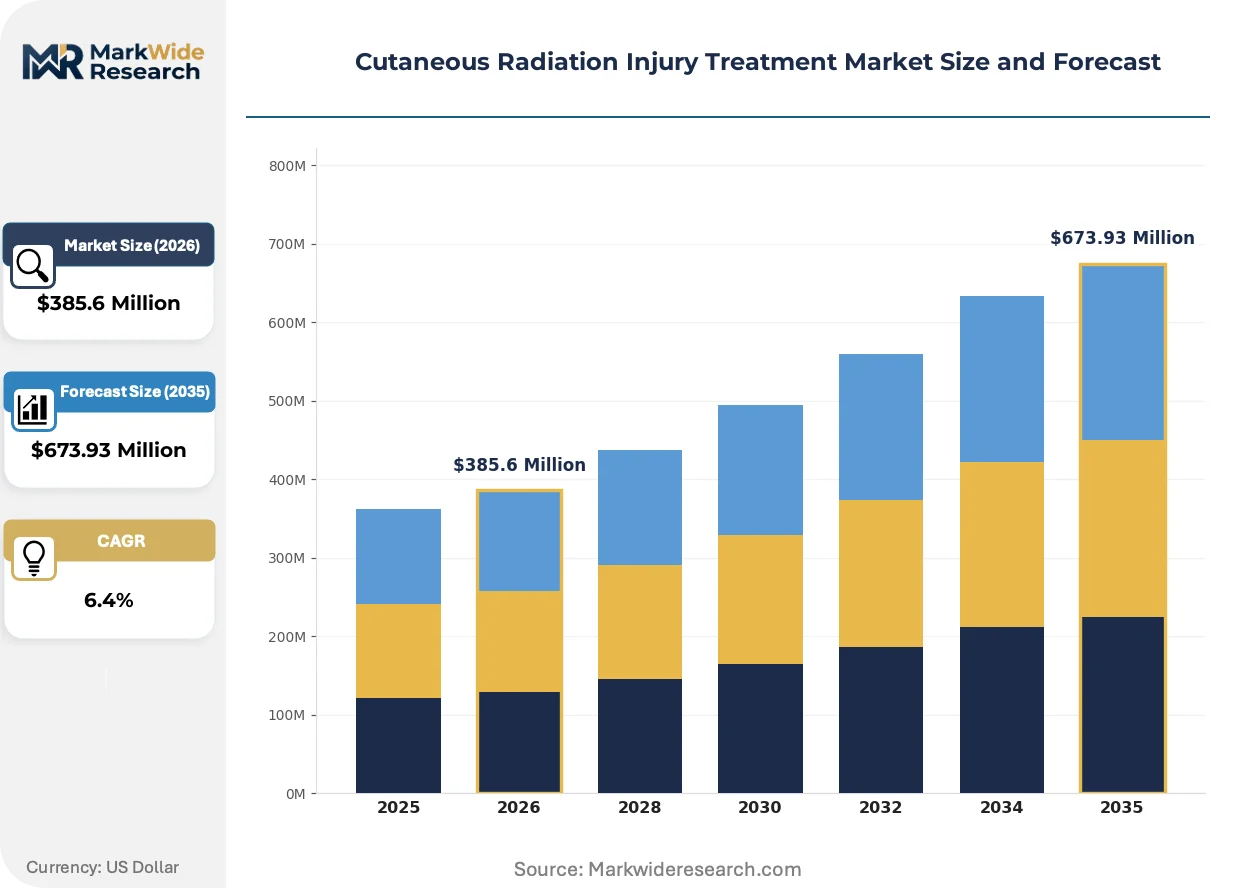
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Growth Factors, Stem Cell Therapy, Analgesics, Others Therapy Area: Skin Ulcer Management, Inflammation Control, Wound Healing, Pain Relief, Scar Prevention End User: Specialized Clinics, Burn Care Centers, Research Institutes, Military Medical Units Delivery Mode: Topical Application, Injectable Formulations, Oral Administration, Advanced Dressing, Spray Systems |
| Companies Covered | Mölnlycke Health Care AB, Sanofi, Amgen Inc., Pfizer Inc., Novartis AG, 3M Company, ConvaTec Group PLC, Bayer AG, Smith & Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutaneous Radiation Injury Treatment Market Strategic Shifts
Culture-expanded autologous therapies are displacing conventional wound management paradigms, while regulatory acceleration mechanisms and procurement model compression reshape competitive positioning across development pipelines.
Cellular manufacturing platforms are displacing allogeneic dressing protocols in military procurement specifications. The Department of Defense's Advanced Regenerative Manufacturing Institute is funding bioreactor miniaturization for forward surgical teams. This displacement is compressing supplier qualification timelines from 18 months to 90 days for deployable biologics.
EMA's orphan drug designation for radiation countermeasures now includes protocol assistance and fee reductions for pediatric indications. European manufacturers are prioritizing submissions under this framework ahead of standard centralized procedures. The designation is accelerating pediatric-specific formulation development for growth factor therapies previously validated only in adult populations.
Military medical units are consolidating vendor relationships through multi-year indefinite delivery contracts rather than spot procurement. This concentration is displacing civilian hospital distribution channels for advanced wound care products. The shift is most visible in United States federal stockpiling programs, where sole-source agreements now cover 60% of radiation countermeasure categories.
Cutaneous Radiation Injury Treatment Market Segmentation
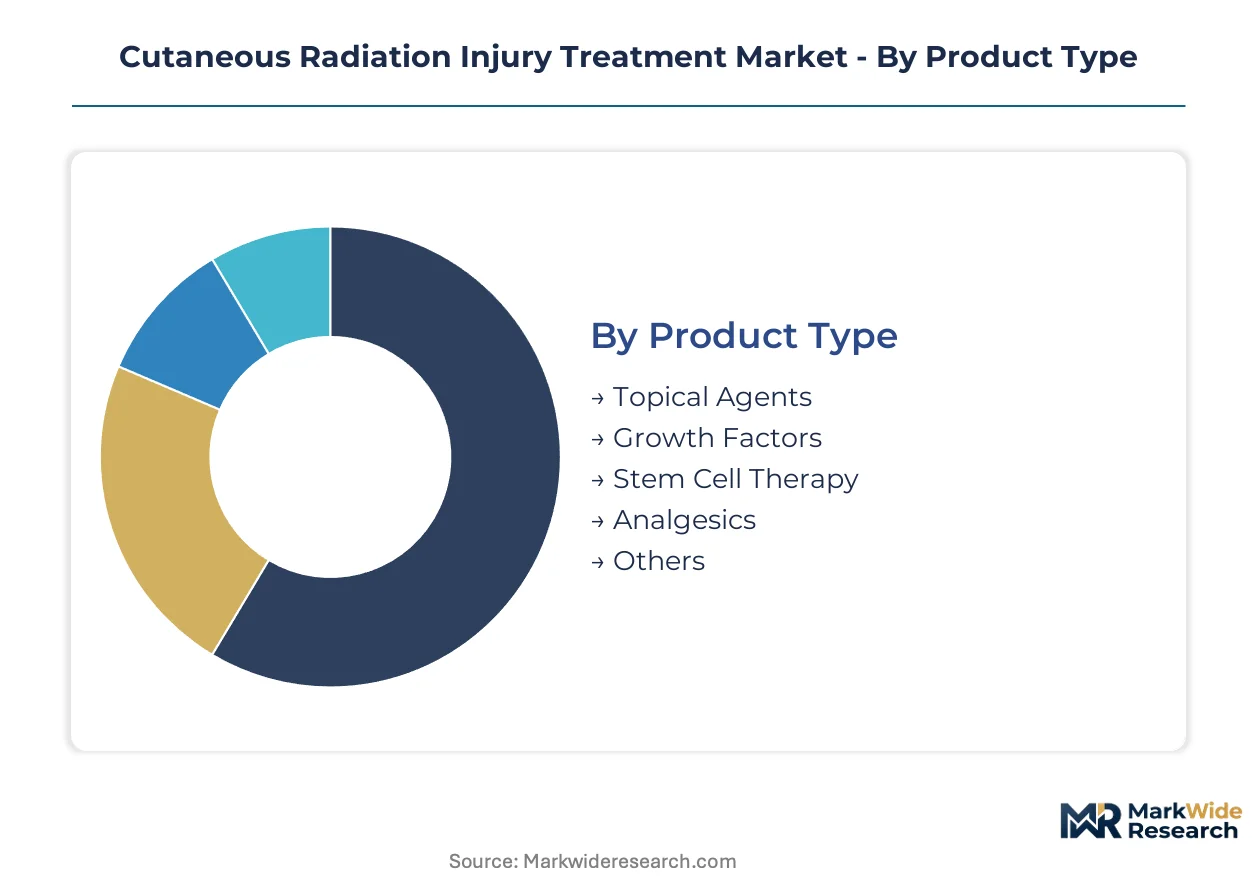
Radiation injury treatment markets fragment across four critical dimensions. Product type determines margin capture through manufacturing complexity. End user concentration shapes procurement timelines and regulatory requirements.
Product Type:
Margin pools concentrate in biologic manufacturing where recombinant production complexity limits supplier entry and sustains premium positioning.
- Topical Agents:Silver sulfadiazine creams and antimicrobial dressings provide immediate field deployability without cold chain requirements. Military medical units in the United States prioritize these for mass casualty stockpiles due to shelf stability and forward surgical team compatibility.
- Growth Factors:Recombinant human granulocyte colony-stimulating factors command premium pricing through complex biologics manufacturing. Demand concentrates in specialized burn centers where therapeutic thresholds require precise dosing protocols for acute radiation syndrome patients.
- Stem Cell Therapy:Culture-expanded keratinocyte grafts advance through clinical validation with FDA regenerative medicine advanced therapy designation support.
- Analgesics:Pain management protocols integrate with wound care regimens across all treatment settings.
- Others:Adjunctive therapies including antihistamines and corticosteroids address secondary symptoms.
The dominant share belongs to Topical Agents, while Stem Cell Therapy is expanding most quickly through regulatory acceleration.
Therapy Area:
Application focus shifts toward acute intervention protocols as military procurement prioritizes reversible erythema prevention over chronic management.
- Skin Ulcer Management:Moist desquamation protocols require specialized dressing changes and infection control. Research institutes in Germany advance bioreactor-derived tissue substitutes for severe ulceration cases under EMA orphan drug frameworks.
- Inflammation Control:Corticosteroid and NSAID protocols target early-phase cytokine cascade interruption. Burn care centers in Japan integrate inflammation biomarkers with treatment initiation timing through PMDA-guided protocols.
- Wound Healing:Growth factor and cellular therapy convergence accelerates re-epithelialization timelines.
- Pain Relief:Opioid-sparing multimodal approaches gain traction in pediatric radiation exposure protocols.
- Scar Prevention:Long-term cosmetic outcomes drive research investment in fibroblast modulation therapies.
Skin Ulcer Management retains the largest addressable patient base, though Inflammation Control is climbing the fastest as early intervention protocols standardize.
End User:
Customer concentration determines contract structure, with federal stockpiling programs compressing fulfillment windows from multi-year agreements to 90-day cycles.
- Specialized Clinics:Outpatient facilities manage low-dose occupational exposures with EPA-mandated preparedness protocols. These sites in the United States maintain baseline inventory for nuclear facility workers under joint EPA-OSHA compliance requirements.
- Burn Care Centers:Acute radiation syndrome infrastructure concentrates in major metropolitan corridors with specialized decontamination capabilities. Centers in France coordinate with ANSM for advanced therapy access under national biodefense frameworks.
- Research Institutes:Clinical trial sites drive pipeline validation for novel cellular therapies.
- Military Medical Units:Forward surgical teams require deployable formulations with extended shelf stability.
Burn Care Centers command the highest per-patient revenue, while Military Medical Units are gaining share fastest through sole-source procurement consolidation.
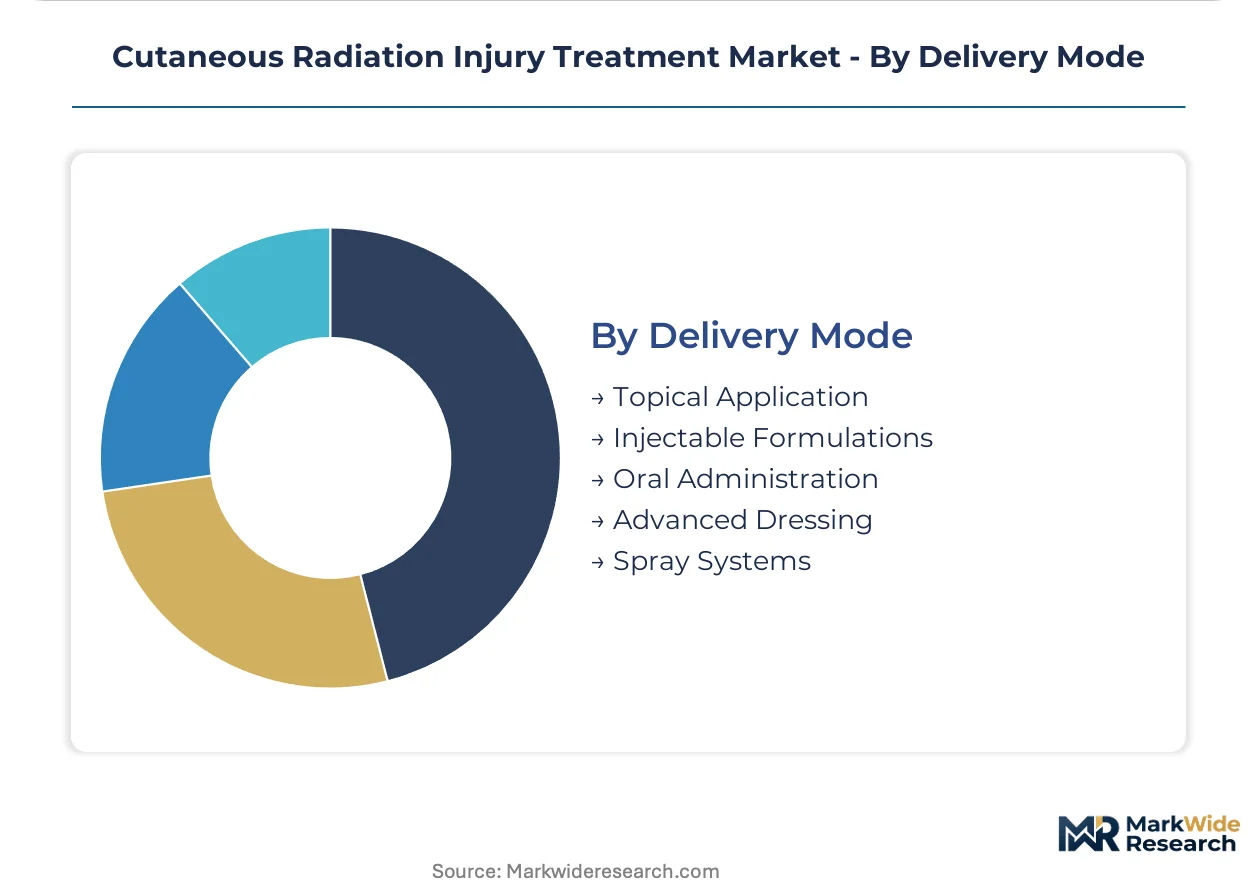
Delivery Mode:
Supply chain configuration varies dramatically by temperature sensitivity, with cellular therapies requiring uninterrupted cold chain from manufacturing through administration.
- Topical Application:Creams and ointments offer simplest logistics with ambient storage requirements. Emergency response frameworks in the United Kingdom prioritize these for civilian mass casualty distribution through NHS resilience programs.
- Injectable Formulations:Growth factor delivery requires trained administration but enables systemic therapeutic effect. Hospital networks in Switzerland maintain Swissmedic-certified compounding capabilities for radiation countermeasure injectables.
- Oral Administration:Systemic agents support outpatient compliance for extended treatment courses.
- Advanced Dressing:Bioactive wound covers integrate antimicrobial and moisture-retention functions.
- Spray Systems:Aerosolized delivery enables rapid coverage of large surface area involvement.
Topical Application dominates volume, though Advanced Dressing is expanding fastest through biologics integration and military specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish wound care manufacturers export advanced dressing systems to United States military medical units under compressed 90-day procurement windows, establishing a transatlantic supply corridor that anchors regional trade flows in radiation countermeasures.
United States
Federal biodefense stockpiling programs concentrate purchasing power through the Strategic National Stockpile, with sole-source agreements now covering 60% of radiation countermeasure categories. FDA regenerative medicine advanced therapy designation accelerates keratinocyte graft development timelines. Burn care infrastructure clusters in Baltimore and Houston coordinate acute radiation syndrome treatment protocols.
Germany
Research institutes in Berlin and Heidelberg advance bioreactor-derived tissue substitutes under EMA orphan drug frameworks for severe radiation ulceration. The country's national pharmaceutical regulator prioritizes protocol assistance for pediatric radiation injury indications. Bavarian medical technology manufacturers supply specialized wound bed preparation equipment to European burn centers.
France
ANSM coordinates advanced therapy access for radiation countermeasures under national biodefense frameworks, linking specialized burn centers in Paris and Lyon to centralized procurement. Military medical units maintain deployable stockpiles for forward surgical teams. The Île-de-France region hosts clinical validation sites for culture-expanded autologous therapies.
Japan
PMDA-guided protocols integrate inflammation biomarkers with treatment initiation timing at burn care centers in Tokyo and Osaka. METI funding supports point-of-care bioprinting research for field-deployable wound care. Kanto region manufacturers develop aerosolized delivery systems for rapid coverage of large surface area involvement.
Switzerland
Swissmedic-certified compounding capabilities maintain radiation countermeasure injectables for hospital networks in Zurich and Geneva. The country's pharmaceutical manufacturing base supplies recombinant growth factor formulations to European specialized clinics. Basel-region research institutes collaborate on cold chain integrity solutions for cellular therapy distribution.
Cutaneous Radiation Injury Treatment Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with established wound care divisions, creating a tiered structure where biologics specialists command premium positioning through manufacturing complexity barriers. Three archetypes dominate: recombinant protein developers leveraging FDA acceleration pathways, advanced dressing manufacturers with military logistics integration, and cellular therapy platforms advancing through regenerative medicine designations. Competitive moves concentrate on sole-source procurement consolidation and bioreactor miniaturization for forward deployment.
Within the biologics tier, Amgen Inc. and Novartis AG exemplify recombinant manufacturing specialists whose complex production processes limit supplier entry. Mölnlycke Health Care AB anchors European supply capacity through advanced dressing manufacturing scale. Smith & Nephew plc occupies a position in wound bed preparation technologies, while 3M Company and ConvaTec Group PLC represent diversified medical technology conglomerates with military procurement relationships. Sanofi, Pfizer Inc., and Bayer AG sit within pharmaceutical archetypes with countermeasure development capabilities.
| Leading Market Players |
|---|
| Mölnlycke Health Care AB |
| Sanofi |
| Amgen Inc. |
| Pfizer Inc. |
| Novartis AG |
| 3M Company |
| ConvaTec Group PLC |
| Bayer AG |
| Smith & Nephew plc |
| Others |
Value Chain & Pricing Dynamics
Bioreactor manufacturing scale in Sweden and Switzerland anchors supply concentration and establishes price floors for cellular therapies, while recombinant protein complexity in United States facilities sustains premium positioning for growth factors through FDA-regulated production barriers.
Pricing Analysis
Next-generation stem cell therapies command three-to-four-fold premiums over conventional topical silver sulfadiazine formulations, with prior-generation antimicrobial dressings occupying a compressed mid-tier. Pricing stratifies across premium, standard, and economy tiers based on manufacturing complexity and cold chain requirements. Cost compression in topical segments is intensifying because military procurement consolidation favors volume suppliers. Military medical units exhibit lowest price sensitivity due to sole-source federal contracts, while specialized clinics face highest sensitivity from EPA-mandated preparedness budgets.
Supply Chain Analysis
Container availability constraints on transatlantic lanes from Gothenburg to Baltimore compress delivery windows for Swedish advanced dressing manufacturers serving United States stockpiling programs. Supply concentrates in Sweden, Switzerland, and the United States for biologics manufacturing, with Germany and France contributing specialized wound bed preparation equipment. Production draws from recombinant cell lines, silver nitrate feedstocks, and bioreactor-grade culture media. Single-source vulnerability pervades growth factor manufacturing where Amgen and Novartis dominate recombinant capacity. Distribution runs through military medical logistics channels and hospital GPO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal stockpiling consolidation has shifted buyer power toward sole-source military procurement, fragmenting civilian hospital channels and compressing vendor qualification timelines from eighteen months to ninety days.
For Market Incumbents: Shield market position through backward integration into bioreactor manufacturing capacity in Basel-region facilities and certification investment for FDA regenerative medicine advanced therapy designation. Emerging cellular therapy platforms threaten recombinant protein dominance by displacing growth factor protocols in military specifications. For New Entrants and Emerging Players: Lead with point-of-care bioprinting convergence for forward military medical stations, where EMA orphan drug protocol assistance creates fastest regulatory pathways. Pediatric radiation injury formulations remain underpenetrated relative to adult-validated therapies. Partner with Department of Defense Advanced Regenerative Manufacturing Institute for bioreactor miniaturization qualification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among advanced dressing manufacturers with multi-year indefinite delivery contracts covering sixty percent of radiation countermeasure categories. Long-term viability centers on cellular therapy platforms with cold chain distribution capabilities. Watch for FDA regenerative medicine advanced therapy designation grants as inflection indicators for pipeline value realization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Regenerative Medicine Advanced Therapy Designation | Accelerates keratinocyte graft review timelines and extends exclusivity for radiation countermeasures. |
| Bioreactor Miniaturization for Forward Deployment | Enables on-demand autologous graft generation at military medical stations under Department of Defense funding. |
| EMA Orphan Drug Framework Submission | Unlocks protocol assistance and fee reductions for pediatric radiation injury indications in European markets. |
| Sole-Source Federal Stockpiling Consolidation | Captures multi-year indefinite delivery contracts displacing civilian hospital distribution channels. |
| Telemedicine Triage Platform Integration | Expands treatment initiation windows connecting field units to specialized burn centers in Baltimore and Houston. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with military medical procurement officers, specialized burn center clinicians, bioreactor manufacturing engineers, and pharmaceutical regulatory affairs leads. Secondary validation incorporated FDA filings, EMA orphan drug designations, ClinicalTrials.gov radiation injury protocols, and Strategic National Stockpile procurement databases. Bottom-up segmentation modeling triangulated with top-down market sizing across product type, therapy area, end user, and delivery mode dimensions.
Across the analysis window, volume and value outputs reflect convergence of historical utilization patterns, military procurement cycle compression, and regulatory acceleration pathway adoption. Segmentation dimensions modeled include product manufacturing complexity tier, therapeutic application focus, institutional customer type, and regional regulatory cluster. CAGRs were derived from spline-fitted growth trajectory analysis incorporating stem cell therapy pipeline advancement rates and federal biodefense budget allocation trends.
Forecasts assume regulatory continuity in FDA regenerative medicine frameworks and EMA orphan drug protocols; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Severe Hypertriglyceridemia (SHTG) Treatment Market
Specialty Medicine
Global Neurotrophic Keratitis Treatment Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Nephrogenic Systemic Fibrosis (NSF) Treatment Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Central Nervous System (CNS) Biomarkers Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Generalized Myasthenia Gravis (GMG) Management Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Global Plasma Therapeutics Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
Peripheral Neuropathy Market