
 Hyperphosphatemia Treatment Market | 2026-2036
Hyperphosphatemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperphosphatemia Treatment Market Intelligence
The expertise of nephrology specialists in managing complex chronic kidney disease patient populations is rotating toward earlier intervention with novel phosphate binders. Sanofi leverages its established portfolio and commercial infrastructure in renal care to maintain its market position. Akebia Therapeutics, Inc. competes by focusing on innovative therapies for kidney disease complications. Takeda Pharmaceutical Company Limited sustains its presence through a combination of legacy products and pipeline development for this patient group.
Hyperphosphatemia treatment comprises pharmacological interventions designed to control elevated serum phosphate levels, a frequent complication in patients with chronic kidney disease. These therapies work to maintain phosphate concentrations below targets like 5.5 mg/dL, mitigating risks of vascular calcification. The product landscape is seeing a shift from calcium-based phosphate binders to newer iron-based and non-calcium-based binders, which offer better safety. Treatment for dialysis patients remains the core therapy area, representing the largest concentration of use.
Regulatory bodies including the US Food and Drug Administration (FDA), the European Medicines Agency (EMA), and Japan's Pharmaceuticals and Medical Devices Agency (PMDA) govern market access. Their stringent requirements for clinical trial endpoints and long-term safety data for new phosphate binders shape product development cycles. Stakeholders must now monitor evolving reimbursement policies for novel therapies and the clinical progress of non-binder treatment modalities.
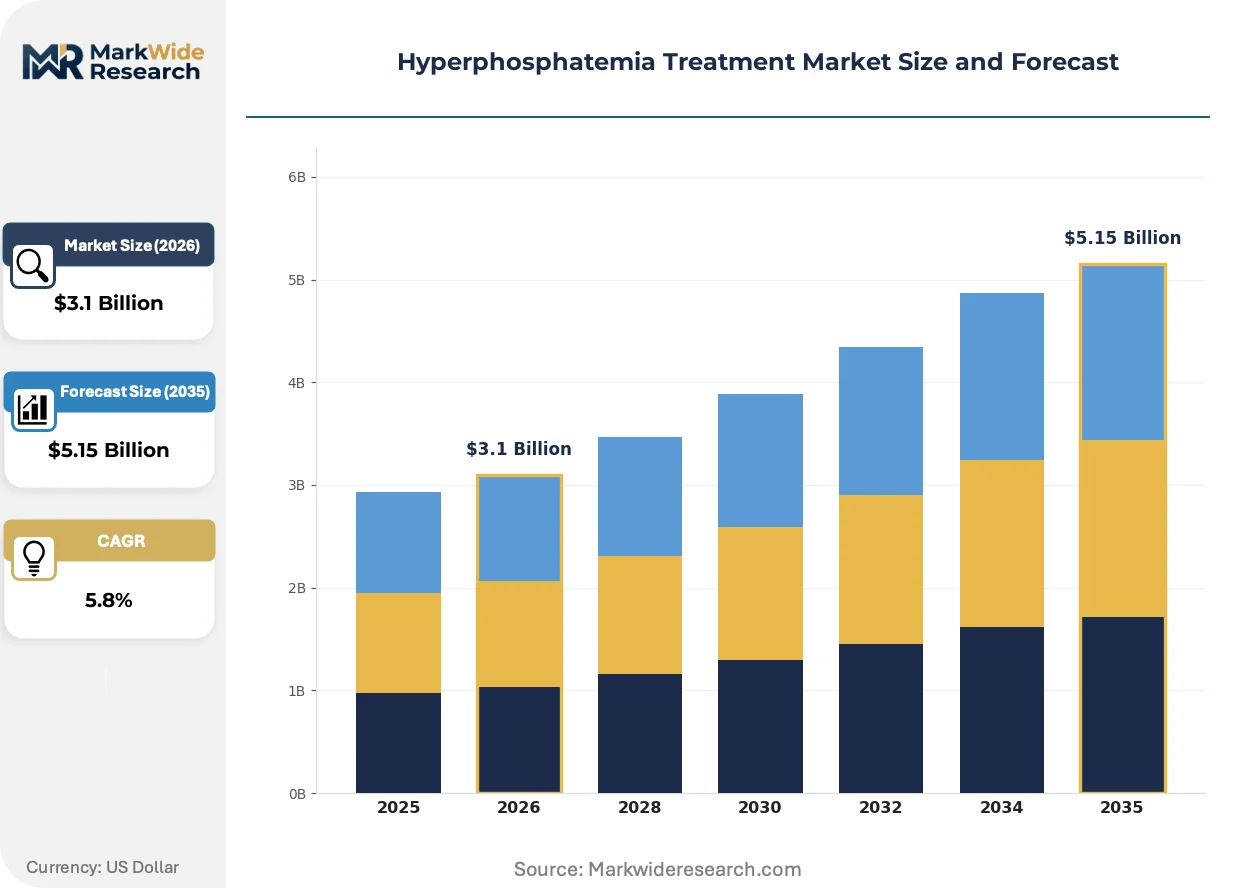
Market Dynamics
The central dynamic shaping the hyperphosphatemia treatment market is the clinical paradigm shift toward earlier intervention with safer, non-calcium-based phosphate binders. This move is driven by mounting evidence linking older calcium-based agents to increased cardiovascular risk in chronic kidney disease patients.
Growth Catalysts
- Aging Demographics:The rising prevalence of chronic kidney disease (CKD) in countries with rapidly aging populations, such as Japan and Germany, directly expands the patient pool requiring phosphate management therapies.
- Favorable Regulatory Pathways:Regulatory bodies like the FDA and EMA are providing clearer approval pathways for novel phosphate binders that demonstrate improved safety profiles, encouraging pipeline development.
- Evolving Clinical Guidelines:Nephrology practice is shifting toward proactive management of mineral and bone disorders earlier in the CKD progression, increasing the utilization of phosphate binders before patients reach dialysis.
Market Restraints
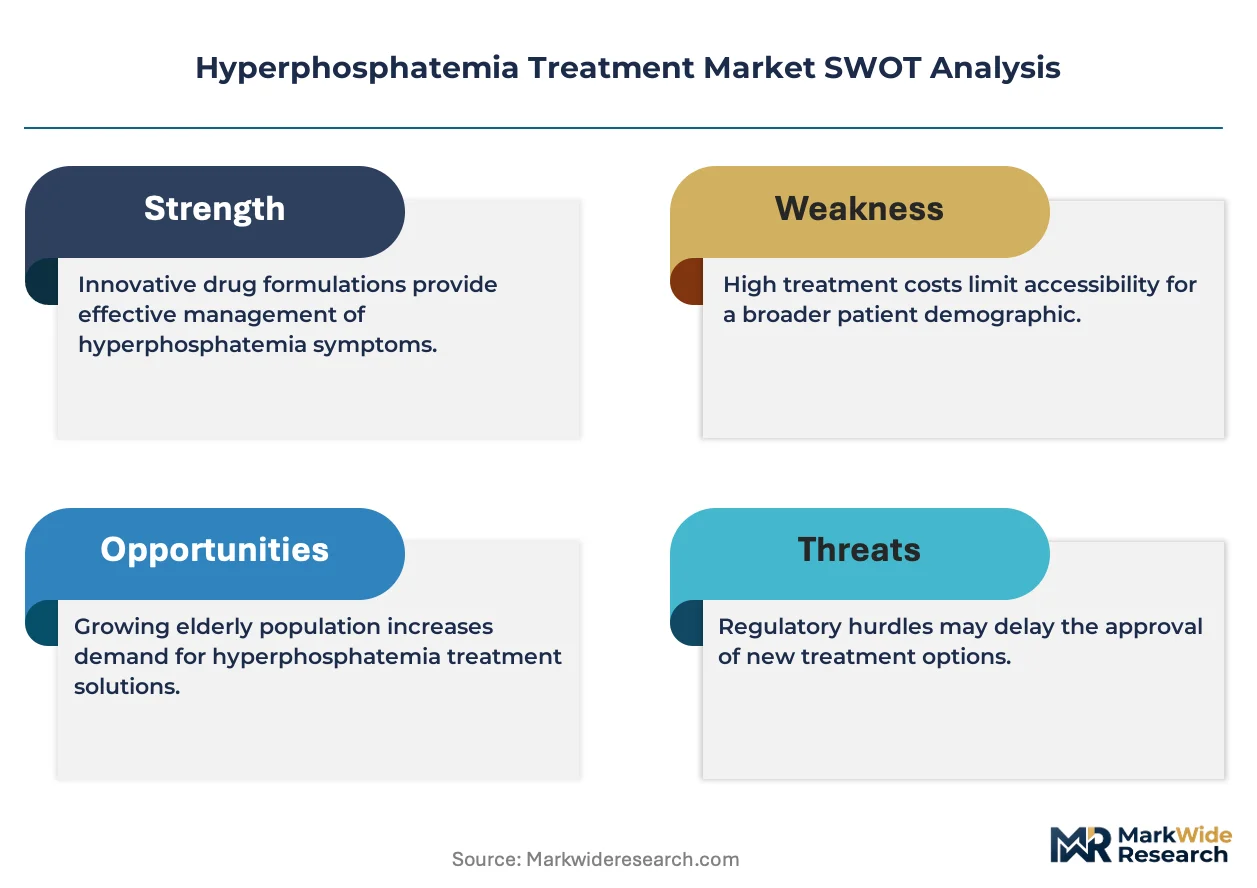
- Cost and Reimbursement Hurdles:The higher price of novel iron-based and non-calcium binders compared to generic calcium-based alternatives creates access barriers in healthcare systems with strict cost-containment policies.
- Dietary Management as a Substitute:Effective dietary intervention and patient education on limiting phosphate intake can reduce the pharmacological need for binders, acting as a non-therapeutic substitute that limits market size.
- Stringent Safety Data Requirements:Long-term cardiovascular outcome data demanded by regulators, including Japan's PMDA, extends clinical trial timelines and increases development costs, delaying market access for new entrants.
Strategic Opportunities
- Emerging Market Penetration:Expanding educational and commercial activities into large, under-resourced markets in Asia and Latin America, where CKD incidence is rising, presents a significant growth opportunity.
- Development of Non-Binder Modalities:Research into alternative mechanisms, such as inhibitors of intestinal phosphate transporters, offers a path to innovative therapies that could complement or replace traditional binders.
- Digital Health Integration:Creating mobile applications and digital platforms to improve medication adherence and track dietary phosphate intake can enhance treatment efficacy and provide a competitive service differentiator.
Industry Challenges
- Clinical Trial Endpoint Complexity:Proving that a phosphate binder provides a mortality benefit, not just a surrogate endpoint reduction, requires large, expensive, and lengthy cardiovascular outcome trials.
- Securing Payer Coverage:Demonstrating cost-effectiveness to secure favorable reimbursement for premium-priced drugs is a major operational hurdle, requiring substantial health economics and outcomes research.
- Patient Adherence Issues:High pill burden associated with phosphate binders leads to poor patient compliance, which can limit the real-world effectiveness of treatments and complicate clinical data interpretation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperphosphatemia Treatment Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium-Based Phosphate Binders, Non-Calcium-Based Phosphate Binders, Iron-Based Phosphate Binders, Combination Therapies Therapy Area: Chronic Kidney Disease, Dialysis Patients, End-Stage Renal Disease, Acute Kidney Injury End User: Nephrology Clinics, Dialysis Centers, Specialty Hospitals, Ambulatory Surgical Centers Delivery Mode: Oral Tablets, Oral Suspension, Intravenous Injection, Extended Release Formulations |
| Companies Covered | Sanofi, Takeda Pharmaceutical Company Limited, Astellas Pharma Inc, Akebia Therapeutics, Inc., Ardelyx, CSL Vifor, Lupin, Unicycive Therapeutics, Inc, Kyowa Kirin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperphosphatemia Treatment Market Strategic Shifts & Innovations
Innovation in hyperphosphatemia treatment is driven by a focus on improving patient safety and long-term cardiovascular outcomes. The market is evolving from simply lowering serum phosphate to providing therapies with minimal systemic side effects and better adherence profiles.
Novel iron-based phosphate binders are designed to chelate dietary phosphate within the gastrointestinal tract, offering an improved safety profile. Nephrologists treating patients with end-stage renal disease are accelerating their adoption of these agents. This newer class of therapy is supplanting traditional calcium-based binders, which carry an association with increased risks of vascular calcification and cardiovascular events in vulnerable patient populations.
The European Medicines Agency (EMA) is placing greater emphasis on real-world evidence in its post-authorization assessments for phosphate binders. This regulatory focus compels manufacturers to invest in ongoing data collection to validate long-term safety and effectiveness outside of controlled clinical trials. Products targeting the large CKD populations in Germany and France are particularly affected, as this data influences national reimbursement and pricing negotiations.
A shift towards integrated care models for chronic kidney disease is altering treatment delivery patterns for hyperphosphatemia. This approach disrupts the traditional prescribing model centered exclusively in specialized nephrology clinics by involving primary care physicians in earlier stages of phosphate monitoring and management. The trend is most prominent in countries with national health systems, where it supports strategies to mitigate long-term complication costs.
Hyperphosphatemia Treatment Market Segmentation
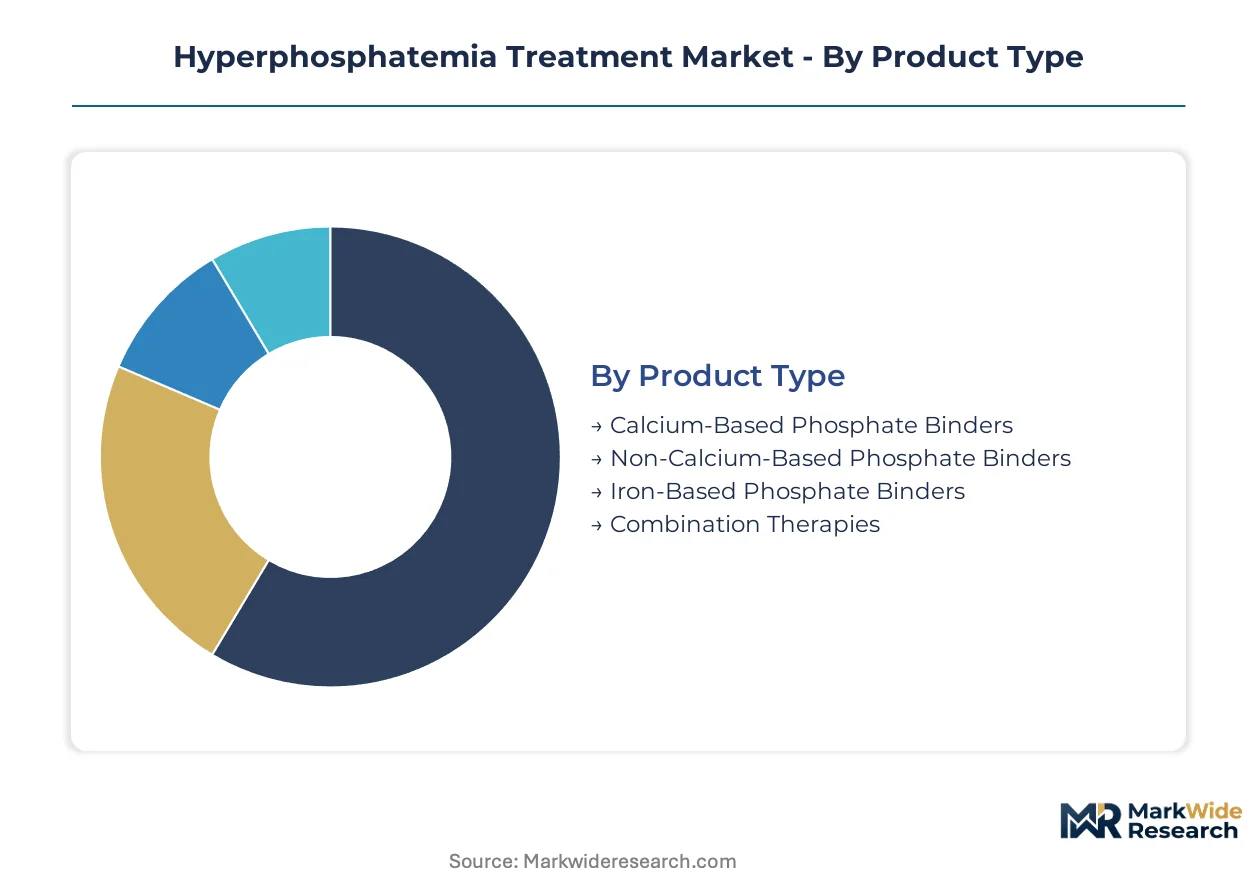
The hyperphosphatemia treatment market categorizes therapies based on various attributes, providing a structured view of product offerings and patient care pathways. Understanding these segments is crucial for stakeholders to identify areas of unmet need and emerging therapeutic opportunities within renal care.
Product Type:
Regulatory bodies globally differentiate hyperphosphatemia treatments based on their chemical composition and safety profiles, influencing market access and clinical adoption.
- Iron-Based Phosphate Binders:These agents chelate dietary phosphate in the gastrointestinal tract, forming insoluble complexes that are excreted. Demand concentrates in dialysis centers across Japan and Germany, driven by their improved safety profiles compared to older alternatives.
- Non-Calcium-Based Phosphate Binders:This class includes various compounds, such as sevelamer, which bind phosphate without contributing to calcium load. Utilization is high in patients with chronic kidney disease in the US and EU, where regulators like the FDA and EMA prioritize cardiovascular safety.
- Calcium-Based Phosphate Binders:These traditional binders contain calcium, which can contribute to vascular calcification in vulnerable patients.
- Combination Therapies:Such treatments involve using multiple binder types or binders with other phosphate-lowering agents for enhanced efficacy.
Calcium-Based Phosphate Binders handle the majority of throughput; Iron-Based Phosphate Binders are the fastest mover on share.
Therapy Area:
Hyperphosphatemia treatment applications vary significantly by patient population, reflecting distinct disease progression stages and therapeutic needs.
- Dialysis Patients:This segment encompasses individuals undergoing hemodialysis or peritoneal dialysis, who frequently experience severe hyperphosphatemia due to impaired renal clearance. Treatment utilization is concentrated in specialized dialysis centers globally, particularly in countries with high dialysis rates like Japan.
- End-Stage Renal Disease:Patients with ESRD, irrespective of dialysis status, represent a critical population requiring aggressive phosphate management to prevent complications. Therapies are widely prescribed in conjunction with other renal care interventions across North America and Europe.
- Chronic Kidney Disease:Management of hyperphosphatemia in earlier CKD stages aims to mitigate long-term cardiovascular risks before dialysis initiation.
- Acute Kidney Injury:This temporary condition can sometimes lead to hyperphosphatemia, requiring short-term pharmacological intervention.
Treatment for dialysis patients forms the largest therapy area, while interventions for chronic kidney disease patients are expanding most quickly.
End User:
The delivery of hyperphosphatemia treatments is segmented by the specialized healthcare settings that manage renal patient populations.
- Dialysis Centers:These facilities provide regular renal replacement therapy and are primary points of care for patients requiring ongoing phosphate binder prescriptions. High volumes of prescriptions originate from these centers, particularly in the US and Germany, due to the chronic nature of treatment.
- Specialty Hospitals:Hospitals with dedicated nephrology departments manage complex CKD and ESRD cases, including patients with severe hyperphosphatemia. These institutions serve as referral centers for advanced treatment initiation and monitoring.
- Nephrology Clinics:Outpatient clinics specializing in kidney health manage early-stage CKD patients and monitor phosphate levels.
- Ambulatory Surgical Centers:These centers primarily focus on surgical procedures and have limited direct involvement in chronic hyperphosphatemia management.
Dialysis Centers represent the highest volume end-user segment, with Nephrology Clinics showing increasing engagement for earlier interventions.
Delivery Mode:
The mode of drug delivery significantly impacts patient adherence and therapeutic efficacy in hyperphosphatemia management.
- Oral Tablets:This delivery mode remains the most common for phosphate binders, offering convenience and ease of administration for long-term chronic use. Patient adherence challenges exist due to high pill burden, particularly in Europe and North America.
- Extended Release Formulations:These innovative formulations are designed to reduce dosing frequency, potentially improving patient compliance and maintaining stable serum phosphate levels. Development efforts focus on enhancing convenience for patients in the US and Japan.
- Oral Suspension:Liquid formulations provide an alternative for patients with dysphagia or those requiring flexible dosing adjustments.
- Intravenous Injection:This mode is rarely used for phosphate binders and is typically reserved for other renal-related medications.
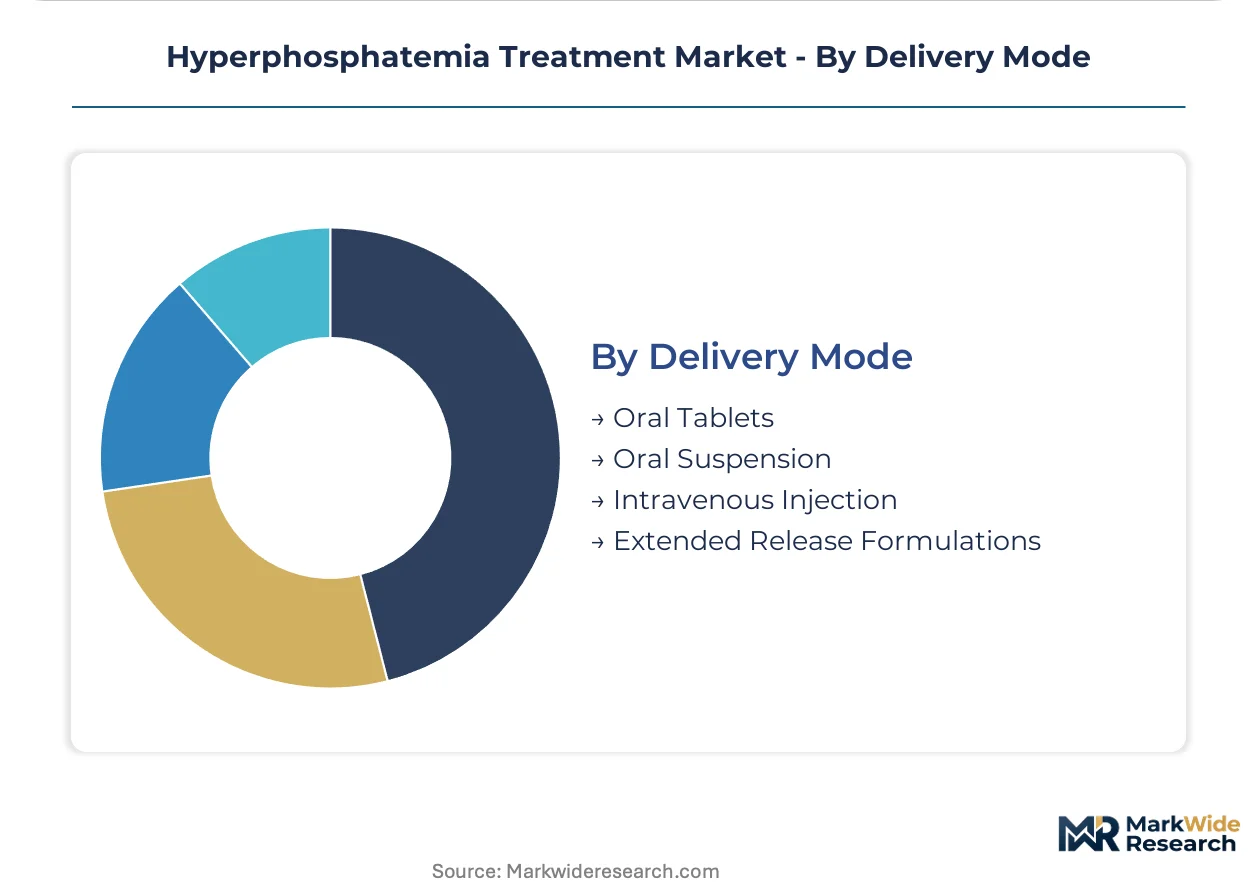
Oral Tablets dominate the delivery landscape, while Extended Release Formulations are gaining traction for their adherence benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hyperphosphatemia treatment market shows a varied consumption mix, with some geographies accelerating the adoption of novel iron-based binders while others maintain reliance on traditional calcium-based agents. This differential reflects diverse healthcare priorities and regulatory landscapes across developed nations. Patient demographics and CKD prevalence also influence regional market dynamics.
United States
High demand for advanced non-calcium binders stems from a large ESRD patient population and a focus on cardiovascular safety. The FDA's clear approval pathways for novel phosphate binders encourage pharmaceutical innovation. Major pharmaceutical research hubs in Boston and San Francisco drive development and commercialization efforts.
Germany
Germany's aging demographic fuels a substantial need for hyperphosphatemia management, with a strong preference for safer iron-based therapies. The EMA's emphasis on real-world evidence influences national reimbursement policies, particularly for new agents. Berlin and Munich serve as key centers for nephrology research and specialized dialysis networks.
Japan
Japan demonstrates a concentrated demand for hyperphosphatemia treatments, especially in its extensive dialysis patient cohort. The PMDA's stringent safety requirements shape product development, favoring binders with established long-term efficacy. Tokyo and Osaka are central to advanced renal care and the distribution of novel therapies.
France
French healthcare prioritizes long-term patient outcomes, driving the utilization of non-calcium phosphate binders to mitigate cardiovascular risks. National health agencies influence treatment guidelines and procurement, impacting market access for new drugs. Paris and Lyon host significant nephrology clinics and research institutions.
Canada
Canadian demand for hyperphosphatemia treatments is consistently growing due to an increasing CKD burden. Health Canada's regulatory framework ensures product safety and efficacy, guiding market entry for pharmaceutical companies. Toronto and Montreal are key urban centers with advanced renal care facilities and specialist nephrology practices.
Hyperphosphatemia Treatment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the hyperphosphatemia treatment market structure. This market exhibits a tiered competitive landscape, with established pharmaceutical companies and innovative biotech firms vying for market share. Strategic archetypes include large-cap diversified pharmaceutical companies and focused renal care specialists. Companies are primarily engaging in pipeline development and strategic partnerships to expand their therapeutic offerings.
Within the large-cap diversified pharmaceutical archetype, Sanofi and Takeda Pharmaceutical Company Limited represent established players leveraging existing commercial infrastructures. Akebia Therapeutics, Inc. exemplifies an innovative therapy developer, focusing on novel solutions for kidney disease complications. These companies anchor market activity through their varied product portfolios and development pipelines. Their strategic positioning reflects the ongoing shift towards advanced non-calcium-based phosphate binders.
| Leading Market Players |
|---|
| Sanofi |
| Takeda Pharmaceutical Company Limited |
| Astellas Pharma Inc |
| Akebia Therapeutics, Inc. |
| Ardelyx |
| CSL Vifor |
| Lupin |
| Unicycive Therapeutics, Inc |
| Kyowa Kirin |
| Others |
Cost & Logistics Intelligence
Extended lead times for novel iron-based phosphate binders influence inventory levels and grant manufacturers significant pricing power. This dynamic reflects the specialized production processes and regulatory hurdles in the pharmaceutical supply chain.
Pricing Analysis
Long-term contract-based arrangements dominate pricing for hyperphosphatemia treatments with healthcare systems and national payers. Price differentiation arises from superior safety profiles of novel iron-based binders and established brand recognition. Pricing pressure stems from strict cost-containment policies implemented by national health agencies, particularly for premium-priced therapies. Dialysis centers demonstrate high price sensitivity due to large volume procurement, while nephrology specialists prioritize clinical outcomes for complex cases.
Supply Chain Analysis
Maintaining optimal inventory levels for hyperphosphatemia treatments requires precise forecasting due to complex manufacturing and regulatory timelines. Supply concentration for advanced pharmaceutical ingredients rests in countries like India and China, while finished product manufacturing often occurs in the USA and Germany. The supply chain relies heavily on specialized Active Pharmaceutical Ingredients and specific excipients. Regulatory approval delays represent a significant structural risk, impacting market entry and product availability. Distribution primarily runs through specialized hospital pharmacies and integrated dialysis center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a defensive-moat story, primarily due to significant regulatory entrenchment from bodies like the FDA and EMA. Stringent approval pathways for novel phosphate binders create substantial barriers to entry for new competitors.
For Market Incumbents: Secure long-term market position by investing in extensive cardiovascular outcome trials for novel agents, reinforcing their safety and efficacy profiles. Expanding commercial infrastructure into emerging markets like Asia and Latin America mitigates the threat from lower-cost generic alternatives. Further R&D into combination therapies and non-binder treatment modalities provides a critical lever against future competitive shifts.
For New Entrants and Emerging Players: Accelerated regulatory pathways, such as orphan drug designations for rare kidney conditions, offer a fast-track for novel therapies. Target white-space opportunities in non-binder treatment modalities, such as inhibitors of intestinal phosphate transporters, to avoid direct competition with established binders. The early chronic kidney disease patient segment represents the most penetrable market. A go-to-market strategy focusing on partnerships with nephrology clinics for proactive management programs can drive initial adoption.
For Investors and Strategic Acquirers: Long-term, this sits as a defensive growth play because of the chronic nature of kidney disease and expanding aging demographics globally. Acquisition targets should prioritize biotech firms developing late-stage non-binder modalities or digital health platforms improving patient adherence. A critical signal to watch is evolving reimbursement policies for novel therapies, particularly in major markets like Germany and the US, indicating broader market acceptance and profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Validating long-term cardiovascular outcomes strengthens market position for novel binders. |
| Regulatory Approval Pathway | Securing expedited FDA or EMA review accelerates market access for innovative treatments. |
| Pipeline Diversification | Investing in non-binder modalities reduces dependency on traditional phosphate binders. |
| Digital Health Integration | Mobile applications for adherence improve patient outcomes and provide a service differentiator. |
| Manufacturing Scale-Up | Efficient production of novel iron-based binders lowers costs and expands global availability. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and robust secondary research. Primary insights came from discussions with nephrology specialists, pharmaceutical R&D executives, and hospital procurement managers. Secondary validation utilized FDA filings, EMA submissions, ClinicalTrials.gov, and national health statistics across key geographies. This approach ensured comprehensive bottom-up market sizing and top-down validation through triangulation.
The forecast horizon spans across the analysis window, employing a sophisticated analytical framework. Segmentation dimensions modeled include product type, therapy area, end user, delivery mode, and patient demographics. Compound Annual Growth Rates were derived from historical growth patterns and projected adoption rates for novel therapies. Key forecast inputs included evolving CKD prevalence rates and the growth of the global dialysis patient population.
Underlying assumptions cover regulatory stability and clinical trial success rates for pipeline products, with deviation risk concentrated in unforeseen shifts in reimbursement policies. Forecasts inherently reflect these assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Middle Ear Infection Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Lysosomal Storage Disease Treatment Market
Medical Treatment
Dementia Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Radiation Proctitis Treatment Market