
 Anti-Rickettsial Treatment Market | 2026-2036
Anti-Rickettsial Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Rickettsial Treatment Market Outlook
Market Context
Indian generic API production is broadening the supply base for tetracycline-class anti-rickettsial compounds. Pfizer Inc. leverages its parenteral formulation expertise to serve hospital networks in endemic zones. Sanofi anchors European distribution through its established infectious disease franchise. Cipla Inc. competes on cost-optimized oral doxycycline output for outpatient programs across South Asia and sub-Saharan Africa.
Technical Definition and Segment Structure
Anti-rickettsial treatments comprise antibiotic therapies targeting obligate intracellular bacteria of the genus Rickettsia, with doxycycline serving as the first-line agent due to its lipophilic tissue penetration and bacteriostatic protein synthesis inhibition. The primary commercial purpose is curative intervention in vector-borne spotted fever and typhus group infections, where delayed diagnosis elevates mortality risk. Oral delivery mode dominates volume due to outpatient suitability, while intravenous formulations capture concentrated margin pools in severe hospitalized cases of Rocky Mountain Spotted Fever. Doxycycline product type leads absolute prescription volume, though azithromycin gains traction in pediatric populations where tetracycline staining contraindications apply.
Regulatory Framework and Outlook
FDA orphan drug incentives, EMA tropical disease priority review vouchers, and WHO prequalification standards collectively shape manufacturer R&D allocation and market access timelines for novel anti-rickettsial candidates. India's CDSCO accelerates local approval for scrub typhus indications, narrowing the gap between endemic disease burden and therapeutic availability. Stakeholders must monitor vector range expansion driven by climate variables and align portfolio development with shifting geographic disease burden rather than historical prescription patterns.
Market Dynamics
Hospital procurement of intravenous doxycycline is accelerating across Southeast Asia, compressing lead times and forcing manufacturers to regionalize parenteral formulation capacity near endemic disease clusters.
Growth Catalysts
- FDA orphan drug designation:The pathway for tropical disease therapies is reshaping manufacturer incentives toward Rickettsia-targeting candidates previously deprioritized due to limited commercial returns.
- Scrub typhus incidence in India:Vector-borne disease burden is driving bulk antibiotic purchasing through public health procurement channels.
- WHO prequalification standards:Harmonized quality benchmarks are enabling Indian generic API producers to supply multinational hospital networks without redundant national filings.
Market Restraints
- Tetracycline API concentration:Active pharmaceutical ingredient production clusters in select Indian manufacturing zones, creating single-source vulnerability for doxycycline supply.
- Pediatric contraindications:Tooth enamel staining risk limits tetracycline-class deployment in children under eight years, forcing reliance on azithromycin with inferior Rickettsia clearance rates.
- CDSCO approval timelines:India's national pharmaceutical regulator maintains extended review periods for novel anti-rickettsial indications, delaying market entry for reformulated candidates.
Strategic Opportunities
- EMA tropical disease priority review vouchers:European regulatory incentives reward developers of neglected disease therapies with transferable accelerated assessment rights.
- Sub-Saharan Africa outpatient programs:Community-based oral doxycycline distribution networks remain underdeveloped relative to malaria treatment infrastructure.
- Climate-driven vector expansion:Spotted fever group range extension into temperate zones is creating first-mover advantage for manufacturers with established cold-chain distribution.
Industry Challenges
- Microbiologist workforce scarcity:Diagnostic capacity for intracellular bacterial identification lags behind clinical suspicion, delaying appropriate anti-rickettsial initiation.
- Legacy cold-chain infrastructure:Parenteral formulation stability requirements strain hospital pharmacy storage capabilities in tropical endemic regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Rickettsial Treatment Market |
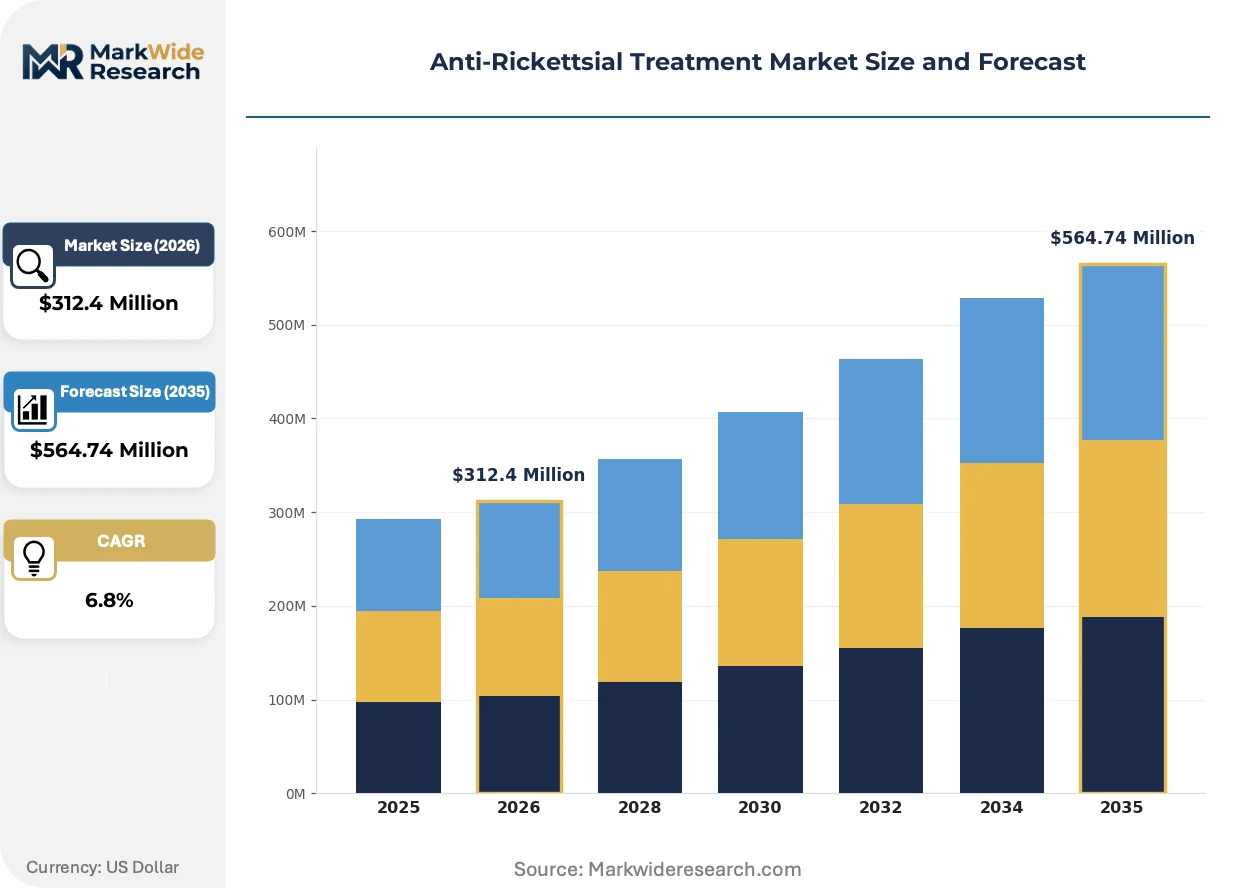
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Doxycycline, Chloramphenicol, Rifampin, Azithromycin Delivery Mode: Oral, Parenteral, Topical, Intravenous End User: Hospitals, Clinics, Outpatient Facilities, Pharmaceutical Companies Indication: Typhus, Rocky Mountain Spotted Fever, Scrub Typhus, Others |
| Companies Covered | GlaxoSmithKline plc, Novartis AG, Pfizer Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Sanofi, Cipla Inc., Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Rickettsial Treatment Market Strategic Shifts
Diagnostic delay remains the dominant friction point in anti-rickettsial therapy, with innovation converging on point-of-care molecular platforms and stabilized oral formulations that extend reach beyond hospital settings.
Liposomal doxycycline encapsulation is modularizing drug delivery architecture for severe hospitalized infections. Academic medical centers in endemic zones are piloting these formulations to reduce infusion frequency and nursing burden. The technology is compressing length-of-stay economics for Rocky Mountain Spotted Fever management.
EMA tropical disease priority review vouchers are redirecting European R&D portfolios toward Rickettsia-targeting candidates. Manufacturers holding these transferable rights are partnering with Indian API producers to split development costs. Severe hospitalized cases capture concentrated margin pools under this accelerated pathway.
Centralized hospital procurement in Thailand and Vietnam is displacing fragmented pharmacy purchasing. Ministry of Health tender consolidation is favoring suppliers with regional manufacturing presence over distant exporters. This concentration is visible in intravenous formulation contracts awarded to Southeast Asian packaging facilities.
Anti-Rickettsial Treatment Market Segmentation
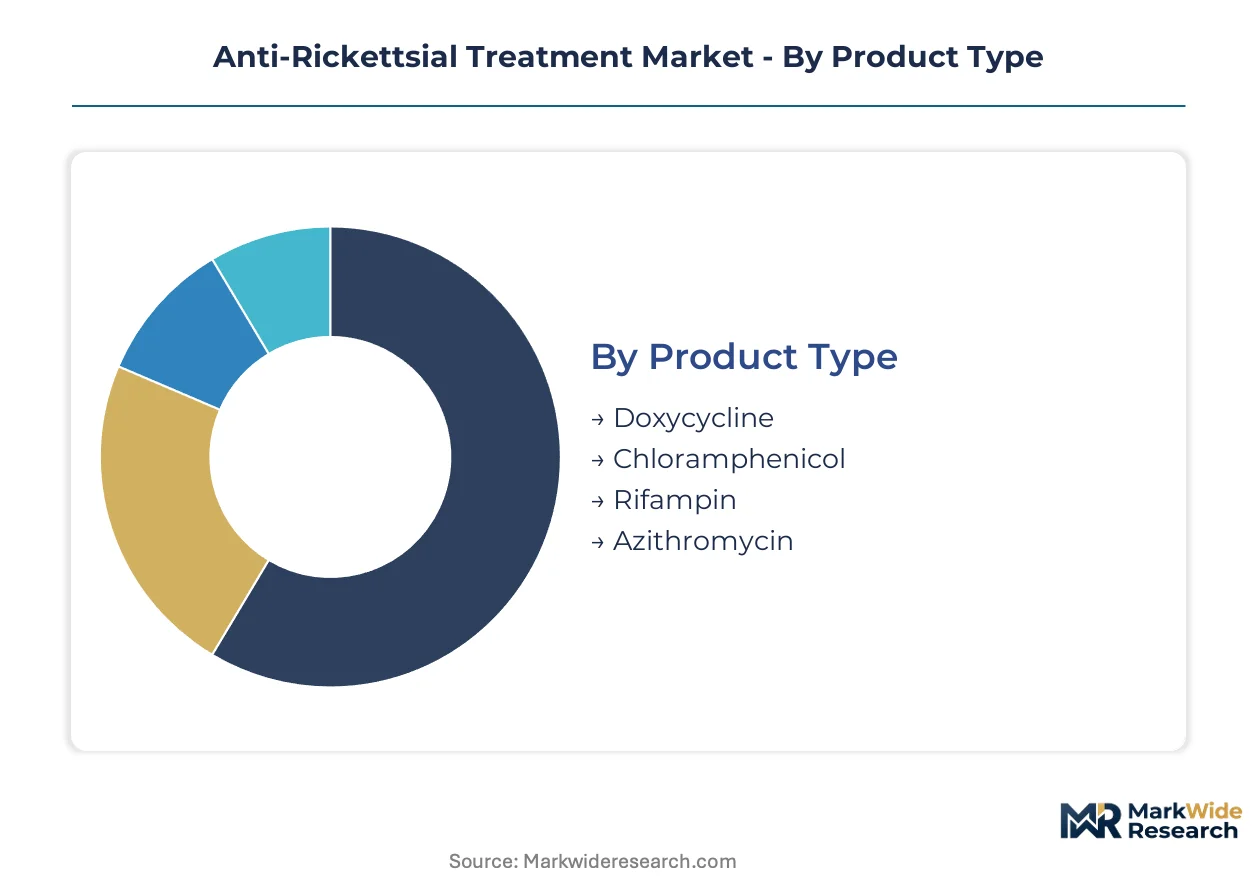
Segmentation in anti-rickettsial therapies reveals divergent margin structures between mass-market oral generics and concentrated-hospital parenteral formulations. Disease-specific procurement patterns and vector geography reshape which delivery modes and product types capture procurement volume.
Product Type:
Volume leadership sits with tetracycline-class agents, while macrolide alternatives carve premium niches in restricted populations.
- Doxycycline:Lipophilic tissue penetration and bacteriostatic protein synthesis inhibition make this the first-line standard across spotted fever and typhus group infections. Indian generic API producers supply bulk purchasing through public health channels in scrub typhus-endemic states.
- Azithromycin:Macrolide mechanism with superior pediatric safety profile where tetracycline enamel staining contraindications apply. Demand concentrates in outpatient pediatric programs across South Asia where diagnostic delay forces empiric coverage.
- Chloramphenicol:Bacteriostatic agent with bone marrow toxicity profile limiting deployment to severe hospitalized cases with documented resistance.
- Rifampin:RNA polymerase inhibitor reserved for combination salvage therapy in treatment failures and documented refractory infections.
Today's leader: Doxycycline. Tomorrow's challenger: Azithromycin.
Delivery Mode:
Hospital procurement economics favor parenteral stability, while community-based programs drive oral formulation scale.
- Oral:Doxycycline tablets and capsules dominate outpatient prescription volume through community distribution networks. Cipla Inc. cost-optimized production serves sub-Saharan Africa programs where cold-chain infrastructure remains underdeveloped.
- Intravenous:Severe Rocky Mountain Spotted Fever cases require continuous infusion capability with liposomal encapsulation pilots reducing nursing burden. Southeast Asian hospital procurement is accelerating regional parenteral formulation capacity.
- Parenteral:Intramuscular depot formulations extend reach into peripheral clinic settings with intermittent dosing schedules.
- Topical:Limited deployment in localized cutaneous manifestations with minimal systemic absorption requirements.
Oral formulations own outpatient volume. Intravenous captures inpatient margin concentration.
End User:
Procurement authority separates bulk public tenders from fragmented retail pharmacy purchasing.
- Hospitals:Centralized Ministry of Health tender consolidation in Thailand and Vietnam favors regional manufacturing presence. Intravenous contracts concentrate in facilities with cold-chain pharmacy storage.
- Clinics:Peripheral diagnostic capacity constraints delay appropriate anti-rickettsial initiation, forcing empiric oral doxycycline deployment.
- Outpatient Facilities:Community-based distribution networks remain underdeveloped relative to malaria infrastructure across sub-Saharan Africa.
- Pharmaceutical Companies:API sourcing and formulation development partnerships split costs under EMA tropical disease priority review voucher incentives.
Hospitals anchor procurement concentration. Outpatient facilities represent the largest untapped expansion frontier.
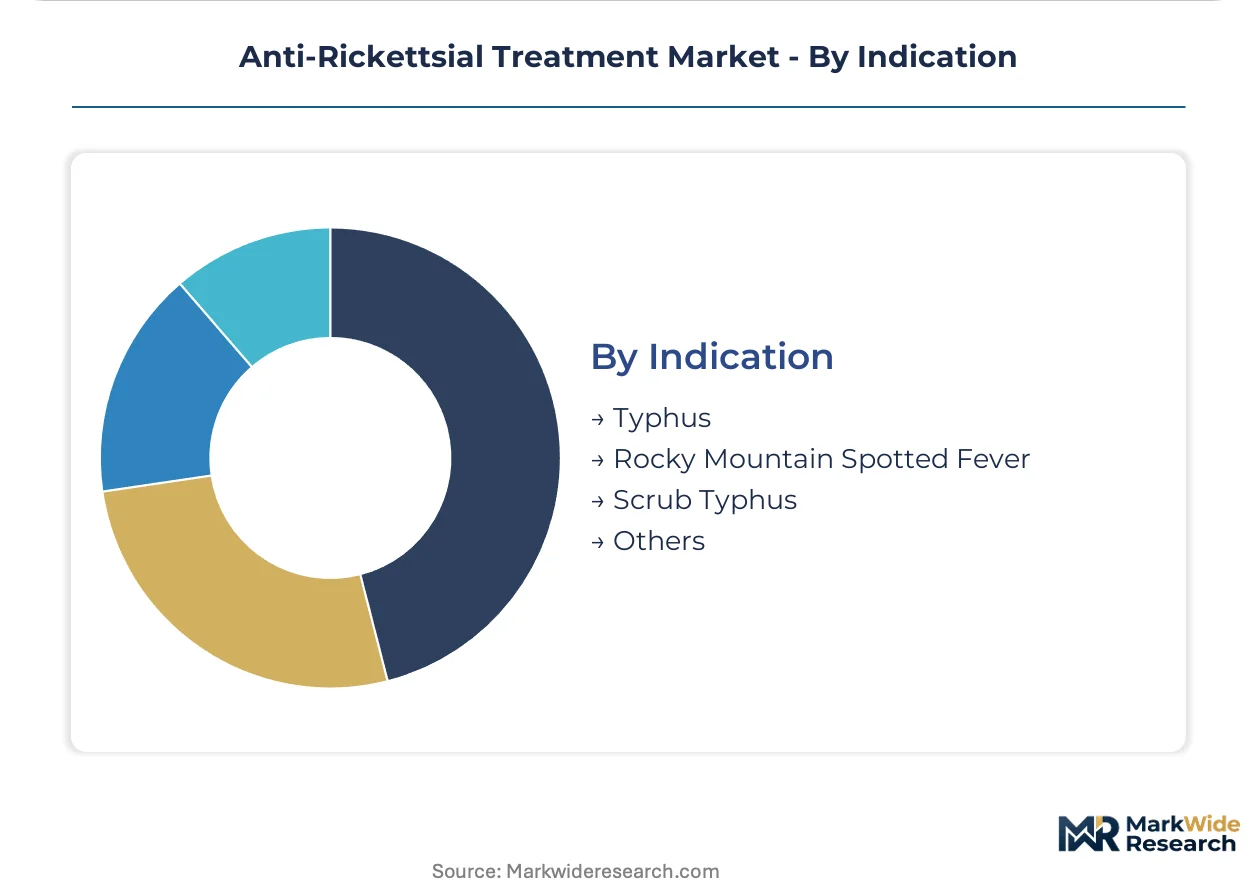
Indication:
Vector geography determines which Rickettsia species drive formulation demand and procurement timing.
- Scrub Typhus:Orientia tsutsugamushi transmission across India, Thailand, and Vietnam drives bulk antibiotic purchasing through national disease control programs. CDSCO accelerated local approval narrows availability gaps.
- Rocky Mountain Spotted Fever:Rickettsia rickettsii mortality risk from diagnostic delay elevates intravenous doxycycline priority in US and Mexican hospital formularies. Liposomal encapsulation pilots target length-of-stay reduction.
- Typhus:Louse-borne Rickettsia prowazekii and flea-borne Rickettsia typhi outbreaks trigger emergency procurement protocols in humanitarian settings.
- Others:Emerging spotted fever group species with climate-driven range extension into temperate zones create first-mover positioning for established cold-chain distributors.
Scrub typhus commands current procurement volume. Climate-driven spotted fever expansion is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting formulation capacity toward jurisdictions with streamlined tropical disease approval pathways. Indian API producers exploit cost-of-compliance gaps against Western regulatory burdens. Southeast Asian governments consolidate hospital procurement to compress supplier margins.
United States
Rocky Mountain Spotted Fever mortality drives intravenous doxycycline prioritization in hospital formularies. FDA orphan drug designation accelerates review timelines for Rickettsia-targeting candidates. Academic medical centers in the Southwest and Southeast pilot liposomal encapsulation to reduce length-of-stay economics.
India
Scrub typhus incidence across Odisha, Himachal Pradesh, and Tamil Nadu powers bulk antibiotic purchasing through national disease control programs. CDSCO accelerates local approval for endemic indications, narrowing availability gaps between disease burden and therapeutic access. Hyderabad and Mumbai anchor generic API production clusters supplying domestic and export markets.
Thailand
Ministry of Health tender consolidation displaces fragmented pharmacy purchasing for intravenous formulations. WHO prequalification standards enable direct supply to multinational hospital networks without redundant national filings. Bangkok-based packaging facilities capture regional parenteral formulation contracts.
Vietnam
Centralized procurement protocols favor suppliers with regional manufacturing presence over distant exporters. The national pharmaceutical regulator maintains quality benchmarks aligned with WHO prequalification. Ho Chi Minh City clusters formulation capacity serving Mekong Delta endemic zones.
Germany
EMA tropical disease priority review vouchers redirect European R&D portfolios toward neglected disease candidates. REACH compliance requirements shape API sourcing decisions for manufacturers serving EU markets. Baden-Württemberg and Bavaria house infectious disease franchise operations anchoring continental distribution.
Anti-Rickettsial Treatment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue pediatric-safe macrolide alternatives and liposomal delivery platforms. The market structure fragments across multinational pharmaceutical conglomerates with parenteral expertise, Indian generic API specialists, and regional formulation packagers. Three archetypes dominate: vertically integrated innovators with regulatory incentive access, cost-optimized bulk manufacturers, and geography-anchored hospital suppliers. Competitive moves concentrate on EMA priority review voucher partnerships and Southeast Asian regional manufacturing expansion.
Within the multinational tier, Pfizer Inc. and Sanofi occupy positions defined by parenteral formulation heritage and infectious disease franchise infrastructure. Cipla Inc. exemplifies the Indian generic archetype, anchoring cost-optimized oral production for outpatient programs. These three entities represent distinct strategic postures: regulatory incentive leverage, established hospital network access, and volume-driven emerging market penetration.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Novartis AG |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Sanofi |
| Cipla Inc. |
| Johnson & Johnson Services, Inc. |
| Others |
Value Chain & Pricing Dynamics
Centralized Ministry of Health tenders in Thailand and Vietnam are compressing supplier margins and forcing manufacturers to regionalize parenteral formulation capacity near endemic disease clusters, which in turn stratifies pricing across hospital procurement tiers.
Pricing Analysis
Hospital distributor margins absorb the primary cost compression from tender consolidation, while retail pharmacy markups remain fragmented across South Asian outpatient channels. Three-tier pricing structure across liposomal intravenous, standard parenteral, and oral generic levels separates premium-tier formulation stability from economy tablet production. Pricing pressure stems from Indian generic API oversupply in tetracycline-class compounds. Public health procurement managers exhibit highest price sensitivity; academic medical centers in severe-case management demonstrate lowest.
Supply Chain Analysis
API production for tetracycline-class compounds rests on specialty chemical manufacturing zones in India, with secondary fermentation capacity in China and tertiary synthetic chemistry in the United States. Doxycycline active pharmaceutical ingredient, liposomal encapsulation phospholipids, and parenteral formulation excipients constitute the critical input trinity. Single-source vulnerability concentrates in Hyderabad and Mumbai manufacturing clusters where environmental regulatory enforcement disruptions can cascade. Distribution runs through hospital procurement consortia in Southeast Asia and fragmented retail pharmacy networks across sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through liposomal formulation premiumization and cost-optimized oral generic scale, with API backward integration in India as the primary cost-down driver.
For Market Incumbents: Deploy liposomal encapsulation technology licensing to academic medical centers piloting length-of-stay reduction programs. Consolidate parenteral formulation capacity in Bangkok and Ho Chi Minh City packaging facilities to defend against regional tender consolidation. Threat: Indian generic API producers expanding into finished formulation exports. Lever: Captive supply of tetracycline fermentation capacity in Hyderabad. For New Entrants and Emerging Players: The premium-economy price gap in pediatric-safe macrolide alternatives opens white-space targeting in South Asian outpatient programs. Penetrable segment: Community-based oral distribution networks in sub-Saharan Africa where malaria infrastructure exceeds rickettsial coverage. Go-to-market angle: WHO prequalification partnership with Indian API producers to bypass redundant national filings. For Investors and Strategic Acquirers: Asymmetric upside sits with regional formulation packagers holding EMA tropical disease priority review voucher partnerships. Long-term viability frames around climate-driven vector range expansion into temperate zones over a multi-year horizon. Acquisition target archetype: Southeast Asian parenteral packaging facilities with Ministry of Health contract relationships. Signal to watch: CDSCO approval timeline compression for novel anti-rickettsial indications.| Strategic Initiative | Industry Significance |
|---|---|
| Liposomal Formulation Licensing | Academic medical centers in endemic zones pilot infusion-frequency reduction for Rocky Mountain Spotted Fever management. |
| Regional Manufacturing Scale-Up | Bangkok-based packaging facilities capture intravenous contracts from centralized Thai Ministry of Health tenders. |
| EMA Priority Review Voucher Partnership | European regulatory incentives split development costs between manufacturers and Indian API producers. |
| WHO Prequalification Pathway | Harmonized quality benchmarks enable direct supply to multinational hospital networks without redundant filings. |
| API Backward Integration | Captive tetracycline fermentation capacity in Hyderabad insulates against single-source supply disruptions. |
Study Parameters
Multiple input streams — formulary director interviews, hospital procurement manager surveys, and regulatory filing analysis — were reconciled against secondary validation from FDA orphan drug designation records, EMA tropical disease priority review voucher databases, CDSCO accelerated approval filings, and WHO prequalification lists. Drug development executives, infectious disease franchise leads, GPO contracts managers, and national disease control program officers provided primary perspective. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated for convergence.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user procurement authority, and indication-specific vector geography. CAGRs were derived from epidemiological trend extrapolation, regulatory incentive impact assessment, and procurement pattern trajectory analysis. Forecast inputs incorporated climate-driven vector range expansion scenarios and CDSCO approval timeline elasticity.
Caveats apply where diagnostic capacity expansion, environmental regulatory enforcement in Indian manufacturing zones, or pediatric formulation safety profile revisions could materially shift the outlook. Forecasts reflect assumptions about tender consolidation velocity and liposomal encapsulation adoption curves. A small set of named triggers — vector range monitoring data, CDSCO staffing levels, and EMA voucher transfer pricing — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Persistent Epithelial Defect Management Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Global Leukapheresis Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Europe Platelet Rich Plasma (PRP) Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Morquio Syndrome Treatment Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Behcet's Disease Treatment Market
Medical Treatment
Liver Transplantation Market
Medical Treatment
Global Radiodermatitis Treatment Market
Medical Treatment
Allergic Rhinitis Treatment Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market