
 Hypothermia Management Market | 2026-2036
Hypothermia Management Market Size, Share, and Industry Trends Forecast 2026-2036
Hypothermia Management Market Analysis
A shortage of perfusionists trained in intraoperative temperature management is redrawing competitive boundaries across the hypothermia management landscape. Stryker Corporation leverages its integrated surgical equipment ecosystem to bundle warming systems with operating room infrastructure. Gentherm anchors its position through proprietary conductive fabric technologies that differentiate its thermal blanket portfolio from conventional forced-air alternatives.
Hypothermia management encompasses the clinical practice of deliberately lowering, maintaining, or raising core body temperature using surface, intravascular, or extracorporeal devices, typically targeting temperature ranges between 32°C and 37°C with precision tolerances of ±0.5°C to protect neural and cardiac tissue during critical care interventions. Active warming systems dominate hospital procurement budgets due to their ability to achieve controlled rewarming rates of 0.25°C to 0.5°C per hour in post-surgical recovery, while portable heaters represent the fastest-expanding product type as pre-hospital care protocols extend temperature management into ambulance and battlefield settings. Emergency rooms generate the largest end-user revenue pool, though military applications are deepening as armed forces integrate hypothermia prevention into prolonged field care doctrine.
The FDA regulates patient warming devices as Class II medical devices requiring 510(k) premarket notification, while the EU Medical Device Regulation mandates clinical evaluation reports for active warming systems sold under CE marking. ISO 80601-2-35 establishes particular requirements for the safety and essential performance of warming devices, creating compliance thresholds that filter marginal competitors from premium hospital contracts. Stakeholders must monitor how evolving reimbursement policies for targeted temperature management after cardiac arrest reshape capital equipment purchasing cycles versus disposable consumable models.
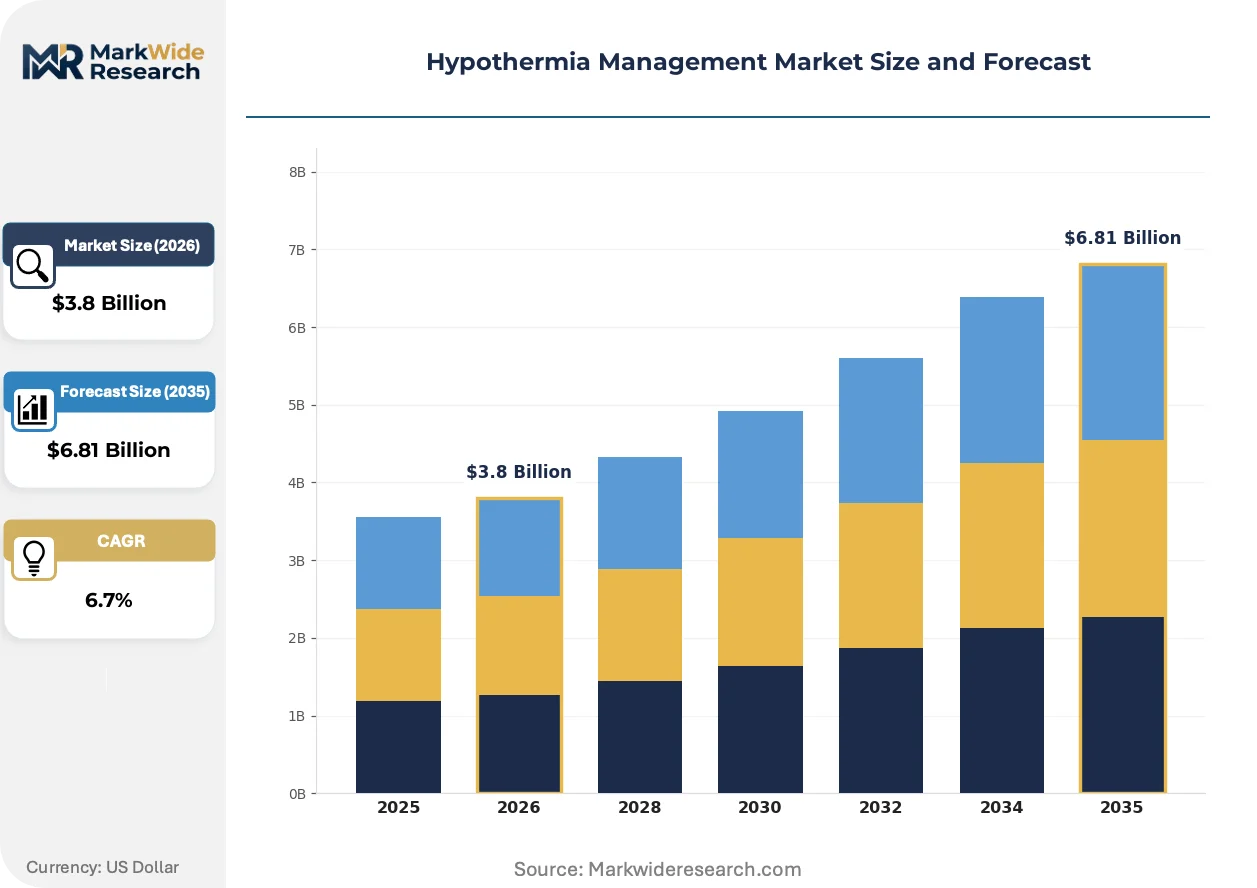
Market Dynamics
The hypothermia management market is experiencing structural pressure from the FDA's tightened 510(k) validation requirements for patient warming devices, which is compressing the competitive field and elevating compliance costs for marginal manufacturers seeking hospital procurement contracts.
Growth Catalysts
- Trauma Center Accreditation Mandates:United States trauma centers now require active warming capabilities under accreditation standards, creating institutional demand pull for surface and intravascular systems.
- ISO 80601-2-35 Compliance Thresholds:Safety and essential performance standards for warming devices filter out low-quality competitors, concentrating hospital contracts among validated suppliers.
- Conductive Fabric Technologies:Advanced materials enable precise temperature control tolerances of ±0.5°C, expanding applications in cardiac surgery and neural protection protocols.
Market Restraints
- Perfusionist Talent Scarcity:Shortage of specialists trained in intraoperative temperature management limits deployment of complex intravascular systems in tertiary hospitals.
- Copper and Silver Price Volatility:Conductive materials in thermal blanket manufacturing face input cost swings that compress margin structures for mid-tier suppliers.
- EU MDR Clinical Evaluation Burden:CE marking requirements for active warming systems impose documentation and testing costs that disadvantage smaller European manufacturers.
Strategic Opportunities
- Military Prolonged Field Care Doctrine:Armed forces integration of hypothermia prevention into battlefield medicine creates demand for portable heaters and ruggedized warming systems.
- Pre-Hospital Ambulance Protocols:Emergency medical services expansion of temperature management into transport settings opens channel opportunities for battery-powered devices.
- Targeted Temperature Management Reimbursement:Evolving post-cardiac arrest coverage policies reshape purchasing cycles toward disposable consumable models over capital equipment.
Industry Challenges
- Integration Complexity with Surgical Workflows:Temperature management systems must interface with existing operating room infrastructure, requiring customized installation and staff retraining.
- 510(k) Timeline Compression:FDA premarket notification processes for Class II warming devices extend product launch windows, delaying revenue recognition for development-stage manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypothermia Management Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Pads, Thermal Blankets, Warmers, Portable Heaters End User: Emergency Rooms, Sports Teams, Outdoor Events, Military Technology: Active Warming Systems, Passive Warming Systems, Chemical Heat, Electrical Heat Application: Pre-Hospital Care, Surgical Settings, Rehabilitation, Research |
| Companies Covered | ZOLL Medical Corporation, Becton, Dickinson and Company, Stryker Corporation, Belmont Medical Technologies, BrainCool AB, Gentherm, 3M Company, Geratherm Medical AG, Smiths Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypothermia Management Market Emerging Trajectories
Device miniaturization and regulatory harmonization are converging to reshape competitive boundaries, while procurement patterns in emergency medicine accelerate adoption of portable systems outside traditional hospital settings.
Intravascular temperature management catheters are miniaturizing from 9 French to 5 French profiles, enabling femoral and jugular placement in smaller patients and reducing vascular access complications. Pediatric cardiac surgery departments at Boston Children's Hospital and Great Ormond Street Hospital are piloting these reduced-diameter systems for congenital heart procedures. This miniaturization is compressing the addressable market for surface-based alternatives in high-acuity surgical settings.
The EU Medical Device Regulation's post-market surveillance requirements for active warming systems mandate systematic clinical follow-up data collection, elevating documentation burdens for manufacturers. German hospital procurement consortiums now require MDR-compliant technical files as pre-qualification criteria for warming device tenders. French and Italian cardiac surgery centers are consolidating supplier relationships toward MDR-certified vendors, reducing fragmentation in premium contract segments.
Hospital purchasing committees are unbundling after-sales service from device capital costs, demanding transparent lifecycle pricing and third-party maintenance options. United States group purchasing organizations are driving this behavioral shift, pressuring Stryker and Gentherm to itemize training, calibration, and warranty terms separately. Emergency room administrators in Texas and California health systems are most vocal in demanding service unbundling, reflecting budget pressures in high-volume trauma settings.
Hypothermia Management Market Segmentation
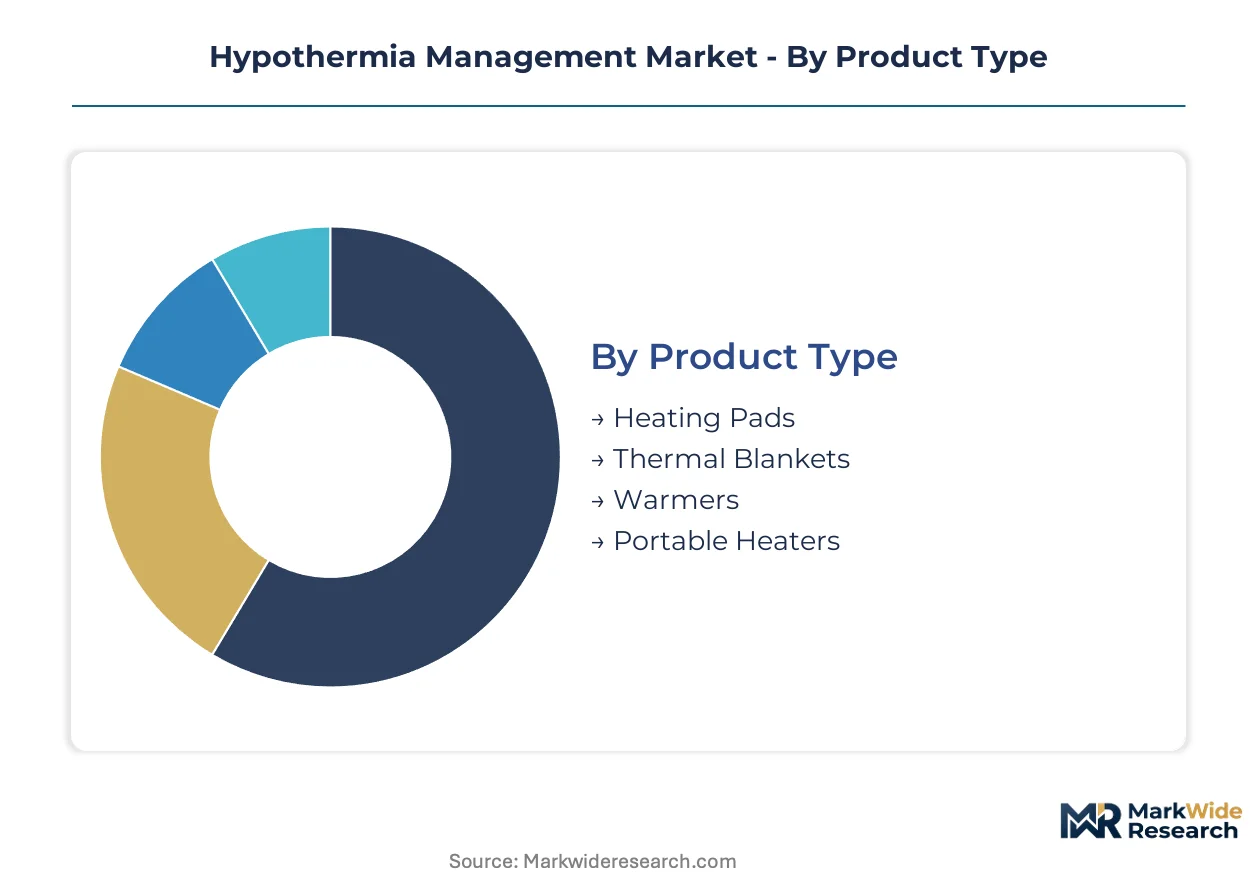
Hypothermia management devices serve distinct clinical and non-clinical environments where temperature control requirements vary by acuity, mobility, and duration of exposure. Understanding how product specifications align with end-user operational constraints enables procurement decisions that balance precision, portability, and total cost of ownership.
Product Type:
Surface-based warming modalities face intensifying substitution pressure from intravascular alternatives in high-acuity surgical settings, though cost and deployment flexibility sustain demand for external systems across broader care environments.
- Thermal Blankets:Conductive fabric systems achieve ±0.5°C precision tolerances through embedded heating elements, concentrating demand in United States cardiac surgery departments where Gentherm's proprietary textiles anchor premium positioning. ISO 80601-2-35 compliance requirements filter hospital contracts toward validated suppliers with documented safety profiles.
- Portable Heaters:Battery-powered and fuel-cell variants extend temperature management into ambulance transport and battlefield medicine, gaining traction as pre-hospital protocols formalize active warming mandates. Military procurement through United States Department of Defense channels and European defense ministries drives ruggedization requirements.
- Heating Pads:Disposable and reusable surface units serve rehabilitation and outpatient settings where intermittent warming suffices.
- Warmers:Forced-air convection systems dominate post-surgical recovery wards with controlled rewarming rates of 0.25°C to 0.5°C per hour.
Thermal blankets retain volume leadership in institutional procurement; portable heaters hold the steepest expansion curve as military and emergency medical services deepen adoption.
End User:
Emergency medicine budgets concentrate capital allocation toward devices that integrate with trauma bay workflows, while military and sporting applications prioritize field durability over clinical precision.
- Emergency Rooms:United States trauma center accreditation standards mandate active warming capabilities, institutionalizing demand for surface and intravascular systems in high-volume acute care settings. Texas and California health systems drive procurement unbundling trends that separate device costs from service contracts.
- Military:Armed forces integration of hypothermia prevention into prolonged field care doctrine creates specifications for ruggedized, battery-independent warming systems. United States, United Kingdom, and German defense medical services are standardizing portable heater procurement across expeditionary medical kits.
- Sports Teams:Professional and collegiate athletic programs deploy sideline warming systems for cold-weather competition and post-exertion recovery.
- Outdoor Events:Mass gathering medical support contracts specify warming capabilities for spectator and participant hypothermia risk in endurance sports and alpine environments.
Emergency rooms dominate revenue concentration; military applications are expanding most quickly as doctrine formalization accelerates procurement cycles.
Technology:
Active warming systems command premium pricing tiers due to closed-loop temperature control, while passive and chemical alternatives compete on deployment speed and logistical simplicity in resource-constrained settings.
- Active Warming Systems:Closed-loop feedback mechanisms maintain target temperatures within ±0.5°C through conductive, convective, or intravascular heat exchange, requiring FDA 510(k) premarket notification as Class II medical devices. Hospital purchasing committees prioritize these systems for cardiac surgery and targeted temperature management protocols.
- Electrical Heat:Resistive and conductive elements embedded in blankets and pads deliver controlled surface warming with programmable temperature profiles, differentiating from chemical alternatives through reusability and precision.
- Passive Warming Systems:Insulating wraps and reflective blankets prevent heat loss without external energy input, serving as backup modalities in power-failure scenarios.
- Chemical Heat:Single-use exothermic packs activate on demand for immediate warming without electrical infrastructure, dominating military and wilderness medicine kits where weight and shelf life constrain logistics.
Active warming systems retain institutional procurement dominance; electrical heat technologies are gaining share fastest as conductive fabric innovations narrow the precision gap with intravascular alternatives.
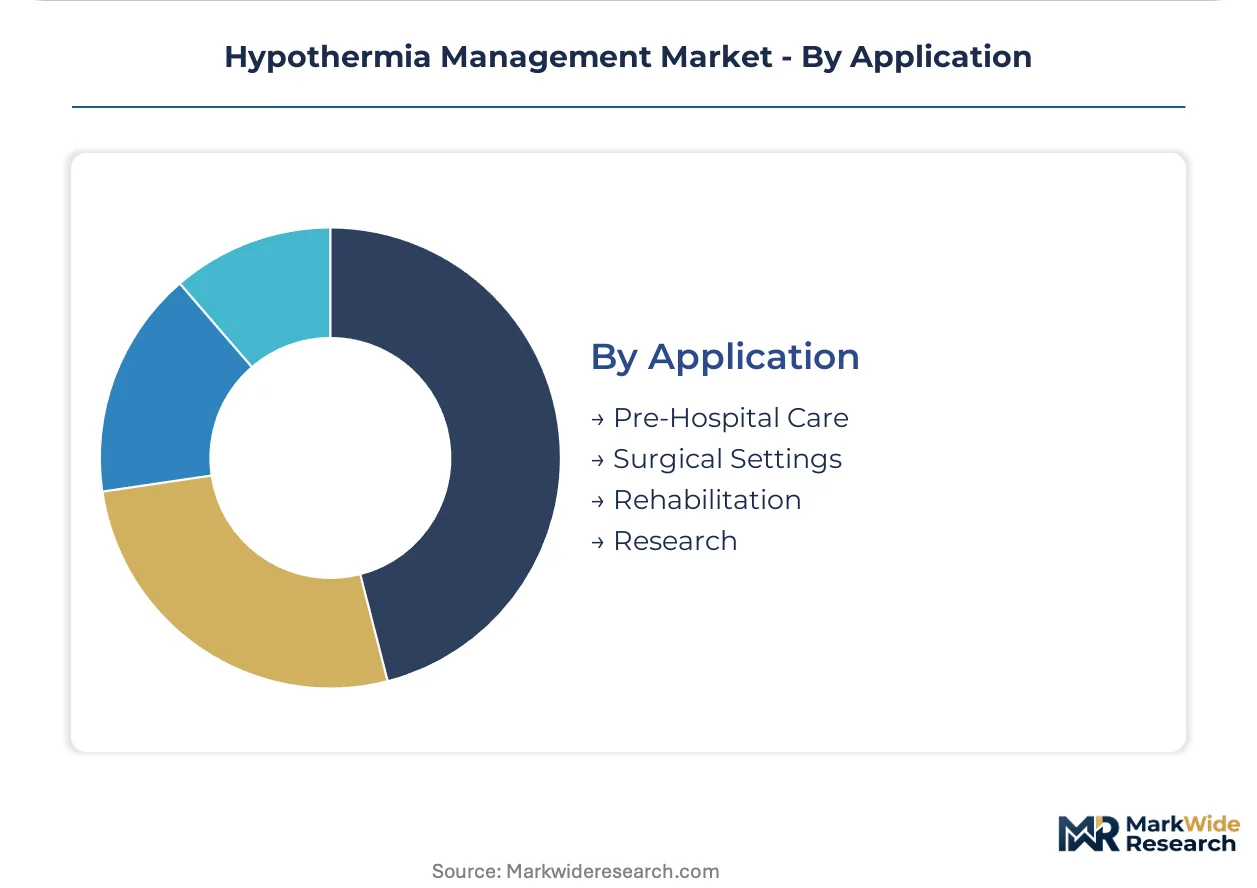
Application:
Surgical settings sustain the highest per-procedure device utilization rates, while pre-hospital and research applications fragment demand across specialized specifications with limited volume concentration.
- Surgical Settings:Operating rooms at tertiary hospitals deploy integrated temperature management protocols combining surface warming with intravascular catheters, with perfusionist staffing levels constraining system complexity. Boston Children's Hospital and Great Ormond Street Hospital pilot 5 French miniaturized catheters for pediatric cardiac procedures.
- Pre-Hospital Care:Ambulance services and battlefield medicine extend warming initiation into the golden hour post-injury, requiring battery-powered portability and rapid deployment. United States emergency medical services in Texas and California health systems are formalizing temperature management protocols for trauma transport.
- Rehabilitation:Post-acute care facilities utilize warming modalities for pain management and circulation support in orthopedic and neurological recovery protocols.
- Research:Academic medical centers and pharmaceutical investigators employ precision temperature control for therapeutic hypothermia studies and device validation trials.
Surgical settings anchor revenue concentration; pre-hospital care demonstrates the steepest expansion trajectory as emergency medical services protocols extend warming into transport environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States trauma centers consume intravascular systems at triple the rate of surface alternatives, while European hospitals favor conductive fabric blankets due to perfusionist staffing constraints. Military procurement in Israel and Germany drives portable heater specifications that diverge from civilian clinical standards.
United States
Texas and California health systems drive procurement unbundling trends that separate device capital costs from service contracts. The FDA's tightened 510(k) validation requirements for Class II warming devices compress the competitive field among hospital suppliers. Boston Children's Hospital pilots 5 French miniaturized catheters for pediatric cardiac procedures, compressing addressable demand for surface-based alternatives.
Germany
Hospital procurement consortiums now require EU MDR-compliant technical files as pre-qualification criteria for warming device tenders. The EU Medical Device Regulation's post-market surveillance mandates systematic clinical follow-up data collection for active warming systems. French and Italian cardiac surgery centers consolidate supplier relationships toward MDR-certified vendors, reducing fragmentation in premium contract segments.
United Kingdom
Great Ormond Street Hospital advances pediatric applications of reduced-diameter intravascular catheters for congenital heart procedures. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for warming device approvals. London tertiary hospitals expand temperature management protocols in cardiac surgery departments, institutionalizing demand for precision-controlled systems.
Israel
Defense medical services standardize portable heater procurement across expeditionary medical kits for prolonged field care doctrine. The Ministry of Health regulates patient warming devices under medical device registration requirements parallel to FDA Class II standards. Tel Aviv-area medical technology clusters develop ruggedized battery-independent warming systems for military and civilian emergency applications.
Japan
Academic medical centers in Tokyo and Osaka employ precision temperature control for therapeutic hypothermia studies and device validation trials. The Pharmaceuticals and Medical Devices Agency requires clinical evaluation reports for active warming systems under harmonized international standards. Kansai-region hospitals integrate surface warming with surgical workflows, driving demand for ISO 80601-2-35 compliant equipment.
Hypothermia Management Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the hypothermia management market. The upper tier commands premium hospital contracts through bundled surgical equipment ecosystems and proprietary conductive fabric technologies. Specialist competitors differentiate through miniaturized intravascular catheter innovations and military-grade portable heater specifications. Consolidation pressure intensifies as FDA 510(k) timelines extend and EU MDR documentation burdens filter marginal manufacturers from institutional procurement.
Within the integrated equipment tier, Stryker Corporation and Gentherm exemplify divergent strategic anchors. Stryker leverages its surgical infrastructure footprint to bundle warming systems with operating room capital purchases. Gentherm occupies a position defined by proprietary textile technologies that differentiate thermal blanket portfolios from conventional forced-air alternatives. Among specialists, ZOLL Medical Corporation represents the emergency medicine vector with pre-hospital and resuscitation-focused device positioning.
| Leading Market Players |
|---|
| ZOLL Medical Corporation |
| Becton, Dickinson and Company |
| Stryker Corporation |
| Belmont Medical Technologies |
| BrainCool AB |
| Gentherm |
| 3M Company |
| Geratherm Medical AG |
| Smiths Medical, Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between United States hospital group purchasing organizations and validated warming device manufacturers lock in supply access and price visibility across multi-year procurement cycles, insulating tier-one suppliers from spot-market volatility in conductive materials while compressing margins for mid-tier competitors lacking contractual scale.
Pricing Analysis
Project-based capital equipment contracts dominate institutional procurement, with pricing stratifying across FDA-validated premium tiers, ISO 80601-2-35 compliant standard tiers, and economy tiers serving outpatient rehabilitation. Cost compression in mid-tier thermal blankets intensifies as copper and silver price volatility feeds into manufacturing inputs. Emergency medical services demonstrate highest price sensitivity due to budget constraints in municipal procurement, while cardiac surgery departments at tertiary hospitals prioritize precision specifications over unit cost.
Supply Chain Analysis
China and South Korea anchor conductive fabric manufacturing for thermal blanket heating elements, while Germany and the United States concentrate precision catheter production for intravascular systems. Raw material dependencies center on copper wire, silver conductive threads, and medical-grade polymers. Single-source vulnerability in specialized textile weaving creates bottleneck exposure. Distribution runs through hospital procurement consortiums and defense medical supply chains, with emergency medical services increasingly sourcing through specialized medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hypothermia management market represents a high-growth disruption as FDA 510(k) validation tightening and EU MDR compliance burdens filter marginal competitors, creating consolidation opportunities for validated players with proprietary conductive technologies.
For Market Incumbents: Consolidate market position by deepening backward integration into conductive fabric production to offset copper and silver price volatility, while accelerating MDR certification investments to capture European hospital procurement consortium tenders before smaller competitors exhaust documentation resources. Lock in long-term offtake agreements with United States group purchasing organizations to defend installed base against emerging portable heater specialists. For New Entrants and Emerging Players: Anchor in military portable heater procurement as the most penetrable segment, where ruggedization specifications and battery-independent designs create white-space outside incumbent thermal blanket dominance. Target United States Department of Defense and European defense ministry channels with expeditionary medical kit integrations, leveraging pre-hospital protocol formalization in Texas and California emergency medical services as reference accounts for civilian market expansion. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with FDA-cleared intravascular catheter platforms and established CE marking pathways, positioned for acquisition by integrated surgical equipment leaders seeking temperature management capabilities. Long-term viability hinges on reimbursement policy evolution for targeted temperature management post-cardiac arrest, with the signal to watch being CMS coverage determinations that shift purchasing cycles toward disposable consumable models.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Clears Class II warming devices for United States hospital procurement, compressing competitive field to validated suppliers. |
| EU MDR Technical File Certification | Qualifies active warming systems for German hospital consortium tenders, filtering marginal manufacturers from premium contracts. |
| Hospital System Partnership | Stryker leverages integrated surgical ecosystems to bundle warming systems with operating room infrastructure purchases. |
| Reimbursement Strategy Development | Aligns device economics with evolving CMS coverage for targeted temperature management post-cardiac arrest protocols. |
| Software Companion Development | Enables closed-loop temperature control integration with electronic health record systems in tertiary cardiac surgery departments. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with perfusionists, hospital purchasing committee members, biomedical engineers, and group purchasing organization contract managers; and secondary validation through FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and ISO 80601-2-35 certification records. Bottom-up and top-down triangulation cross-checked unit demand assumptions against capital equipment spending patterns.
Across the analysis window, the forecasting framework modeled product type, end-user environment, technology platform, and application setting dimensions. CAGRs were derived from procedure volume growth in cardiac surgery and trauma center accreditation mandates, with inputs including perfusionist staffing ratios, military doctrine formalization timelines, and conductive materials cost indices.
Material uncertainties — regulatory timeline extensions, copper and silver price spikes, and reimbursement policy reversals — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding ISO compliance adoption curves and defense procurement cycles. Recalibration cycles align with material shifts in FDA guidance issuance and EU MDR implementation enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Birch Allergy Treatment Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Scalp Care Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Motion Sickness Treatment Market
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Menopause Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market