
 Merkel Cell Carcinoma (MCC) Treatment Market | 2026-2036
Merkel Cell Carcinoma (MCC) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Merkel Cell Carcinoma (MCC) Treatment Market Foresight
Oncology clinic procurement is narrowing around a handful of immuno-oncology suppliers with proven PD-1/L1 portfolios. Bristol-Myers Squibb leverages its established checkpoint inhibitor infrastructure to sustain formulary access across integrated delivery networks. Merck & Co. anchors the competitive set with pembrolizumab's entrenched position in MCC guidelines. Pfizer Inc. competes through co-development arrangements that extend its reach into combination regimens.
Merkel Cell Carcinoma treatment encompasses systemic and locoregional interventions directed at a rare neuroendocrine skin cancer characterized by Merkel cell polyomavirus association in approximately 80% of cases, with immunotherapy now representing the standard-of-care backbone based on durable response data. Chemotherapy retains utility in platinum-eligible patients with rapid disease progression, though its role contracts as immunotherapy penetration deepens. Radiation therapy occupies a defined adjuvant niche in localized disease, while targeted therapy remains investigational with limited approved agents. The delivery mode landscape tilts toward intravenous administration for biologics, with subcutaneous formulations emerging as a convenience differentiator in outpatient settings.
FDA oncology center review standards and EMA's Committee for Medicinal Products for Human Use (CHMP) benefit-risk frameworks govern market access for novel MCC therapeutics, with both agencies prioritizing overall survival endpoints in rare malignancies. The country's national pharmaceutical regulator in Japan, PMDA, applies orphan drug incentives that accelerate MCC indication reviews for sponsors with Japanese development programs. Stakeholders must monitor evolving biomarker definitions that could segment addressable populations and reshape trial enrollment criteria.
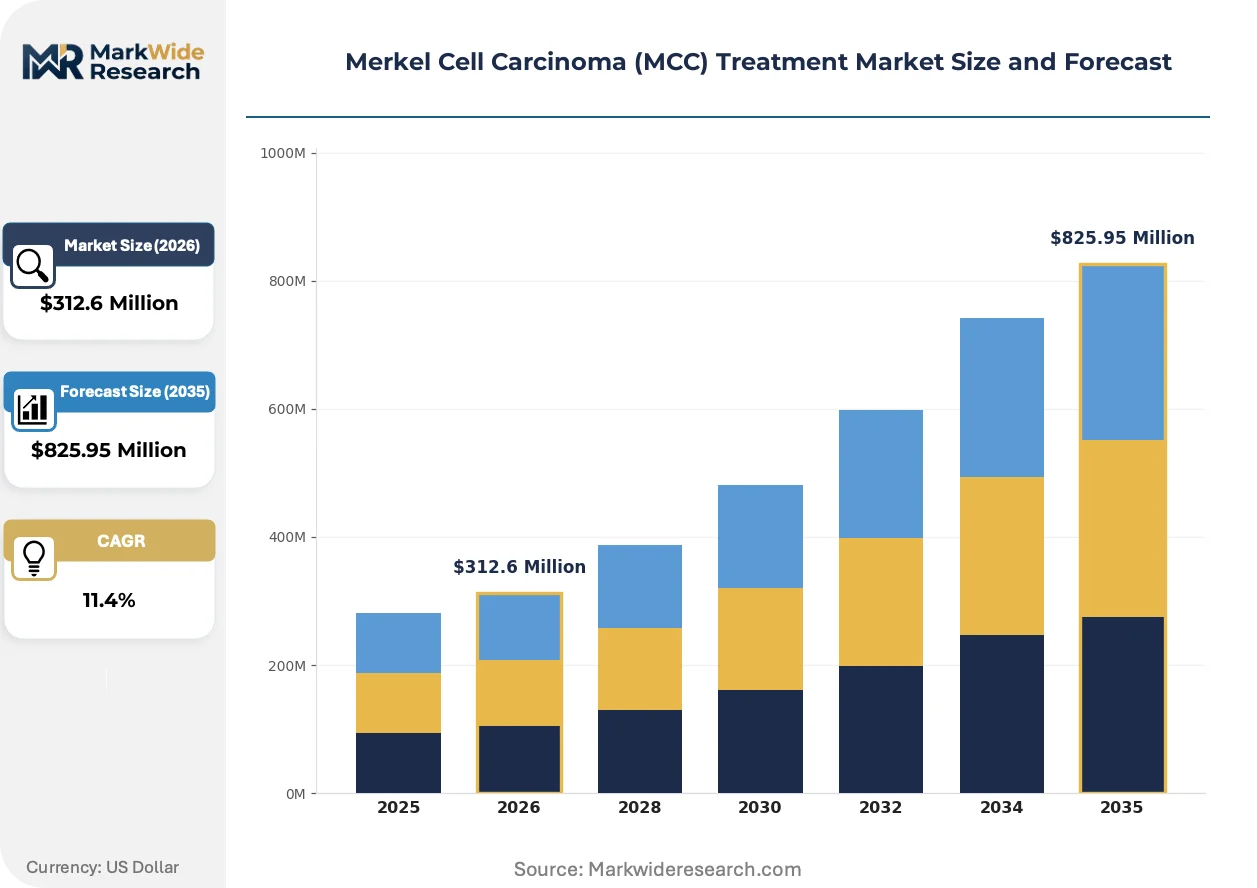
Market Dynamics
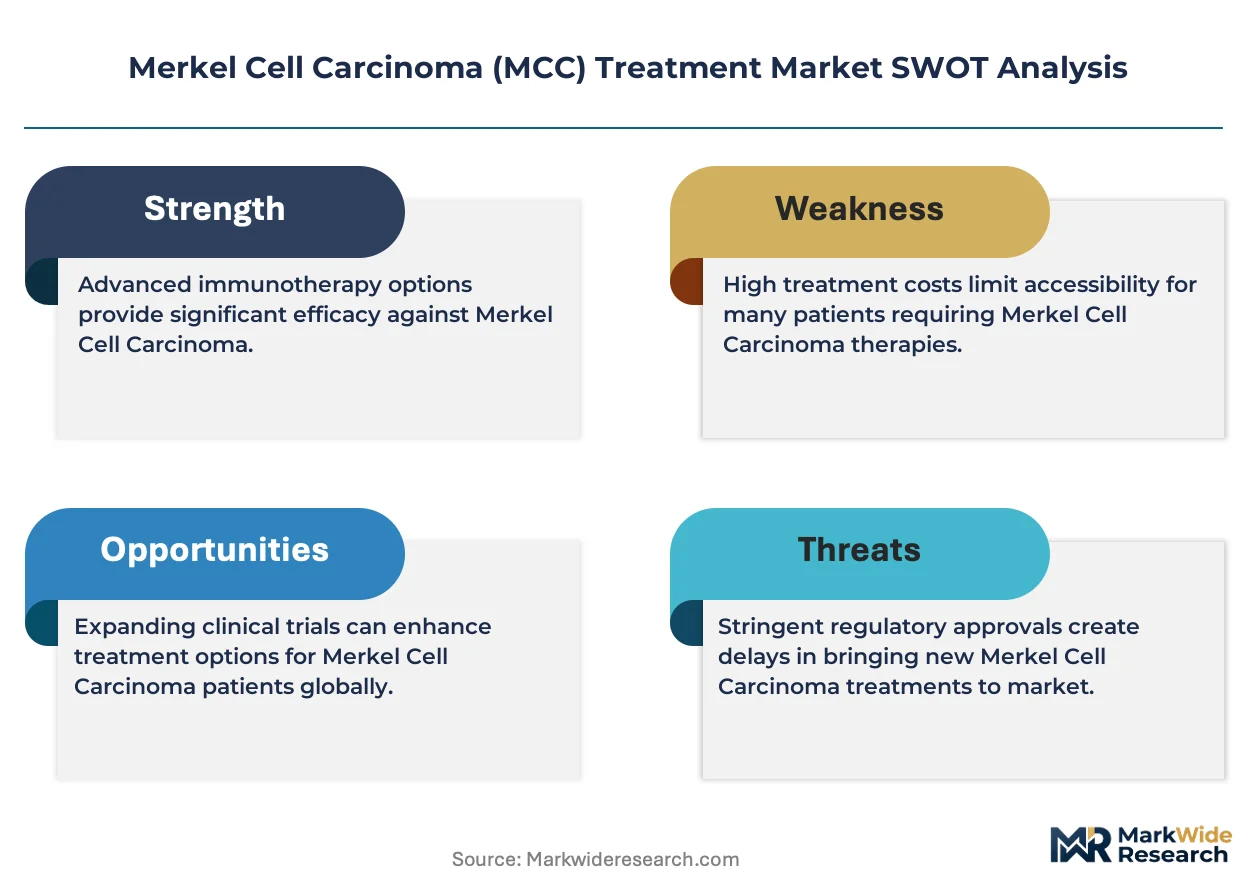
Checkpoint inhibitor dominance in first-line protocols is compressing chemotherapy's role and forcing oncology clinics to reconfigure infusion capacity around immuno-oncology administration workflows. This therapeutic shift concentrates procurement power among suppliers with established PD-1/L1 portfolios and validated cold-chain logistics.
Growth Catalysts
- FDA Accelerated Approval Pathway:The FDA oncology center's streamlined review for breakthrough therapies compresses development timelines for novel biologics targeting rare malignancies, enabling faster patient access.
- Reference Pricing Frameworks:Germany's centralized hospital procurement and oncology drug reference pricing creates predictable reimbursement pathways that incentivize manufacturer investment in MCC indications.
- Subcutaneous Formulation Development:Convenience-driven delivery innovation is expanding outpatient administration capacity and reducing infusion center burden across integrated delivery networks.
Market Restraints
- Platinum Eligibility Constraints:Chemotherapy retains utility only in rapid progressors, limiting addressable population for cytotoxic agents as immunotherapy penetration deepens.
- Cold-Chain Infrastructure Requirements:Biologic storage and handling specifications concentrate distribution capability among specialized logistics providers with validated temperature control systems.
- Biomarker Definition Uncertainty:Evolving Merkel cell polyomavirus status criteria and PD-L1 expression thresholds create enrollment friction in clinical trial design.
Strategic Opportunities
- Combination Regimen White Space:Co-development arrangements pairing checkpoint inhibitors with novel mechanisms offer differentiation in a landscape dominated by monotherapy standards.
- EMA Conditional Marketing Authorization:The European framework enables earlier commercial access based on surrogate endpoints, accelerating revenue generation prior to confirmatory data completion.
- Adjuvant Radiation Integration:Locoregional disease management protocols present opportunity for therapy sequencing optimization between systemic and radiation modalities.
Industry Challenges
- Immuno-oncology Nursing Specialization:Infusion center staffing requirements for immune-related adverse event management outpace training program expansion at community oncology sites.
- Trial Enrollment Competition:Rare disease prevalence limits patient availability across multiple simultaneous studies investigating overlapping mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Merkel Cell Carcinoma (MCC) Treatment Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $825.95 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Radiation Therapy, Targeted Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Oncology Clinics, Research Institutes, Homecare Settings Treatment Stage: Adjuvant, Neoadjuvant, Palliative, Metastatic |
| Companies Covered | Merck & Co., Bristol-Myers Squibb, Merck KGaA, Amgen Inc., Novartis AG, Pfizer Inc., Johnson & Johnson, Regeneron Pharmaceuticals, AstraZeneca PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Merkel Cell Carcinoma (MCC) Treatment Market Shifts & Advancements
Biomarker-driven patient segmentation is fragmenting historical treatment paradigms and creating new competitive battlegrounds around Merkel cell polyomavirus status and tumor mutational burden profiling.
Subcutaneous checkpoint inhibitor administration is collapsing the distinction between hospital-based infusion and community clinic delivery, enabling oncology practices to shift capacity toward higher-acuity services. Community sites across the United States are adopting these formulations to reduce chair time and expand patient throughput. The structural consequence compresses site-of-care economics and rewards networks with distributed administration infrastructure.
EMA's Committee for Medicinal Products for Human Use benefit-risk frameworks now prioritize overall survival endpoints in rare malignancy reviews, elevating the evidentiary bar for conditional approvals. This regulatory posture pressures sponsors to design larger confirmatory studies earlier in development. German reference pricing authorities are responding by tightening cost-effectiveness assessments for therapies with immature survival data.
Hospital procurement consolidation is concentrating formulary decision-making within integrated delivery networks that demand standardized protocols across multi-site systems. Oncology clinics are responding by centralizing pharmacy and therapeutics committees and adopting pathway-driven prescribing. This pattern is most pronounced in United States metropolitan markets where health system merger activity has accelerated.
Merkel Cell Carcinoma (MCC) Treatment Market Segmentation
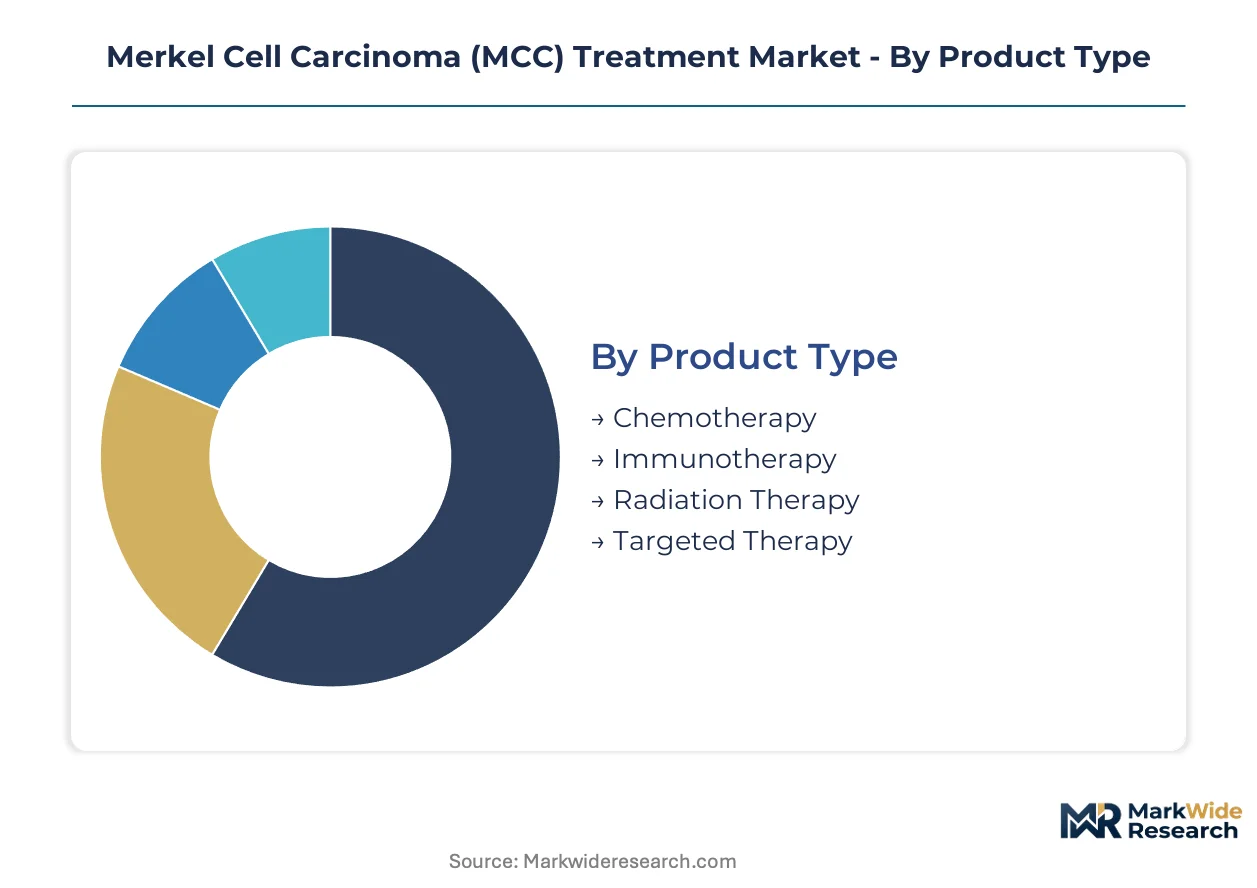
MCC treatment segmentation reveals divergent velocity across therapeutic modalities. Immunotherapy cycles refresh faster than radiation protocols, while delivery mode innovation compresses administration windows. Understanding these turnover differentials shapes capacity planning and inventory management for oncology providers.
Product Type:
Cycle times vary dramatically across modalities, with checkpoint inhibitor regimens turning over every 2-3 weeks versus multi-week radiation courses that lock patients into fixed schedules.
- Immunotherapy:PD-1 and PD-L1 inhibitors constitute the backbone of first-line systemic therapy, administered in repeating cycles that generate consistent infusion center throughput. Demand concentrates in United States oncology clinics expanding immuno-oncology capacity, driven by durable response data displacing chemotherapy in guidelines.
- Chemotherapy:Platinum-based regimens retain utility for rapid progressors and platinum-eligible patients, though their role contracts as immunotherapy penetration deepens. Demand concentrates in Germany's centralized hospital procurement systems, constrained by reference pricing pressures and shrinking addressable populations.
- Radiation Therapy:External beam and brachytherapy approaches occupy defined adjuvant niches in localized disease management.
- Targeted Therapy:Investigational agents with limited approved indications remain confined to clinical trial settings.
Immunotherapy dominates installed base. Chemotherapy is where expansion concentrates fastest.
Delivery Mode:
Cost tier stratification separates capital-intensive infusion infrastructure from self-administered oral regimens that shift economic burden to patient compliance.
- Intravenous:Hospital-based infusion requires specialized nursing staff and cold-chain logistics for biologic stability. Demand concentrates in United States integrated delivery networks centralizing pharmacy operations, driven by checkpoint inhibitor volume and immune-related adverse event management protocols.
- Subcutaneous:Emerging formulations collapse chair time and enable community clinic administration without full infusion infrastructure. Demand concentrates in outpatient settings across metropolitan United States markets, propelled by convenience differentiation and expanded patient throughput.
- Oral:Self-administered regimens reduce site-of-care costs but introduce adherence monitoring challenges.
- Topical:Limited applicability in systemic MCC management restricts use to investigational or palliative contexts.
Intravenous delivery commands current revenue. Subcutaneous administration is climbing the fastest.
End User:
Customer type segmentation maps to acuity gradients, with highest-margin complex cases concentrating in specialized centers while stable patients migrate downstream.
- Oncology Clinics:Dedicated cancer centers anchor immunotherapy administration, managing checkpoint inhibitor protocols and combination regimens. Demand concentrates in United States community oncology practices adopting subcutaneous formulations, driven by pathway-driven prescribing and centralized therapeutics committee decisions.
- Hospitals:Academic medical centers handle complex cases requiring multidisciplinary coordination and radiation integration. Demand concentrates in Germany's university hospital networks, shaped by centralized procurement and reference pricing frameworks.
- Research Institutes:Clinical trial sites compete for limited patient populations across overlapping mechanism studies.
- Homecare Settings:Subcutaneous self-administration and oral regimens expand reach beyond traditional infusion centers.
Oncology clinics capture the fastest volume expansion. Hospitals retain the highest-complexity case concentration.
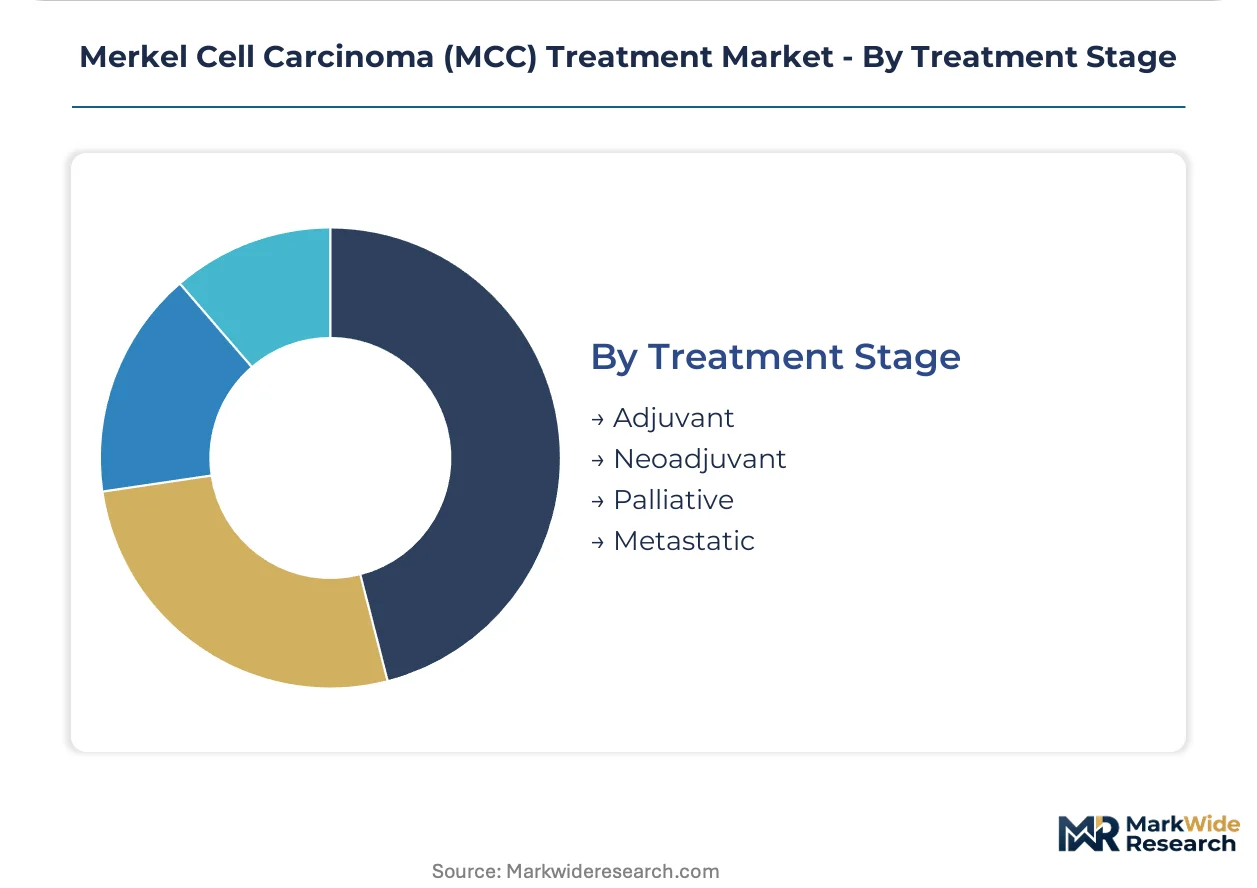
Treatment Stage:
Maturity gradients separate established adjuvant protocols from emerging neoadjuvant applications that reshape surgical timing and radiation sequencing.
- Metastatic:First-line systemic therapy for advanced disease represents the largest addressable population, with checkpoint inhibitors now standard. Demand concentrates in United States and German treatment centers, driven by FDA and EMA approval pathways compressing access timelines for novel biologics.
- Adjuvant:Post-surgical systemic and radiation therapy prevents recurrence in localized disease with high-risk features. Demand concentrates in integrated delivery networks standardizing protocols across multi-site systems, propelled by quality metrics and pathway compliance.
- Neoadjuvant:Pre-surgical systemic therapy remains investigational with limited established protocols.
- Palliative:Symptom-focused care integrates radiation and systemic options for end-stage disease management.
Metastatic treatment anchors current volume. Neoadjuvant protocols are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orphan drug incentives and accelerated approval pathways concentrate development investment in jurisdictions with streamlined regulatory frameworks. The United States, Germany, Japan, and the United Kingdom anchor commercial activity through distinct reimbursement and access mechanisms.
United States
Oncology clinics across metropolitan markets are expanding infusion capacity to accommodate checkpoint inhibitor volume growth. FDA accelerated approval pathways compress timelines for breakthrough therapies targeting rare malignancies. Integrated delivery networks in Texas and California centralize pharmacy operations to standardize immuno-oncology protocols.
Germany
Centralized hospital procurement systems and reference pricing frameworks create predictable reimbursement pathways for oncology biologics. EMA conditional marketing authorization enables earlier commercial access based on surrogate endpoints. University hospital networks in Bavaria and North Rhine-Westphalia anchor complex case management and multidisciplinary coordination.
Japan
PMDA orphan drug incentives accelerate indication reviews for sponsors with Japanese development programs. The country's national pharmaceutical regulator prioritizes overall survival endpoints in rare malignancy assessments. Tokyo and Osaka metropolitan clusters concentrate clinical trial enrollment and specialized cancer center capacity.
United Kingdom
NICE technology appraisals and Cancer Drugs Fund access schemes shape commercial strategy for novel therapeutics. MHRA post-Brexit regulatory autonomy maintains alignment with EMA scientific standards while enabling streamlined national approvals. London and Manchester academic medical centers compete for investigator-initiated studies and early-phase trial sponsorship.
Australia
TGA priority review pathways and orphan drug designation incentives attract sponsor investment in rare oncology indications. Pharmaceutical Benefits Scheme listing negotiations determine market access timelines and volume potential. Melbourne and Sydney clinical trial networks specialize in immuno-oncology studies with biomarker-enriched enrollment criteria.
Merkel Cell Carcinoma (MCC) Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around established checkpoint inhibitor portfolios with validated cold-chain logistics and infusion center relationships. Large-cap pharmaceutical companies anchor the competitive set through PD-1/L1 franchise dominance, while mid-tier biotechnology firms pursue differentiation through combination regimen development. Strategic archetypes include: integrated immuno-oncology platforms, co-development specialists, and radiation-systemic sequencing innovators. Competitive moves center on formulary access defense within integrated delivery networks and subcutaneous formulation development to expand community clinic reach.
Within the integrated platform tier, Merck & Co. and Bristol-Myers Squibb occupy positions as archetypal checkpoint inhibitor incumbents with entrenched guideline presence. Pfizer Inc. represents the co-development specialist model, leveraging partnership arrangements to extend reach into combination regimens. These three companies exemplify distinct strategic postures: direct franchise ownership, portfolio diversification through collaboration, and convenience-driven delivery innovation.
| Leading Market Players |
|---|
| Merck & Co. |
| Bristol-Myers Squibb |
| Merck KGaA |
| Amgen Inc. |
| Novartis AG |
| Pfizer Inc. |
| Johnson & Johnson |
| Regeneron Pharmaceuticals |
| AstraZeneca PLC |
| Others |
Supply & Pricing Matrix
Checkpoint inhibitor manufacturing concentrates in Ireland and Singapore, where biologic production clusters feed directly into oncology clinic margin pools across United States integrated delivery networks. This upstream concentration shapes downstream pricing power through cold-chain logistics premiums and formulary access fees that concentrate among suppliers with validated distribution infrastructure.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with three-tier pricing separating originator biologics from biosimilar entrants and institutional contract bundles. Price differentiation rests on PD-1 portfolio breadth and immune-related adverse event management protocols. Cost compression in chemotherapy tiers is intensifying because reference pricing authorities in Germany are tightening oncology drug assessments. Community oncology practices show highest price sensitivity, while academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Export-control regimes limiting flows of specialized bioreactor technology and single-use manufacturing systems constrain capacity expansion outside established production zones. Supply concentrates in Ireland, Singapore, and Puerto Rico for active pharmaceutical ingredient synthesis, with fill-finish operations drawing from Swiss and German contract manufacturing networks. Raw material dependencies center on recombinant protein media, chromatography resins, and sterilization-grade filtration assemblies. Single-source vulnerability persists for temperature-controlled logistics providers with validated oncology distribution credentials. Distribution runs through specialized pharmaceutical wholesalers with cold-chain certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as subcutaneous checkpoint inhibitor formulations penetrate community oncology settings and displace hospital-based infusion workflows. Immunotherapy guideline penetration in first-line MCC protocols provides the foundational tailwind justifying capacity investment.
For Market Incumbents: Entrench formulary access through centralized pharmacy and therapeutics committee relationships across multi-site integrated delivery networks. Expand subcutaneous formulation portfolios to capture community clinic volume migrating away from full infusion infrastructure. Vertical integration into cold-chain logistics capabilities defends against emerging entrants with third-party distribution partnerships. For New Entrants and Emerging Players: Pursue combination regimen white space pairing checkpoint inhibitors with novel mechanisms in neoadjuvant MCC protocols. Target community oncology practices in United States metropolitan markets adopting pathway-driven prescribing with limited immuno-oncology specialization. Lead with immune-related adverse event management training programs as differentiated go-to-market support. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap biotechnology firms with differentiated combination assets and established relationships with Merck & Co. or Bristol-Myers Squibb for co-development frameworks. Long-term viability hinges on confirmatory trial completion and overall survival data maturation. Watch EMA conditional marketing authorization conversion rates as the signal indicating sustainable revenue trajectories versus regulatory setback risk.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Collapses chair time and expands community clinic administration capacity across outpatient networks. |
| Combination Regimen Licensing | Extends checkpoint inhibitor reach into novel mechanisms through co-development arrangements with mid-tier biotech. |
| Immuno-Oncology Nursing Certification | Addresses staffing shortages for immune-related adverse event management at community oncology sites. |
| EMA Conditional Marketing Authorization | Accelerates European commercial access prior to confirmatory overall survival data completion. |
| Integrated Delivery Network Partnership | Centralizes formulary decision-making and standardizes protocols across multi-site hospital systems. |
Research Methodology
Desk research of FDA oncology center guidance documents, EMA CHMP assessment reports, and ClinicalTrials.gov enrollment data preceded structured interviews with immuno-oncology nursing directors, hospital pharmacy and therapeutics committee chairs, formulary access specialists, and biologics distribution logistics managers. Secondary validation drew from SEC 10-K oncology segment disclosures, Medicare Part B reimbursement databases, and German reference pricing authority publications. Bottom-up patient volume estimates triangulated against top-down pharmaceutical manufacturer reported sales across the analysis window.
Assumptions held fixed include regulatory approval timelines for breakthrough therapy designations and stable reference pricing frameworks in Germany. The analytical framework modeled segmentation across treatment line, delivery mode, and regional regulatory cluster. CAGRs derived from patient population incidence projections cross-referenced with therapy penetration curves and dosing duration assumptions. Forecast inputs incorporated checkpoint inhibitor cycle frequency, radiation therapy course completion rates, and subcutaneous formulation adoption velocity.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, German reference pricing adjustments, or biologics manufacturing input costs would shift the trajectory. Forecasts reflect assumptions regarding immunotherapy guideline persistence and chemotherapy role contraction. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Global Hyperhidrosis Treatment Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
US Direct Anterior Approach (Total Hip Replacement) Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Laser Therapy Market